
 Global Skateboard Market | 2026-2036
Global Skateboard Market Size, Share, and Industry Trends Forecast 2026-2036
Global Skateboard Market Outlook
Aftermarket deck customization and component replacement is reconfiguring margin pools away from complete board sales toward higher-margin spare parts and accessories. Santa Cruz Skateboards leverages its heritage graphics archive to sustain premium pricing across collector segments. Powell Peralta anchors its position through in-house urethane formulation for wheels, controlling a critical input cost. Element Skateboards competes via vertical channel ownership spanning direct-to-consumer webstores and selective wholesale partnerships.
A skateboard is a short, narrow platform typically measuring 28-33 inches in length and 7.5-8.5 inches in width, constructed from laminated maple or bamboo veneers bonded with epoxy resin and mounted on cast aluminum trucks with polyurethane wheels, designed for human-propelled transportation, trick execution, and recreational mobility. Complete Skateboards dominate unit volume through entry-level retail placement, while Skate Decks as standalone SKUs capture superior margins among enthusiast segments who self-assemble configurations. The Material dimension shows maple sustaining its grip on performance applications while bamboo gains share in sustainability-positioned product lines.
The US Consumer Product Safety Commission enforces mechanical and chemical safety standards for wheeled youth products, while California's Proposition 65 mandates formaldehyde and phthalate disclosure thresholds that shape adhesive and finish selections across manufacturing bases. The EU's REACH regulation restricts hazardous substance migration in articles intended for prolonged skin contact, directly affecting grip tape adhesives and deck lacquers exported to European distribution. Stakeholders must monitor evolving state-level chemical restriction cascades and skate park infrastructure bond measures as dual demand levers.
Market Dynamics
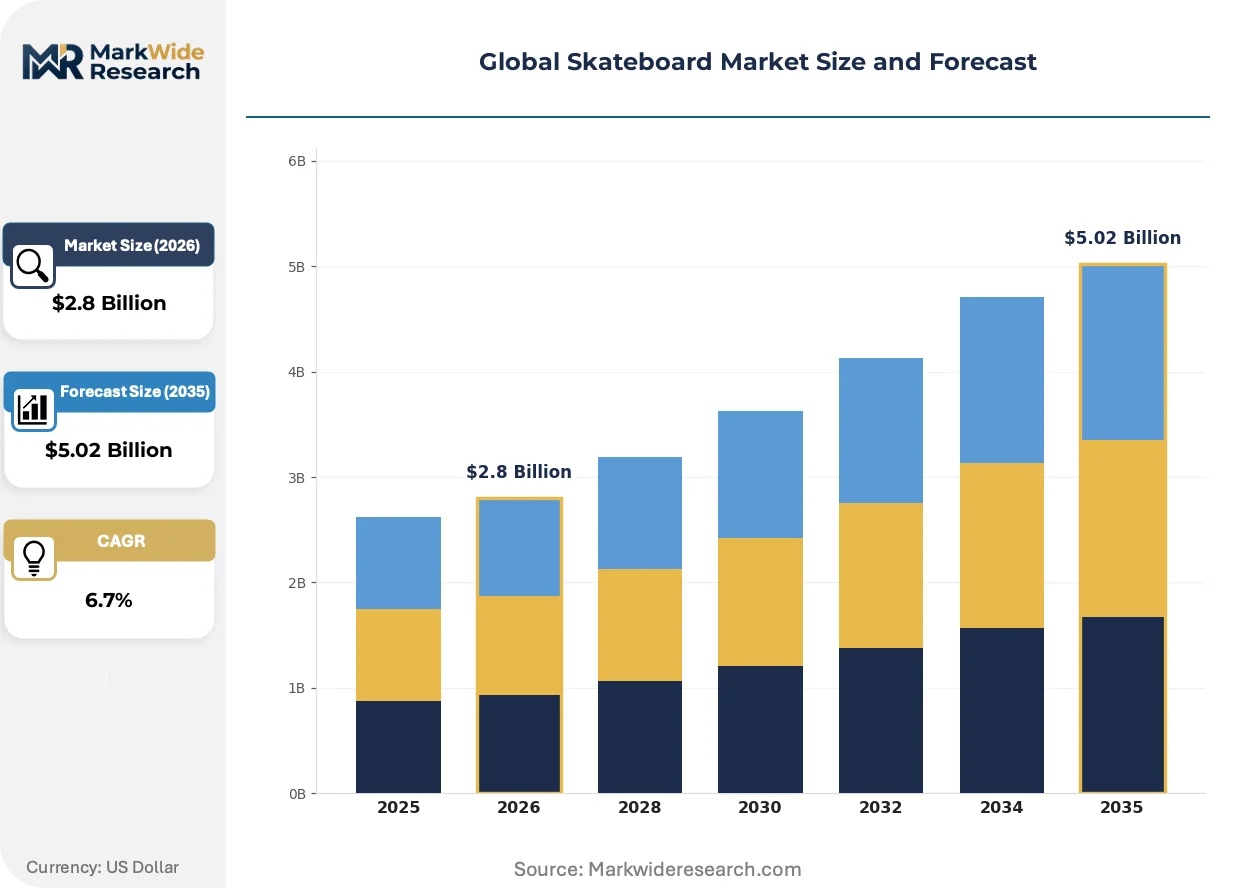
Aftermarket component economics and youth recreation infrastructure investment are restructuring margin distribution and demand geography across the skateboard industry. California's Proposition 65 enforcement on chemical disclosures is compressing adhesive and finish supplier options while concentrating compliant manufacturing capacity.
Growth Catalysts
- School District Recreation Expansion:North American public education systems are formalizing board sports curricula, creating institutional procurement channels that bypass traditional retail and establish recurring volume commitments.
- REACH Compliance as Quality Signal:EU hazardous substance restrictions on grip tape adhesives and deck lacquers are filtering export-capable manufacturers from opportunistic suppliers, elevating compliant producers into premium distribution tiers.
- Urban Skate Park Infrastructure Bonds:Municipal capital programs in Southern California's urban corridor are hardening dedicated recreation surfaces, reducing equipment wear rates while expanding accessible rider hours and replacement part demand.
Market Restraints
- Maple Veneer Supply Concentration:Great Lakes region hardwood suppliers control performance-grade stock, exposing deck manufacturers to regional climate disruption and freight cost volatility on cross-continent shipment.
- Urethane Formulation IP Barriers:In-house wheel chemistry capabilities remain captive to a narrow supplier tier, constraining new entrants from matching rebound and durometer specifications at competitive unit economics.
- Complete Board Margin Compression:Mass retail placement of entry-level assemblies is eroding price realization on standardized configurations, forcing margin extraction toward replacement decks and hardware.
Strategic Opportunities
- Brazilian Urban Youth Penetration:São Paulo and Rio de Janeiro municipal recreation departments lack endemic brand presence, offering first-mover positioning through local distributor partnerships and Portuguese-language media integration.
- Digital Direct Channel Capture:Direct-to-consumer webstores with configuration tools are intercepting enthusiast self-assembly demand, capturing full retail margin that wholesale partnerships historically diluted.
- Sustainability-Positioned Bamboo Lines:Environmental credentialing through bamboo veneer construction is unlocking specialty retail placement and price premiums in European markets with elevated consumer environmental sensitivity.
Industry Challenges
- Proposition 65 Labeling Complexity:California's evolving chemical disclosure thresholds require continuous reformulation documentation, extending product development timelines and legal review costs for multi-SKU portfolios.
- Skate Park Design Standardization Gaps:Absence of unified international construction specifications forces manufacturers to maintain regional product variants, fragmenting production runs and inventory carrying costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Skateboard Market |
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.02 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Complete Skateboards, Skate Decks, Trucks, Wheels Material: Maple, Bamboo, Plastic, Composite Use Case: Street, Park, Vert, Cruise Customer Type: Amateurs, Professionals, Kids, Adults |
| Companies Covered | Globe, DGK, Santa Cruz Skateboards, Plan B Skateboards, Powell Peralta, Zero Skateboards, Spitfire, Almost Skateboards, Element Skateboards, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Skateboard Market Strategic Shifts
Material substitution, regulatory disclosure escalation, and channel disintermediation are converging to restructure how skateboard products are specified, sourced, and consumed across enthusiast and entry-level segments.
Carbon fiber reinforced polymer deck construction is rendering obsolete traditional seven-ply maple assemblies in high-impact trick applications. Professional riders and dedicated park skaters are migrating toward composite substrates that resist stress fractures across extended use cycles. This material transition is compressing replacement frequency for core users while elevating upfront price points and supplier technical qualification requirements.
California's Proposition 65 enforcement mechanism is mandating formaldehyde and phthalate disclosure thresholds that exceed federal baseline requirements for wheeled youth products. Manufacturers serving California distribution must maintain dual formulation inventories or elevate all production to stricter standards, effectively exporting California's regulatory stringency to national supply chains. European exporters to California are consolidating compliance documentation to avoid port-of-entry detention and retailer liability exposure.
Configuration-based purchasing through brand-operated digital channels is displacing pre-assembled complete board transactions among enthusiast segments. Riders are specifying truck geometry, wheel durometer, and bearing grade independently, unbundling manufacturer-curated packages. This behavioral shift concentrates in Southern California's urban corridor where brand flagship stores and endemic retail density have normalized component-level literacy and self-assembly competence.
Global Skateboard Market Segmentation
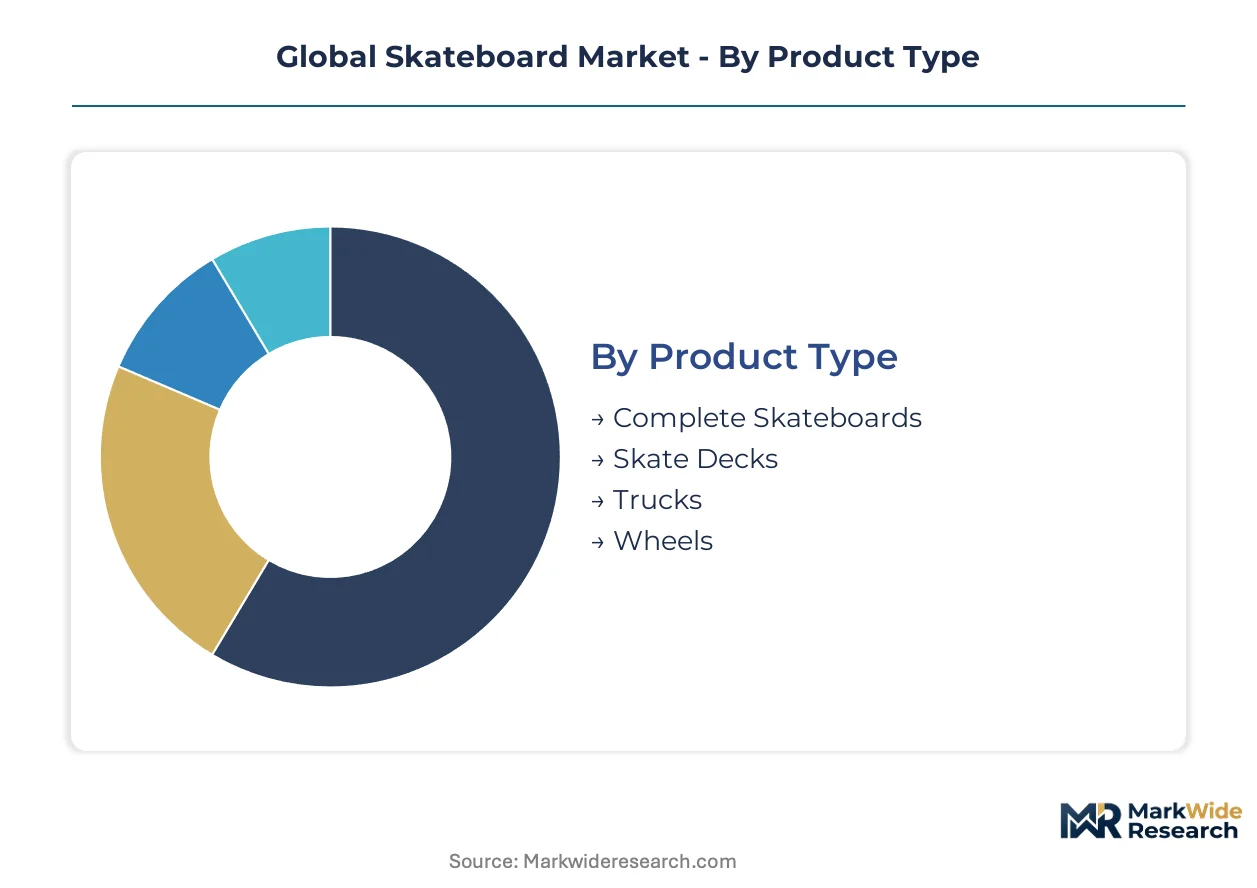
Skateboard market segmentation reveals divergent replacement cycles that restructure revenue timing and margin capture across the value chain. Component-level purchasing patterns concentrate among enthusiasts with technical literacy, while complete board transactions dominate entry-level acquisition channels.
Product Type:
Replacement frequency varies dramatically across product categories, with consumable components turning over fastest and durable assemblies persisting longest in rider inventories.
- Complete Skateboards:Factory-assembled configurations ship with standardized truck geometry and wheel durometer, targeting first-time buyers through mass retail placement. Institutional procurement by North American school districts is hardening volume commitments for entry-level specifications, compressing margin realization on standardized SKUs.
- Skate Decks:Seven-ply laminated maple or bamboo platforms serve as the primary replacement unit for self-assembling enthusiasts, capturing superior margins through direct-to-consumer channels. Southern California's urban corridor concentrates demand for performance-grade constructions where rider competence justifies premium substrate selection.
- Trucks:Cast aluminum axle assemblies with hardened steel kingpins withstand extended use cycles, delaying replacement until structural fatigue or geometry preference shifts.
- Wheels:Urethane formulations with varying rebound characteristics and durometer ratings wear predictably based on surface abrasiveness, creating recurring demand calibrated to local skate park infrastructure conditions.
Complete Skateboards dominate installed base. Skate Decks is where expansion concentrates.
Material:
Raw material selection stratifies across performance tier and environmental positioning, with supply geography constraining manufacturer optionality.
- Maple:Great Lakes region hardwood delivers the stiffness-to-weight ratio required for high-impact trick execution, sustaining grip among professional riders and dedicated park skaters. Regional climate disruption and freight cost volatility expose deck manufacturers to input cost swings on cross-continent shipment from concentrated veneer suppliers.
- Bamboo:Rapid-growth grass veneer construction unlocks sustainability credentialing and reduced environmental footprint claims, commanding placement in European specialty retail with elevated consumer environmental sensitivity. REACH compliance documentation requirements filter export-capable producers from opportunistic suppliers.
- Plastic:Injection-molded polymer substrates serve novelty and toy-adjacent segments with lower performance expectations and compressed price points.
- Composite:Carbon fiber reinforced polymer constructions resist stress fractures across extended use cycles, elevating upfront price points while compressing replacement frequency among core users.
Maple commands performance applications. Bamboo is climbing the fastest on sustainability positioning.
Use Case:
Riding discipline dictates equipment specification, with terrain geometry and impact profiles driving component selection and wear patterns.
- Street:Technical flatground and obstacle-based trick execution demands responsive deck flex and low-profile truck configurations, concentrating wear on grip tape and deck tails.
- Park:Transition riding on concrete and wooden structures requires durable wheel formulations and reinforced truck hangers to withstand repeated impact loading.
- Vert:Vertical ramp and pool riding subjects equipment to maximum structural stress, favoring composite deck constructions and precision-machined truck geometries.
- Cruise:Transportation-oriented riding prioritizes wheel softness and deck stability over technical responsiveness, extending equipment life through reduced impact exposure.
Street and Park dominate participation hours. Vert captures the steepest equipment spend per rider.
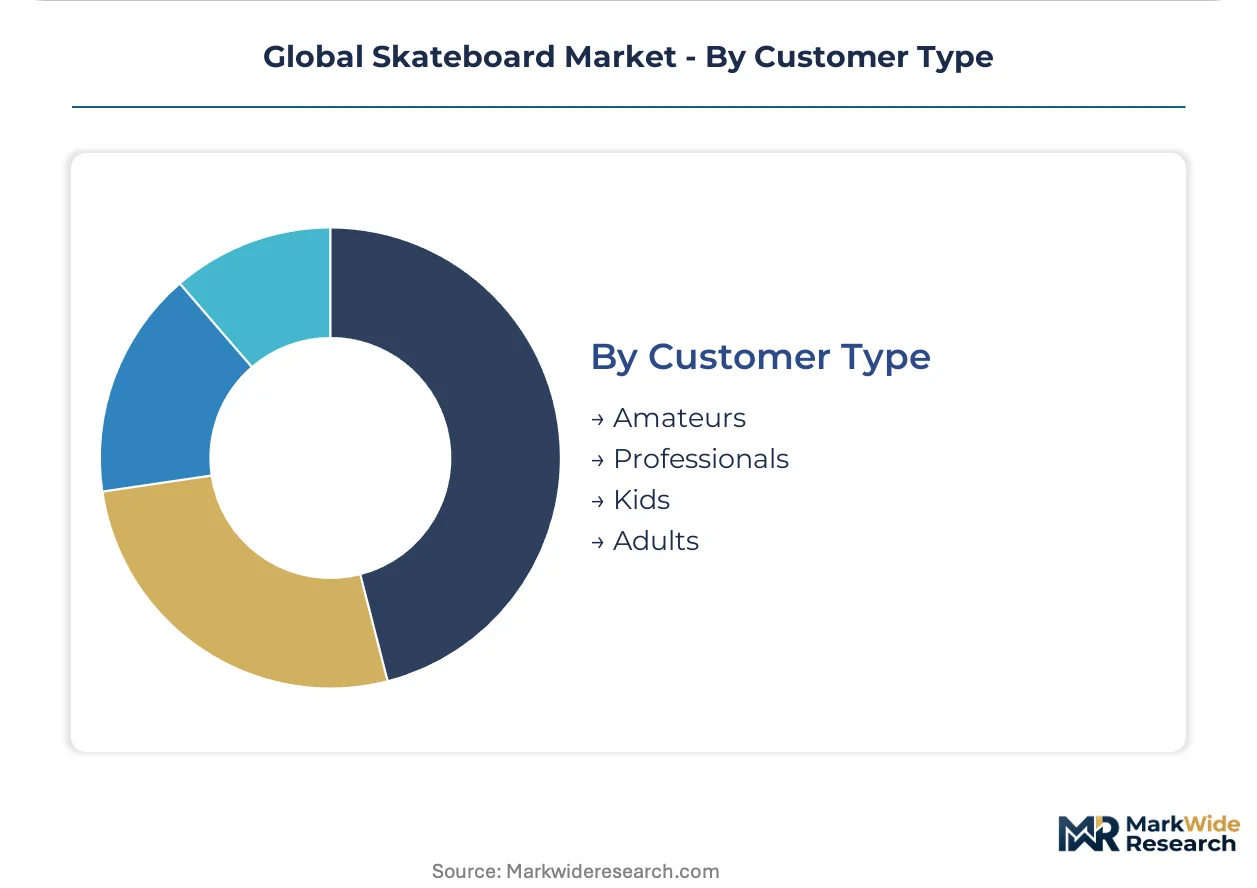
Customer Type:
Purchasing sophistication and price elasticity diverge sharply across experience levels and age cohorts, channeling margin extraction toward technically literate segments.
- Amateurs:Recreational riders with limited technical knowledge default to complete board purchases through traditional retail, accepting manufacturer-curated configurations.
- Professionals:Sponsored and competitive riders access equipment through endemic brand relationships, with specification requirements influencing product development pipelines.
- Kids:Youth segments drive institutional procurement through school district recreation programs, establishing recurring volume outside traditional retail channels.
- Adults:Returning and late-entry riders with disposable income self-assemble premium configurations through direct-to-consumer platforms, intercepting full retail margin.
Amateurs anchor unit volume. Adults is where margin expansion concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price elasticity diverges sharply across geographies. Southern California buyers absorb premium pricing for heritage graphics and composite constructions. Emerging markets in Brazil and Southeast Asia remain acutely price-sensitive, channeling volume toward entry-level complete boards.
United States
School district recreation programs across California, Texas, and Florida are formalizing board sports curricula, creating institutional procurement channels. The US Consumer Product Safety Commission enforces mechanical and chemical safety standards for wheeled youth products. Southern California's urban corridor concentrates endemic brand density and skate park infrastructure investment, hardening dedicated recreation surfaces.
Germany
European specialty retail with elevated consumer environmental sensitivity commands price premiums for sustainability-positioned bamboo lines. The EU's REACH regulation restricts hazardous substance migration in articles intended for prolonged skin contact. Berlin and Hamburg anchor distribution networks for compliant grip tape adhesives and deck lacquers exported from regional manufacturing bases.
Japan
Returning adult riders with disposable income self-assemble premium configurations through direct-to-consumer platforms. METI standards shape product safety documentation for imported wheeled goods. Tokyo and Osaka metropolitan areas concentrate enthusiast segments with technical literacy and component-level purchasing competence.
Brazil
São Paulo and Rio de Janeiro municipal recreation departments lack endemic brand presence, offering first-mover positioning opportunities. ANVISA regulates consumer product safety for imported sporting goods. Local distributor partnerships and Portuguese-language media integration remain underdeveloped relative to market scale.
Australia
Urban skate park infrastructure bonds in Sydney and Melbourne are expanding accessible rider hours and replacement part demand. The TGA oversees product safety compliance for consumer goods. Pacific coast metropolitan clusters concentrate participation hours for street and park riding disciplines.
Global Skateboard Market Competitive Environment
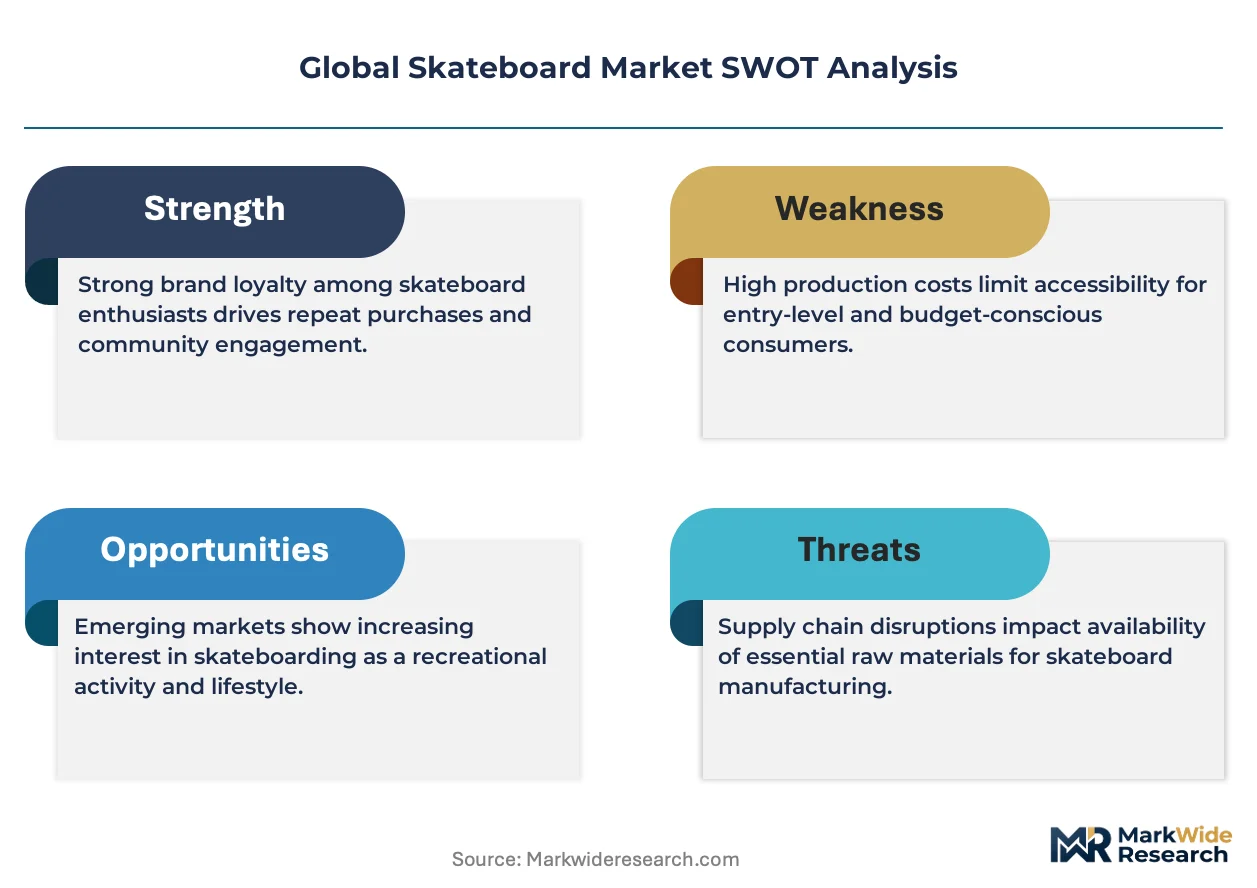
Capability concentration sits with heritage brands commanding urethane formulation expertise and graphics archive depth; scale advantage sits with vertically integrated manufacturers controlling cross-channel distribution. The vendor base stratifies into three tiers: endemic heritage houses, vertically integrated mid-cap specialists, and mass-market assemblers. Strategic moves center on direct-to-consumer channel capture and sustainability credentialing through material substitution.
Within the heritage graphics tier, Santa Cruz Skateboards and Powell Peralta exemplify archetypes leveraging archive depth and in-house chemistry control respectively. Element Skateboards occupies a position representing vertical channel ownership spanning webstores and selective wholesale partnerships. These three entities anchor competitive positioning across premium collector segments, performance-grade component supply, and direct margin capture.
| Leading Market Players |
|---|
| Globe |
| DGK |
| Santa Cruz Skateboards |
| Plan B Skateboards |
| Powell Peralta |
| Zero Skateboards |
| Spitfire |
| Almost Skateboards |
| Element Skateboards |
| Others |
Value Chain & Pricing Dynamics
Undercapacity in compliant California manufacturing is elevating premium pricing for Proposition 65-certified decks while compressing margins on mass-market complete boards. Great Lakes maple veneer suppliers wield pricing power through regional concentration, forcing cross-continent freight absorption or formulation trade-offs.
Pricing Analysis
Aftermarket deck and component sales generate lifetime value that exceeds initial complete board transactions by substantial multiples. Three-tier pricing structure across premium, standard, and economy levels stratifies by substrate certification and heritage graphics licensing. Cost compression in entry-level complete boards is intensifying because institutional procurement channels demand volume discounts. School district buyers exhibit acute price sensitivity while self-assembling adult enthusiasts absorb premiums for performance-grade constructions.
Supply Chain Analysis
Export-control scrutiny on carbon fiber precursor chemicals limits composite substrate flows to qualified manufacturers. Great Lakes region hardwood suppliers, Chinese bamboo veneer processors, and German REACH-compliant finish houses anchor global deck production. Urethane wheel chemistry draws from captive in-house formulation, specialized chemical suppliers, and recycled content feedstocks. Single-source vulnerability concentrates in Great Lakes maple veneer where climate disruption threatens harvest cycles. Distribution runs through brand-operated direct-to-consumer webstores, endemic specialty retailers, and institutional procurement channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Skateboard market fragmentation creates entry niches as configuration-based purchasing unbundles manufacturer-curated packages into component-level transactions.
For Market Incumbents: Pre-empt margin erosion in complete boards by accelerating direct-to-consumer channel capture and in-house urethane formulation investment. Carbon fiber composite entrants threaten heritage maple positioning; defend through archive licensing and collector segment cultivation. Backward integration into captive veneer sourcing reduces Great Lakes supplier dependency. For New Entrants and Emerging Players: Establish a beachhead in Brazilian municipal recreation departments where endemic brand presence remains underdeveloped. São Paulo and Rio de Janeiro procurement channels lack Portuguese-language media integration and local distributor partnerships. Configuration tools and self-assembly education content unlock enthusiast segment entry without wholesale margin dilution. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among aftermarket component suppliers with established wheel and bearing replacement cycles. Five-to-ten year viability favors manufacturers with REACH documentation depth and California compliance infrastructure already amortized. Watch for inflection in municipal skate park infrastructure bond passage rates as replacement part demand accelerators.| Strategic Initiative | Industry Significance |
|---|---|
| Direct-to-Consumer Channel Expansion | Captures full retail margin from self-assembling enthusiasts in Southern California's urban corridor. |
| Sustainability-Positioned Bamboo Line Launch | Unlocks European specialty retail placement under REACH-compliant documentation requirements. |
| In-House Urethane Formulation Investment | Replicates Powell Peralta's chemistry control over wheel rebound and durometer specifications. |
| Brazilian Distribution Partnership Formation | Secures first-mover positioning in São Paulo municipal recreation procurement channels. |
| Heritage Graphics Archive Licensing Program | Extends Santa Cruz Skateboards' premium pricing model across collector and reissue segments. |
Study Parameters
A standing panel of deck manufacturing plant managers, urethane R&D chemists, endemic retail buyers, and school district recreation coordinators provided ongoing calibration. Primary interviews with industry stakeholders combined with secondary validation from US Consumer Product Safety Commission enforcement records, California Proposition 65 settlement databases, EU REACH substance restriction updates, and municipal skate park infrastructure bond filings. Bottom-up SKU-level demand modeling and top-down category value triangulation anchored projections.
Scenario-bracketing around regulatory enforcement intensity and youth recreation program expansion pace shaped analytical framework development across the projection horizon. Segmentation dimensions modeled include product type, material substrate, use case discipline, and customer experience tier. CAGRs derived from replacement cycle frequency analysis calibrated to local skate park surface abrasiveness conditions and regional climate disruption probabilities for maple veneer supply.
Sensitivities concentrate around Proposition 65 disclosure threshold revisions and Great Lakes climate disruption severity. Forecasts reflect assumptions on institutional procurement channel maturation and carbon fiber composite adoption curves among professional riders. Material shifts in California chemical enforcement stringency or Brazilian municipal recreation budget allocation would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sports Equipment
Gymnastic Hoops Market
Sports Equipment
Football Market
Sports Equipment
Rubber Fitness Flooring Market
Sports Equipment
Ice Cleat Market
Sports Equipment
Skating Shoes Market
Sports Equipment
BMX Bikes Market
Sports Equipment
Basketball Shooting Machine Market
Sports Equipment
Smart Swim Goggles Market
Sports Equipment
US Fencing Market
Sports Equipment
Bicycle Pumps Market
Sports Equipment
Golf Ball Market
Sports Equipment
Ankle Roll Guard Market
Sports Equipment
Padel Balls Market
Sports Equipment
Gym Bag Market
Sports Equipment
Boxing Equipment Market
Sports Equipment
Synthetic Ice Skating Rink Market