
 Boxing Gloves Market | 2026-2036
Boxing Gloves Market Size, Share, and Industry Trends Forecast 2026-2036
Boxing Gloves Market Analysis
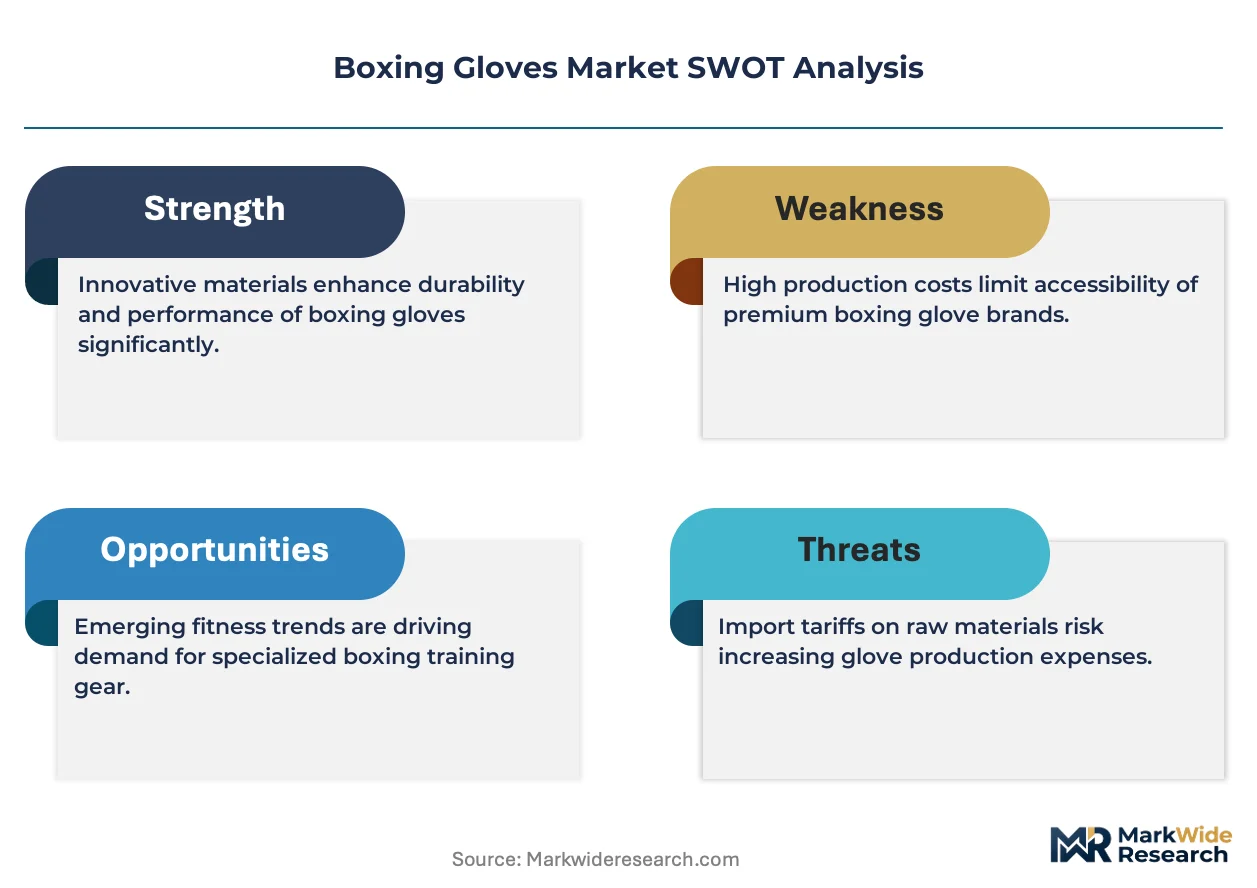
A shortage of specialized pattern cutters and leather artisans in traditional manufacturing hubs is unwinding production capacity across premium glove lines. Everlast Worldwide, Inc. leverages its century-old brand equity and vertical manufacturing control to sustain North American shelf presence. Hayabusa Fightwear Inc. differentiates through biomechanics-driven padding systems and occupies the performance-tier channel. Fairtex anchors Southeast Asian supply with in-house Thai leather sourcing and dominates regional export flows into European fight sports retailers.
Boxing gloves are padded hand coverings engineered with layered foam or horsehair stuffing beneath leather or synthetic shells, designed to absorb impact force and protect both striker and target during combat sports training or competition. Multi-density foam injection molding achieves calibrated shock attenuation measured in kilonewtons of transmitted force. Training gloves command the largest volume pool due to gym membership expansion, while competition gloves concentrate margin in certified lace-up constructions. Synthetic material variants represent the fastest-growing segment as tannery environmental compliance costs reshape sourcing economics across mid-tier price bands.
The Consumer Product Safety Commission monitors impact attenuation standards for youth boxing equipment, while California's Proposition 65 imposes labeling burdens on chrome-tanned leather components that elevate compliance costs for US-bound shipments. REACH restrictions across the European Union limit certain azo dyes and chromium VI in leather finishing, redirecting formulation R&D toward vegetable-tanned and polymer alternatives. Stakeholders must weigh synthetic material transitions against athlete preference for leather hand-feel when configuring multi-year product roadmaps and regional certification budgets.
Market Dynamics
California's Proposition 65 enforcement on chrome-tanned leather components is forcing wholesale material transitions across mid-tier boxing glove supply chains, compressing margins for manufacturers dependent on traditional tannery networks while opening volume pathways for synthetic alternatives.
Growth Catalysts
- Amateur boxing program expansion:School and community center procurement in the United States and Mexico is generating sustained institutional demand for training-grade equipment with standardized safety specifications.
- REACH-compliant synthetic formulations:European Union restrictions on chromium VI and azo dyes are redirecting R&D investment toward polymer-based shell materials that bypass tannery compliance costs.
- Biomechanics-driven padding innovation:Multi-density foam injection molding calibrated to transmitted force measurements is differentiating performance-tier products in competitive retail channels.
Market Restraints
- Specialized artisan scarcity:A shortage of pattern cutters and leather craftspeople in traditional manufacturing hubs is constraining production capacity for premium lace-up competition gloves.
- Environmental compliance cost escalation:Vegetable-tanning process investments required by tightening wastewater regulations in Thailand and Pakistan are elevating unit economics for leather-shelled products.
- Raw material price volatility:Petrochemical feedstock fluctuations directly impact synthetic shell production costs, compressing margin predictability for manufacturers without backward integration into polymer supply.
Strategic Opportunities
- Youth segment certification capture:Consumer Product Safety Commission impact attenuation standards for junior boxing equipment create first-mover advantage for brands achieving compliant labeling ahead of enforcement ramp-up.
- Direct-to-gym distribution models:Bypassing traditional sporting goods retail through equipment leasing partnerships with boutique fitness studios and martial arts academies secures recurring revenue streams.
- Thai leather cluster integration:In-house sourcing from Bangkok-region tanneries with established EU export compliance histories insulates premium product lines from supply disruption risks affecting South Asian competitors.
Industry Challenges
- Cross-regional certification complexity:Simultaneous compliance with CPSC youth standards, REACH chemical restrictions, and Proposition 65 labeling requirements demands dedicated regulatory affairs capacity that smaller manufacturers lack.
- Legacy equipment replacement cycles:Extended durability of high-quality training gloves slows volume turnover in saturated North American gym markets, pressuring new customer acquisition costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Boxing Gloves Market |
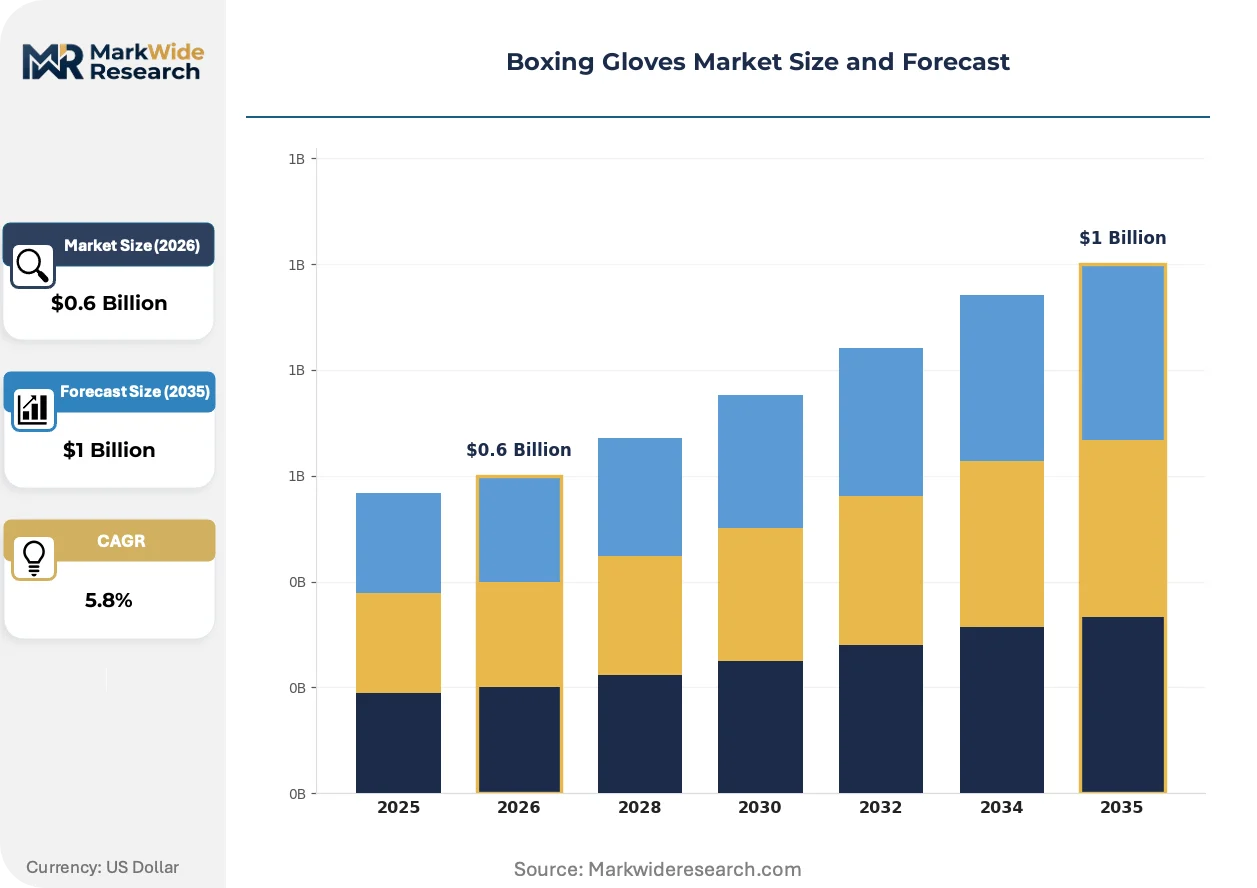
| Market Size in 2026 | $0.6 Billion |
| Market Size in 2035 | $1 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Training Gloves, Sparring Gloves, Competition Gloves, Bag Gloves Material: Leather, Synthetic, Vinyl, Foam Closure Type: Velcro, Lace-Up, Slip-On, Hook and Loop Weight Category: 8 oz, 10 oz, 12 oz, 16 oz |
| Companies Covered | Everlast Worldwide, Inc., Winning, Cleto Reyes, Hayabusa Fightwear Inc., Venum, Grant, TWINS SPECIAL, Fairtex, RDX, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Boxing Gloves Market Emerging Trajectories
Material science advances and regulatory pressure are restructuring competitive advantage around environmental compliance credentials rather than traditional craftsmanship heritage, compressing the timeline for synthetic adoption while fragmenting premium positioning strategies.
Multi-density foam injection molding is bifurcating the performance-tier segment from commodity training equipment. Competitive amateur programs and professional corner teams are specifying calibrated kilonewton attenuation metrics in procurement tenders. This technology is compressing price premiums previously commanded by horsehair-stuffed heritage constructions while enabling volume manufacturers to achieve performance parity.
California's Proposition 65 warning label mandates for chrome-tanned leather are restructuring West Coast distribution economics. Retailers facing liability exposure are delisting non-compliant SKUs ahead of enforcement deadlines. The mid-tier synthetic segment is capturing shelf space as brands reformulate with polymer alternatives that bypass tanning chemical disclosure requirements entirely.
Gym operators are consolidating equipment procurement through centralized buying cooperatives rather than individual franchisee purchasing. Boutique fitness chains and martial arts academy networks are negotiating master service agreements with direct manufacturer relationships. This consolidation is most visible in Mexico's combat sports training market, where domestic production clusters leverage geographic proximity to undercut import landed costs for volume orders.
Boxing Gloves Market Segmentation
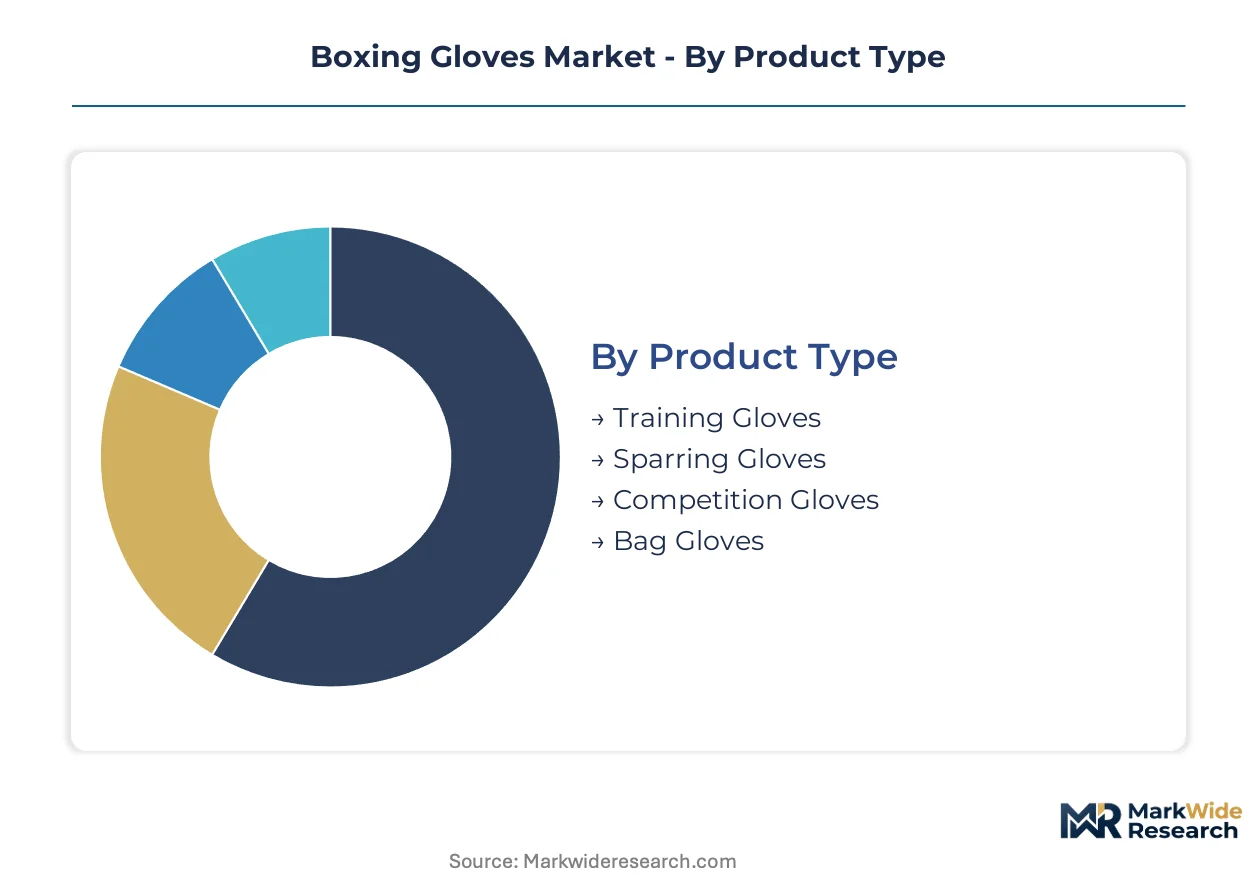
Segmentation in boxing gloves reveals how procurement channels, material compliance costs, and athlete use-case specificity fragment pricing power across otherwise standardized protective equipment. Manufacturers configure production lines around certification requirements and durability expectations that diverge sharply between institutional buyers and individual consumers.
Product Type:
Margin pools concentrate in competition-grade lace-up constructions where certified specifications and limited production runs sustain price premiums, while training volumes generate cash flow through replacement cycles in commercial gym environments.
- Training Gloves:Multi-density foam padding beneath synthetic or leather shells absorbs repeated impact during heavy bag and mitt work. Demand concentrates in United States boutique fitness chains and Mexican martial arts academies where institutional procurement contracts specify 16 oz standardized weights for member safety protocols.
- Sparring Gloves:Thicker padding configurations than competition specifications reduce partner injury risk during controlled exchanges. Mexican domestic production clusters capture North American distribution for this segment through geographic proximity to California and Texas gym networks.
- Competition Gloves:Lace-up constructions with calibrated kilonewton attenuation metrics for sanctioning body approval.
- Bag Gloves:Minimalist padding designs prioritizing hand speed over protection for heavy bag conditioning.
Training Gloves holds installed capacity. Sparring Gloves is rotating up the share rankings.
Material:
Cost tier stratification separates premium hand-feel positioning from compliance-driven synthetic adoption as California Proposition 65 enforcement elevates chrome-tanned leather disclosure burdens.
- Leather:Full-grain cowhide or Thai-sourced hides provide tactile feedback and durability heritage prized by professional corners and amateur competitors. Vegetable-tanning investments in Bangkok-region tanneries insulate premium lines from REACH and Proposition 65 disruptions affecting South Asian chrome-tanning networks.
- Synthetic:Polymer-based shell materials bypass tanning chemical regulations entirely while achieving performance parity through advanced foam injection molding. United States West Coast retailers are delisting non-compliant leather SKUs ahead of enforcement deadlines, accelerating shelf space capture.
- Vinyl:Entry-level price positioning for youth programs and occasional recreational users prioritizing cost over longevity.
- Foam:Molded polymer constructions eliminating separate shell-pad assembly for disposable or rental gym equipment applications.
Leather maintains heritage pricing authority. Synthetic is climbing the fastest as compliance economics restructure mid-tier sourcing.
Closure Type:
Application context dictates closure selection—competitive environments demand lace-up security while commercial gym throughput favors rapid donning and doffing.
- Velcro:Hook-and-loop wrist straps enable self-application without corner assistance, dominating commercial gym and home training environments where convenience outweighs micro-adjustment precision. United States fitness studio chains specify Velcro closures for group class equipment inventories to minimize instructor assistance requirements.
- Lace-Up:Traditional cotton or synthetic laces distributed across wrist and palm surfaces provide customizable compression and competition-legal security. Professional corner teams and sanctioned amateur tournaments mandate lace-up constructions for glove integrity under impact.
- Slip-On:Elasticized wrist entry for youth introductory programs and physical education contexts prioritizing rapid equipment distribution.
- Hook and Loop:Reinforced Velcro variants for high-frequency commercial use where standard adhesive surfaces degrade prematurely.
Lace-Up holds installed capacity in competition channels. Velcro is rotating up the share rankings through gym network expansion.
Weight Category:
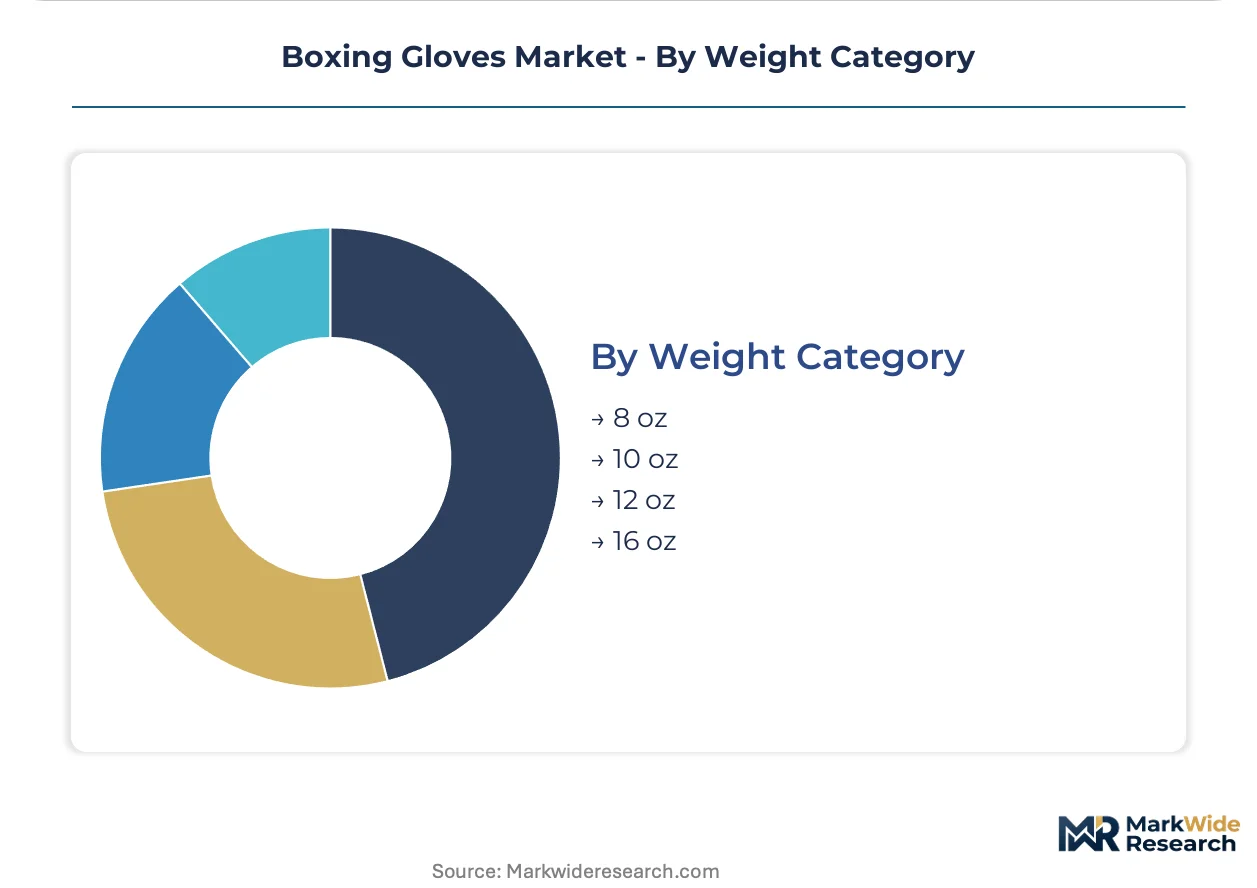
Volume concentration sits in 16 oz standardized training specifications while competition weights fragment across sanctioning body requirements and athlete class divisions.
- 16 oz:Standardized sparring and training weight mandated by most amateur boxing federations for athlete protection during extended sessions. Mexican community center procurement and United States school district programs specify 16 oz exclusively for liability mitigation.
- 12 oz:Transitional weight bridging training conditioning and competition preparation for lighter weight class athletes. Boutique fitness studios in California and Texas stock 12 oz for female and youth members transitioning from fitness boxing to technical training.
- 8 oz:Professional competition weight for welterweight through heavyweight divisions under major sanctioning bodies.
- 10 oz:Lighter professional competition specification for featherweight through lightweight classes.
16 oz holds installed capacity. 12 oz is rotating up the share rankings through demographic expansion in recreational boxing.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States gym networks favor 16 oz Velcro training gloves for group class throughput, while Mexican procurement concentrates on institutional sparring specifications and Thailand exports premium lace-up competition constructions to European fight sports retailers.
United States
Boutique fitness chains in California and Texas drive 12 oz and 16 oz training glove volumes for member safety protocols. The Consumer Product Safety Commission monitors youth boxing equipment impact attenuation standards, elevating compliance costs for junior product lines. Los Angeles-area distributors face Proposition 65 enforcement on chrome-tanned leather, accelerating synthetic SKU shelf space capture ahead of warning label mandates.
Mexico
Community center and school district procurement generates institutional demand for standardized 16 oz sparring gloves across Mexico City and Guadalajara metro areas. Federal consumer protection standards align with North American safety specifications, facilitating cross-border distribution into Texas and California gym networks. Domestic production clusters in Nuevo León leverage geographic proximity to undercut import landed costs for volume orders serving Latin American markets.
Thailand
Bangkok-region tanneries supply premium full-grain hides to competition glove manufacturers exporting to European fight sports retailers. REACH restrictions on chromium VI and azo dyes redirect formulation R&D toward vegetable-tanned alternatives with established EU export compliance histories. Samut Prakan industrial zones concentrate leather finishing capacity insulated from South Asian chrome-tanning network disruptions.
Germany
Amateur boxing federation procurement specifies calibrated kilonewton attenuation metrics for sanctioned tournament equipment. ECHA REACH enforcement limits certain chemical finishes in leather processing, elevating compliance investment requirements for imported products. Bavaria-based combat sports retailers source certified competition gloves through direct relationships with Bangkok-region manufacturers bypassing South Asian supply chains.
United Kingdom
London and Manchester gym networks drive training glove replacement cycles through membership expansion in boutique boxing fitness studios. Trading standards enforcement aligns with EU-derived chemical safety regulations for imported leather goods. Midlands-based distributors consolidate procurement through master service agreements with domestic academy chains, compressing traditional retail channel margins.
Boxing Gloves Market Vendor Landscape
A small set of integrated leaders sits above a broader specialist tier in boxing glove supply, with century-old heritage brands controlling North American shelf presence and Bangkok-region manufacturers anchoring Southeast Asian export flows. The structure bifurcates between volume-driven training equipment producers and premium competition constructors constrained by artisan scarcity. Three archetypes dominate: vertically integrated heritage houses with captive manufacturing, biomechanics-focused performance specialists, and regional export champions leveraging geographic cluster advantages. Competitive moves concentrate on synthetic material transitions to bypass tanning chemical regulations and direct-to-gym distribution partnerships that bypass traditional sporting goods retail.
Within the heritage tier, Everlast Worldwide, Inc. represents century-old brand equity sustained through vertical manufacturing control, while Fairtex anchors Southeast Asian supply with Bangkok-region leather sourcing advantages. Hayabusa Fightwear Inc. occupies the performance-tier position through biomechanics-driven positioning. These three exemplify how competitive advantage fragments across regulatory compliance capabilities, geographic cluster access, and technical differentiation in padding systems.
| Leading Market Players |
|---|
| Everlast Worldwide, Inc. |
| Winning |
| Cleto Reyes |
| Hayabusa Fightwear Inc. |
| Venum |
| Grant |
| TWINS SPECIAL |
| Fairtex |
| RDX |
| Others |
Supply Flow & Price Mechanics
Batch-scale foam injection molding in Bangkok-region factories creates capacity utilization advantages that compress unit economics for mid-tier synthetic gloves while elevating price floors for artisan-dependent leather competition constructions. California's Proposition 65 enforcement on chrome-tanned leather components feeds back into sourcing decisions, redirecting procurement budgets toward polymer alternatives that bypass disclosure burdens entirely.
Pricing Analysis
Long-term offtake contracts between Mexican production clusters and United States gym networks anchor volume pricing for standardized 16 oz training specifications, while spot-market transactions govern premium lace-up competition grades where artisan scarcity limits supply elasticity. Three-tier pricing structure across premium, standard, and economy levels separates certified competition constructions from institutional training volumes and entry-level vinyl alternatives. Cost compression in mid-tier synthetic segments is intensifying because REACH-compliant polymer formulations bypass tannery compliance investments. Institutional buyers in school districts and community centers exhibit highest price sensitivity, whereas professional corner teams prioritize kilonewton attenuation metrics over unit cost.
Supply Chain Analysis
Inventory lead times for Thai-sourced full-grain hides extend production cycles for premium lace-up gloves, while synthetic shell materials from Chinese and South Korean petrochemical networks enable faster turnaround on training-grade orders. Raw material flows draw from Bangkok-region tanneries, Nuevo León assembly plants, and Guangdong polymer suppliers. Single-source vulnerability concentrates in chrome-tanned leather networks facing Proposition 65 and REACH restrictions simultaneously. Distribution runs through direct-to-gym master service agreements that bypass traditional sporting goods retail, particularly visible in Mexico's consolidated academy procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbent boxing glove manufacturers face substitution pressure from adjacent combat sports protective equipment and fitness technology platforms that capture training expenditure. Defense requires consolidating position around regulatory compliance capabilities and captive supply relationships.
For Market Incumbents: Consolidate Bangkok-region tannery relationships to insulate premium lines from South Asian chrome-tanning disruptions. Acquire in-house foam injection molding capacity to capture mid-tier synthetic volume growth as California Proposition 65 enforcement accelerates material transitions. Vertical control over multi-density padding technology defends against biomechanics-focused entrants.
For New Entrants and Emerging Players: Differentiate on youth segment certification compliance ahead of Consumer Product Safety Commission enforcement ramp-up. Target United States boutique fitness studio chains with equipment leasing partnerships that bypass entrenched retail shelf relationships. White-space exists in REACH-compliant synthetic formulations for European amateur boxing federation procurement.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors manufacturers with backward integration into polymer supply and established regulatory affairs capacity. Five-to-ten year viability hinges on navigating material science transitions while preserving athlete preference for leather hand-feel in premium tiers. Monitor California retail delisting patterns as inflection indicator for synthetic adoption velocity.
| Strategic Initiative | Industry Significance |
|---|---|
| Synthetic Material Transition | Proposition 65 compliance bypasses chrome-tanned leather disclosure burdens for West Coast distribution. |
| Direct-to-Gym Distribution | Master service agreements with Mexican academy networks secure recurring revenue outside retail channels. |
| Youth Certification Capture | Consumer Product Safety Commission compliance creates first-mover advantage in institutional procurement. |
| Thai Leather Cluster Integration | Bangkok-region tanneries with REACH histories insulate premium lines from South Asian supply disruption. |
| Biomechanics R&D Investment | Multi-density foam calibration to kilonewton metrics differentiates performance-tier from commodity training equipment. |
Methodological Framework
Two parallel data streams informed the analysis: structured primary interviews with equipment manufacturers, tannery operations managers, gym procurement directors, and amateur boxing federation officials; and secondary validation through customs trade records, Consumer Product Safety Commission filings, ECHA REACH substance databases, and state-level Proposition 65 enforcement actions. Bottom-up triangulation across production capacity estimates and top-down demand modeling from gym membership and institutional program expansion data anchored volume forecasts.
Across the analysis window, the forecasting framework modeled segmentation dimensions including product type, material composition, closure mechanism, weight category, and regional regulatory cluster. CAGRs were derived from installed capacity utilization rates and replacement cycle analysis across commercial gym networks. Industry-specific inputs incorporated leather tanning compliance cost trajectories and foam injection molding technology diffusion curves.
The analysis sits within stated boundaries; outcomes outside sustained amateur program funding levels or accelerated Proposition 65 enforcement timelines would require recalibration. Forecasts reflect documented assumptions regarding material substitution elasticities and regional certification harmonization progress. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sports Equipment
Smart Swim Goggles Market
Sports Equipment
Tennis Racquet Market
Sports Equipment
Ice Cleat Market
Sports Equipment
UAE Horse Riding Equipment Market
Sports Equipment
Surfing Equipment Market
Sports Equipment
Volleyball Shoes Market
Sports Equipment
Basketball Gear Market
Sports Equipment
Licensed Sports Merchandise Market
Sports Equipment
Global Badminton Equipment and Facilities Market
Sports Equipment
Surface Water Sports Equipment Market
Sports Equipment
Squash Equipment Market
Sports Equipment
Clay Pigeon Thrower Market
Sports Equipment
Tetherball Market
Sports Equipment
Europe Archery Equipment Market
Sports Equipment
Air Sports Equipment Market
Sports Equipment
Golf Ball Market