
 Window Automation Market | 2026-2036
Window Automation Market Size, Share, and Industry Trends Forecast 2026-2036
Window Automation Market Analysis
Energy performance certification upgrades are redrawing competitive boundaries across the window automation sector. ASSA ABLOY leverages its electromechanical lock and actuator integration to dominate secure automated opening solutions. GEZE GmbH sustains technology leadership in door and window drive systems through intensive R&D on low-energy motors. Somfy anchors the residential smart shading segment with proprietary radio protocols and channel control across European distribution networks.
Window automation encompasses electromechanical systems that enable remote or programmed operation of fenestration units, typically incorporating torque-rated linear actuators, position sensors, and bus-compatible control interfaces to manage daylight admission, thermal loads, and indoor air quality in built environments. Motorized windows lead product type demand in commercial new construction, while smart film represents the fastest-growing segment as electrochromic glazing displaces conventional shading in premium facades. IoT-enabled technology stacks capture expanding margin pools by enabling predictive maintenance and grid-responsive load management, whereas basic remote control systems face commoditization pressure in residential retrofits.
REACH compliance and CE marking govern material safety and electromagnetic compatibility for window automation equipment sold across Europe, while the EU Green Deal's revised Energy Performance of Buildings Directive mandates automated shading integration in large commercial renovations. The US market falls under FCC oversight for wireless control modules and OSHA guidelines for powered opening force limits in workplace installations. Stakeholders must monitor evolving building codes that increasingly prescribe automated natural ventilation as a primary compliance pathway for indoor air quality standards.
Market Dynamics
Electrochromic glazing integration is fragmenting the traditional motorized window segment as building operators seek unified facade management systems rather than discrete shading and ventilation components. This convergence is compressing margins for standalone actuator suppliers while rewarding full-stack platform vendors.
Growth Catalysts
- EU Green Deal Energy Performance of Buildings Directive:Large commercial renovations across Germany, France, and the Netherlands now mandate automated shading integration, creating pull-through demand for motorized window systems in retrofit projects.
- Smart building IoT convergence:Facility management platforms in premium office developments are standardizing on BACnet and KNX protocols, requiring window automation hardware with native bus compatibility.
- Daylight harvesting optimization:LEED and BREEAM certification pathways reward automated fenestration controls, driving specification in North American and European sustainable construction.
Market Restraints
- Rare earth magnet supply concentration:Neodymium and dysprosium dependency on Chinese processing creates input cost volatility for permanent magnet motors in linear actuators.
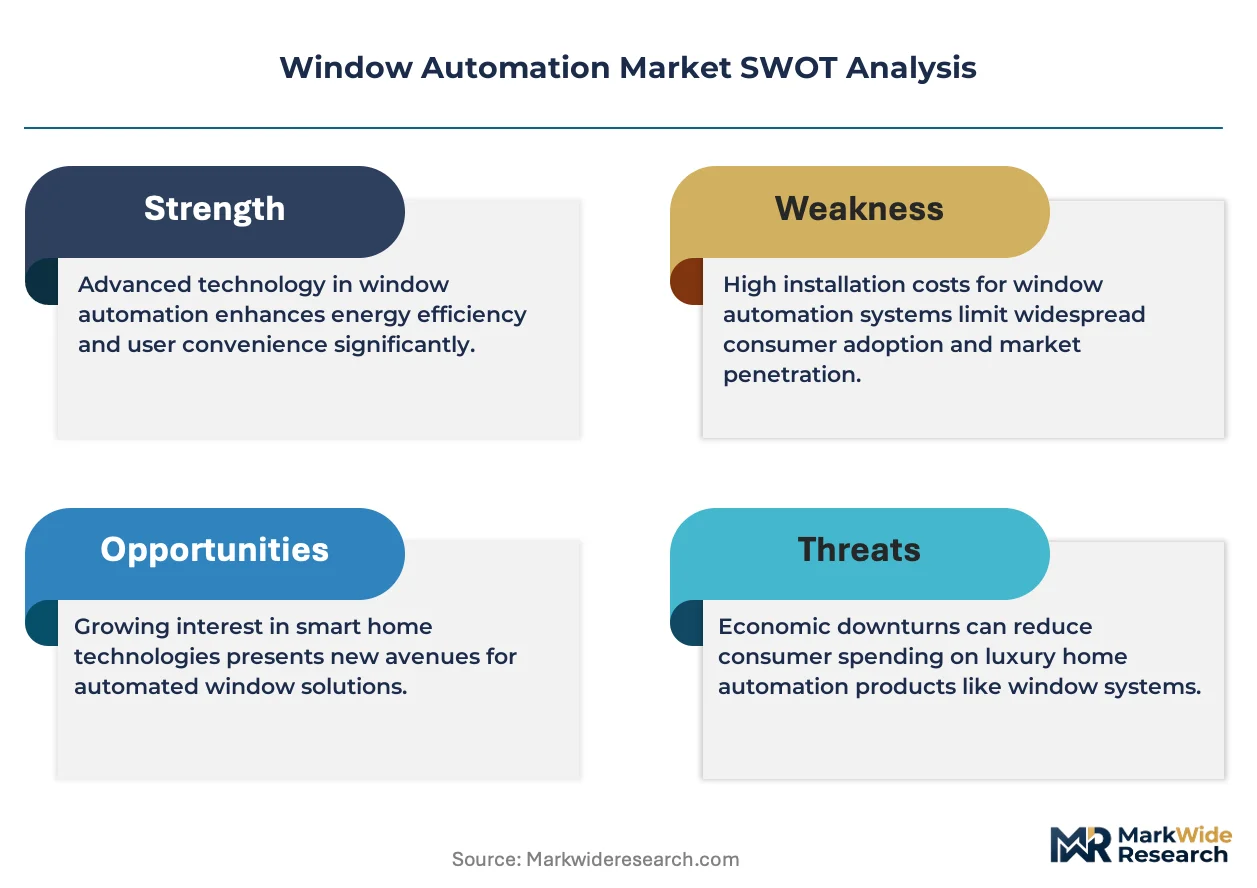
- Electromechanical complexity premium:Integrated torque sensors and position feedback systems add material cost overhead that limits penetration in residential retrofits and budget commercial segments.
- REACH substance restrictions:ECHA scrutiny of flame retardants and plasticizers in cable assemblies and housing materials forces reformulation cycles that extend product development timelines.
Strategic Opportunities
- Underpenetrated Nordic residential markets:Sweden, Norway, and Denmark show low smart window penetration despite high construction quality standards and energy-conscious consumer bases.
- Healthcare ventilation automation:Hospital patient rooms and operating suites present emerging application demand for touchless, programmable natural ventilation to supplement mechanical HVAC.
- Grid-responsive load management:Utility demand response programs in California and Texas create regulatory tailwinds for window automation systems with embedded power curtailment capabilities.
Industry Challenges
- Embedded systems firmware expertise scarcity:Shortage of engineers with real-time control and cybersecurity hardening skills delays product development for connected window platforms.
- CE marking and FCC certification parallelism:Dual jurisdiction testing requirements for wireless control modules extend time-to-market for vendors targeting transatlantic deployment.
- Legacy building automation integration:Proprietary legacy protocols in existing commercial stock force expensive gateway development or rip-and-replace scenarios.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Window Automation Market |
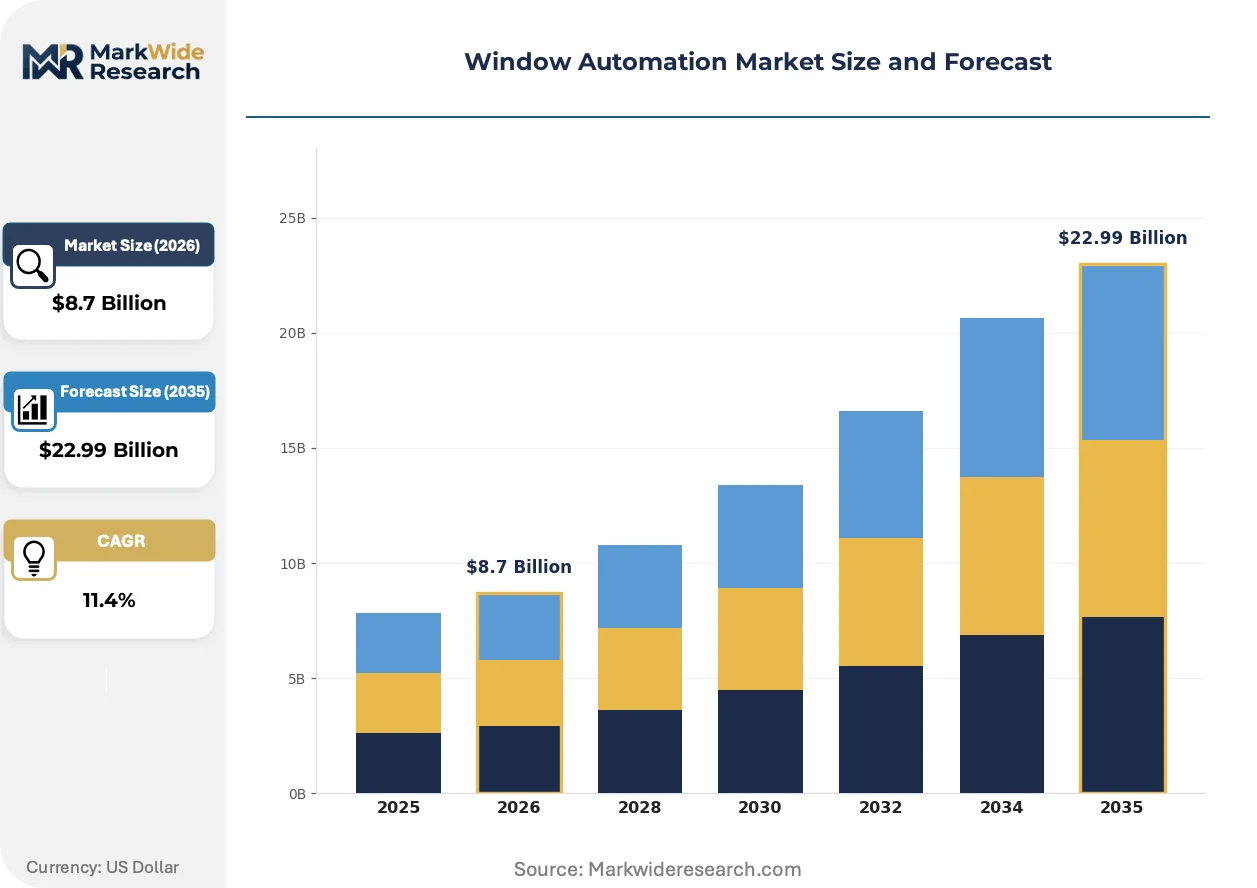
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $22.99 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Motorized Windows, Automated Shades, Smart Film, Actuators Technology: IoT, Smart Sensors, Remote Control, Home Automation End User: Residential, Commercial, Industrial, Automotive Application: Energy Efficiency, Security Solutions, Privacy Management, Ventilation |
| Companies Covered | ASSA ABLOY, Allegion Plc, Nabtesco Corporation, Schüco International KG, GEZE GmbH, Somfy, Velux Group, Andersen Corporation, Schneider Electric, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Window Automation Market Emerging Trajectories
Facade automation is converging with building energy management platforms, dissolving the boundary between passive envelope performance and active HVAC control. This integration is redefining supplier value propositions and procurement evaluation criteria.
Electrochromic smart glass is fragmenting the conventional shading market by embedding tint control within the glazing unit itself. Premium office developers in London, New York, and Singapore are specifying electrochromic curtain walls that eliminate external blinds and internal shades entirely. This displacement is compressing demand for motorized roller systems while expanding the addressable market for integrated facade control platforms.
The EU Green Deal's revised Energy Performance of Buildings Directive is mandating automated shading and natural ventilation in large commercial renovations across member states. Germany's federal building codes and France's RE2020 environmental regulations are accelerating adoption timelines. Building owners in the Netherlands and Belgium are responding by bundling window automation into comprehensive energy retrofit contracts.
Facility management procurement is consolidating vendor relationships around full-service facade automation providers. Single-source responsibility for glazing, shading, and ventilation controls is displacing fragmented specification of discrete subsystems. This concentration is most visible in North American Class A office developments and European public-sector building modernization programs.
Window Automation Market Segmentation
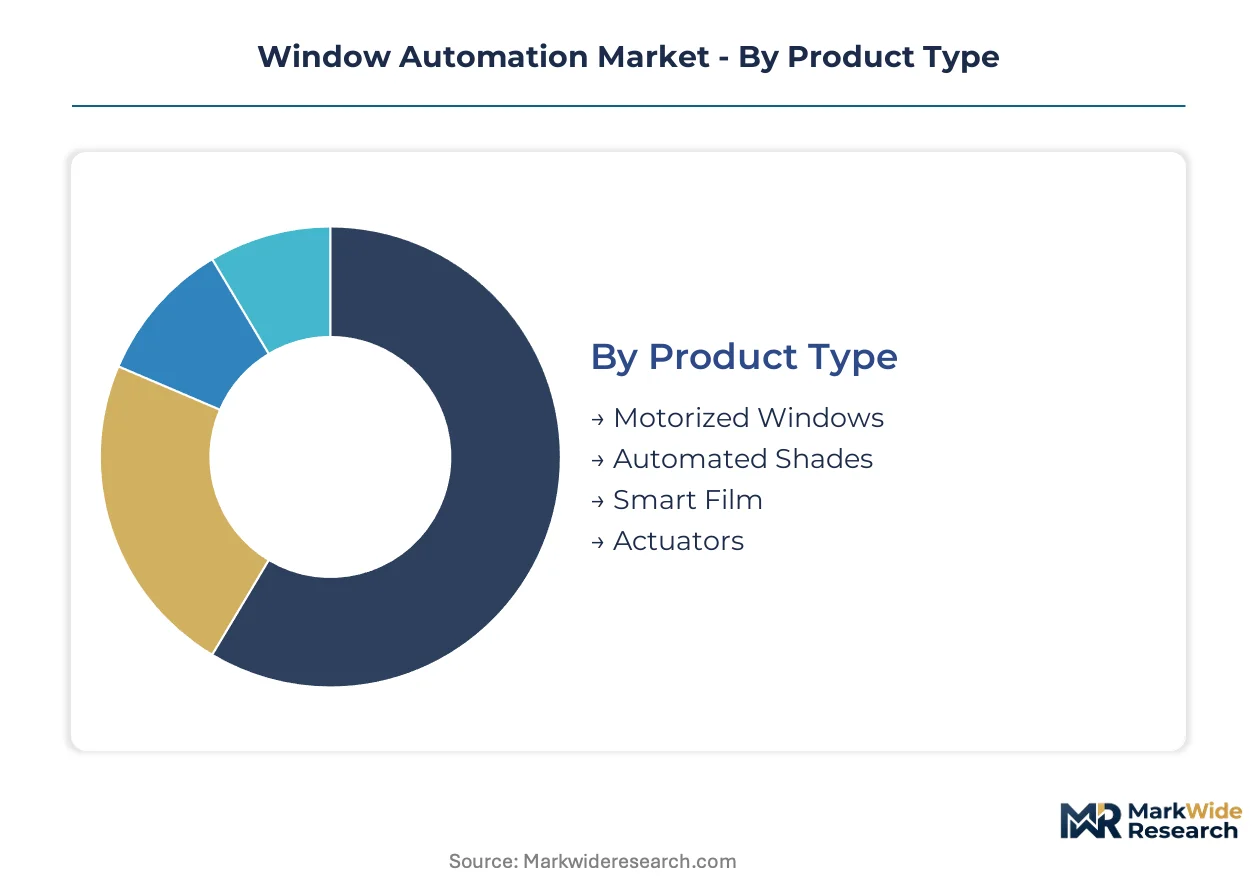
Window automation segmentation reflects divergent compliance burdens and performance specifications across building codes. Product architecture, connectivity protocols, and installation context determine margin structures and vendor positioning.
Product Type:
CE marking requirements under the EU Machinery Directive impose stricter safety validation on motorized opening systems than static shading products.
- Motorized Windows:Electromechanical systems integrating torque-rated linear actuators, position sensors, and bus-compatible control interfaces for automated natural ventilation. Demand concentrates in German, French, and Dutch commercial retrofits where the EU Green Deal mandates automated shading integration in large renovations.
- Automated Shades:Motorized roller and Venetian systems with radio or wired control for daylight harvesting. Penetration is deepest in North American LEED-certified office developments seeking BREEAM-equivalent performance credentials.
- Smart Film:Electrochromic and suspended particle device glazing with embedded tint control eliminating external hardware.
- Actuators:Standalone drive mechanisms supplying torque and linear force to legacy fenestration retrofits.
Motorized windows handle the majority of throughput; smart film is expanding most quickly on share as premium facades displace conventional shading.
Technology:
Protocol standardization separates premium integrated platforms from commodified standalone controls.
- IoT:Cloud-connected stacks enabling predictive maintenance, grid-responsive load management, and API integration with building management systems. BACnet and KNX native compatibility drives specification in premium European office developments.
- Smart Sensors:Ambient light, temperature, and CO2 detectors triggering automated responses without user intervention. Deployment concentrates in California and Texas utility demand response programs requiring embedded power curtailment capabilities.
- Remote Control:Handheld or wall-mounted transmitters operating on proprietary radio frequencies.
- Home Automation:Consumer-grade integration with voice assistants and residential hubs.
IoT-enabled systems command expanding margin pools; remote control faces steepest commoditization pressure in residential retrofits.
End User:
Procurement sophistication and specification authority vary sharply across customer types.
- Commercial:Facility managers and developers prioritizing unified facade management, energy certification compliance, and single-source vendor accountability. Class A office developments in London, New York, and Singapore drive electrochromic curtain wall specification.
- Residential:Homeowners and multifamily developers selecting automated shading for convenience and energy savings. Nordic markets in Sweden, Norway, and Denmark show underpenetration despite high construction quality standards.
- Industrial:Warehousing and manufacturing facilities requiring automated ventilation for air quality and thermal load management.
- Automotive:Sunroof and side-window automation in passenger vehicles and commercial transport.
Commercial end users dominate revenue concentration; residential retrofits in Northern Europe present the steepest expansion trajectory.
Application:
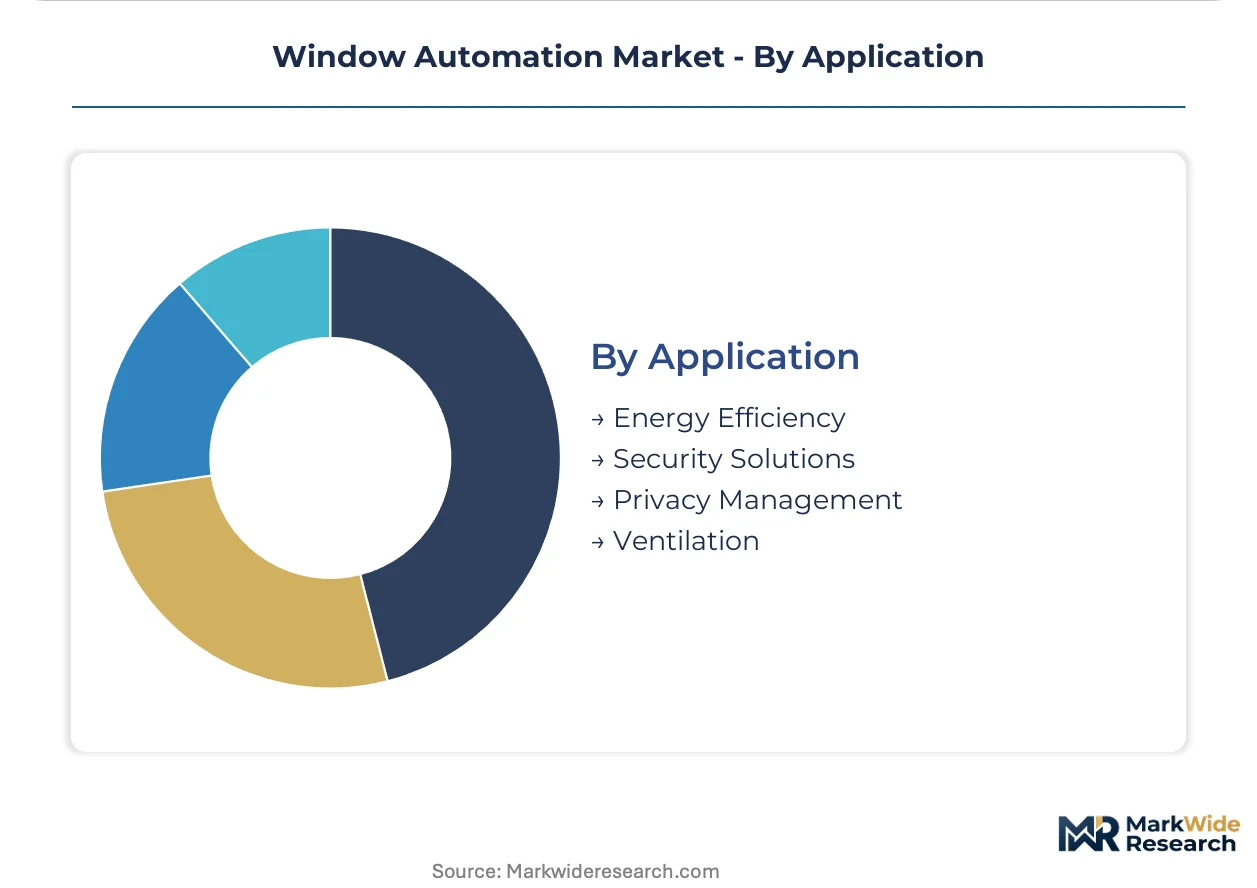
Regulatory tailwinds favor energy efficiency and ventilation automation over security and privacy use cases.
- Energy Efficiency:Automated daylight harvesting and thermal load reduction for building performance certification. Germany's federal building codes and France's RE2020 environmental regulations accelerate specification timelines.
- Ventilation:Programmable natural airflow to supplement mechanical HVAC and meet indoor air quality standards. Hospital patient rooms and operating suites in healthcare construction emerge as high-specification demand pockets.
- Security Solutions:Automated locking and intrusion detection integration with access control systems.
- Privacy Management:On-demand opacity control for conference rooms, healthcare settings, and residential bathrooms.
Energy efficiency applications absorb the largest share of investment; ventilation automation is climbing the fastest as post-pandemic air quality codes tighten.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany posts a window automation trade surplus driven by facade system exports to neighboring EU markets, while the United States relies on actuator imports from European and Asian suppliers to meet commercial retrofit demand.
Germany
Federal building codes mandate automated shading integration in large commercial renovations, pulling demand through retrofit channels. The EU Green Deal's Energy Performance of Buildings Directive tightens enforcement timelines for facade automation compliance. Industrial concentration centers on North Rhine-Westphalia, where integrated facade system suppliers cluster around Düsseldorf and Cologne.
United States
LEED certification pathways and utility demand response programs in California and Texas drive specification of grid-responsive window systems. FCC oversight governs wireless control module certification for commercial installations. The Pacific Northwest corridor, spanning Seattle and Portland, anchors smart building integration projects with native BACnet protocol adoption.
France
RE2020 environmental regulations accelerate automated natural ventilation requirements in new construction and major renovations. CE marking under the EU Machinery Directive imposes stricter safety validation on motorized opening systems. The Île-de-France region concentrates premium office development activity, with Parisian business districts specifying electrochromic curtain walls.
Netherlands
Building owners bundle window automation into comprehensive energy retrofit contracts to meet EU Green Deal performance standards. ECHA REACH compliance scrutiny affects cable assembly and housing material formulations. The Randstad metropolitan cluster, encompassing Amsterdam, Rotterdam, and The Hague, leads integrated facade management procurement.
China
Dual carbon goals and green building certification expansion create regulatory tailwinds for smart facade adoption in tier-one cities. GB standards and MIIT oversight govern electromechanical safety and electromagnetic compatibility for building automation equipment. The Yangtze River Delta, centered on Shanghai and Suzhou, concentrates premium commercial development specifying unified facade management platforms.
Window Automation Market Vendor Landscape
Concentration sits with electromechanical specialists and building technology conglomerates that command specification authority in commercial new construction. The vendor base organizes around three strategic archetypes: integrated facade platform providers, standalone actuator manufacturers, and smart shading system specialists. Competitive dynamics favor M&A activity targeting IoT connectivity capabilities and strategic partnerships with building management system vendors.
Within the integrated platform tier, ASSA ABLOY and Schneider Electric exemplify archetypes combining electromechanical hardware with digital control infrastructure. GEZE GmbH occupies a position among German precision engineering specialists focused on door and window drive systems. These anchors illustrate how geographic origin and corporate structure shape competitive positioning across European and North American specification channels.
| Leading Market Players |
|---|
| ASSA ABLOY |
| Allegion Plc |
| Nabtesco Corporation |
| Schüco International KG |
| GEZE GmbH |
| Somfy |
| Velux Group |
| Andersen Corporation |
| Schneider Electric |
| Others |
Supply Flow & Price Mechanics
CE marking under the EU Machinery Directive gates both supplier qualification and price differentiation in window automation, forcing vendors to absorb compliance overhead that separates certified electromechanical platforms from uncertified commodity actuators. This regulatory threshold simultaneously protects incumbent margins in commercial specification channels and compresses returns for undifferentiated residential retrofits.
Pricing Analysis
Industrial OEM buyers anchor project-based pricing structures across commercial new construction and large-scale retrofit deployments. Three-tier pricing stratifies across premium integrated facade platforms, standard bus-compatible systems, and economy remote-control units, with differentiation driven by BACnet/KNX certification level and after-sales service bundling. Cost compression in the economy tier intensifies as Chinese actuator imports flood residential channels. Facility managers in Class A office developments show lowest price sensitivity, prioritizing single-source vendor accountability over unit economics.
Supply Chain Analysis
Rare earth processing concentration in Chinese Inner Mongolia and Jiangxi provinces underwrites permanent magnet motor supply for linear actuators. Neodymium and dysprosium sourcing rests on concentrated refining capacity, while electronic control modules draw from Taiwanese semiconductor foundries and German precision sensor manufacturers. Single-source vulnerability in rare earth magnet supply creates input cost volatility that propagates through actuator pricing. Distribution runs through integrated facade system vendors in Düsseldorf and Cologne, regional building automation distributors in North America, and direct specification channels for premium electrochromic glazing projects.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The window automation market sits in early-cycle expansion as EU Green Deal building performance mandates create regulatory pull-through that outpaces pure technology diffusion curves. Penetration in commercial retrofits remains below saturation despite accelerating compliance timelines.
For Market Incumbents: Fortify specification authority in integrated facade platforms by deepening backward integration into sensor manufacturing and securing exclusive distribution partnerships with KNX/BACnet gateway providers. Electrochromic smart glass substitution threatens standalone motorized window margins, demanding preemptive platform consolidation around unified envelope management software stacks. For New Entrants and Emerging Players: Predictive maintenance service layers represent a critical gap where incumbents under-serve mid-market facility managers lacking in-house building automation expertise. Nordic residential markets in Sweden, Norway, and Denmark offer the steepest penetration trajectory given high construction quality standards and limited local competition. A retrofit-focused go-to-market angle emphasizing wireless installation and utility demand response program enrollment bypasses entrenched new construction specification channels. For Investors and Strategic Acquirers: France's RE2020 environmental regulation acceleration reshapes the acquisition landscape by elevating natural ventilation automation from optional premium to code-mandated infrastructure. Long-term viability favors platform vendors with native IoT connectivity and healthcare sector penetration rather than standalone hardware manufacturers. The signal to watch is hospital construction backlog growth in Germany and the Netherlands as ventilation automation specification tightens in operating suite and patient room design standards.| Strategic Initiative | Industry Significance |
|---|---|
| IoT Platform Integration | Native BACnet and KNX compatibility secures specification in premium European office developments. |
| Backward Integration into Sensors | In-house production of position feedback systems protects margins against electromechanical complexity premiums. |
| Healthcare Sector Partnership | Hospital system relationships unlock high-specification demand for touchless ventilation automation in patient rooms. |
| Grid-Responsive Capability Development | Embedded power curtailment features qualify systems for California and Texas utility demand response programs. |
| Nordic Market Expansion | Direct distribution buildout in Sweden and Denmark captures underpenetrated residential retrofit demand. |
Methodological Framework
Two parallel data streams informed the analysis: structured primary interviews with facility management directors, electromechanical engineering leads at facade system vendors, building automation integrators, and healthcare construction procurement officers; and secondary validation through EU Energy Performance of Buildings Directive implementation tracking, REACH substance restriction updates, SEC filings from listed building technology conglomerates, and customs trade data on actuator imports. Bottom-up shipment modeling and top-down construction spend allocation triangulated market sizing across product categories.
Across the projection horizon, the analytical framework modeled volume and value outputs by product architecture, connectivity protocol tier, end-user procurement sophistication, application compliance burden, and regional regulatory enforcement intensity. CAGRs derived from segment-level growth rate synthesis weighted by construction pipeline data and retrofit incentive program budgets. Forecast inputs incorporated rare earth magnet price indices, hospital construction permit flows, and utility demand response program enrollment trajectories.
Underlying assumptions cover sustained EU Green Deal enforcement, stable rare earth supply chain configuration, and continued BACnet/KNX protocol standardization, with deviation risk concentrated in REACH substance restriction expansion and potential tariff disruption on Chinese electronic components. Practitioners should keep alternative scenarios live as building code acceleration timelines and healthcare ventilation standards evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automation
Smart Home Automation Market
Automation
Global Direct Mail Automation Software Market
Automation
Global Automated Sample Storage Systems Market
Automation
Asia-Pacific Micro Fulfillment Market
Automation
Home Automation System Market
Automation
Global Business Process Automation Software Market
Automation
Universal Process Control Market
Automation
Global Field Force Automation Market
Automation
Process Automation Market
Automation
Global Door and Window Automation Market
Automation
Lab Automation Market
Automation
US Workload Scheduling and Automation Market
Automation
North America Home Automation Systems Market
Automation
Laboratory Automation Market
Automation
Workflow Automation Market
Automation
AR Automation Market