
 Mexico Beauty and Personal Care Market | 2026-2036
Mexico Beauty and Personal Care Market Size, Share, and Industry Trends Forecast 2026-2036
Mexico Beauty and Personal Care Market Outlook
Cosmetic chemist talent is rotating toward digital formulation labs and sustainable ingredient sourcing, tightening supply for traditional manufacturing roles. L'Oréal SA leverages its Celaya production hub to anchor North American distribution networks. Natura & Co differentiates through its direct-sales consultant base across secondary cities. Procter & Gamble Co. sustains mass-market penetration via pharmacy and supermarket shelf dominance.
Beauty and personal care encompasses topical formulations for skin, hair, color cosmetics, and scent designed to cleanse, protect, or enhance human appearance, typically requiring stability testing at elevated temperatures and controlled humidity to ensure shelf life in tropical climates. The sector serves retail consumers, licensed estheticians, and hospitality operators seeking efficacy and sensory performance. Skin care commands the largest margin pool as consumers prioritize active-ingredient transparency and dermatological endorsement. Hair care competes on salon professional loyalty and keratin treatment specialization. Makeup growth concentrates in online retail channels where virtual try-on technology reduces return rates.
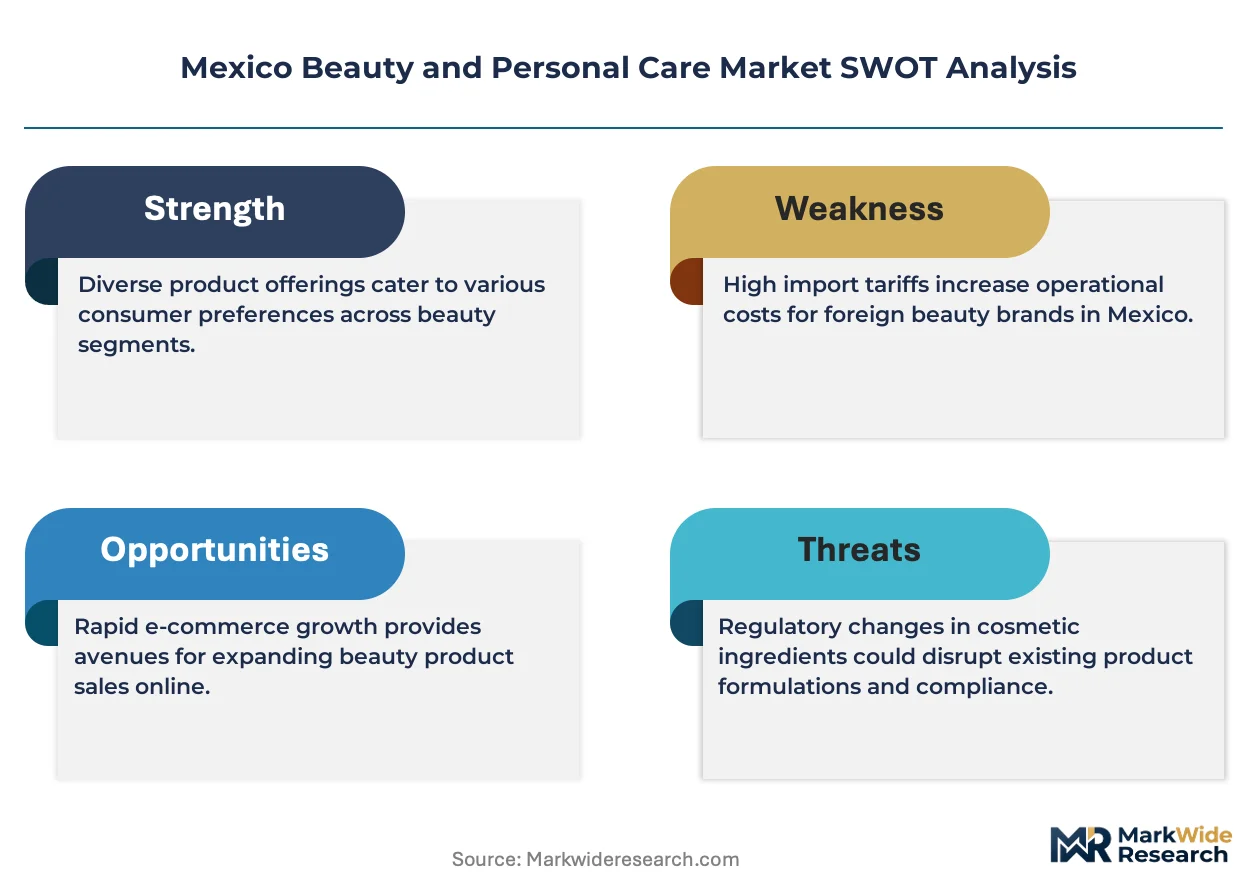
COFEPRIS mandates full ingredient disclosure and prohibits specific preservatives, forcing reformulation cycles across imported and domestic portfolios. PROFECO price monitoring and advertising standards constrain promotional claims while NOM standards govern product safety testing protocols. Stakeholders must weigh regulatory compliance investments against the speed of clean-beauty positioning demanded by younger consumer cohorts.
Market Dynamics
COFEPRIS ingredient disclosure mandates and PROFECO advertising standards are compressing formulation cycles while elevating compliance costs across domestic and imported portfolios. Manufacturers must reconcile regulatory timelines with clean-beauty positioning demanded by younger urban cohorts.
Growth Catalysts
- Direct-to-consumer digital channels:Virtual try-on tools and social commerce platforms reduce return rates and accelerate conversion among Gen Z buyers in Mexico City and Guadalajara.
- NOM safety testing alignment:Harmonized protocols with US FDA standards lower re-certification burdens for cross-border manufacturers operating Celaya production hubs.
- Professional salon channel expansion:Keratin treatment specialization and licensed esthetician networks concentrate demand in Bajío and northern border states.
Market Restraints
- Cosmetic chemist supply tightness:Talent rotation toward digital formulation labs and sustainable sourcing roles constrains traditional manufacturing recruitment.
- Import dependency for active ingredients:Concentrated sourcing of peptides and retinoids from Asian suppliers exposes margins to currency volatility and shipping disruptions.
- Preservative prohibition scope:COFEPRIS bans on specific stabilizers force reformulation of legacy SKUs without guaranteed efficacy equivalence.
Strategic Opportunities
- Secondary city consultant networks:Underpenetrated direct-sales infrastructure in Querétaro, León, and Mérida offers scalable penetration without competing for saturated Mexico City shelf space.
- Pharmacy channel professionalization:Dermocosmetic positioning through Farmacias Guadalajara and Benavides chains elevates margin capture versus mass-market supermarket placement.
- Biodegradable packaging mandates:Anticipated PROFECO environmental labeling rules create first-mover advantage for domestic suppliers with captive recycled material streams.
Industry Challenges
- Stability testing infrastructure gaps:Accelerated aging protocols at elevated temperature and humidity require capital investment in climate-controlled validation labs that mid-tier formulators lack.
- Ingredient traceability complexity:Multi-tier supplier documentation for clean-beauty claims demands ERP integration that legacy domestic manufacturers struggle to implement.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mexico Beauty and Personal Care Market |
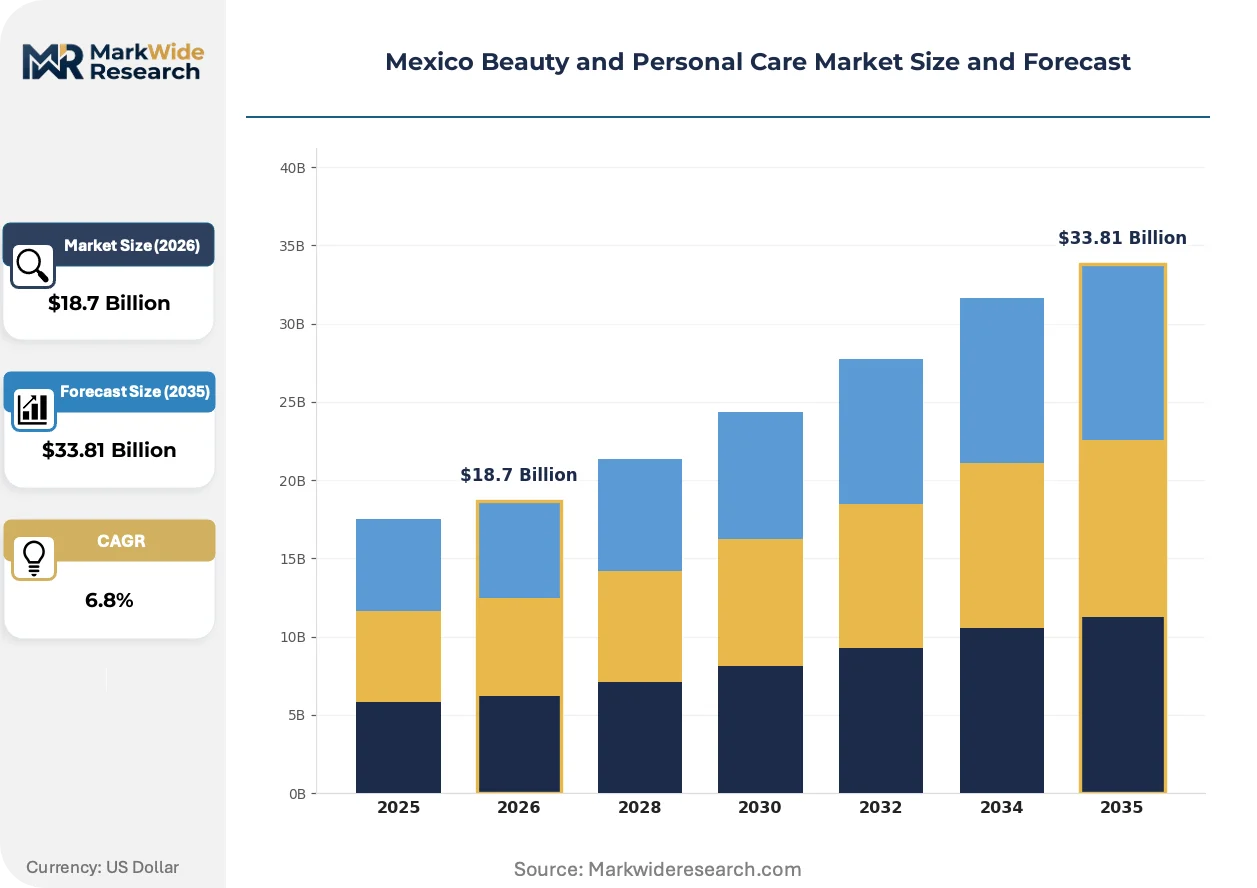
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $33.81 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Skin Care, Hair Care, Makeup, Fragrance Customer Type: Retail Consumers, Salons, Estheticians, Spas Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Pharmacies End Use: Personal Use, Professional Use, Gift, Travel |
| Companies Covered | Colgate-Palmolive Co., Beiersdorf AG, L'Oréal SA, Estee Lauder Inc., Johnson & Johnson Services Inc., Unilever PLC, Natura & Co, Mary Kay Inc., Procter & Gamble Co., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mexico Beauty and Personal Care Market Strategic Shifts
Active-ingredient transparency and dermatological endorsement are compressing traditional marketing hierarchies while elevating efficacy claims verification. Technology convergence between biotech sourcing and digital retail is reconfiguring competitive positioning.
Encapsulation technology for retinol and vitamin C stabilization is miniaturizing delivery systems to enhance bioavailability without compromising shelf stability. Premium skin care brands serving licensed estheticians are adopting these formats to justify professional-grade pricing. The structural consequence is compression of conventional emulsion-based product lines that lack comparable active protection.
COFEPRIS expanded its prohibited substance list to align with EU REACH Annex XVII restrictions on certain parabens and formaldehyde releasers. Domestic manufacturers must complete reformulation cycles ahead of enforcement deadlines or face import suspension. Color cosmetics and hair care segments with legacy preservative systems are accelerating alternative validation timelines.
Subscription replenishment models for core skin care routines are displacing episodic retail purchasing among urban professionals. Pharmacy and specialty e-commerce platforms capture recurring revenue that supermarkets cannot replicate. This pattern concentrates in Mexico City and Monterrey where delivery infrastructure supports predictable restocking intervals.
Mexico Beauty and Personal Care Market Segmentation
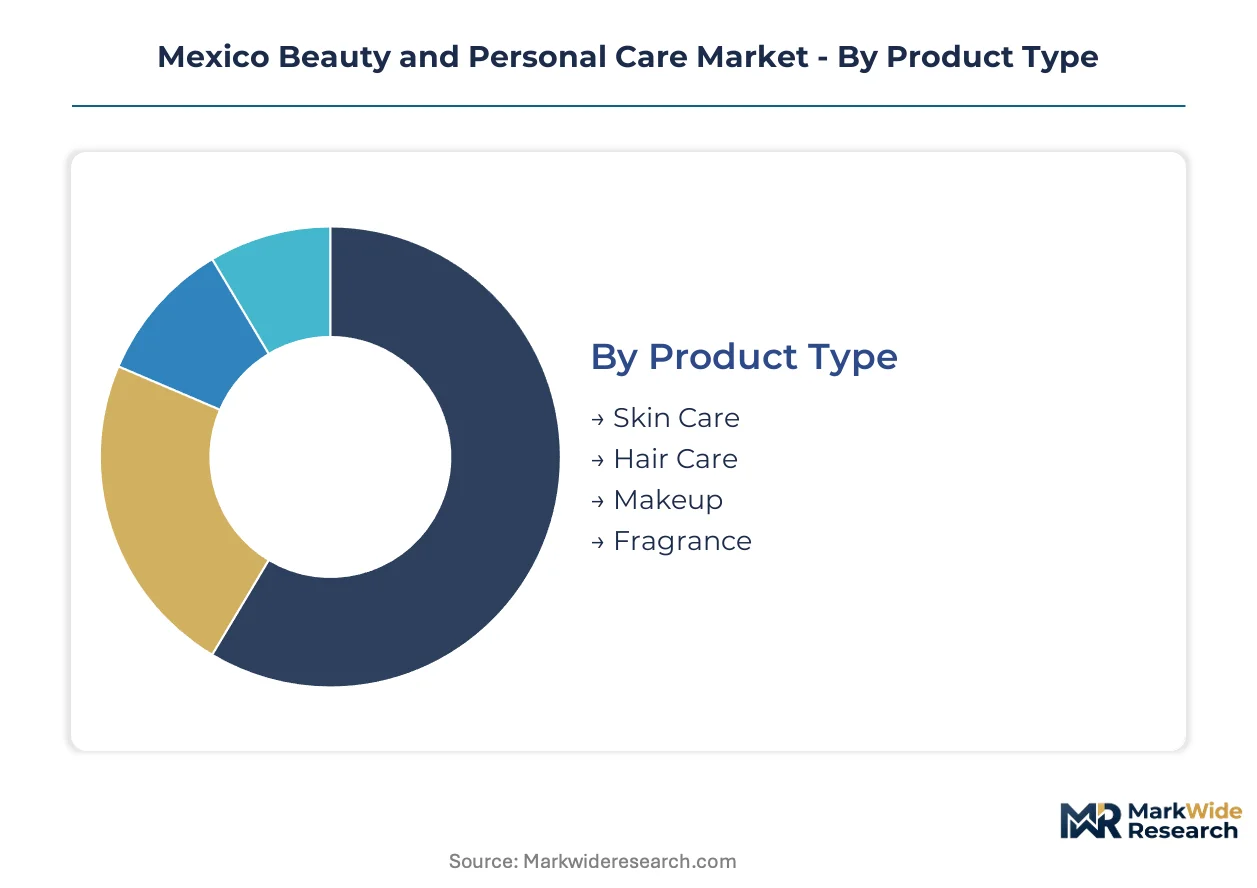
Segmentation in the Mexico market reflects regulatory pressure from COFEPRIS disclosure mandates and PROFECO advertising standards that reshape how products reach distinct buyer groups. Formulation cycles, channel strategies, and pricing architecture all diverge across these boundaries.
Product Type:
COFEPRIS ingredient disclosure mandates and preservative prohibitions hit each category with asymmetric compliance burdens, forcing portfolio-specific reformulation timelines.
- Skin Care:Active-ingredient transparency requirements elevate dermatological endorsement as a competitive filter. Concentrated demand among young urban professionals in Mexico City and Guadalajara prioritizes peptide and retinoid formulations despite import dependency for these actives.
- Hair Care:Keratin treatment specialization drives salon professional loyalty, particularly in Bajío and northern border states where licensed technician networks concentrate. Legacy preservative systems face accelerated replacement timelines under expanded COFEPRIS prohibited substance lists.
- Makeup:Virtual try-on technology reduces return rates in digital channels. Color cosmetics with legacy stabilizers require reformulation ahead of enforcement deadlines.
- Fragrance:Shelf stability testing at elevated tropical humidity shapes formulation architecture. Mass-market positioning competes on supermarket shelf dominance.
Skin Care handles the majority of throughput; Makeup is expanding most quickly on share.
Customer Type:
Margin capture and purchase frequency diverge sharply across these buyer groups, with professional channels commanding premium pricing but requiring specialized distribution infrastructure.
- Retail Consumers:Episodic purchasing patterns in supermarkets are displacing toward subscription replenishment models in Mexico City and Monterrey where delivery infrastructure supports predictable restocking.
- Salons:Licensed professional networks in Guadalajara and Monterrey drive keratin treatment and color service demand. Technician certification requirements elevate barrier to channel entry.
- Estheticians:Professional-grade skin care procurement concentrates in dermocosmetic-positioned pharmacy chains. Active-ingredient transparency mandates reshape supplier qualification criteria.
- Spas:Hospitality operator procurement prioritizes sensory performance and bulk packaging economics. Secondary city expansion in Mérida and Querétaro creates new addressable demand.
Retail Consumers anchor volume throughput; Estheticians are climbing the fastest on margin contribution.
Distribution Channel:
Channel selection determines compliance documentation burden and promotional claim latitude under PROFECO monitoring regimes.
- Online Retail:Social commerce platforms and virtual try-on tools accelerate Gen Z conversion in Mexico City. Return rate reduction from augmented reality validation improves unit economics.
- Supermarkets:Mass-market shelf dominance sustains volume but constrains margin capture. Price monitoring from PROFECO limits promotional flexibility.
- Specialty Stores:Curated assortment and consultant-guided selling justify premium positioning. Secondary city penetration lags primary metro corridors.
- Pharmacies:Farmacias Guadalajara and Benavides chains professionalize dermocosmetic placement. Recurring revenue models from core routine replenishment outperform episodic retail.
Supermarkets handle the majority of throughput; Pharmacies are gaining share fastest on margin expansion.
End Use:
Usage occasion shapes packaging format, stability testing protocols, and regulatory documentation requirements.
- Personal Use:Daily regimen products require tropical climate validation at elevated temperature and humidity. COFEPRIS safety testing alignment with US FDA standards lowers re-certification burdens for cross-border manufacturers.
- Professional Use:Licensed technician application demands bulk sizing and efficacy documentation. Salon channel concentration in Bajío states elevates regional logistics requirements.
- Gift:Seasonal demand spikes strain inventory planning. Premium positioning depends on packaging aesthetics and ingredient transparency claims.
- Travel:Miniaturized formats compete on TSA compliance and shelf stability in variable climates. Airport retail and hospitality amenity channels concentrate demand.
Personal Use handles the majority of throughput; Professional Use shows the steepest expansion trajectory on service economy growth.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
COFEPRIS ingredient disclosure mandates and PROFECO advertising standards anchor Mexico's regulatory framework, shaping formulation cycles and compliance investments across sub-regional markets with distinct demand profiles and channel concentrations.
Mexico City Metro
Young urban professionals drive premium skin care adoption with peptide and retinoid formulations. COFEPRIS safety testing protocols require tropical climate validation for shelf stability claims. Polanco and Condesa districts concentrate dermocosmetic boutique density and subscription replenishment model penetration.
Nuevo León
Monterrey's professional class sustains pharmacy channel growth for core routine products. PROFECO price monitoring constrains promotional flexibility in supermarket placements. San Pedro Garza García anchors specialty store expansion with consultant-guided selling formats.
Jalisco
Guadalajara's licensed esthetician networks elevate professional-grade procurement through Farmacias Guadalajara chains. NOM standards alignment with US FDA lowers re-certification burdens for cross-border manufacturers. Zapopan corridors concentrate salon professional demand for keratin treatment specialization.
Bajío Region
Querétaro and León present underpenetrated direct-sales infrastructure for scalable consultant network expansion. COFEPRIS preservative prohibitions force accelerated reformulation of legacy hair care SKUs. Celaya production hub anchors North American distribution logistics for multinational portfolios.
Northern Border States
Tijuana and Ciudad Juárez leverage cross-border consumer traffic for dual-market product registration strategies. Import dependency for Asian-sourced active ingredients exposes margins to currency volatility. Matamoros and Reynosa concentrate professional salon channel demand from maquiladora workforce segments.
Mexico Beauty and Personal Care Market Competitive Environment
Technology leadership and cost leadership are held by different player archetypes, with multinational R&D-intensive specialists competing against mass-market scale operators and direct-sales network builders. The market structure reflects tiered consolidation: three to four global conglomerates anchor premium and mass segments while regional consultants and domestic formulators fill specialty niches. Strategic archetypes include dermatological endorsement specialists, supply-chain-integrated mass producers, and relationship-driven direct-sales platforms. Dominant competitive moves center on pharmacy channel professionalization and sustainable packaging pre-positioning ahead of anticipated environmental labeling mandates.
Within the multinational conglomerate tier, L'Oréal SA and Procter & Gamble Co. exemplify divergent scale strategies, with the former leveraging production hub integration and the latter sustaining mass-market shelf dominance. Natura & Co occupies a distinct position through consultant-based relationship selling across secondary cities. These three anchors represent the primary competitive archetypes: R&D-driven premium positioning, supply-chain-optimized mass penetration, and network-amplified direct distribution.
| Leading Market Players |
|---|
| Colgate-Palmolive Co. |
| Beiersdorf AG |
| L'Oréal SA |
| Estee Lauder Inc. |
| Johnson & Johnson Services Inc. |
| Unilever PLC |
| Natura & Co |
| Mary Kay Inc. |
| Procter & Gamble Co. |
| Others |
Value Chain & Pricing Dynamics
Biodegradable packaging substrate substitution for conventional petroleum-derived plastics simultaneously redraws supplier geography toward domestic recycled material processors and compresses margin structures for importers lacking captive recycling streams. COFEPRIS disclosure mandates and PROFECO environmental labeling anticipation force dual-cost accounting across legacy and next-generation formulations.
Pricing Analysis
Pharmacy-supermarket price spreads widen 40-60% across identical SKUs, with Farmacias Guadalajara and Benavides commanding premium positioning through dermocosmetic certification tier and licensed esthetician endorsement. Three-tier pricing structure across premium, standard, and economy levels stratifies by active-ingredient concentration and dermatological backing rather than brand heritage alone. Cost compression in mass-market tiers intensifies as supermarket price monitoring limits promotional latitude. Retail consumers in secondary cities exhibit highest price sensitivity; licensed professionals in Monterrey and Guadalajara demonstrate lowest.
Supply Chain Analysis
China and South Korea anchor peptide and retinoid active ingredient production, while domestic Celaya manufacturing clusters concentrate final formulation and North American distribution. Mexican portfolios draw from Asian-sourced actives, European fragrance compounds, and domestic aloe and agave extracts for regional positioning. Single-source vulnerability for retinoid precursors exposes margins to shipping disruption and currency fluctuation. Distribution runs through pharmacy chains and direct-sales consultant networks, with e-commerce platforms capturing fastest-growing downstream share.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Mexico beauty and personal care market is exiting a regulatory adjustment cycle as COFEPRIS enforcement deadlines pass and reformulation investments convert to shelf-ready SKUs. Urban consumption recovery in Mexico City and Monterrey validates premium positioning bets placed during compliance-heavy years.
For Market Incumbents: Secure pharmacy channel professionalization through exclusive dermocosmetic placement agreements with Farmacias Guadalajara and Benavides before shelf space saturates. Deepen backward integration into domestic biodegradable packaging substrate production to preempt PROFECO environmental labeling cost penalties. Threat of direct-sales network expansion from Natura-type consultants demands preemptive consultant recruitment in Querétaro and León. For New Entrants and Emerging Players: Differentiate on COFEPRIS pre-certified clean-beauty positioning to bypass 18-month reformulation timelines burdening legacy portfolios. White-space concentration sits in secondary city esthetician supply to underpenetrated Mérida and Querétaro spa segments. Go-to-market angle: subscription replenishment partnerships with regional pharmacy chains bypassing Mexico City customer acquisition cost inflation. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed domestic formulators holding COFEPRIS-compliant SKU libraries but lacking pharmacy channel access. Long-term viability centers on regulatory compliance as a moat against Asian import competition. Signal to watch: accelerated hiring of cosmetic chemists with digital formulation lab experience indicates portfolio refresh velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Pharmacy Channel Professionalization | Farmacias Guadalajara exclusive placement elevates margin capture above supermarket tiers. |
| Biodegradable Packaging Transition | Domestic recycled substrate sourcing preempts PROFECO environmental labeling mandates. |
| Direct-Sales Network Expansion | Consultant recruitment in Querétaro and León accesses underpenetrated secondary city demand. |
| Active Ingredient Sourcing Diversification | Reduced reliance on Chinese peptide suppliers mitigates currency and logistics volatility. |
| Subscription Replenishment Platform Launch | Recurring revenue models through pharmacy e-commerce displace episodic supermarket purchasing. |
Study Parameters
Cross-validation between primary interviews with cosmetic chemists, pharmacy category buyers, and licensed esthetician network managers anchors the qualitative findings against secondary validation. Regulatory affairs specialists at COFEPRIS and brand managers at multinational formulators provided compliance timeline and reformulation cost perspectives. Secondary sources span COFEPRIS prohibited substance registry updates, PROFECO advertising standard enforcement records, Nielsen retail audit data for pharmacy and supermarket channels, and customs import records for active ingredient shipments. Bottom-up SKU-level volume builds triangulate against top-down category expenditure estimates from household consumption surveys.
Sensitivity analysis tests forecast outputs against variable regulatory enforcement intensity and alternative GDP growth assumptions across the projection horizon. Segmentation dimensions modeled include product type, customer archetype, distribution channel, and end-use occasion, with regional cluster differentiation for Mexico City, Nuevo León, Jalisco, Bajío, and northern border states. CAGRs derive from regression-weighted historical trajectory analysis adjusted for structural break points at COFEPRIS mandate implementation. Industry-specific inputs capture cosmetic chemist wage inflation and biodegradable packaging substrate cost curves.
The analysis sits within stated boundaries; outcomes outside sustained COFEPRIS enforcement intensity or accelerated PROFECO environmental rulemaking would require recalibration. Forecasts reflect assumptions regarding urban consumption recovery trajectory and pharmacy channel expansion velocity. Specific risks that could revise projections include retinoid supply disruption from Asian sourcing concentration and accelerated preservative prohibition expansion beyond current COFEPRIS lists. Recalibration cycles align with material shifts in regulatory enforcement patterns and primary city consumption indicators.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Beauty & Personal Care
Facial Makeup Setting Spray Market
Beauty & Personal Care
Global Massage Oil Market
Beauty & Personal Care
UV Nail Gel Market
Beauty & Personal Care
Brazil Beauty and Personal Care Products Market
Beauty & Personal Care
Facial Wipes Market
Beauty & Personal Care
Europe Beauty and Personal Care Products Market
Beauty & Personal Care
Asia-Pacific Perms and Relaxants Market
Beauty & Personal Care
Shaving and Hair Removal Products Market
Beauty & Personal Care
Global Bath Salts Market
Beauty & Personal Care
Global Organic Personal Care Products Market
Beauty & Personal Care
Body Firming Creams Market
Beauty & Personal Care
Women Intimate Care Products Market
Beauty & Personal Care
South America E-Commerce Skin Care Products Market
Beauty & Personal Care
Cosmetics and Personal Care Stores Market
Beauty & Personal Care
Hair Removal Creams for Private Parts Market
Beauty & Personal Care
At-Home Beauty Devices Market