
 Global Body Wash and Shower Gel Market | 2026-2036
Global Body Wash and Shower Gel Market Size, Share, and Industry Trends Forecast 2026-2036
Global Body Wash and Shower Gel Market Analysis
Project finance tied to contract manufacturing networks is reconfiguring competitive entry barriers for mid-sized brands. Unilever PLC leverages its captive supply of surfactant chemicals across multiple continents. Henkel AG & Co. KGaA anchors European production through centralized batching facilities. L'Oréal S.A. differentiates via dermatological testing protocols that command pharmacy shelf placement.
Body wash and shower gel denotes a surfactant-based liquid cleansing formulation with pH typically balanced between 5.5 and 6.5, designed for epidermal application during water-based hygiene routines. These products employ mild anionic or amphoteric surfactants combined with emollients to remove sebum and environmental contaminants without stripping the stratum corneum. Gel formats dominate volume throughput in supermarket channels due to pump-dispenser compatibility and lower unit cost per use. Natural ingredient positioning commands price premiums in specialty stores where consumers prioritize botanical extract disclosure. Pharmacy distribution gravitates toward antibacterial variants carrying clinical endorsement claims.
FDA cosmetic labeling requirements and the EU REACH framework govern surfactant safety assessments, while India's BIS standards mandate preservative concentration ceilings. These regulations elevate compliance costs for synthetic formulation producers while creating certification advantages for brands meeting multiple jurisdictional standards. Stakeholders must monitor evolving state-level restrictions on microplastic additives in cleansing formulations across key manufacturing jurisdictions.
Market Dynamics
Surfactant chemistry convergence with hospitality amenity specifications is compressing formulation cycles, forcing manufacturers to reconcile bulk industrial production with premium dispenser-compatible viscosity and fragrance stability requirements.
Growth Catalysts
- EU REACH surfactant disclosure mandates:These frameworks accelerate transparency investments by multinationals, creating certification barriers that filter out informal competitors and consolidate shelf access for compliant brands.
- Urban pharmacy retail density in Brazil:Concentrated distribution networks in São Paulo and Rio de Janeiro enable rapid SKU turnover and direct consumer education at point-of-purchase.
- Post-pandemic hygiene protocol institutionalization:Healthcare-adjacent facilities and hospitality chains now mandate liquid cleanser availability, embedding body wash into facility operating standards.
Market Restraints
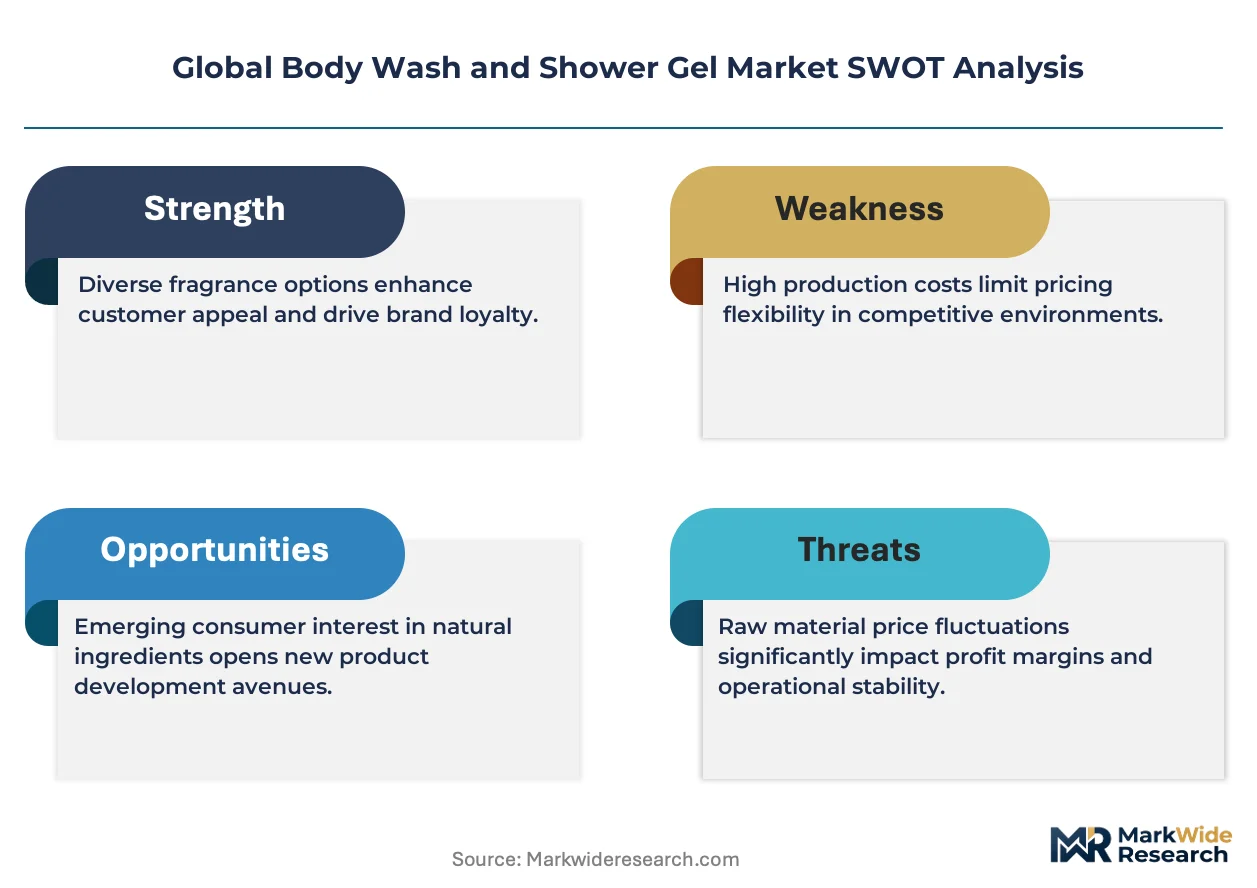
- Palm kernel oil and coconut-derived surfactant price volatility:Tropical weather disruptions and biodiesel policy competition in Southeast Asia inject raw material cost instability into margin structures.
- China surfactant intermediate concentration:Over half of global sodium lauryl ether sulfate capacity clusters in Guangdong and Jiangsu provinces, exposing brands to single-jurisdiction supply risk.
- India BIS preservative ceiling restrictions:Methylisothiazolinone concentration limits below EU thresholds force reformulation or market exclusion for standard global SKUs.
Strategic Opportunities
- Indonesia hospitality construction pipeline:New resort and business hotel developments in Bali and Jakarta create captive demand for bulk amenity programs with 5-year supply contracts.
- Biodegradable surfactant-microbial fermentation convergence:Rhamnolipid and sophorolipid biosurfactants from sugar feedstocks offer regulatory pre-qualification for EU microplastic restrictions.
- Direct-to-hotel refill systems:IoT-enabled dispenser monitoring and automated replenishment logistics bypass traditional retail markups while locking in recurring revenue.
Industry Challenges
- Cosmetic chemist talent scarcity:Formulation expertise bridging dermatological safety, fragrance chemistry, and manufacturing scale resides in a narrow pool concentrated in Basel, Paris, and Mumbai.
- Multi-jurisdiction label compliance synchronization:Simultaneous FDA, REACH, and BIS disclosure requirements demand parallel documentation systems with conflicting ingredient nomenclature standards.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Body Wash and Shower Gel Market |
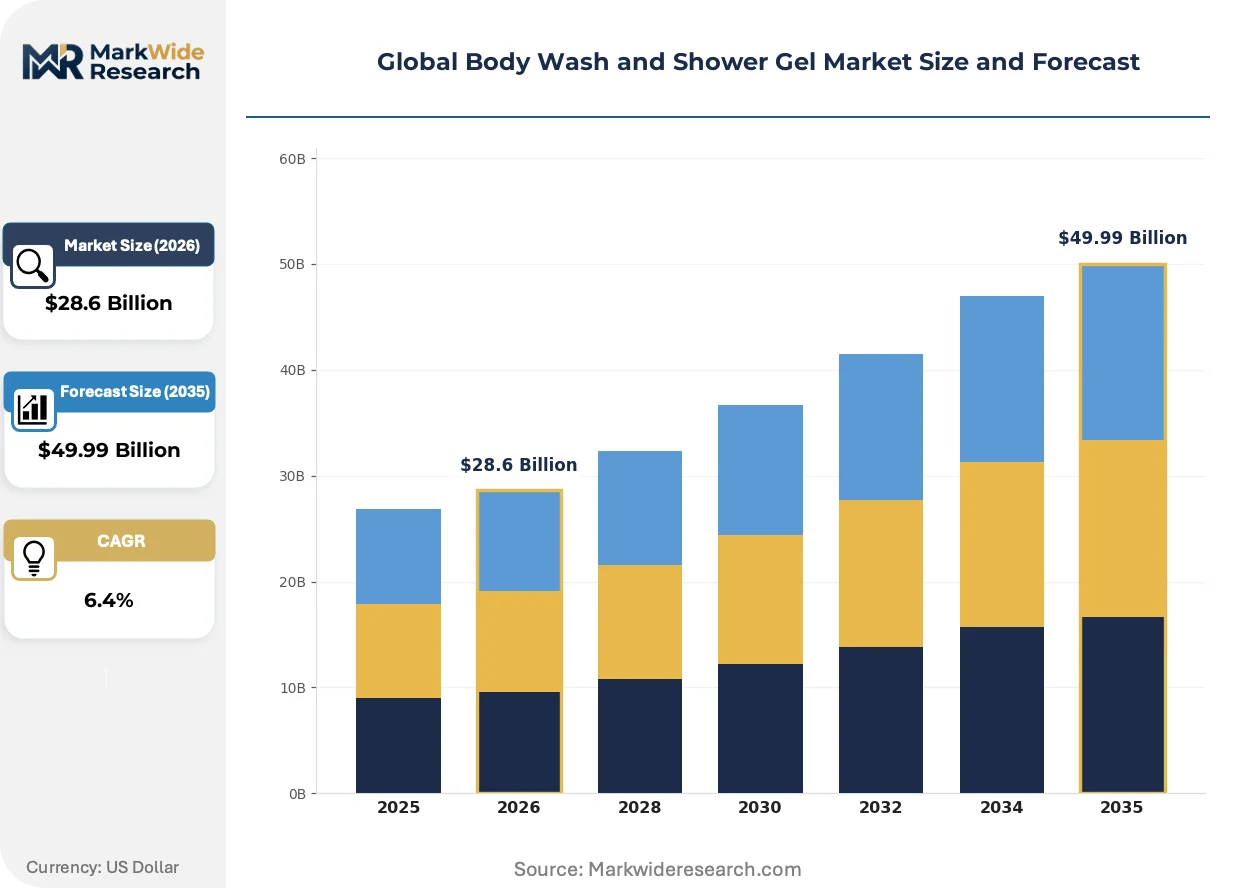
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $49.99 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Gel, Foam, Liquid, Cream Ingredient: Natural, Synthetic, Ayurvedic, Antibacterial Distribution Channel: Online Retail, Supermarket, Specialty Store, Pharmacy End User: Men, Women, Children, Seniors |
| Companies Covered | Beiersdorf AG, Johnson & Johnson Consumer Inc., Unilever PLC, Kao Corporation, Reckitt Benckiser Group PLC, The Procter & Gamble Company, Colgate-Palmolive Company, Henkel AG & Co. KGaA, L'Oréal S.A., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Body Wash and Shower Gel Market Emerging Trajectories
Waterless and solid-format cleansing alternatives are pressuring conventional liquid formulations, while regulatory microplastic bans and hospitality sustainability mandates accelerate packaging and chemistry reinvention.
Concentrated anhydrous cleansing pastes is migrating from niche zero-waste retailers to mainstream hospitality procurement. These formulations eliminate water weight from shipping and activate upon contact with shower water. Marriott and Accor pilot programs in Germany and France are validating dispenser-compatible paste extrusion systems. The technology is migrating from environmental positioning to total-cost-of-ownership calculations as logistics savings compound.
California's microbead-free waters act and pending state-level restrictions on synthetic polymer thickeners are forcing reformulation of gel viscosity builders. Manufacturers are substituting cellulose derivatives and sclerotium gum for carbomer and acrylate copolymers. Premium pharmacy lines in Los Angeles and San Francisco are first-movers, with reformulated SKUs appearing six to nine months ahead of compliance deadlines to capture early-adopter positioning.
Subscription-based replenishment for residential body wash is displacing supermarket impulse purchases among urban millennials in London, Toronto, and Melbourne. Algorithmic scent profiling and seasonal rotation reduce decision fatigue while building brand lock-in. The model concentrates demand forecasting accuracy for contract manufacturers and compresses working capital cycles for direct-to-consumer brands with captive formulation capacity.
Global Body Wash and Shower Gel Market Segmentation
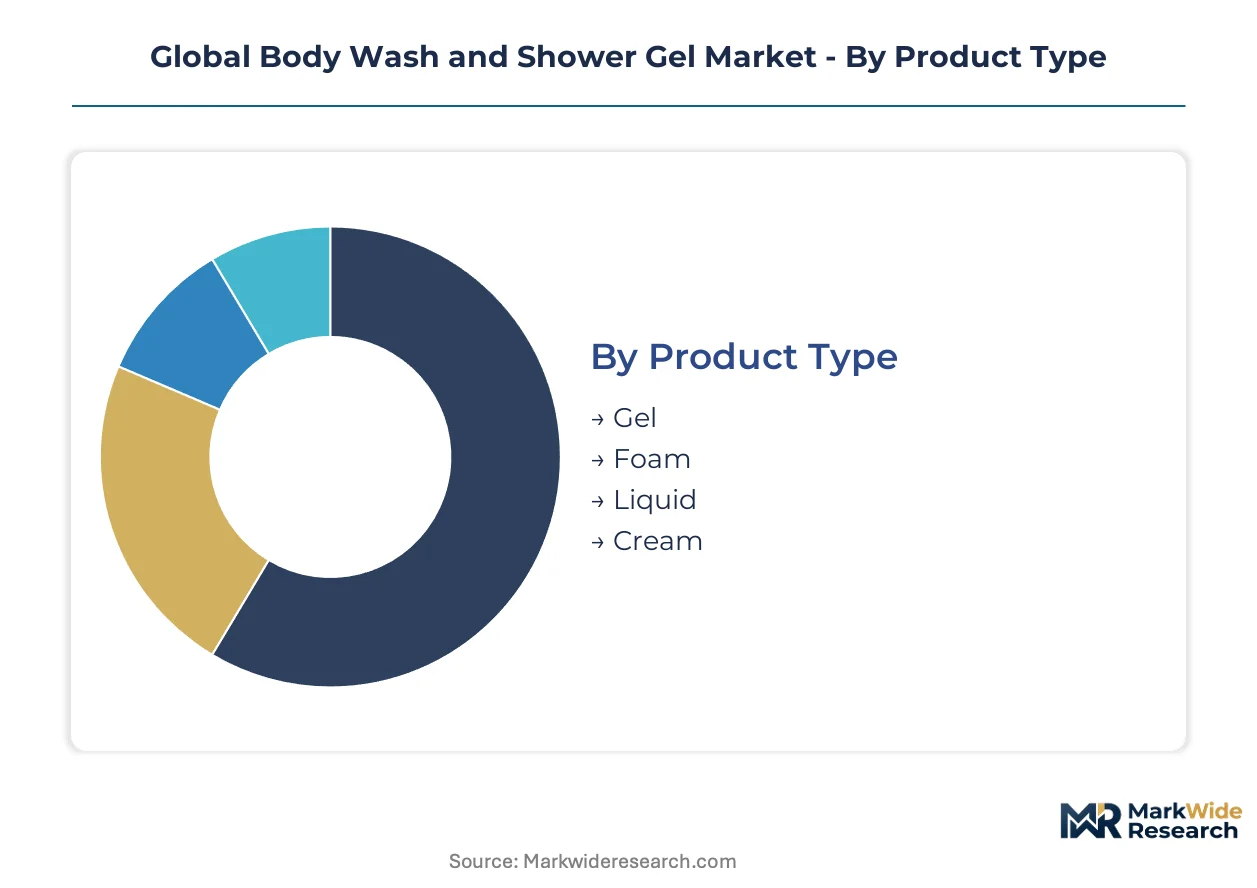
Product architecture in body wash and shower gel determines manufacturing scale, surfactant selection, and dispenser compatibility. Segmentation by formulation chemistry, procurement channel, and demographic targeting reveals where margin pools concentrate and where reformulation investments yield shelf access.
Product Type:
Volume throughput and packaging compatibility separate formats by cost tier and channel placement.
- Gel:Thixotropic formulations with carbomer or cellulose-derived viscosity builders enable precise pump dispensing. Brazilian pharmacy chains and Southeast Asian hospitality bulk programs drive concentrated demand for this format.
- Liquid:Lower viscosity surfactant solutions dominate supermarket private-label SKUs due to simpler filling equipment and reduced packaging material per unit. India's tightening BIS preservative rules force reformulation of standard liquid bases for compliance.
- Foam:Pre-foamed dispersions require specialized aeration packaging and command premium positioning in specialty retail.
- Cream:High-emollient body cleansers target dry-skin demographics with lipid-replenishing claims in European pharmacy channels.
Gel commands the established base. The steepest expansion runs through liquid formats as private-label manufacturing scales.
Ingredient:
Regulatory pre-qualification and sourcing geography determine which chemistry platforms access premium shelf placement.
- Synthetic:Sodium lauryl ether sulfate and cocamidopropyl betaine formulations deliver consistent foaming and cost efficiency. China's concentration of intermediate production in Guangdong and Jiangsu provinces exposes brands to single-jurisdiction supply risk.
- Natural:Plant-derived surfactants from coconut and palm kernel oils carry EU REACH disclosure advantages and command price premiums in specialty stores. Tropical weather disruptions in Indonesia and Malaysia inject raw material cost instability.
- Antibacterial:Triclosan-restricted markets now deploy benzalkonium chloride or essential oil alternatives for clinical endorsement claims.
- Ayurvedic:Herb-infused formulations with neem, tulsi, and sandalwood extracts target domestic Indian demand and diaspora channels.
Synthetic chemistry retains the volume base. Natural ingredient positioning climbs the fastest as EU microplastic restrictions harden formulation rules.
Distribution Channel:
Customer acquisition cost and margin retention diverge sharply across procurement pathways.
- Pharmacy:Dermatological testing protocols and clinical endorsement claims secure shelf placement alongside prescription skincare. São Paulo and Rio de Janeiro retail density enables rapid SKU turnover with direct consumer education at point-of-purchase.
- Supermarket:High-volume, low-margin throughput favors gel formats with pump-dispenser compatibility and lower unit cost per use.
- Specialty Store:Botanical extract disclosure and fragrance layering command price premiums where consumers prioritize ingredient transparency.
- Online Retail:Algorithmic scent profiling and subscription replenishment compress working capital cycles for direct-to-consumer brands.
Pharmacy channels anchor premium positioning. Online retail gains share fastest as algorithmic personalization reduces consumer decision fatigue.
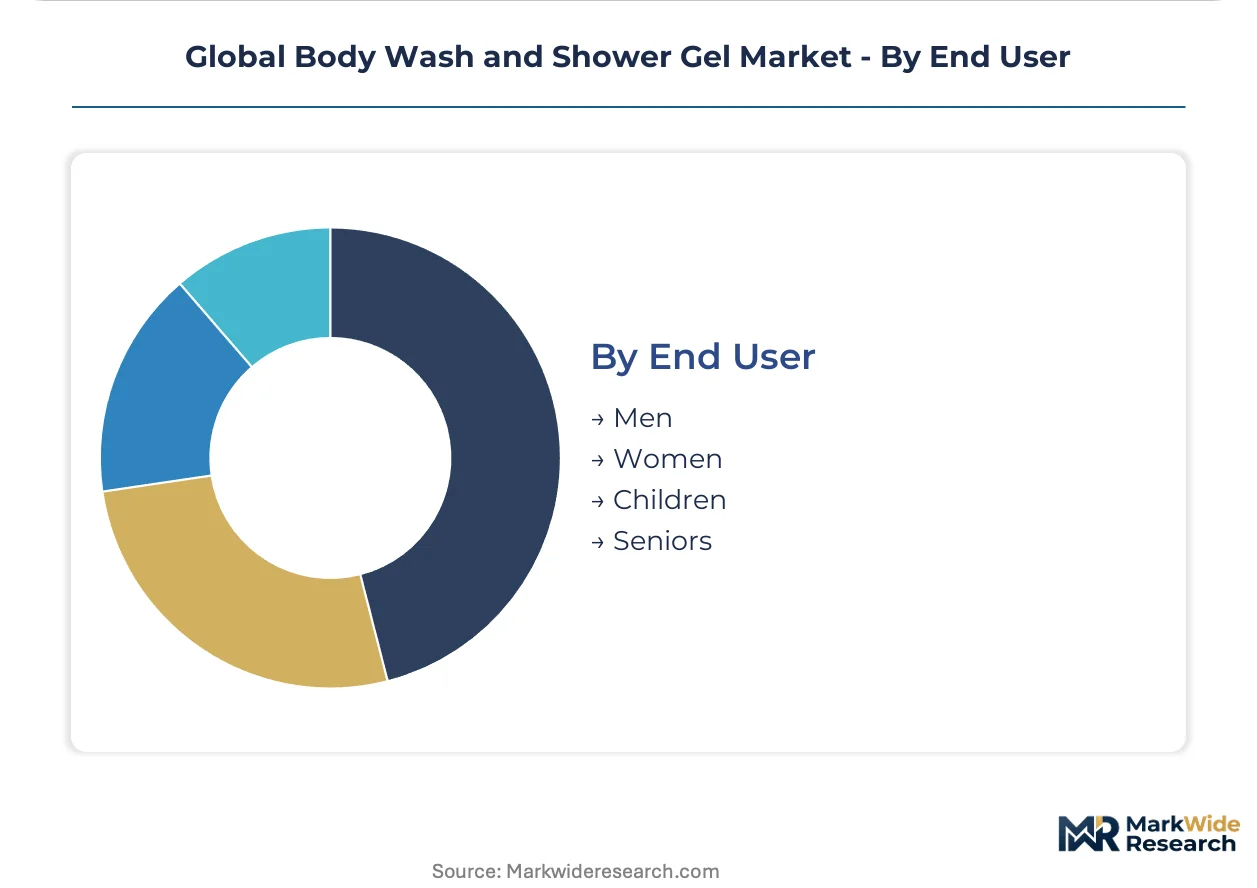
End User:
Demographic targeting dictates fragrance chemistry, packaging aesthetics, and clinical claim intensity.
- Women:Fragrance-forward formulations with layered scent profiles and moisturizing positioning dominate volume.
- Men:Woody or citrus scent families with simplified ingredient lists and sports-performance claims concentrate in mass retail.
- Children:Tear-free surfactant systems with mild amphoteric chemistry and pediatric testing protocols access pharmacy placement.
- Seniors:pH-balanced, lipid-replenishing formulations address age-related epidermal barrier compromise.
Women's segments retain the revenue base. Men's grooming positioning expands most quickly as fragrance houses develop dedicated masculine scent architecture.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Surfactant trade flows shape regional competitiveness, with export-oriented manufacturing clusters in Asia supplying formulation bases to branded finishers in Europe and North America. Import dependency for specialty emollients and fragrance compounds concentrates value capture in jurisdictions with captive chemical production.
United States
Pharmacy retail consolidation in California and New York drives demand for dermatologist-tested formulations with FDA-compliant labeling. The EPA's emerging scrutiny on per- and polyfluoroalkyl substances in cosmetic applications is accelerating reformulation timelines for synthetic thickeners. New Jersey's specialty chemical corridor houses fragrance compounding facilities serving mass-market brands.
Germany
REACH registration requirements for surfactant intermediates create compliance moats favoring established German chemical conglomerates with dedicated regulatory affairs teams. ECHA's microplastic restriction proposals are forcing substitution of synthetic polymer thickeners with cellulose alternatives. The Cologne-Düsseldorf industrial belt concentrates contract manufacturing for European pharmacy chains.
China
Guangdong and Jiangsu provinces host over half of global sodium lauryl ether sulfate capacity, exposing downstream brands to single-jurisdiction supply concentration. SAMR's cosmetic supervision regulations mandate ingredient disclosure standards converging with EU frameworks. Shanghai's formulation R&D centers serve as launchpads for domestic brands targeting Southeast Asian export markets.
Brazil
ANVISA's cosmetic registration pathways govern shelf access for antibacterial variants in São Paulo and Rio de Janeiro pharmacy networks. Pharmacy retail density in these metros enables rapid SKU turnover with trained beauty advisors at point-of-purchase. The São Paulo state industrial zone houses surfactant production feeding Mercosur distribution.
India
BIS tightening of preservative concentration ceilings, particularly methylisothiazolinone limits below EU thresholds, forces reformulation of standard global SKUs for domestic compliance. Maharashtra's chemical manufacturing belt around Mumbai supplies surfactant bases to contract finishers serving both domestic and Gulf export markets. Karnataka's Bangalore corridor hosts emerging direct-to-consumer brands leveraging algorithmic personalization.
Global Body Wash and Shower Gel Market Vendor Landscape
Platform integrators command the system tier; component specialists sit upstream supplying surfactant intermediates and fragrance compounds to branded finishers. The market structures around three tiers: multinational consumer goods conglomerates with captive chemical supply, regional pharmacy-focused brands with dermatological positioning, and private-label contract manufacturers serving retail chains. Strategic moves concentrate on backward integration into surfactant production and geographic licensing agreements to bypass regulatory registration burdens in protected markets.
Among European-headquartered conglomerates, Beiersdorf AG and Henkel AG & Co. KGaA exemplify the integrated archetype combining formulation R&D with regional manufacturing scale. Unilever PLC anchors the Anglo-Dutch platform tier with multi-continent surfactant supply networks. These three occupy positions where compliance investments across FDA, REACH, and BIS frameworks simultaneously defend market access and raise competitive barriers for mid-sized challengers.
| Leading Market Players |
|---|
| Beiersdorf AG |
| Johnson & Johnson Consumer Inc. |
| Unilever PLC |
| Kao Corporation |
| Reckitt Benckiser Group PLC |
| The Procter & Gamble Company |
| Colgate-Palmolive Company |
| Henkel AG & Co. KGaA |
| L'Oréal S.A. |
| Others |
Supply Flow & Price Mechanics
Guangdong and Jiangsu provinces concentrate over half of global sodium lauryl ether sulfate capacity, granting Chinese intermediate producers outsized leverage over formulation costs for downstream brands. This geographic concentration compresses margin structures for finished goods manufacturers while amplifying price volatility signals from tropical feedstock markets.
Pricing Analysis
Industrial OEM buyers anchor three-tier pricing stratification across premium pharmacy, standard mass retail, and economy private-label tiers. Price differentiation rests on dermatological certification grade and hospitality dispenser compatibility rather than surfactant chemistry alone. Pricing pressure intensifies in economy tiers as Brazilian and Indian contract manufacturers scale liquid format output. Pharmacy channels exhibit lowest price sensitivity due to clinical endorsement requirements, while supermarket private-label buyers drive hardest bargain on unit economics.
Supply Chain Analysis
Contract manufacturing concentrates among Southeast Asian facility networks serving hospitality bulk programs and European pharmacy private-label finishers. Raw material dependencies center on palm kernel oil from Indonesia and Malaysia, coconut-derived surfactants from Philippines and Sri Lanka, and specialty emollients from Germany and Switzerland. Single-source vulnerability runs through Guangdong province intermediate concentration. Distribution feeds through pharmacy retail density in São Paulo and Rio de Janeiro, supermarket mass channels, and direct-to-hotel IoT-enabled refill systems.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Body wash and shower gel sits in early-cycle expansion as post-pandemic hygiene protocol institutionalization embeds liquid cleanser into facility operating standards across healthcare-adjacent and hospitality sectors. This structural tailwind supports penetration gains ahead of saturation dynamics.
For Market Incumbents: Entrench compliance moats by accelerating multi-jurisdiction certification investments across FDA, REACH, and BIS frameworks. Deepen captive surfactant supply through backward integration into Guangdong and Jiangsu intermediate networks before supply concentration risks materialize. Lock in 5-year hospitality amenity contracts in Indonesia's resort construction pipeline to preempt emerging competitor access. For New Entrants and Emerging Players: Indonesia's hospitality construction pipeline in Bali and Jakarta offers the most penetrable white space for bulk amenity program capture. Direct-to-hotel IoT-enabled refill systems bypass traditional retail markups while building recurring revenue lock-in. Target biodegradable biosurfactant positioning—rhamnolipid and sophorolipid platforms—to preempt EU microplastic restriction compliance advantages ahead of incumbent reformulation cycles. For Investors and Strategic Acquirers: Carve-out targets emerge from multinational consumer goods parents seeking portfolio simplification, particularly regional pharmacy-focused brands with dermatological positioning but subscale global compliance infrastructure. Long-term viability favors assets with captive formulation R&D in Basel, Paris, or Mumbai talent clusters. Watch for inflection signals in Indonesia hospitality contract award velocity and EU ECHA microplastic restriction implementation timelines.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Surfactant Intermediates | Captive Guangdong and Jiangsu capacity insulates margin structures from tropical feedstock volatility. |
| Biodegradable Biosurfactant R&D Investment | Rhamnolipid platforms from sugar feedstocks secure EU REACH pre-qualification ahead of microplastic bans. |
| Direct-to-Hotel IoT Refill System Deployment | Automated dispenser monitoring in Marriott and Accor properties locks in recurring amenity revenue. |
| Multi-Jurisdiction Compliance Certification | Simultaneous FDA, REACH, and BIS registration filters informal competitors from pharmacy shelf access. |
| Indonesia Hospitality Supply Contract Capture | Five-year bulk amenity agreements in Bali and Jakarta construction pipeline secure volume anchoring. |
Methodological Framework
Findings reconcile primary fieldwork against secondary review of customs trade data, BIS cosmetic registration filings, and EU ECHA substance registrations. Interviews with contract manufacturing plant managers, pharmacy category buyers in São Paulo and Rio de Janeiro, hospitality procurement directors, and surfactant R&D technical directors informed demand and supply-side calibration. Secondary validation drew from ANVISA cosmetic filings, Nielsen retail audit data, and SEC 10-K disclosures from listed consumer goods conglomerates. Bottom-up volume builds across gel, liquid, foam, and cream formats triangulated against top-down category spend estimates.
Forecast inputs span formulation chemistry segmentation, distribution channel procurement patterns, end-user demographic targeting, and regional regulatory cluster adoption curves. Modeled dimensions include product type viscosity specifications, ingredient platform regulatory pre-qualification, pharmacy versus supermarket channel margin structures, and hospitality versus residential end-use concentration. CAGRs derived from surfactant intermediate capacity expansion timelines, hospitality construction pipeline visibility, and prescription skincare adjacency penetration rates across the analysis window.
The forecast holds incumbent behavior within observed patterns; aggressive capacity additions by Chinese state-backed chemical conglomerates or accelerated EU microplastic restriction implementation would shift outcomes. Model boundaries exclude waterless solid-format alternatives and pharmaceutical therapeutic cleanser classifications. Quarterly review of Indonesia hospitality contract awards, Guangdong surfactant intermediate pricing, and ECHA restriction proposal advancement is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Beauty & Personal Care
Anti-Acne Cosmetics Market
Beauty & Personal Care
Natural Deodorant Crystal Market
Beauty & Personal Care
Dry Shampoo Market
Beauty & Personal Care
North America Hair Removal Wax Market
Beauty & Personal Care
Handmade False Eyelash Market
Beauty & Personal Care
US Natural Personal Care Market
Beauty & Personal Care
Brazil Sustainable Personal Care Market
Beauty & Personal Care
Facial Cleansers and Toners Market
Beauty & Personal Care
Digitalization of Beauty Industry Market
Beauty & Personal Care
India Hair Oil Market
Beauty & Personal Care
Germany Lip Care Products Market
Beauty & Personal Care
Europe Cosmetics Market
Beauty & Personal Care
Face Makeup Market
Beauty & Personal Care
Scalp Massager Market
Beauty & Personal Care
Sustainable Personal Care Market
Beauty & Personal Care
South America Deodorants Market