
 Saudi Arabia Body Care and Personal Hygiene Market | 2026-2036
Saudi Arabia Body Care and Personal Hygiene Market Size, Share, and Industry Trends Forecast 2026-2036
Saudi Arabia Body Care and Personal Hygiene Market Analytics
Aftermarket service revenue in product consultation and skin analysis is fragmenting across pharmacy chains, e-commerce platforms, and dedicated beauty counters. L'Oréal S.A. leverages its dermatological research infrastructure to anchor professional-grade offerings within retail environments. Beiersdorf AG sustains brand loyalty through Nivea's long-standing shelf presence in Saudi supermarkets and drugstores. Unilever PLC competes via aggressive distribution breadth across mass-market channels.
Body care and personal hygiene encompasses topical formulations, oral care preparations, and cleansing agents designed for epidermal maintenance, microbial control, and aesthetic conditioning; products typically specify pH balance, active ingredient concentrations, and dermatological safety profiles to ensure compatibility with diverse skin types in arid climates. The primary commercial purpose centers on consumer health protection, appearance management, and sensory satisfaction within daily grooming rituals. Moisturizers and cleansers within skin care command the largest volume share given year-round hydration needs in Saudi Arabia's dry environment. Premium segment positioning accelerates fastest as Gulf consumers prioritize ingredient transparency and halal certification standards. Online retail distribution captures expanding margin pools through direct-to-consumer subscription models and influencer-driven conversion funnels.
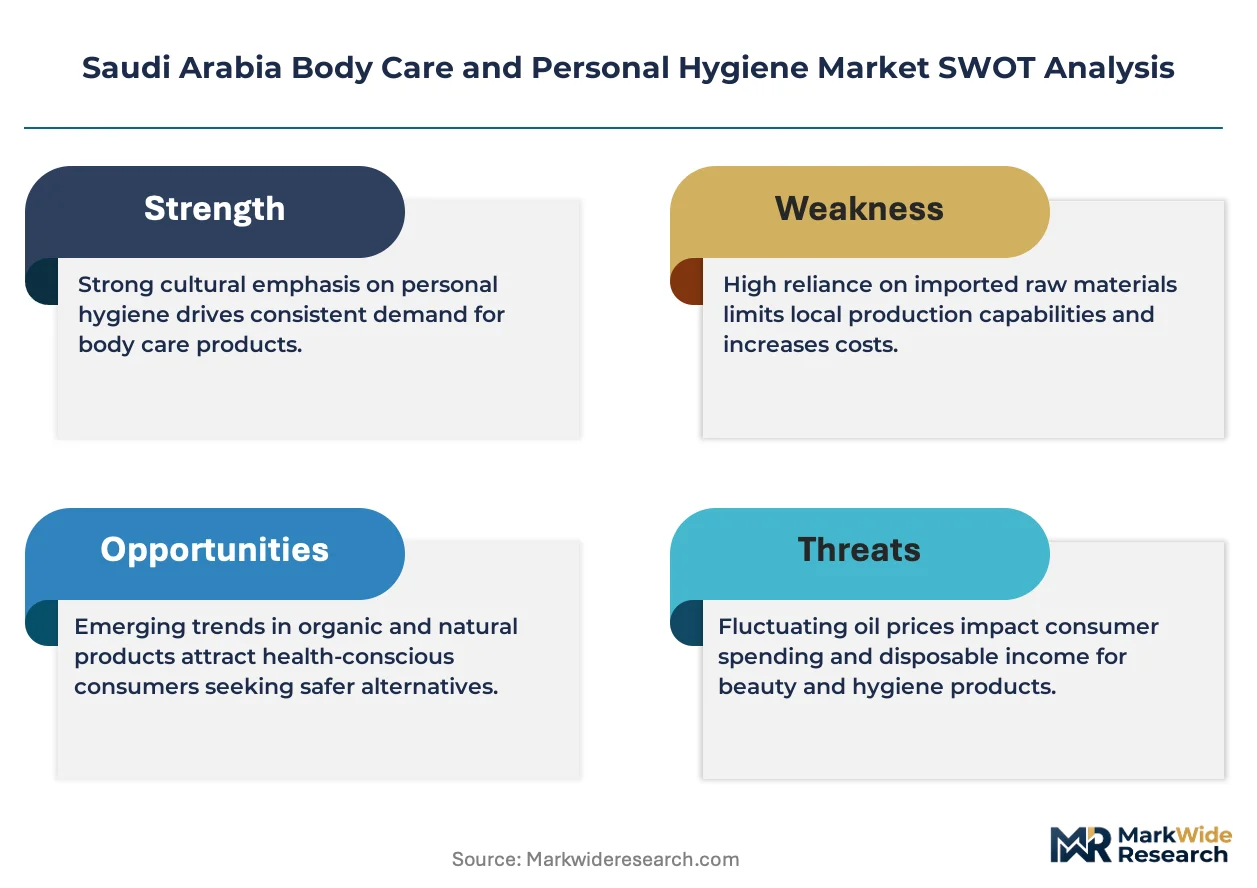
SFDA governs cosmetic safety assessments, ingredient disclosure mandates, and product registration requirements for all body care items entering Saudi commerce. The General Authority for Food and Drug Administration enforces compliance with Gulf Standardization Organization specifications for personal hygiene manufacturing and labeling. Halal certification protocols administered by accredited Islamic bodies further constrain formulation choices and sourcing networks. Stakeholders must monitor evolving SFDA guidance on preservative bans and fragrance allergen declarations to preempt reformulation costs and market access disruptions.
Market Dynamics
SFDA's tightening cosmetic ingredient standards are forcing wholesale reformulation across the Saudi body care sector, compressing product development cycles while elevating compliance costs for both domestic manufacturers and importers.
Growth Catalysts
- Halal Certification Mandates:Islamic accreditation bodies are tightening purity protocols for personal hygiene formulations, creating preferential market access for compliant producers and reshaping sourcing networks toward certified supply chains.
- Riyadh-Jeddah Urban Clustering:Disposable income concentration in these metropolitan corridors concentrates demand for premium skin care lines, with modern retail density enabling brand penetration at scale.
- Arid Climate Hydration Needs:Year-round low humidity drives consistent replenishment cycles for moisturizers and cleansers, establishing baseline consumption volumes that stabilize manufacturer revenue planning.
Market Restraints
- Ingredient Import Dependency:Specialty active compounds and fragrance molecules concentrate in European and Asian supplier networks, exposing formulators to currency fluctuation and shipping cost volatility.
- SFDA Registration Timelines:Product approval protocols extend commercialization lead times, freezing capital in inventory and delaying revenue recognition for new launches.
- Preservative Ban Cascades:Expanding prohibition lists for parabens and formaldehyde-releasing agents force costly reformulation of legacy products with established consumer recognition.
Strategic Opportunities
- Eastern Province Penetration:Dammam and Khobar retail infrastructure remains underdeveloped relative to Riyadh and Jeddah, presenting first-mover advantages for distribution network expansion.
- Subscription Commerce Models:Direct-to-consumer replenishment platforms are capturing margin pools previously allocated to wholesale intermediaries, with influencer-driven conversion funnels reducing customer acquisition costs.
- Dermatological-Retail Convergence:Pharmacy chains are expanding in-store skin analysis services, creating new revenue streams in product consultation that blur retail and clinical boundaries.
Industry Challenges
- Formulation Chemistry Expertise Scarcity:Local talent pools lack depth in halal-compliant preservative systems and arid-climate stability testing, forcing reliance on expatriate specialists.
- Legacy System Integration Friction:ERP and inventory management platforms at established Saudi distributors resist seamless connection with emerging e-commerce fulfillment networks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Saudi Arabia Body Care and Personal Hygiene Market |
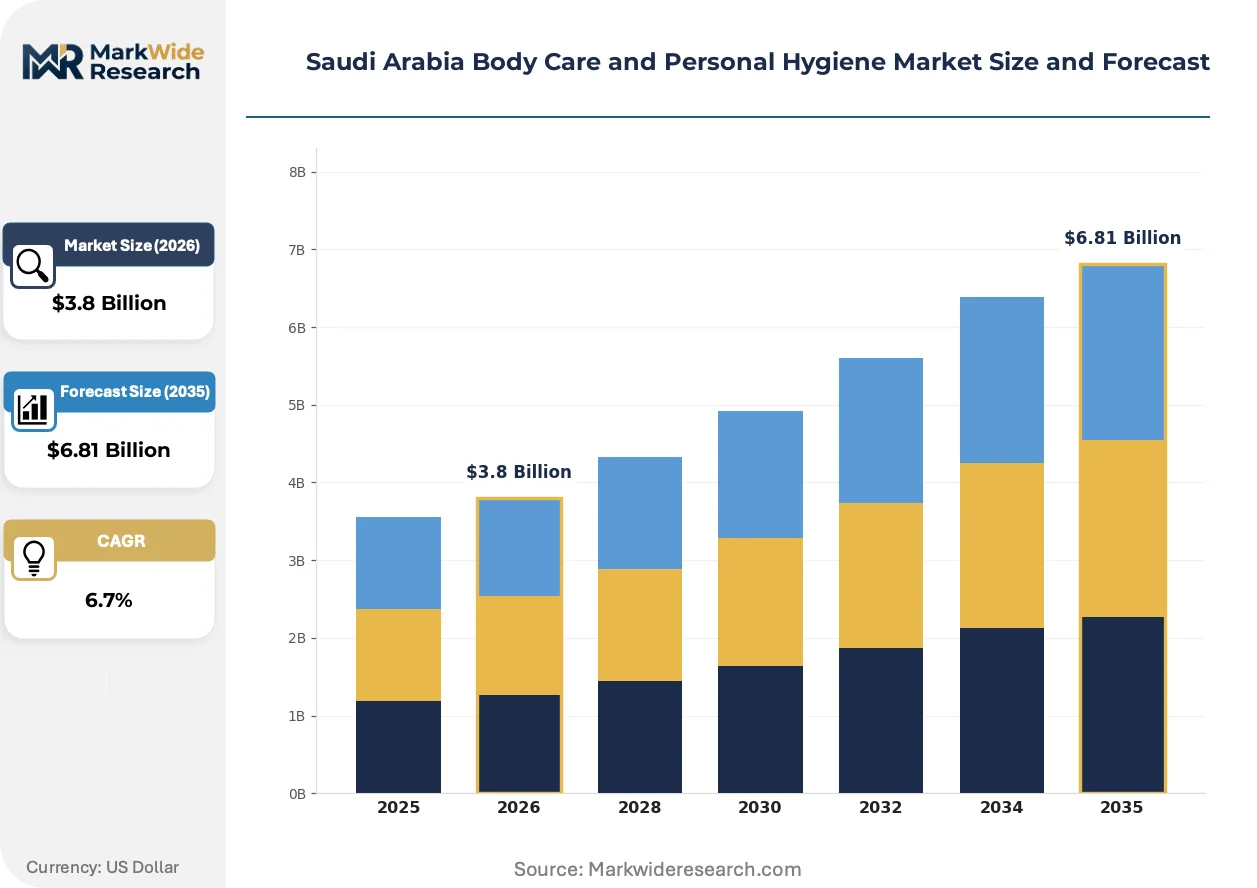
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Moisturizers, Exfoliators, Cleansers, Antiperspirants Application: Skin Care, Oral Hygiene, Hair Care, Bathing Customer Type: Mass Market, Premium Segment, Natural Products, Men Distribution Channel: Online Retail, Supermarkets, Drugstores, Specialty Stores |
| Companies Covered | Beiersdorf AG, Estée Lauder Companies Inc., L'Oréal S.A., Colgate-Palmolive Company, Coty Inc., Unilever PLC, Johnson & Johnson, Henkel AG & Co. KGaA, Procter & Gamble Company, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Saudi Arabia Body Care and Personal Hygiene Market Evolving Landscape
Digital skin diagnostics and ingredient transparency platforms are compressing the traditional trial-and-error purchase journey, while regulatory disclosure mandates accelerate supply chain digitization.
AI-powered skin analysis applications are virtualizing the in-person dermatological consultation. Young urban consumers in Riyadh and Jeddah adopt these tools at accelerating rates, bypassing pharmacy counters for algorithmic product matching. This virtualization is compressing brand loyalty cycles by enabling rapid competitor switching based on real-time skin condition data.
SFDA's fragrance allergen declaration requirements are mandating granular ingredient labeling across all body care categories. Manufacturers must now map and disclose supply chain compositions previously treated as proprietary. Premium segment players face the steepest compliance costs, as complex formulations require extensive documentation and reformulation to meet disclosure thresholds.
Pharmacy-led skin consultation services are unbundling from product sales, with consumers increasingly paying separately for diagnostic advice. This separation disrupts the traditional bundled retail model where consultation subsidized product margins. The shift concentrates in Jeddah's high-income districts, where consumers demonstrate willingness to pay for professional guidance independent of purchase commitment.
Saudi Arabia Body Care and Personal Hygiene Market Segmentation
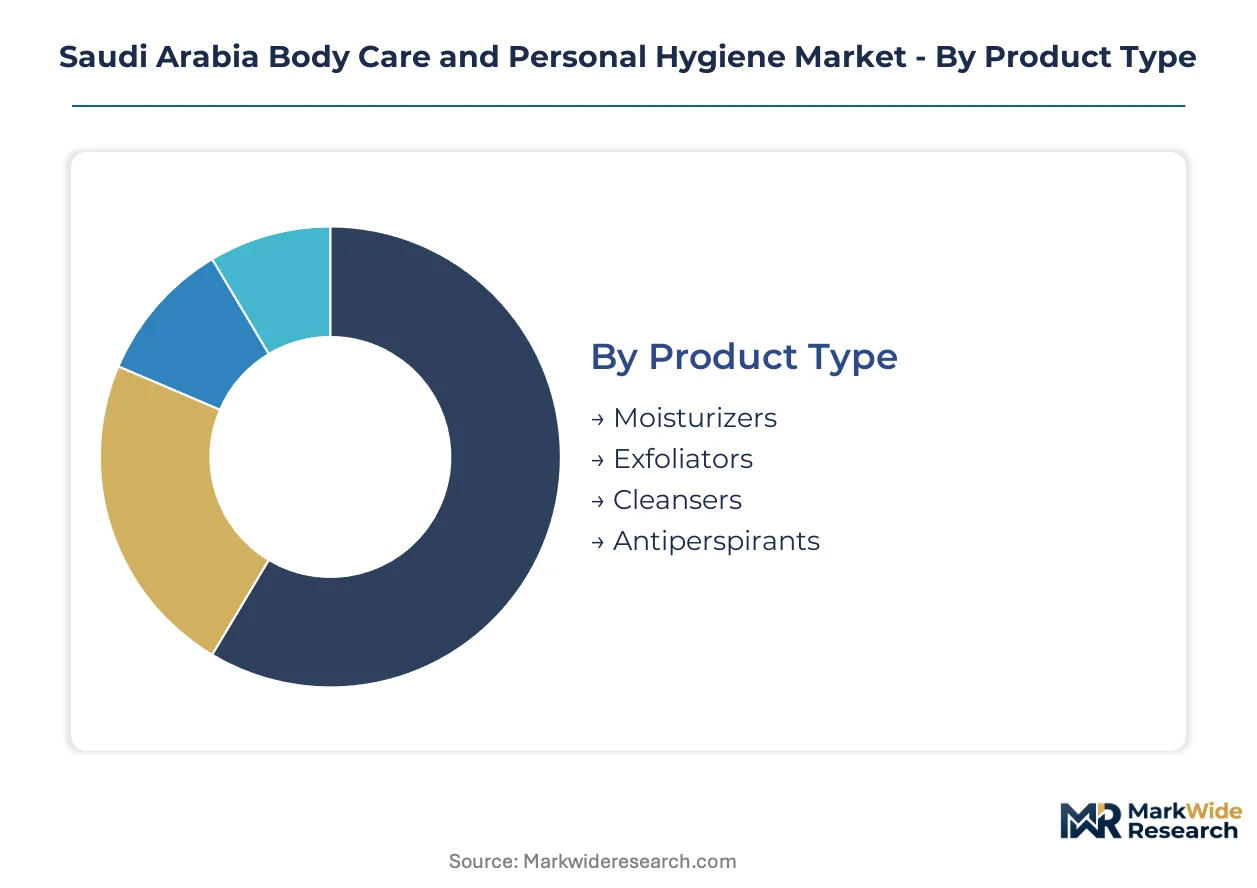
Segmentation in Saudi Arabia's body care market reveals how arid climate needs, halal certification requirements, and urban income concentration reshape product development priorities. Manufacturers calibrate formulations, pricing tiers, and channel strategies against distinct consumer clusters rather than treating the market as uniform.
Product Type:
After-sales service intensity varies sharply across product categories, with moisturizers requiring ongoing skin consultation support while antiperspirants demand minimal post-purchase engagement.
- Moisturizers:Emollient-rich formulations with humectant systems address transepidermal water loss in desert climates. Demand clusters in Riyadh's premium retail corridors where consumers seek dermatological guidance on layering protocols. SFDA hydration claim substantiation rules elevate R&D investment thresholds.
- Cleansers:pH-balanced surfactant systems remove impurities without compromising barrier function in low-humidity environments. Jeddah's coastal humidity variation creates need for seasonal formulation switching among affluent households. Halal certification for surfactant sources constrains supplier selection.
- Exfoliators:Mechanical and chemical desquamation products target hyperpigmentation concerns from sun exposure.
- Antiperspirants:Aluminum-based and aluminum-free formulations compete on efficacy duration in high-heat conditions.
By volume, cleansers lead. By growth pace, moisturizers are ahead.
Application:
Cost tier stratification separates commodity oral hygiene from premium skin care where ingredient transparency commands price premiums.
- Skin Care:Multi-step regimens encompassing serums, essences, and protective layers dominate household expenditure. Eastern Province consumers demonstrate rising sophistication in active ingredient literacy. SFDA's tightening cosmetic ingredient standards force continuous reformulation cycles.
- Oral Hygiene:Toothpastes and mouthwashes with fluoride and antibacterial agents maintain stable replenishment frequencies. Mass-market penetration in smaller Saudi cities relies on price-promotion mechanics. Halal certification for glycerin sources affects formulation choices.
- Hair Care:Scalp treatments and conditioning systems address hard water mineral buildup.
- Bathing:Shower gels and liquid soaps compete on fragrance longevity and skin-softening claims.
Skin care commands margin concentration. Oral hygiene anchors volume consistency.
Customer Type:
Volume distribution skews toward mass-market channels while margin capture concentrates in segments willing to pay for certification rigor and clinical validation.
- Premium Segment:Consumers prioritize ingredient provenance, clinical testing documentation, and personalized consultation access. Riyadh's luxury retail developments host dedicated brand boutiques with in-store skin analysis. SFDA disclosure mandates elevate transparency expectations.
- Natural Products:Plant-derived formulations with preservative-free positioning attract ingredient-conscious buyers. Jeddah's wellness-oriented consumer base drives adoption of clean beauty claims. Supply chain traceability requirements complicate sourcing.
- Mass Market:Price-sensitive purchasing through hypermarkets and discount channels dominates household penetration.
- Men:Gender-specific grooming lines expand beyond basic hygiene into specialized skin concern targeting.
Premium segment leads margin generation. Natural products are expanding most quickly.
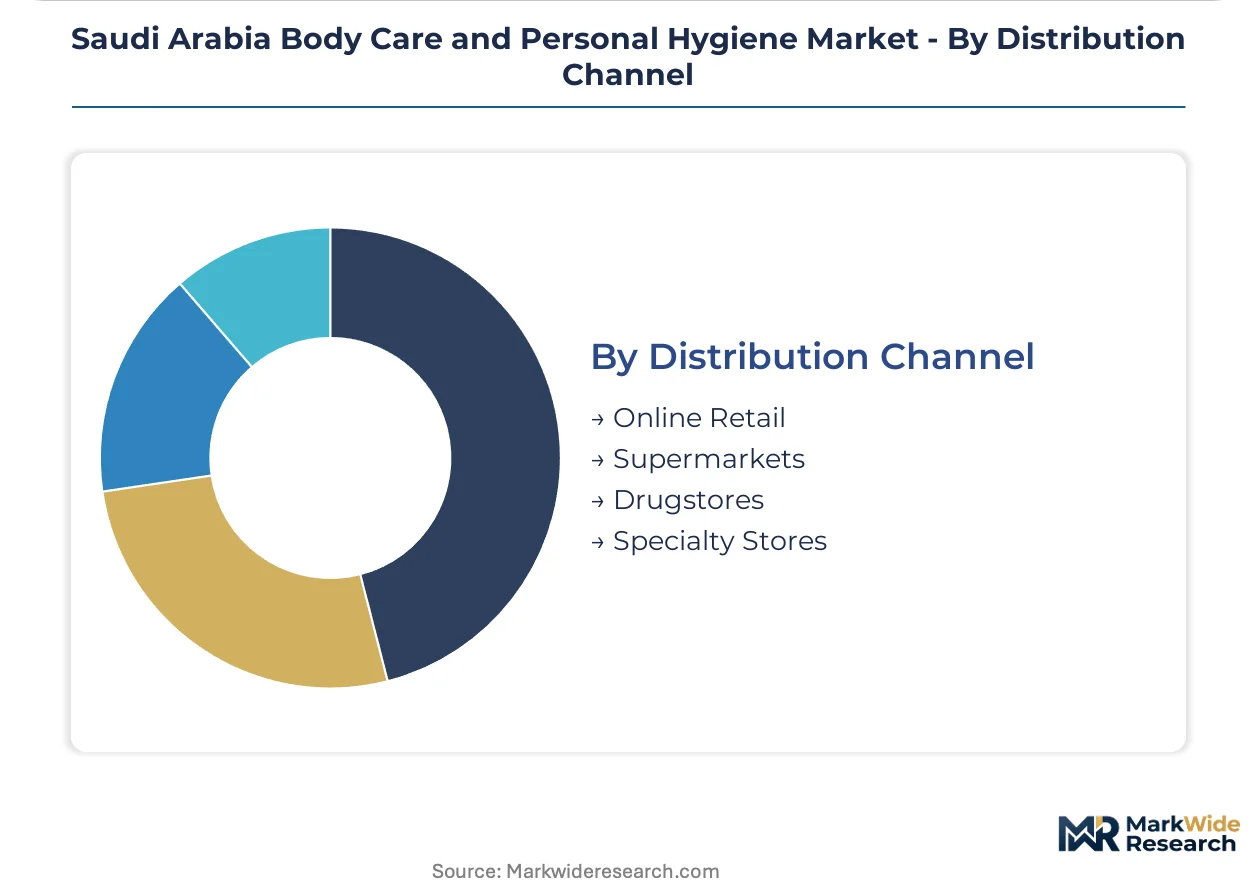
Distribution Channel:
Supply concentration in modern retail favors established players with shelf-space negotiation leverage, while digital channels enable challenger brand entry.
- Online Retail:Direct-to-consumer platforms capture subscription replenishment and influencer-driven discovery. Young urban consumers in Riyadh and Jeddah demonstrate highest conversion rates for algorithmic product matching. SFDA e-commerce labeling requirements impose compliance complexity.
- Drugstores:Pharmacy chains leverage professional credibility for skin care recommendation authority. In-store diagnostic services create consultation revenue streams separate from product margins. Regulatory pharmacy licensing restricts pure retail competitors.
- Supermarkets:Mass-market volume moves through hypermarket chains with promotional calendar dependency.
- Specialty Stores:Beauty-focused retailers curate assortments around brand storytelling and experiential engagement.
Supermarkets anchor volume throughput. Online retail shows steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand elasticity varies sharply across Saudi Arabia's body care landscape. Riyadh and Jeddah consumers absorb premium pricing for dermatologically validated formulations, while smaller cities remain anchored to mass-market promotional mechanics.
Riyadh
Luxury retail corridors concentrate spending on clinical-grade skin care with personalized consultation access. SFDA's tightening cosmetic ingredient standards elevate compliance costs for brands targeting affluent households. The King Abdullah Financial District hosts dedicated beauty boutiques where in-store skin analysis drives conversion.
Eastern Province
Dammam and Khobar demonstrate rising sophistication in active ingredient literacy among young professionals. Halal certification mandates from accredited Islamic bodies constrain supplier networks for formulators serving this cluster. Retail infrastructure remains underdeveloped relative to Riyadh, creating first-mover opportunities for distribution expansion.
Western Region
Jeddah's coastal humidity variation generates seasonal formulation switching among wellness-oriented consumers. The city's wellness tourism positioning attracts clean beauty brands emphasizing preservative-free claims. SFDA fragrance allergen disclosure requirements impose documentation burdens on complex formulations popular here.
NEOM Northwest
Eco-city development ambitions attract sustainable packaging innovators and waterless formulation specialists. Regulatory sandbox provisions under Vision 2030 frameworks enable accelerated product testing protocols. The project's zero-carbon mandates reshape sourcing requirements for personal hygiene supply chains.
Qassim and Northern Borders
Price-sensitive purchasing through hypermarket chains dominates household penetration in these provinces. Traditional distribution networks resist seamless integration with emerging e-commerce fulfillment platforms. Government subsidy programs for domestic manufacturing aim to reduce import dependency for basic hygiene commodities.
Saudi Arabia Body Care and Personal Hygiene Market Competitive Landscape
Dermatological-research conglomerates and mass-market distribution specialists split the Saudi body care market along premium-mass fault lines. The competitive structure consolidates around players with SFDA registration expertise and halal certification capabilities. Three archetypes dominate: science-backed premium houses, shelf-space dominant FMCG giants, and agile clean-beauty challengers. Capacity expansion through dedicated Saudi manufacturing facilities and strategic partnerships with pharmacy chains represent the primary competitive vectors.
Within the dermatological-research tier, L'Oréal S.A. and Beiersdorf AG exemplify the integration of clinical credibility with retail accessibility. Unilever PLC anchors the mass-market vector through distribution breadth across Saudi hypermarkets and drugstores. These three entities occupy positions that reflect divergent strategic bets: L'Oréal on professional-grade service convergence, Beiersdorf on heritage brand loyalty, and Unilever on promotional scale economics.
| Leading Market Players |
|---|
| Beiersdorf AG |
| Estée Lauder Companies Inc. |
| L'Oréal S.A. |
| Colgate-Palmolive Company |
| Coty Inc. |
| Unilever PLC |
| Johnson & Johnson |
| Henkel AG & Co. KGaA |
| Procter & Gamble Company |
| Others |
Value Network & Pricing Analysis
Jeddah's port infrastructure and bonded warehousing capacity anchor ingredient import flows for Saudi formulators, concentrating supply leverage among distributors with established SFDA clearance relationships and compressing margin capture for challengers lacking scale economies in regulatory compliance.
Pricing Analysis
Product consultation and skin analysis services drive lifetime value for premium body care brands. Three-tier pricing structure across premium, standard, and economy levels separates dermatological-grade formulations with clinical validation from mass-market alternatives. Price differentiation rests on halal certification tier and after-sales consultation access. Cost compression in the mass tier is intensifying because hypermarket promotional calendars force margin sacrifice for shelf-space retention. Mass-market households demonstrate highest price sensitivity, while Riyadh's affluent consumers absorb premium positioning with minimal elasticity.
Supply Chain Analysis
Specialty active compounds and fragrance molecules feed from concentrated European and Asian supplier networks. Germany, France, and South Korea anchor feedstock capacity for halal-compliant preservatives and arid-climate stability enhancers. Raw material dependencies center on surfactant precursors, emollient bases, and allergen-free fragrance systems. Single-source vulnerability runs through specialty glycerin certified for Islamic purity protocols. Distribution runs through pharmacy chains with regulatory licensing, supermarket hypermarket networks, and direct-to-consumer platforms with SFDA e-commerce labeling compliance.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Saudi Arabia's body care sector represents early-cycle expansion as subscription commerce models and dermatological-retail convergence penetrate below Riyadh-Jeddah corridors, with Eastern Province infrastructure development creating new addressable demand clusters.
For Market Incumbents: Harden SFDA registration expertise as a competitive moat against import challengers facing extended approval timelines. Deepen pharmacy chain partnerships to capture skin consultation revenue streams unbundling from product sales. Capacity addition in King Abdullah Economic City reduces logistics exposure to Jeddah port congestion.
For New Entrants and Emerging Players: Pursue Dammam and Khobar distribution gaps before established players consolidate Eastern Province shelf space. The natural products segment offers most penetrable white space given Jeddah's wellness-oriented consumer base and supply chain traceability requirements that favor agile sourcing. Direct-to-consumer launch with influencer-driven conversion funnels bypasses modern retail gatekeeping.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors clean-beauty challengers with waterless formulation capabilities aligned to NEOM sustainability mandates. Five-to-ten year viability concentrates on brands with halal certification infrastructure and arid-climate R&D assets. Watch SFDA preservative ban expansion velocity as inflection indicator for reformulation cost cascades affecting legacy portfolio valuations.
| Strategic Initiative | Industry Significance |
|---|---|
| Halal Certification Infrastructure Investment | SFDA tightening and Islamic accreditation body protocols create preferential market access for compliant producers. |
| Eastern Province Distribution Expansion | Dammam and Khobar retail underdevelopment relative to Riyadh offers first-mover shelf-space advantages. |
| Direct-to-Consumer Platform Launch | Subscription replenishment models capture margin pools previously allocated to wholesale pharmacy intermediaries. |
| Waterless Formulation Development | NEOM zero-carbon mandates and sustainability positioning attract eco-city procurement preferences. |
| In-Store Skin Analysis Service Integration | Pharmacy chains unbundle consultation from product sales, creating new revenue streams in diagnostic advice. |
Research Methodology
Desk research of SFDA regulatory filings, Gulf Standardization Organization specifications, and halal certification body protocols preceded structured interviews with dermatological brand managers, pharmacy chain procurement directors, and e-commerce platform supply planners. Secondary validation drew from customs import records, modern retail audit data, and pharmaceutical distribution databases. Bottom-up segment sizing and top-down macroeconomic triangulation cross-checked volume and value estimates.
Assumptions held fixed include SFDA regulatory trajectory and halal certification mandate expansion, while variables included urban income growth dispersion and e-commerce penetration rates across the analysis window. Segmentation dimensions modeled encompass product type, application category, customer tier, and distribution channel. CAGRs derived from historical trajectory analysis adjusted for regulatory intervention effects and climate-driven consumption baselines. Forecast inputs incorporated arid-climate hydration need elasticity and subscription commerce adoption curves.
Sensitivities concentrate around SFDA preservative ban cascades, currency fluctuation in European and Asian supplier networks, and logistics cost volatility through Jeddah port capacity constraints. Cross-checking against Saudi customs body care import value trends and pharmacy chain same-store sales data is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Beauty & Personal Care
Beauty Oils Market
Beauty & Personal Care
Colombia Cosmetics Products Market
Beauty & Personal Care
North America Cosmetics Market
Beauty & Personal Care
Luxury Bath and Body Products Market
Beauty & Personal Care
UV Nail Gel Lamp Market
Beauty & Personal Care
Stretch Mark Removal Products Market
Beauty & Personal Care
Nail Care Products Market
Beauty & Personal Care
Personal Care and Cosmetic Preservatives Market
Beauty & Personal Care
Asia-Pacific Beauty and Personal Care Products Market
Beauty & Personal Care
Europe Cosmeceuticals Market
Beauty & Personal Care
Herbal Beauty Products Market
Beauty & Personal Care
Herbal Haircare Products Market
Beauty & Personal Care
Facial Makeup Setting Spray Market
Beauty & Personal Care
Brazil Beauty and Personal Care Products Market
Beauty & Personal Care
Herbal Cosmetics Market
Beauty & Personal Care
Natural Hair Care Product Market