
 Middle East and Africa Effervescent Tablet Market | 2026-2036
Middle East and Africa Effervescent Tablet Market Size, Share, and Industry Trends Forecast 2026-2036
Middle East and Africa Effervescent Tablet Market Foresight
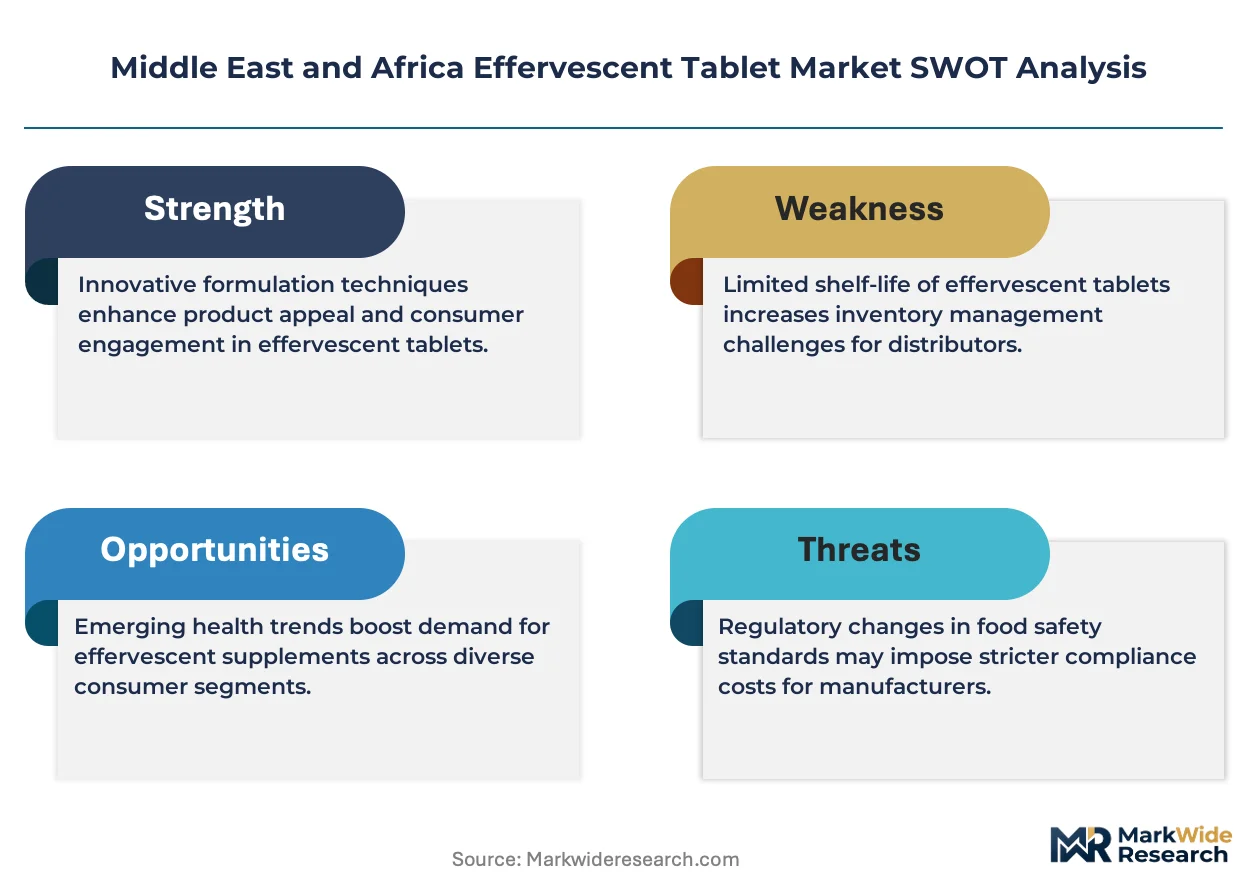
Pharmaceutical-grade effervescent formulations is bifurcating the Middle East and Africa market between premium regulated channels and mass-market retail. Reckitt Benckiser Group plc leverages its pharmacy distribution networks across Gulf states to sustain brand loyalty. Bayer AG anchors its position through backward integration into active ingredient sourcing, while GSK plc differentiates via pediatric formulation specialization.
Effervescent tablets are solid dosage forms containing organic acids and carbonate sources that generate carbon dioxide upon contact with water, producing a rapidly dissolving solution with enhanced bioavailability compared to conventional tablets. These products serve therapeutic and nutritional supplementation purposes across clinical and consumer health settings. Vitamins and electrolytes segments command the widest retail shelf presence, while antacids generate concentrated margin pools through hospital procurement contracts. Athletes represent the fastest-growing end-user cohort as sports nutrition expands beyond traditional protein formats into hydration and recovery effervescents.
SFDA in Saudi Arabia and SAHPRA in South Africa enforce divergent stability-testing protocols that fragment regional product registration timelines. The UAE's MOHAP accelerates market access through streamlined health supplement notifications, though Gulf standards harmonization remains incomplete. Stakeholders must monitor regulatory convergence negotiations between GCC member states to anticipate which manufacturing specifications will dominate cross-border trade.
Market Dynamics
Pharmacy modernization across Gulf Cooperation Council states is compressing distribution layers and forcing manufacturers to choose between premium regulated channels and mass-market retail penetration.
Growth Catalysts
- SFDA stability protocols:Saudi Arabia's pharmaceutical regulator mandates accelerated shelf-life testing that rewards manufacturers with proven formulation expertise, filtering out low-quality imports.
- Sports nutrition pivot:Athletes across the UAE and Qatar are replacing traditional hydration powders with effervescent electrolyte formats that dissolve faster and travel lighter.
- SAHPRA registration elevation:South Africa's health product regulator tightened manufacturing standards, creating competitive moats for compliant producers serving the broader Sub-Saharan region.
Market Restraints
- Active ingredient concentration:Carbonate and citric acid sourcing depends on concentrated chemical suppliers in India and China, exposing margins to input cost volatility and currency fluctuation.
- Moisture sensitivity:Effervescent tablets require humidity-controlled packaging and cold-chain adjacent storage that elevates logistics costs above conventional solid dosages.
- Regulatory fragmentation:Divergent stability-testing timelines between SFDA and SAHPRA force manufacturers to maintain parallel product variants, duplicating registration expenditures.
Strategic Opportunities
- Pediatric formulation gap:Nigeria and Kenya show minimal penetration of child-friendly effervescent vitamins, presenting first-mover advantages for taste-masked, low-dose formats.
- MOHAP notification streamlining:The UAE's health ministry accelerates health supplement market access, enabling faster product iteration cycles than Saudi registration pathways.
- Direct-to-consumer pharmacy apps:Digital prescription platforms in Egypt and Morocco are creating bypass channels around traditional wholesale distribution.
Industry Challenges
- Formulation chemist scarcity:The specialized skill set for effervescent reaction kinetics and moisture barrier design concentrates in European and Indian talent pools, complicating regional manufacturing scale-up.
- Cross-border batch certification:GCC member states maintain non-harmonized lot-release requirements that delay inventory movement between Saudi Arabia, UAE, and Kuwait warehouses.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle East and Africa Effervescent Tablet Market |
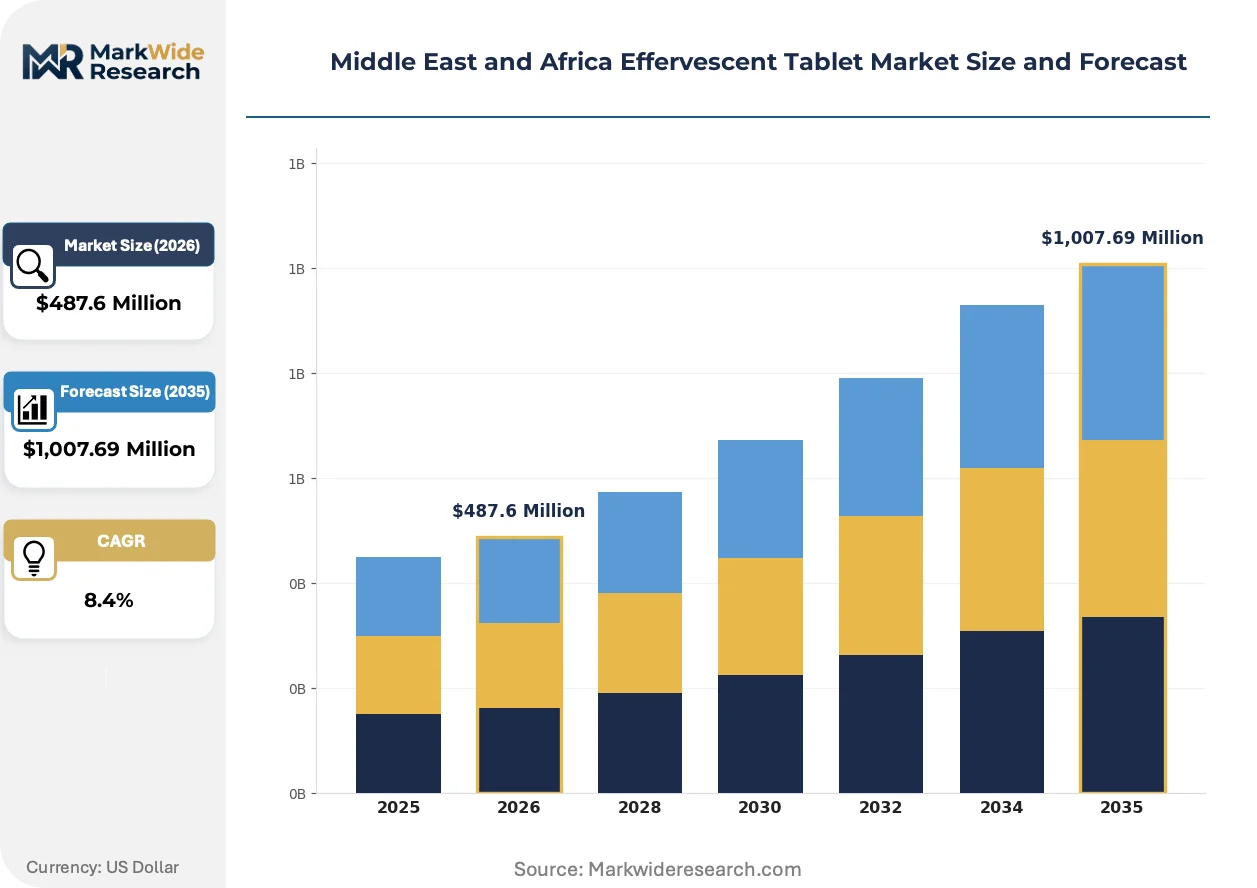
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $1,007.69 Million |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Vitamins, Minerals, Electrolytes, Antacids Formulation: Powder, Granules, Salt, Tablets Distribution Channel: Pharmacies, Supermarkets, Online Retailers, Health Stores End User: Adults, Children, Athletes, Seniors |
| Companies Covered | Reckitt Benckiser Group plc, Bliss GVS Pharma Ltd, Bayer AG, Chiesi Farmaceutici S.p.A., S. G. Biopharm Pvt. Ltd, GSK plc, Hermes Pharma GmbH, Nuun and Company Inc., Perrigo Company plc, Others |
| Regions Covered | Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle East and Africa Effervescent Tablet Market Shifts & Advancements
Manufacturers are compressing tablet dimensions while expanding functional claims, creating a tension between portability and dosage precision that shapes R&D allocation across the region.
Effervescent tablet production is miniaturizing through micro-granulation technology that embeds active ingredients within smaller effervescent matrices without sacrificing dissolution speed. Sports nutrition brands in Qatar and the UAE are adopting these compact formats for single-serve sachets. The structural consequence is compressing packaging material costs while enabling airport retail and gym vending machine placement that was previously uneconomical.
SAHPRA's updated stability-testing guidelines now require real-time data under ambient African climate conditions rather than accelerated laboratory protocols. This policy shift extends registration timelines for imported products while privileging local manufacturers with climate-adapted facilities. Vitamin and electrolyte segments face the steepest compliance burden, driving joint-venture formation between multinational brands and South African contract manufacturers.
Hospital procurement committees across Saudi Arabia and the UAE are consolidating supplier lists and demanding consolidated invoices spanning multiple therapeutic categories. This buyer concentration is displacing single-product vendors and favoring diversified pharmaceutical portfolios that bundle effervescent antacids with injectable and solid-dose lines. The shift is most visible in Riyadh and Dubai health system tenders, where three-year framework agreements now dominate annual purchasing cycles.
Middle East and Africa Effervescent Tablet Market Segmentation
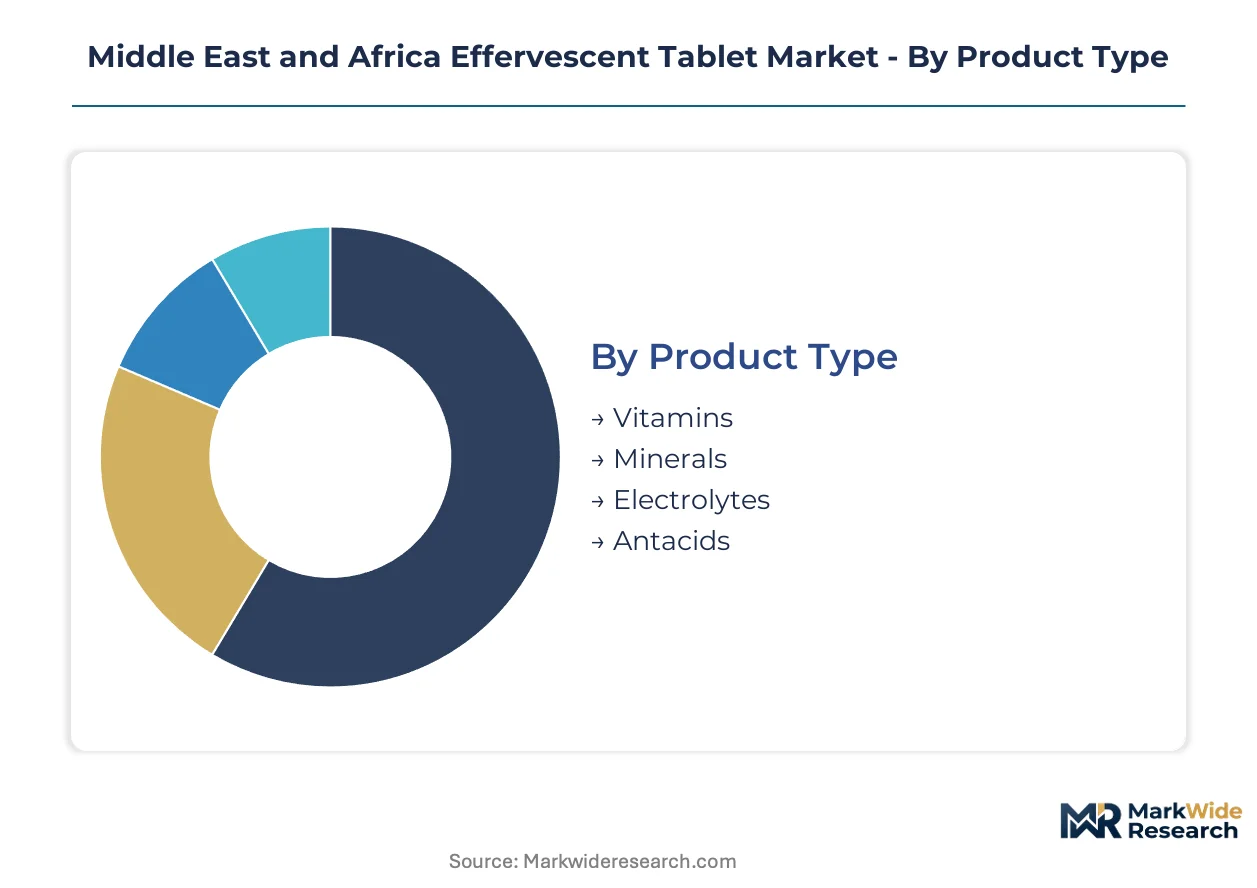
Effervescent tablet segmentation in the Middle East and Africa reveals distinct channel affinities that shape manufacturer portfolio strategy. Product type and end-user alignment determine whether formulations flow through regulated pharmacy networks or mass-market retail, with significant margin implications across each route.
Product Type:
Pharmacy chains across Saudi Arabia and the UAE prioritize vitamin and antacid SKUs with SAHPRA or SFDA registration, while supermarkets in South Africa and Kenya drive volume for electrolyte formats.
- Vitamins:Multivitamin complexes dominate shelf space in Gulf pharmacy chains, with vitamin C and B-complex variants generating repeat purchase cycles among urban professionals. Egyptian and Moroccan consumers favor single-vitamin effervescents for immune support, particularly during seasonal transitions.
- Electrolytes:Sodium-potassium effervescent matrices dissolve faster than powder alternatives, capturing athlete demand across Qatar and UAE fitness centers. Sports clubs in Dubai and Riyadh now stock single-serve sachets as standard hydration protocol, displacing traditional isotonic beverages.
- Minerals:Calcium and magnesium formulations target senior consumers through South African pharmacy loyalty programs.
- Antacids:Sodium bicarbonate-based effervescents secure hospital procurement contracts in Saudi Arabia through gastroenterology department tenders.
Vitamins dominate installed base. Electrolytes is where expansion concentrates.
Formulation:
Cost tiers separate premium tablet formats from economy powder sachets, with granule intermediates capturing price-sensitive segments in North African markets.
- Tablets:Compressed effervescent matrices with precise acid-carbonate ratios enable exact dosing for pharmaceutical applications. UAE health authorities mandate tablet formats for prescription-adjacent antacids, creating regulatory moats against powder competitors.
- Powder:Bulk effervescent powder offers lowest per-dose cost for institutional buyers across Nigerian and Kenyan healthcare facilities. Hospital procurement committees in Lagos and Nairobi favor 500g canisters for ward-level dispensing.
- Granules:Free-flowing granule formats bridge tablet precision and powder economy in Moroccan retail.
- Salt:Effervescent salt preparations serve specialized therapeutic niches in South African compounding pharmacies.
Tablets command margin concentration. Powder captures volume scale.
Distribution Channel:
Channel selection determines regulatory burden and working capital intensity, with pharmacy networks requiring registration investment that online platforms circumvent.
- Pharmacies:Licensed pharmacy chains across GCC states enforce cold-storage standards that filter out moisture-compromised inventory. Saudi Arabia's SFDA mandates lot-traceability systems for pharmacy-supplied effervescents, elevating compliance costs for market entry.
- Online Retailers:Direct-to-consumer platforms in Egypt and Morocco bypass traditional wholesale markups, enabling price experimentation. Cairo-based pharmacy apps now offer same-day effervescent delivery, compressing purchase cycles for replenishment-driven categories.
- Supermarkets:Mass-market retail in South Africa and Kenya drives impulse purchases for vitamin and electrolyte formats.
- Health Stores:Specialized wellness retailers in Dubai and Abu Dhabi curate premium imported effervescents for expatriate consumers.
Pharmacies anchor premium positioning. Online retailers are gaining share fastest.
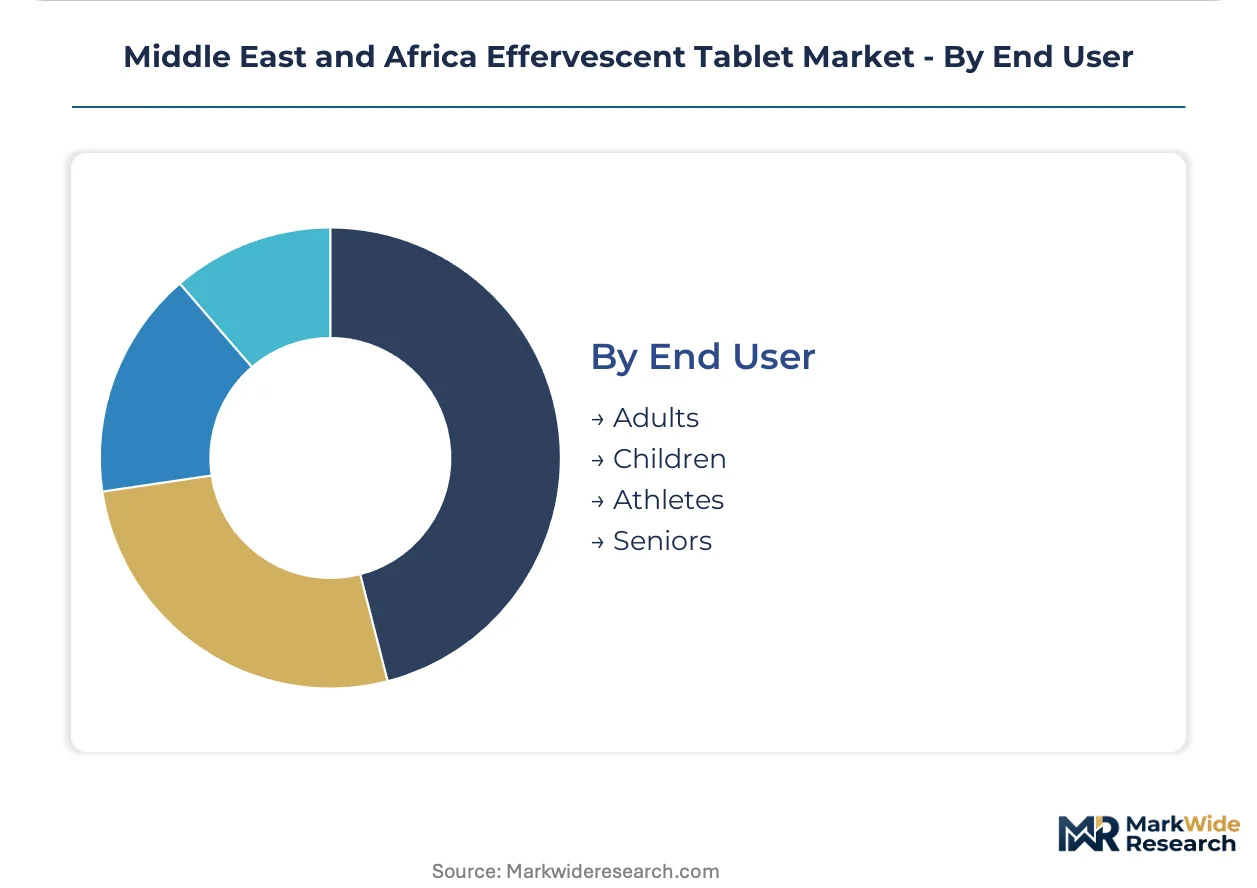
End User:
Demographic targeting shapes flavor profiling, dosage strength, and packaging format decisions across regional markets.
- Adults:Working-age consumers across Gulf states drive demand for convenience-oriented multivitamin formats. Office workers in Dubai and Riyadh favor effervescents for mid-day energy restoration, replacing traditional caffeine delivery methods.
- Athletes:Endurance sports participants in Qatar and UAE demand rapid-dissolution electrolyte matrices with optimized osmolality. Triathlon clubs in Abu Dhabi specify effervescent protocols for training and competition hydration.
- Children:Pediatric effervescent penetration remains minimal in Nigeria and Kenya, presenting formulation gaps for taste-masked variants.
- Seniors:South African retirement communities generate concentrated demand for bone-health mineral combinations.
Adults constitute the core user base. Athletes show the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Effervescent tablet manufacturing concentrates in South Africa and the Gulf states, where SAHPRA and SFDA registration requirements filter out low-capability imports. Chemical precursor sourcing remains concentrated in India and China, exposing regional formulators to input cost volatility.
Saudi Arabia
SFDA stability protocols mandate accelerated shelf-life testing that rewards manufacturers with proven formulation expertise. The regulator's pharmaceutical-grade standards filter out moisture-compromised imports from non-compliant sources. Riyadh's hospital procurement committees now consolidate supplier lists into three-year framework agreements, displacing single-product vendors.
United Arab Emirates
MOHAP notification streamlining accelerates health supplement market access faster than Saudi registration pathways. Dubai's sports nutrition retail channels drive demand for compact effervescent formats in single-serve sachets. Abu Dhabi's triathlon clubs specify effervescent electrolyte protocols for training hydration, replacing traditional isotonic beverages.
South Africa
SAHPRA's updated stability-testing guidelines require real-time data under ambient African climate conditions rather than accelerated laboratory protocols. Cape Town and Johannesburg manufacturing facilities gain competitive advantage with climate-adapted production lines. The regulator's tightened standards create moats for compliant producers serving the broader Sub-Saharan region.
Nigeria
Pediatric effervescent penetration remains minimal, presenting formulation gaps for taste-masked, low-dose vitamin variants. The country's national pharmaceutical regulator maintains divergent batch certification requirements that delay cross-border inventory movement. Lagos hospital procurement committees favor bulk effervescent powder in 500g canisters for ward-level dispensing.
Qatar
Endurance sports participants demand rapid-dissolution electrolyte matrices with optimized osmolality. Doha's fitness centers and sports clubs stock single-serve effervescent sachets as standard hydration protocol. The emirate's pharmacy modernization compresses distribution layers, forcing manufacturers to choose between premium regulated channels and mass-market retail.
Middle East and Africa Effervescent Tablet Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the Middle East and Africa effervescent tablet market. European and Indian multinational pharmaceutical groups anchor premium regulated channels through backward integration into active ingredient sourcing, while regional contract manufacturers capture volume scale in institutional procurement. Three archetypes dominate: diversified pharmaceutical portfolios with pharmacy network control, specialized effervescent formulators with climate-adapted facilities, and sports nutrition brands with direct-to-consumer digital platforms. Competitive intensity concentrates in M&A activity targeting South African manufacturing assets and strategic partnerships bridging Gulf distribution networks.
Within the diversified pharmaceutical tier, Bayer AG and GSK plc exemplify portfolio breadth that bundles effervescent antacids with injectable and solid-dose lines. Reckitt Benckiser Group plc occupies a position anchored in Gulf pharmacy distribution networks. Among specialized formulators, Hermes Pharma GmbH represents European expertise in effervescent reaction kinetics that regional players license to accelerate climate-adapted production scale-up.
| Leading Market Players |
|---|
| Reckitt Benckiser Group plc |
| Bliss GVS Pharma Ltd |
| Bayer AG |
| Chiesi Farmaceutici S.p.A. |
| S. G. Biopharm Pvt. Ltd |
| GSK plc |
| Hermes Pharma GmbH |
| Nuun and Company Inc. |
| Perrigo Company plc |
| Others |
Supply & Pricing Matrix
Long-term offtake contracts with Indian and Chinese carbonate suppliers lock in both raw material access and cost visibility for Gulf-based formulators, insulating premium tablet producers from citric acid spot-market volatility while compressing margins for spot-dependent entrants.
Pricing Analysis
SFDA pharmaceutical-grade registration dictates the pricing tier structure across Saudi Arabia, separating SAHPRA-certified premium antacids from unregistered economy powders in Nigerian hospital tenders. Price differentiation rests on cold-chain compliance certification and Gulf pharmacy network access, with electrolyte sachets facing downward pressure from sports nutrition brand proliferation. Hospital procurement committees in Riyadh exhibit lowest price sensitivity, while Lagos ward-level buyers prioritize per-dose cost minimization.
Supply Chain Analysis
India and China anchor global citric acid and sodium bicarbonate production, feeding effervescent reaction chemistry for regional formulators in South Africa and the Gulf. Active ingredient sourcing draws from concentrated chemical suppliers near Mumbai and Shanghai, exposing margin structures to currency fluctuation and maritime logistics chokepoints. Distribution runs through Dubai's pharmaceutical free zones into GCC pharmacy chains, with SAHPRA-registered products bypassing regional hubs for direct Sub-Saharan delivery.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Effervescent tablet incumbents face substitution pressure from fast-dissolving oral films and liquid shot formats that bypass hydration requirements entirely, forcing portfolio defense around bioavailability claims and pharmacy channel control.
For Market Incumbents: Shield registered product moats by deepening backward integration into climate-adapted manufacturing assets in Cape Town and Johannesburg, while accelerating SFDA lot-traceability system deployment to filter out moisture-compromised imports. Pediatric formulation R&D investment counters liquid vitamin substitute threats in Nigerian and Kenyan markets.
For New Entrants and Emerging Players: MOHAP notification fast-tracks enable UAE market entry ahead of Saudi registration timelines, opening white-space capture in Dubai sports nutrition retail and Abu Dhabi triathlon club supply chains. Taste-masked low-dose formats for Nigerian children present the most penetrable segment, with direct-to-consumer pharmacy apps in Cairo offering bypass channels around wholesale markups.
For Investors and Strategic Acquirers: Climate-adapted South African contract manufacturers with SAHPRA real-time stability data capabilities represent the priority acquisition archetype, positioned to serve Sub-Saharan expansion while multinational brands consolidate Gulf distribution networks. GCC regulatory harmonization negotiations signal the inflection point for cross-border manufacturing scale economics.
| Strategic Initiative | Industry Significance |
|---|---|
| Climate-Adapted Manufacturing Scale-Up | Cape Town facilities with ambient stability testing capabilities capture SAHPRA registration advantages. |
| Pediatric Formulation Development | Taste-masked low-dose vitamins address underpenetration in Nigerian and Kenyan markets. |
| MOHAP Notification Fast-Track Utilization | UAE streamlined pathways compress product iteration cycles versus Saudi SFDA timelines. |
| Direct-to-Consumer Pharmacy Platform Launch | Cairo and Casablanca digital prescription apps bypass traditional wholesale distribution layers. |
| Backward Integration into Active Ingredient Sourcing | Captive citric acid supply insulates margins from Indian and Chinese carbonate volatility. |
Research Methodology
Operator-level perspectives from pharmaceutical manufacturing directors, SAHPRA regulatory affairs leads, Gulf pharmacy procurement managers, and sports nutrition brand formulators anchored the qualitative base, cross-referenced with SFDA filing databases, SAHPRA registration records, GCC customs trade data, and hospital tender documentation. Bottom-up volume builds triangulated against top-down macroeconomic sizing across the forecast period.
Sensitivity analysis tested forecast robustness across alternative regulatory harmonization scenarios and raw material cost trajectories, with segmentation modeling spanning product type, formulation format, distribution channel, and end-user demographic dimensions. CAGRs derived from regression-weighted historical growth patterns and forward-looking pharmacy modernization indicators, incorporating climate-stability compliance timelines and digital channel penetration rates as industry-specific inputs.
Decision-makers should treat outputs as directional under base assumptions of sustained Gulf pharmacy modernization and stable carbonate supply economics; material deviation in GCC regulatory convergence or maritime logistics disruption would warrant model refresh. Recalibration cycles align with material shifts in SFDA-SAHPRA protocol harmonization and sports nutrition channel expansion velocity.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nutraceuticals
North America Collagen Market
Nutraceuticals
North America Nutraceuticals Market
Nutraceuticals
Anti Aging Agent Market
Nutraceuticals
Global Nicotinamide Mononucleotide (NMN) Market
Nutraceuticals
Phosphatidylserine Market
Nutraceuticals
Tetrahydropalmatine Market
Nutraceuticals
Global Human Microbiome Market
Nutraceuticals
Europe Collagen Peptide Products Market
Nutraceuticals
North America OTC Health Products Market
Nutraceuticals
Native Collagen Market
Nutraceuticals
Cartino Collagen Market
Nutraceuticals
Eye Health Ingredients Market
Nutraceuticals
Marine Olive Collagen Hybrid Nutricosmetic Systems Market
Nutraceuticals
Eggshell Membrane Market
Nutraceuticals
Chondroitin Sulfate Market
Nutraceuticals
PMS and Menstrual Health Supplements Market