
 North America Decorative and Illuminated Mirror Market | 2026-2036
North America Decorative and Illuminated Mirror Market Size, Share, and Industry Trends Forecast 2026-2036
North America Decorative and Illuminated Mirror Market Insights
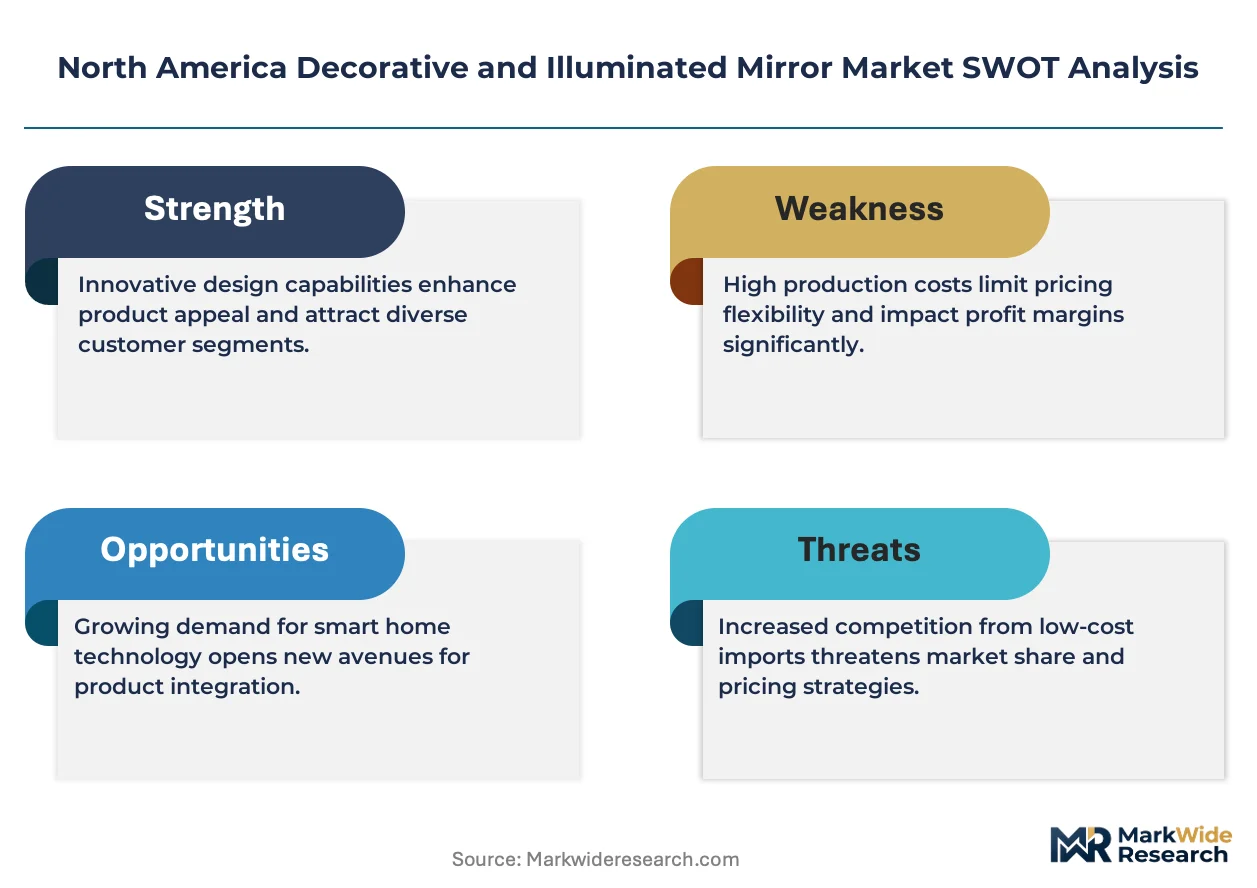
LED-integrated vanity specifications is bifurcating the North America Decorative and Illuminated Mirror Market into premium architectural-grade and mass-market residential tiers. Kohler anchors the premium hospitality and residential channel through captive manufacturing of proprietary lighting modules. Seura specializes in custom-integrated mirror displays for luxury hotel and casino environments across Las Vegas and Miami corridors. Simplehuman competes in the direct-to-consumer segment with sensor-activated brightness calibration and surgical-grade optical clarity.
Decorative and illuminated mirrors encompass reflective glass substrates bonded to aluminum or polymer frames, incorporating solid-state LED arrays, defogging heating elements, and optional capacitive touch controls for residential bathrooms, hospitality suites, and retail fitting rooms. Illuminated mirrors with anti-fog and adjustable brightness features command the highest margin pools, while smart-feature integration represents the fastest-growing specification tier as voice-assistant compatibility and circadian lighting algorithms penetrate master-bath renovations. Wall-mounted installations dominate volume, though integrated vanity-mirror systems are displacing standalone units in new luxury condominium construction across Toronto, Vancouver, and Manhattan.
The U.S. Department of Energy enforces minimum efficacy standards for residential LED luminaires, while Canada's Natural Resources Office regulates standby power consumption for connected mirror systems, and UL certification requirements govern electrical safety for damp-location installations throughout the trade area. California's Title 24 Building Energy Efficiency Standards mandate high-efficacy lighting in bathrooms, directly favoring LED-integrated mirror specifications over conventional sconce arrangements. Stakeholders must monitor evolving federal appliance efficiency rulemakings and provincial energy codes to anticipate specification shifts before inventory commitments lock in obsolete product configurations.
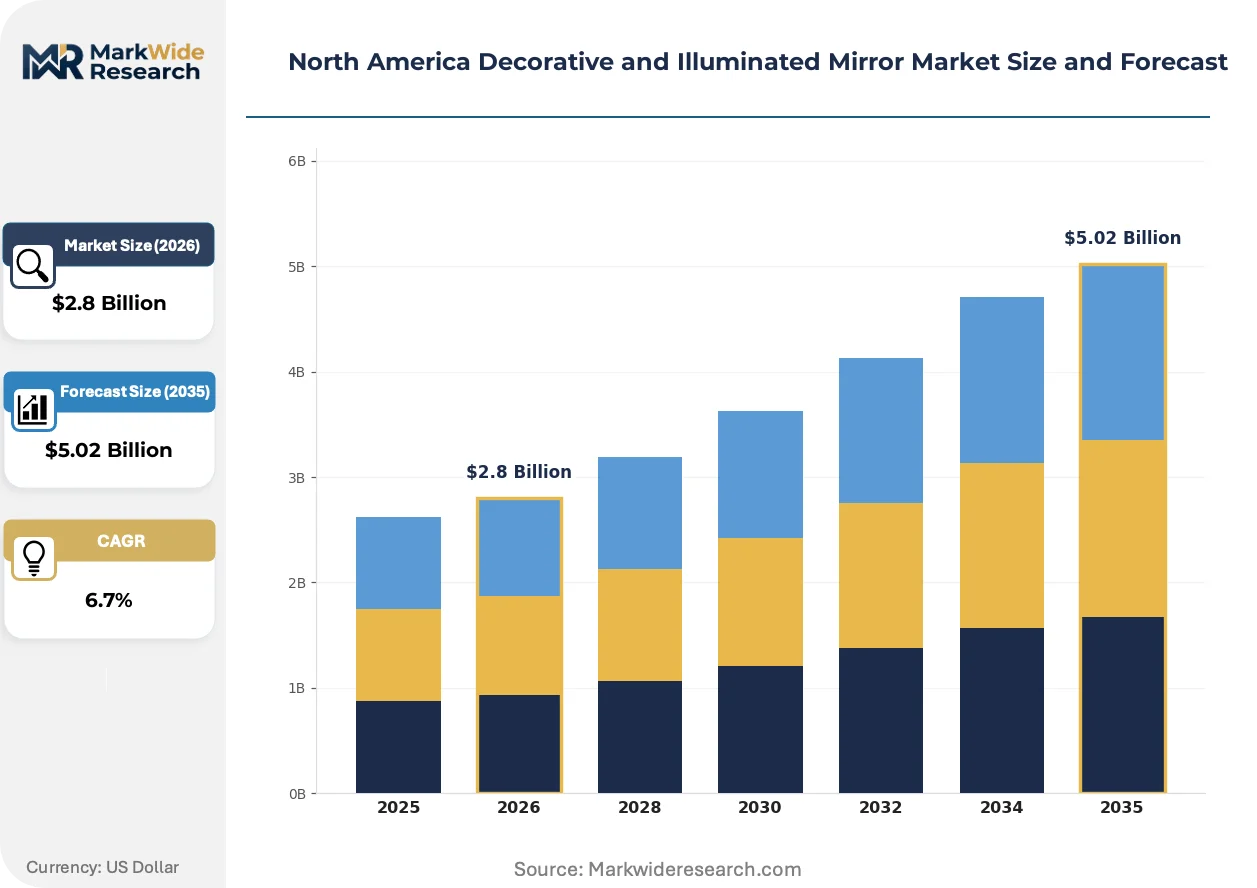
Market Dynamics
California's Title 24 Building Energy Efficiency Standards are compressing specification timelines for LED-integrated mirror systems across residential new-build and hospitality renovation pipelines, forcing distributors to pre-certify inventory before code enforcement windows close.
Growth Catalysts
- Residential Energy Codes:California's Title 24 mandates high-efficacy bathroom lighting, directly favoring LED-integrated mirror specifications over conventional sconce arrangements in new construction.
- Hospitality Renovation Cycles:Luxury hotel chains across Las Vegas and Miami corridors are accelerating backlit vanity installations as part of property-wide guest room modernization programs.
- LED Efficacy Thresholds:The U.S. Department of Energy's appliance efficiency standards are pushing manufacturers toward lower-wattage LED configurations that meet minimum lumen-per-watt requirements.
Market Restraints
- Aluminum Frame Input Volatility:Raw material cost swings for extruded aluminum profiles constrain margin stability for mid-tier manufacturers serving price-sensitive residential channels.
- Electrical Certification Timelines:UL damp-location certification requirements extend product development cycles by four to six months, delaying revenue recognition for seasonal product launches.
- Conventional Sconce Substitution:Wall-mounted decorative lighting fixtures retain specification share in renovation projects where electrical rough-in modifications prove cost-prohibitive.
Strategic Opportunities
- Voice-Assistant Integration:Circadian lighting algorithms paired with Amazon Alexa and Google Home compatibility represent unpenetrated specification tiers in master-bath renovations across Texas and Florida markets.
- Integrated Vanity Systems:New luxury condominium construction in Toronto and Vancouver is displacing standalone mirrors with factory-integrated vanity-mirror units that reduce field installation labor.
- Canadian Standby Power Rules:Natural Resources Canada regulations on connected mirror systems create first-mover advantages for manufacturers pre-certifying low-phantom-load designs.
Industry Challenges
- Optical Calibration Expertise:Surgical-grade clarity specifications require specialized glass coating technicians, creating recruitment bottlenecks for manufacturers expanding premium product lines.
- Multi-Jurisdictional Compliance:Simultaneous UL, CSA, and DOE certification requirements fragment quality assurance resources and extend time-to-market for cross-border product launches.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Decorative and Illuminated Mirror Market |
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.02 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Decorative Mirrors, Illuminated Mirrors, Compact Mirrors, Magnifying Mirrors Material: Glass, Plastic, Metal, Wood Feature: Anti-Fog, LED Lighting, Adjustable Brightness, Smart Features Installation Type: Wall-Mounted, Free-Standing, Tabletop, Integrated |
| Companies Covered | Koninklijke Philips N.V., The Procter & Gamble Company, Ikea, Kohler, Seura, Majestic Mirror & Frame, Paris Mirror, Simplehuman, Impressions Vanity, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Decorative and Illuminated Mirror Market Trends and Innovations
Technological convergence between solid-state lighting and sensor-activated controls is redefining product architecture across residential and hospitality segments, compressing traditional fixture categories into unified surface systems.
Capacitive touch interfaces with programmable brightness memory are supplanting mechanical rocker switches in master-bath specifications. High-end residential buyers in Manhattan and Los Angeles are specifying these interfaces as standard. The shift is compressing demand for separate dimmer hardware and rewiring electrical contractor procurement patterns.
The U.S. Department of Energy's ongoing appliance efficiency rulemakings are tightening minimum efficacy thresholds for residential LED luminaires. Manufacturers are redesigning optical engines to maintain lumen output at reduced wattage. California's Title 24 enforcement is accelerating this redesign cycle ahead of federal adoption timelines.
Builder-direct procurement channels are consolidating specification authority for multi-family residential developments. National homebuilders in Phoenix and Austin are bypassing traditional lighting showrooms for factory-direct mirror system contracts. This channel compression is squeezing regional distributor margins and reallocating marketing spend toward volume rebate structures.
North America Decorative and Illuminated Mirror Market Segmentation
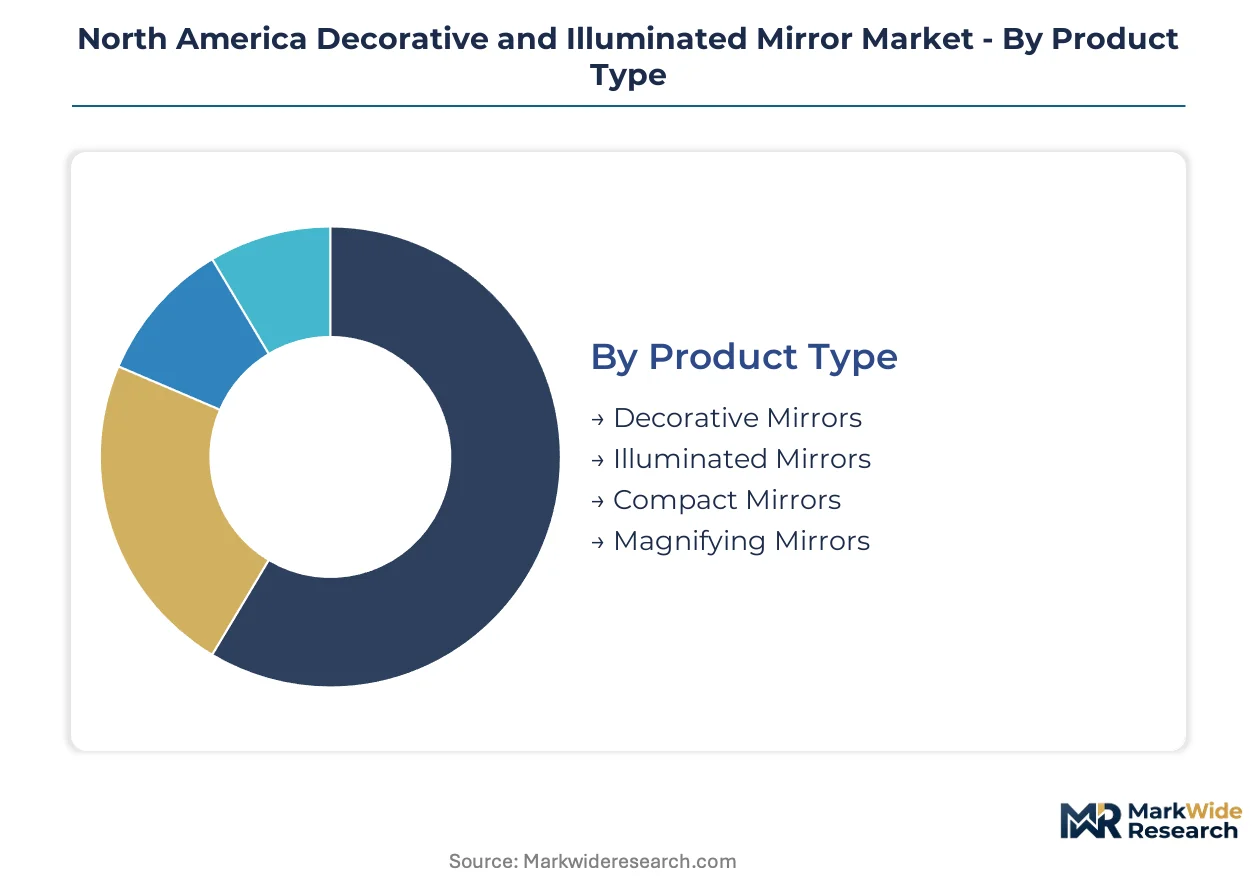
Segmentation in the North America Decorative and Illuminated Mirror Market reveals how specification authority fragments across residential, hospitality, and retail channels. Understanding these divides exposes where margin pools concentrate and where substitution threats from conventional lighting fixtures remain most acute.
Product Type:
Decorative mirrors face the most severe substitution pressure from standalone art installations and conventional wall treatments, while illuminated variants benefit from regulatory tailwinds that conventional fixtures cannot match.
- Decorative Mirrors:Non-illuminated glass substrates in ornamental frames serve entryways, living spaces, and hospitality lobbies where aesthetic function dominates. Demand concentrates in Texas and Florida residential new-builds where builder-grade specifications prioritize cost over integrated lighting.
- Illuminated Mirrors:LED-integrated units with aluminum or polymer frames incorporate solid-state arrays and optional defogging elements. California's Title 24 mandates are compressing specification timelines for these systems across Los Angeles and San Diego bathroom renovations.
- Compact Mirrors:Portable single-glass units target travel and personal grooming segments with minimal electrical integration.
- Magnifying Mirrors:Optical-grade substrates with 5x to 10x magnification serve precision grooming applications in master baths and hotel suites.
Decorative mirrors anchor the volume base while illuminated mirrors gain share at the steepest rate.
Material:
Cost tier differentiation separates premium architectural specifications from mass-market residential procurement, with raw material volatility constraining mid-tier positioning.
- Glass:Silvered float glass with copper-free backing dominates reflective substrates across all price tiers. Surgical-grade optical clarity commands specification in Manhattan and Vancouver luxury condominiums where distortion tolerances approach zero.
- Metal:Extruded aluminum and stainless steel frames provide structural rigidity for large-format hospitality installations. Raw material cost swings for aluminum profiles constrain margin stability for manufacturers serving price-sensitive Phoenix and Austin multi-family channels.
- Plastic:ABS and polycarbonate frames reduce unit costs for entry-level residential segments.
- Wood:Solid and engineered timber frames serve rustic and transitional design palettes in Pacific Northwest and Northeast markets.
Glass substrates dominate specification value while metal frames expand most quickly in hospitality renovation pipelines.
Feature:
Technology integration intensity separates three distinct customer tiers, with smart-feature penetration creating the widest specification gaps.
- LED Lighting:Solid-state arrays with color temperatures from 2700K to 6500K constitute the baseline illuminated mirror specification. The U.S. Department of Energy's efficacy standards are pushing manufacturers toward lower-wattage configurations that maintain lumen output.
- Anti-Fog:Resistive heating elements bonded to rear glass surfaces prevent condensation in humid bathroom environments. These systems command the highest margin pools in Las Vegas and Miami hospitality corridors where guest experience metrics drive capital allocation.
- Adjustable Brightness:Dimming circuits with memory functions serve circadian lighting protocols in wellness-focused residential renovations.
- Smart Features:Voice-assistant compatibility and programmable lighting algorithms represent unpenetrated specification tiers in Texas and Florida master-bath markets.
LED lighting anchors the volume base while smart features gain share at the steepest rate.
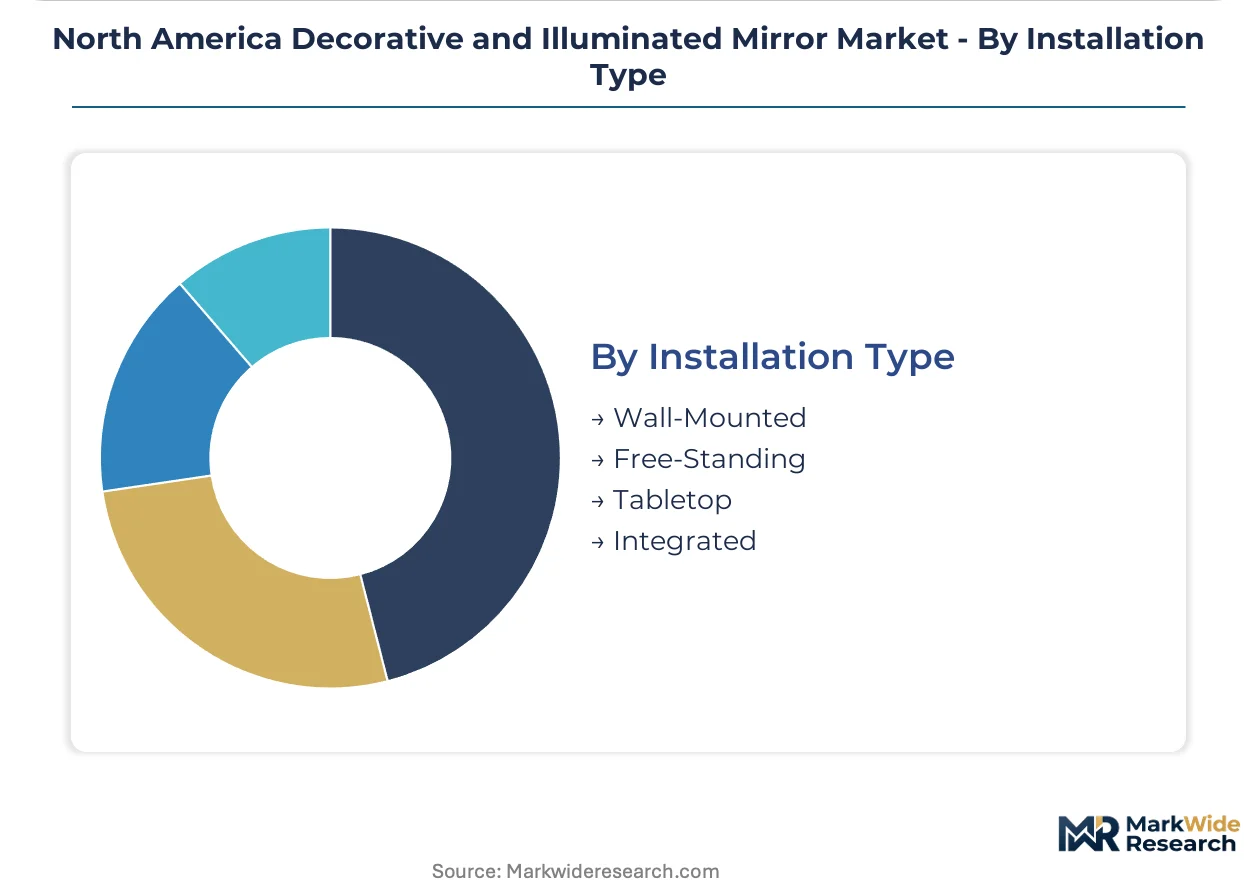
Installation Type:
Customer type fragmentation separates new construction specification from renovation retrofit constraints, with integrated systems capturing growing share in factory-built environments.
- Wall-Mounted:Bracket or cleat systems dominate volume across residential replacement and hospitality renovation channels. These installations retain specification share where electrical rough-in modifications prove cost-prohibitive in older Toronto and Vancouver housing stock.
- Integrated:Factory-assembled vanity-mirror units reduce field installation labor in new luxury condominium construction. National homebuilders in Phoenix and Austin are bypassing traditional lighting showrooms for direct procurement of these systems.
- Free-Standing:Floor-based units with weighted bases serve rental and temporary installation environments.
- Tabletop:Compact surfaces for dressing areas and hospitality desks require no electrical rough-in.
Wall-mounted installations anchor the volume base while integrated systems gain share at the steepest rate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manufacturing capacity for LED-integrated mirror systems clusters in the United States and Canada, with specification authority fragmenting across sub-regional energy code jurisdictions and hospitality renovation corridors.
United States
California's Title 24 Building Energy Efficiency Standards mandate high-efficacy bathroom lighting in new construction, compressing specification timelines for LED-integrated systems across Los Angeles and San Diego metro areas. The U.S. Department of Energy enforces minimum efficacy standards for residential LED luminaires, pushing manufacturers toward lower-wattage configurations. Las Vegas and Miami hospitality corridors anchor demand for backlit vanity installations as luxury hotel chains accelerate property-wide modernization programs.
Canada
Natural Resources Canada regulates standby power consumption for connected mirror systems, creating compliance thresholds that favor low-phantom-load designs in Toronto and Vancouver luxury condominium developments. CSA certification requirements govern electrical safety for damp-location installations, extending product development cycles for cross-border launches. British Columbia's building code amendments are accelerating integrated vanity-mirror specifications in new high-rise residential construction across the Vancouver metro.
Mexico
Manufacturing cost advantages in Nuevo León and Baja California are attracting contract assembly operations for aluminum-framed mirror systems serving North American distribution channels. Mexico's national energy efficiency standards for lighting products are gradually converging with U.S. DOE thresholds, though enforcement remains fragmented across state jurisdictions. Querétaro's industrial corridor is emerging as a secondary hub for glass substrate processing and metal frame fabrication.
North America Decorative and Illuminated Mirror Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes, creating a bifurcated market structure where premium specification authority concentrates among integrated solution providers while mass-market volume flows through scale-oriented fabricators. The vendor base spans captive lighting manufacturers, specialized mirror-integrated display producers, and direct-to-consumer sensor-technology companies. Three archetypes dominate: hospitality-focused custom integrators, residential-channel brand owners with proprietary LED modules, and consumer-electronics specialists with algorithmic control systems. Competitive moves center on backward integration into optical engine production and strategic partnerships with national homebuilders for factory-direct procurement.
Among North America-based specialists, Kohler Co. and Seura occupy positions on the premium architectural tier, exemplifying the integrated-solution archetype through captive manufacturing capabilities and custom hospitality specifications. Simplehuman represents the consumer-technology vector, anchoring the direct-to-consumer segment with sensor-activated control systems. Koninklijke Philips N.V. and IKEA provide scale-oriented counterpoints, with the former leveraging global lighting technology portfolios and the latter commanding mass-market residential distribution density.
| Leading Market Players |
|---|
| Koninklijke Philips N.V. |
| The Procter & Gamble Company |
| Ikea |
| Kohler |
| Seura |
| Majestic Mirror & Frame |
| Paris Mirror |
| Simplehuman |
| Impressions Vanity |
| Others |
Pricing and Supply Chain Analysis
Factory-direct procurement contracts with national homebuilders lock in both aluminum frame supply and price visibility across Phoenix and Austin multi-family developments. These arrangements compress distributor margins while securing volume commitments for extruded profile suppliers facing volatile LME pricing.
Pricing Analysis
California's Title 24 Building Energy Efficiency Standards dictate the pricing tier structure across residential new-build specifications. Three-tier pricing structure across premium hospitality, standard residential, and economy builder-grade levels separates UL-certified damp-location systems from uncertified imports. Pricing pressure stems from aluminum input cost volatility constraining mid-tier manufacturers serving price-sensitive Texas and Florida channels. National homebuilders exhibit highest price sensitivity, while Las Vegas luxury hotel operators prioritize guest experience metrics over unit cost.
Supply Chain Analysis
Port congestion along Los Angeles-Long Beach corridors elevates inbound logistics costs for glass substrate shipments originating from Asian float-glass producers. Manufacturing gravity centers on Mexico's Nuevo León and Baja California for aluminum frame fabrication, with glass processing clustering in Querétaro. Raw material dependencies encompass silvered float glass, extruded aluminum profiles, and solid-state LED arrays. Single-source vulnerability concentrates in copper-free mirror backing suppliers. Distribution runs through builder-direct channels consolidating specification authority for multi-family developments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Installation service contracts and extended warranty programs represent faster-expanding revenue layers than hardware sales as master-bath renovations demand field calibration expertise. Recurring service attach is reshaping vendor economics across the North American trade area.
For Market Incumbents: Compound specification authority through captive LED module production and UL pre-certification investments ahead of federal appliance efficiency rulemakings. Defend hospitality channel position against sensor-technology entrants by deepening optical calibration capabilities. Backward integration into glass coating operations secures surgical-grade clarity specifications that command premium positioning in Manhattan and Vancouver luxury developments.
For New Entrants and Emerging Players: Anchor in voice-assistant integration white space across Texas and Florida master-bath markets where circadian lighting algorithms remain underpenetrated. Target factory-integrated vanity systems for Toronto and Vancouver luxury condominium pipelines displacing standalone mirror specifications. Direct-to-consumer digital channels bypass showroom consolidation squeezing regional distributors.
For Investors and Strategic Acquirers: Custom-integrated display specialists with captive hospitality relationships in Las Vegas and Miami corridors offer defensible acquisition targets. Long-term viability hinges on regulatory compliance infrastructure spanning UL, CSA, and DOE certification requirements. Watch for Title 24 enforcement acceleration across additional state jurisdictions as inflection indicator for LED-integrated specification penetration.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into LED Module Production | Captive optical engine manufacturing insulates margin pools from component price volatility. |
| UL Damp-Location Pre-Certification Investment | Compressed four-to-six-month approval timelines accelerate seasonal product launch windows. |
| Voice-Assistant Platform Partnership | Amazon Alexa and Google Home compatibility unlocks unpenetrated Texas and Florida specification tiers. |
| Builder-Direct Channel Development | Factory-direct procurement contracts with national homebuilders displace regional distributor intermediation. |
| Circadian Lighting Algorithm Development | Programmable brightness memory functions align with wellness-focused residential renovation demand. |
Research Methodology
Cross-validation between primary interviews with hospitality procurement directors, residential lighting specification consultants, and electrical contractor field supervisors anchors the qualitative findings. Secondary validation draws from U.S. Department of Energy appliance efficiency filings, California Energy Commission Title 24 documentation, and Natural Resources Canada standby power regulations. Bottom-up demand modeling triangulates against top-down trade flow analysis across North American distribution channels.
Sensitivity analysis across aluminum price scenarios, enforcement timing for energy codes, and hospitality renovation cycle phasing stress-tests projection robustness. Segmentation dimensions encompass product type, material grade, feature integration intensity, installation configuration, and regional regulatory cluster. CAGRs derive from iterative convergence between historical specification penetration patterns and forward-looking code adoption curves. Input assumptions incorporate LED efficacy threshold trajectories and builder procurement channel evolution.
Decision-makers should treat outputs as directional under steady regulatory enforcement and stable raw material cost assumptions; material deviation would warrant model refresh. Specific risks include accelerated federal appliance efficiency rulemakings, sustained aluminum price volatility, and hospitality capital expenditure contraction. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Lighting and Fixtures
Candle Holder Market
Lighting and Fixtures
Floor Lamps Market
Lighting and Fixtures
Europe Electric Fireplace Market
Lighting and Fixtures
United States Electric Fireplace Market
Lighting and Fixtures
Outdoor Lighting Market
Lighting and Fixtures
Smart Desk Lamp Market
Lighting and Fixtures
Kitchen Lighting Market
Lighting and Fixtures
Europe Ceiling Fan Market
Lighting and Fixtures
North Africa Ceiling Fan Market
Lighting and Fixtures
Decorative Lighting Market
Lighting and Fixtures
Global Lamp Shades Market
Lighting and Fixtures
North America Ceiling Fan Market
Lighting and Fixtures
Christmas Lights and Christmas Decorations Market
Lighting and Fixtures
Chandelier Market
Lighting and Fixtures
Landscape Lighting Market
Lighting and Fixtures
Kids Desk Lamp Market