
 Middle East Amusement Parks Market | 2026-2036
Middle East Amusement Parks Market Size, Share, and Industry Trends Forecast 2026-2036
Middle East Amusement Parks Market Outlook
Annual pass subscription models is hardening into the dominant revenue architecture across the Middle East amusement parks landscape. Miral leverages its integrated destination development model to anchor visitor loyalty across Yas Island's cluster of properties. Warner Bros. Discovery competes through deep intellectual property control, sustaining repeat visitation via character-driven seasonal programming. Qiddiya Investment Company positions its Riyadh mega-project as a counterweight to established UAE hubs, extending Saudi Arabia's entertainment infrastructure at unprecedented scale.
Middle East amusement parks constitute large-scale outdoor entertainment complexes featuring mechanical thrill rides, water-based attractions, live performance venues, and immersive themed environments engineered for throughput capacities exceeding 20,000 guests daily. These facilities generate revenue through controlled-access admission systems, in-park hospitality services, and licensed merchandise distribution. Theme parks and water parks command the largest capital allocation pools, with themed attractions capturing premium ticket pricing through intellectual property integration. Family and tourist customer segments represent the core volume base, while corporate groups deliver higher per-capita spending through event packages and private venue rentals.
Saudi Arabia's General Entertainment Authority and the UAE's Department of Culture and Tourism shape operational licensing, safety certification, and content standards across the region's park developments. The UAE's civil defense authorities enforce ride-specific technical inspection protocols that operators must satisfy before seasonal opening approvals. Stakeholders must monitor how Saudi entertainment localization mandates and evolving Emirati visa facilitation policies redistribute visitor flows between Riyadh, Jeddah, and Dubai corridor investments.
Market Dynamics
Saudi Arabia's General Entertainment Authority licensing reforms are compressing project approval timelines from years to months, triggering a capital deployment race that is reshaping competitive positioning across the Arabian Peninsula's entertainment corridor.
Growth Catalysts
- SFDA Safety Harmonization:Saudi Arabia's unified ride certification standards are eliminating redundant testing cycles for cross-border operators, accelerating park openings in Riyadh and Jeddah corridors.
- Expatriate Population Density:The UAE's concentrated South Asian and European professional communities generate consistent weekday foot traffic that stabilizes revenue during traditional tourism lulls.
- MOHAP Medical Tourism Integration:Dubai's health authority is mandating wellness-entertainment hybrid zoning, creating co-location requirements that boost extended-stay visitor economics.
Market Restraints
- Steel and Aluminum Input Volatility:Roller coaster track fabrication depends on Gulf-sourced specialty alloys whose prices fluctuate with regional petrochemical output cycles.
- European Engineering Concentration:Major ride system suppliers cluster in Germany and Switzerland, exposing operators to euro-denominated contract exposure and extended lead times.
- Water Scarcity Constraints:Abu Dhabi's Environment Agency imposes absolute consumption caps on water park operations, limiting expansion capacity during peak summer demand.
Strategic Opportunities
- Oman Underpenetration:Muscat's entertainment infrastructure remains nascent relative to UAE and Saudi benchmarks, presenting first-mover positioning for integrated resort developers.
- Saudi Localization Mandates:The General Entertainment Authority's 70% local content requirements are creating captive supply opportunities for domestic fabrication and themed construction services.
- Extended Reality Convergence:Augmented reality overlays combined with physical ride hardware are enabling intellectual property licensing at reduced capital intensity versus full themed environments.
Industry Challenges
- Themed Entertainment Engineering Talent Scarcity:The region's universities produce insufficient ride system design and show control programming graduates, forcing reliance on expensive expatriate specialists.
- SFDA Seasonal Certification Bottlenecks:Saudi safety inspectors concentrate approvals in pre-Ramadan windows, compressing maintenance windows and forcing operational downtime during peak revenue periods.
- Intellectual Property Licensing Complexity:Character rights negotiations with Hollywood studios involve territory-specific carve-outs that fragment regional marketing campaigns and merchandise distribution.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle East Amusement Parks Market |
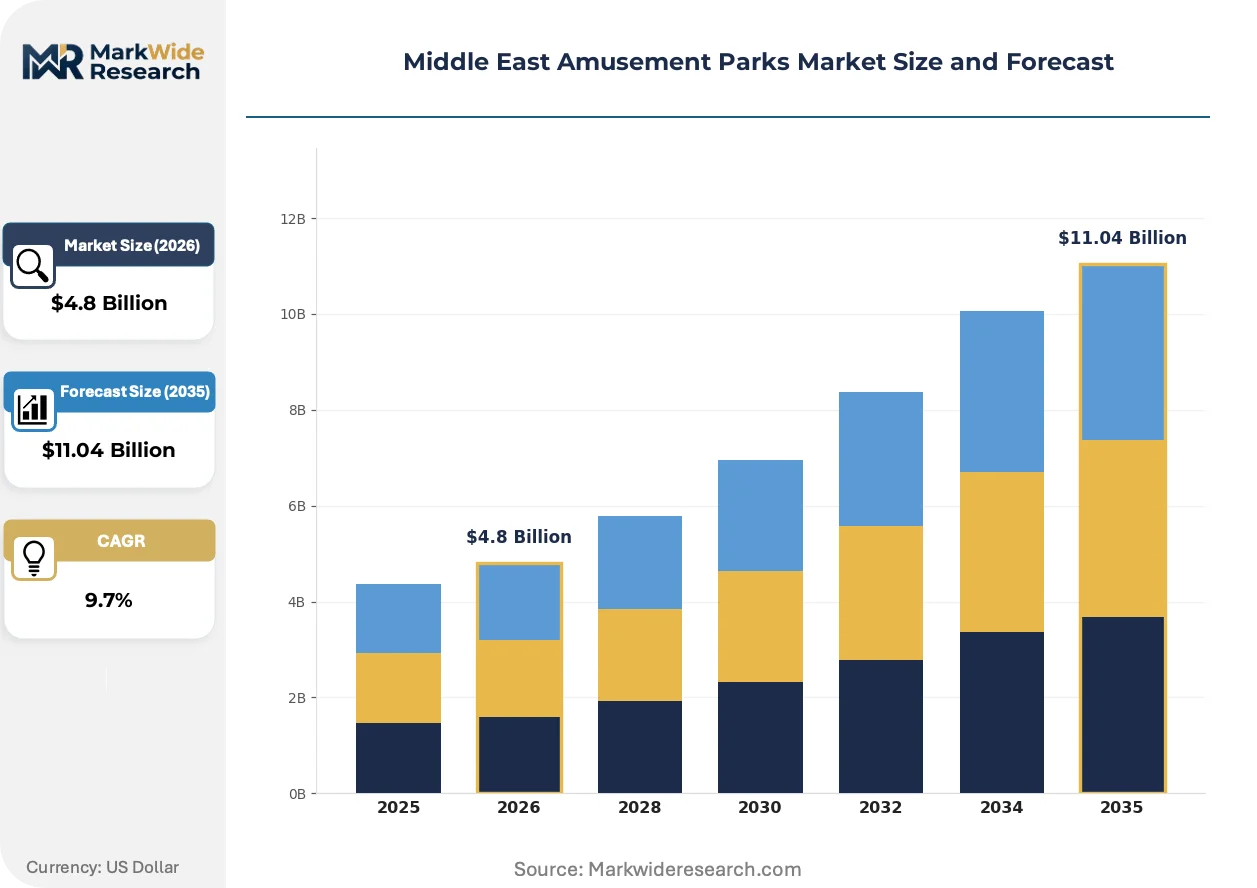
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $11.04 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Park Type: Theme Parks, Water Parks, FECs, Adventure Parks Attraction Type: Roller Coasters, Water Rides, Live Shows, Themed Attractions Customer Segment: Families, Teenagers, Tourists, Corporate Groups Revenue Source: Admissions, Food & Beverage, Merchandise, Sponsorship |
| Companies Covered | Universal Destinations & Experiences, SeaWorld Parks & Entertainment, Six Flags Entertainment, Ferrari World Abu Dhabi, Warner Bros. Discovery, Miral, Disney Experiences, Qiddiya Investment Company, Aldar Properties, Others |
| Regions Covered | Middle East: Saudi Arabia, UAE, Qatar, Israel, Kuwait, Oman, Bahrain, Iran, Iraq, Rest of Middle East |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle East Amusement Parks Market Strategic Shifts
Digital infrastructure investments are fragmenting control systems across Middle East amusement parks, distributing operational intelligence from centralized command centers to edge-based ride controllers and guest-facing mobile platforms.
Edge computing architectures are decentralizing ride control and safety monitoring functions across distributed sensor networks. Regional operators in Dubai and Abu Dhabi are deploying these systems to reduce single-point-of-failure risks in high-throughput attractions. This decentralization is compressing emergency response protocols while enabling real-time capacity optimization that shifts guest flows based on live wait-time data.
SFDA's 2024 technical inspection digitization mandate is forcing compliance documentation onto blockchain-verified platforms. The regulation eliminates paper-based certification trails and enables cross-border equipment transfers between Saudi and UAE parks. Water park operators face the steepest adaptation costs due to corrosion-sensitive sensor calibration requirements.
Visitor purchasing patterns are fragmenting across subscription, single-day, and dynamic pricing tiers. Saudi domestic tourists increasingly favor annual pass models that lock in visitation frequency, while UAE-based tourists remain anchored to bundled hospitality packages. This bifurcation is most pronounced in Riyadh, where Qiddiya's pre-opening membership drives have captured substantial advance commitment pools.
Middle East Amusement Parks Market Segmentation
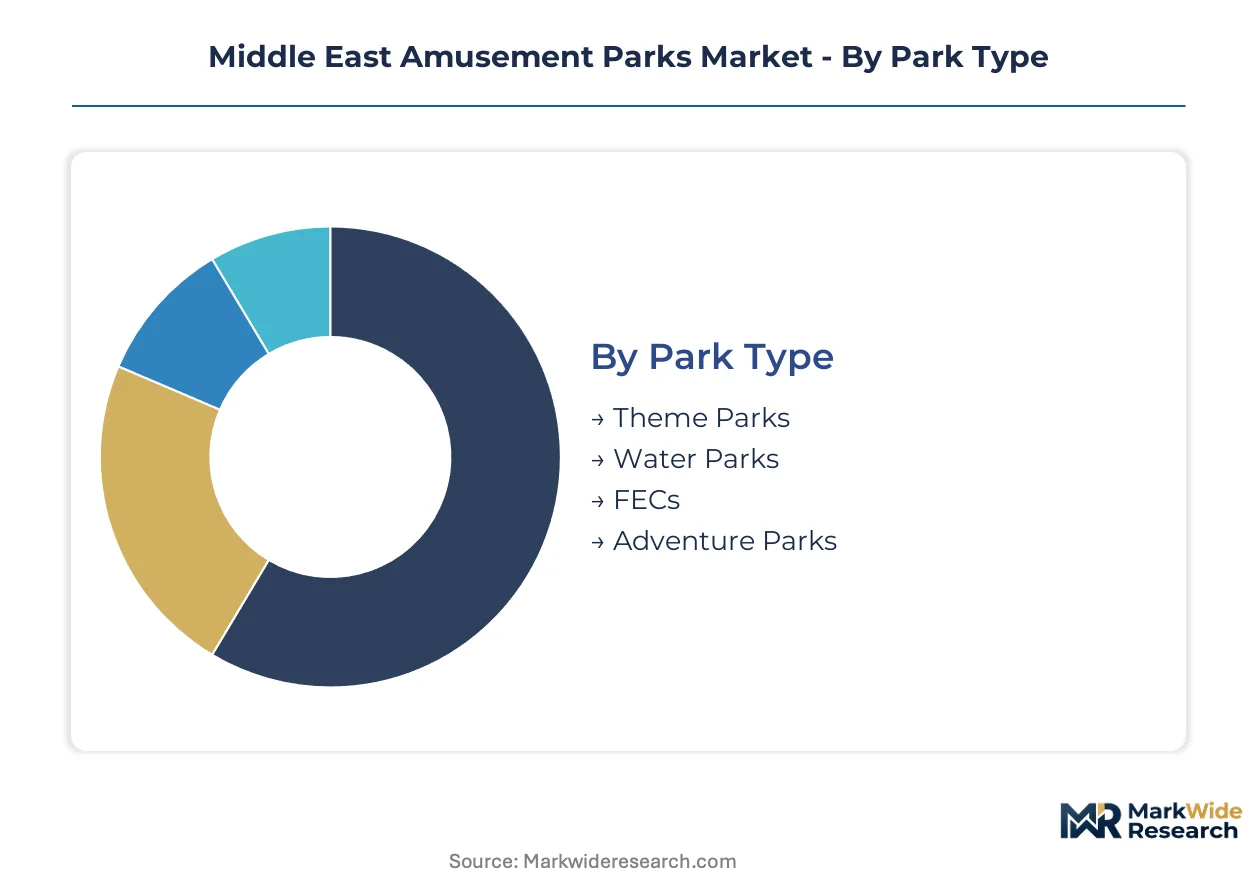
Middle East amusement parks deploy distinct capital allocation strategies across park formats, with upgrade cycles varying from 3-year attraction refreshes to decade-long master plan overhauls. Understanding these segment boundaries clarifies where operators concentrate maintenance budgets versus expansion investments.
Park Type:
Replacement cycles differ sharply across park formats, with water infrastructure demanding more frequent capital redeployment than mechanical ride portfolios.
- Theme Parks:These facilities integrate intellectual property licensing with high-capacity mechanical attractions and immersive environments. Demand concentrates in Dubai and Abu Dhabi, where Yas Island and Dubai Parks anchor regional visitor flows through multi-day destination packaging.
- Water Parks:Temperature-responsive operations with seasonal compression drive accelerated slide and filtration system replacement. Abu Dhabi's Environment Agency consumption caps constrain expansion capacity, forcing operators toward recirculation technology upgrades rather than footprint growth.
- FECs:Compact urban entertainment centers in Riyadh and Jeddah shopping districts capture weekday family traffic through rotating redemption game lineups.
- Adventure Parks:Saudi Arabia's wadi and desert terrain supports zipline and obstacle course developments outside traditional tourism corridors.
Volume placements concentrate in Theme Parks; the faster expansion belongs to FECs.
Attraction Type:
Cost tiers separate attraction investments, with steel-track roller coasters commanding premium engineering outlays against lower-capital show-based alternatives.
- Roller Coasters:Steel and aluminum track systems sourced from European fabricators require 15-20 year structural recertification cycles. SFDA's digitized inspection mandates are compressing maintenance windows for Saudi operators.
- Water Rides:Flume and river rapid systems face accelerated corrosion protocols in Gulf humidity conditions. UAE operators front-load seasonal opening approvals to maximize winter revenue capture.
- Live Shows:Theatrical productions and stunt performances deliver per-capita spending through premium seating tiers without mechanical depreciation burdens.
- Themed Attractions:Dark rides and walk-through environments license Hollywood intellectual property for fixed-term territorial exclusivity.
Capital deployment concentrates in Roller Coasters; the steepest expansion trajectory belongs to Themed Attractions.
Customer Segment:
Application patterns diverge across visitor types, with corporate event programming requiring dedicated venue infrastructure absent from family-oriented zones.
- Families:Multi-generational groups generate baseline weekday traffic through annual pass subscriptions. Riyadh's Qiddiya pre-opening membership drives captured substantial advance commitment pools from Saudi domestic households.
- Teenagers:Thrill-seeking segments concentrate social media shareability demands on high-intensity mechanical attractions. Dubai operators optimize queue designs for mobile content capture to sustain organic marketing.
- Tourists:International visitors anchor revenue in UAE gateway cities through bundled hospitality packages combining park access with hotel stays.
- Corporate Groups:Private event rentals and team-building programming command per-capita premiums exceeding standard admission multiples.
Visitor volume concentrates in Families; the sharpest share gains belong to Corporate Groups.
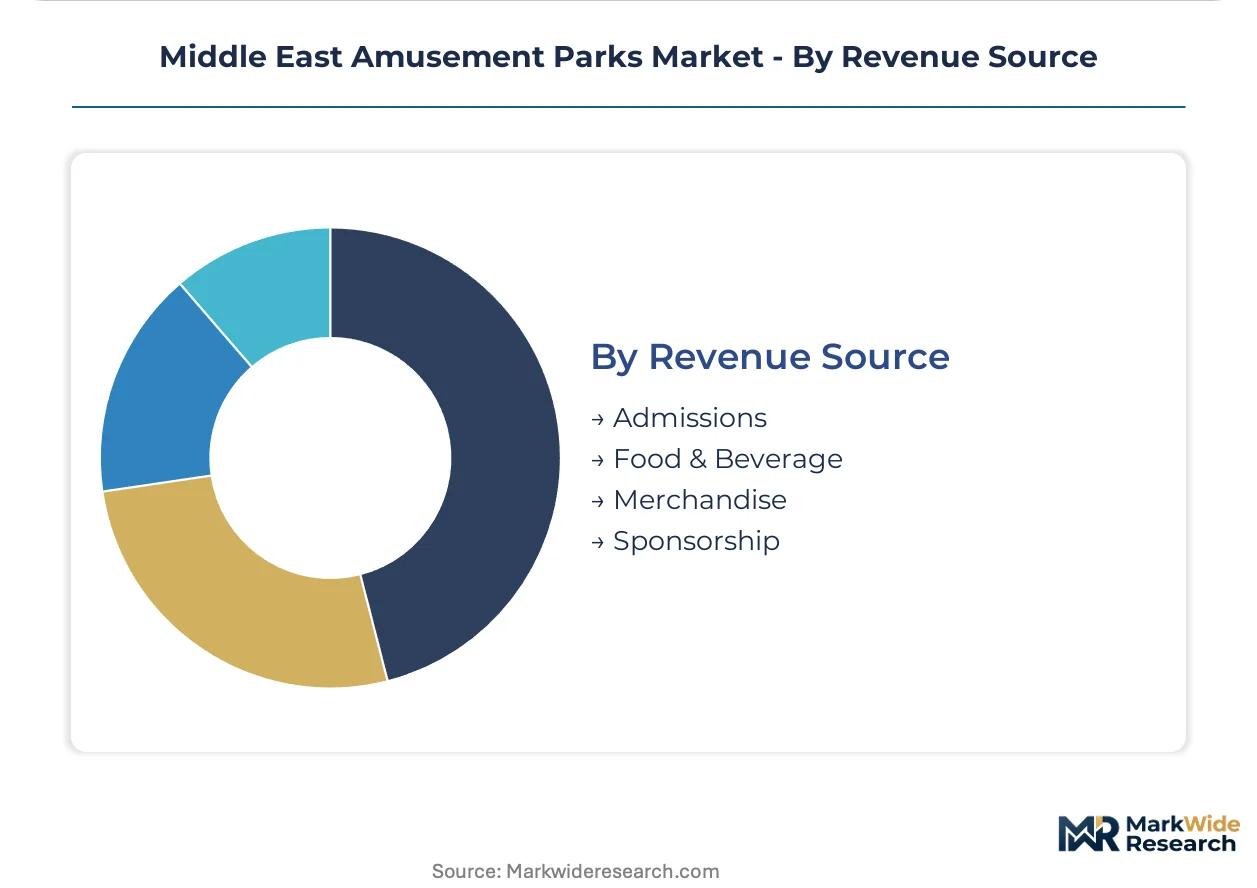
Revenue Source:
Margin structures vary across revenue streams, with in-park hospitality delivering superior per-visit economics against fixed-price admission models.
- Admissions:Controlled-access entry systems generate base load revenue through dynamic pricing tiers responding to seasonal demand curves. Saudi annual pass penetration is climbing fastest among domestic segments.
- Food & Beverage:Captive dining environments within park perimeters sustain extended visit durations. UAE operators integrate celebrity chef partnerships to differentiate from off-site alternatives.
- Merchandise:Licensed character products face territorial carve-out complexity that fragments regional distribution rights.
- Sponsorship:Brand integration deals with Gulf consumer goods companies offset capital costs for new attraction launches.
Revenue concentration sits with Admissions; the fastest margin expansion belongs to Food & Beverage.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Middle East amusement parks market concentrates consumption in the UAE and Saudi Arabia while sourcing ride engineering and steel fabrication from European suppliers. Domestic production capabilities remain nascent, forcing capital deployment toward imported mechanical systems and specialized construction services.
United Arab Emirates
Dubai and Abu Dhabi anchor regional visitor flows through integrated destination clusters on Yas Island and Dubai Parks. MOHAP mandates wellness-entertainment hybrid zoning that extends visitor dwell times through co-located hospitality infrastructure. Dubai's Department of Tourism and Commerce Marketing facilitates bundled visa-hotel-park packages that capture extended-stay economics from South Asian and European source markets.
Saudi Arabia
Riyadh and Jeddah corridors absorb the bulk of domestic entertainment investment following General Entertainment Authority licensing reforms. SFDA's unified ride certification standards eliminate redundant testing cycles for cross-border operators, compressing project timelines. Qiddiya's mega-development outside Riyadh positions Saudi Arabia as a counterweight to established UAE hubs through unprecedented scale and localization mandates requiring 70% domestic content.
Qatar
Doha's entertainment infrastructure leverages FIFA World Cup legacy assets to sustain year-round visitor engagement. The Qatar Tourism Authority channels investment toward family-oriented attractions that capture weekend traffic from the concentrated expatriate professional population. Lusail's planned entertainment district represents a nascent cluster competing for regional visitor spending.
Kuwait
Kuwait City's family entertainment centers capture pent-up domestic demand amid limited regional-scale theme park alternatives. The Ministry of Commerce and Industry regulates commercial entertainment licensing with emphasis on safety certification alignment with Gulf Cooperation Council standards. Salmiya and Al Rai shopping districts concentrate FEC deployment in retail-anchored configurations.
Oman
Muscat's entertainment infrastructure remains underdeveloped relative to UAE and Saudi benchmarks, presenting first-mover positioning for integrated resort developers. The Ministry of Heritage and Tourism prioritizes cultural-entertainment hybrid attractions that differentiate from pure thrill-ride competitors. Al Hajar mountain terrain supports adventure park formats outside traditional coastal tourism corridors.
Middle East Amusement Parks Market Competitive Environment
Top-tier vendors anchor destination-scale developments, while mid-tier operators concentrate on compact urban entertainment centers and seasonal attractions. The market structure reflects a bifurcation between integrated resort developers controlling multi-park clusters and specialized ride system suppliers delivering turnkey mechanical attractions. Strategic archetypes include intellectual property licensors extracting territorial exclusivity premiums, destination developers bundling hospitality and retail, and engineering specialists fabricating steel-track systems. Competitive moves center on exclusive IP licensing negotiations and backward integration into themed construction services.
Within the integrated destination tier, Miral and Qiddiya Investment Company exemplify divergent geographic strategies anchoring rival hub developments. Miral occupies a position representing UAE-based cluster management across Yas Island properties, while Qiddiya Investment Company anchors Saudi Arabia's counter-positioning through Riyadh mega-project scale. Among Hollywood-studio licensors, Warner Bros. Discovery and Universal Destinations & Experiences represent archetypes of character-driven seasonal programming versus destination-scale immersive environments.
| Leading Market Players |
|---|
| Universal Destinations & Experiences |
| SeaWorld Parks & Entertainment |
| Six Flags Entertainment |
| Ferrari World Abu Dhabi |
| Warner Bros. Discovery |
| Miral |
| Disney Experiences |
| Qiddiya Investment Company |
| Aldar Properties |
| Others |
Value Chain & Pricing Dynamics
Premium-attraction pricing divergence against family-entertainment commoditization manifests in both ticket architecture and supply sourcing patterns across Middle East amusement parks. Operators commanding intellectual property licensing leverage extract superior per-capita economics through bundled hospitality packages, while compact urban centers compete on volume throughput with standardized redemption hardware sourced from Asian fabricators.
Pricing Analysis
Margin tightening in family entertainment centers reflects accelerated depreciation cycles on redemption game hardware. Three-tier pricing structure across premium, standard, and economy levels separates Yas Island's IP-anchored destinations from Riyadh's domestic-focused annual pass models. Steel-track roller coaster procurement from European specialists sustains premium positioning in UAE gateway markets. Corporate event programming exhibits lowest price sensitivity through private venue rental premiums.
Supply Chain Analysis
Specialty steel and aluminum alloy supply rests on German and Swiss engineering fabricators dominating roller coaster track production. Ride control systems draw from Italian and Dutch electromechanical specialists, while filtration and recirculation equipment for water parks sources from Scandinavian environmental technology providers. Euro-denominated contract exposure creates currency risk concentration for Saudi mega-developments. Distribution runs through turnkey EPC contractors delivering integrated attraction packages to Gulf operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Vertical-integration momentum is accelerating across themed construction services and captive fabrication capabilities as operators respond to Saudi localization mandates and extended European engineering lead times.
For Market Incumbents: Lock in intellectual property exclusivity through multi-year territorial licensing renewals before Qiddiya's full opening fragments character rights availability. Secure backward integration into themed construction services to capture 70% domestic content value pools mandated by Saudi Arabia's General Entertainment Authority. Miral's cluster management model offers template for cross-property annual pass ecosystems that deepen visitor loyalty against emerging Riyadh competition. For New Entrants and Emerging Players: Enter via Oman's underdeveloped Muscat corridor, where integrated resort zoning permits first-mover positioning absent entrenched UAE competition. Target adventure park formats leveraging Al Hajar mountain terrain for differentiation from coastal mechanical-ride competitors. Partner with Qatar Tourism Authority on Lusail entertainment district assets to access FIFA World Cup legacy infrastructure without greenfield capital deployment. For Investors and Strategic Acquirers: Re-rating potential sits with domestic fabrication specialists given Saudi Arabia's localization mandate enforcement and Qiddiya's phased opening cadence. Themed construction capabilities and ride maintenance services represent acquisition archetypes with captive demand visibility across Riyadh and Jeddah corridors. Monitor SFDA inspection digitization compliance costs as inflection indicator for operational scalability among mid-tier operators.| Strategic Initiative | Industry Significance |
|---|---|
| Exclusive IP Licensing Renewal | Warner Bros. Discovery and Universal leverage character portfolios to secure territorial exclusivity premiums ahead of competitive openings. |
| Backward Integration into Themed Construction | Qiddiya Investment Company's captive fabrication capabilities capture 70% domestic content mandates while reducing European subcontractor dependency. |
| Annual Pass Subscription Ecosystem | Miral's Yas Island cluster locks visitor commitment across multiple properties through unified membership architecture. |
| Edge Computing Safety Infrastructure | Dubai operators deploy distributed sensor networks to satisfy MOHAP emergency response protocols while optimizing real-time capacity. |
| Water Recirculation Technology Upgrade | Abu Dhabi water parks invest in filtration systems to comply with Environment Agency consumption caps without footprint expansion. |
Study Parameters
Multi-period observation of visitor throughput metrics, licensing agreement structures, and regulatory filing patterns anchored the trend analysis, supplemented by interviews with park operations directors, themed construction project managers, ride system procurement leads, and General Entertainment Authority licensing officials. Secondary validation drew from SFDA technical inspection protocols, MOHAP wellness-entertainment zoning mandates, UAE Department of Culture and Tourism visitor statistics, and European ride fabricator order backlogs. Bottom-up attraction-level capacity modeling triangulated against top-down national entertainment investment flows.
Input-output matrices mapped capital deployment across park format segments, attraction type tiers, and revenue source categories throughout the projection horizon. Modeled dimensions included park scale tier, intellectual property integration depth, customer segment composition, and geographic corridor concentration. CAGRs derived from installed base expansion rates, replacement cycle compression, and per-capita spending trajectory assumptions. Forecast inputs incorporated Saudi expatriate population growth curves and UAE visa facilitation policy evolution.
Forecast precision tightens around the base case; tail outcomes carry wider variance under steel price volatility conditions and European engineering capacity constraints. Analytical boundaries exclude post-2035 project pipelines and speculative regulatory shifts beyond currently enacted localization mandates. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Destination Management and Attractions
Global Desert Tourism Market
Destination Management and Attractions
Monaco Casino Tourism Market
Destination Management and Attractions
Jordan Faith-Based Tourism Market
Destination Management and Attractions
Europe Destination Wedding Market
Destination Management and Attractions
Thailand Culinary Tourism Market
Destination Management and Attractions
Safari Tourism Market
Destination Management and Attractions
Culinary Tourism Market
Destination Management and Attractions
India Culinary Tourism Market
Destination Management and Attractions
Heritage Tourism Market
Destination Management and Attractions
India Casino Tourism Market
Destination Management and Attractions
Destination Wedding Market
Destination Management and Attractions
Desert Island Tourism Market
Destination Management and Attractions
Theme Park Tourism Market
Destination Management and Attractions
Geotourism Market
Destination Management and Attractions
Art Tourism Market
Destination Management and Attractions
North America Amusement Parks Market