
 Global Telecom Cable Market | 2026-2036
Global Telecom Cable Market Size, Share, and Industry Trends Forecast 2026-2036
Global Telecom Cable Market Outlook
The capital-intensity divergence between integrated fiber producers and assembly-only competitors is rotating competitive advantage toward players with captive preform capacity. Prysmian Group leverages vertical integration from optical fiber to cable systems across European and North American projects. Hengtong Group anchors its position through massive manufacturing scale and domestic supply chain control in China. Sumitomo Electric Industries differentiates via advanced pure silica core fiber technology for submarine and long-haul networks.
Global telecom cable encompasses transmission media engineered from glass optical fiber, copper conductors, or hybrid compositions, typically specified by attenuation rates, bandwidth-distance products, and tensile strength ratings for installation stress. These products serve the fundamental commercial purpose of carrying voice, video, and data signals across terrestrial, submarine, and premises networks. Optical fiber commands the dominant margin pool as telecom operators replace legacy copper infrastructure, while hybrid cable segments gain traction in data center applications where single-cable power-plus-data convergence reduces pathway congestion. Coaxial cable retains structural importance in residential connectivity and broadcasting distribution networks despite fiber encroachment.
FCC broadband deployment mandates in the United States, EU Green Deal material compliance requirements under REACH, and China's MIIT fiber network standards collectively shape product certification, halogen-free jacketing adoption, and market access conditions. India's BIS cable standards and TRAI infrastructure sharing rules further constrain import sourcing while promoting domestic manufacturing qualification. Stakeholders must monitor regulatory divergence on flame retardancy classifications and circular economy material recovery targets as these standards increasingly determine competitive eligibility in procurement tenders.
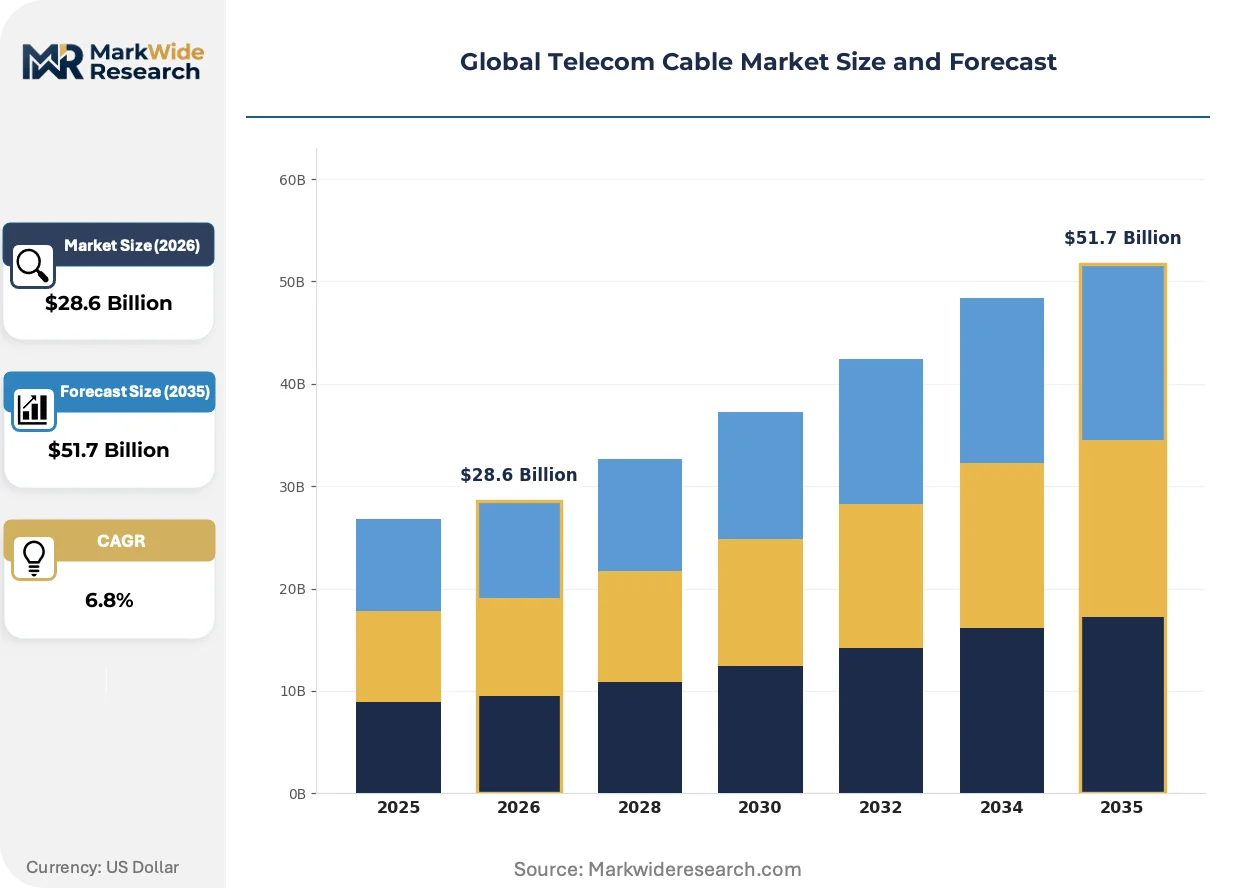
Market Dynamics
Preform-to-cable vertical integration is redefining competitive moats as optical fiber demand outstrips merchant supply capacity, forcing operators to qualify integrated suppliers for multi-year backbone contracts.
Growth Catalysts
- EU Green Deal material mandates:Halogen-free jacketing requirements under REACH are accelerating cable specification upgrades across European utility tenders, displacing legacy PVC-sheathed products.
- India's BharatNet initiative:Government-funded rural fiberization is creating sustained demand for low-attenuation single-mode cable across 600,000 village gram panchayats.
- Submarine cable system expansion:Hyperscaler-funded transoceanic routes are pulling high-fiber-count armored cable demand through specialized marine installation contractors.
Market Restraints
- Silicon tetrachloride supply concentration:Purified precursor manufacturing clusters in China and Germany create single-source vulnerability for optical fiber dopant chemistry.
- Copper price volatility:Hybrid cable margins compress unpredictably when London Metal Exchange copper futures spike above rolling procurement hedges.
- FCC environmental review timelines:National Historic Preservation Act compliance for terrestrial fiber routes extends project approval cycles by 8-14 months in federally managed corridors.
Strategic Opportunities
- Indonesia's Palapa Ring completion:Eastern island provinces still lack submarine backhaul connectivity, opening greenfield cable-laying contracts for domestic-international joint ventures.
- Data center power-plus-data convergence:Hybrid copper-fiber composite cables are penetrating hyperscale facilities to reduce underfloor pathway congestion.
- China MIIT circular economy targets:Mandated recycling recovery rates for cable jacketing polymers are creating closed-loop material service contracts.
Industry Challenges
- Specialized fusion s technician scarcity:Precision fiber termination skills lag deployment timelines in emerging African and Southeast Asian markets.
- Multi-standard certification stacking:Simultaneous UL, CE, and BIS fire-resistance testing extends product qualification cycles by 4-6 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Telecom Cable Market |
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $51.7 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Optical Fiber, Coaxial Cable, Twisted Pair, Hybrid Cable Application: Telecom Networks, Data Centers, Residential Connectivity, Broadcasting End User: Telecom Operators, Internet Service Providers, Enterprises, Government Installation Type: Indoor, Outdoor, Aerial, Undersea |
| Companies Covered | NKT, Hengtong Group, Prysmian Group, Zhongtian Technology, Southwire, Nexans, Sumitomo Electric Industries, Fujikura, LS Cable & System, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Telecom Cable Market Strategic Shifts
Material science breakthroughs and procurement model compression are restructuring how cable performance is validated and purchased, shifting value capture toward specification-integrated suppliers.
Multicore optical fiber is miniaturizing transmission infrastructure by packing twelve independent signal paths within a single 250-micron coating diameter. Submarine system operators are piloting this technology for trans-Pacific capacity expansion without additional cable ship deployments. The structural consequence is miniaturizing repeater station footprint requirements and compressing per-bit physical infrastructure cost curves.
REACH SVHC candidate list expansion is forcing reformulation of flame-retardant phosphorus additives in polyethylene cable jackets. European cable assemblers face 18-month material requalification timelines to maintain CE marking validity. Submarine and railway signaling cable segments are absorbing the highest compliance costs due to dual fire-resistance and low-smoke toxicity specifications.
Consolidated procurement through hyperscaler direct sourcing is disintermediating traditional distribution channels for high-volume data center interconnect orders. Tier-1 cloud operators now specify cable assemblies through direct engineering engagement with integrated manufacturers. This pattern concentrates most visibly in Northern Virginia and Frankfurt data center clusters where single-site fiber counts exceed 100,000 strands.
Global Telecom Cable Market Segmentation
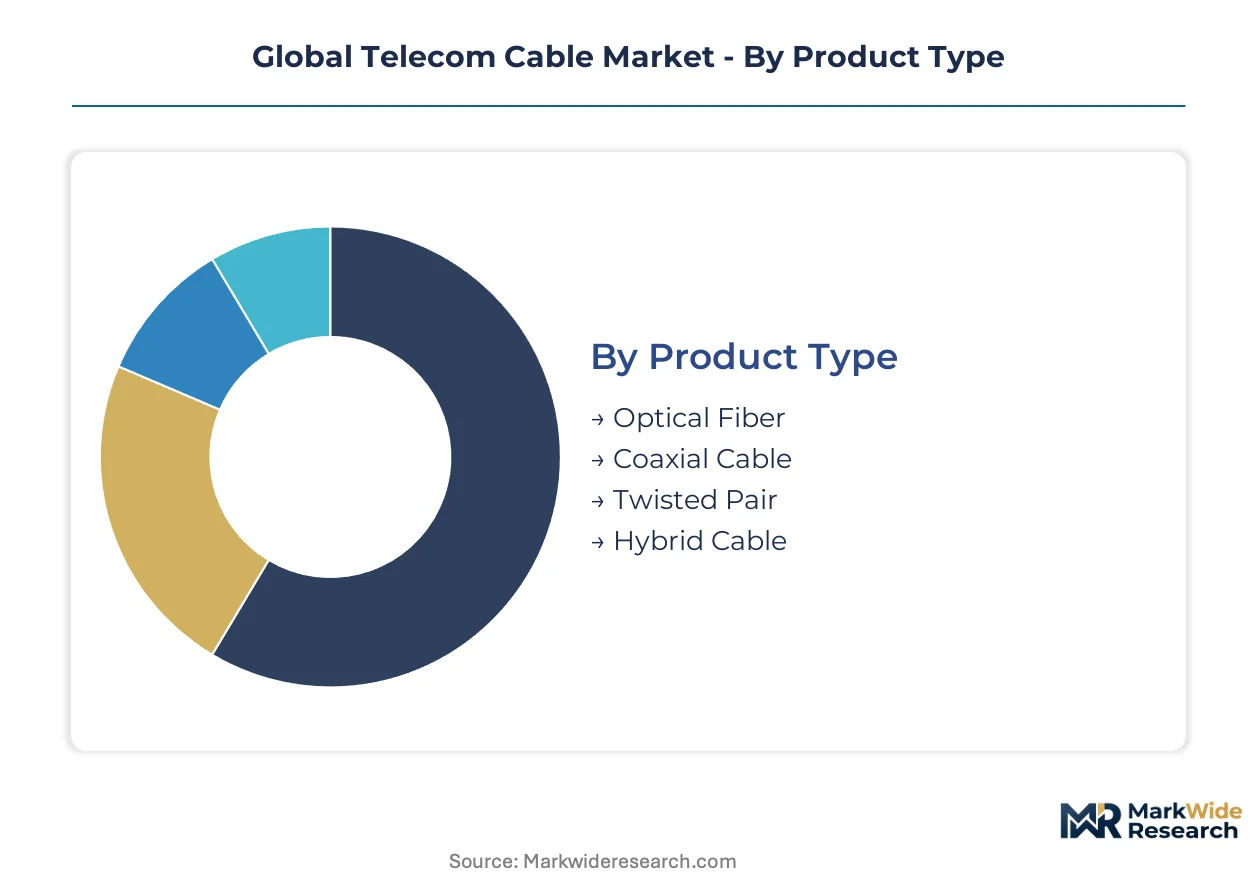
Telecom cable procurement patterns fragment sharply across product architectures and deployment environments. Understanding these divisions reveals where specification power concentrates and which integration strategies command premium positioning.
Product Type:
Domestic production clusters dominate optical fiber and coaxial supply in China, Germany, and the United States, while hybrid and twisted pair categories rely more heavily on cross-border component sourcing.
- Optical Fiber:Glass-based transmission media specified by attenuation coefficients and bandwidth-distance products. Demand concentrates in India's BharatNet rural fiberization and hyperscaler submarine routes, where low-loss single-mode specifications face qualified supplier shortages.
- Hybrid Cable:Composite copper-fiber constructions enabling power-plus-data convergence. Data center operators in Northern Virginia and Frankfurt specify these for underfloor pathway reduction, compressing installation labor costs.
- Coaxial Cable:Copper-core shielded constructions retain residential broadband distribution share. Legacy cable operators in the United States and Latin America maintain embedded plant investments.
- Twisted Pair:Copper conductor pairs for premises voice and low-speed data. Enterprise LAN refresh cycles in Japan and Western Europe sustain residual demand.
Optical fiber holds the largest share; momentum sits with hybrid cable.
Application:
Cost-tier stratification separates backbone infrastructure from premises connectivity, with certification requirements and volume economics diverging sharply.
- Telecom Networks:Long-haul terrestrial and metro fiber systems carrying aggregated traffic. India's gram panchayat fiberization and EU Green Deal-compliant utility tenders drive specification intensity for halogen-free armored cable.
- Data Centers:High-strand-count fiber interconnects and power-data hybrid assemblies. Hyperscalers in Singapore, Ireland, and Oregon bypass distribution channels through direct manufacturer engagement.
- Residential Connectivity:Last-mile drops and in-building distribution. Fiber-to-the-home rollouts in Indonesia's Palapa Ring completion zones and Brazil's underserved municipalities create greenfield demand.
- Broadcasting:Coaxial and fiber links for content distribution networks. Stadium and venue connectivity upgrades in Qatar and Saudi Arabia absorb specialized armored coaxial.
Telecom networks capture the dominant revenue pool; data centers are expanding most quickly.
End User:
Customer-type concentration determines contract structure, with government tenders favoring domestic content and hyperscalers prioritizing engineering integration.
- Telecom Operators:Incumbent and competitive carriers building backbone and access infrastructure. China's MIIT fiber network standards and India's BIS certification requirements constrain their supplier qualification lists.
- Internet Service Providers:Regional and municipal broadband deployers. FCC broadband deployment mandates in the United States shape their procurement timelines and environmental review obligations.
- Enterprises:Campus and private network operators. Financial services firms in London and Singapore specify low-latency fiber for trading infrastructure.
- Government:Defense, rural broadband, and smart city programs. Indonesia's eastern island provinces and India's TRAI infrastructure sharing rules influence their contracting patterns.
Telecom operators command the deepest specification authority; government segments show the steepest expansion trajectory.
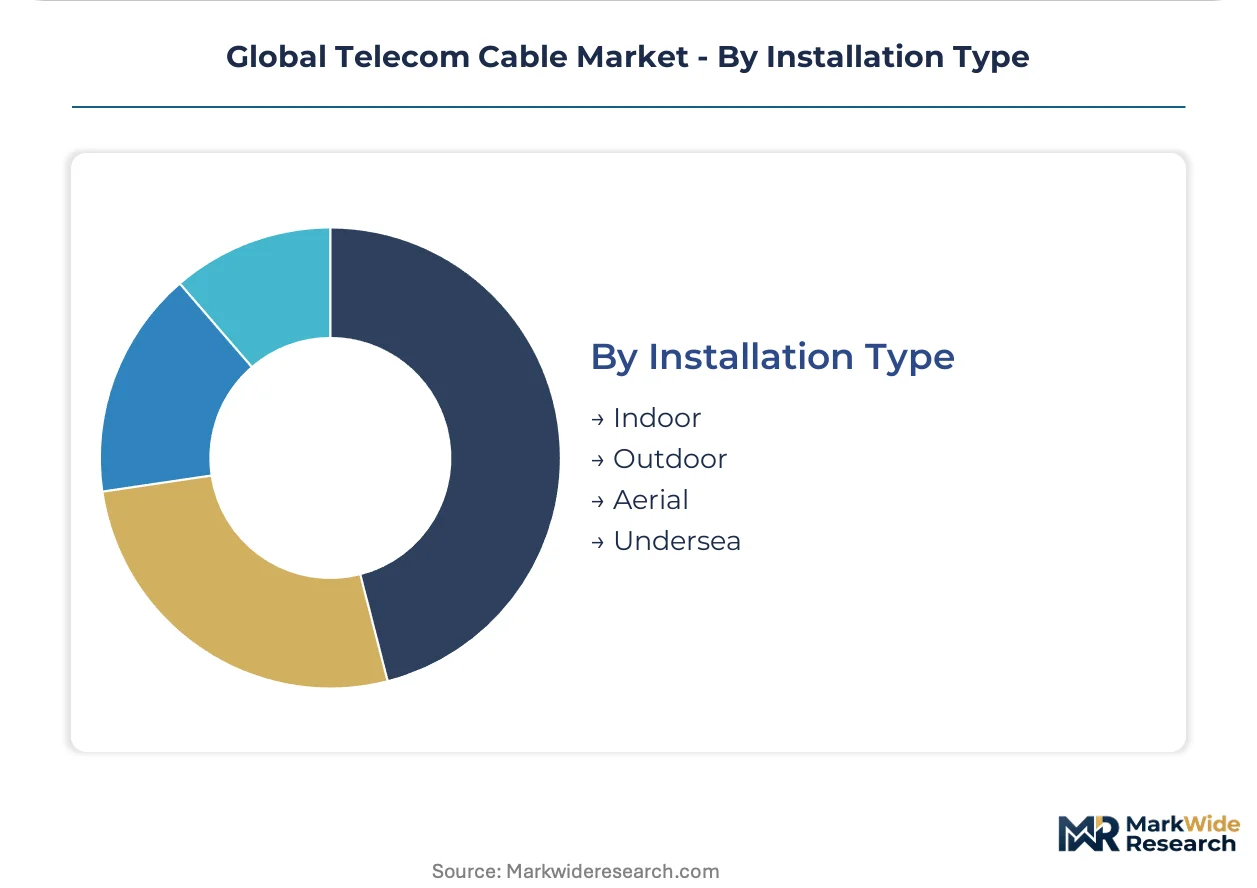
Installation Type:
Volume distribution skews toward outdoor terrestrial deployment, while margin concentration sits with specialized submarine and aerial applications.
- Outdoor:Direct-buried and conduit-deployed cable for terrestrial routes. FCC National Historic Preservation Act compliance extends approval cycles by 8-14 months in federally managed United States corridors.
- Undersea:Armored fiber systems for transoceanic and coastal links. Specialized marine installation contractors in Japan and France qualify limited supplier pools for hyperscaler-funded Pacific routes.
- Indoor:Riser and plenum-rated cable for buildings and data centers. REACH SVHC candidate list expansion forces 18-month material requalification for European jacketing formulations.
- Aerial:Self-supporting and lashed cable for pole-mounted deployment. Rural electrification corridors in Brazil and the Philippines provide shared infrastructure access.
Outdoor installation holds the largest share; undersea commands the highest margin concentration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price sensitivity in telecom cable procurement varies sharply by geography. India's government-funded rural programs prioritize cost efficiency, while hyperscaler submarine routes in Japan and specialized European utility tenders absorb premium specifications for low-attenuation and halogen-free products.
United States
FCC broadband deployment mandates and National Historic Preservation Act compliance extend terrestrial fiber project timelines by 8-14 months in federally managed corridors. Northern Virginia data center clusters drive direct manufacturer engagement for high-strand-count interconnects exceeding 100,000 fibers per site.
China
MIIT fiber network standards and dual carbon goals reshape material sourcing and energy efficiency mandates for domestic cable production. Yangtze River Delta manufacturing bases anchor massive optical fiber capacity serving both domestic rollouts and export markets.
India
BharatNet rural fiberization targets 600,000 village gram panchayats with sustained demand for low-attenuation single-mode cable. BIS certification requirements and TRAI infrastructure sharing rules constrain import sourcing while promoting domestic manufacturing qualification.
Germany
EU Green Deal REACH mandates on halogen-free jacketing displace legacy PVC-sheathed products across European utility tenders. Western industrial clusters face 18-month material requalification timelines to maintain CE marking validity for railway and submarine cable segments.
Japan
Specialized marine installation contractors qualify limited supplier pools for hyperscaler-funded trans-Pacific submarine routes. Advanced pure silica core fiber technology development concentrates in domestic R&D centers serving long-haul and undersea network specifications.
Global Telecom Cable Market Competitive Environment
A small set of integrated leaders sits above a broader specialist tier in the telecom cable market. Backward integration from optical fiber preform through cable assembly defines the upper tier's competitive moat, while assembly-only competitors face qualified supplier shortages for multi-year backbone contracts. Three archetypes dominate: vertically integrated preform-to-cable manufacturers, scale-driven domestic champions, and technology-differentiated specialists. Capacity expansion and captive preform supply control represent the dominant competitive moves as fiber demand outstrips merchant availability.
Among integrated European manufacturers, Prysmian Group and Nexans occupy positions exemplifying the preform-to-cable control archetype. Hengtong Group anchors the scale-driven tier with massive manufacturing presence and domestic supply chain concentration. Sumitomo Electric Industries represents the technology-specialist vector, with its positioning in advanced fiber formulations for demanding submarine and long-haul applications.
| Leading Market Players |
|---|
| NKT |
| Hengtong Group |
| Prysmian Group |
| Zhongtian Technology |
| Southwire |
| Nexans |
| Sumitomo Electric Industries |
| Fujikura |
| LS Cable & System |
| Others |
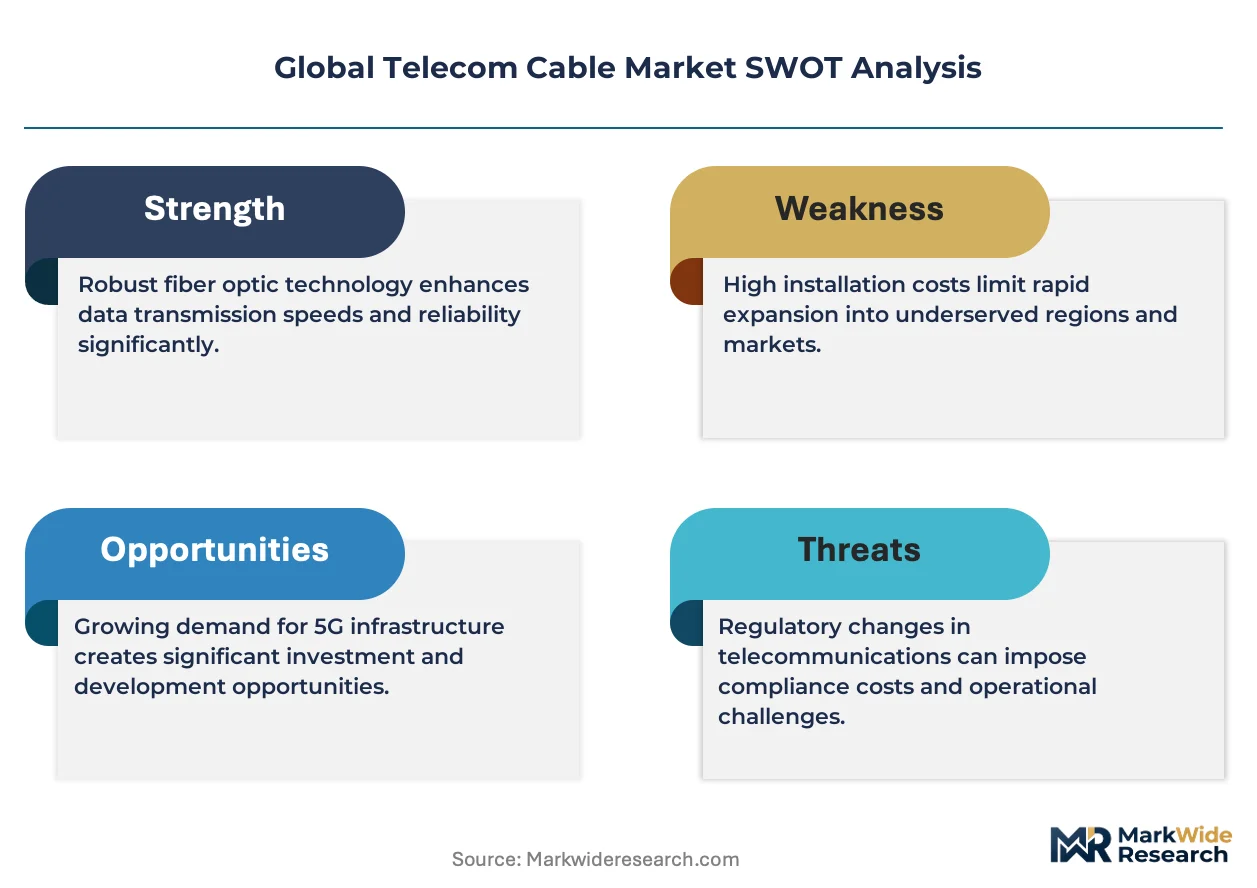
Value Chain & Pricing Dynamics
Halogen-free jacketing substitution for legacy PVC-sheathed cable is simultaneously relocating compound formulation capacity toward EU REACH-compliant manufacturing clusters and compressing margin structures for assemblers facing 18-month requalification timelines.
Pricing Analysis
After-sales service contracts spanning fusion splicing technician deployment and jacketing polymer recovery services drive lifetime value capture for integrated manufacturers. Three-tier pricing structure across premium, standard, and economy levels segments by certification grade and captive preform availability. Cost compression in standard-grade terrestrial fiber is intensifying because merchant preform shortages force buyers toward qualified integrated suppliers. Government-funded rural programs in India exhibit highest price sensitivity, while hyperscaler submarine routes in Japan absorb premium specifications with minimal negotiation leverage.
Supply Chain Analysis
China and Germany anchor purified silicon tetrachloride precursor manufacturing for optical fiber dopant chemistry. Japan and France host specialized marine installation contractors for armored submarine cable deployment. The supply chain draws from concentrated preform production in the Yangtze River Delta, copper conductor rolling mills in the United States, and halogen-free compound blending in Western European industrial clusters. Single-source vulnerability in Chinese and German precursor clusters threatens fiber production continuity. Distribution runs through direct manufacturer engagement for hyperscale data center orders and traditional utility tender channels for telecom operator procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is recovering from the merchant preform capacity shortage cycle, with capital expenditure normalization by hyperscalers on transoceanic submarine routes providing the cyclical impetus.
For Market Incumbents: Consolidate backward integration into optical fiber preform production to defend against emerging Chinese scale players capturing BharatNet tenders. Prysmian Group and Hengtong Group have demonstrated that captive dopant chemistry control secures multi-year backbone contract qualification. Priority investment in REACH-compliant halogen-free jacketing compound capacity protects CE marking validity for European utility procurement.
For New Entrants and Emerging Players: Anchor in Indonesia's eastern island provinces where Palapa Ring completion gaps create greenfield submarine backhaul demand without incumbent supplier lock-in. India's gram panchayat fiberization offers volume scale for domestic manufacturing qualification under BIS standards. Joint venture structures with established marine installation contractors provide the essential go-to-market credibility for undersea cable qualification.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with private equity-backed cable assemblers lacking captive preform capacity and facing margin compression from integrated competitors. Long-term viability over the coming decade hinges on upstream control over optical fiber production rather than assembly-only positioning. The signal to monitor is hyperscaler direct sourcing consolidation in Northern Virginia and Frankfurt data center clusters, which will determine which integrated manufacturers capture volume concentration.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Preform Production | Prysmian Group and Hengtong Group have secured multi-year backbone contracts through captive dopant chemistry control. |
| REACH-Compliant Compound Capacity Expansion | Western European assemblers face 18-month requalification timelines to maintain CE marking validity for utility tenders. |
| Direct Hyperscaler Engagement Model | Tier-1 cloud operators in Northern Virginia now specify cable assemblies through direct engineering relationships. |
| Marine Installation Contractor Partnerships | Specialized contractors in Japan and France qualify limited supplier pools for trans-Pacific submarine routes. |
| Domestic Manufacturing Qualification | India's BIS certification requirements and TRAI infrastructure sharing rules constrain import sourcing for BharatNet. |
Study Parameters
A spread of perspectives from telecom operator procurement directors, cable assembly plant managers, hyperscaler infrastructure planners, and marine installation contractors converged on the working assumptions for demand segmentation. Primary interview insights were validated against secondary sources including FCC broadband deployment filings, EU ECHA REACH substance database updates, India's TRAI infrastructure sharing directives, and MIIT fiber network standard publications. Bottom-up volume estimates from country-level deployment programs were triangulated with top-down capacity assessments from major manufacturing clusters.
Segmentation dimensions modeled include product architecture, installation environment, end-user type, and geographic regulatory cluster across the analysis window. CAGRs were derived from deployment pipeline analysis and capacity expansion announcements. Hyperscaler capex disclosures for transoceanic submarine routes and government-funded rural fiberization budget allocations served as industry-specific forecast inputs.
Material uncertainties — silicon tetrachloride supply disruptions, copper price volatility beyond hedging coverage, and regulatory divergence on flame retardancy classifications — sit outside the modeled envelope. Forecasts reflect assumptions about continued hyperscaler infrastructure investment and government broadband program continuity. Recalibration cycles align with material shifts in FCC funding authorization levels and EU Green Deal material mandate implementation timelines.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Telecommunications Infrastructure
Germany Telecom Towers Market
Telecommunications Infrastructure
Thailand Telecom Towers Market
Telecommunications Infrastructure
Vietnam Telecom Towers Market
Telecommunications Infrastructure
Japan Telecom Market
Telecommunications Infrastructure
Wireless Infrastructure Market
Telecommunications Infrastructure
Fixed-Line Communications Market
Telecommunications Infrastructure
Terrestrial Trunked Radio (TETRA) System Market
Telecommunications Infrastructure
Chile Telecom Tower Market
Telecommunications Infrastructure
United States Telecom Towers Market
Telecommunications Infrastructure
NLD and ILD Telecom Service Market
Telecommunications Infrastructure
OTN Equipment Market
Telecommunications Infrastructure
Nigeria Telecom Tower Market
Telecommunications Infrastructure
Global Telecom System Integration Market
Telecommunications Infrastructure
Fixed Telephony Service Market
Telecommunications Infrastructure
5G Network Infrastructure Market
Telecommunications Infrastructure
Carrier Infrastructure in Telecom Applications Market