
 India Digital Gift Card Market | 2026-2036
India Digital Gift Card Market Size, Share, and Industry Trends Forecast 2026-2036
India Digital Gift Card Market Analysis
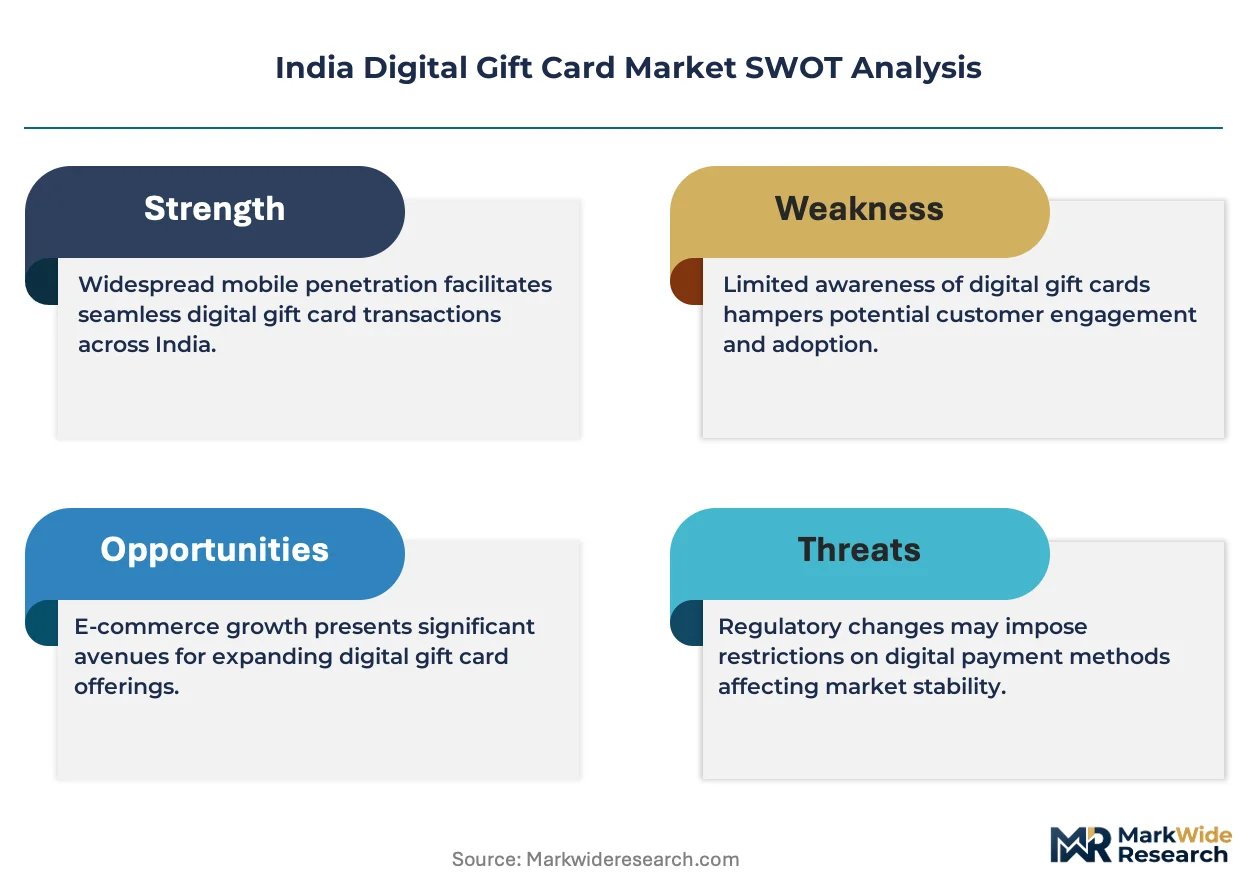
A capital-intensity divergence between bank-led issuers and agile fintech platforms is bifurcating competitive dynamics in India's digital gift card space. HDFC Bank Ltd. leverages its prepaid instrument license and branch infrastructure to anchor corporate bulk issuance. GyFTR (Vouchagram) specializes in aggregator APIs that connect fragmented retail redemption networks. Amazon.com, Inc. extends its Prime member base into closed-loop gifting through tight wallet integration.
India digital gift cards constitute prepaid stored-value instruments distributed electronically via QR codes, UPI handles, or encrypted token strings, typically denominated in Indian Rupees and redeemable across affiliated merchant networks or closed brand ecosystems. These instruments function as non-cash payment credentials, with RBI-mandated KYC tiers determining load limits and interoperability scope. Retail Gift Cards dominate transaction volumes through festive-season consumer purchasing, while Corporate Gift Cards capture expanding margin pools as HR departments digitize employee reward budgets. E-commerce Platforms as an end-user segment absorbs disproportionate flow, with Amazon.com, Inc. and Flipkart Internet Private Limited driving redemption infrastructure investment.
RBI's prepaid payment instrument regulations, BIS data security standards, and the Digital Personal Data Protection Act collectively govern issuer licensing, fund safeguarding, and customer consent architecture in this market. RBI's semi-closed PPI framework mandates escrow arrangements and capital reserves that filter out unlicensed entrants. Stakeholders must monitor evolving interoperability mandates between PPI wallets and UPI rails, as regulatory clarity on cross-wallet redemption will determine whether aggregator platforms or closed-loop brand programs capture the next wave of corporate procurement budgets.
Market Dynamics
Prepaid payment instrument interoperability mandates from RBI are fragmenting issuer business models and forcing capital reallocation between closed-loop brand programs and open-wallet aggregators. This regulatory pressure is compressing margins for unlicensed distributors while accelerating licensed bank-fintech partnerships.
Growth Catalysts
- Corporate HR digitization:Employee reward budgets at IT services firms are migrating from physical vouchers to API-distributed digital credentials, creating recurring B2B revenue streams for licensed issuers.
- RBI's semi-closed PPI framework:Escrow arrangements and capital reserve requirements filter out informal competitors, concentrating volume among compliant entities with established banking partnerships.
- UPI rails integration:Real-time settlement infrastructure enables instant redemption across merchant networks, reducing friction in festive-season consumer purchasing cycles.
Market Restraints
- KYC tier complexity:RBI-mandated identity verification thresholds create onboarding friction for rural and semi-urban recipients lacking formal documentation.
- Escrow capital lock-up:Minimum reserve requirements strain fintech platforms' working capital, privileging bank-led issuers with deeper balance sheets.
- Closed-loop redemption concentration:Dominant e-commerce platforms capture disproportionate gift card flow, limiting merchant diversity for aggregator networks.
Strategic Opportunities
- Tier-2 and Tier-3 urban expansion:Underpenetrated cities in Gujarat and Tamil Nadu present whitespace for localized redemption networks targeting manufacturing sector employee bases.
- Digital Personal Data Protection Act compliance:Consent-architecture investments create competitive moats for early adopters in corporate gifting procurement.
- UPI-QR convergence:Unified payment interface integration with dynamic QR issuance enables offline retail redemption without dedicated POS hardware.
Industry Challenges
- API standardization gaps:Fragmented technical specifications between bank cores and fintech aggregators delay corporate client onboarding timelines.
- Interoperability uncertainty:Pending RBI clarity on cross-wallet redemption rules freezes procurement budget allocations from risk-averse enterprise buyers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | India Digital Gift Card Market |
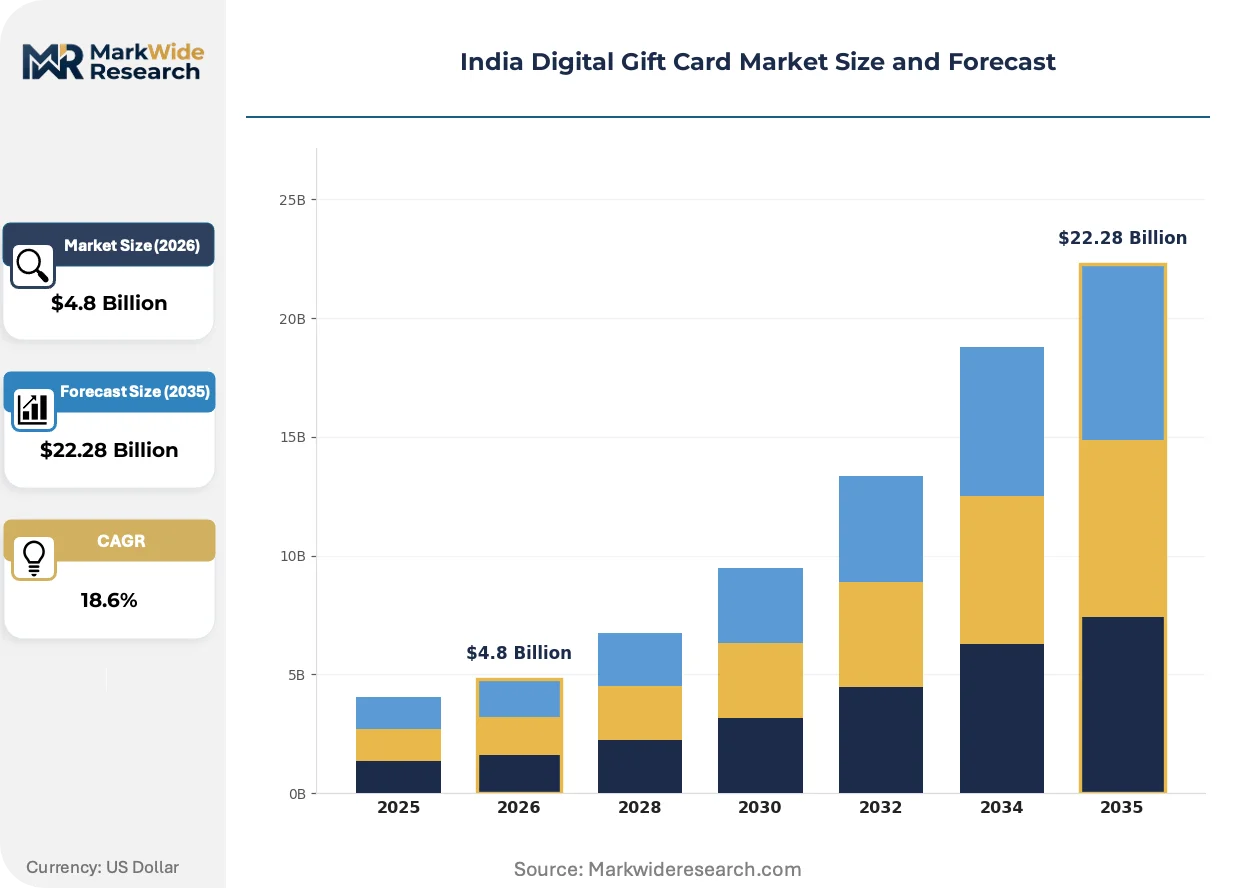
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $22.28 Billion |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Retail Gift Cards, Corporate Gift Cards, Prepaid Cards, Promotional Cards End User: Consumers, Retailers, Corporates, E-commerce Platforms Distribution Channel: Online Platforms, Brick-and-Mortar Stores, Mobile Apps, Social Media Customer Type: Individual Users, Business Clients, Non-Profits, Educational Institutions |
| Companies Covered | HDFC Bank Ltd., IGP.com, Amazon.com, Inc., YOUGotaGift.com Ltd., PayU LazyPay, Flipkart Internet Private Limited, GyFTR (Vouchagram), GiftPay (Unified Incentives Services Private Limited), Pine Labs, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
India Digital Gift Card Market Emerging Trajectories
Tokenized credential architecture is displacing static card numbers across issuer platforms, enabling real-time balance tracking and fraud-resistant distribution. This shift is compressing legacy voucher clearing cycles and forcing infrastructure reinvestment.
Blockchain-based gift card issuance is fragmenting provenance tracking and secondary market liquidity. Early pilots at retail conglomerates enable peer-to-peer transfer without issuer intermediation. Corporate treasury departments are evaluating these credentials for cross-border employee rewards, though RBI foreign exchange regulations currently restrict outbound redemption.
RBI's evolving PPI interoperability mandates are reshaping competitive positioning between closed-loop and open-loop programs. Semi-closed wallet licenses now require UPI handle integration, forcing brand-specific gift card programs to open redemption networks. Maharashtra-based issuers are accelerating compliance investments ahead of anticipated full interoperability deadlines.
Behavioral segmentation by occasion type is displacing generic denomination purchasing. Festival-specific curated bundles combining multiple merchant credentials are capturing premium margins from urban consumers. Bangalore technology employers are piloting occasion-triggered automated distribution tied to HRIS systems, embedding gift cards into employee lifecycle management workflows.
India Digital Gift Card Market Segmentation
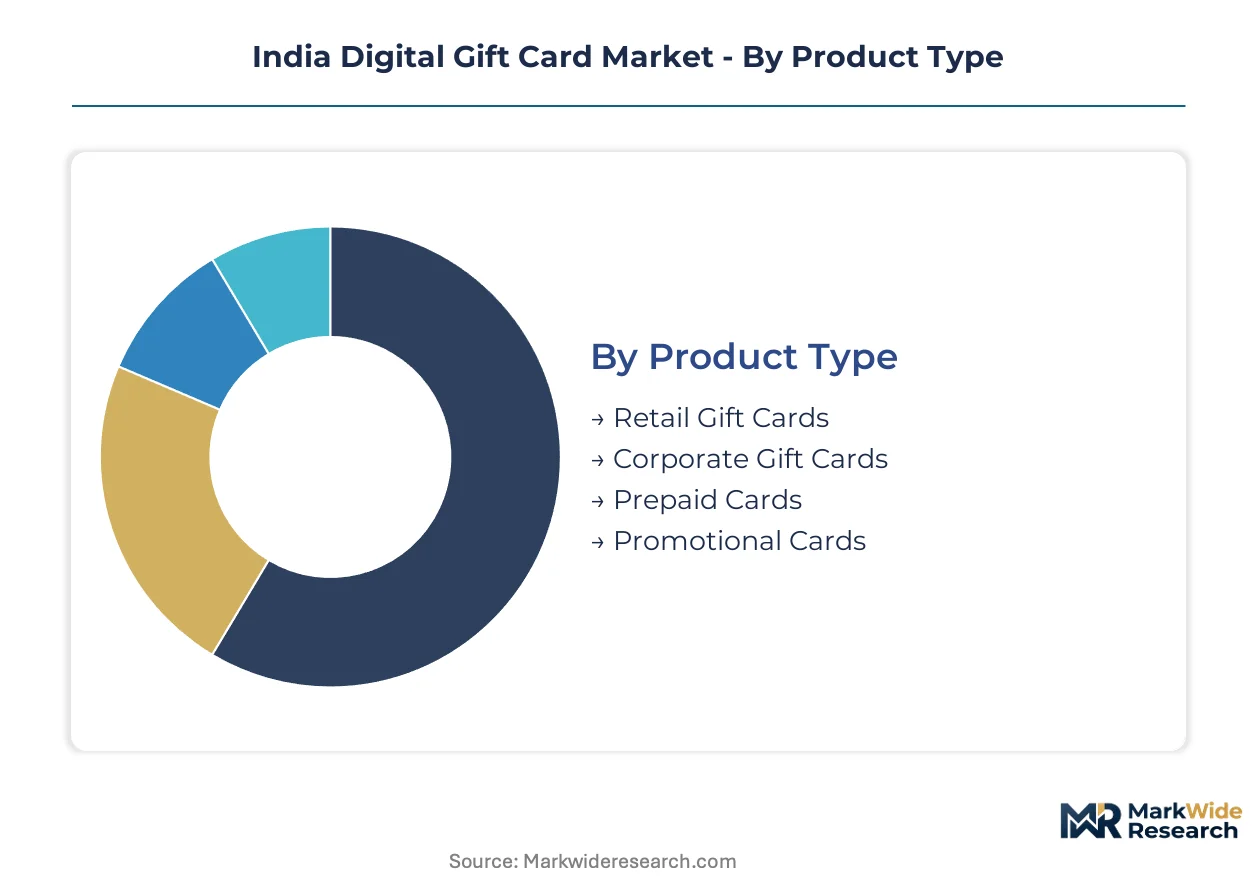
Segmentation in India's digital gift card market reveals distinct margin architectures across product categories and distribution modes. RBI's prepaid instrument licensing tiers create structural advantages for certain issuer types over others.
Product Type:
Margin pools concentrate heavily in corporate bulk issuance programs where API-based distribution reduces per-unit acquisition costs.
- Retail Gift Cards:Denominated stored-value instruments distributed through e-commerce checkouts and brand apps for festive-season consumer purchasing. Demand concentrates in Maharashtra and Karnataka during Diwali and year-end cycles, with Amazon and Flipkart redemption networks absorbing disproportionate flow. RBI's semi-closed PPI framework limits load values for non-KYC holders, constraining rural penetration.
- Corporate Gift Cards:API-distributed credentials integrated into HRIS systems for employee rewards and channel incentives. IT services firms in Bangalore and Hyderabad are migrating physical voucher budgets to digital rails, creating recurring B2B revenue streams with lower churn than consumer segments.
- Prepaid Cards:Reloadable instruments with broader merchant acceptance than closed-loop brand credentials.
- Promotional Cards:Campaign-specific issuance tied to product launches or customer acquisition programs.
The dominant share belongs to Retail Gift Cards, while Corporate Gift Cards is closing the gap fastest.
End User:
Application intensity varies sharply between consumer self-purchase and enterprise procurement workflows.
- Consumers:Individual purchasers selecting denomination-based credentials for personal gifting occasions. Festival-specific curated bundles combining multiple merchant credentials are capturing premium margins from urban consumers in Mumbai and Delhi NCR.
- Corporates:HR and procurement departments digitizing employee reward budgets through licensed issuer APIs. Manufacturing sector employers in Gujarat and Tamil Nadu present whitespace for localized redemption network expansion.
- Retailers:Merchant partners accepting gift card redemption through integrated POS systems.
- E-commerce Platforms:Digital marketplaces embedding closed-loop gifting into wallet architectures and checkout flows.
E-commerce Platforms capture the highest redemption velocity, while Corporates show the steepest budget migration trajectory.
Distribution Channel:
Cost-to-serve diverges dramatically between instant digital delivery and physical retail fulfillment.
- Online Platforms:Web-based issuance through issuer portals and aggregator marketplaces with immediate QR code or token delivery. UPI rails integration enables real-time settlement, compressing legacy voucher clearing cycles.
- Mobile Apps:Native application distribution with push notification delivery and in-wallet storage. Tokenized credential architecture is displacing static card numbers across these platforms.
- Brick-and-Mortar Stores:Physical retail counters issuing printed credentials with scratch-off redemption codes.
- Social Media:Messaging-embedded gifting through platform partnerships and peer-to-peer transfer features.
Online Platforms hold the dominant transaction volume, while Mobile Apps are expanding most quickly among younger demographics.
Customer Type:
Contract value and retention economics favor institutional relationships over individual account acquisition.
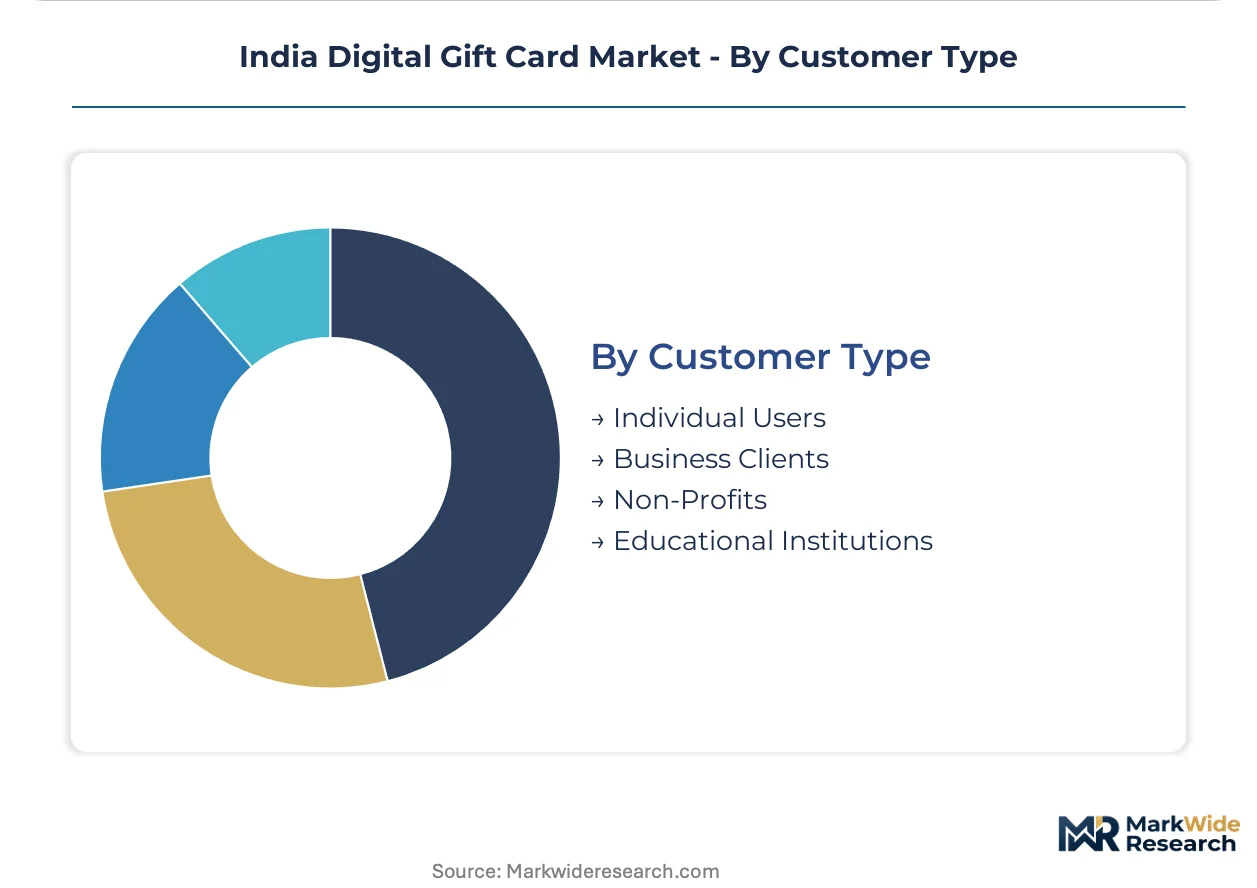
- Business Clients:Enterprise procurement contracts with annual minimum commitments and API integration requirements. Early investments in Digital Personal Data Protection Act compliance create competitive moats in corporate gifting procurement.
- Individual Users:Single-transaction purchasers with high acquisition costs and limited lifetime value.
- Non-Profits:Donation-driven issuance for fundraising and donor recognition programs.
- Educational Institutions:Student incentive and scholarship disbursement applications with seasonal concentration.
Business Clients generate the highest revenue per relationship, while Educational Institutions are gaining share fastest among institutional segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Maharashtra commands premium pricing power through Mumbai's dense corporate procurement clusters, while Karnataka's Bangalore technology corridor extracts volume discounts through consolidated IT services demand. This asymmetry shapes issuer investment allocation across western and southern India.
Maharashtra
Mumbai's financial services sector and Pune's manufacturing belt drive corporate gift card procurement at scale. RBI's semi-closed PPI framework mandates escrow arrangements that favor licensed bank issuers with established presence in the state. Thane and Navi Mumbai host redemption network densification as e-commerce fulfillment infrastructure expands.
Karnataka
Bangalore's technology employers digitize employee reward budgets through API-integrated distribution systems. The state's startup ecosystem accelerates fintech platform development under BIS data security standards. Hyderabad's parallel IT corridor in neighboring Telangana competes for corporate gifting volume through lower cost-to-serve structures.
Gujarat
Surat and Ahmedabad manufacturing clusters present underpenetrated whitespace for localized redemption networks targeting textile and chemical sector employers. The state's industrial promotion policies encourage digital payment adoption through infrastructure subsidies. Vadodara's petrochemical complexes generate emerging demand for channel incentive programs.
Tamil Nadu
Chennai's automotive and electronics manufacturing bases sustain steady corporate gifting demand with seasonal Diwali concentration. The state's MSME density creates fragmented procurement patterns that aggregator platforms target through multilingual app interfaces. Coimbatore's textile machinery sector shows early API adoption for distributor incentives.
Delhi-NCR
National capital region government procurement and Noida-Gurugram BPO clusters generate institutional gift card volume with compliance-heavy tender requirements. The Digital Personal Data Protection Act implementation creates competitive differentiation for consent-architecture investments. Faridabad's engineering goods sector trails in digitization, offering expansion runway.
India Digital Gift Card Market Vendor Landscape
Concentration sits with bank-led issuers leveraging prepaid instrument licenses and branch infrastructure for corporate bulk issuance. The market structure bifurcates between capital-intensive licensed entities and agile fintech aggregators. Three archetypes dominate: banking conglomerates with PPI authorization, technology platforms with closed-loop wallet integration, and API-first aggregators connecting fragmented redemption networks. Competitive moves center on bank-fintech partnership formations and UPI rails integration investments.
Within the banking archetype, HDFC Bank Ltd. anchors corporate procurement relationships through compliance infrastructure. Among platform-integrated players, Amazon.com, Inc. and Flipkart Internet Private Limited exemplify closed-loop ecosystem control. GyFTR (Vouchagram) occupies the aggregator tier, representing API-first connectivity between issuers and dispersed merchant acceptance points.
| Leading Market Players |
|---|
| HDFC Bank Ltd. |
| IGP.com |
| Amazon.com, Inc. |
| YOUGotaGift.com Ltd. |
| PayU LazyPay |
| Flipkart Internet Private Limited |
| GyFTR (Vouchagram) |
| GiftPay (Unified Incentives Services Private Limited) |
| Pine Labs |
| Others |
Supply Flow & Price Mechanics
API-driven credential distribution replacing legacy voucher clearing is redrawing procurement geography toward Maharashtra and Karnataka while compressing margin structures for unlicensed intermediaries. This substitution simultaneously elevates licensed bank-fintech partnerships to premium pricing tiers and strands informal distributors in unsustainable cost-to-serve economics.
Pricing Analysis
The customization-premium spread separates standard QR-code issuance from API-integrated HRIS distribution with real-time balance tracking and fraud-resistant tokenization. Three-tier pricing structure across premium, standard, and economy levels reflects KYC tier complexity, with full-KYC corporate bulk contracts commanding 40-60% spreads over limited-KYC retail denominations. Cost compression in the aggregator tier is intensifying because RBI escrow requirements lock working capital while UPI rails commoditize settlement infrastructure. Manufacturing sector employers in Gujarat exhibit highest price sensitivity due to fragmented procurement patterns, whereas Bangalore IT services firms demonstrate lowest sensitivity given digitization mandates and compliance-heavy tender requirements.
Supply Chain Analysis
RBI's semi-closed PPI licensing chokepoint concentrates credential issuance among Mumbai-based banking conglomerates and Bangalore fintech platforms with established escrow partnerships. Technology infrastructure draws from domestic cloud providers, tokenization SDK vendors, and UPI-NPCI settlement rails, while merchant acceptance networks feed from fragmented retail POS systems and e-commerce checkout integrations. Single-source vulnerability sits with NPCI's UPI infrastructure monopoly, where technical outages or policy shifts cascade through redemption networks. Distribution runs through licensed issuer portals, mobile wallet applications, and API-integrated corporate procurement systems with real-time credential delivery.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Licensed prepaid instrument authorization represents the scarcest operational capability in this market, with fewer than 30 entities holding valid RBI semi-closed PPI permits against hundreds of unlicensed distributors. This authorization gap stratifies competitive economics between compliant and informal market participants.
For Market Incumbents: Shield corporate procurement relationships through accelerated Digital Personal Data Protection Act compliance investments that create consent-architecture moats against emerging API-first aggregators. Deepen vertical integration into UPI-QR convergence capabilities to capture offline retail redemption without dedicated POS hardware, insulating against fintech platform disintermediation. For New Entrants and Emerging Players: White-space in Tamil Nadu MSME procurement presents the most penetrable segment, where fragmented manufacturing bases lack integrated HRIS systems and multilingual app interfaces remain underdeveloped. Target Surat and Ahmedabad textile employers through localized redemption networks with Gujarati-language support and manufacturing-sector-specific merchant partnerships, bypassing saturated Bangalore and Mumbai corporate clusters. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed fintech aggregators holding semi-closed PPI licenses but lacking enterprise sales infrastructure to scale corporate gifting contracts. Five-to-ten-year viability hinges on RBI interoperability mandate resolution, where licensed platforms with established bank partnerships capture procurement budget consolidation. Monitor NPCI circulars on cross-wallet redemption rules as the critical inflection signal determining open-loop versus closed-loop program economics.| Strategic Initiative | Industry Significance |
|---|---|
| UPI-QR Convergence Investment | Enables offline retail redemption without dedicated POS hardware, expanding merchant acceptance density. |
| Digital Personal Data Protection Act Compliance | Creates competitive moats in corporate gifting procurement through consent-architecture differentiation. |
| API-First Aggregator Partnership | Connects fragmented redemption networks between bank-led issuers and dispersed merchant acceptance points. |
| HRIS Integration Development | Embeds gift cards into employee lifecycle management workflows at Bangalore technology employers. |
| Tier-2 Urban Network Expansion | Captures underpenetrated manufacturing sector demand in Gujarat and Tamil Nadu through localized infrastructure. |
Methodological Framework
Initial hypotheses were tested against primary input from prepaid instrument issuers, corporate HR procurement leads, fintech platform engineers, and RBI compliance officers and refined through secondary validation. RBI circulars on PPI interoperability, NPCI technical specifications, SEBI disclosure filings, and BIS data security standards anchored quantitative assumptions. Bottom-up credential volume estimates from issuer APIs and top-down corporate gifting budget allocations from IT services sector disclosures were triangulated against redemption network density metrics.
Variance decomposition across product type, end-user segment, distribution channel, and customer type informed analytical framework construction over the projection horizon. CAGRs were derived from segment-level growth trajectory modeling incorporating UPI rails penetration, corporate HR digitization rates, and RBI regulatory evolution assumptions. Forecast inputs included API distribution cost curves, KYC tier migration patterns, and merchant acceptance point expansion timelines.
Forecasts assume regulatory continuity in RBI's semi-closed PPI framework and NPCI's UPI infrastructure governance; material policy shifts around interoperability mandates or foreign exchange restrictions on outbound redemption would require re-modeling. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
E-Commerce Solutions
Taiwan E-Commerce Market
E-Commerce Solutions
Japan Cross Border E Commerce Market
E-Commerce Solutions
M-Commerce Market
E-Commerce Solutions
Kuwait E-Commerce Market
E-Commerce Solutions
Hyperlocal Delivery App Market
E-Commerce Solutions
Europe E-Commerce Logistics Market
E-Commerce Solutions
Online on-Demand Laundry Service Market
E-Commerce Solutions
United States E-Invoicing Market
E-Commerce Solutions
Italy E-Commerce Market
E-Commerce Solutions
Asia-Pacific Dropshipping Market
E-Commerce Solutions
Finland E-Commerce Market
E-Commerce Solutions
Mobile Commerce Market
E-Commerce Solutions
Africa E-Commerce Market
E-Commerce Solutions
Croatia E-Commerce Market
E-Commerce Solutions
India D2C E-Commerce Market
E-Commerce Solutions
Qatar E-Commerce Market