
 United Kingdom Same Day Delivery Market | 2026-2036
United Kingdom Same Day Delivery Market Size, Share, and Industry Trends Forecast 2026-2036
United Kingdom Same Day Delivery Market Analytics
Low Emission Zone expansion across Greater London is repositioning fleet economics for same-day operators. Amazon Logistics UK leverages its captive warehouse network to sustain sub-two-hour delivery windows in dense postcodes. DPD UK anchors its competitive stance through a nationwide electric van rollout programme. CitySprint competes by specializing in time-critical medical specimen transport where compliance rigour creates defensible margins.
Same-day delivery denotes logistics services completing order fulfilment within twenty-four hours of purchase confirmation, typically employing hub-and-spoke distribution with micro-fulfilment nodes positioned within fifteen miles of recipient concentrations. Courier services dominate volume flows, while pharmaceutical product types carry the densest margin pools due to cold-chain integrity requirements and GDP (Good Distribution Practice) compliance overhead. Business-to-Consumer delivery models absorb the majority of capital deployment as e-commerce platforms integrate slot-based scheduling APIs directly into checkout flows.
The UK's Traffic Commissioner enforces operator licensing standards that dictate vehicle maintenance intervals and driver hour limits, while HSE guidelines govern manual handling protocols in last-mile sortation facilities. DVSA roadside inspections and impending ZEV mandate thresholds from the Department for Transport are accelerating diesel fleet retirement timelines. Stakeholders must monitor whether congestion charging boundary extensions to Bristol and Birmingham replicate London's demand compression effects on delivery radius profitability.
Market Dynamics
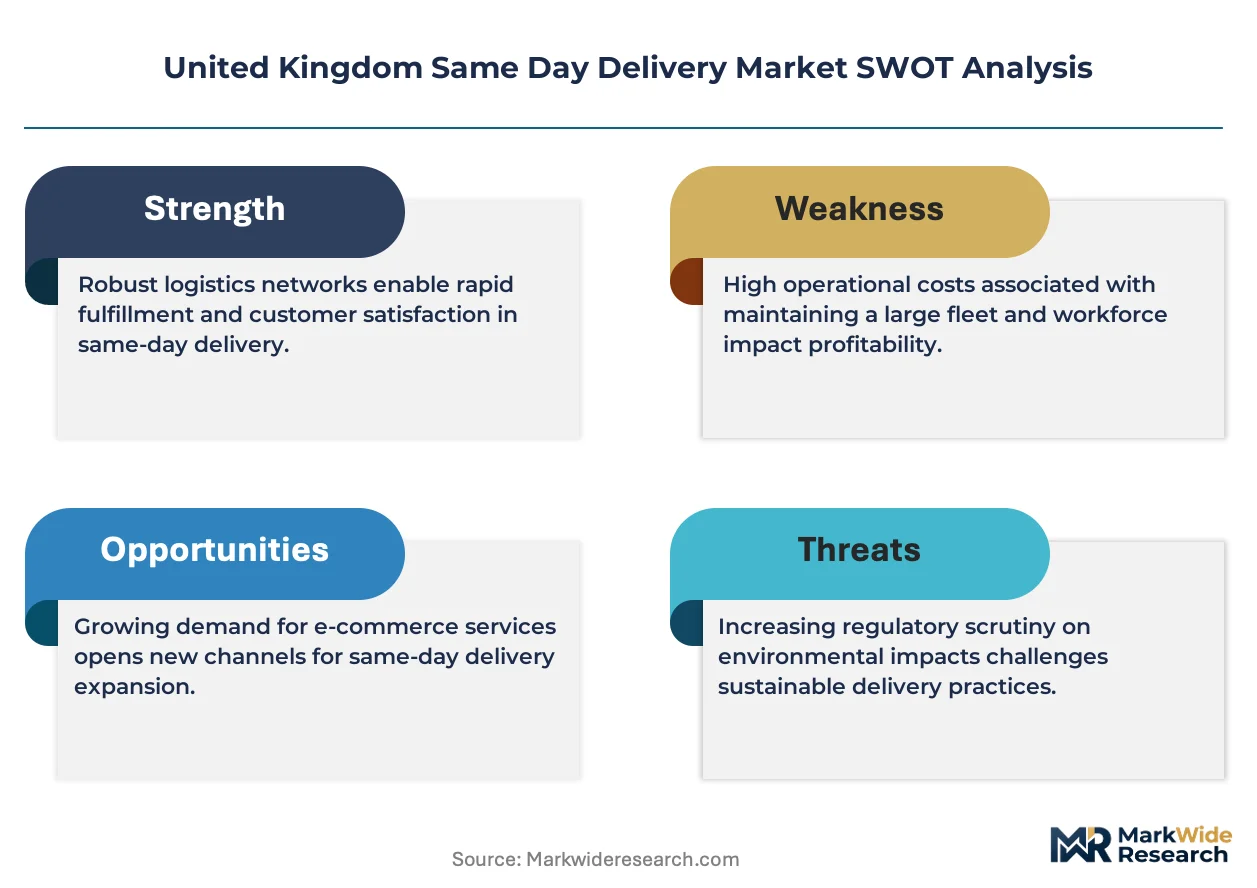
The UK's Low Emission Zone expansion is compressing delivery radius economics while forcing wholesale fleet electrification. Operators must absorb ZEV mandate compliance costs or forfeit access to dense metropolitan revenue pools.
Growth Catalysts
- Department for Transport ZEV Mandate:The 2030 diesel van phase-out deadline is accelerating capital deployment into electric fleet infrastructure across Birmingham and Manchester corridors.
- Pharmaceutical cold-chain integrity:GDP compliance requirements for temperature-controlled medical specimen transport create premium service tiers with defensible margin structures.
- Micro-fulfilment node density:Hub-and-spoke networks with sub-fifteen-mile spoke radii are reducing last-mile cost per delivery in Greater London postcodes.
Market Restraints
- Congestion charging boundary creep:DVLA-registered commercial vehicles face escalating daily charges as Bristol and Birmingham evaluate London-style zone replication.
- Driver hour limits:Traffic Commissioner enforcement of operator licensing standards restricts fleet utilisation rates during peak demand windows.
- Electric van payload trade-offs:Battery weight penalties reduce cubic capacity per vehicle, forcing higher trip frequency for equivalent parcel volumes.
Strategic Opportunities
- Scotland and Wales corridor development:Edinburgh and Cardiff metropolitan zones remain underpenetrated by sub-two-hour delivery networks relative to English density.
- API-integrated slot scheduling:Direct checkout flow embedding is displacing third-party courier selection interfaces on independent e-commerce platforms.
- DVSA roadside inspection data monetisation:Telematics-derived compliance scoring creates subscription revenue streams from fleet insurance underwriters.
Industry Challenges
- HGV licence conversion timelines:Van-to-LGV driver reclassification bottlenecks constrain workforce elasticity during seasonal volume spikes.
- Legacy warehouse management system integration:Micro-fulfilment node WMS protocols frequently conflict with parent hub ERP architectures, delaying real-time inventory visibility.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United Kingdom Same Day Delivery Market |
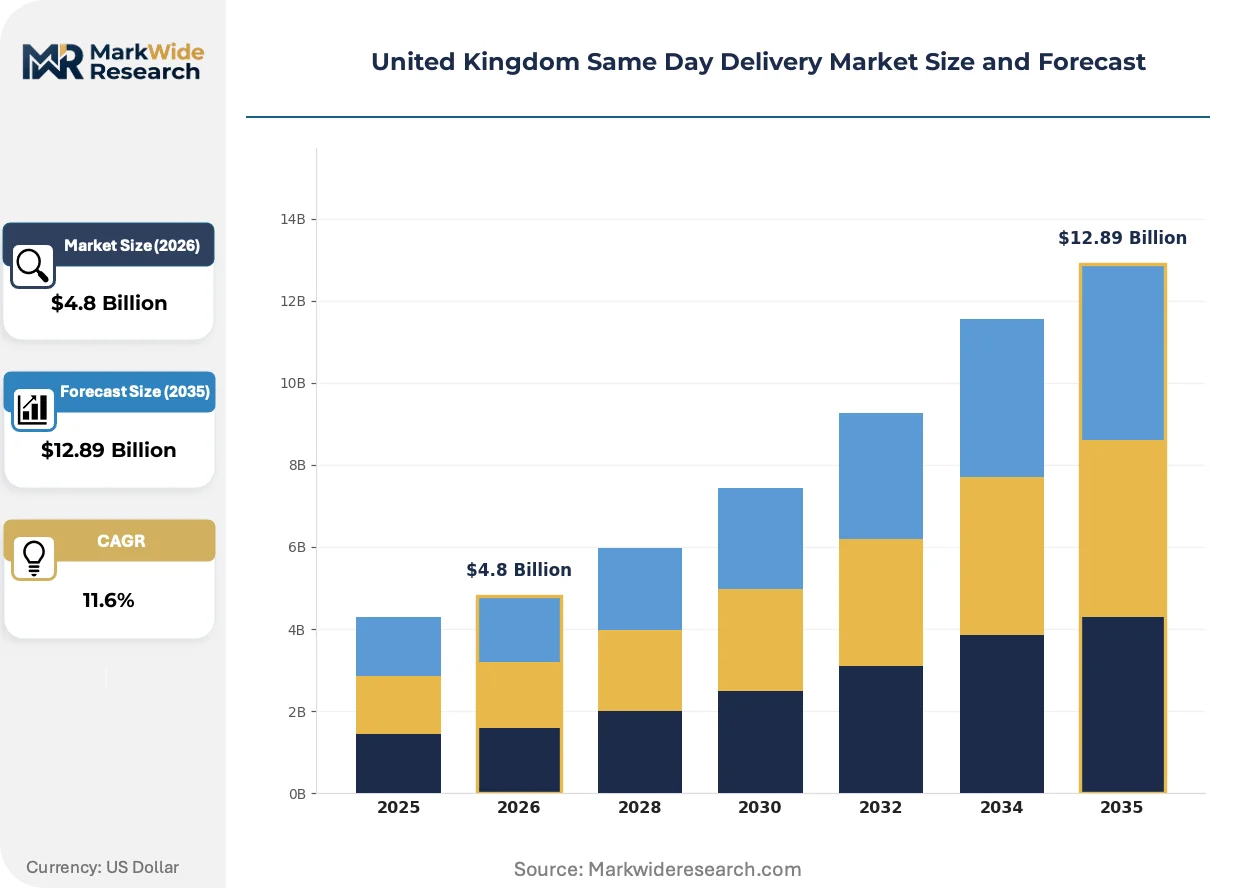
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $12.89 Billion |
| CAGR (2026 – 2036) | 11.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Courier, Logistics, Freight, Express Delivery Delivery Model: Business-to-Consumer, Consumer-to-Consumer, Business-to-Business, E-commerce Product Type: Documents, Perishable Goods, Retail Items, Pharmaceuticals Customer Segment: Enterprises, Individuals, E-commerce Platforms, Local Businesses |
| Companies Covered | Royal Mail, DPD UK, CitySprint, Amazon Logistics UK, Deliveroo Hop, Addison Lee, DHL Supply Chain, Fast UK Group, Evri, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United Kingdom Same Day Delivery Market Evolving Landscape
Operational technology convergence is compressing delivery window commitments while regulatory compliance costs reshape competitive moats. Three forces are restructuring how operators capture value.
Telematics-enabled dynamic routing is consolidating dispatch control from human planners to algorithmic optimisation engines. Pharmaceutical and grocery verticals with temperature-sensitive cargo are adopting these platforms fastest. The shift is consolidating mid-market courier networks into technology-dependent cost structures that favour scale.
REACH-aligned battery supply chain due diligence requirements are elevating procurement compliance overhead for electric fleet operators. The regulation mandates full material provenance documentation for lithium-ion cells. UK-based operators sourcing from non-EU suppliers face extended vendor qualification timelines that compress vehicle deployment schedules.
Slot-based scheduling preference is displacing open-window delivery tolerance among Business-to-Consumer buyers. E-commerce checkout flows now embed time-definite arrival commitments as default options. This pattern concentrates demand into narrow temporal bands across London and Birmingham metropolitan zones, intensifying peak capacity requirements.
United Kingdom Same Day Delivery Market Segmentation
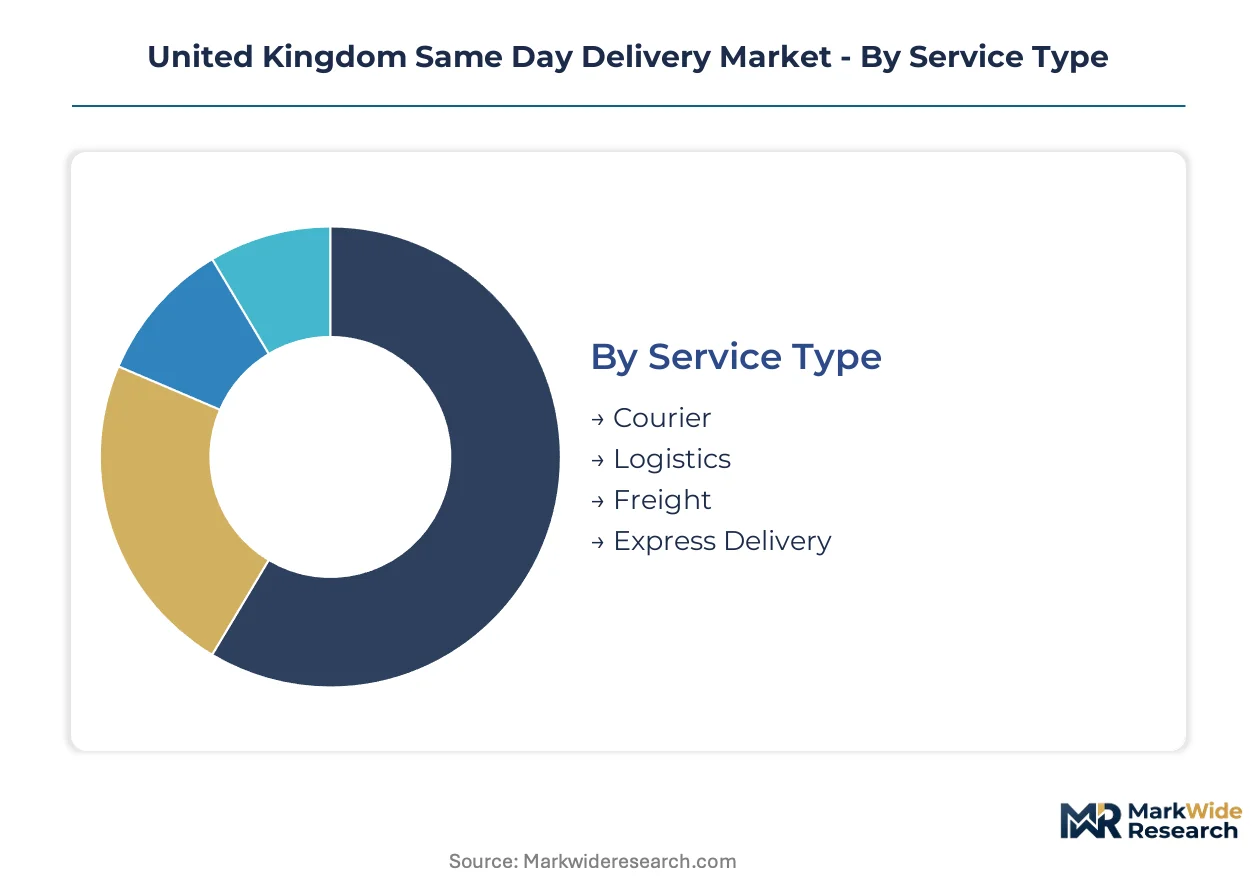
Same-day delivery operators in the United Kingdom segment their service architecture across four dimensions that dictate fleet configuration, pricing power, and regulatory exposure. Each segmentation axis reveals distinct margin structures and capital intensity requirements that shape competitive positioning within metropolitan corridors.
Service Type:
Supply concentration in courier services reflects the dominance of hub-and-spoke networks with sub-fifteen-mile spoke radii across Greater London postcodes.
- Courier:Hub-and-spoke distribution employing micro-fulfilment nodes positioned within fifteen miles of recipient concentrations. Demand concentrates in pharmaceutical and grocery verticals where temperature-controlled last-mile capabilities command premium positioning in Birmingham and Manchester metropolitan corridors.
- Logistics:Integrated warehousing and transportation management spanning inventory storage through final-mile handoff. Fleet utilisation rates face compression from Traffic Commissioner enforcement of driver hour limits during peak demand windows across English urban zones.
- Freight:Larger-capacity vehicle deployment for palletised or bulk consignment movement. Payload economics favour electric van adoption despite battery weight penalties reducing cubic capacity per vehicle.
- Express Delivery:Sub-two-hour delivery windows sustained through captive warehouse network density. DVSA roadside inspections and ZEV mandate thresholds from the Department for Transport accelerate diesel fleet retirement timelines for operators serving dense postcodes.
Today's leader: Courier. Tomorrow's challenger: Express Delivery.
Delivery Model:
Cost tier differentiation separates capital-light intermediary models from infrastructure-heavy captive networks.
- Business-to-Consumer:Direct checkout flow embedding via slot-based scheduling APIs absorbs the majority of capital deployment as e-commerce platforms integrate time-definite arrival commitments. HSE guidelines govern manual handling protocols in last-mile sortation facilities handling high-volume B2C flows.
- E-commerce:Platform-native fulfilment with slot-based scheduling preference displacing open-window delivery tolerance among buyers. Demand concentrates into narrow temporal bands across London and Birmingham metropolitan zones, intensifying peak capacity requirements.
- Business-to-Business:Contracted volume commitments with enterprise procurement functions. GDP compliance requirements for temperature-controlled medical specimen transport create premium service tiers with defensible margin structures.
- Consumer-to-Consumer:Peer-to-peer consignment movement through digital marketplace interfaces. Edinburgh and Cardiff metropolitan zones remain underpenetrated by sub-two-hour delivery networks relative to English density.
Volume dominance: Business-to-Consumer. Margin expansion: E-commerce.
Product Type:
Margin concentration tracks regulatory compliance overhead and cold-chain integrity requirements.
- Pharmaceuticals:Temperature-controlled medical specimen transport governed by GDP compliance standards. CitySprint and specialist operators capture defensible margins through compliance rigour that generalist networks cannot replicate.
- Perishable Goods:Time-definite cold-chain fulfilment for grocery and foodservice verticals. Micro-fulfilment node density in Greater London postcodes reduces last-mile cost per delivery for temperature-sensitive cargo.
- Documents:High-frequency low-weight consignment movement with minimal handling complexity. DVLA-registered commercial vehicles face escalating daily charges as congestion charging boundaries expand.
- Retail Items:General merchandise fulfilment spanning apparel, electronics, and household goods. REACH-aligned battery supply chain due diligence requirements elevate procurement compliance overhead for electric fleet operators serving this volume-heavy segment.
Premium capture: Pharmaceuticals. Volume scale: Retail Items.
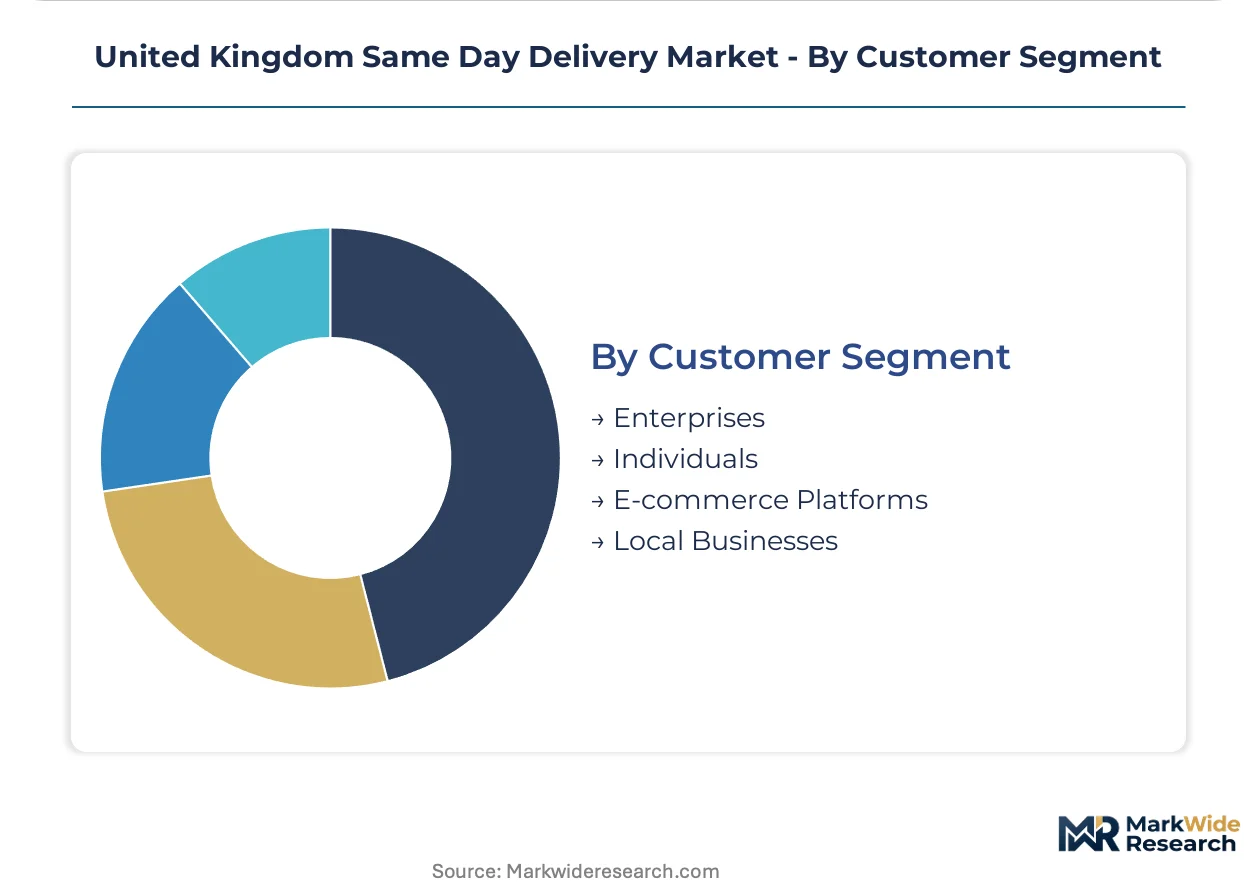
Customer Segment:
Application concentration determines API integration depth and contract tenure structures.
- E-commerce Platforms:Direct checkout flow embedding displaces third-party courier selection interfaces on independent platforms. Telematics-enabled dynamic routing consolidates dispatch control from human planners to algorithmic optimisation engines for these high-volume accounts.
- Enterprises:Multi-year contracted relationships with dedicated fleet allocation and SLA-governed performance metrics. Legacy warehouse management system integration conflicts with parent hub ERP architectures delay real-time inventory visibility.
- Local Businesses:Fragmented demand aggregation through marketplace interfaces or direct sales relationships. Scotland and Wales corridor development in Edinburgh and Cardiff zones offers expansion headroom relative to saturated English markets.
- Individuals:On-demand transactional usage with minimal loyalty attachment and high price sensitivity. Slot-based scheduling preference concentrates demand into narrow temporal bands that strain peak capacity.
Integration depth: E-commerce Platforms. Contract stability: Enterprises.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Workforce concentration in Greater London's courier networks anchors national capacity deployment. Driver hour regulations from the Traffic Commissioner constrain utilisation rates across English metropolitan corridors. Scotland and Wales present expansion headroom with underpenetrated sub-two-hour delivery infrastructure.
Greater London
E-commerce platform density and pharmaceutical cold-chain demand concentrate premium same-day volume in the capital. The Low Emission Zone expansion and congestion charging boundary extensions force fleet electrification timelines. Micro-fulfilment node networks in Camden, Croydon, and Stratford postcodes reduce last-mile spoke radii below fifteen miles.
Midlands
Birmingham's metropolitan corridor attracts pharmaceutical specimen transport specialists seeking GDP-compliant infrastructure. The Department for Transport ZEV mandate accelerates diesel van retirement across West Midlands operator fleets. Coventry and Leicester distribution hubs serve as spoke nodes for London hub-and-spoke networks.
North England
Manchester's e-commerce fulfilment density rivals Birmingham for B2C slot-based scheduling volume. Traffic Commissioner enforcement of operator licensing standards restricts peak-hour fleet deployment. Liverpool and Leeds sub-regions remain underserved by sub-two-hour express networks relative to population density.
Scotland
Edinburgh's financial services sector generates time-critical document and specimen transport demand. The Scottish Government's net-zero transport targets advance electric van adoption timelines ahead of UK-wide mandates. Glasgow metropolitan zones lack equivalent micro-fulfilment node density to English corridors.
Wales
Cardiff's pharmaceutical manufacturing base exports temperature-controlled consignments to English distribution networks. DVSA roadside inspection regimes apply uniform compliance standards across Welsh operator fleets. Newport and Swansea corridors remain dependent on Bristol-based hub infrastructure for same-day coverage.
United Kingdom Same Day Delivery Market Competitive Landscape
The competitive structure tilts toward platform-integrated captive networks over third-party courier intermediaries. Royal Mail's universal service obligation and DPD UK's electric fleet programme anchor the consolidated tier. CitySprint and Addison Lee occupy specialist niches where compliance rigour or executive service premiums justify defensible margins. Strategic moves concentrate on micro-fulfilment node densification and API-embedded slot scheduling partnerships with e-commerce platforms.
Among UK-based operators, Royal Mail, DPD UK, and Amazon Logistics UK exemplify three distinct archetypes. Royal Mail represents the incumbent universal service provider with inherited post office infrastructure. DPD UK anchors the parcel network specialist tier through nationwide electric van deployment. Amazon Logistics UK occupies the captive platform-integrated position with warehouse network control enabling sub-two-hour windows. CitySprint and Deliveroo Hop sit within specialist verticals where medical compliance or foodservice velocity requirements filter out generalist competition.
| Leading Market Players |
|---|
| Royal Mail |
| DPD UK |
| CitySprint |
| Amazon Logistics UK |
| Deliveroo Hop |
| Addison Lee |
| DHL Supply Chain |
| Fast UK Group |
| Evri |
| Others |
Value Network & Pricing Analysis
Electric fleet conversion timelines under the Department for Transport ZEV mandate are compressing operating cost structures while concentrating procurement power among operators with captive charging infrastructure. Battery weight penalties and payload trade-offs force higher trip frequency economics that reshape how carriers price express versus standard service tiers across metropolitan corridors.
Pricing Analysis
Bundled cold-chain compliance services versus unbundled courier-only rates split the market into distinct price bands. Three-tier pricing structure across premium, standard, and economy levels reflects GDP certification grade and geographic delivery cost differentials. Pricing pressure stems from electric van capital absorption and congestion charging boundary creep into Birmingham and Bristol. Individual consumers exhibit highest price sensitivity, while pharmaceutical enterprise procurement functions accept premium positioning for specimen integrity guarantees.
Supply Chain Analysis
Reverse-logistics flows for temperature-controlled pharmaceutical returns and failed delivery reattempts add cost layers that generalist networks avoid. Vehicle manufacturing concentrates in Germany, China, and South Korea for electric van chassis and battery cell supply. Lithium-ion cells, telematics hardware, and refrigerant units constitute critical input dependencies. Single-source vulnerability in battery supply chains elevates procurement risk. Distribution runs through hub-and-spoke networks with micro-fulfilment nodes positioned within fifteen miles of recipient concentrations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion opportunities concentrate in GDP-compliant pharmaceutical verticals where electric fleet investment converts regulatory compliance into defensible pricing power. Cold-chain integrity premiums offset battery weight penalty costs for operators achieving scale in specimen transport corridors.
For Market Incumbents: Anticipate congestion charging boundary extensions replicating London's demand compression effects across Birmingham and Manchester metropolitan zones. Defensive consolidation through micro-fulfilment node densification in Camden, Croydon, and Stratford postcodes protects sub-two-hour delivery window commitments. Certification investment in GDP compliance creates moats against generalist courier competition in medical specimen transport. For New Entrants and Emerging Players: Telematics-first dynamic routing platforms offer wedge positioning against human-planner-dependent mid-market networks. White-space targets concentrate in Edinburgh and Cardiff metropolitan zones with underpenetrated sub-two-hour infrastructure relative to English density. API-embedded slot scheduling partnerships with independent e-commerce platforms provide the most penetrable go-to-market angle against Amazon Logistics UK's captive network control. For Investors and Strategic Acquirers: Valuations sit cheapest among regional courier networks lacking electric fleet deployment scale or pharmaceutical compliance certification. Long-term viability hinges on ZEV mandate compliance trajectory and hub-and-spoke network density across the analysis window. Acquisition target archetypes include Scotland and Wales corridor specialists with established local fleet relationships. Monitor DVSA roadside inspection telematics data monetisation progress as inflection indicator for subscription revenue model validation.| Strategic Initiative | Industry Significance |
|---|---|
| Electric Fleet Deployment | ZEV mandate compliance secures access to London, Birmingham, and Manchester revenue pools under Low Emission Zone expansion. |
| Micro-Fulfilment Node Densification | Sub-fifteen-mile spoke radii in Greater London postcodes reduce last-mile cost per delivery for temperature-sensitive cargo. |
| GDP Certification Investment | Compliance rigour in pharmaceutical specimen transport creates premium service tiers that generalist networks cannot replicate. |
| API-Embedded Slot Scheduling | Direct checkout flow integration displaces third-party courier selection interfaces on independent e-commerce platforms. |
| Telematics Data Monetisation | DVSA roadside inspection compliance scoring creates subscription revenue streams from fleet insurance underwriters. |
Research Methodology
Bottom-up e-commerce platform modeling reconciled against top-down electric fleet deployment tracking forms the analytical core of this study. Primary interviews with logistics operations directors, pharmaceutical procurement managers, Traffic Commissioner licensing officers, and fleet telematics engineers combined with secondary validation from Department for Transport ZEV mandate filings, DVSA inspection statistics, and Low Emission Zone boundary extension announcements. Customs data on electric van imports and hub-and-spoke network facility registrations provided supply-side triangulation.
Input-output matrices mapped courier volume flows against micro-fulfilment node density, cold-chain compliance overhead, and congestion charging exposure across the projection horizon. Segmentation dimensions modeled include service type, delivery model, product type, and customer segment with pharmaceutical cold-chain integrity as an industry-specific overlay. CAGRs derived from regression analysis of historical fleet electrification cost curves and slot-based scheduling adoption patterns. Forecast inputs incorporated driver hour limit enforcement intensity and battery weight penalty effects on trip frequency economics.
The model holds under steady ZEV mandate enforcement timelines and congestion charging boundary stability; deviation in diesel phase-out acceleration or Low Emission Zone geographic expansion would shift fleet retirement schedules and delivery radius profitability. Forecasts reflect assumptions on electric van procurement cost trajectories and pharmaceutical vertical demand growth. Practitioners should monitor DVSA roadside inspection telematics scoring adoption and Scotland-Wales corridor infrastructure buildout for early signals of competitive positioning shifts.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
E-Commerce Solutions
E-Tailing Market
E-Commerce Solutions
E-Commerce in Luxembourg Market
E-Commerce Solutions
Global Ecommerce Platform Market
E-Commerce Solutions
IT Consumer Electronics E-Commerce Market
E-Commerce Solutions
Europe Food Platform-To-Consumer Delivery Market
E-Commerce Solutions
Austria E-Commerce Market
E-Commerce Solutions
China E-Commerce Market
E-Commerce Solutions
Indonesia E-Commerce Market
E-Commerce Solutions
Moldova E-Commerce Market
E-Commerce Solutions
E-Commerce Electronics Market
E-Commerce Solutions
China Cross-Border E-Commerce Logistics Market
E-Commerce Solutions
Conversational Commerce Market
E-Commerce Solutions
Japan Same Day Delivery Market
E-Commerce Solutions
Europe E-Commerce Watch Market
E-Commerce Solutions
United States E-Commerce Logistics Market
E-Commerce Solutions
Global Subscription E-Commerce Platform Market