
 HR Saas Market | 2026-2036
HR Saas Market Size, Share, and Industry Trends Forecast 2026-2036
HR Saas Market Insights
Platform bundling is expanding as buyers favor unified suites over point solutions, forcing vendors to integrate payroll, compliance, and analytics into single contracts. Workday Inc. leverages its native financials-to-HR architecture to anchor enterprise renewals. SAP SE competes through deep ERP interoperability that sustains cross-sell momentum in European manufacturing accounts. Oracle Corporation dominates database-layer integration, extending its infrastructure control into talent management workflows.
HR SaaS denotes cloud-hosted software delivering human capital management functions through subscription licensing, typically deployed via multi-tenant architectures with API-first connectivity to enterprise systems. The category automates workforce administration, compensation calculation, and regulatory reporting across distributed organizations. Payroll Management occupies the largest margin pool due to complexity-driven switching costs and jurisdictional tax engine requirements. Cloud-based deployment leads volume expansion as mid-market buyers abandon on-premises maintenance, while Compliance Management features command premium pricing amid fragmented labor laws across operating geographies.
FDA oversight of clinical trial workforce systems, GDPR data residency mandates from European regulators, and OSHA record-keeping digitization rules in the United States collectively elevate compliance module priority in vendor development cycles. The EU AI Act introduces algorithmic auditing obligations for automated hiring tools, reshaping product certification requirements for vendors serving European multinational employers. Stakeholders must evaluate whether their vendor's regulatory update velocity matches the accelerating pace of cross-border labor law divergence.
Market Dynamics
Platform consolidation is compressing vendor margins as mid-market buyers demand unified payroll-compliance-analytics suites over fragmented point solutions, forcing architecture investments that strain smaller competitors.
Growth Catalysts
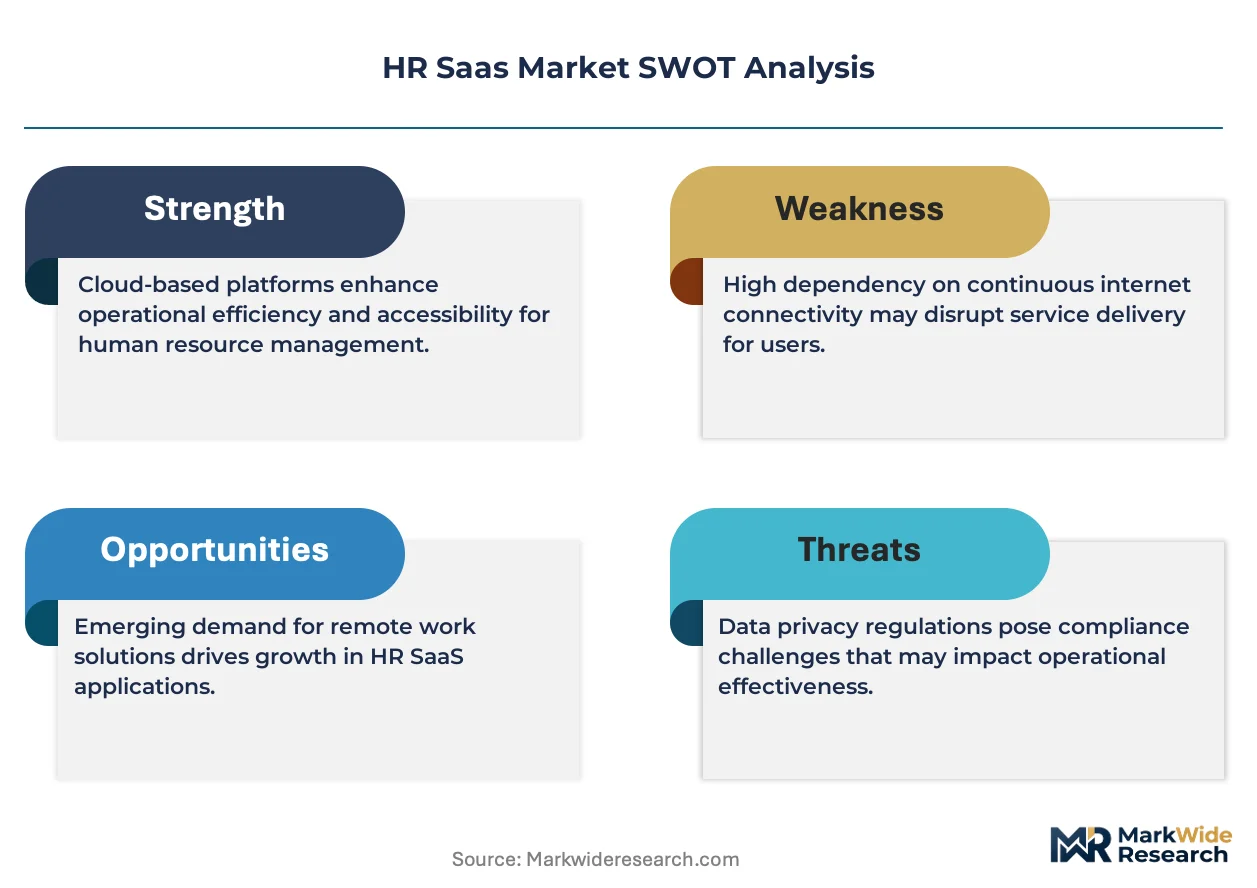
- EU AI Act enforcement:Algorithmic auditing mandates for automated hiring tools are accelerating replacement cycles among European multinational employers seeking compliant vendor certifications.
- Healthcare workforce digitization:FDA oversight of clinical trial workforce systems is driving specialized HR SaaS adoption across pharmaceutical contract research organizations managing distributed investigator networks.
- India's digital infrastructure buildout:Mid-sized companies in Bangalore and Hyderabad are abandoning on-premises payroll systems for cloud-native compliance modules as labor law digitization accelerates.
Market Restraints
- Jurisdictional tax engine complexity:Fragmented labor laws across operating geographies create switching costs that lock buyers into incumbent vendors despite functional limitations.
- Data residency infrastructure concentration:GDPR-mandated European data centers limit vendor expansion options, constraining mid-tier providers lacking capital for regional server deployments.
- Legacy ERP entrenchment:Deep SAP and Oracle database-layer integrations in manufacturing accounts create technical friction for standalone HR SaaS replacement initiatives.
Strategic Opportunities
- German Mittelstand cloud migration:Family-owned industrial mid-caps represent underpenetrated demand for unified payroll-compliance bundles as KBA labor reporting requirements digitize.
- OSHA record-keeping automation:United States workplace safety digitization rules create regulatory tailwind for vendors embedding incident-tracking modules into core HR platforms.
- API-first ecosystem convergence:Open banking standards and HR SaaS interoperability protocols are enabling embedded finance integrations that capture payroll-disbursement float revenue.
Industry Challenges
- Algorithmic bias litigation exposure:Plaintiff attorneys are targeting automated screening tools under emerging state-level AI employment laws, forcing defensive product redesign cycles.
- Cross-border payroll certification timelines:Multi-country tax engine validation requires 18-24 month compliance roadmaps that delay product launches and consume engineering resources.
- Mainframe integration complexity:Large enterprises running IBM zSystems for core financials demand costly custom middleware to connect cloud HR workflows to batch-processed general ledgers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | HR Saas Market |
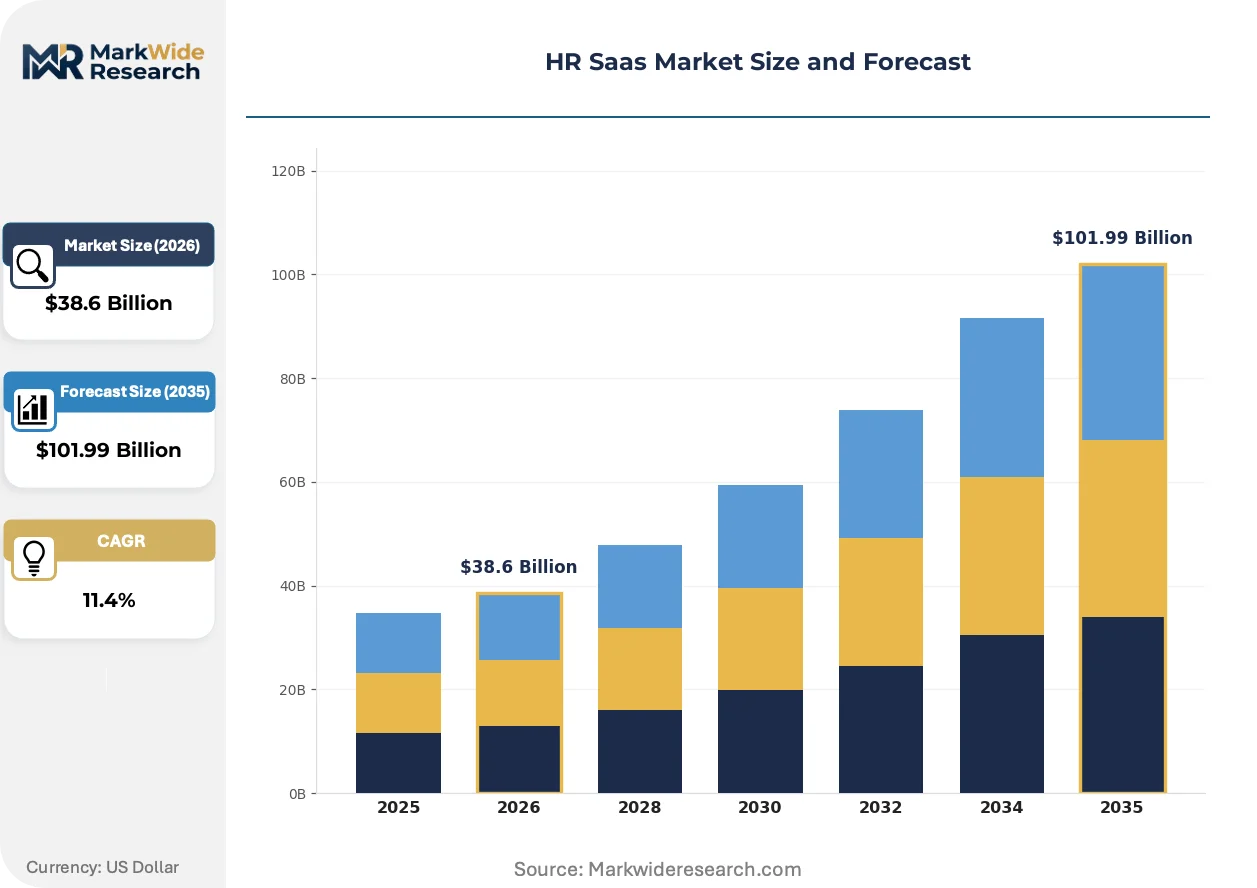
| Market Size in 2026 | $38.6 Billion |
| Market Size in 2035 | $101.99 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Applicant Tracking System, Employee Onboarding, Performance Management, Payroll Management Deployment: Cloud-based, On-premises, Hybrid, Mobile End User: Small Enterprises, Mid-sized Companies, Large Corporations, Non-profits Feature: Recruitment Analytics, Time Tracking, Compliance Management, Employee Engagement |
| Companies Covered | Workday Inc., SAP SE, Oracle Corporation, Microsoft, Automatic Data Processing, Ultimate Kronos Group, Paychex, Rippling, Gusto, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
HR Saas Market Trends and Innovations
Generative AI is embedding into workforce analytics dashboards, compressing insight generation cycles from weeks to hours while regulatory pressure on automated decision-making intensifies vendor liability frameworks.
Natural language processing engines are expanding into self-service HR portals, enabling conversational query resolution for benefits and policy questions. Mid-market professional services firms are deploying these tools fastest, reducing tier-one support ticket volumes. This capability is expanding into predictive retention modeling that flags flight-risk employees before formal resignation.
The EU AI Act's risk classification system for employment algorithms is mandating conformity assessments and CE marking for automated hiring modules. Vendors serving European multinational employers must maintain technical documentation and human oversight protocols. German automotive and French luxury goods conglomerates are demanding vendor compliance certifications before contract renewal.
Subscription pricing for point solutions is giving way to bundled suite contracts that embed implementation and change management services. Channel partners and systems integrators are capturing margin previously retained by software vendors. United States healthcare and professional services buyers are leading this shift, negotiating all-inclusive per-employee-per-month rates that transfer deployment risk to providers.
HR Saas Market Segmentation
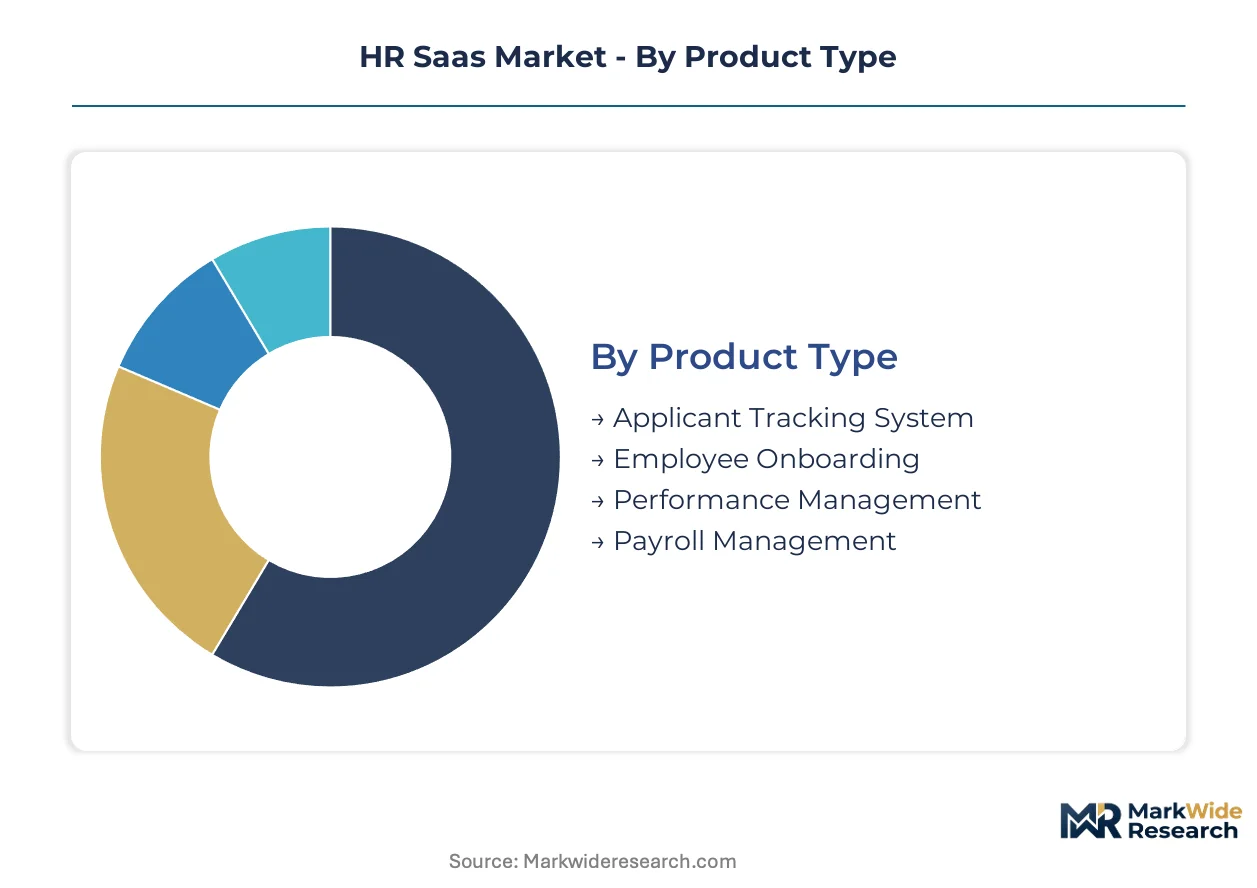
HR SaaS purchasing decisions hinge on upgrade cycles driven by regulatory mandates and workforce digitization imperatives. Buyers evaluate segments through the lens of replacement economics, where switching costs and compliance risk determine upgrade priority.
Product Type:
Upgrade cycles vary sharply by functional complexity, with tax engine-dependent modules commanding longer replacement timelines than workflow automation tools.
- Applicant Tracking System:AI-powered candidate screening and ranking engines automate sourcing pipelines. Demand concentrates in United States professional services firms replacing legacy systems ahead of state-level AI employment law enforcement.
- Payroll Management:Multi-jurisdictional tax calculation engines with real-time regulatory update feeds anchor enterprise contracts. German automotive suppliers and Indian IT services firms drive replacement cycles as KBA labor reporting and Indian labor law digitization accelerate.
- Employee Onboarding:Digital document workflows with e-signature integration compress time-to-productivity for distributed hires.
- Performance Management:Continuous feedback platforms with 360-degree review automation replace annual appraisal cycles.
Volume placements concentrate in Payroll Management; the faster expansion belongs to Applicant Tracking System.
Deployment:
Cost tier structures separate capital-intensive infrastructure commitments from operational expenditure models favored by mid-market buyers.
- Cloud-based:Multi-tenant architectures with API-first connectivity eliminate on-premises maintenance overhead. Bangalore and Hyderabad mid-sized companies accelerate migration as India's digital infrastructure buildout reduces latency constraints.
- Mobile:Native iOS and Android applications with offline synchronization extend HR workflows to field-based workforces. United States healthcare organizations managing distributed clinical trial investigator networks prioritize mobile-first deployments under FDA workforce oversight requirements.
- Hybrid:Split architectures retaining sensitive payroll data on-premises while routing analytics to cloud instances.
- On-premises:Single-tenant installations in regulated environments with strict data residency requirements.
Cloud-based deployments capture the dominant volume share; mobile delivery is climbing the fastest as frontline workforce digitization accelerates.
End User:
Customer type determines contract structure, with employee-count pricing models scaling differently across organizational maturity stages.
- Mid-sized Companies:Organizations with 100-999 employees demand unified payroll-compliance bundles without enterprise implementation complexity. German Mittelstand industrial mid-caps represent underpenetrated demand as family-owned manufacturers abandon fragmented point solutions.
- Large Corporations:Multi-entity employers with complex jurisdictional footprints require customizable workflow engines and dedicated account management. GDPR-mandated European data center deployments constrain vendor selection for these buyers.
- Small Enterprises:Sub-100 employee organizations prioritize out-of-box configurations with minimal IT overhead.
- Non-profits:Grant-funded operations with seasonal staffing fluctuations need flexible subscription terms.
Large Corporations anchor current revenue concentration; Mid-sized Companies are gaining share fastest as vendor bundling strategies penetrate this historically underserved tier.
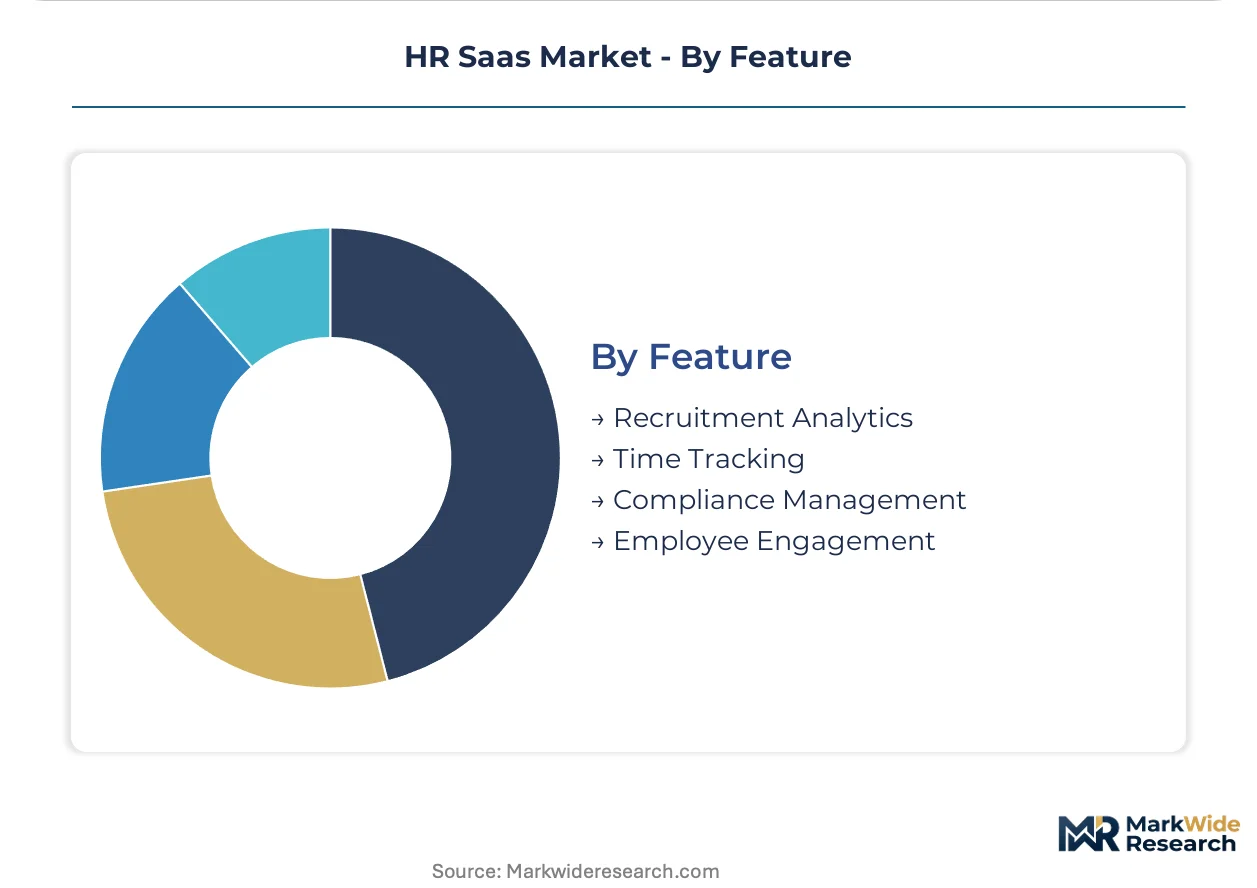
Feature:
Margin structures diverge by regulatory enforcement intensity, with compliance-linked features commanding premium pricing versus administrative automation tools.
- Compliance Management:Automated regulatory update feeds with audit trail documentation and jurisdiction-specific reporting templates. EU AI Act algorithmic auditing mandates for automated hiring tools are accelerating replacement cycles among European multinational employers seeking compliant vendor certifications.
- Recruitment Analytics:Predictive hiring models with diversity pipeline tracking and source-of-hire attribution. United States plaintiff attorneys targeting automated screening tools under emerging state-level AI employment laws are forcing defensive product redesign cycles that favor certified analytics platforms.
- Time Tracking:Biometric and geofenced attendance capture with overtime calculation automation.
- Employee Engagement:Pulse survey engines with sentiment analysis and action planning workflows.
Compliance Management commands the steepest pricing premium; Recruitment Analytics shows the steepest expansion trajectory as algorithmic accountability requirements spread.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
HR SaaS consumption concentrates in economies with complex labor regulations and digital infrastructure maturity, while production of platform engineering talent clusters in technology hubs across three continents.
United States
Enterprise buyers in healthcare and professional services drive replacement cycles for compliance-integrated suites. OSHA record-keeping digitization rules and emerging state-level AI employment laws elevate audit-ready platform requirements. The Boston-to-Washington corridor anchors demand from pharmaceutical contract research organizations managing FDA-overseen clinical trial workforces.
Germany
Family-owned Mittelstand manufacturers accelerate abandonment of fragmented point solutions for unified payroll-compliance bundles. KBA labor reporting digitization mandates and EU AI Act algorithmic auditing obligations reshape vendor certification requirements. Industrial mid-caps in Baden-Württemberg and North Rhine-Westphalia represent underpenetrated demand as cloud migration gathers pace.
India
Bangalore and Hyderabad mid-sized companies abandon on-premises payroll systems for cloud-native compliance modules as national labor law digitization accelerates. TRAI-supported digital infrastructure buildout reduces latency constraints for multi-tenant architectures. The country's IT services exporters drive specialized demand for multi-jurisdictional tax engines serving global client workforces.
United Kingdom
Financial services and professional services employers prioritize GDPR-compliant data residency configurations amid post-Brexit regulatory divergence. London-headquartered multinational employers demand vendor certifications for automated hiring tools ahead of anticipated domestic AI employment legislation. The Southeast England technology corridor sustains platform engineering talent pipelines for vendor R&D operations.
Japan
Large manufacturers with lifetime employment traditions adopt performance management and continuous feedback platforms to replace rigid appraisal cycles. METI-guided workplace digitization initiatives accelerate HR SaaS procurement among industrial conglomerates. The Tokyo-Osaka corridor concentrates demand from automotive and electronics employers integrating talent data with ERP systems.
HR Saas Market Competitive Landscape
The competitive structure tilts toward integrated suite providers over point solution specialists. Enterprise-grade vendors anchor long-term contracts through deep ERP interoperability and native financials-to-HR architectures. Three archetypes dominate: database-layer incumbents extending infrastructure control, cloud-native challengers bundling payroll-compliance-analytics, and vertical specialists serving regulated industries. Consolidation pressure and API-first ecosystem investments represent the dominant competitive moves reshaping vendor positioning.
Within the integrated enterprise tier, Workday Inc., SAP SE, and Oracle Corporation exemplify contrasting architectural strategies for anchoring renewals. Workday leverages native financials-to-HR connectivity, SAP sustains cross-sell momentum through manufacturing ERP entrenchment, and Oracle extends database-layer integration into talent workflows. Cloud-native challengers including Rippling and Gusto occupy positions favoring mid-market buyers seeking unified bundles without implementation complexity.
| Leading Market Players |
|---|
| Workday Inc. |
| SAP SE |
| Oracle Corporation |
| Microsoft |
| Automatic Data Processing |
| Ultimate Kronos Group |
| Paychex |
| Rippling |
| Gusto |
| Others |
Pricing and Supply Chain Analysis
Certification-grade divergence between EU AI Act-compliant suites and non-compliant legacy platforms manifests in both pricing stratification and supply chain architecture. Premium vendors absorb algorithmic auditing costs through dedicated European data center deployments, while mid-tier competitors face margin compression from compliance-driven engineering reallocation.
Pricing Analysis
Cost-down pressure on mid-tier payroll modules accelerates because bundled suite contracts are displacing standalone point solutions. Per-employee-per-month subscription models dominate, with price differentiation resting on GDPR certification tier and multi-jurisdictional tax engine coverage. Enterprise buyers in Germany and the United States show lowest price sensitivity due to switching cost entrenchment, while Indian mid-sized companies drive hardest bargain negotiations.
Supply Chain Analysis
Direct-to-enterprise channels handle hyperscale employer demand, supplemented by systems integrator partnerships for mid-market deployment. Engineering talent concentrates in the United States, Germany, and India, with cloud infrastructure provisioning drawing from AWS, Azure, and Google Cloud regional data centers. Single-source vulnerability in European data residency compliance creates supply chain risk for vendors lacking redundant GDPR-certified server deployments. Distribution runs through channel partners capturing implementation and change management margin.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform consolidation is compressing vendor margins as unified suite demands force architecture investments that strain smaller competitors, accelerating exit timelines for point solution specialists.
For Market Incumbents: Deepen ERP interoperability investments to anchor manufacturing account renewals against cloud-native challengers. Prioritize EU AI Act certification velocity to preempt compliance-driven replacement cycles among European multinational employers. Extend database-layer integration control into talent management workflows to sustain technical switching costs. For New Entrants and Emerging Players: OSHA record-keeping digitization in the United States opens a window for embedded safety module specialists to capture regulatory tailwind demand. Target German Mittelstand mid-caps abandoning fragmented point solutions for unified payroll-compliance bundles. Pursue API-first ecosystem partnerships enabling embedded finance integrations that capture payroll-disbursement float revenue. For Investors and Strategic Acquirers: Re-rating potential sits with vertical specialists serving FDA-overseen clinical trial workforce systems given healthcare digitization acceleration. Long-term viability favors vendors with multi-jurisdictional tax engine certification depth across 10+ operating geographies. Monitor EU AI Act enforcement timelines as inflection indicator for compliance-module pricing power expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Native financials-to-HR connectivity anchors enterprise renewals for Workday and SAP against point solution displacement. |
| Regulatory Certification Investment | EU AI Act algorithmic auditing compliance creates vendor differentiation barrier serving European multinational employers. |
| Geographic Expansion | GDPR-mandated European data center deployments constrain mid-tier providers lacking capital for regional infrastructure. |
| Strategic Partnership | Systems integrator alliances capture implementation margin as bundled suite contracts transfer deployment risk to providers. |
| Acquisition of Specialist Firm | Vertical specialists in FDA-overseen clinical trial workforce systems command premium valuations from healthcare-focused acquirers. |
Research Methodology
Document review covered SEC 10-K filings, vendor certification databases, and regulatory guidance documents, complemented by interviews with HR technology procurement officers, platform engineers at cloud-native challengers, compliance directors at European multinational employers, and channel partners in systems integration. Secondary validation drew from EU AI Act technical documentation, OSHA digitization rulemaking records, and TRAI infrastructure deployment disclosures. Bottom-up and top-down triangulation reconciled vendor-reported contract values with employer adoption pattern analysis.
Historical growth trajectories were cross-referenced against panel input from industry stakeholders to derive expansion rates across the projection horizon. Segmentation modeling incorporated deployment architecture, organization size tier, vertical industry, integration complexity depth, and regional regulatory cluster dimensions. CAGRs were synthesized from replacement cycle velocity, compliance mandate enforcement timelines, and cloud migration penetration curves specific to payroll and applicant tracking modules.
The model assumes a particular technology adoption path; alternative pathways for generative AI workforce analytics would alter the outlook if regulatory liability frameworks accelerate faster than vendor product certification cycles. Forecasts reflect documented assumptions regarding EU AI Act enforcement intensity and mid-market bundling preference evolution. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Email Marketing Software Market
Software & Services
Global Janitorial Software Market
Software & Services
Desktop Publishing Software Market
Software & Services
Global 360 Degree Feedback Software Market
Software & Services
Quote Management Software Market
Software & Services
Global Sweepstakes Software Market
Software & Services
Co-Browsing Software Market
Software & Services
Automated Testing Software Market
Software & Services
Global Electronic Lab Notebook (ELN) Market
Software & Services
POS Software Market
Software & Services
Indonesia IT Services Market
Software & Services
Lab Automation Software Market
Software & Services
Lead Management Software Market
Software & Services
Application Platform As a Service Market
Software & Services
Global Molecular Modeling Software for Chemistry Market
Software & Services
Generative Design Software Market