
 Face Oil Market | 2026-2036
Face Oil Market Size, Share, and Industry Trends Forecast 2026-2036
Face Oil Market Analysis
Market Context
ISO 16128 natural and organic cosmetics certification is collapsing the barrier between niche botanical brands and mainstream shelf presence. Englewood Lab leverages its New Jersey manufacturing base to supply private-label face oils to premium North American retailers. HSA Cosmetics anchors European production through its Swiss facilities, competing on formulation consistency for clean beauty lines. Guangzhou Rysun Biotechnology dominates contract manufacturing across Asia-Pacific, extending capacity for fermented botanical extracts.
Technical Definition and Segments
Face oil denotes a lipid-based topical preparation comprising triglycerides, fatty acids, and lipid-soluble bioactives such as squalane, jojoba esters, or rosehip seed oil, manufactured through cold-press extraction or supercritical CO2 processing to preserve oxidative stability and dermal penetration. The ingredient type dimension stratifies sharply: natural and botanical segments occupy premium price tiers where consumers pay for provenance traceability, while synthetic emollients sustain mass-market volume through cost-engineered stability. Distribution channel structure reveals margin concentration in specialty stores and online retail, where direct-to-consumer education justifies unit economics that supermarkets and pharmacies cannot replicate.
Regulatory Frame and Outlook
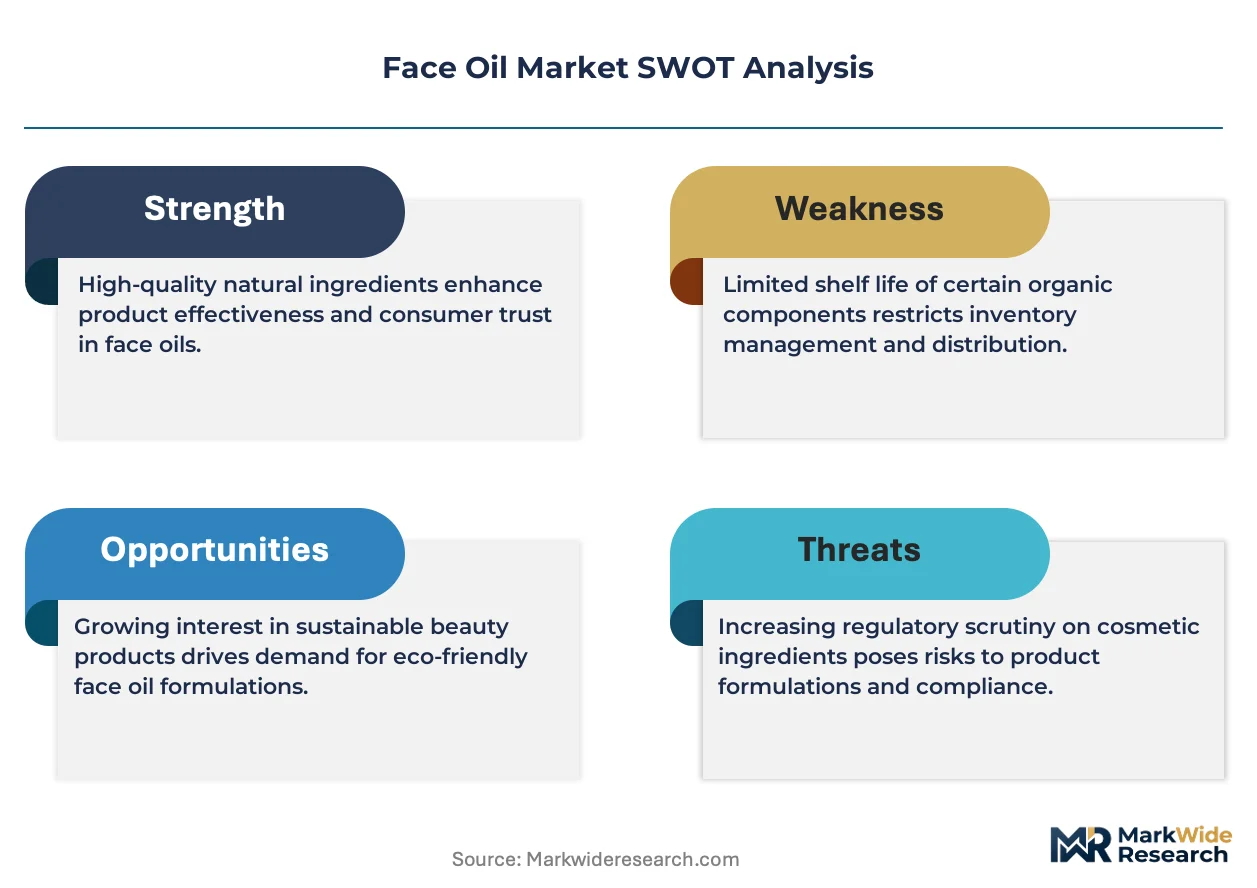
U.S. FDA cosmetic labeling requirements, EU REACH substance restrictions, and ECHA allergen disclosure mandates collectively elevate compliance costs for face oil entrants while advantaging established formulators with regulatory infrastructure. South Korea's MFDS governs functional cosmetic claims, creating a separate approval pathway for anti-aging and brightening oils that conditions market access. Stakeholders must monitor shifting definitions of naturalness under ISO 16128 revisions and decide whether to pursue dual certification across FDA and EFSA jurisdictions or specialize in single-market dominance.
Market Dynamics
Clean beauty certification under ISO 16128 is compressing formulation cycles and forcing contract manufacturers to revalidate entire botanical supply chains, redistributing competitive advantage toward laboratories with pre-certified ingredient libraries.
Growth Catalysts
- EU REACH substance restrictions:These mandates accelerate clean-label migration by banning unvetted synthetic emollients, pulling R&D investment toward cold-press extraction infrastructure.
- Gen Z skincare routines:This demographic segment normalizes facial oil layering, expanding addressable volume beyond anti-aging demographics into preventive daily use.
- Fermented botanical extracts:This processing technology unlocks bioactive potency without synthetic preservatives, commanding shelf-space premiums in specialty retail.
Market Restraints
- Rosehip and marula oil price volatility:Climate stress on Southern African and South American harvest regions compresses gross margins for natural-segment formulators.
- Swiss and South Korean supply concentration:Premium clean-beauty manufacturing clusters in these geographies create bottleneck risk for brands lacking dual-source strategies.
- Supercritical CO2 equipment capex:The capital intensity of oxidative-stability processing limits mid-tier entrants to toll-manufacturing dependencies.
Strategic Opportunities
- India's nascent premium skincare channel:Underpenetration in organized retail creates first-mover positioning for ISO-certified entrants before domestic clean-beauty standards crystallize.
- Biometric skin-analysis integration:Convergence of AI diagnostics with personalized oil blending enables subscription models that bypass traditional retail margin extraction.
- U.S. IRA clean-manufacturing incentives:Tax credits for domestic biotechnology production subsidize fermentation-capacity expansion for North American contract manufacturers.
Industry Challenges
- Cosmetic chemist specialization gap:Shortage of formulators trained in both lipid chemistry and botanical toxicology extends product-development timelines.
- Dual FDA-EFSA certification timelines:Parallel regulatory pathways for naturalness claims consume 18-24 months, delaying cross-Atlantic launches.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Face Oil Market |
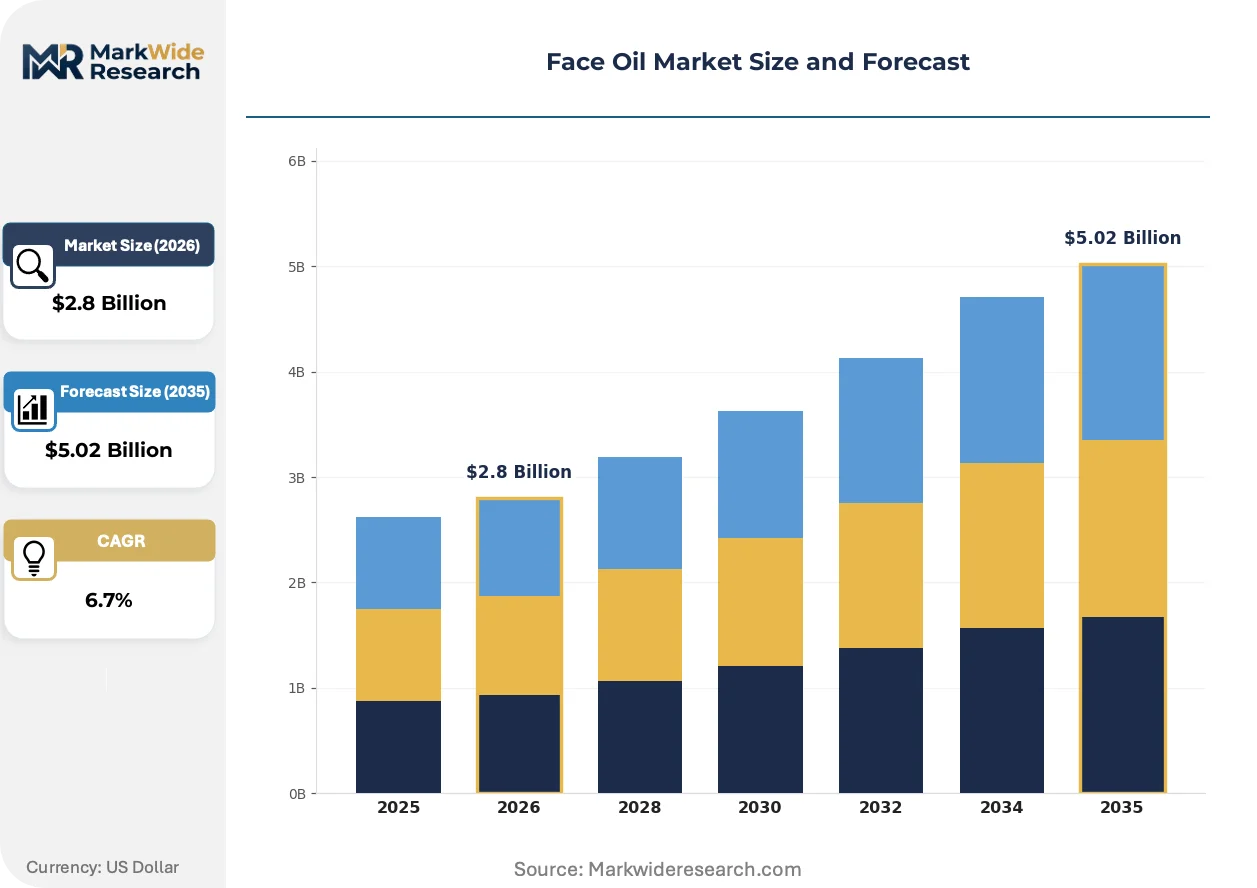
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.02 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Serum, Hydrating Oil, Anti-Aging Oil, Brightening Oil Ingredient Type: Natural, Organic, Synthetic, Botanical Application: Daily Moisturization, Night Care, Spot Treatment, Makeup Base Distribution Channel: Online Retail, Specialty Stores, Pharmacies, Supermarkets |
| Companies Covered | Englewood Lab, HSA Cosmetics, RainShadow Labs, NATURA WISH LIMITED, Columbia Cosmetics Manufacturing, Guangzhou Rysun Biotechnology, Fareva, UpCircle Beauty, Cosmetic Solutions, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Face Oil Market Emerging Trajectories
Biotechnology-derived squalane and precision-fermented actives are collapsing the cost-performance gap between petroleum-based emollients and botanical alternatives, forcing incumbents to reposition around traceability narratives rather than functional superiority.
Squalane produced via engineered yeast fermentation is displacing shark-liver and olive-derived sourcing across mass-market and prestige tiers alike. Mid-tier brands in the United States and France have adopted this material fastest, compressing price premiums for traditional botanicals by half within three formulation cycles. The displacement is enabling private-label manufacturers to offer clean-label parity at synthetic price points.
EU ECHA allergen disclosure mandates now require component-level labeling for 26 fragrance compounds in leave-on facial products. This regulatory tightening forces reformulation of legacy essential-oil blends and advantages synthetic-biology alternatives with zero-declaration profiles. South Korean exporters to Europe are accelerating MFDS pre-certification to maintain access.
Direct-to-consumer sampling via dermatologist-endorsed subscription boxes is fragmenting traditional specialty-retail gatekeeping. Millennial buyers in France and the United States now discover facial oils through algorithmic curation rather than counter consultation, compressing brand-building cycles and elevating influencer-chemist hybrids. This channel shift rewards agile contract manufacturers with low minimum-order quantities.
Face Oil Market Segmentation
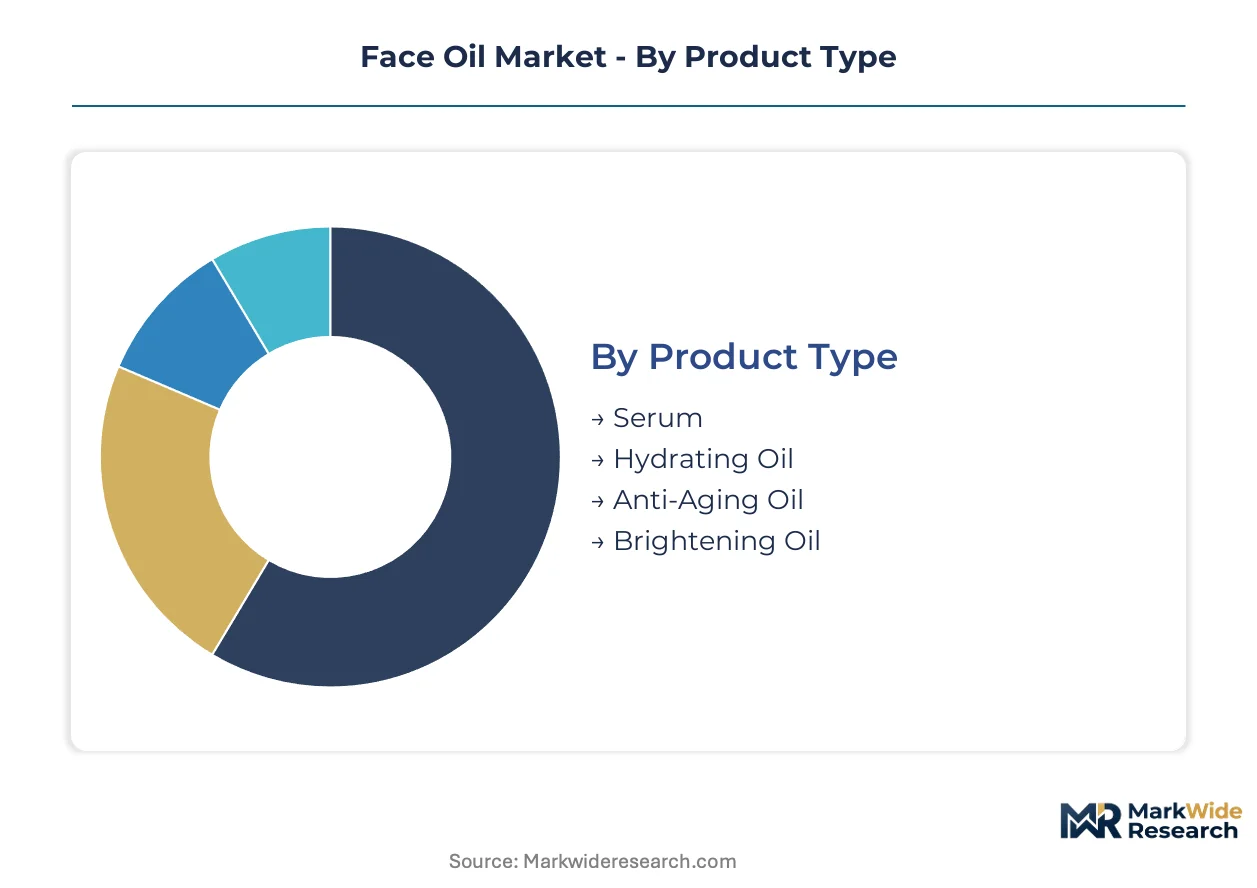
Face oil segmentation reflects divergent compliance burdens across regulatory jurisdictions. ISO 16128 certification tiers and FDA labeling requirements reshape how brands position within each category, compressing margins for uncertified entrants while rewarding pre-validated supply chains.
Product Type:
EU REACH substance restrictions and South Korea MFDS functional-claim pathways create divergent product-development timelines across these segments.
- Serum:Lightweight lipid-soluble formulations with squalane or jojoba esters as carrier oils. Demand concentrates in France and the United States where millennial consumers layer serums under moisturizers, though ECHA allergen disclosure mandates force reformulation of fragranced variants.
- Anti-Aging Oil:Retinol-infused or bakuchiol-based preparations targeting dermal collagen support. South Korea's MFDS pre-certification requirement for functional anti-aging claims conditions market access, advantaging domestic formulators with established regulatory infrastructure.
- Hydrating Oil:Occlusive barrier-repair formulations with ceramide analogs. Mass-market volume in U.S. supermarkets.
- Brightening Oil:Vitamin C or licorice-root derivatives addressing hyperpigmentation. Niche positioning in specialty retail.
Established volume favors Hydrating Oil; emerging adoption favors Serum.
Ingredient Type:
Cost tiers stratify sharply between petroleum-derived synthetics and fermentation-capable biotech alternatives.
- Natural:Cold-pressed rosehip, marula, or argan oils with traceable provenance. Climate stress on Southern African harvest regions compresses gross margins, pushing brands toward dual-source strategies or biotech substitutes.
- Synthetic:Petroleum-derived squalane and mineral oil emollients engineered for oxidative stability. Mass-market dominance in U.S. pharmacy channels where price elasticity limits botanical premiums.
- Organic:USDA or ECOCERT-certified cultivation with full supply-chain documentation. Premium positioning in French specialty retail.
- Botanical:Plant-derived actives without full organic certification. Intermediate pricing in online direct-to-consumer channels.
Volume concentration sits with Synthetic; steepest expansion trajectory belongs to Natural.
Application:
Customer usage patterns determine channel economics and subscription-model viability.
- Daily Moisturization:Lightweight absorption-profile oils for morning routines. Gen Z normalization of facial oil layering expands addressable volume beyond traditional anti-aging demographics into preventive daily use across the United States.
- Night Care:Richer occlusive formulations for repair-phase application. Premium pricing in French and South Korean specialty stores where counter consultation justifies unit economics.
- Spot Treatment:Targeted application for dry patches or barrier disruption. Niche pharmacy positioning.
- Makeup Base:Pre-foundation priming oils with fast-absorbing esters. Emerging online discovery through influencer curation.
Margin concentration favors Night Care; algorithmic discovery favors Makeup Base.
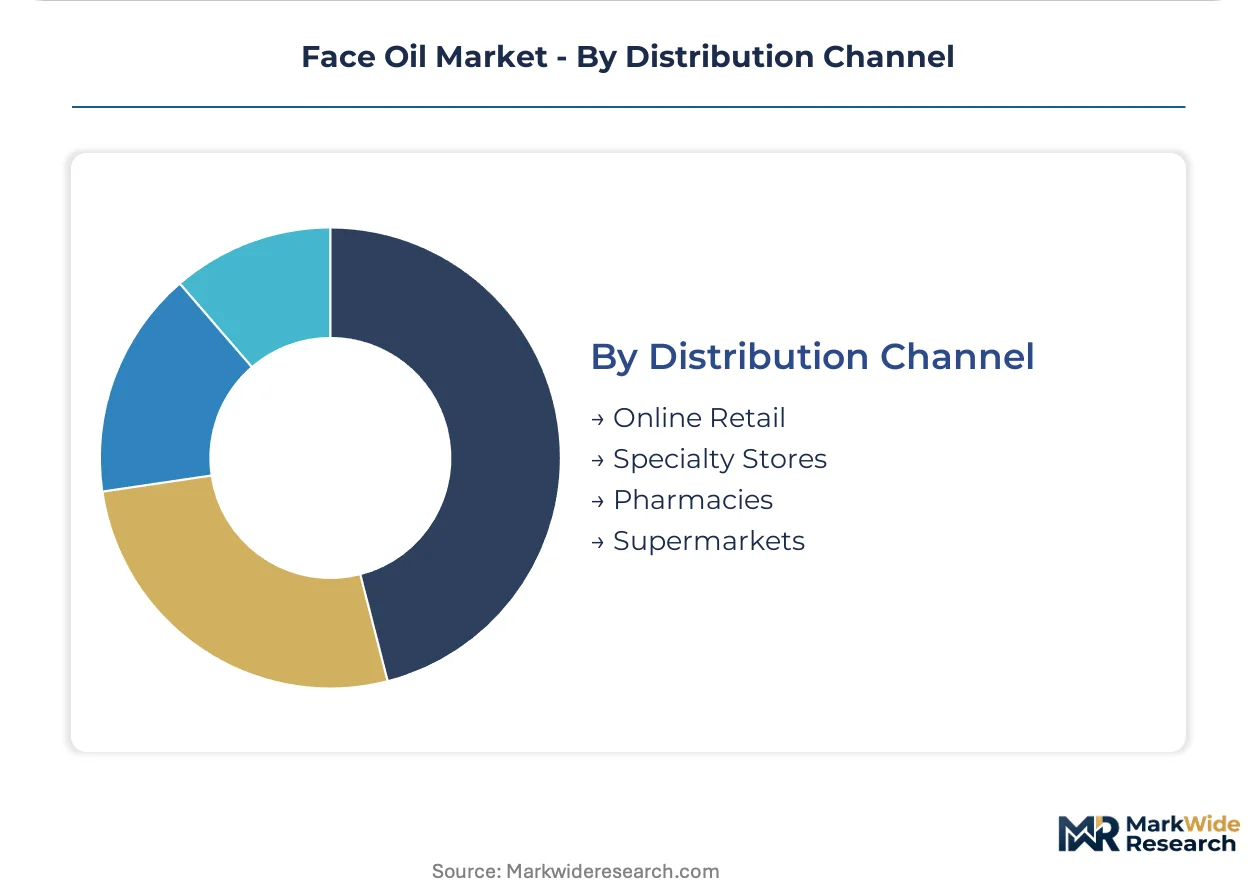
Distribution Channel:
Supply concentration in Swiss and South Korean manufacturing clusters shapes regional channel access.
- Online Retail:Direct-to-consumer platforms with AI-driven personalization and subscription mechanics. Algorithmic curation displaces traditional counter consultation in France and the United States, rewarding agile contract manufacturers with low minimum-order quantities.
- Specialty Stores:Sephora, Douglas, or department-store beauty halls with trained consultation staff. Margin extraction justifies premium positioning for ISO-certified botanical lines.
- Pharmacies:Mass-market synthetic emollients with clinical positioning. Volume concentration in U.S. and French drugstore chains.
- Supermarkets:Price-engineered basic oils with minimal differentiation. Commodity tier.
Margin capture favors Specialty Stores; channel shift momentum favors Online Retail.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Clean beauty certification requirements under EU REACH and U.S. FDA guidelines are reshaping formulation standards across major consumption centers. Demand concentrates in the United States, France, and South Korea as these markets drive premium facial oil adoption through regulatory clarity and retail infrastructure investment.
United States
Millennial and Gen Z consumers normalize facial oil layering in preventive daily routines, expanding addressable volume beyond anti-aging demographics. U.S. FDA cosmetic labeling requirements elevate compliance costs while advantaging established formulators with regulatory infrastructure. Englewood Lab leverages its New Jersey manufacturing base to supply private-label face oils to premium North American retailers.
France
Specialty retail consultation justifies premium unit economics for ISO-certified botanical lines in Paris and Lyon beauty halls. ANSM enforces EU ECHA allergen disclosure mandates requiring component-level labeling for fragrance compounds in leave-on products. HSA Cosmetics anchors European production through its Swiss facilities, competing on formulation consistency for clean beauty lines.
South Korea
MFDS functional cosmetic claims create a separate approval pathway for anti-aging and brightening oils that conditions market access for domestic and foreign brands. Seoul-based formulators with established regulatory infrastructure capture disproportionate share of export-oriented production. Fermented botanical extract technology commands shelf-space premiums in domestic specialty retail.
Switzerland
Swissmedic oversight of cosmetic safety combines with ECOCERT certification infrastructure to position Basel and Geneva as premium clean-beauty manufacturing clusters. Precision-fermented actives production concentrates in biotech corridors near Zurich. Supply concentration in Swiss facilities creates bottleneck risk for brands lacking dual-source strategies.
China
NMPA registration requirements for imported cosmetics condition market access for foreign face oil brands seeking organized retail placement. Yangtze River Delta manufacturing hubs develop fermentation capacity for biotech-derived squalane. Guangzhou Rysun Biotechnology dominates contract manufacturing across Asia-Pacific, extending capacity for fermented botanical extracts.
Face Oil Market Vendor Landscape
Listed leaders compete with private specialists across certification and capacity dimensions. The vendor base stratifies between multinational contract manufacturers with ISO 16128 pre-certified libraries and agile mid-tier laboratories serving direct-to-consumer brands. Three archetypes dominate: fermentation-capable biotech specialists, cold-press extraction traditionalists, and private-label mass-market suppliers. Competitive moves concentrate on dual FDA-EFSA certification acquisition and supercritical CO2 capacity expansion.
Among North American and European contract manufacturers, Englewood Lab and HSA Cosmetics exemplify the certification-heavy tier, while Guangzhou Rysun Biotechnology occupies the Asia-Pacific scale position. RainShadow Labs and Columbia Cosmetics Manufacturing represent mid-tier agility archetypes. UpCircle Beauty and Cosmetic Solutions sit within the sustainability-narrative specialist segment. NATURA WISH LIMITED and Fareva occupy positions bridging private-label volume and premium positioning.
| Leading Market Players |
|---|
| Englewood Lab |
| HSA Cosmetics |
| RainShadow Labs |
| NATURA WISH LIMITED |
| Columbia Cosmetics Manufacturing |
| Guangzhou Rysun Biotechnology |
| Fareva |
| UpCircle Beauty |
| Cosmetic Solutions |
| Others |
Supply Flow & Price Mechanics
Biotechnology-derived squalane displacing shark-liver and olive-sourced alternatives simultaneously redraws raw material sourcing geography from Southern African harvest regions to North American fermentation facilities and collapses historical price premiums by half across three formulation cycles.
Pricing Analysis
Certification level under ISO 16128 creates the primary spread between mass-market synthetic emollients and premium botanical lines, with USDA and ECOCERT tiers commanding substantial premiums in French specialty retail. Three-tier pricing structure across premium certified, standard natural, and economy synthetic levels stratifies the market, though fermentation-derived alternatives are compressing inter-tier spreads. Pricing pressure stems from climate-induced volatility in rosehip and marula harvests, squeezing gross margins for natural-segment formulators. Mass-market pharmacy buyers exhibit highest price sensitivity, while specialty store consumers absorb certification premiums through consultation-justified value perception.
Supply Chain Analysis
Inventory lead times for cold-pressed botanicals stretch substantially longer than fermentation-derived alternatives due to harvest seasonality and climate dependency. Supply concentrates in Swiss precision-fermentation corridors, South Korean MFDS-certified facilities, and New Jersey contract manufacturing hubs. Raw material flows draw from engineered yeast feedstocks, Southern African marula cooperatives, and Argentine rosehip estates. Single-source vulnerability pervades premium clean-beauty manufacturing clusters lacking dual-source strategies. Distribution runs through direct-to-consumer platforms, specialty retail beauty halls, and mass-market pharmacy chains.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The face oil market sits within a cyclical recovery phase as post-pandemic premium skincare normalization and Gen Z preventive routine adoption restore volume growth trajectories interrupted by earlier discretionary spending compression.
For Market Incumbents: Fortify regulatory infrastructure advantages by pursuing parallel FDA-EFSA certification pathways ahead of ISO 16128 revision implementation, while securing dual-source supply agreements for climate-stressed botanical inputs to defend margin position against harvest volatility. Capacity expansion into India before domestic clean-beauty standards crystallize captures first-mover positioning in underpenetrated organized retail. For New Entrants and Emerging Players: Differentiate on biometric skin-analysis integration enabling personalized oil blending subscriptions that bypass traditional retail margin extraction. India's nascent premium skincare channel presents the most penetrable geography, with algorithmic curation through dermatologist-endorsed discovery platforms offering viable go-to-market angles against established specialty store gatekeepers. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed fermentation-capable contract manufacturers possessing pre-certified ingredient libraries and supercritical CO2 processing infrastructure. Long-term viability across the analysis window hinges on regulatory compliance scalability rather than formulation novelty alone. Watch for MFDS pre-certification acceleration among South Korean exporters to Europe as signal of cross-jurisdictional expansion readiness.| Strategic Initiative | Industry Significance |
|---|---|
| Dual FDA-EFSA Certification Acquisition | Parallel regulatory pathways compress cross-Atlantic launch timelines from 24 months toward 18. |
| Fermentation Capacity Expansion | U.S. IRA clean-manufacturing tax credits subsidize biotechnology-derived squalane production scale-up. |
| Biometric Personalization Platform Launch | AI-driven skin analysis enables subscription models that extract margins from algorithmic curation. |
| India Market Entry | Underpenetration in organized retail creates positioning window before domestic clean-beauty standards crystallize. |
| Dual-Source Botanical Supply Agreement | Climate stress on Southern African harvest regions demands supply redundancy for margin protection. |
Methodological Framework
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with cosmetic chemists, contract manufacturing executives, specialty retail category buyers, regulatory affairs specialists, and clean-beauty brand founders. Secondary validation drew from FDA cosmetic labeling guidance, EU ECHA allergen disclosure mandates, MFDS functional cosmetic claim pathways, SEC filings of listed personal care companies, and customs trade data for botanical oil imports. Bottom-up volume modeling across ingredient type and application segments was triangulated against top-down market sizing from channel-level revenue analysis.
Across the projection horizon, the analytical framework modeled segmentation dimensions spanning product type, ingredient certification tier, application routine, and distribution channel structure. CAGRs were derived from regression analysis of historical volume trajectories adjusted for regulatory inflection points and generational consumption pattern shifts. Forecast inputs incorporated climate stress indices for Southern African and South American harvest regions alongside biotechnology capacity expansion timelines.
Material uncertainties — regulatory definition shifts under ISO 16128 revisions, climate volatility in botanical sourcing regions, and MFDS approval timeline extensions — sit outside the modeled envelope and could substantially revise trajectory assumptions. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Beauty & Personal Care
LAMEA Hair Removal Wax Market
Beauty & Personal Care
Mens Intimate Care Products Market
Beauty & Personal Care
Magnetic Eyelashes Market
Beauty & Personal Care
Premium Cosmetics Market
Beauty & Personal Care
Coffee Beauty Products Market
Beauty & Personal Care
Asia-Pacific Hair Removal Wax Market
Beauty & Personal Care
Bangladesh Shampoo Market
Beauty & Personal Care
North America Lip Care Products Market
Beauty & Personal Care
Europe Cosmeceuticals Market
Beauty & Personal Care
Global Hot Air Brushes Market
Beauty & Personal Care
Nail Lamps Market
Beauty & Personal Care
Hair Straightener Market
Beauty & Personal Care
Facial Massager Market
Beauty & Personal Care
Eyelash Serum Market
Beauty & Personal Care
At Home Hair Dye Market
Beauty & Personal Care
North America Hair Removal Wax Market