
 Deodorant & Anti-Perspirant Market | 2026-2036
Deodorant & Anti-Perspirant Market Size, Share, and Industry Trends Forecast 2026-2036
Deodorant & Anti-Perspirant Market Insights
The capability gap between capital-heavy integrated manufacturers and asset-light brand marketers is bifurcating competitive dynamics in personal care. Procter & Gamble leverages captive supply chains and in-house fragrance compounding to sustain margin control across mass and premium tiers. Unilever anchors its position through geographic density in emerging markets, while Beiersdorf specializes in dermatological positioning for sensitive-skin segments.
Deodorant and anti-perspirant formulations combine active ingredients such as aluminum chlorohydrate or aluminum zirconium tetrachlorohydrex gly with emollient bases to inhibit eccrine sweat secretion and neutralize odor-causing bacterial metabolism; these products serve daily hygiene, social confidence, and occupational compliance needs across consumer and institutional channels. Spray formats lead volume in Europe and Latin America due to dry-application convenience and faster drying times, while stick and gel segments capture premium shelf space in North American retail. Natural and clinical formulation tiers represent divergent margin pools, with the former commanding price premiums through clean-label positioning and the latter securing pharmacy and medical-channel access.
Regulators including the FDA in the United States, the European Commission through REACH and the EU Cosmetics Regulation, and Health Canada govern active-ingredient concentrations, labeling claims, and environmental release thresholds for aerosol propellants. These frameworks elevate compliance costs for new entrants while creating barrier-protected positions for incumbents with dedicated regulatory affairs infrastructure. Stakeholders must monitor evolving restrictions on aluminum-based actives and propellant chemistries, as substitution mandates would reshape formulation R&D priorities and manufacturing asset configurations.
Market Dynamics
Aluminum-based active ingredient scrutiny under REACH and state-level disclosure mandates in California and Vermont is fragmenting formulation R&D roadmaps, forcing parallel development tracks for conventional clinical actives and aluminum-free alternatives.
Growth Catalysts
- Men's Grooming Normalization:Urban male consumers in Indonesia and Vietnam now view daily deodorant use as occupational and social necessity, expanding addressable household penetration rates.
- REACH Chemical Transparency Mandates:ECHA's tightening disclosure requirements for fragrance allergens and aluminum salts is accelerating clean-label innovation cycles among EU-based formulators.
- Spray Format Infrastructure:Aerosol filling capacity expansion in Brazil and Mexico supports dry-application preference diffusion across Latin American retail and pharmacy channels.
Market Restraints
- Propellant Chemistry Constraints:F-Gas Regulation phase-down schedules in Europe compress hydrofluorocarbon availability, elevating reformulation costs for legacy aerosol portfolios.
- Active Ingredient Concentration Limits:Health Canada and FDA aluminum zirconium tetrachlorohydrex gly caps restrict clinical-strength claim substantiation, constraining premium tier differentiation.
- Fragrance Compound Supply Concentration:Four Givaudan-Firmenich-Symrise-IFF suppliers control 70% of captive fragrance molecules, creating input cost volatility and exclusivity bottlenecks.
Strategic Opportunities
- Microbiome-Friendly Formulation White Space:Prebiotic and postbiotic actives that preserve axillary skin flora without aluminum occlusion represent unclaimed pharmacy and dermocosmetic positioning.
- Refill and Concentrate Systems:Solid stick refills and waterless concentrate formats align with EU Green Deal circular economy targets while reducing logistics intensity.
- Occupational Channel Penetration:Institutional supply contracts for healthcare, hospitality, and manufacturing facilities remain underdeveloped relative to retail saturation.
Industry Challenges
- Regulatory Affairs Talent Scarcity:Shortage of professionals fluent in REACH, FDA 21 CFR, and Health Canada ICH Q3D guidelines delays multi-territory product registration timelines.
- Legacy Aerosol Asset Stranding:F-Gas transition requirements and aluminum-substitution R&D demands simultaneous capital deployment without guaranteed format winner.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Deodorant & Anti-Perspirant Market |
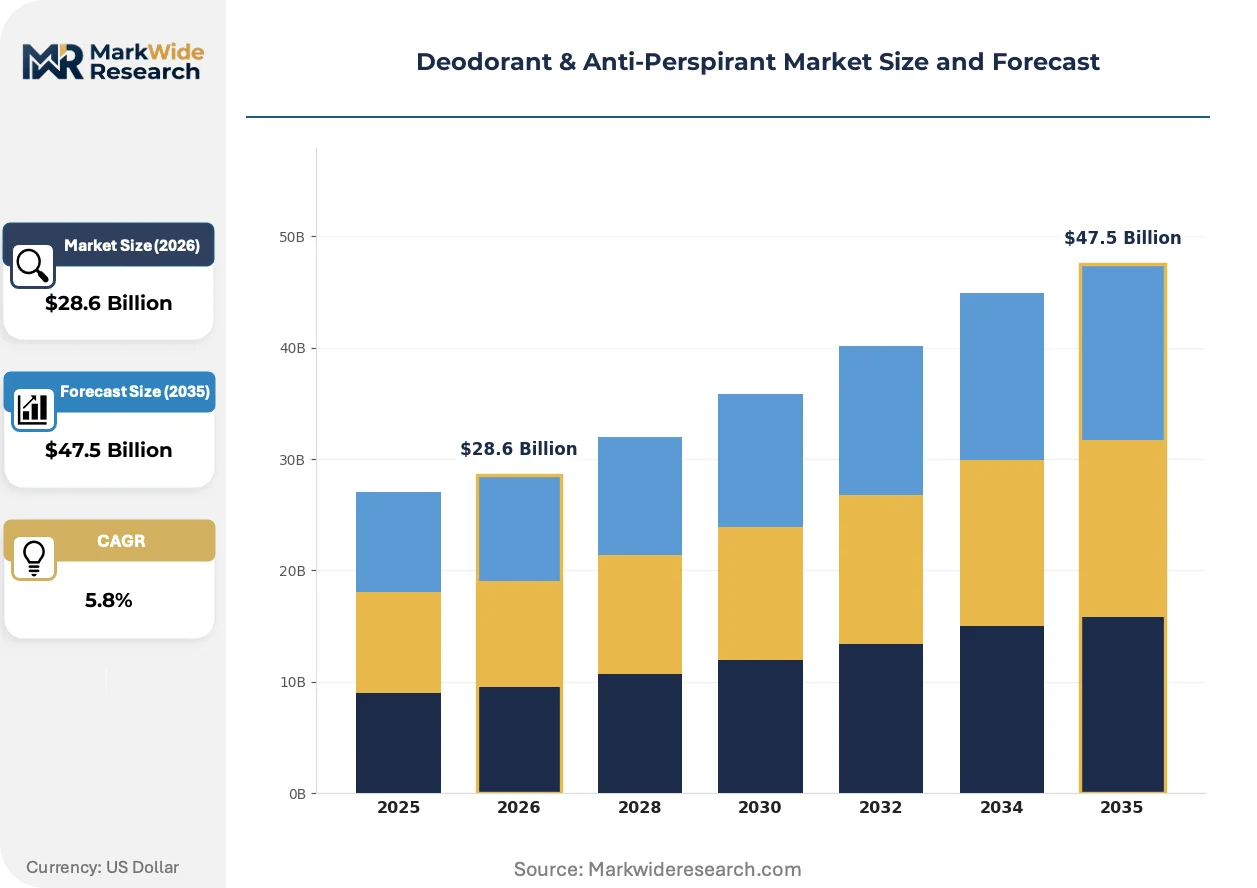
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $47.5 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Roll-on, Spray, Stick, Gel Formulation: Natural, Antiperspirant, Deodorant, Clinical End User: Men's Care, Women's Care, Unisex Products, Sensitive Skin Distribution Channel: Retail Stores, Online Sales, Supermarkets, Specialty Shops |
| Companies Covered | Procter & Gamble, Unilever, Colgate-Palmolive, Beiersdorf, Henkel, Reckitt Benckiser, L'Oréal, Church & Dwight, Coty, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Deodorant & Anti-Perspirant Market Trends and Innovations
Formulation science and channel architecture are diverging along clean-label and clinical-efficacy axes, with technology investments clustering around biotechnology-derived actives and sustainable packaging systems rather than incremental aluminum salt optimization.
Enzymatic odor-neutralization biotechnology is supplanting traditional fragrance masking and aluminum-based bacterial inhibition in premium natural-positioned lines. Indie brands and pharmacy retailers in Germany and France are accelerating adoption curves through dermatologist endorsement networks. This shift is compressing conventional fragrance-heavy SKU margins while expanding R&D partnerships with industrial biotechnology suppliers.
REACH Annex XVII restrictions on per- and polyfluoroalkyl substances (PFAS) and expanding fragrance allergen labeling requirements are forcing reformulation of antiperspirant emollient bases and propellant systems. European manufacturers face 18-24 month validation cycles for alternative chemistries. Mass-market spray formats bear disproportionate compliance burden as they rely on PFAS-containing film-formers for dry-touch aesthetics.
Subscription and direct-to-consumer replenishment models are capturing trial-to-repeat conversion from mass retail impulse purchase environments. Stick and roll-on formats dominate these channels due to shipping weight and temperature stability advantages over aerosols. This behavioral pivot is most pronounced in US and UK metropolitan markets where convenience-oriented millennials and Gen Z cohorts consolidate personal care purchasing into curated digital bundles.
Deodorant & Anti-Perspirant Market Segmentation
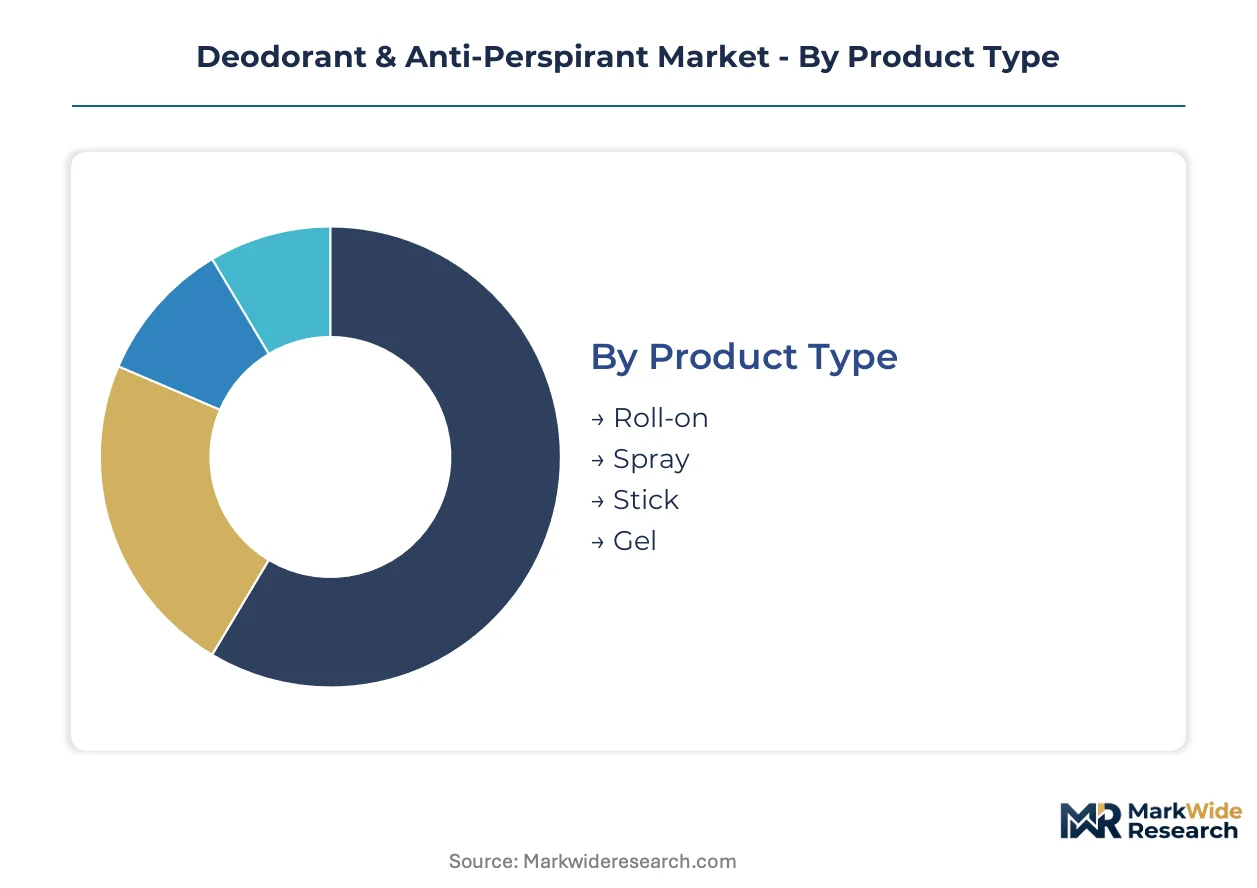
Deodorant and anti-perspirant segmentation reveals divergent margin architectures across format chemistry and channel access. Product type and formulation tiers create distinct competitive battlegrounds where convenience preferences clash with regulatory compliance costs.
Product Type:
Spray formats dominate export-led volume into Latin American markets, while stick and roll-on variants anchor domestic consumption in North American and European retail.
- Roll-on:Liquid emulsion delivered through ball applicator provides precise dosage control and reduced propellant dependency. Demand concentrates in German and French pharmacy channels where ECHA disclosure requirements favor lower-aerosol portfolios; aluminum-free formulations command shelf space premiums here.
- Spray:Aerosol-dispensed dry-touch application relies on hydrofluorocarbon or hydrocarbon propellant systems. Brazil and Mexico drive volume through expanded filling infrastructure; F-Gas Regulation phase-down timelines compress European manufacturing economics for this format.
- Stick:Solid wax-and-silicone base enables waterless concentrate formulations aligned with EU Green Deal circular economy targets. Direct-to-consumer subscription channels favor this format for shipping weight efficiency.
- Gel:Clear-drying hydro-alcoholic suspensions target visible-residue avoidance in professional and social contexts. Southeast Asian humidity drives adoption in Indonesian and Vietnamese urban centers.
Spray holds the largest share; momentum sits with stick formats gaining share fastest through refill system innovation.
Formulation:
Cost tier stratification separates commodity aluminum-based clinical efficacy from premium-positioned biotech-derived alternatives.
- Natural:Prebiotic and enzymatic actives preserve axillary microbiome without aluminum salt occlusion. German dermocosmetic retailers and French pharmacy networks accelerate adoption through dermatologist endorsement channels.
- Antiperspirant:Aluminum chlorohydrate or aluminum zirconium tetrachlorohydrex gly formulations inhibit eccrine sweat secretion through temporary duct occlusion. Health Canada and FDA concentration caps constrain clinical-strength claim differentiation in North American markets.
- Deodorant:Fragrance-forward bacterial metabolism masking without sweat-blocking actives serves daily hygiene maintenance. Mass retail impulse purchasing in US and UK supermarkets sustains volume.
- Clinical:Prescription-strength aluminum zirconium tetrachlorohydrex gly concentrations target hyperhidrosis and occupational compliance needs. Pharmacy channel access requires medical claim substantiation.
Antiperspirant maintains volume leadership; natural formulations are climbing the fastest through clean-label positioning.
End User:
Application context diverges between occupational necessity drivers and dermatological sensitivity requirements.
- Men's Care:Urban male consumers in Indonesia and Vietnam normalize daily deodorant use as workplace and social hygiene standard. Retail expansion in Southeast Asian metropolitan areas accelerates household penetration.
- Women's Care:Fragrance-forward and residue-invisible formulations target professional and formal occasion contexts. Subscription bundle integration captures trial-to-repeat conversion in US and UK digital channels.
- Unisex Products:Neutral fragrance profiles and minimalist packaging serve shared household purchasing and travel convenience needs.
- Sensitive Skin:Aluminum-free and fragrance-minimized formulations address dermatological intolerance and post-shave irritation. Beiersdorf and pharmacy specialists dominate this positioning in German-speaking markets.
Women's Care retains the largest segment; Men's Care shows steepest expansion trajectory through emerging market urbanization.
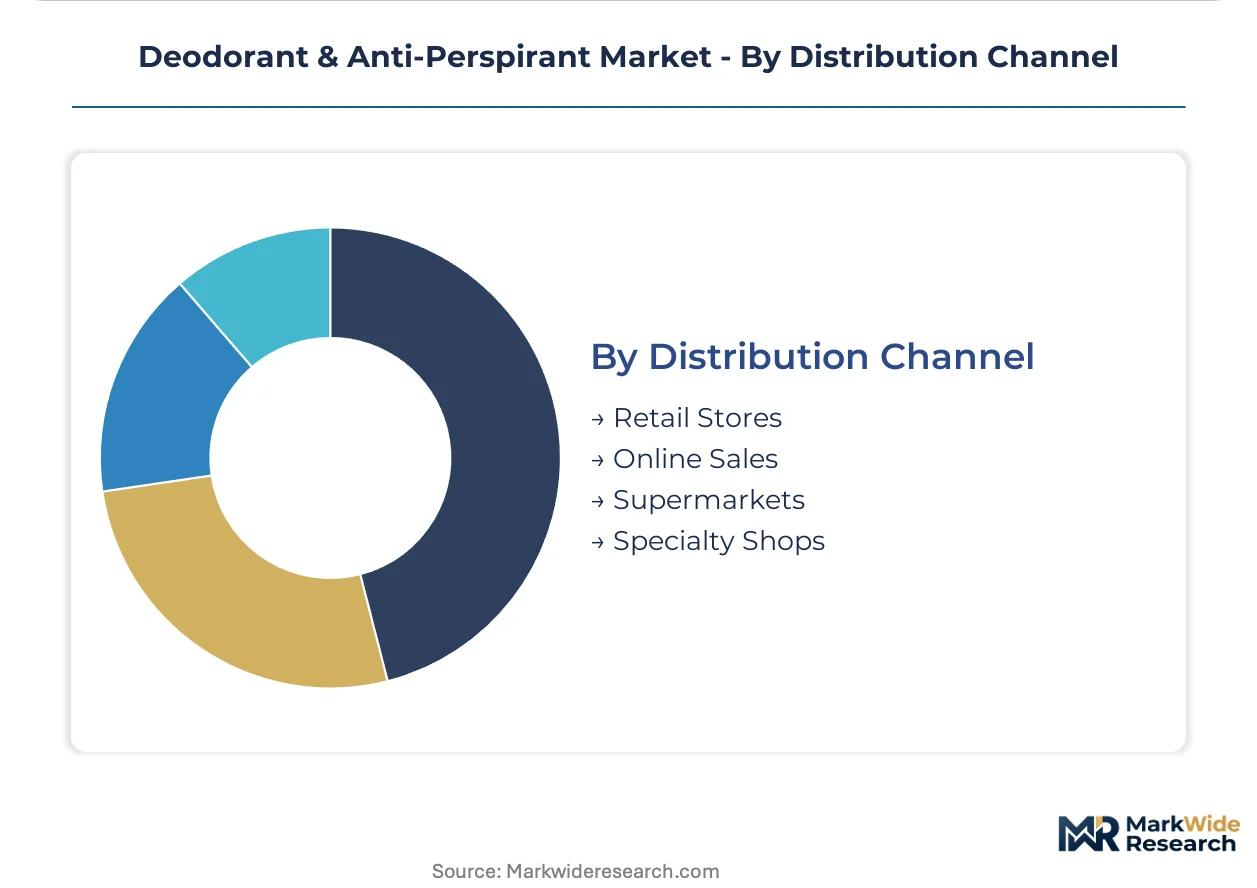
Distribution Channel:
Customer type stratification separates convenience-driven mass retail from curated digital bundling and professional consultation environments.
- Retail Stores:Impulse placement at checkout and seasonal promotional calendars drive trial conversion for fragrance-forward variants. Latin American pharmacy and mass retail hybrids sustain aerosol format dominance.
- Online Sales:Direct-to-consumer replenishment models capture subscription loyalty through curated personal care bundles. Stick and roll-on formats benefit from temperature stability and shipping weight advantages over aerosols.
- Supermarkets:High-frequency foot traffic and private-label penetration sustain volume economics for standard antiperspirant tiers.
- Specialty Shops:Sephora and pharmacy retailers elevate premium natural and clinical-positioned SKUs through assisted selling and sampling infrastructure.
Retail Stores command the largest share; Online Sales are expanding most quickly through millennial and Gen Z purchasing consolidation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in European pharmacy channels while Southeast Asian mass retail operates on compressed margin structures. German and French consumers absorb premium tiers for aluminum-free formulations. Indonesian and Vietnamese households drive volume expansion through entry-level adoption curves.
United States
Subscription bundling and direct-to-consumer channels capture millennial and Gen Z trial-to-repeat conversion in metropolitan markets. FDA aluminum zirconium tetrachlorohydrex gly concentration caps constrain clinical-strength claim differentiation. Greater Boston and Pacific Northwest clusters host biotechnology partnerships for enzymatic odor-neutralization R&D.
Germany
Pharmacy channel density and dermatologist endorsement networks accelerate aluminum-free and microbiome-friendly formulation adoption. ECHA REACH Annex XVII restrictions on fragrance allergens and PFAS force 18-24 month reformulation validation cycles. Bavaria and North Rhine-Westphalia concentrate manufacturing assets for roll-on and stick format production.
Brazil
Aerosol format preference sustains volume leadership through expanded filling infrastructure in São Paulo and Rio de Janeiro industrial corridors. ANVISA alignment with international regulatory standards elevates compliance costs for imported formulations. Domestic manufacturers leverage hydrocarbon propellant systems as F-Gas Regulation phase-down timelines compress European competitor economics.
Indonesia
Urban male grooming normalization expands household penetration rates beyond traditional female-skewed consumption patterns. Retail expansion in Jakarta and Surabaya metropolitan areas accelerates daily deodorant use as occupational hygiene standard. Local distributors prioritize gel and spray formats suited to humid climate conditions.
Vietnam
Modern trade penetration in Ho Chi Minh City and Hanoi reshapes purchasing behavior from traditional trade toward branded personal care. Young professional cohorts adopt deodorant as social confidence necessity in workplace and dating contexts. E-commerce platforms capture trial conversion for international brands seeking emerging market footholds.
Deodorant & Anti-Perspirant Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the deodorant and anti-perspirant sector. Integrated consumer goods conglomerates with captive fragrance compounding and aerosol filling infrastructure dominate mass-market volume tiers. Asset-light brand marketers and dermocosmetic specialists capture premium positioning through clean-label innovation and pharmacy channel access. Competitive dynamics center on geographic density expansion in emerging markets and parallel R&D tracks for aluminum-based clinical formulations versus aluminum-free alternatives.
Among integrated consumer goods conglomerates, Procter & Gamble and Unilever occupy positions exemplifying scale-driven supply chain control and emerging market penetration depth. Beiersdorf represents the dermatological specialization archetype through sensitive-skin positioning and pharmacy channel anchoring in German-speaking markets. These three entities collectively illustrate the bifurcation between mass-market volume economics and premium-tier margin extraction strategies.
| Leading Market Players |
|---|
| Procter & Gamble |
| Unilever |
| Colgate-Palmolive |
| Beiersdorf |
| Henkel |
| Reckitt Benckiser |
| L'Oréal |
| Church & Dwight |
| Coty |
| Others |
Pricing and Supply Chain Analysis
Long-term fragrance supply contracts lock in both aluminum salt access and propellant chemistry visibility for integrated manufacturers, insulating them from Givaudan-Firmenich-Symrise-IFF oligopoly pricing volatility while compressing margin flexibility for asset-light brand marketers dependent on spot procurement.
Pricing Analysis
The customization-premium spread separates standard aluminum-based antiperspirant tiers from microbiome-friendly enzymatic formulations commanding pharmacy channel premiums. Three-tier pricing structure across premium, standard, and economy levels stratifies by formulation complexity and dermatological certification grade. Price differentiation stems from ECHA REACH compliance costs and fragrance allergen disclosure requirements. Cost compression in mass-market spray formats intensifies because F-Gas Regulation phase-down timelines elevate hydrocarbon propellant switching expenses. Supermarket private-label buyers exhibit highest price sensitivity; German pharmacy consumers demonstrate lowest.
Supply Chain Analysis
Just-in-time aluminum chlorohydrate sourcing dominates North American and European manufacturing, while strategic stockpiling of fragrance compounds buffers against Symrise-IFF supply concentration in Germany and France. Geographic supply concentration centers on China for aerosol can components, Brazil for hydrocarbon propellant filling infrastructure, and Switzerland for captive fragrance molecule synthesis. Raw material dependencies rest on aluminum zirconium tetrachlorohydrex gly, hydrofluorocarbon propellants, and prebiotic active feedstocks. Single-source vulnerability in the four-supplier fragrance oligopoly creates formulation exclusivity bottlenecks. Distribution runs through Latin American pharmacy-mass retail hybrids and Southeast Asian modern trade expansion.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat story anchored in regulatory entrenchment: REACH and FDA compliance infrastructure creates asymmetric barriers that favor incumbents with dedicated regulatory affairs teams over new entrants facing 18-24 month validation cycles.
For Market Incumbents: Shield market position by deepening captive fragrance compounding capabilities and accelerating aluminum-free formulation R&D ahead of potential REACH substitution mandates. Prioritize capacity addition in Indonesia and Vietnam to capture urban male grooming normalization. Channel control through pharmacy network density in Germany and France defends margin extraction against direct-to-consumer disruption.
For New Entrants and Emerging Players: Subscription fulfillment infrastructure gaps in Southeast Asia represent the most penetrable service-layer white space, as incumbents under-serve e-commerce logistics for temperature-stable stick formats. Target Vietnamese young professionals through social commerce trial conversion. Microbiome-friendly positioning with dermatologist endorsement networks offers pharmacy channel access without legacy aerosol asset burdens.
For Investors and Strategic Acquirers: German dermocosmetic specialists with REACH-validated aluminum-free portfolios constitute the priority acquisition target archetype, offering regulatory entrenchment and pharmacy channel density. Long-term viability across the analysis window hinges on clean-label R&D pipelines and emerging market distribution reach. Watch ECHA announcements on aluminum salt restrictions as the inflection indicator warranting portfolio rebalancing.
| Strategic Initiative | Industry Significance |
|---|---|
| Microbiome-Friendly Formulation Launch | Captures pharmacy channel premiums through dermatologist endorsement networks in Germany and France. |
| Refill System Infrastructure Investment | Aligns with EU Green Deal circular economy targets while reducing logistics intensity for stick formats. |
| Southeast Asian Distribution Expansion | Captures urban male grooming normalization in Jakarta and Ho Chi Minh City metropolitan clusters. |
| Regulatory Affairs Capability Buildout | Accelerates multi-territory product registration timelines amid REACH and FDA aluminum scrutiny. |
| Direct-to-Consumer Channel Launch | Captures millennial trial-to-repeat conversion through curated personal care subscription bundling. |
Research Methodology
A spread of perspectives from brand managers at integrated consumer goods conglomerates, category buyers at German pharmacy retailers, procurement leads at fragrance compound suppliers, and regulatory affairs directors at EU-based formulators converged on the working assumptions underlying this analysis. Primary interview insights triangulated against secondary validation from ECHA REACH Annex XVII filings, FDA 21 CFR guidance documents, ANVISA regulatory alignment disclosures, and Nielsen retail audit data for Southeast Asian metropolitan markets. Bottom-up volume modeling across format and formulation tiers reconciled with top-down market sizing through trade flow analysis and production capacity assessments.
Segmentation dimensions modeled include product type hierarchy, formulation chemistry tier, end-user application context, and distribution channel structure across the analysis window. CAGRs derived from weighted growth assumptions reflecting urbanization trajectories, regulatory phase-in schedules, and format substitution elasticity. Industry-specific forecast inputs incorporated F-Gas Regulation phase-down timelines and aluminum salt concentration cap enforcement patterns.
Forecasts assume regulatory continuity in EU REACH, FDA, and Health Canada frameworks; material policy shifts on aluminum-based actives or PFAS restrictions would require re-modeling. Specific risk factors include propellant chemistry substitution mandates, fragrance allergen disclosure expansion, and emerging market retail expansion velocity. Revision becomes warranted when ECHA aluminum salt restriction announcements cross implementation thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Beauty & Personal Care
Spain Sustainable Personal Care Market
Beauty & Personal Care
Shaving and Hair Removal Products Market
Beauty & Personal Care
Mexico Beauty and Personal Care Market
Beauty & Personal Care
Wrinkle Release Spray Market
Beauty & Personal Care
South America Hair Styling Products Market
Beauty & Personal Care
Anti Stretch Mark Products Market
Beauty & Personal Care
Natural Cosmetics Market
Beauty & Personal Care
United States Bath Soap Market
Beauty & Personal Care
Germany Lip Care Products Market
Beauty & Personal Care
Eyelash Curler Market
Beauty & Personal Care
Pre-Shave Care Market
Beauty & Personal Care
Herbal Shampoo Market
Beauty & Personal Care
Middle East and Africa Hair Styling Products Market
Beauty & Personal Care
Shaving Foam Market
Beauty & Personal Care
Anti-Acne Cosmetics Market
Beauty & Personal Care
Australia Skin Care Products Market