
 Microchip Electrophoresis Market | 2026-2036
Microchip Electrophoresis Market Size, Share, and Industry Trends Forecast 2026-2036
Microchip Electrophoresis Market Foresight
High-sensitivity optical detection specifications is redrawing competitive boundaries in microchip electrophoresis. Thermo Fisher Scientific leverages its integrated mass spectrometry-electrophoresis workflows to anchor premium instrument positions. Bio-Rad Laboratories sustains dominance in capillary-based microfluidic platforms for clinical diagnostics. Agilent Technologies specializes in automated sample preparation systems that extend laboratory throughput capabilities.
Microchip electrophoresis employs micrometer-scale channels etched into glass or polymer substrates, with electric fields driving analyte separation based on charge-to-size ratios and detection limits reaching picomolar concentrations. The technology serves nucleic acid fragment analysis, protein characterization, and point-of-care diagnostic applications where speed and reagent minimization outweigh conventional gel methods. Microfluidic chips command the largest revenue share due to consumable replenishment cycles and customization for multiplexed assays. Electrokinetic transport technology leads instrument architecture, though surface plasmon resonance detection is gaining traction for label-free protein interaction studies. Pharmaceutical companies represent the fastest-expanding end-user category as biologics pipelines multiply analytical validation requirements.
FDA 21 CFR Part 11 electronic records requirements shape software architecture for diagnostic-grade systems, while ISO 13485 quality management standards govern manufacturing processes for clinical deployment. The EPA's Good Automated Manufacturing Practice guidelines influence environmental testing protocols that employ microchip separation methods. Stakeholders must monitor convergence between microchip electrophoresis and artificial intelligence-driven peak interpretation algorithms that promise autonomous analytical decision-making without human spectral review.
Market Dynamics
Precision medicine pipelines are compressing analytical validation timelines, forcing pharmaceutical quality control labs to replace gel-based workflows with microchip electrophoresis systems that deliver picomolar sensitivity and multiplexed throughput.
Growth Catalysts
- FDA 21 CFR Part 11:Electronic records mandates for diagnostic-grade systems are accelerating replacement cycles in US clinical laboratories. Compliance investments now favor integrated microfluidic platforms over fragmented legacy setups.
- Biologics manufacturing:Monoclonal antibody and cell therapy pipelines are multiplying protein characterization workloads. Microchip electrophoresis reduces sample volumes from microliters to nanoliters.
- Glass substrate etching:Advances in photolithography are lowering microfluidic chip fabrication costs. Polymer alternatives now compete for point-of-care disposable applications.
Market Restraints
- High-purity reagent costs:Electrophoresis buffers and fluorescent dyes face price volatility tied to specialty chemical supply chains concentrated in Germany and Switzerland.
- Optical detection complexity:Laser-induced fluorescence systems require precision alignment that extends field service dependencies. Maintenance contracts consume 15-25% of total ownership costs.
- Capillary electrophoresis substitution:Mature CE platforms retain installed base advantages in regulated pharmaceutical environments where method transfer costs deter switching.
Strategic Opportunities
- Point-of-care diagnostics:Unmet demand exists in rural India and Southeast Asia for portable nucleic acid analyzers. Battery-powered microchip systems bypass centralized lab infrastructure gaps.
- AI-driven peak interpretation:Machine learning algorithms trained on spectral libraries promise autonomous quality control decisions. Early deployments focus on fragment analysis for synthetic biology workflows.
- EU MDR harmonization:In vitro diagnostic device regulations are consolidating certification pathways across member states. Streamlined CE marking reduces time-to-market for European clinical launches.
Industry Challenges
- Cross-disciplinary talent scarcity:Microfluidics engineering requires simultaneous mastery of surface chemistry, photonics, and software integration. Universities produce fewer hybrid specialists than instrument makers require.
- ISO 13485 compliance timelines:Quality management system audits for clinical device manufacturing extend 12-18 months. Small instrument developers face working capital strain during certification gaps.
- Legacy LIMS integration:Hospital and pharmaceutical laboratory information systems use proprietary data formats. Middleware development consumes 20-30% of deployment engineering resources.
Report Scope
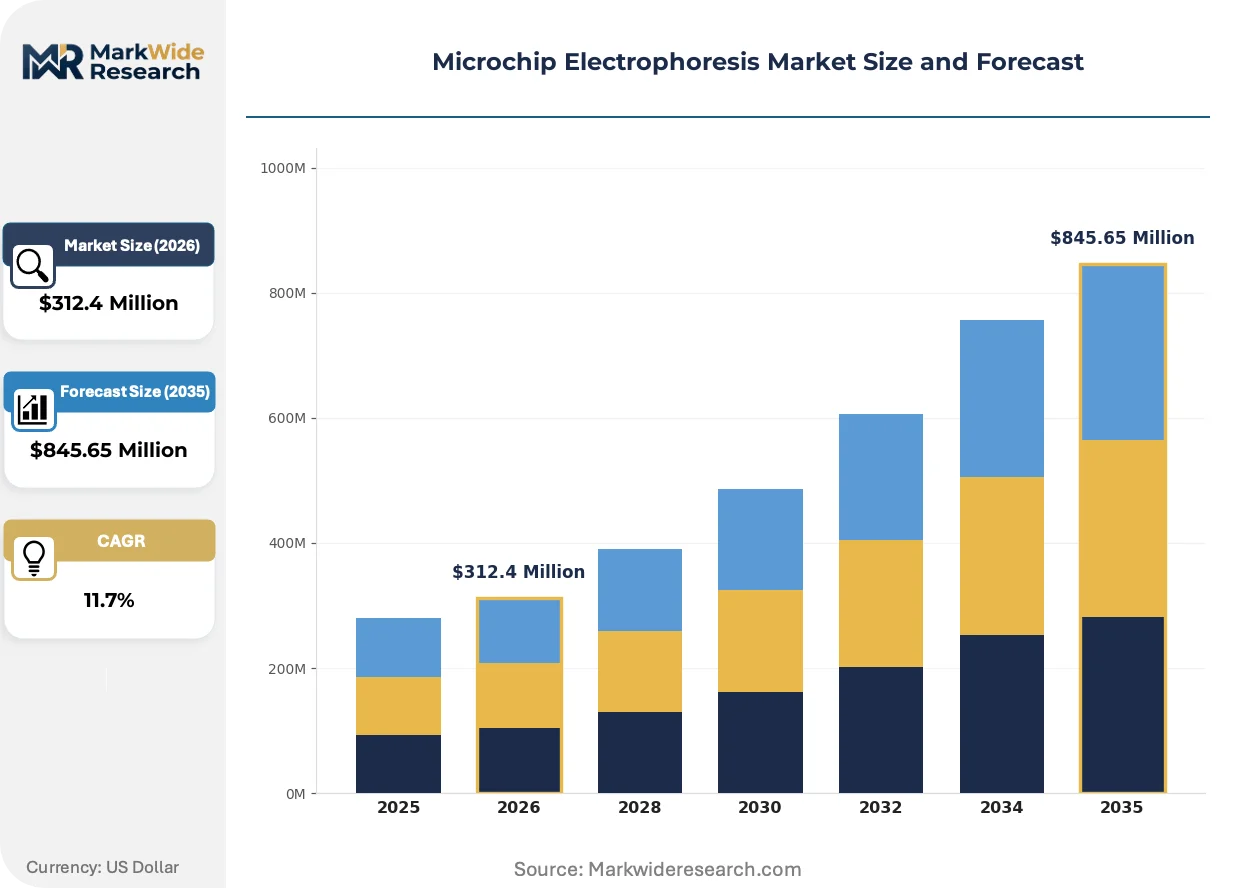
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Microchip Electrophoresis Market |
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $845.65 Million |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Capillaries, Microfluidic Chips, Power Supplies, Buffers Technology: Electrokinetic Transport, Dielectrophoresis, Surface Plasmon Resonance, Optical Detection End User: Research Laboratories, Diagnostic Centers, Pharmaceutical Companies, Academic Institutions Application: Genomics, Proteomics, Forensic Analysis, Clinical Diagnostics |
| Companies Covered | Thermo Fisher Scientific, Bio-Rad Laboratories, Agilent Technologies, Merck Group, Danaher Corporation, GE Healthcare, PerkinElmer, QIAGEN N.V., Shimadzu Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Microchip Electrophoresis Market Shifts & Advancements
Detection modality diversification is redrawing competitive boundaries as label-free methods challenge fluorescence dominance in protein interaction studies.
Surface plasmon resonance detection is fragmenting the optical subsystem market. This label-free approach eliminates fluorescent tagging steps for protein binding kinetics. Contract research organizations adopt hybrid instruments combining SPR with electrophoretic separation. The technology is compressing timelines for biotherapeutic candidate screening.
EMA's evolving guidance on analytical method validation for complex biotherapeutics is tightening performance documentation requirements. Sponsor companies must demonstrate equivalence between microchip and reference methods. European pharmaceutical quality control labs are investing in dual-platform redundancy. This regulatory pressure is elevating instrument vendor service capabilities as competitive differentiators.
Service unbundling is disrupting traditional capital equipment sales in North American academic core facilities. Shared instrument access models separate hardware ownership from per-sample processing fees. Core directors prioritize throughput guarantees over feature specifications. This procurement evolution favors vendors with remote diagnostic capabilities and rapid consumable logistics.
Microchip Electrophoresis Market Segmentation
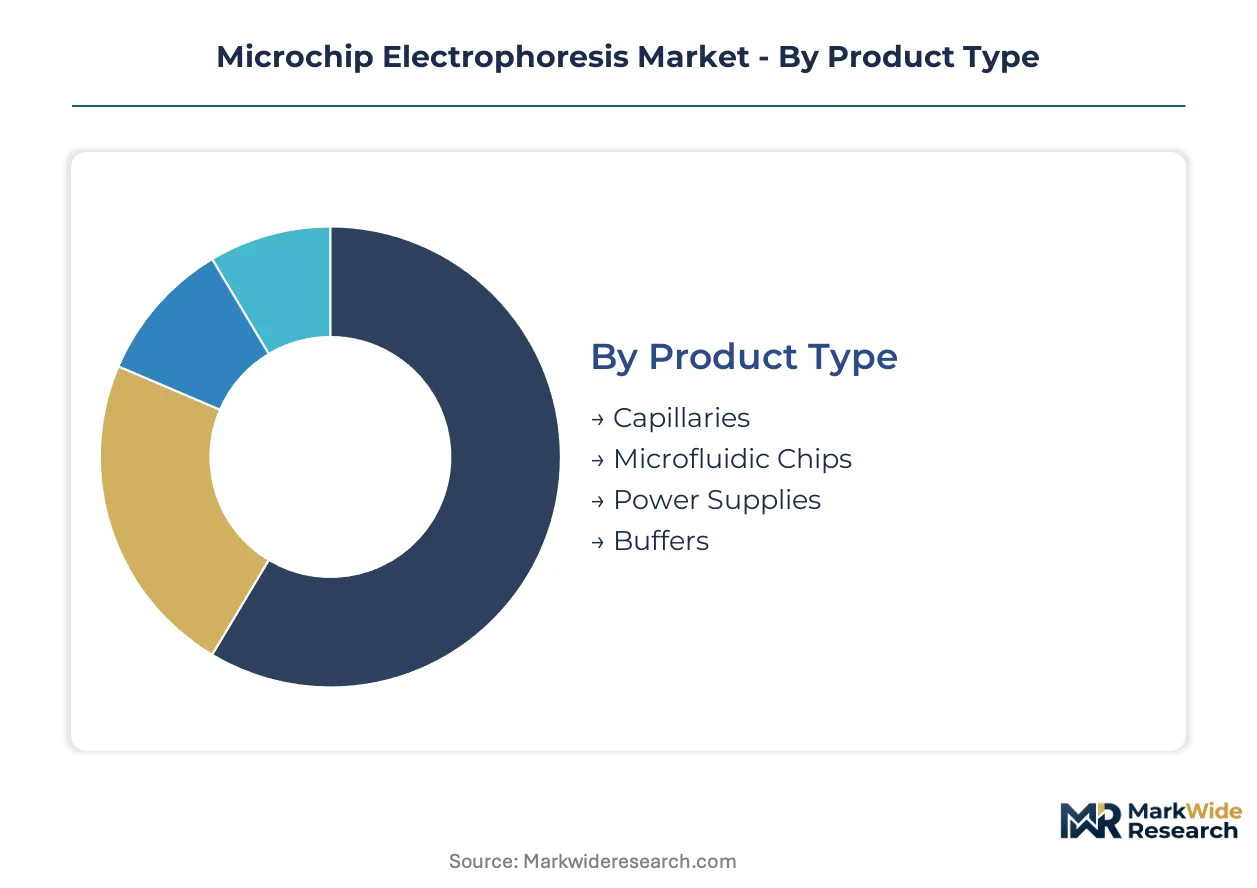
Segmentation in microchip electrophoresis reveals distinct procurement patterns between centralized pharmaceutical manufacturing hubs and distributed diagnostic networks. Technology choices diverge sharply based on whether laboratories prioritize throughput scalability or point-of-care portability.
Product Type:
Domestic production concentrates consumables manufacturing in Germany and Switzerland, while instrument assembly spreads across US and Japanese facilities with heavy import dependence on specialty glass substrates.
- Microfluidic Chips:Photolithography-etched glass or polymer substrates form the consumable core, with channel geometries customized for multiplexed assays. Pharmaceutical quality control labs in Massachusetts and New Jersey drive procurement volumes as biologics validation requirements multiply.
- Capillaries:Fused silica tubes with internal coatings enable high-resolution separations for protein characterization. Academic core facilities in California and Texas favor capillary-based systems for nucleic acid fragment analysis where method transfer from gel electrophoresis remains prioritized.
- Power Supplies:Precision voltage controllers with programmable field gradients support reproducible migration times.
- Buffers:High-purity ionic solutions with defined pH and conductivity specifications face supply chain concentration in specialty chemical producers.
Microfluidic chips command the largest revenue share; momentum sits with capillaries as method transfer costs ease in regulated environments.
Technology:
Cost tiering separates premium label-free detection systems from economy fluorescence-based platforms, with mid-tier hybrid instruments capturing expanding share in contract research organizations.
- Electrokinetic Transport:Electric field-driven analyte migration through microchannels enables picomolar sensitivity with nanoliter sample volumes. Pharmaceutical companies in North Carolina and Pennsylvania deploy electrokinetic systems for monoclonal antibody charge variant analysis under FDA 21 CFR Part 11 compliance mandates.
- Surface Plasmon Resonance:Label-free optical detection measures protein binding kinetics without fluorescent tagging steps. European biopharma clusters in Basel and Cambridge leverage SPR-electrophoresis hybrids for biotherapeutic candidate screening timelines.
- Optical Detection:Laser-induced fluorescence systems with photomultiplier tubes remain the dominant signal transduction architecture.
- Dielectrophoresis:Non-uniform field manipulation enables particle trapping and sorting for cell therapy quality control applications.
Electrokinetic transport anchors installed base; SPR detection is climbing the fastest as label-free methods displace fluorescence in protein interaction studies.
End User:
Application intensity varies by customer sophistication, with pharmaceutical companies demanding validated workflows while academic users prioritize experimental flexibility over regulatory documentation.
- Pharmaceutical Companies:Integrated quality control departments require 21 CFR Part 11-compliant systems with electronic signatures and audit trails. Biologics manufacturing expansion in Massachusetts and California accelerates instrument procurement for release testing and stability protocols.
- Diagnostic Centers:Clinical laboratories seek automated sample-to-answer systems with minimal operator intervention. CLIA-certified facilities in Florida and Arizona drive demand for FDA-cleared microchip platforms in infectious disease testing.
- Research Laboratories:Government and private R&D facilities prioritize method development flexibility over throughput specifications.
- Academic Institutions:University core facilities balance capital constraints against multi-user access requirements.
Pharmaceutical companies hold the largest share; diagnostic centers are gaining share fastest as point-of-care nucleic acid testing expands.
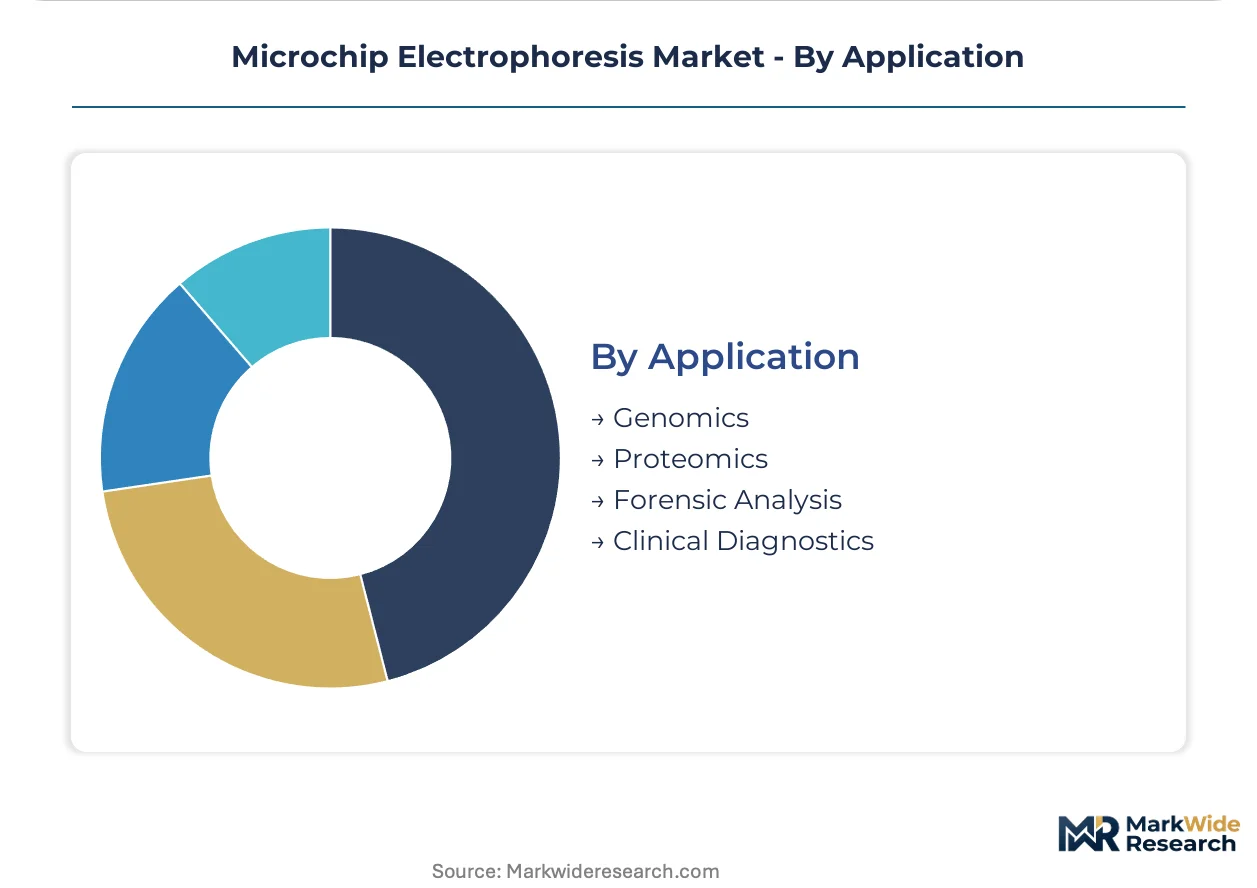
Application:
Volume concentration clusters in genomics and proteomics, with forensic and clinical diagnostics representing higher-margin niches requiring specialized regulatory pathways.
- Genomics:DNA fragment sizing, SNP detection, and sequencing library quality control dominate analytical workloads. Precision medicine initiatives at NIH-funded centers in Maryland and Texas sustain demand for high-throughput nucleic acid analysis.
- Proteomics:Protein separation, charge variant profiling, and glycan analysis support biotherapeutic characterization. Massachusetts biotech corridors deploy microchip electrophoresis for cell therapy product consistency testing under evolving FDA guidance.
- Clinical Diagnostics:Point-of-care infectious disease testing and pharmacogenomics screening require portable instrument formats.
- Forensic Analysis:DNA profiling for criminal casework and disaster victim identification demands chain-of-custody documentation.
Genomics maintains the largest share; proteomics shows the steepest expansion trajectory as biologics pipelines multiply analytical validation requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Import dependence on German and Swiss specialty chemical suppliers shapes procurement economics across major consuming markets. Export competitiveness in microfluidic chip fabrication concentrates in photolithography-equipped facilities in Japan and the Netherlands. Regional regulatory divergence on diagnostic device approval timelines creates arbitrage opportunities for instrument vendors.
United States
Precision medicine initiatives at NIH-funded centers in Maryland and Texas sustain demand for high-throughput nucleic acid analysis systems. FDA 21 CFR Part 11 electronic records mandates accelerate replacement cycles in CLIA-certified clinical laboratories. Massachusetts and California biotech corridors deploy microchip electrophoresis for cell therapy product consistency testing under evolving agency guidance.
Germany
Specialty chemical producers in Ludwigshafen and Leverkusen anchor high-purity buffer and fluorescent dye supply chains for electrophoresis workflows. REACH compliance requirements for laboratory reagents shape formulation specifications and documentation burdens. The Munich-Stuttgart industrial corridor hosts precision optics manufacturers supplying laser-induced fluorescence detection subsystems.
Japan
PMDA streamlined approval pathways for in vitro diagnostic devices compress time-to-market for new microchip platform launches. Photolithography equipment manufacturers in Nagoya and Yokohama supply etching systems for glass substrate microfluidic fabrication. METI funding for advanced medical device development supports domestic instrument makers expanding into proteomics applications.
Switzerland
Swissmedic quality standards for clinical diagnostic systems elevate manufacturing documentation requirements for CE-marked devices. Basel's biopharma cluster drives demand for surface plasmon resonance-electrophoresis hybrid instruments in biotherapeutic candidate screening. The country's specialty chemical sector supplies high-purity reagents facing price volatility tied to concentrated production.
India
CDSCO regulatory harmonization efforts with ICH guidelines streamline import approval for diagnostic-grade microchip systems. CDSCO and state-level FDA offices in Maharashtra and Telangana oversee clinical trial applications for point-of-care nucleic acid analyzers. Bangalore and Hyderabad host contract research organizations adopting microchip electrophoresis for biologics analytical method development.
Microchip Electrophoresis Market Competitive Landscape
Listed leaders compete with private specialists across capital intensity and regulatory compliance capabilities. Thermo Fisher Scientific and Danaher Corporation anchor the publicly traded tier with integrated life science portfolios spanning reagents through software. Three archetypes dominate: diversified conglomerates with diagnostic divisions, pure-play analytical instrument specialists, and contract manufacturers supplying private-label microfluidic chips. Competitive moves concentrate on M&A for complementary detection technologies and strategic partnerships with academic core facilities for early-stage platform validation.
Within the diversified conglomerate tier, Thermo Fisher Scientific and Danaher Corporation exemplify scale-driven positions spanning reagent supply through service contracts. Bio-Rad Laboratories occupies a specialist position in capillary-based microfluidic platforms. Agilent Technologies anchors the automated sample preparation segment. These three companies represent distinct competitive vectors: integrated workflow breadth, clinical diagnostics focus, and laboratory productivity enhancement respectively.
| Leading Market Players |
|---|
| Thermo Fisher Scientific |
| Bio-Rad Laboratories |
| Agilent Technologies |
| Merck Group |
| Danaher Corporation |
| GE Healthcare |
| PerkinElmer |
| QIAGEN N.V. |
| Shimadzu Corporation |
| Others |
Supply & Pricing Matrix
FDA 21 CFR Part 11 compliance certification gates both supplier qualification and price differentiation simultaneously, separating diagnostic-grade systems with validated electronic records from research-use-only platforms. Pharmaceutical quality control labs absorb premium pricing for audit-trail capabilities while academic facilities prioritize cost efficiency over regulatory documentation.
Pricing Analysis
Pharmaceutical companies anchor a three-tier pricing structure across premium, standard, and economy levels. Premium tiers command price multiples for ISO 13485-certified manufacturing and FDA-cleared software, while economy segments serve research laboratories with stripped-down detection modules. Cost compression in mid-tier systems is intensifying because polymer substrate alternatives displace glass etching for disposable point-of-care applications. Academic core facilities exhibit highest price sensitivity; biologics manufacturers show lowest sensitivity due to method validation lock-in costs.
Supply Chain Analysis
Germany and Switzerland anchor high-purity reagent production for electrophoresis buffers and fluorescent dyes. Japan and the Netherlands supply photolithography equipment for glass substrate microfluidic fabrication. Specialty chemical feedstocks draw from concentrated European producers, creating single-source vulnerability for clinical-grade dye formulations. Distribution runs through authorized distributors serving CLIA-certified laboratories and direct OEM relationships with pharmaceutical manufacturers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Microchip electrophoresis sits in early-cycle expansion as biologics pipelines multiply analytical validation requirements across pharmaceutical manufacturing. Precision medicine initiatives compress timelines for nucleic acid and protein characterization workflows.
For Market Incumbents: Consolidate service capabilities as competitive differentiators against capillary electrophoresis substitution threats. Deepen backward integration into specialty glass substrate production to buffer photolithography equipment lead times. Invest in AI-driven peak interpretation software to preempt autonomous analytical decision-making disruption.
For New Entrants and Emerging Players: Anchor in point-of-care diagnostic white space across rural India and Southeast Asia where centralized laboratory infrastructure gaps persist. Target battery-powered portable nucleic acid analyzers for infectious disease testing. Pursue CDSCO regulatory harmonization pathways to accelerate import approval timelines against established competitors.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across surface plasmon resonance detection subsystems as label-free methods displace fluorescence dominance. Five-to-ten year viability favors contract manufacturers with captive microfluidic chip fabrication and ISO 13485 quality management certification. Monitor EMA analytical method validation guidance evolution as signal for European pharmaceutical quality control replacement cycle timing.
| Strategic Initiative | Industry Significance |
|---|---|
| AI-Driven Peak Interpretation Development | Machine learning algorithms trained on spectral libraries promise autonomous quality control decisions for synthetic biology workflows. |
| SPR Detection Subsystem Integration | Surface plasmon resonance hybrids compress biotherapeutic candidate screening timelines for European biopharma clusters. |
| Point-of-Care Portable Platform Launch | Battery-powered systems bypass centralized laboratory infrastructure gaps in rural diagnostic networks. |
| ISO 13485 Certification Investment | Quality management system audits extend manufacturing documentation capabilities for clinical device deployment. |
| Backward Integration into Glass Substrates | In-house photolithography etching buffers supply chain concentration in Japanese and Dutch equipment suppliers. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of FDA 510(k) filings, EMA marketing authorization applications, and ISO 13485 certification databases. Interviews with pharmaceutical quality control directors, clinical laboratory managers, microfluidics engineers, and diagnostic device procurement officers inform demand-side validation. Customs trade data for electrophoresis instrument imports, SEC filings of listed instrument manufacturers, and NIH precision medicine initiative budget disclosures provide supply-side triangulation. Bottom-up instrument shipment analysis cross-references against top-down pharmaceutical R&D expenditure allocation.
Segmentation dimensions modeled span product type, technology architecture, end-user category, and application area across the analysis window. CAGRs derive from weighted average of historical shipment growth, pharmaceutical pipeline expansion rates, and regulatory compliance investment trajectories. Forecast inputs incorporate biologics manufacturing capacity buildout schedules and point-of-care diagnostic reimbursement pathway developments.
Material uncertainties — regulatory guidance revisions on analytical method validation, specialty chemical supply disruptions, and AI-driven workflow automation adoption curves — sit outside the modeled envelope. Forecasts reflect assumptions about continued FDA 21 CFR Part 11 enforcement and sustained pharmaceutical outsourcing of analytical services. Recalibration cycles align with material shifts in EMA guidance documents and PMDA streamlined approval pathway modifications.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Analytical Instruments
Near-Infrared Spectroscopy Market
Analytical Instruments
High-Sensitivity Luminometers Market
Analytical Instruments
North America Liquid Chromatography Devices Market
Analytical Instruments
Scientific Instruments Market
Analytical Instruments
Europe Dissolved Gas Analyzer Market
Analytical Instruments
Spatial Mass Spectrometry Market
Analytical Instruments
Middle East and Africa Dissolved Gas Analyzer Market
Analytical Instruments
Turbidimeter Market
Analytical Instruments
Automated Microscopy Market
Analytical Instruments
Next Generation Mass Spectrometer Market
Analytical Instruments
Life Science and Analytical Instruments Market
Analytical Instruments
Network Analyzers Market
Analytical Instruments
Universal Probe Library Market
Analytical Instruments
Global Spectroscopy Market
Analytical Instruments
Global Ion Mobility Spectrometry Market
Analytical Instruments
Global Gel Documentation Systems Market