
 Nail Care Market | 2026-2036
Nail Care Market Size, Share, and Industry Trends Forecast 2026-2036
Nail Care Market Intelligence
ISO 22716 Good Manufacturing Practices certification is bifurcating the competitive landscape between compliant manufacturers and informal suppliers. OPI leverages its professional salon heritage to sustain channel control across premium nail polish lines. Shiseido anchors its position through R&D intensity in nail treatment formulations targeting dermatology clinics. Sally Hansen competes on mass-market accessibility through pharmacy and department store distribution networks.
Nail care encompasses cosmetic and therapeutic products applied to fingernails and toenails, typically formulated with film-forming polymers, plasticizers, and pigments that cure through evaporation or UV polymerization to provide color, protection, or structural reinforcement. The primary commercial purpose spans aesthetic enhancement, nail plate strengthening, and cuticle health maintenance across consumer and professional settings. Nail polish occupies the largest value pool within product type segmentation, though nail treatments command premium pricing in dermatology clinic channels. Professional nail services within application segmentation generate recurring revenue streams that home care cannot replicate, while online stores as a distribution channel are displacing department stores for discovery among retail consumers.
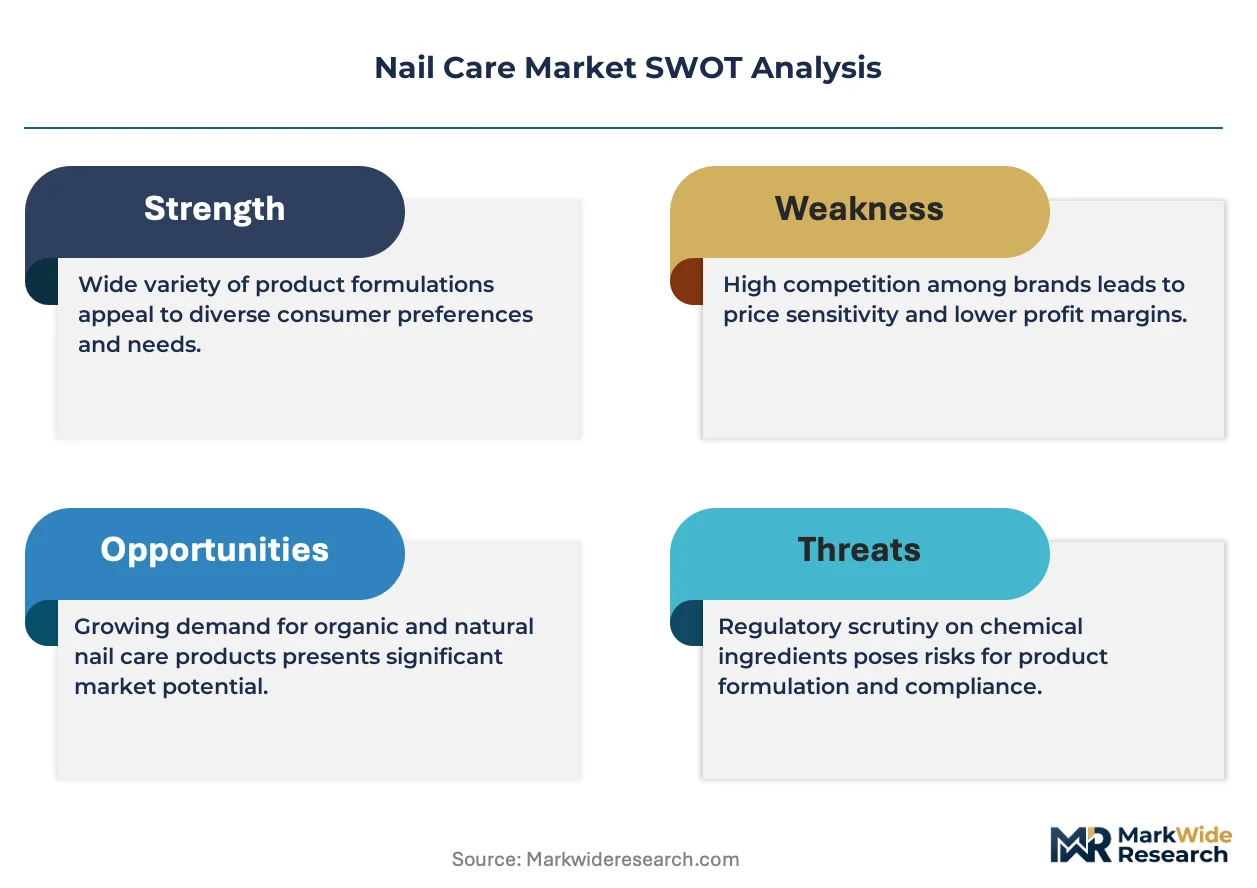
FDA cosmetic labeling requirements and the EU REACH framework govern ingredient safety thresholds, with California's Proposition 65 adding state-level disclosure obligations that influence national formulation decisions. China's SAMR cosmetic registration rules create separate compliance pathways for brands entering that market, extending time-to-market for international entrants. Stakeholders must monitor evolving state-level chemical restrictions and platform-specific e-commerce regulations as these rules increasingly determine which formulations qualify for shelf placement.
Market Dynamics
Live-stream commerce is restructuring how nail care brands acquire customers, compressing traditional retail discovery cycles and forcing manufacturers to build content production capabilities alongside formulation expertise.
Growth Catalysts
- Professional salon service expansion:Salon chains are broadening treatment menus to include medical-grade nail therapies, creating recurring revenue streams that home care products cannot replicate.
- REACH compliance differentiation:Manufacturers achieving full EU chemical registration gain preferential shelf placement in European pharmacy channels, locking out informal competitors.
- China e-commerce infrastructure:Domestic platforms enable direct brand-to-consumer relationships that bypass traditional import markups for international entrants.
Market Restraints
- Petrochemical input volatility:Film-forming polymers and plasticizers derive from oil-based feedstocks, exposing margins to energy price swings without long-term supply contracts.
- UV curing equipment concentration:Professional-grade LED and UV lamp manufacturing clusters in Guangdong province, creating single-source vulnerability for salon chains.
- California Proposition 65 friction:State-level disclosure requirements for formaldehyde and toluene force national reformulation decisions that raise costs for all US distribution.
Strategic Opportunities
- Dermatology clinic channel penetration:Medical settings represent underdeveloped distribution for therapeutic nail treatments targeting onychomycosis and nail psoriasis patients.
- ISO 22716 certification arbitrage:Compliant manufacturers can capture pharmacy shelf space as retailers eliminate informal suppliers under quality audits.
- Sustainable polymer convergence:Bio-based film formers combined with water-based delivery systems open premium positioning in environmentally regulated Nordic markets.
Industry Challenges
- Nail technician certification gaps:Professional service quality varies widely where vocational training lacks standardized curricula for gel application and cuticle health protocols.
- Dual regulatory pathway complexity:Brands entering China must navigate SAMR cosmetic registration timelines that extend 12-18 months beyond typical Western market entry schedules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Nail Care Market |
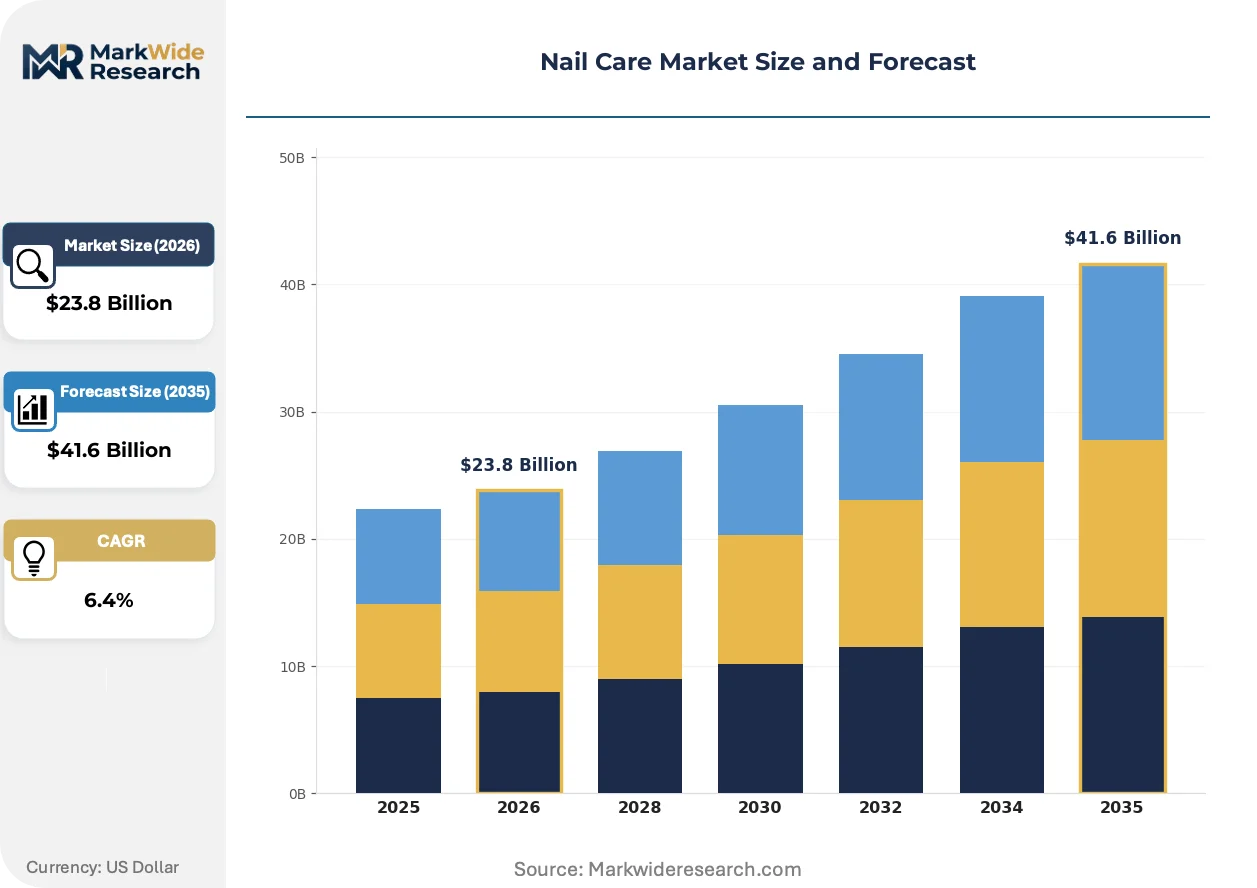
| Market Size in 2026 | $23.8 Billion |
| Market Size in 2035 | $41.6 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Nail Polish, Nail Hardeners, Cuticle Removers, Nail Treatments, Nail Art Supplies Application: Salon Use, Home Care, Professional Nail Services, Bridal Services, Spa Treatments End User: Beauty Salons, Nail Technicians, Retail Consumers, Dermatology Clinics, Spa Centers Distribution Channel: Online Stores, Specialty Beauty Retailers, Pharmacies, Department Stores, Direct Sales |
| Companies Covered | Revlon, Chanel, OPI, China Glaze, Shiseido, Sally Hansen, L'Oreal Paris, Dior, Essie, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Nail Care Market Strategic Shifts & Innovations
Formulation science and channel economics are diverging sharply, with laboratory R&D investments decoupling from go-to-market execution as digital platforms rewrite customer acquisition economics.
Peptide-infused nail strengtheners are decomposing the traditional divide between cosmetic color cosmetics and therapeutic treatments. Prestige beauty retailers are accelerating shelf space allocation for these hybrid products. The technology is decomposing standalone treatment categories into integrated color-care formulations that command price premiums.
EU REACH substance restriction updates are tightening permissible thresholds for formaldehyde-releasing preservatives in nail hardeners. Manufacturers face reformulation costs or market withdrawal for non-compliant SKUs. Professional salon channels in Germany and France are responding by sourcing exclusively from pre-registered suppliers with full safety data sheet documentation.
Subscription-based replenishment models are capturing high-frequency nail polish purchasers who previously bought through seasonal department store visits. Direct-to-consumer brands are displacing legacy wholesale relationships with personalized shade-matching algorithms. This behavioral shift concentrates most visibly in South Korea, where platform loyalty programs integrate nail care with broader beauty category purchasing.
Nail Care Market Segmentation
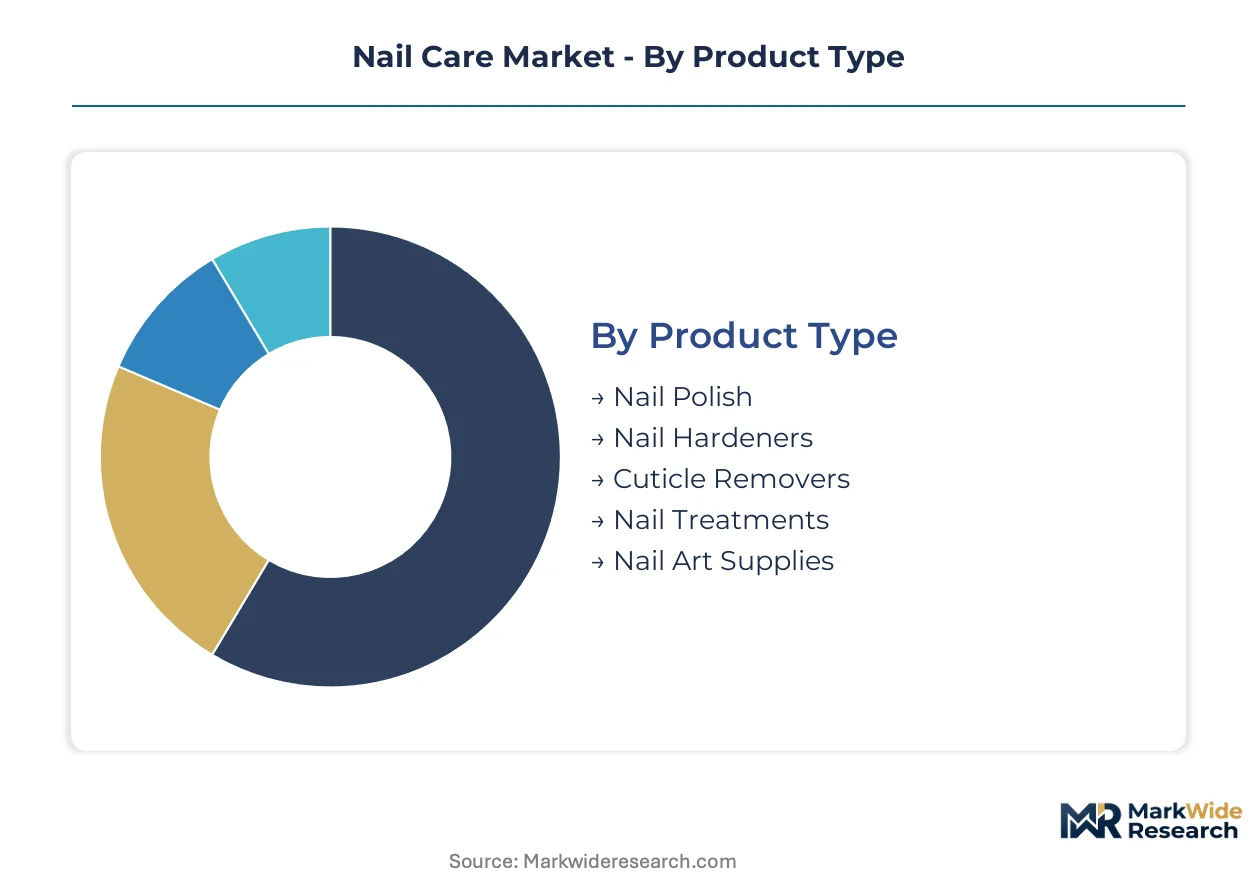
Segmentation in nail care reveals divergent margin architectures across product chemistry, service delivery, and channel economics. Understanding these fault lines exposes where formulation investments yield pricing power versus where scale and logistics dominate profitability.
Product Type:
Margin pools concentrate in products requiring polymer science expertise and regulatory documentation, separating commodity color cosmetics from premium therapeutic formulations.
- Nail Polish:Film-forming nitrocellulose and acrylic copolymer bases deliver color through solvent evaporation or UV-cured gel systems. Demand clusters in China and South Korea, where live-stream commerce compresses shade turnover cycles and rewards agile supply chains.
- Nail Treatments:Peptide-infused strengtheners and keratin-repair serums target brittle nail plates and post-gel damage recovery. Dermatology clinics in Germany and France drive prescription-adjacent sales, with ECHA REACH pre-registration serving as a pharmacy shelf gatekeeper.
- Nail Hardeners:Formaldehyde resin and calcium-based formulations provide structural reinforcement for soft nail plates. FDA cosmetic labeling rules govern US distribution, while California Proposition 65 disclosure requirements shape national formulation decisions.
- Cuticle Removers:Alkaline formulations with potassium hydroxide dissolve keratinized tissue for manicure preparation. Professional salon chains standardize procurement around ISO 22716 certified suppliers.
- Nail Art Supplies:Stamping plates, chrome powders, and magnetic pigments enable decorative customization. South Korean platform ecosystems integrate these with broader K-beauty purchasing patterns.
The dominant share belongs to Nail Polish, while Nail Treatments are climbing the fastest as therapeutic positioning commands premium shelf placement.
Application:
Service delivery models split between recurring professional revenue streams and transactional home use, with medical-grade protocols opening new margin corridors.
- Professional Nail Services:Gel extension, sculpting, and medical-grade pedicure protocols generate subscription-like visit frequency. Salon chains in the United States and France are expanding treatment menus to capture recurring revenue that retail products cannot replicate.
- Spa Treatments:Paraffin therapy and aromatherapy manicures position nail care within wellness tourism packages. Resort destinations in Thailand and UAE integrate these into hospitality revenue per available room metrics.
- Salon Use:In-salon polish application and basic manicure services represent entry-level professional engagement. Volume concentrates in franchise networks with centralized procurement contracts.
- Home Care:Consumer-directed polish application and maintenance kits serve price-sensitive segments. E-commerce live-streaming in China displaces traditional retail discovery for this cohort.
- Bridal Services:Specialized nail art and long-wear gel packages target wedding event planning. Seasonal demand peaks create capacity utilization challenges for independent technicians.
Professional Nail Services capture the largest revenue pool, though Spa Treatments are gaining share fastest as wellness positioning commands pricing premiums.
End User:
Customer type determines regulatory pathway complexity and purchase frequency, with institutional buyers enforcing certification standards that exclude informal suppliers.
- Beauty Salons:Full-service establishments purchasing bulk polish and treatment inventories through distributor networks. German salon chains now require ECHA REACH documentation for all hardener and adhesive products.
- Dermatology Clinics:Medical settings prescribing therapeutic nail treatments for onychomycosis and psoriasis patients. FDA oversight in the United States and ANSM registration in France create separate compliance pathways.
- Retail Consumers:Individual purchasers selecting through pharmacy, department store, or digital channels. South Korean platform loyalty programs integrate nail care with broader beauty category purchasing.
- Nail Technicians:Independent contractors sourcing professional-grade supplies through specialty distributors. Certification gaps in vocational training create quality variation across markets.
- Spa Centers:Wellness facilities bundling nail services with massage and skincare treatments. Procurement decisions increasingly weight ISO 22716 certification under quality audit pressure.
Beauty Salons maintain the dominant procurement volume, while Dermatology Clinics are expanding most quickly as therapeutic nail care penetrates medical channels.
Distribution Channel:
Channel selection determines customer acquisition economics and inventory risk allocation, with digital platforms rewriting traditional wholesale relationships.
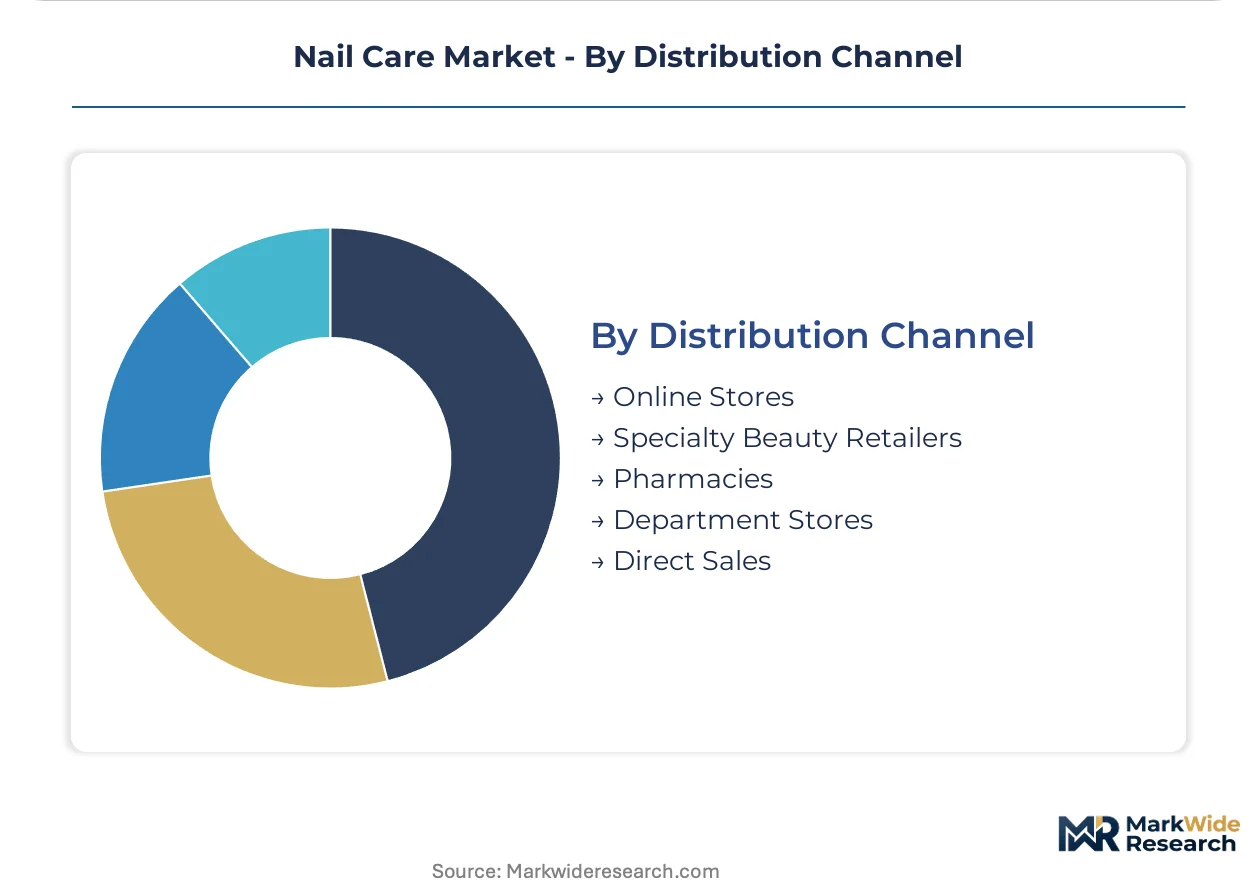
- Online Stores:Direct-to-consumer platforms and marketplace storefronts enabling personalized shade matching and subscription replenishment. Domestic Chinese platforms bypass import markups for international entrants through cross-border e-commerce infrastructure.
- Specialty Beauty Retailers:Sephora, Ulta, and equivalent prestige chains curating discovery-oriented merchandising. Prestige beauty retailers are accelerating shelf space allocation for peptide-infused hybrid products.
- Pharmacies:Drugstore chains and independent chemists stocking mass-market treatments and basic color cosmetics. EU pharmacy channels increasingly restrict placement to REACH-registered suppliers with full safety data sheet documentation.
- Department Stores:Traditional beauty counters experiencing foot traffic erosion as discovery shifts digital. Seasonal purchasing patterns persist for gift-oriented nail art collections.
- Direct Sales:Multi-level marketing networks and brand-owned retail boutiques. Personalized consultation models retain relevance in markets with lower e-commerce penetration.
Online Stores command the dominant transaction volume, while Specialty Beauty Retailers are capturing share fastest through experiential merchandising and exclusive brand partnerships.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Government incentive programs and regulatory harmonization initiatives are reshaping geographic demand distribution across nail care markets. SAMR cosmetic registration timelines in China and EU REACH substance restrictions are creating divergent compliance pathways that favor domestic incumbents in each jurisdiction.
China
Live-stream commerce infrastructure and domestic platform ecosystems are compressing shade turnover cycles for nail polish brands. SAMR cosmetic registration rules mandate 12-18 month approval timelines that extend market entry for international entrants. Guangdong province manufacturing clusters dominate UV curing equipment production for professional salon chains.
United States
FDA cosmetic labeling requirements and state-level chemical disclosure mandates are elevating compliance costs for formaldehyde-containing hardeners. California Proposition 65 obligations for toluene and formaldehyde force national reformulation decisions that raise production expenses. Salon chain expansion in Texas and Florida is broadening treatment menus to capture recurring professional service revenue.
Germany
ECHA REACH pre-registration documentation serves as a pharmacy shelf gatekeeper for nail hardeners and adhesives. ISO 22716 certification requirements under quality audit pressure are eliminating informal suppliers from distributor networks. Industrial concentration in North Rhine-Westphalia supports polymer science R&D for therapeutic nail treatment formulations.
France
ANSM registration pathways for dermatology clinic distribution create separate compliance corridors for prescription-adjacent nail therapies. Prestige beauty retail chains in Paris are accelerating shelf space allocation for peptide-infused hybrid color-care products. Provence-Alpes-Côte d'Azur wellness tourism destinations integrate medical-grade pedicure protocols into hospitality revenue models.
South Korea
Platform loyalty programs integrating nail care with broader K-beauty purchasing patterns are displacing traditional department store discovery. MFDS cosmetic safety standards govern ingredient thresholds for nail strengtheners targeting post-gel damage recovery. Seoul Capital Area content production capabilities support direct-to-consumer shade-matching algorithm deployment.
Nail Care Market Key Industry Players
Listed leaders compete with private specialists across formulation expertise and channel control dimensions. The market structure tilts toward brand heritage concentration in professional salon channels while mass-market accessibility fragments across pharmacy and digital platforms. Three archetypes dominate: legacy beauty conglomerates leveraging R&D scale, professional heritage brands sustaining channel discipline, and direct-to-consumer entrants exploiting platform economics. Competitive moves concentrate on certification arbitrage for pharmacy placement and content production capability building for live-stream commerce.
Among legacy beauty conglomerates, L'Oreal Paris and Revlon occupy positions defined by mass-market distribution scale and pharmacy network penetration. Chanel and Dior exemplify the premium heritage archetype, anchoring prestige retail positioning through exclusive brand partnerships and experiential merchandising. OPI represents the professional channel specialist, sitting within salon-centric supply relationships that sustain formulation credibility among licensed technicians.
| Leading Market Players |
|---|
| Revlon |
| Chanel |
| OPI |
| China Glaze |
| Shiseido |
| Sally Hansen |
| L'Oreal Paris |
| Dior |
| Essie |
| Others |
Cost & Logistics Intelligence
Long-term offtake agreements between Guangdong-based UV lamp manufacturers and US salon chains lock in supply access while fixing equipment costs against petrochemical volatility. These contracts insulate professional service providers from spot-market swings in film-forming polymer feedstocks that otherwise compress margins on nail polish production.
Pricing Analysis
Certification level creates the primary spread between REACH-registered pharmacy-grade hardeners and informal economy alternatives. Three-tier pricing structure across premium salon-exclusive gel systems, standard retail polish lines, and economy bulk refills reflects compliance documentation burdens. Cost compression in the economy tier is intensifying because California Proposition 65 reformulation requirements propagate nationally. Retail consumers demonstrate highest price sensitivity, while dermatology clinics accept premiums for ANSM-registered therapeutic formulations.
Supply Chain Analysis
Inventory cycles for nitrocellulose and acrylic copolymers stretch 8-12 weeks from Guangdong chemical clusters to European formulators. Manufacturing concentrates in China, South Korea, and Germany for polymer synthesis, with Italy and France contributing specialty pigment compounding. Raw material dependencies on toluene, formaldehyde resins, and photoinitiator chemicals expose margins to energy price swings. Single-source vulnerability concentrates in Guangdong province for professional-grade LED curing equipment. Distribution runs through pharmacy chains in Germany, live-stream platforms in China, and specialty beauty retailers in France.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward salon chains and pharmacy retailers that consolidate procurement through centralized quality audits, squeezing informal suppliers from shelf placement.
For Market Incumbents: Compound formulation credibility through ISO 22716 certification investments that preempt retailer quality audits eliminating uncertified competitors. Deepen backward integration into bio-based polymer R&D to defend margin position against petrochemical volatility. Lock in exclusive distribution through long-term offtake agreements with expanding US salon chains that broaden medical-grade treatment menus. For New Entrants and Emerging Players: Anchor in dermatology clinic channels where therapeutic nail treatments for onychomycosis remain underpenetrated by cosmetic heritage brands. Target the Nordic premium segment with water-based delivery systems that satisfy environmental regulations while commanding price premiums. Deploy direct-to-consumer shade-matching algorithms through Seoul-based content production capabilities to bypass legacy wholesale relationships. For Investors and Strategic Acquirers: Capital is best deployed toward mid-cap specialists with pre-existing REACH documentation and live-stream commerce infrastructure rather than legacy mass-market brands dependent on eroding department store traffic. Long-term viability favors assets with dual regulatory pathway experience navigating both FDA cosmetic rules and SAMR registration timelines. Monitor ECHA substance restriction updates as the signal indicating which formulation portfolios face forced obsolescence versus sustainable competitive moats.| Strategic Initiative | Industry Significance |
|---|---|
| ISO 22716 Certification Investment | Eliminates informal competitors as German pharmacy chains enforce quality audits. |
| Live-Stream Commerce Infrastructure Buildout | Captures Chinese consumer discovery cycles that bypass traditional import markups. |
| Bio-Based Polymer R&D Partnership | Opens premium positioning in Nordic markets with strict environmental regulations. |
| Dermatology Clinic Channel Expansion | Penetrates medical settings for therapeutic treatments with prescription-adjacent pricing. |
| REACH Pre-Registration Acceleration | Secures pharmacy shelf placement ahead of ECHA substance restriction enforcement. |
Research Approach
Findings reconcile primary fieldwork against secondary review of FDA cosmetic labeling guidance, ECHA REACH substance restriction updates, SAMR registration databases, and customs trade data for polymer feedstock flows. Primary interviews engaged formulation chemists at polymer manufacturers, procurement directors at German pharmacy chains, regulatory affairs leads navigating dual FDA-SAMR pathways, and salon chain operations heads expanding treatment menus. Bottom-up triangulation across product-type volume estimates converged with top-down market sizing from trade flow analysis and platform transaction data.
Segmentation dimensions modeled include product chemistry tier, application setting, end-user type, and distribution channel across the projection horizon. CAGRs derive from growth rate convergence across analyst consensus, historical elasticity patterns, and regulatory timeline impacts. Industry-specific forecast inputs incorporate live-stream commerce penetration curves and REACH compliance cost pass-through assumptions.
Material uncertainties — petrochemical price volatility, ECHA substance restriction timing, SAMR registration backlog resolution — sit outside the modeled envelope. Forecasts reflect documented assumptions regarding regulatory enforcement intensity and platform commerce adoption curves. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Beauty & Personal Care
Bath and Shower Products Market
Beauty & Personal Care
Nail Salon Market
Beauty & Personal Care
Hair Removal Creams for Private Parts Market
Beauty & Personal Care
Slimming Cream Market
Beauty & Personal Care
Hair Thickener Serum Market
Beauty & Personal Care
Hair Removal Epilator Market
Beauty & Personal Care
South Korea Dermocosmetics Market
Beauty & Personal Care
Colombia Cosmetics Products Market
Beauty & Personal Care
Europe Hair and Skincare Market
Beauty & Personal Care
Global Probiotic Cosmetic Products Market
Beauty & Personal Care
Saudi Arabia Hair Care Market
Beauty & Personal Care
Global Electric Head and Scalp Massager Market
Beauty & Personal Care
Bath Oil Market
Beauty & Personal Care
US Personal Care Contract Manufacturing Market
Beauty & Personal Care
South America Hair Conditioner Market
Beauty & Personal Care
Saudi Arabia Eyelash Serum Market