
 United States Live Music Market | 2026-2036
United States Live Music Market Size, Share, and Industry Trends Forecast 2026-2036
United States Live Music Market Insights
The Inflation Reduction Act's clean energy incentives for venue operators is decoupling carbon-intensive touring from growth strategies across the sector. Live Nation Entertainment leverages its vertically integrated ticketing and promotion platform to sustain margin capture across the value chain. AEG anchors its position through venue ownership in major metropolitan markets. Oak View Group differentiates through specialized arena development and public-private partnerships.
United States live music comprises professionally staged performances delivered through permanent venues, temporary festival grounds, and touring productions, requiring calibrated acoustic engineering, load-bearing stage infrastructure, and crowd-safety systems designed for occupancy loads exceeding ten thousand attendees. Concerts and festivals command the largest revenue share, with festivals generating disproportionate per-attendee ancillary spend through multi-day programming. Corporate events represent the fastest-expanding segment as B2B buyers redirect budgets from digital channels to experiential formats. Premium ticket tiers concentrate margin pools, while economy pricing expands total addressable audience.
FAA regulations govern drone and aerial performance elements above outdoor venues, while OSHA standards enforce worker protections during stage construction and load-in operations. State-level alcohol beverage control boards shape on-site revenue models through licensing requirements that vary across jurisdictions. Stakeholders must monitor how municipal noise ordinances and curfew restrictions in high-growth secondary markets will constrain scheduling flexibility and capacity utilization.
Market Dynamics
Live Nation Entertainment's vertical control over ticketing, promotion, and venue operations is compressing margins for independent promoters and forcing structural realignment across the United States live music value chain.
Growth Catalysts
- The Inflation Reduction Act's clean energy incentives:Venue operators in Texas and Florida are retrofitting facilities to capture tax credits, reducing operational carbon intensity while lowering long-term energy costs.
- Corporate event buyers:B2B procurement teams are reallocating digital marketing budgets toward experiential programming, creating sustained demand for mid-size amphitheaters and private festival activations.
- Festival permit acceleration:Municipal authorities in Tennessee and secondary Texas markets are streamlining temporary event licensing, compressing lead times for large-scale outdoor productions.
Market Restraints
- ADA infrastructure mandates:The Department of Justice's accessibility enforcement is imposing six-figure renovation requirements on legacy venues built before 1990, particularly in the Northeast and Rust Belt.
- Labor concentration in stage construction:Specialized rigging and load-bearing crews cluster in Las Vegas, Nashville, and Los Angeles, creating bottleneck risk during peak summer touring season.
- Municipal noise ordinances:Curfew restrictions in Austin, Denver, and Atlanta secondary markets constrain scheduling flexibility and compress per-night revenue potential for outdoor amphitheaters.
Strategic Opportunities
- Underpenetrated secondary markets:Boise, Des Moines, and Little Rock exhibit per-capita venue capacity deficits relative to comparable metro populations, presenting greenfield development potential.
- Drone and aerial performance integration:FAA Part 107 waiver expansion is enabling synchronized drone light shows above festival grounds, differentiating premium-tier ticket packages.
- Public-private arena partnerships:Oak View Group's municipal financing models in Milwaukee and Seattle demonstrate replicable structures for taxpayer-subsidized venue construction in mid-tier markets.
Industry Challenges
- Acoustic engineering talent scarcity:Certified live sound designers and venue acousticians face generational replacement gaps as retirement waves hit the specialized consulting sector.
- OSHA compliance during load-in operations:Stage construction crews operate under compressed timelines that conflict with mandated fall protection and heavy-lift protocols, generating inspection exposure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States Live Music Market |
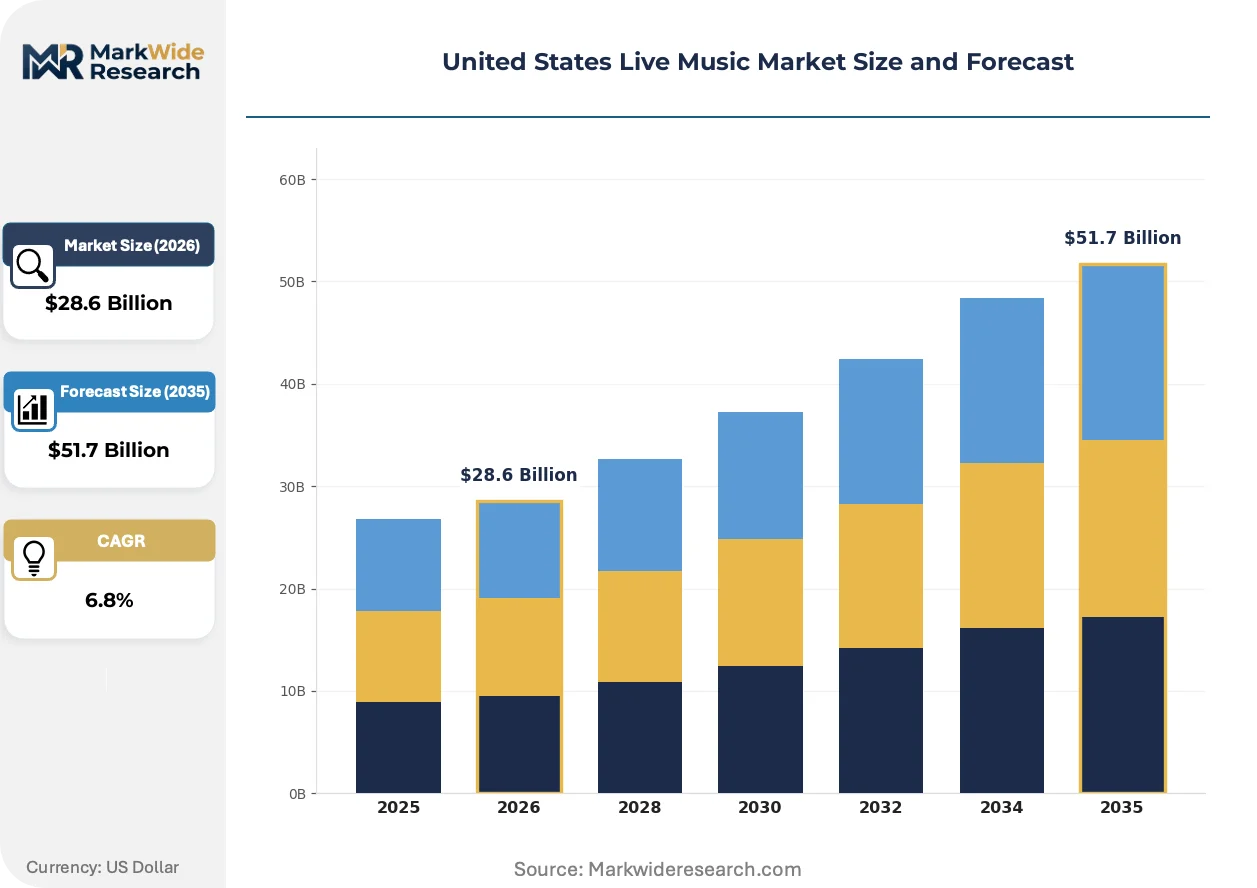
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $51.7 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Event Type: Concerts, Festivals, Club Performances, Corporate Events Ticket Pricing: Premium, Standard, Economy, VIP Audience Demographics: Millennials, Gen Z, Families, Seniors Music Genre: Rock, Pop, Jazz, Electronic |
| Companies Covered | MSG Entertainment Holdings, Oak View Group, Live Nation Entertainment, LiveStyle, Endeavor Group Holdings, AEG, Liberty Media Corporation, Goldenvoice, Madison Square Garden Entertainment, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States Live Music Market Trends and Innovations
Immersive audiovisual technologies and sustainability-driven production practices are reconfiguring capital allocation priorities for venue operators and touring productions across the United States.
Spatial audio systems and holographic display arrays are integrating into permanent venue installations and touring rigs. Premium amphitheaters in California and Colorado are deploying these technologies to justify 40-60% ticket price premiums over standard configurations. The capital intensity of these deployments is consolidating upgrade decisions among multi-venue operators with balance sheet capacity.
OSHA's updated fall protection standards for entertainment industry rigging are mandating engineered anchor systems and certified personnel for all temporary stage structures. Festival promoters in Florida and Tennessee are absorbing compliance costs through expanded safety staffing budgets. Smaller independent operators without dedicated safety officers are outsourcing to third-party compliance firms, fragmenting execution quality.
Corporate buyers are consolidating experiential programming decisions into centralized procurement functions with multi-year venue partnership agreements. Technology and financial services firms in New York and Chicago are displacing transactional ticket purchasing with preferred venue relationships that guarantee access and customize production elements. This concentration is compressing margins for promoters dependent on spot-market corporate sales.
United States Live Music Market Segmentation
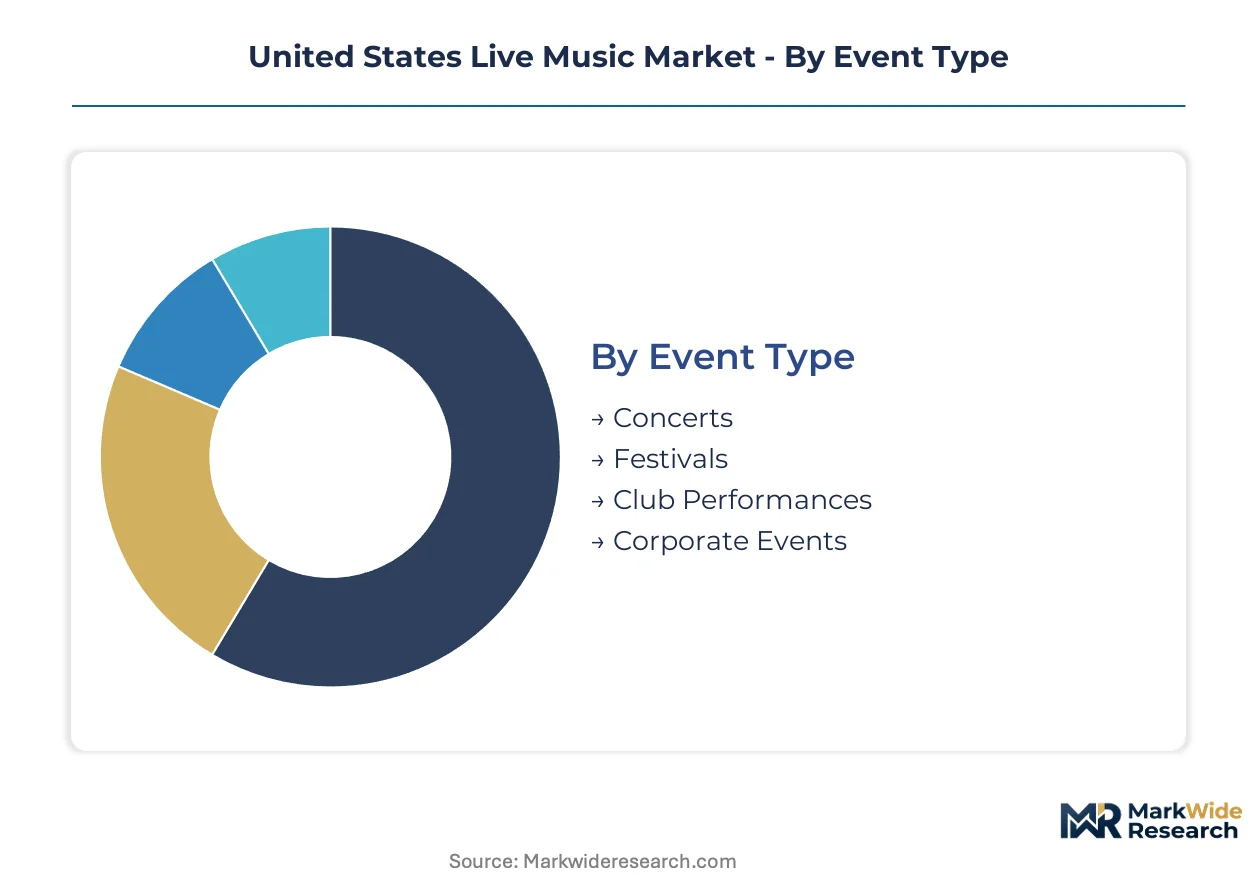
Segmentation in the United States live music market reveals how capital allocation, pricing power, and audience targeting diverge across production formats. Venue operators and promoters calibrate infrastructure investments against per-attendee revenue potential within each category.
Event Type:
Capital intensity escalates dramatically from temporary club installations to permanent amphitheaters and multi-day festival grounds requiring engineered crowd-safety systems.
- Concerts:Single-night performances in dedicated venues demand calibrated acoustic engineering and load-bearing stage infrastructure designed for occupancy loads exceeding ten thousand attendees. Texas and Florida concentrate new venue construction as municipal permitting accelerates.
- Festivals:Multi-day temporary productions on dedicated grounds generate disproportionate per-attendee ancillary spend through camping, food, and merchandise programming. Tennessee authorities are streamlining temporary event licensing, compressing lead times for large-scale outdoor productions.
- Club Performances:Intimate venues under five hundred capacity require minimal permanent infrastructure but face compressed margins from municipal noise ordinances.
- Corporate Events:B2B buyers redirect budgets from digital channels to experiential formats, creating sustained demand for mid-size amphitheaters and private festival activations.
Concerts absorb the bulk of installed capacity; Corporate Events is expanding most quickly.
Ticket Pricing:
Margin pools concentrate at price extremes while economy tiers expand total addressable audience through volume-driven accessibility.
- Premium:Tiered seating with dedicated amenities and exclusive access commands substantial price premiums over standard configurations. Spatial audio and holographic display arrays in California amphitheaters justify forty-to-sixty percent uplifts.
- VIP:Backstage access, artist meet-and-greets, and complimentary hospitality packages target corporate procurement teams with centralized experiential budgets.
- Standard:General admission and reserved seating constitute the volume base for most venue operators.
- Economy:Reduced-friction entry pricing expands audience reach for emerging artists and secondary market venues.
Premium captures the deepest margin per attendee; VIP is climbing the fastest as corporate buyers consolidate multi-year venue partnerships.
Audience Demographics:
Programming decisions track generational spending patterns and platform-native consumption habits across streaming and social channels.
- Gen Z:Digital-native audiences discover artists through short-form video platforms and demand immersive audiovisual production values. Festival promoters in Colorado deploy drone light shows above grounds to differentiate premium-tier ticket packages.
- Millennials:Established discretionary spenders drive demand for nostalgia programming and premium hospitality experiences in major metropolitan markets.
- Families:All-ages programming with enhanced safety protocols and daytime scheduling expands addressable occasion types.
- Seniors:Seated amphitheater configurations with ADA-compliant access infrastructure attract audiences prioritizing comfort and acoustic clarity.
Millennials retain the largest aggregate spending footprint; Gen Z is gaining share fastest through platform-driven discovery mechanics.
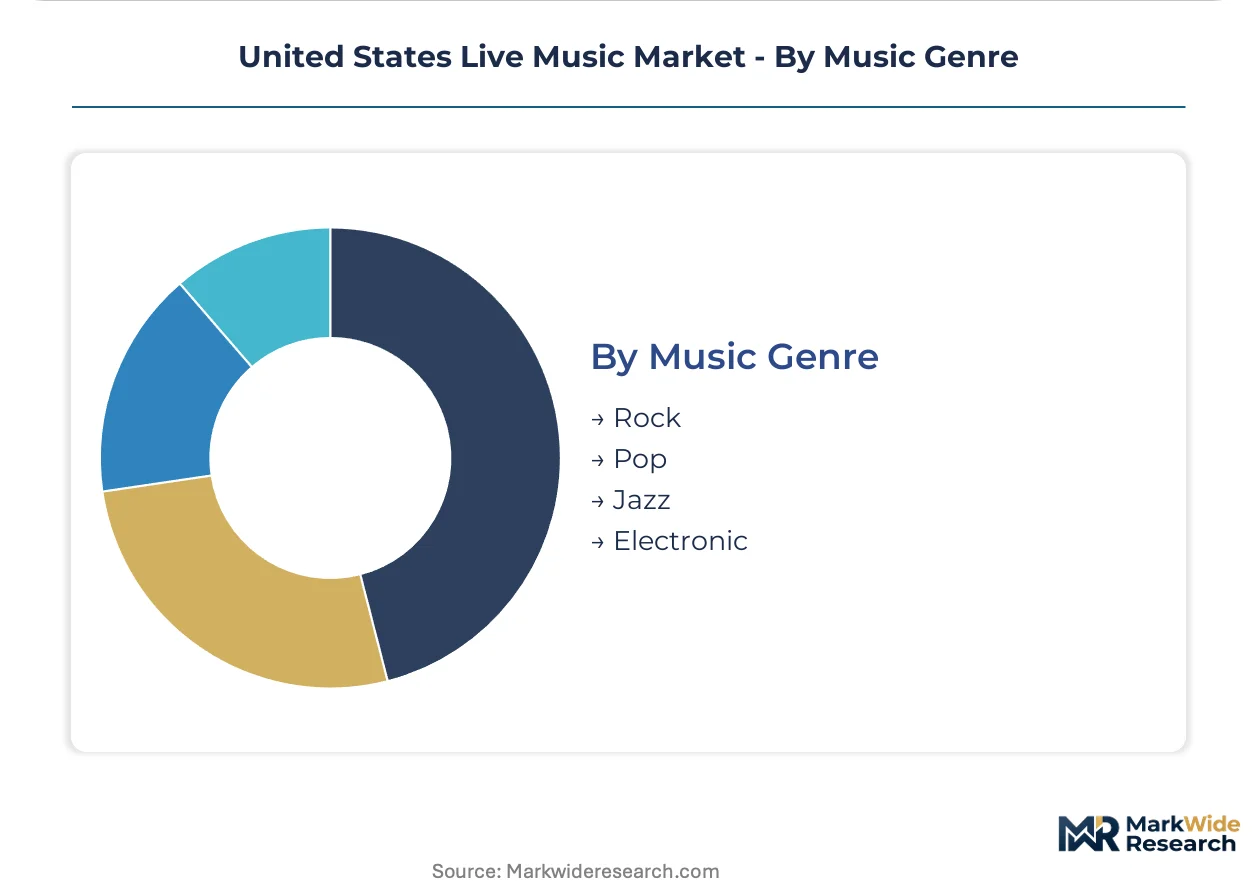
Music Genre:
Production requirements vary substantially across acoustic instrumentation, electronic amplification, and hybrid live-digital performance systems.
- Pop:Elaborate staging with synchronized visual elements and choreographed production demands the highest capital deployment per tour stop. The Inflation Reduction Act's clean energy incentives are decoupling carbon-intensive touring from growth strategies across major pop productions.
- Rock:Traditional backline configurations with substantial power amplification require specialized electrical infrastructure and load-bearing rigging systems.
- Electronic:DJ and live electronic performances prioritize spatial audio deployment and visual production over traditional stagecraft, reducing crew footprint while intensifying technology spend.
- Jazz:Acoustic-centric programming in dedicated clubs and theater venues commands premium pricing through intimacy and heritage positioning.
Pop commands the largest production budgets; Electronic is expanding most quickly through festival programming and immersive venue installations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Austin anchors live music infrastructure development as municipal authorities streamline festival permitting and venue construction timelines across Central Texas corridors.
Texas
Houston and Dallas-Fort Worth metroplexes concentrate new amphitheater construction as corporate event buyers expand experiential programming budgets. FAA regulations govern drone light shows above outdoor festival grounds in Austin's secondary markets. San Antonio's River Walk corridor attracts mid-size venue operators targeting family demographic programming with daytime scheduling flexibility.
Florida
Miami and Orlando metro areas drive festival permit acceleration as temporary event licensing compresses lead times for large-scale outdoor productions. The Inflation Reduction Act's clean energy incentives motivate venue operators in Tampa Bay to retrofit facilities for tax credit capture. Jacksonville's emerging market status presents greenfield development potential for arena-scale public-private partnerships.
Tennessee
Nashville's Music Row cluster sustains specialized stage construction crew concentration for peak summer touring season demand. OSHA standards enforce fall protection protocols during load-in operations at Ryman Auditorium and Ascend Amphitheater. Memphis exhibits per-capita venue capacity deficits relative to comparable metro populations, attracting development interest from regional promoters.
California
Los Angeles and San Francisco Bay Area markets deploy spatial audio and holographic display arrays to justify premium ticket pricing tiers. Municipal noise ordinances in San Diego constrain scheduling flexibility for outdoor amphitheaters along coastal zones. Sacramento's secondary market position benefits from proximity touring route economics between Pacific Northwest and Southwest corridors.
Colorado
Denver's Red Rocks Amphitheatre anchors immersive audiovisual technology integration as drone light shows differentiate premium-tier festival packages. State-level alcohol beverage control board licensing shapes on-site revenue models for multi-day camping productions. Boulder and Fort Collins satellite markets expand addressable occasion types through all-ages programming with enhanced safety protocols.
United States Live Music Market Competitive Landscape
Premium-margin players sit above commodity-margin players across venue ownership and promotion control dimensions. The United States live music sector exhibits consolidated structure at the top tier with fragmented independent operators occupying mid-market and club-scale segments. Three strategic archetypes dominate: vertically integrated ticketing-promotion-venue platforms, specialized arena developers with municipal financing expertise, and legacy entertainment conglomerates with media distribution synergies. Dominant competitive moves include venue portfolio expansion through public-private partnerships and backward integration into proprietary ticketing infrastructure.
Within the vertically integrated tier, Live Nation Entertainment and AEG exemplify platform-scale operators with balance sheet capacity for technology-intensive venue upgrades. Oak View Group represents the specialized development archetype through its municipal financing models in mid-tier markets. MSG Entertainment Holdings anchors legacy position through iconic venue ownership in major metropolitan corridors. These three entities collectively illustrate how capital intensity consolidates strategic decision-making among multi-venue operators while independent promoters face margin compression from ticketing control asymmetries.
| Leading Market Players |
|---|
| MSG Entertainment Holdings |
| Oak View Group |
| Live Nation Entertainment |
| LiveStyle |
| Endeavor Group Holdings |
| AEG |
| Liberty Media Corporation |
| Goldenvoice |
| Madison Square Garden Entertainment |
| Others |
Pricing and Supply Chain Analysis
Live Nation Entertainment's vertical control over ticketing, promotion, and venue operations anchors both supply positioning and pricing power across the United States live music value chain. This integration pattern compresses margins for independent promoters while concentrating margin capture at premium ticket tiers through proprietary infrastructure.
Pricing Analysis
Experience-based pricing anchors ticket structures to production value and exclusivity rather than commodity seating. Premium amphitheaters in California and Colorado deploy spatial audio and holographic arrays to justify forty-to-sixty percent uplifts over standard configurations. Corporate buyers with centralized experiential budgets exhibit lowest price sensitivity, while economy-tier audiences in secondary markets face compressed margins from municipal noise ordinance constraints.
Supply Chain Analysis
Dual-sourcing requirements for specialized rigging and load-bearing crews mandate multi-supplier qualification across Las Vegas, Nashville, and Los Angeles clusters. Stage construction draws from certified personnel pools in these hubs, with temporary structures resting on engineered anchor systems and OSHA-compliant fall protection. Single-source vulnerability concentrates in peak summer touring season, while distribution runs through venue-operator-controlled procurement channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The United States live music market reads as supply-constrained, with specialized acoustic engineering talent scarcity propping pricing power at premium production tiers.
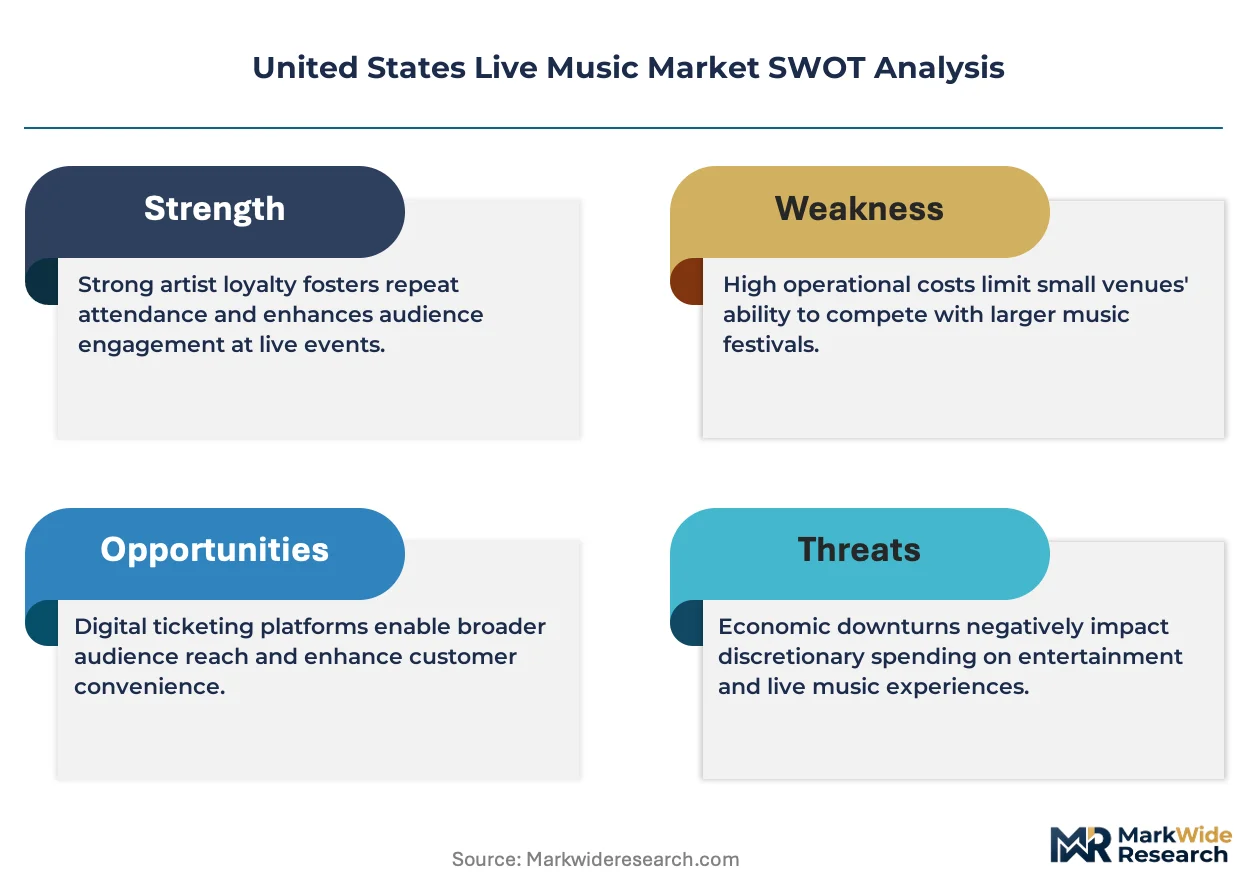
For Market Incumbents: Deepen venue ownership in Texas and Florida growth corridors to defend against Oak View Group's municipal financing encroachment. Expand backward integration into proprietary ticketing infrastructure to capture margin pools currently leaking to third-party platforms. Prioritize ADA compliance retrofitting ahead of Department of Justice enforcement waves in Northeast legacy venues. For New Entrants and Emerging Players: Begin with Boise, Des Moines, and Little Rock where per-capita venue capacity deficits relative to comparable metro populations create greenfield development potential. Target family demographic programming with daytime scheduling flexibility in San Antonio River Walk corridors. Deploy drone light show capabilities as FAA Part 107 waivers expand to differentiate premium-tier festival packages. For Investors and Strategic Acquirers: Exit pathways concentrate in specialized arena developers with municipal financing expertise and proven public-private partnership track records. Long-term viability hinges on balance sheet capacity for technology-intensive venue upgrades across the coming decade. Watch for inflection in corporate procurement consolidation toward multi-year venue partnership agreements displacing transactional ticket purchasing.| Strategic Initiative | Industry Significance |
|---|---|
| Venue Portfolio Expansion | Live Nation Entertainment captures margin pools through proprietary ticketing infrastructure in high-growth Texas and Florida markets. |
| Public-Private Partnership | Oak View Group's municipal financing models in Milwaukee and Seattle demonstrate replicable taxpayer-subsidized construction structures. |
| Technology Integration | Spatial audio and holographic display deployment in California amphitheaters justifies premium pricing tiers through production differentiation. |
| ADA Compliance Retrofit | Department of Justice accessibility enforcement imposes six-figure renovation requirements on pre-1990 legacy venues. |
| Drone Performance Capability | FAA Part 107 waiver expansion enables synchronized light shows above festival grounds for premium ticket packaging. |
Research Methodology
SEC filings, FAA regulatory databases, and municipal permitting records formed the secondary backbone for this United States live music market analysis. Primary interviews with venue operations directors, festival promoters, corporate event procurement managers, and specialized stage construction crew supervisors combined with secondary validation. Bottom-up venue capacity modeling and top-down industry revenue triangulation anchored segmentation outputs across event type, ticket pricing tier, and regional market clusters.
Historical trendline analysis of venue construction permits and festival licensing velocity informed projection frameworks across the analysis window. Segmentation dimensions modeled include event format, pricing tier, audience demographic cohort, and music genre production requirements. CAGRs derived from installed capacity expansion rates, corporate experiential budget reallocation patterns, and clean energy incentive capture assumptions under the Inflation Reduction Act.
Underlying measurement precision varies by segment; Texas and Florida venue construction data carry tighter precision than emerging secondary market estimates. Forecasts reflect assumptions around municipal noise ordinance enforcement consistency and FAA drone waiver expansion timelines. Deviation in Department of Justice ADA enforcement intensity or specialized rigging crew availability would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Music
Music Synthesizers Market
Music
Global Background Music Market
Music
Vinyl Records Market
Music
Electronic Dance Music (EDM) Market
Music
Virtual Musical Instruments Market
Music
Global Stock Music Market
Music
Music Distribution Services Market
Music
Music Publishing Market
Music
Traditional Music Market
Music
Traditional Chinese Instruments Market
Music
Music Production Software Market
Music
Europe Independent Artist Market
Music
Musical Groups and Artists Market
Music
Global Free Music Making Software Market
Music
Asia-Pacific Independent Artist Market
Music
Discography Market