
 Subscription Background Music Service Market | 2026-2036
Subscription Background Music Service Market Size, Share, and Industry Trends Forecast 2026-2036
Subscription Background Music Service Market Insights
Capital-intensity divergence between cloud-native platforms and legacy hardware-dependent providers is bifurcating competitive dynamics across the sector. Soundtrack Your Brand leverages pure software architecture to sustain lower deployment costs for mid-market retail chains. Mood Media anchors its position through integrated audiovisual systems that dominate physical-dominant venues such as hotels and large-format stores. Cloud Cover Music competes on API-first customization tools that extend developer ecosystems for enterprise clients.
Subscription background music services deliver licensed audio content through internet-connected streaming infrastructure to commercial environments, with technical specifications encompassing adaptive bitrate delivery, zone-based audio routing, and real-time playlist curation algorithms designed to comply with performing rights organization mandates. The primary commercial purpose involves creating controlled sonic environments that influence customer dwell time, purchase behavior, and brand recall in physical spaces. Streaming services occupy the largest revenue pool given recurring revenue predictability, while catalog access arrangements represent the fastest-expanding segment as rights holders pursue direct commercial licensing relationships. End-user concentration in restaurants and hotels generates premium margin opportunities due to high-ambience sensitivity and operational scale.
FCC broadband infrastructure standards in the United States influence streaming reliability requirements for commercial deployments, while EU Copyright Directive provisions administered by national collective management organizations reshape royalty collection mechanisms across European member states. GDPR compliance obligations affect customer data handling for personalization algorithms in European operations. Stakeholders must monitor evolving performing rights frameworks and network resilience benchmarks as determinants of service differentiation and geographic expansion feasibility.
Market Dynamics
Cloud-native streaming infrastructure is compressing deployment timelines and eroding the installed base of satellite-fed hardware systems across commercial music distribution. This architectural shift is forcing legacy providers to accelerate software transitions while opening margin advantages for pure-play SaaS operators.
Growth Catalysts
- FCC broadband infrastructure standards:United States commercial venues now mandate resilient internet connectivity, creating baseline conditions for streaming-first music services to replace legacy satellite hardware without redundancy concerns.
- Restaurant chain standardization:Multi-location franchise operators in the United States consolidate vendor relationships, driving volume commitments that subsidize platform development costs and accelerate feature roadmaps.
- EU Copyright Directive obligations:Extended licensing mandates across European member states are legitimizing commercial streaming usage, reducing legal ambiguity that previously constrained adoption in hospitality sectors.
Market Restraints
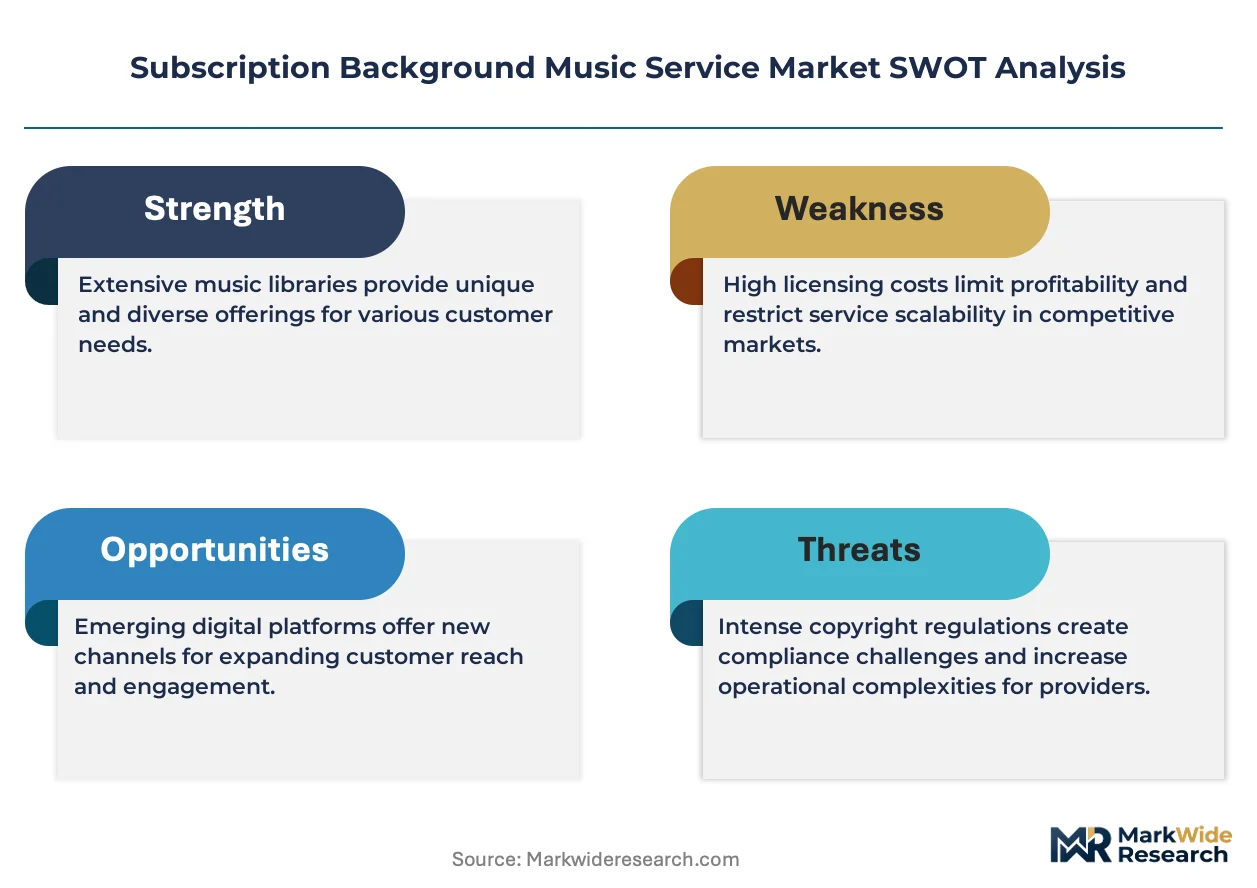
- Performing rights royalty escalation:Collective management organizations in France and Germany are extracting higher per-stream rates from commercial users, compressing gross margins for platform operators.
- Last-mile connectivity dependency:Rural and ex-urban retail locations in the United States face inconsistent broadband penetration, limiting addressable market expansion beyond metropolitan corridors.
- Catalog exclusivity fragmentation:Major rights holders are withholding content from non-exclusive distributors, forcing platforms to overpay for parity coverage or accept content gaps.
Strategic Opportunities
- India commercial hospitality expansion:Organized retail and quick-service restaurant chains in Mumbai and Bangalore remain underpenetrated by licensed streaming, presenting first-mover advantages for compliant entrants.
- API-first enterprise integration:Developer ecosystems enabling real-time audio-environment synchronization with point-of-sale and customer-analytics systems are creating stickiness in large-format retail.
- GDPR-compliant personalization:European venues are demanding algorithmic playlist curation that operates within strict data-handling frameworks, rewarding platforms with privacy-by-design architectures.
Industry Challenges
- Audio-engineering talent scarcity:Platforms struggle to hire specialists capable of optimizing adaptive bitrate delivery across heterogeneous commercial sound systems.
- Legacy hardware integration friction:Enterprises with sunk investments in proprietary amplification infrastructure face costly retrofitting to achieve streaming compatibility.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Subscription Background Music Service Market |
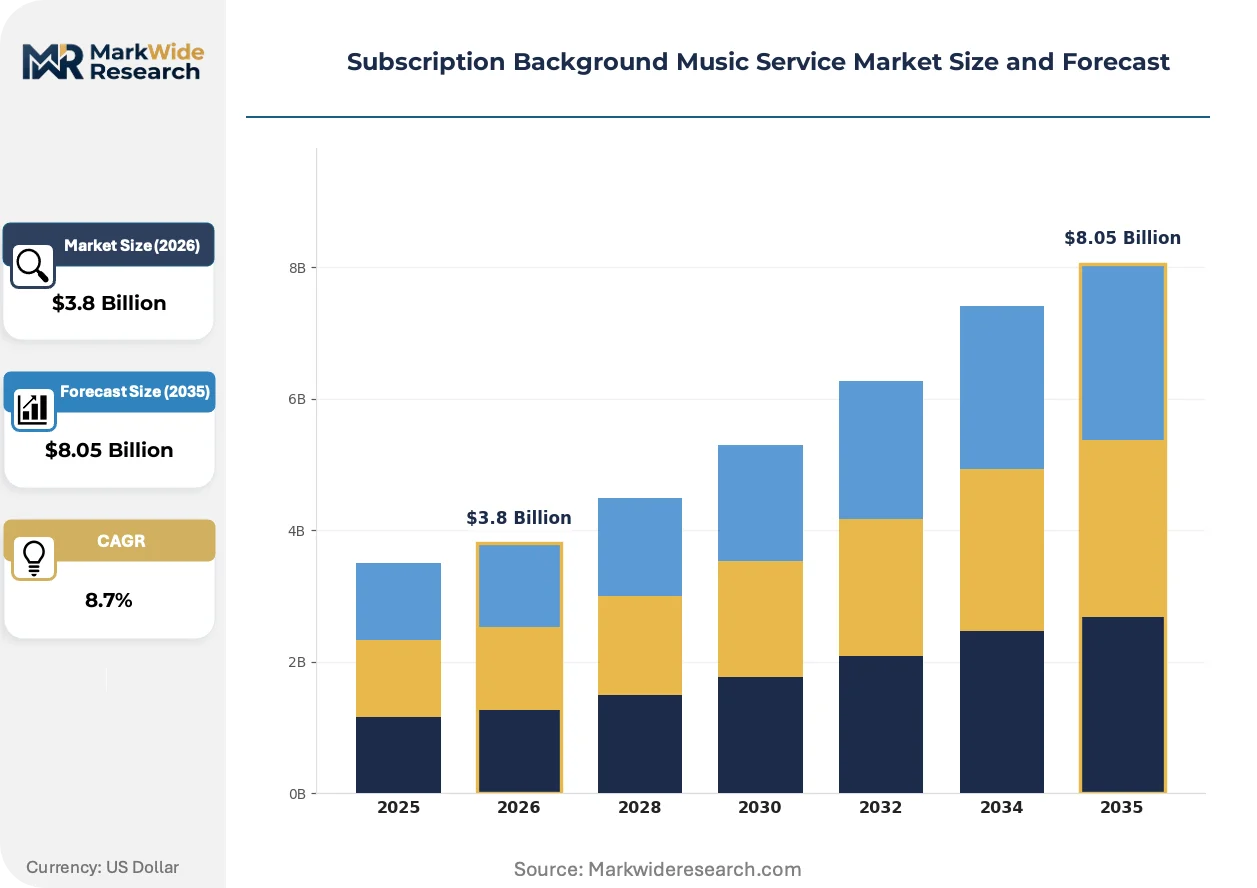
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.05 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Streaming, Licensing, Customization, Catalog Access End User: Retail Stores, Restaurants, Events, Hotels Distribution Channel: Online, Direct Sales, Partnerships, Affiliates Content Type: Instrumental, Genre-Based, Seasonal, Curated Playlists |
| Companies Covered | SoundMachine, Soundtrack Your Brand, Cloud Cover Music, Mood Media, Rockbot, SiriusXM Music for Business, Imagesound, Custom Channels, Soundtrack, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Subscription Background Music Service Market Trends and Innovations
Algorithmic curation engines are replacing human-programmed playlists as the primary value proposition, with machine-learning models now dictating competitive differentiation in commercial music services. This automation shift is compressing operational costs while raising technical barriers to entry.
Edge-computing audio processors are supplanting centralized cloud rendering for latency-sensitive applications. Quick-service restaurants with drive-through operations in the United States are deploying local inference nodes to synchronize menu-board audio with real-time order status. This architecture is enabling sub-50-millisecond response times that cloud-only delivery cannot match.
The EU Copyright Directive's Article 17 implementation is forcing platforms to deploy content-recognition systems for rights-holder revenue sharing. German and French collective management organizations are auditing algorithmic transparency, compelling vendors to document matching accuracy rates. Hospitality operators in these markets are selecting providers based on compliance documentation depth rather than catalog breadth alone.
Enterprise procurement teams are consolidating music licensing with broader facilities-management contracts, unbundling standalone streaming subscriptions. Large-format retailers in the United States now source background audio through integrated workplace-experience vendors. This channel compression is marginalizing direct-sales relationships and elevating platform API documentation as a procurement evaluation criterion.
Subscription Background Music Service Market Segmentation
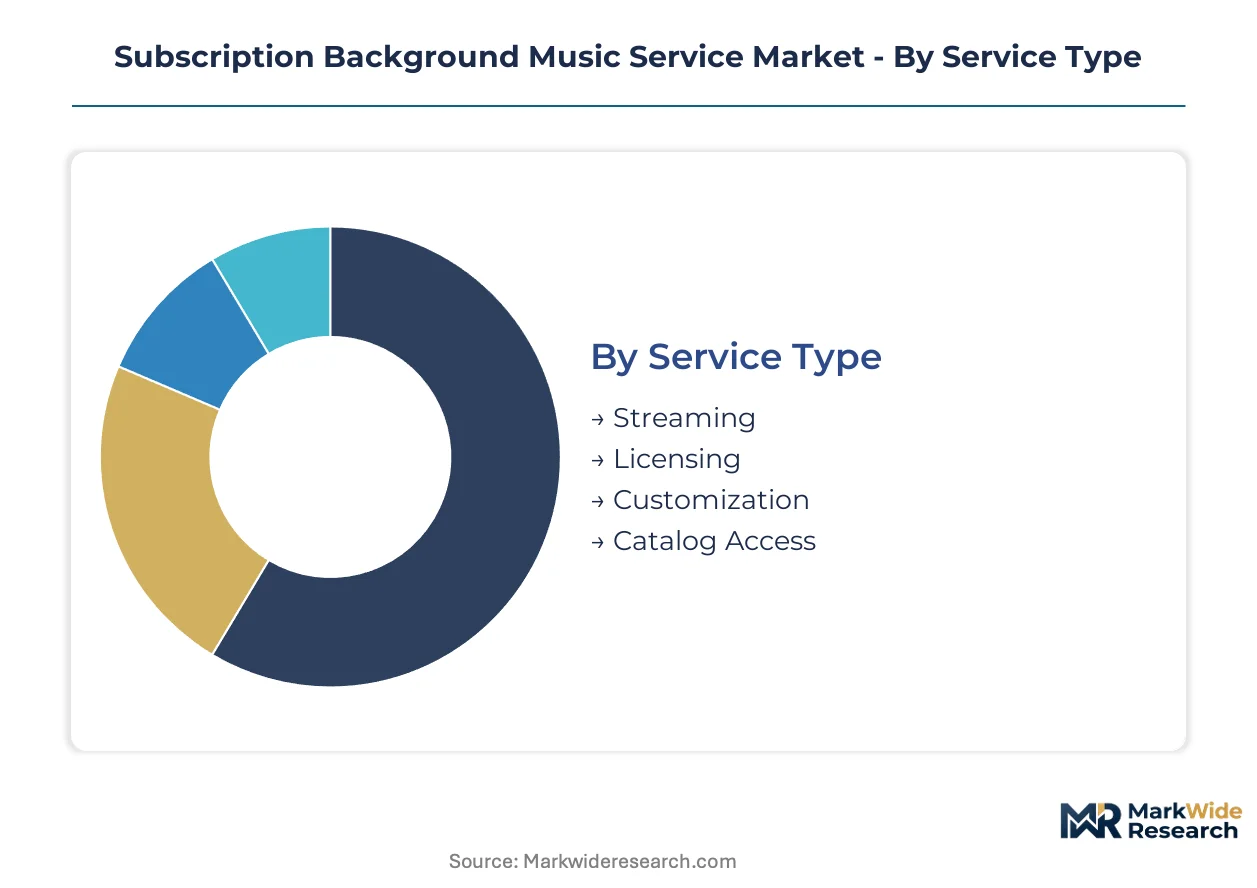
Commercial music platforms segment operations across service architecture, venue requirements, delivery mechanisms, and content formats. Each dimension carries distinct regulatory exposure and margin profiles that determine platform viability across geographic markets.
Service Type:
FCC broadband standards and EU Copyright Directive obligations create divergent compliance burdens that reshape competitive positioning across service models.
- Streaming:Cloud-native delivery with adaptive bitrate protocols dominates mid-market retail deployments. United States restaurant chains standardize on streaming-first architectures to eliminate satellite hardware redundancy and accelerate multi-location rollouts.
- Licensing:Direct rights-holder agreements bypass collective management organizations in high-royalty jurisdictions. French and German collective management organizations extract elevated per-stream rates, compressing margins for platforms dependent on statutory licensing frameworks.
- Customization:API-first toolsets enable real-time audio-environment synchronization with point-of-sale systems.
- Catalog Access:Rights holders pursue direct commercial relationships, fragmenting exclusive content availability across platforms.
Established volume favors Streaming; emerging adoption favors Catalog Access.
End User:
Operational scale and ambience sensitivity determine willingness to pay premium rates for compliant, curated audio environments.
- Restaurants:Quick-service and full-service operators demand zone-based audio routing for distinct dining areas. Franchise standardization across United States multi-location portfolios generates volume commitments that subsidize platform development investments.
- Hotels:Integrated audiovisual systems dominate large-format properties with heterogeneous spaces. GDPR-compliant personalization algorithms operate within strict European data-handling frameworks, rewarding privacy-by-design architectures.
- Retail Stores:Drive-through and in-store audio synchronization requires sub-50-millisecond latency.
- Events:Temporary deployments favor rapid-setup streaming configurations with minimal infrastructure.
Revenue concentration sits with Restaurants; margin expansion favors Hotels.
Distribution Channel:
Enterprise procurement consolidation is compressing standalone subscription channels into integrated facilities-management relationships.
- Direct Sales:Platform-controlled relationships retain margin but face displacement as large-format retailers source audio through workplace-experience vendors. United States procurement teams evaluate API documentation depth as a primary selection criterion.
- Partnerships:Integration with facilities-management contracts creates stickiness through bundled service delivery. Channel compression marginalizes standalone offerings while elevating technical documentation standards.
- Online:Self-service onboarding targets small and mid-market venues with standardized requirements.
- Affiliates:Referral networks extend reach into underpenetrated hospitality markets.
Margin protection favors Direct Sales; volume scaling favors Partnerships.
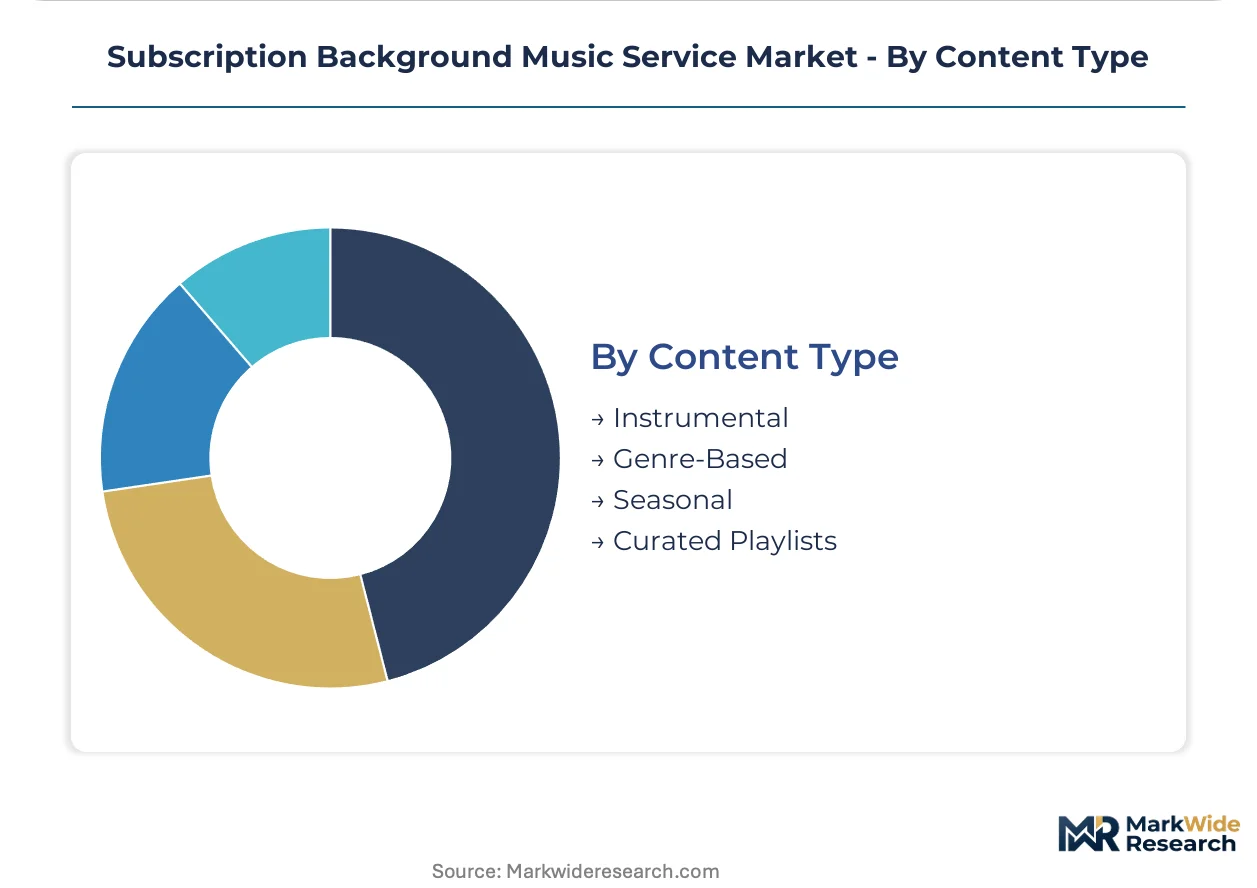
Content Type:
Algorithmic curation engines are displacing human-programmed playlists, with machine-learning models dictating competitive differentiation.
- Curated Playlists:Machine-learning models optimize for dwell time and purchase behavior in commercial environments. EU Copyright Directive Article 17 implementation compels content-recognition systems for rights-holder revenue sharing, with German and French regulators auditing algorithmic transparency.
- Genre-Based:Brand identity alignment through consistent sonic signatures dominates franchise operator requirements. Restaurant chains embed licensed streaming into standardized brand programs across North American and European portfolios.
- Instrumental:Lyrics-free delivery avoids language barriers and verbal distraction in service environments.
- Seasonal:Calendar-driven programming rotates automatically for holiday and promotional periods.
Technology leadership centers on Curated Playlists; brand standardization drives Genre-Based adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Commercial music streaming adoption varies sharply by geography, with United States franchise operators pursuing standardization while European venues navigate complex royalty frameworks and Asian markets confront infrastructure gaps.
United States
FCC broadband infrastructure standards mandate resilient connectivity for commercial deployments, enabling streaming-first architectures to displace satellite-fed legacy systems. Restaurant chains consolidate vendor relationships across multi-location portfolios, generating volume commitments that subsidize platform development. Quick-service operators in Texas and California deploy zone-based audio routing for drive-through synchronization.
Germany
GEMA and GVL collective management organizations extract elevated per-stream rates from commercial users, compressing margins for platforms dependent on statutory licensing. The EU Copyright Directive's Article 17 implementation compels content-recognition systems for transparent rights-holder revenue sharing. Hospitality clusters in Berlin and Munich select providers based on compliance documentation depth.
United Kingdom
PPL and PRS for Music administer dual licensing requirements that increase administrative burden for commercial streaming deployments. Franchise operators in London and Manchester embed licensed audio into standardized brand identity programs across retail and foodservice portfolios. GDPR-compliant personalization algorithms reward platforms with privacy-by-design architectures.
France
SACEM and SDRM collective management organizations pursue aggressive rate escalation for commercial background music usage. The EU Copyright Directive obliges platforms to document algorithmic transparency in content-matching systems. Hospitality venues in Paris and Lyon prioritize providers with demonstrated compliance infrastructure over catalog breadth alone.
India
Organized retail and quick-service restaurant chains in Mumbai and Bangalore remain underpenetrated by licensed streaming services, presenting first-mover advantages for compliant entrants. TRAI broadband penetration benchmarks lag metropolitan requirements, constraining streaming reliability in secondary cities. Hospitality operators in Delhi-NCR and Hyderabad demonstrate growing willingness to pay premium rates for rights-cleared audio environments.
Subscription Background Music Service Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with pure-play SaaS operators compressing deployment timelines while legacy hardware-dependent providers defend installed bases through audiovisual bundling. Cloud-native platforms exploit margin advantages from software-only architectures, forcing satellite-fed incumbents to accelerate digital transitions. Strategic archetypes include API-first developers, integrated facilities vendors, and catalog-exclusive rights aggregators. Competitive moves center on enterprise procurement consolidation and edge-computing audio processing for latency-sensitive applications.
Among cloud-native specialists, Soundtrack Your Brand and Cloud Cover Music exemplify the API-first archetype with developer-centric customization toolsets. Mood Media anchors the integrated tier, representing legacy providers pivoting toward software-defined delivery while retaining audiovisual system dominance in physical-dominant venues. These three entities collectively illustrate the capital-intensity divergence bifurcating sector dynamics.
| Leading Market Players |
|---|
| SoundMachine |
| Soundtrack Your Brand |
| Cloud Cover Music |
| Mood Media |
| Rockbot |
| SiriusXM Music for Business |
| Imagesound |
| Custom Channels |
| Soundtrack |
| Others |
Pricing and Supply Chain Analysis
Ninety-day content licensing cycles from performing rights organizations compress margin visibility for platform operators while amplifying pricing power for rights holders across North American and European markets. This inventory-like obligation structure forces streaming services to absorb royalty escalation or pass costs to price-sensitive mid-market retail chains.
Pricing Analysis
Long-term franchise offtake agreements dominate United States restaurant chain procurement, locking in volume-scaled rates that subsidize platform development while spot arrangements for independent venues face sharper per-location pricing. Three-tier pricing structure across premium API-integrated, standard streaming, and economy catalog-access levels differentiates by customization depth and zone-routing capability. Pricing pressure stems from GEMA and SACEM rate escalations in Germany and France, compressing gross margins for statutory-licensing-dependent operators. Mid-market retail chains exhibit highest price sensitivity, while luxury hotel portfolios accept premium tiers for integrated audiovisual bundling.
Supply Chain Analysis
The United States and Sweden anchor cloud-native platform development, while Ireland and Germany host content-recognition compliance engineering for EU Copyright Directive mandates. Raw material dependencies center on licensed audio catalogs from major rights holders, edge-computing audio processors for latency-sensitive drive-through deployments, and broadband infrastructure for reliable streaming delivery. Single-source vulnerability concentrates in exclusive catalog arrangements where withholding content fragments competitive parity. Distribution runs through direct enterprise sales teams for large-format retail and integrated facilities-management partnerships for hospitality portfolios.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform-economics inflection is accelerating as API-first developer ecosystems displace standalone subscription relationships, with enterprise procurement teams now evaluating technical documentation depth as a primary vendor selection criterion.
For Market Incumbents: Consolidate around edge-computing audio processing capabilities to defend against latency advantages held by cloud-native specialists in quick-service restaurant drive-through synchronization. Deepen backward integration into content-recognition compliance engineering to meet German and French regulatory audit requirements. Prioritize franchise offtake renewals before procurement consolidation shifts volume to integrated workplace-experience vendors.
For New Entrants and Emerging Players: Anchor in Mumbai and Bangalore hospitality clusters where organized retail and quick-service restaurant penetration remains underdeveloped for licensed streaming services. Target API-first integration partnerships with point-of-sale and customer-analytics platforms as the primary go-to-market angle, bypassing direct sales displacement in saturated United States metropolitan corridors.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across cloud-native SaaS architectures as satellite hardware dependencies erode, elevating pure-play software operators above legacy audiovisual bundling providers for long-term viability across a five-to-ten-year window. Prioritize acquisition targets with demonstrated GDPR-compliant personalization algorithms and documented EU Copyright Directive Article 17 transparency. Watch for inflection in enterprise procurement consolidation rates as the signal for platform margin compression acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| API-First Platform Integration | Developer ecosystems embedding audio-environment synchronization with POS systems create enterprise stickiness. |
| Edge-Computing Audio Deployment | Local inference nodes achieve sub-50-millisecond latency for drive-through menu-board synchronization. |
| GDPR-Compliant Personalization Buildout | Privacy-by-design architectures capture European hotel procurement evaluating algorithmic data handling. |
| Content-Recognition Compliance Investment | Transparent rights-holder revenue sharing systems satisfy German GEMA and French SACEM audit requirements. |
| Franchise Volume Offtake Expansion | Multi-location standardization commitments subsidize platform development across United States restaurant chains. |
Research Methodology
Initial hypotheses were tested against primary input from streaming platform engineering directors, restaurant chain procurement officers, hotel facilities managers, and performing rights organization licensing leads and refined through secondary validation. Bottom-up triangulation combined stakeholder interviews with regulatory filings from FCC broadband infrastructure proceedings, EU Copyright Directive national implementation texts, and collective management organization rate schedules. Top-down cross-checks incorporated SEC filings from publicly traded platform operators, trade data on commercial audio equipment imports, and hospitality sector capital expenditure disclosures.
Variance-decomposition framing isolated volume, price, and mix effects across the projection horizon. Segmentation dimensions modeled include service architecture, venue type, distribution channel, and content curation method alongside regional regulatory cluster differentiation. CAGRs were derived from iterative convergence of demand-side adoption curves and supply-side capacity expansion trajectories. Industry-specific forecast inputs encompassed franchise standardization rollout schedules and broadband penetration benchmarks from TRAI and FCC infrastructure reporting.
Material uncertainties — collective management organization rate litigation, catalog exclusivity fragmentation, and last-mile connectivity deployment delays — sit outside the modeled envelope. Forecasts reflect assumptions regarding regulatory stability and rights-holder negotiation postures that could shift with judicial reinterpretation of statutory licensing frameworks. Recalibration cycles align with material shifts in franchise procurement consolidation patterns and EU member state Article 17 implementation enforcement intensity.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Media and Entertainment
Social Media Advertisement Market
Media and Entertainment
Wedding Photography Market
Media and Entertainment
Asia-Pacific Arts Promoters Market
Media and Entertainment
Europe Gaming Peripherals Market
Media and Entertainment
India Event Services Market
Media and Entertainment
Microphone Market
Media and Entertainment
Big Data Pharmaceutical Advertising Market
Media and Entertainment
Digital Cinema Projectors Market
Media and Entertainment
Chile OOH and DOOH Market
Media and Entertainment
Latin America Mobile Gaming Market
Media and Entertainment
Sports Graphics Market
Media and Entertainment
Europe Location-Based Entertainment Market
Media and Entertainment
India Smart TV and OTT Market
Media and Entertainment
Curved Television Market
Media and Entertainment
Newspaper Market
Media and Entertainment
News and Magazines App Market