
 Music Production Software Market | 2026-2036
Music Production Software Market Size, Share, and Industry Trends Forecast 2026-2036
Music Production Software Market Outlook
CE marking for electromagnetic compatibility under EU Radio Equipment Directive 2014/53/EU is rotating as the gatekeeping standard for audio interface hardware bundled with production software suites. Ableton AG leverages its Berlin engineering base to sustain integrated hardware-software workflows. Avid Technology Inc. anchors professional post-production through Pro Tools dominance in film and television mixing stages. Apple Inc. competes via Logic Pro's tight silicon optimization across Mac, iPad, and iPhone ecosystems.
Music production software encompasses digital audio workstations, plugin architectures, virtual instrument engines, and mixing consoles that manipulate, record, edit, and synthesize sound through digital signal processing algorithms operating at sample rates typically between 44.1 kHz and 192 kHz with bit depths of 16 to 32 bits. Its primary commercial purpose is enabling professional-grade audio creation, post-production, and distribution across recorded music, broadcast, gaming, and live entertainment industries. DAWs occupy the largest revenue pool as the central production hub, while cloud-based deployment represents the fastest-expanding structural segment as subscription models displace perpetual licenses. Film scoring applications command premium pricing tiers due to orchestral sample library integration and surround format requirements.
FCC Part 15 regulations govern wireless MIDI and audio transmission protocols in US-sold production hardware, while EU REACH compliance restricts hazardous substances in circuit board manufacturing for bundled interfaces. Japan's METI enforces energy efficiency standards on powered studio monitors and audio processors sold with software bundles. Stakeholders must monitor how generative AI disclosure mandates from multiple jurisdictions reshape plugin development roadmaps and user agreement architectures.
Market Dynamics
Cloud-native digital audio workstations are collapsing the traditional hardware-software boundary, forcing vendors to rearchitect licensing models around real-time collaboration infrastructure rather than perpetual ownership.
Growth Catalysts
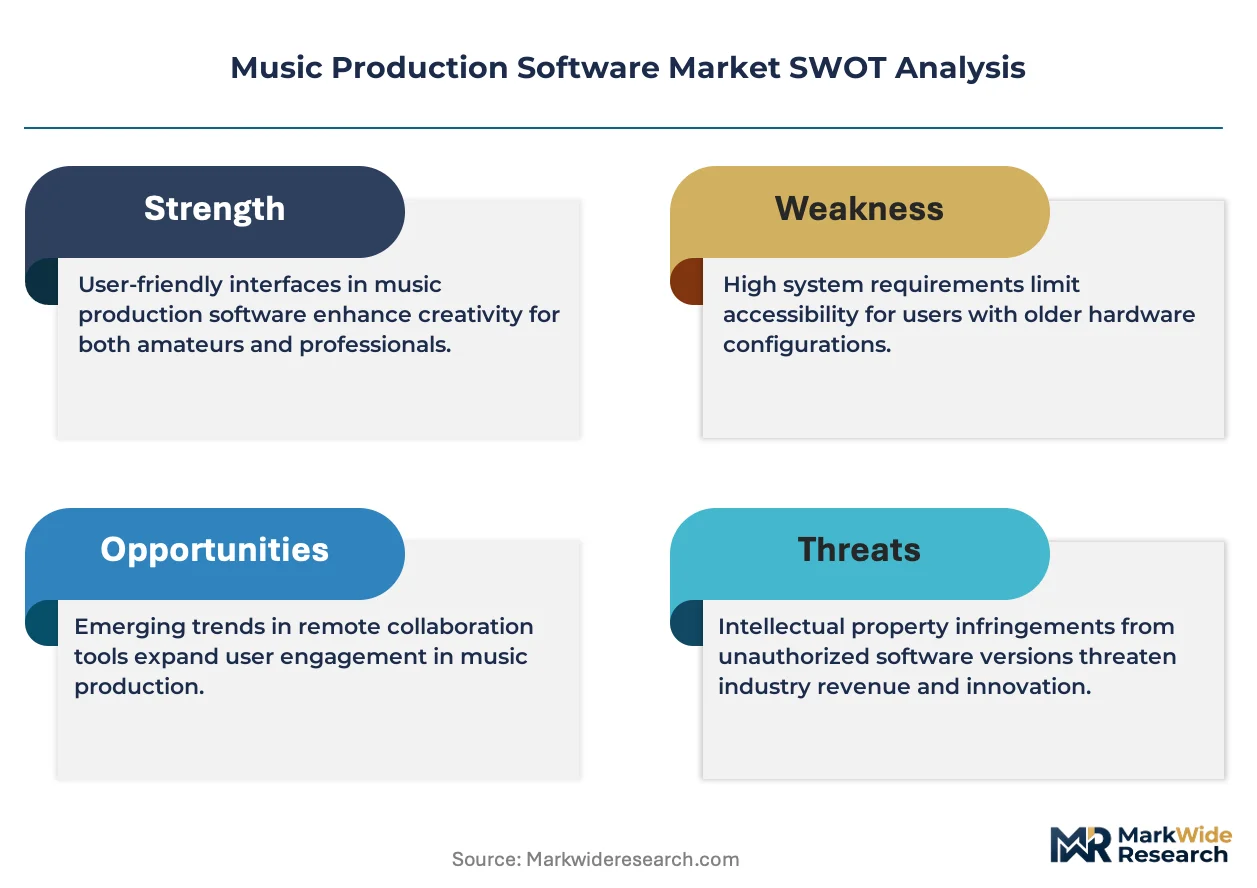
- EU AI Act transparency mandates:Generative audio plugin developers face disclosure requirements for training data provenance, creating compliance service demand from smaller studios.
- Independent music producers:Subscription pricing models lower capital barriers for bedroom producers, expanding the addressable user base beyond institutional buyers.
- Spatial audio formats:Dolby Atmos and Sony 360 Reality Audio adoption in streaming platforms drives surround-capable DAW upgrades across post-production facilities.
Market Restraints
- Silicon supply concentration:Taiwan-based foundries control advanced DSP chip fabrication, creating vulnerability for hardware-dependent software bundles.
- Perpetual license revenue collapse:Transition to recurring subscriptions compresses near-term cash flow for established vendors with large installed bases.
- Latency floor in browser-based processing:WebAssembly audio engines cannot match native DAW performance for professional tracking workflows.
Strategic Opportunities
- India educational institutions:Government-funded music technology programs in Mumbai and Bangalore lack standardized curriculum, creating white-space for bundled training-software offerings.
- Gaming audio middleware convergence:Real-time synthesis engines from music production are migrating into interactive sound design for Unreal Engine and Unity environments.
- Japan METI energy efficiency labeling:Powered studio monitor certification creates differentiation avenue for bundled hardware-software packages targeting sustainability-conscious buyers.
Industry Challenges
- Generative training data licensing:Copyright ambiguity around AI models trained on commercial sample libraries generates legal exposure for plugin developers.
- Legacy project file migration:Decades of proprietary DAW formats create friction for users attempting cross-platform collaboration.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Music Production Software Market |
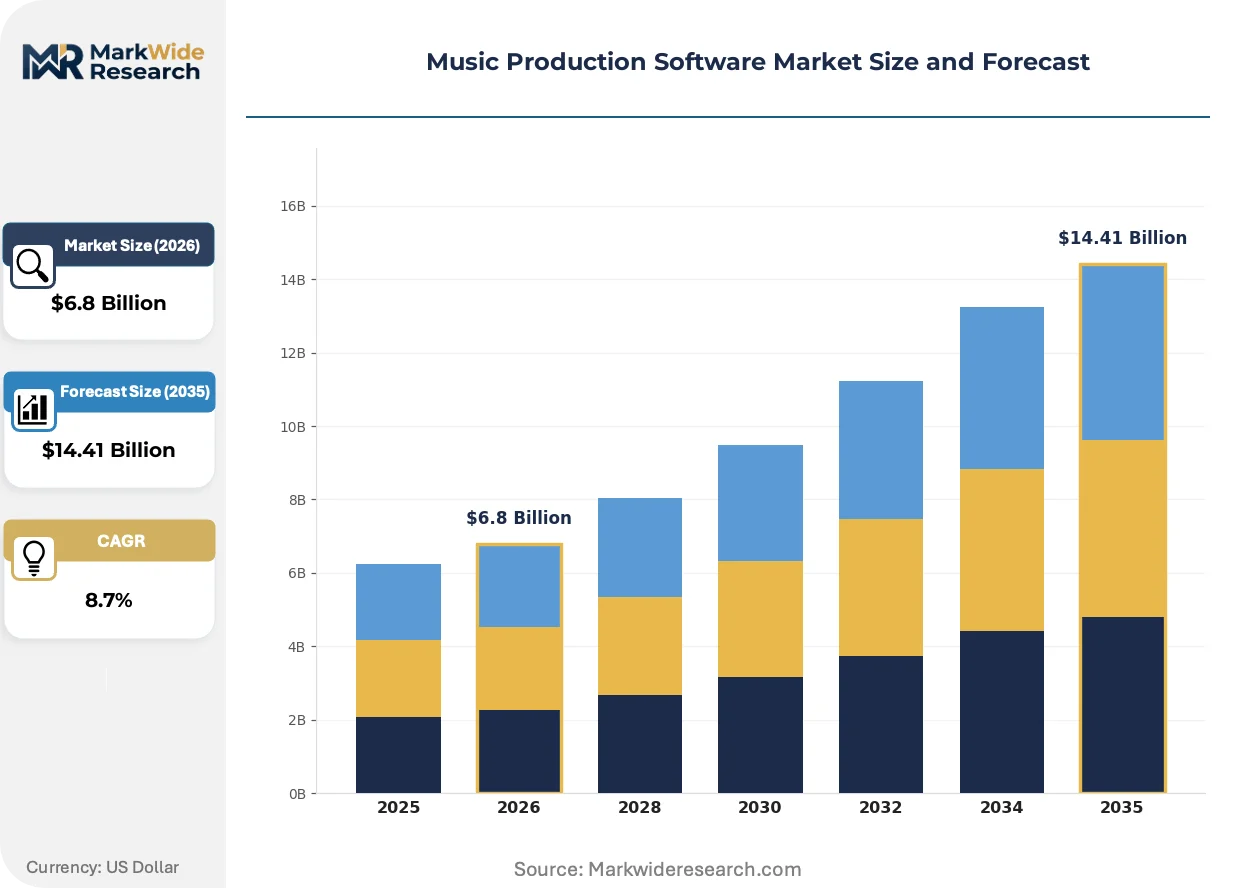
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $14.41 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: DAWs, Plugins, Virtual Instruments, Mixers End User: Producers, Musicians, Sound Engineers, Educators Application: Film Scoring, Music Composition, Podcasting, Live Performance Deployment: On-Premises, Cloud-Based, Hybrid, Mobile |
| Companies Covered | Ableton AG, Avid Technology Inc., Apple Inc., Steinberg Media Technologies GmbH, Image Line Software NV, PreSonus Audio Electronics Inc., Reason Studios AB, Bitwig GmbH, Cockos Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Music Production Software Market Strategic Shifts
Audio production infrastructure is fragmenting between browser-based accessibility and silicon-optimized performance, with neither pole fully displacing the other.
Neural audio synthesis is bifurcating the sample library market. Generative models from Google's Magenta and open-source alternatives now render instrument articulations on demand. Bedroom producers adopt these tools for cost efficiency, while orchestral composers retain premium sample libraries for timbral authenticity. The technology is bifurcating vendor strategies between democratized access and premium fidelity tiers.
EU REACH substance restrictions are reshaping hardware bundling strategies. Restrictions on lead and cadmium in circuit board manufacturing force audio interface redesigns for European market entry. Vendors with integrated hardware-software workflows absorb compliance costs internally, while pure-play software companies face partner certification delays.
Educational licensing is displacing individual seat sales in institutional procurement. Universities in the United States negotiate site-wide DAW access through consortium purchasing agreements. This concentrates buying power among procurement officers rather than department heads, compressing price realization per student. The shift is most visible in Los Angeles and Nashville, where accredited audio engineering programs anchor vendor relationship investments.
Music Production Software Market Segmentation
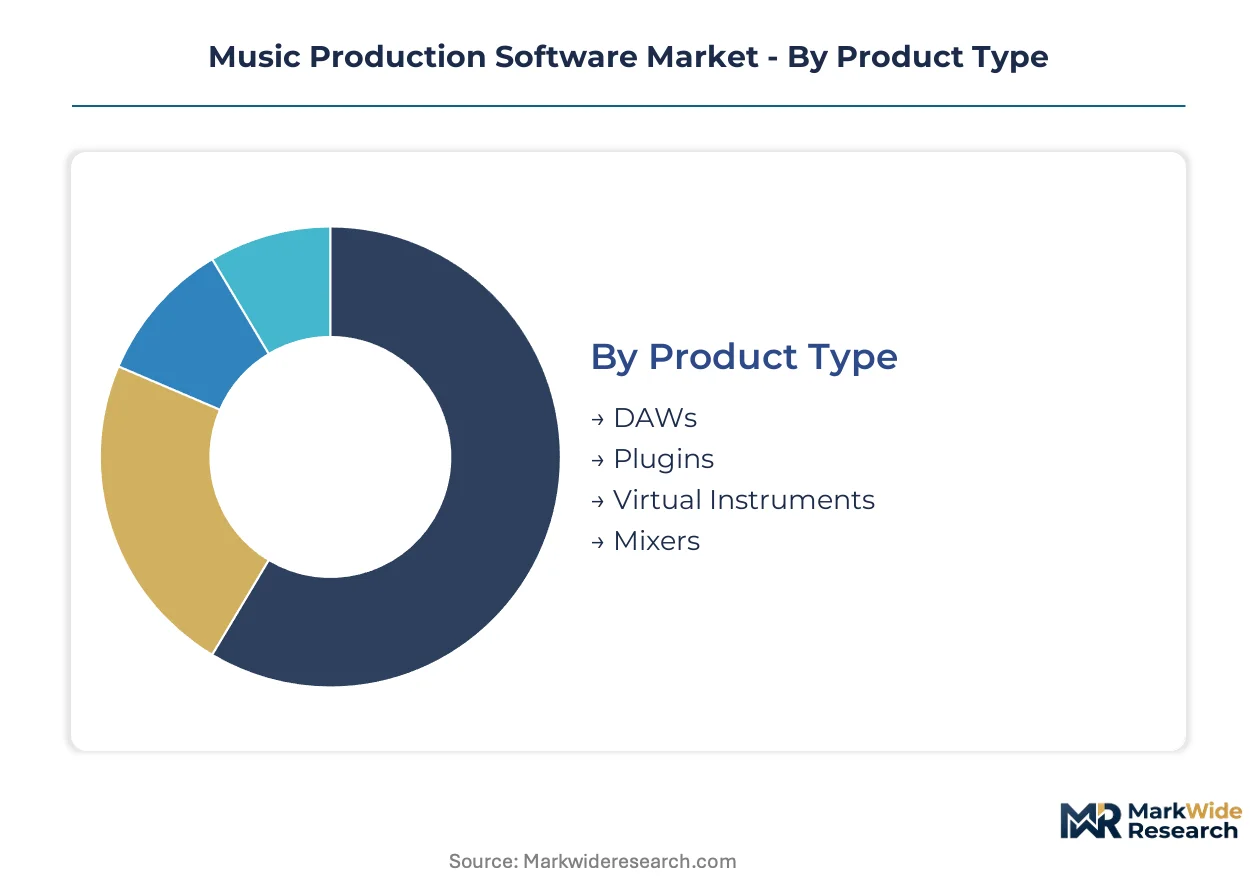
Segmentation in music production software reveals how substitute technologies pressure different product tiers. Cloud-based collaboration tools threaten perpetual-license DAWs, while generative AI plugins displace traditional sample libraries. Understanding these substitution dynamics guides vendor resource allocation across diverging user needs.
Product Type:
DAWs face the most intense substitution pressure from browser-based alternatives, while hardware-integrated bundles resist displacement through ecosystem lock-in.
- DAWs:Central production environments integrating multitrack recording, MIDI sequencing, and mixing at sample rates up to 192 kHz. Professional studios in Los Angeles and Nashville drive demand for surround-capable systems as streaming platforms mandate spatial audio delivery. Subscription pricing is compressing perpetual-license revenue for established vendors.
- Plugins:Modular signal processors including EQ, compression, and reverb algorithms operating as VST/AU/AAX architectures. Bedroom producers in the United States adopt AI-powered generative plugins to bypass expensive sample library procurement. EU AI Act transparency mandates are forcing training-data disclosure in new releases.
- Virtual Instruments:Synthesizer and sampler engines rendering acoustic and electronic timbres through physical modeling or wavetable synthesis.
- Mixers:Digital console software controlling gain staging, panning, and bus routing across multiple output formats.
DAWs anchor the volume base while plugins gain share at the steepest rate.
End User:
Cost tier differentiation separates institutional buyers with site-wide licensing power from individual creators financing subscriptions through project revenue.
- Producers:Independent creators and commercial studio operators managing full production workflows from tracking through mastering. Cloud-based subscription models in the United States have expanded this cohort beyond traditional institutional buyers. EU AI Act compliance costs disproportionately burden smaller studios lacking legal infrastructure.
- Sound Engineers:Technical specialists focused on mixing, mastering, and post-production for broadcast and theatrical release. Post-production facilities in Los Angeles drive demand for Dolby Atmos-capable systems as streaming platforms expand immersive audio catalogs. Latency requirements in professional tracking workflows resist browser-based DAW migration.
- Musicians:Performers using production tools for composition, practice, and demo creation.
- Educators:University and conservatory instructors procuring site-licensed software for classroom instruction.
Producers anchor the volume base while sound engineers command the highest per-seat pricing.
Application:
Application segmentation tracks how performance requirements diverge between real-time live use and non-realtime studio production.
- Music Composition:Original songwriting and arrangement workflows spanning electronic production to orchestral scoring. Composers in Nashville retain premium sample libraries for timbral authenticity while bedroom producers adopt neural synthesis for cost efficiency. Generative AI tools are bifurcating this segment between democratized access and premium fidelity tiers.
- Film Scoring:Synchronized music production for theatrical and streaming visual media requiring SMPTE timecode integration and surround format delivery. Professional facilities command premium pricing for orchestral sample library integration and Atmos mixing stages. Cloud collaboration features are reducing facility-based project concentration.
- Podcasting:Spoken-word production with emphasis on noise reduction, dialogue editing, and distribution integration.
- Live Performance:Real-time playback and effects processing for concert and event environments.
Music composition anchors the volume base while film scoring maintains the highest revenue per project.
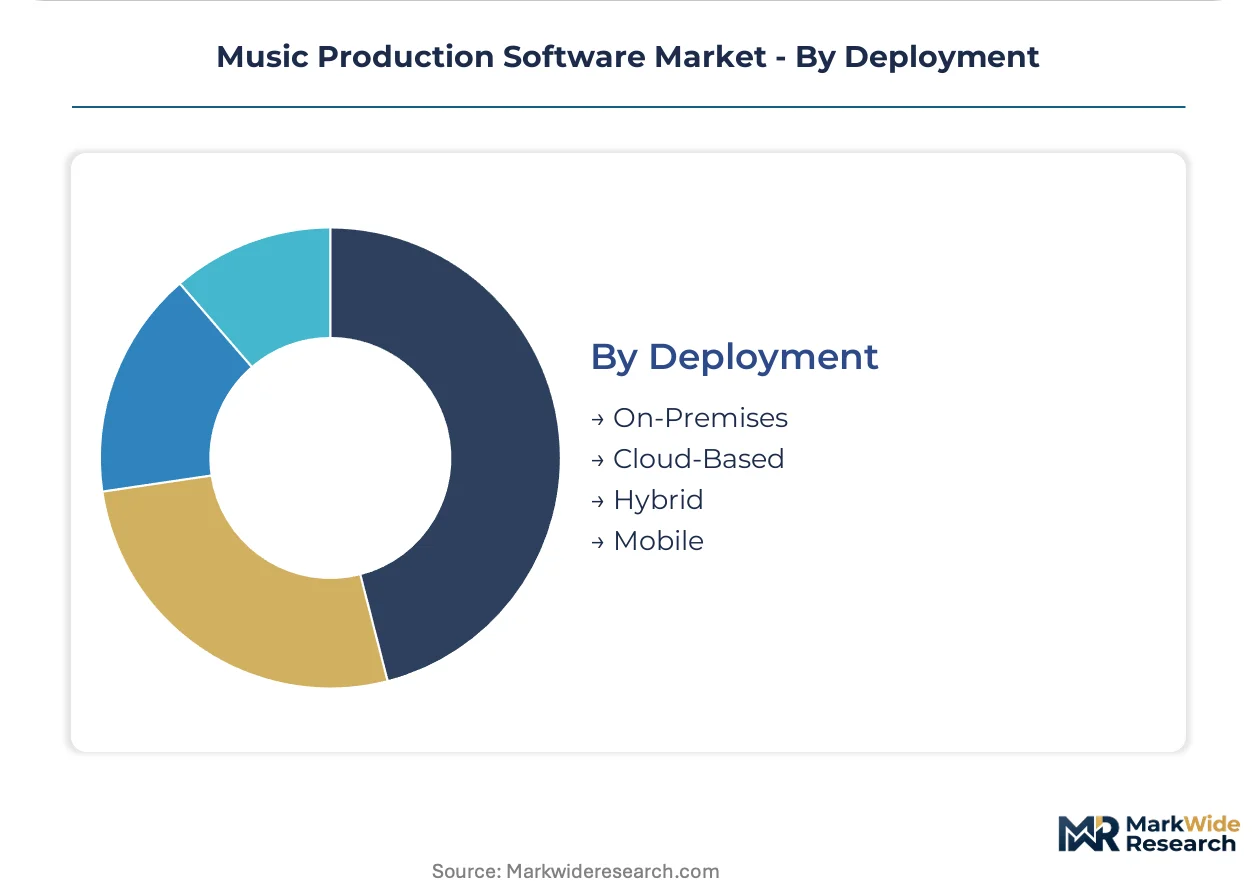
Deployment:
Customer type segmentation separates enterprise procurement officers negotiating site licenses from individual creators selecting personal tools.
- Cloud-Based:Browser-accessible or thin-client architectures enabling real-time collaboration and automatic feature updates. Independent producers across the United States drive adoption as subscription pricing eliminates upfront capital requirements. WebAssembly audio engines face latency floors that exclude professional tracking workflows.
- Mobile:Touch-optimized applications for iOS and Android tablets and smartphones extending production to field environments. Apple silicon optimization across iPad and iPhone ecosystems creates hardware-software integration advantages. Educational institutions in Los Angeles pilot mobile-first curricula for accessibility.
- On-Premises:Perpetually licensed software installed on local workstations with offline capability.
- Hybrid:Architectures combining local processing with cloud storage and collaboration features.
Cloud-based deployment is expanding most quickly while on-premises retains the largest installed base.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Government-funded music technology programs and regulatory transparency mandates are redirecting procurement patterns across major markets. Fiscal incentives for creative industries intersect with compliance costs from emerging AI disclosure frameworks.
United States
Nashville, Los Angeles, and New York anchor professional studio density and educational institution procurement. FCC Part 15 regulations govern wireless MIDI and audio transmission protocols in production hardware. Post-production facilities in Los Angeles drive demand for Dolby Atmos-capable systems as streaming platforms expand immersive audio catalogs.
Germany
Berlin's engineering base sustains integrated hardware-software workflows for European market entry. EU REACH substance restrictions on lead and cadmium force audio interface redesigns for bundled hardware-software packages. The city's concentration of electronic music producers creates distinctive demand for real-time performance-optimized tools.
United Kingdom
London's post-production houses command premium pricing tiers for film scoring applications requiring orchestral sample library integration. The EU AI Act's transparency requirements for generative audio tools reshape vendor compliance obligations for UK-based plugin developers. Educational institutions negotiate site-wide DAW access through consortium purchasing agreements.
Japan
METI energy efficiency standards on powered studio monitors and audio processors influence bundled package design. Tokyo's broadcast infrastructure drives demand for surround-format mixing stages. Sustainability-conscious buyers respond to certification-based differentiation in hardware-software offerings.
India
Government-funded music technology programs in Mumbai and Bangalore lack standardized curriculum, creating white-space for bundled training-software offerings. The country's national electronics regulator enforces electromagnetic compatibility for imported audio interfaces. Independent producers in metropolitan centers adopt cloud-based subscription models to bypass capital barriers.
Music Production Software Market Competitive Environment
Player mix skews toward integrated hardware-software specialists and pure-play DAW developers with divergent margin structures. Market structure exhibits tiered consolidation with a dominant professional post-production segment and fragmented entry-level creator tools. Strategic archetypes include silicon-optimized ecosystem vendors, cloud-native collaboration platforms, and modular plugin specialists. Competitive moves center on subscription model migration and generative AI feature integration.
Within the integrated hardware-software tier, Ableton AG and Steinberg Media Technologies GmbH exemplify European engineering-centric positioning. Avid Technology Inc. anchors professional post-production archetypes through film and television mixing stage dominance. Apple Inc. occupies a position defined by silicon optimization across computing ecosystems. These three entities represent divergent strategic vectors: Berlin-based workflow integration, professional facility concentration, and consumer-to-pro ecosystem bridging.
| Leading Market Players |
|---|
| Ableton AG |
| Avid Technology Inc. |
| Apple Inc. |
| Steinberg Media Technologies GmbH |
| Image Line Software NV |
| PreSonus Audio Electronics Inc. |
| Reason Studios AB |
| Bitwig GmbH |
| Cockos Inc. |
| Others |
Value Chain & Pricing Dynamics
Perpetual-to-subscription contract migrations lock in recurring revenue visibility while ceding upfront pricing power to vendor balance sheets across Berlin, Cupertino, and Los Angeles engineering centers. This structural shift concentrates buyer leverage among educational procurement officers negotiating site-wide DAW access while compressing margins for hardware-dependent bundles facing EU REACH compliance costs.
Pricing Analysis
Certification level (CE marking under EU Radio Equipment Directive 2014/53/EU) creates the primary spread between professional studio tiers and entry-level bedroom producer packages. Subscription SaaS-tiered models dominate deployment, with price differentiation resting on silicon optimization depth and spatial audio format support. Cost compression in cloud-native tiers intensifies as WebAssembly latency floors exclude professional tracking workflows from premium pricing. Independent producers exhibit highest price sensitivity; post-production facilities in Los Angeles command lowest sensitivity due to Atmos delivery mandates.
Supply Chain Analysis
Inbound logistics costs from Taiwan and South Korea fluctuate with container availability across Pacific trade lanes, directly affecting DSP chip procurement for audio interface manufacturing. Advanced semiconductor fabrication concentrates in Taiwan, with secondary sourcing from South Korea and Japan for analog converter components. Supply chain risk centers on single-source vulnerability for 7nm DSP fabrication. Distribution runs through direct-to-producer digital storefronts and educational consortium purchasing agreements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Browser-based DAW substitution threatens perpetual-license incumbents, forcing defensive repositioning around silicon-optimized performance moats and hardware-software ecosystem lock-in.
For Market Incumbents: Secure generative AI training data licensing frameworks ahead of EU AI Act enforcement to preempt legal exposure from plugin development. Anchor backward integration into Taiwan-based DSP supply chains through capacity reservation agreements, insulating hardware bundles from foundry allocation volatility. For New Entrants and Emerging Players: Anchor in India's government-funded music technology programs across Mumbai and Bangalore, where curriculum standardization gaps create white-space for bundled training-software offerings. Target cloud-native collaboration features for bedroom producers bypassing capital-intensive studio infrastructure. For Investors and Strategic Acquirers: Capital is best deployed toward modular plugin specialists with established VST/AU/AAX architectures and disclosed training-data provenance compliant with emerging transparency mandates. Monitor EU AI Act enforcement velocity as inflection indicator for generative audio plugin valuations.| Strategic Initiative | Industry Significance |
|---|---|
| Generative AI Compliance Investment | EU AI Act transparency mandates reshape plugin development roadmaps and user agreement architectures. |
| Silicon Optimization Deepening | Apple's ecosystem integration across Mac, iPad, and iPhone creates hardware-software performance differentiation. |
| Educational Licensing Expansion | Site-wide DAW access through Los Angeles and Nashville consortium purchasing concentrates procurement leverage. |
| Spatial Audio Format Adoption | Dolby Atmos capability drives premium pricing tiers in post-production facilities serving streaming platforms. |
| Cloud-Native Architecture Migration | Real-time collaboration infrastructure displaces perpetual ownership models among independent producers. |
Study Parameters
Cross-validation between primary interviews with DAW product managers, audio engineering educators, post-production facility technical directors, and plugin developers anchors the qualitative findings against secondary validation from SEC filings, App Annie mobile deployment data, hyperscaler cloud infrastructure disclosures, and EU regulatory transparency databases. Bottom-up demand modeling from individual producer cohorts triangulates with top-down market sizing from vendor revenue disclosures.
Sensitivity analysis across deployment model, end-user scale from bedroom producers to institutional facilities, application complexity from podcasting to orchestral film scoring, and regional regulatory adoption patterns structures the analytical framework. CAGRs derive from segment-level growth rate reconciliation against aggregate market expansion. Neural synthesis engine adoption curves and spatial audio format penetration serve as industry-specific forecast inputs across the projection horizon.
Decision-makers should treat outputs as directional under assumptions of sustained cloud subscription migration and stable Taiwan foundry capacity; material deviation in either would warrant model refresh. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Music
Electronic Dance Music (EDM) Market
Music
Global in-Store Music Service Market
Music
Virtual Musical Instruments Market
Music
Musical Groups and Artists Market
Music
Music Publishing Market
Music
Asia-Pacific Independent Artist Market
Music
Vinyl Records Market
Music
Global Free Music Making Software Market
Music
Traditional Chinese Instruments Market
Music
Music Distribution Services Market
Music
Global Stock Music Market
Music
Discography Market
Music
Global Background Music Market
Music
Europe Independent Artist Market
Music
Music Synthesizers Market
Music
United States Live Music Market