
 Global Customer Engagement Solutions Market | 2026-2036
Global Customer Engagement Solutions Market Size, Share, and Industry Trends Forecast 2026-2036
Global Customer Engagement Solutions Market Foresight
Enterprise buyer concentration is broadening from traditional Fortune 500 monoliths toward mid-market digital-native companies seeking modular engagement stacks. Salesforce.com Inc. leverages its CRM-centric ecosystem to anchor enterprise accounts across financial services and telecommunications verticals. Oracle Corporation sustains competitive positioning through deep database integration and on-premise migration pathways for regulated industries. SAP SE differentiates via ERP-embedded customer data unification that appeals to manufacturing and retail conglomerates.
Customer engagement solutions encompass software platforms that orchestrate multi-channel interactions through real-time data processing, API-driven connectivity, and AI-powered personalization engines designed to unify fragmented touchpoints into coherent customer journeys. These systems integrate behavioral analytics, natural language processing, and workflow automation to reduce churn and increase lifetime value across B2C and B2B relationships. Cloud-Based deployment models lead absolute spending as enterprises retire legacy on-premise contact center infrastructure, while Social Media Management tools represent the fastest-expanding solution category as brand-community interaction shifts from broadcast to conversational models. Banking & Financial Services occupies the deepest margin pool due to compliance complexity and high account values demanding secure, auditable engagement architectures.
The EU AI Act imposes strict algorithmic transparency requirements on automated customer interactions deployed across European markets, while GDPR continues to constrain cross-border data flows that underpin real-time personalization engines. The FCC in the United States enforces TCPA restrictions on outbound voice and SMS engagement that shape channel mix decisions for domestic campaigns. Stakeholders must monitor emerging interoperability mandates from ISO and IEC that will determine which platform architectures qualify for regulated industry procurement frameworks.
Market Dynamics
Cloud migration is compressing deployment cycles for customer engagement infrastructure as enterprises abandon decade-old contact center hardware. The EU AI Act's algorithmic transparency mandates are forcing architectural redesigns of automated interaction systems before vendors can serve European financial institutions.
Growth Catalysts
- GDPR-compliant data orchestration:Unified consent management platforms enable real-time personalization across EU member states without cross-border transfer violations.
- Telecommunications infrastructure modernization:5G network rollouts in Germany, South Korea, and the United States reduce latency for voice and video engagement channels.
- Conversational AI:Natural language processing engines trained on sector-specific corpora now handle tier-one support queries in retail banking and healthcare administration.
Market Restraints
- Skilled platform architect scarcity:Shortages of engineers certified in Salesforce Service Cloud and Genesys Cloud limit deployment velocity for mid-market buyers.
- ISO/IEC interoperability delays:Pending standards for cross-platform customer data exchange create procurement uncertainty among regulated industries.
- On-premise technical debt:Legacy Avaya and Cisco contact center estates require expensive migration consulting before cloud-native engagement stacks can activate.
Strategic Opportunities
- India's digital public infrastructure:Account Aggregator framework and UPI payment rails create native channels for financial services engagement without proprietary data silos.
- Outcome-based pricing models:Vendors tie contract value to measurable churn reduction or Net Promoter Score improvement rather than seat-based subscriptions.
- Voice biometric authentication:Convergence of speech recognition and fraud detection opens passwordless verification in contact centers serving high-net-worth segments.
Industry Challenges
- Fragmented martech integration:Enterprise buyers operate 15-25 separate engagement tools with brittle API connections that break during peak traffic.
- AI model explainability certification:Financial regulators in Singapore, the United Kingdom, and Brazil demand documented decision trails for credit and collections automation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Customer Engagement Solutions Market |
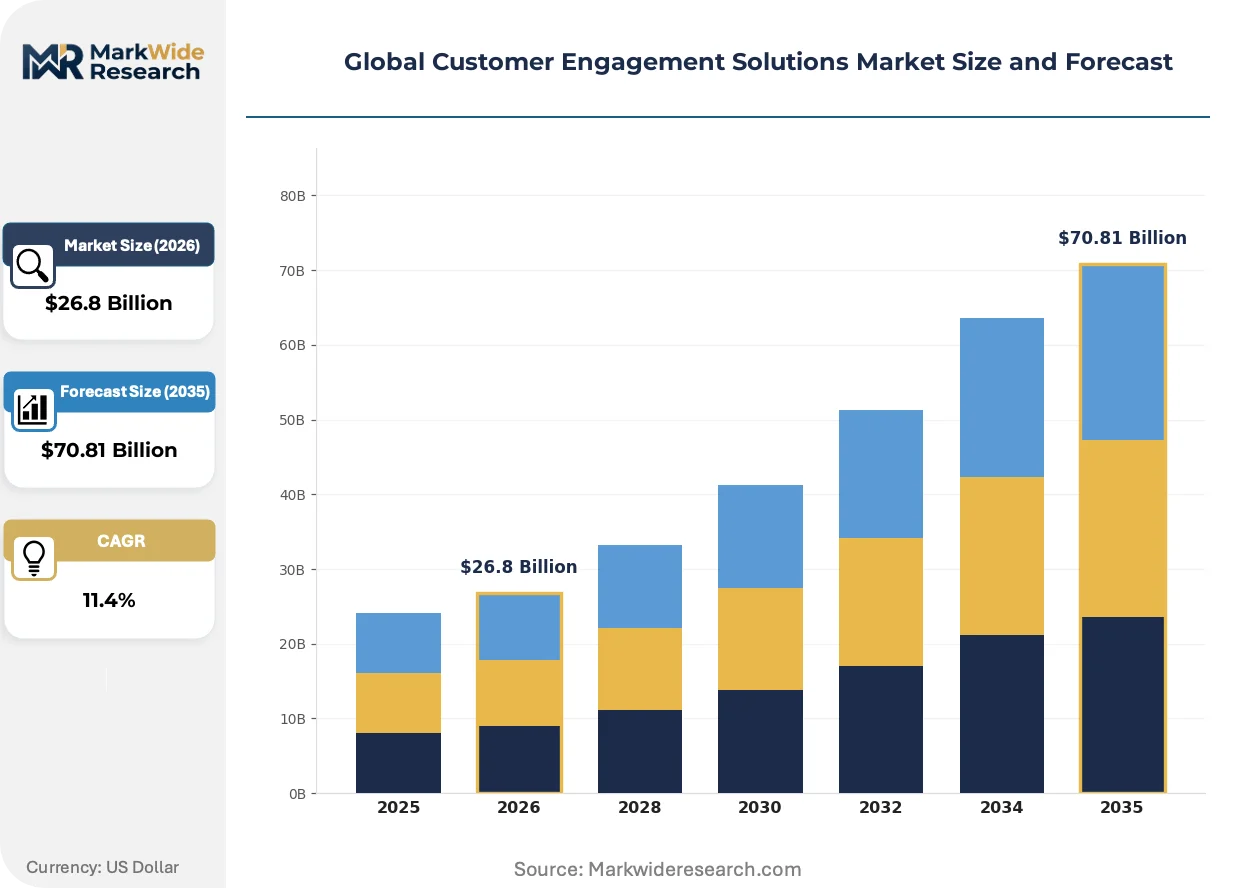
| Market Size in 2026 | $26.8 Billion |
| Market Size in 2035 | $70.81 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Solution Type: Customer Relationship Management, Social Media Management, Live Chat Software, Email Marketing Platforms, Customer Feedback Tools Deployment Model: Cloud-Based, On-Premise, Hybrid, Software as a Service, Platform as a Service End User Industry: Banking & Financial Services, Telecommunications Providers, E-Commerce Companies, Travel & Hospitality Firms, Media Agencies Customer Engagement Channel: Mobile Messaging, Web Customer Portals, Voice Call Systems, Social Media Platforms, Email, In-Person Interactions |
| Companies Covered | SAP SE, Avaya Inc., Salesforce.com Inc., Braze, Alvaria, Inc., Oracle Corporation, Genesys, MoEngage, IBM Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Customer Engagement Solutions Market Shifts & Advancements
Real-time interaction management is absorbing behavioral signals from Internet of Things endpoints and mobile applications to trigger contextual engagement before customers initiate contact. This convergence of data streams and decision engines is compressing response windows from hours to milliseconds.
Generative AI for agent augmentation is absorbing routine inquiry handling across insurance claims and subscription management workflows. Fortune 500 contact centers in the United States deploy large language models to draft responses that human agents edit before sending, cutting average handle time by one-third. The technology is absorbing tier-one support volume previously routed to offshore business process outsourcing providers.
The EU AI Act's risk-based classification system is forcing vendors to document training data provenance and model performance benchmarks for high-risk customer-facing applications. Deployment of automated credit decisioning and employment screening tools now requires conformity assessments in France, Germany, and the Netherlands. Banking software providers are reengineering algorithms to satisfy Article 13 transparency requirements before 2025 enforcement deadlines.
Subscription fatigue among B2B buyers is shortening evaluation cycles for engagement platform procurement. Mid-market technology companies in Israel and Sweden now demand modular pricing with 90-day termination clauses rather than three-year enterprise agreements. Vendor sales organizations are unbundling implementation services from software licenses to accommodate this preference for operational flexibility over capital commitment.
Global Customer Engagement Solutions Market Segmentation
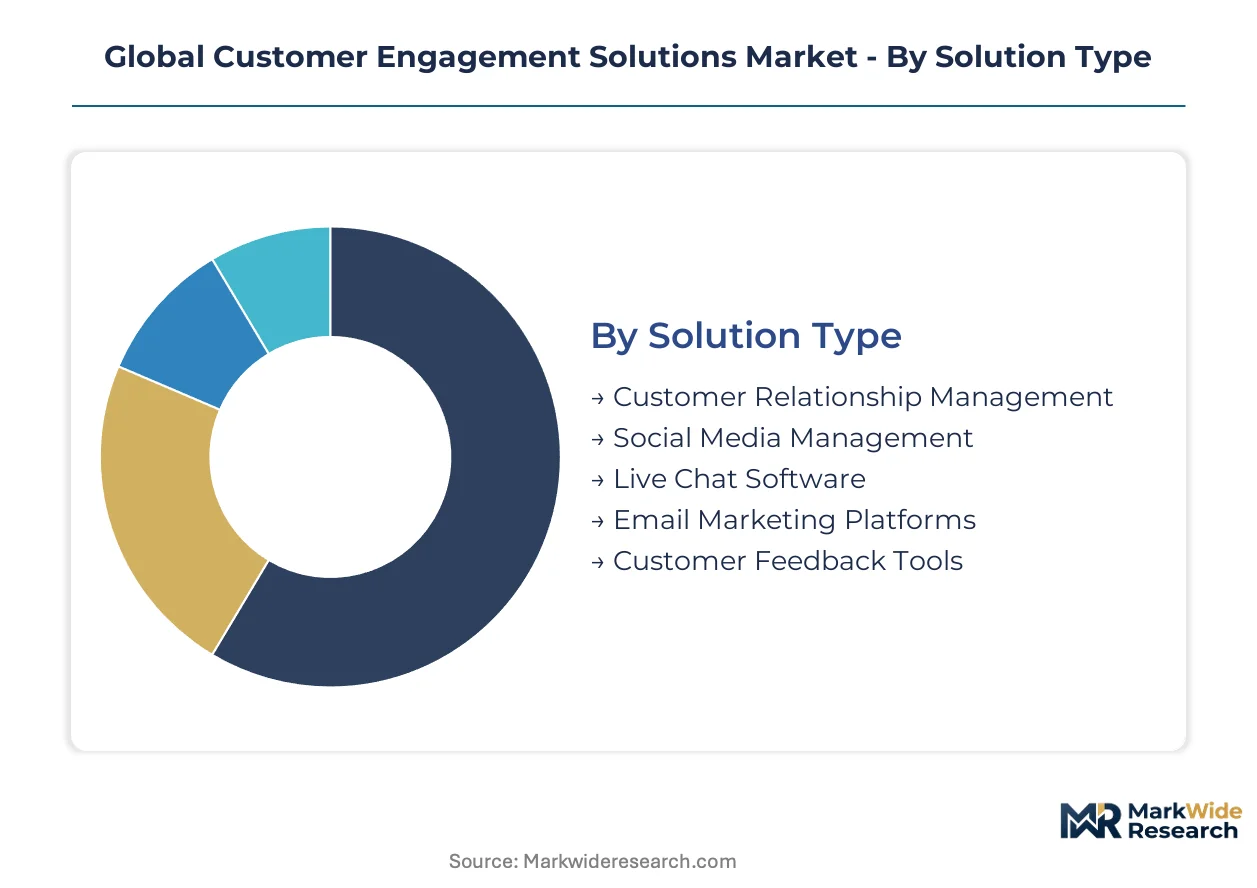
Customer engagement solutions fragment across four intersecting dimensions that determine procurement priorities. Solution type and deployment model shape technical architecture decisions, while end-user industry and engagement channel dictate compliance requirements and integration complexity. Buyers navigate these categories to balance operational flexibility against regulatory constraints.
Solution Type:
Volume concentration sits with established CRM platforms, while premium pricing attaches to specialized social and real-time interaction tools.
- Customer Relationship Management:Core database systems consolidate transaction history, preference profiles, and interaction logs into unified customer records. Demand concentrates among Fortune 500 enterprises in the United States modernizing legacy Siebel and Microsoft Dynamics estates, driven by API consolidation mandates that reduce integration overhead.
- Social Media Management:Publishing, listening, and community response platforms orchestrate brand presence across LinkedIn, Instagram, and emerging channels. Growth concentrates in mid-market digital-native companies in Israel and Sweden seeking modular stacks with 90-day termination clauses, reflecting subscription fatigue and preference for operational flexibility.
- Live Chat Software:Real-time messaging infrastructure embedded in websites and mobile applications.
- Email Marketing Platforms:Campaign orchestration tools managing segmentation, deliverability, and automated nurture sequences.
- Customer Feedback Tools:Survey, Net Promoter Score, and voice-of-customer analytics platforms.
Mature deployment sits with Customer Relationship Management. Newer deployment is concentrated in Social Media Management.
Deployment Model:
Cloud-native architectures dominate new procurement, though regulated industries retain hybrid configurations for sensitive data handling.
- Cloud-Based:Multi-tenant SaaS infrastructure operated by vendors across distributed data centers. Demand concentrates among retail banking institutions in Germany and the Netherlands replacing Avaya and Cisco contact center hardware, constrained by EU AI Act algorithmic transparency mandates requiring architectural redesigns.
- Software as a Service:Subscription-licensed applications with vendor-managed infrastructure and automatic feature updates. Growth concentrates in mid-market buyers across the United States facing skilled platform architect scarcity in Salesforce Service Cloud and Genesys Cloud certifications.
- On-Premise:Customer-operated hardware and software within private data centers.
- Hybrid:Split architectures retaining sensitive workloads on-premise while routing standard interactions to cloud.
- Platform as a Service:Developer-centric environments enabling custom engagement application construction.
Legacy retention persists in On-Premise. Steepest expansion trajectory belongs to Cloud-Based.
End User Industry:
Compliance complexity drives pricing power in financial services, while volume scale characterizes telecommunications and e-commerce procurement.
- Banking & Financial Services:Core banking, wealth management, and insurance engagement platforms requiring audit trails and fraud-resistant authentication. Demand concentrates among institutions in Singapore, the United Kingdom, and Brazil facing AI model explainability certification requirements for credit and collections automation.
- E-Commerce Companies:Purchase journey optimization, cart abandonment recovery, and post-transaction support systems. Growth concentrates in India's digital public infrastructure leveraging Account Aggregator framework and UPI payment rails for native engagement channels without proprietary data silos.
- Telecommunications Providers:Subscriber lifecycle management and network outage communication systems.
- Travel & Hospitality Firms:Booking engines, loyalty program management, and real-time service recovery platforms.
- Media Agencies:Campaign performance tracking and advertiser-client collaboration portals.
Margin depth concentrates in Banking & Financial Services. Fastest adoption velocity appears in E-Commerce Companies.
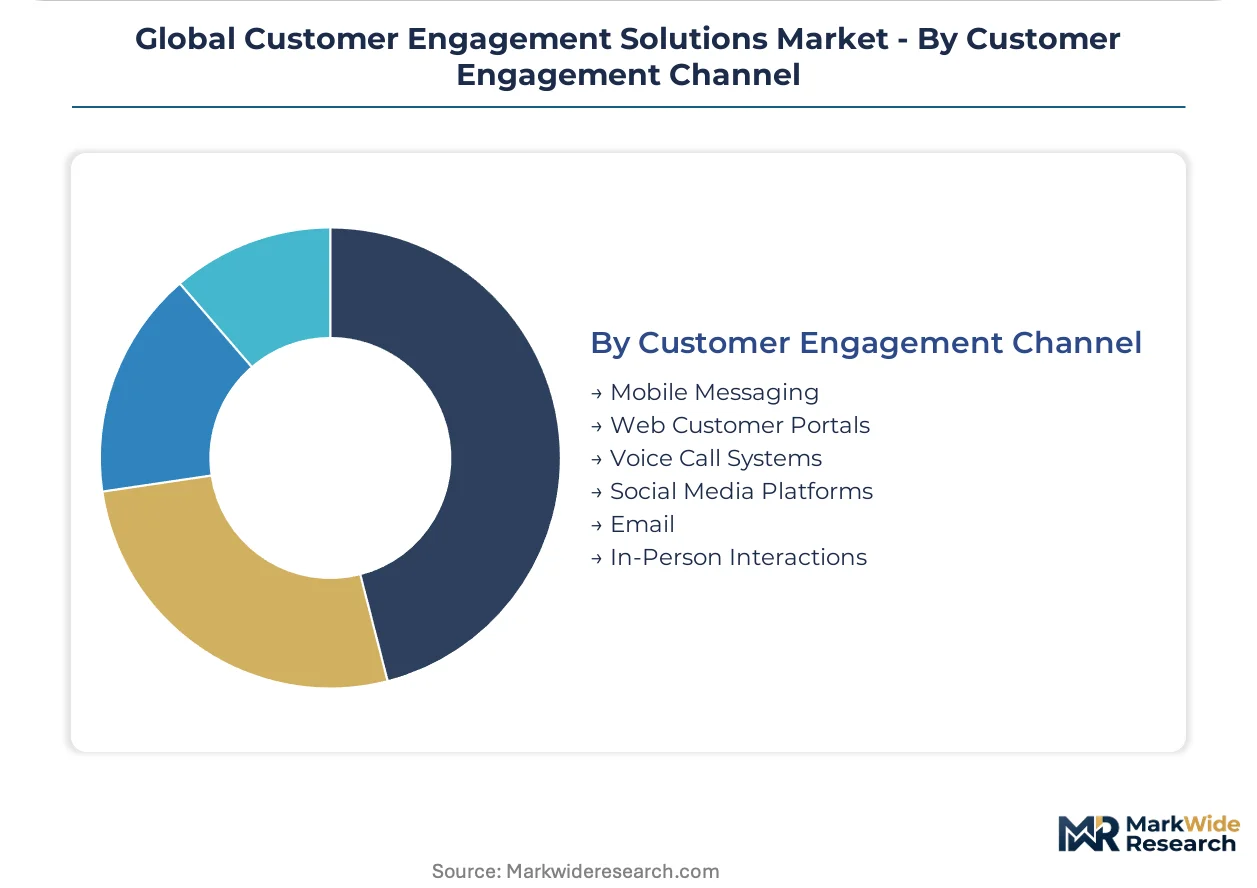
Customer Engagement Channel:
Asynchronous digital channels scale efficiently, while synchronous voice and in-person interactions retain premium service positioning.
- Mobile Messaging:SMS, WhatsApp Business, and proprietary app-based notification systems. Demand concentrates among telecommunications providers in Germany, South Korea, and the United States reducing latency through 5G network rollouts for voice and video engagement channels.
- Voice Call Systems:Interactive voice response, automatic call distribution, and agent desktop integration. Growth concentrates in high-net-worth banking segments deploying voice biometric authentication for passwordless verification combining speech recognition with fraud detection.
- Social Media Platforms:Public and direct message handling across consumer networks.
- Web Customer Portals:Self-service knowledge bases and account management interfaces.
- Email:Transactional and marketing message delivery infrastructure.
- In-Person Interactions:Branch, store, and field service engagement capture systems.
Cost efficiency leadership sits with Mobile Messaging. Premium service differentiation attaches to Voice Call Systems.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Data center infrastructure in Northern Virginia and cloud availability zones across Frankfurt anchor capacity deployment for real-time customer engagement platforms. Regulatory divergence between the EU AI Act and FCC TCPA enforcement is fragmenting architectural standards across Atlantic markets.
United States
Fortune 500 enterprises in New York and Chicago are retiring Avaya and Cisco contact center estates for cloud-native stacks. The FCC enforces TCPA restrictions on outbound voice and SMS that constrain channel mix decisions for domestic campaigns. Silicon Valley clusters concentrate generative AI development for agent augmentation tools.
Germany
Retail banking institutions in Frankfurt and Munich are replacing legacy hardware with unified engagement platforms under compliance pressure. The EU AI Act mandates algorithmic transparency documentation for automated credit decisioning systems before 2025 deadlines. The KBA supervises voice biometric authentication deployments in high-net-worth wealth management segments.
United Kingdom
Financial regulators in London demand AI model explainability certification for collections automation and credit scoring workflows. The Financial Conduct Authority coordinates with the Information Commissioner's Office on GDPR-compliant cross-border data orchestration. Edinburgh and Manchester host mid-market technology companies seeking modular engagement stacks with short termination clauses.
India
E-commerce platforms in Bangalore and Mumbai leverage Account Aggregator framework and UPI payment rails for native engagement channels. The RBI oversees data localization requirements that shape cloud deployment architectures for financial services. Hyderabad clusters concentrate Salesforce Service Cloud and Genesys Cloud certification programs addressing skilled platform architect scarcity.
Singapore
Wealth management firms deploy voice biometric authentication for passwordless verification in private banking contact centers. The Monetary Authority of Singapore mandates documented decision trails for automated customer interactions in credit and collections. The central business district anchors regional headquarters for vendors serving ASEAN financial institutions.
Global Customer Engagement Solutions Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue outcome-based pricing and modular microservices. The vendor base stratifies across three tiers: CRM-centric ecosystem providers anchoring enterprise accounts, database-integrated incumbents serving regulated migration pathways, and cloud-native specialists capturing mid-market subscription fatigue. Strategic moves concentrate on M&A for AI talent acquisition and vertical partnership networks with system integrators certified in legacy-to-cloud migration.
Within the enterprise ecosystem tier, Salesforce.com Inc. and Oracle Corporation occupy positions defined by integration depth with adjacent enterprise software stacks. SAP SE anchors the ERP-embedded segment for manufacturing and retail conglomerates requiring unified customer data architectures. These three entities exemplify competitive positioning through platform consolidation rather than point-solution specialization.
| Leading Market Players |
|---|
| SAP SE |
| Avaya Inc. |
| Salesforce.com Inc. |
| Braze |
| Alvaria, Inc. |
| Oracle Corporation |
| Genesys |
| MoEngage |
| IBM Corporation |
| Others |
Supply & Pricing Matrix
Horizontal integration across cloud infrastructure and professional services anchors supply positioning while concentrating pricing power among vendors with certified migration capabilities. Enterprises purchasing customer engagement solutions face bundled implementation costs that separate full-service providers from modular specialists.
Pricing Analysis
Service-bundling differentiation separates vendors offering end-to-end implementation from those unbundling professional services to accommodate subscription-fatigued buyers. Three-tier pricing structure across premium, standard, and economy levels reflects deployment complexity, with premium tiers capturing compliance-heavy financial services requiring EU AI Act documentation. Cost compression in standard tiers is intensifying because mid-market buyers demand 90-day termination clauses. Digital-native companies in Israel and Sweden exhibit highest price sensitivity, while Fortune 500 banking institutions show lowest sensitivity due to regulatory non-negotiables.
Supply Chain Analysis
ISO/IEC certification gating constrains vendor qualification for regulated industry procurement frameworks, filtering platform providers by interoperability documentation. Cloud infrastructure concentrates in the United States, Germany, and India, with data center capacity anchored in Northern Virginia, Frankfurt, and Hyderabad. Proprietary AI training data, API middleware, and voice biometric libraries constitute critical inputs. Single-source vulnerability runs through hyperscaler compute dependencies. Distribution runs through certified system integrators specializing in Avaya-to-cloud migration pathways.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Skilled platform architect scarcity props pricing power for vendors with Salesforce Service Cloud and Genesys Cloud certification pipelines. Capacity bottlenecks in certified migration consulting sustain margin premiums.
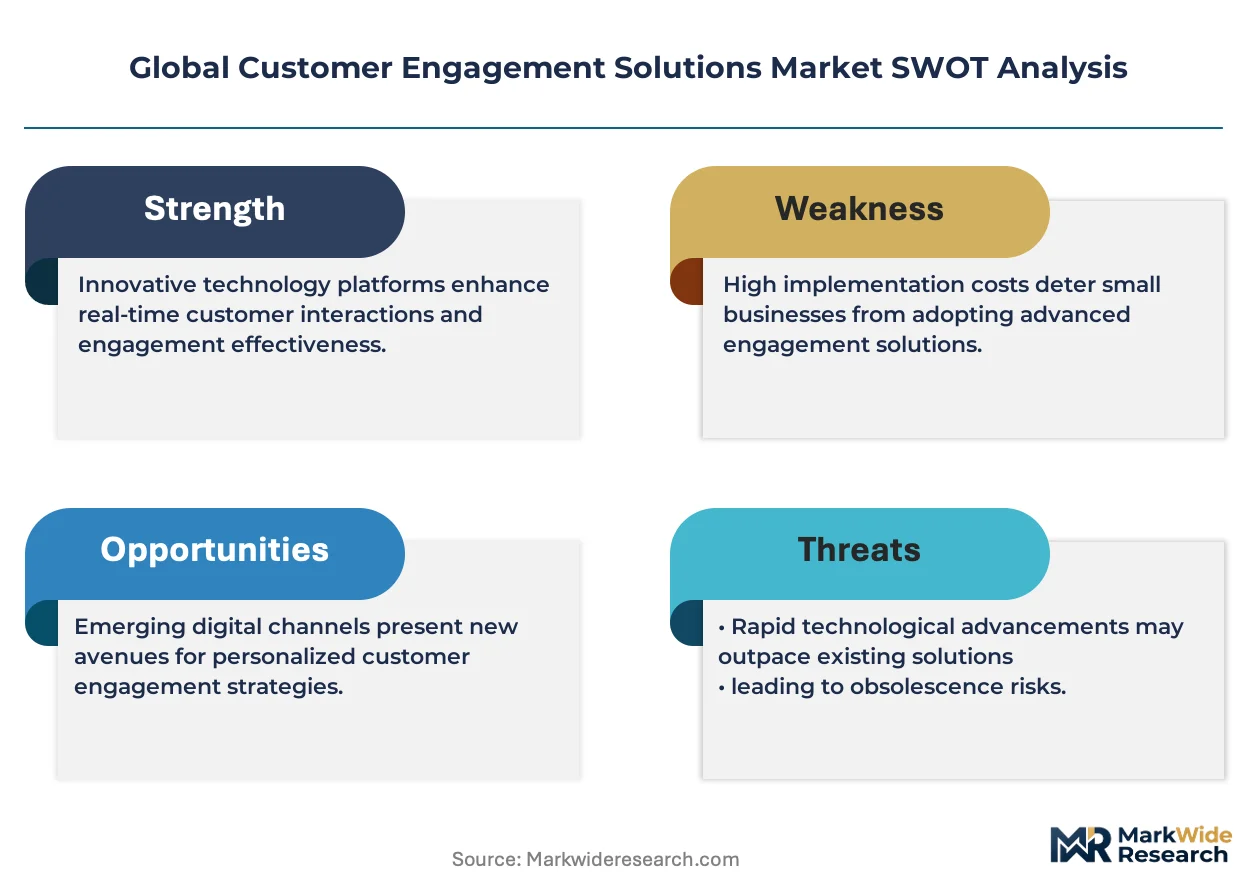
For Market Incumbents: Anticipate displacement pressure from modular microservices vendors by deepening vertical integration into legacy-to-cloud migration services. Anchor enterprise accounts through ERP-embedded customer data unification that appeals to manufacturing conglomerates. Prioritize AI talent acquisition to defend against generative AI specialists eroding agent augmentation margins.
For New Entrants and Emerging Players: WhatsApp Business API routes offer lowest-friction entry into India's e-commerce engagement stack, where Account Aggregator framework adoption creates native channel demand. Target mid-market technology companies in Sweden seeking 90-day termination flexibility. Deploy outcome-based pricing tied to measurable churn reduction to differentiate from seat-based incumbents.
For Investors and Strategic Acquirers: Exit pathways concentrate in strategic acquisitions by hyperscalers seeking vertical AI capabilities. Five-to-ten year viability favors vendors with documented EU AI Act conformity assessments for high-risk automated decisioning. Watch Singapore Monetary Authority enforcement patterns as the inflection signal for explainability certification requirements spreading to ASEAN markets.
| Strategic Initiative | Industry Significance |
|---|---|
| AI Talent Acquisition | Genesys and Salesforce-certified engineers command premium valuations in migration-heavy markets. |
| EU AI Act Conformity Assessment | Documentation of training data provenance unlocks French and German banking procurement. |
| Outcome-Based Pricing Launch | Contracts tied to Net Promoter Score improvement attract subscription-fatigued mid-market buyers. |
| Voice Biometric Integration | Passwordless authentication modules penetrate Singapore private banking contact centers. |
| India Digital Infrastructure Partnership | UPI rail integration enables native engagement channels without proprietary data silos. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs, combined with primary interviews across CTOs, IT procurement officers, platform engineers, and integration specialists. SEC filings, hyperscaler capex disclosures, and EU AI Act implementation guidance provided demand-side validation. Bottom-up deployment counts triangulated against top-down enterprise software spend estimates.
Data-stream reconciliation across cloud infrastructure spend, certified professional services capacity, and regulatory compliance timelines shaped the analytical framework. Segmentation dimensions modeled include deployment model, organization size, vertical industry, integration complexity, and regional adoption pattern across the analysis window. CAGRs derived from vendor revenue disclosures and enterprise procurement survey data, with EU AI Act enforcement timelines and 5G network rollout schedules as industry-specific inputs.
The model holds under steady regulatory enforcement timelines; deviation in EU AI Act interpretation or FCC TCPA expansion would shift channel mix assumptions. Forecasts reflect documented assumptions about certified architect supply elasticity and hyperscaler pricing discipline. A model refresh is warranted upon material change in ISO/IEC interoperability standard finalization.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Customer Relationship Management (CRM)
Mobile CRM Market
Customer Relationship Management (CRM)
Canada Customer Relationship Management Market
Customer Relationship Management (CRM)
Healthcare CRM Market
Customer Relationship Management (CRM)
Client Onboarding Solutions Market
Customer Relationship Management (CRM)
Mortgage CRM Software Market
Customer Relationship Management (CRM)
CRM Outsourcing Market
Customer Relationship Management (CRM)
Customer Information System (CIS) Market
Customer Relationship Management (CRM)
Thailand CRM Market
Customer Relationship Management (CRM)
Loyalty Management Solutions Market
Customer Relationship Management (CRM)
Global Customer Relationship Management Market
Customer Relationship Management (CRM)
Cloud CRM Market
Customer Relationship Management (CRM)
Android CRM Software Market
Customer Relationship Management (CRM)
Global Customer Reference Management Software Market
Customer Relationship Management (CRM)
CRM Analytics Market
Customer Relationship Management (CRM)
Complaint Management Software Market
Customer Relationship Management (CRM)
Social CRM Market