
 CRM Application Software Market | 2026-2036
CRM Application Software Market Size, Share, and Industry Trends Forecast 2026-2036
CRM Application Software Market Analysis
Indirect software distribution through value-added resellers and systems integrators is rewriting how CRM platforms reach enterprise buyers. Salesforce leverages an expansive partner ecosystem to sustain deployment scale across Fortune 500 accounts. Microsoft Dynamics anchors mid-market penetration through native integration with Office 365 and Azure infrastructure. Oracle competes in regulated industries where database affinity and security certifications differentiate its offering.
CRM application software encompasses systems that capture, process, and analyze customer interactions across sales, marketing, and service functions, typically operating through centralized databases with API connectivity to enterprise resource planning and communication tools. These platforms orchestrate lead scoring, pipeline management, and predictive churn analytics to compress sales cycles and improve retention economics. Cloud-based deployment leads in new bookings as multi-tenant architectures reduce infrastructure overhead and accelerate implementation timelines. On-premises installations retain structural importance in healthcare and finance segments where data residency requirements govern platform selection. Small businesses represent the fastest-growing end-user tier as freemium pricing and low-code configuration tools lower adoption barriers.
The EU AI Act and GDPR impose algorithmic transparency and consent-management obligations that reshape how CRM vendors design automated recommendation engines and customer profiling workflows. In the United States, HIPAA and state-level privacy statutes such as the California Consumer Privacy Act constrain data-sharing architectures in healthcare and cross-industry deployments. Stakeholders must monitor evolving enforcement patterns around AI disclosure and third-party cookie deprecation to anticipate which deployment models and integration strategies preserve competitive access.
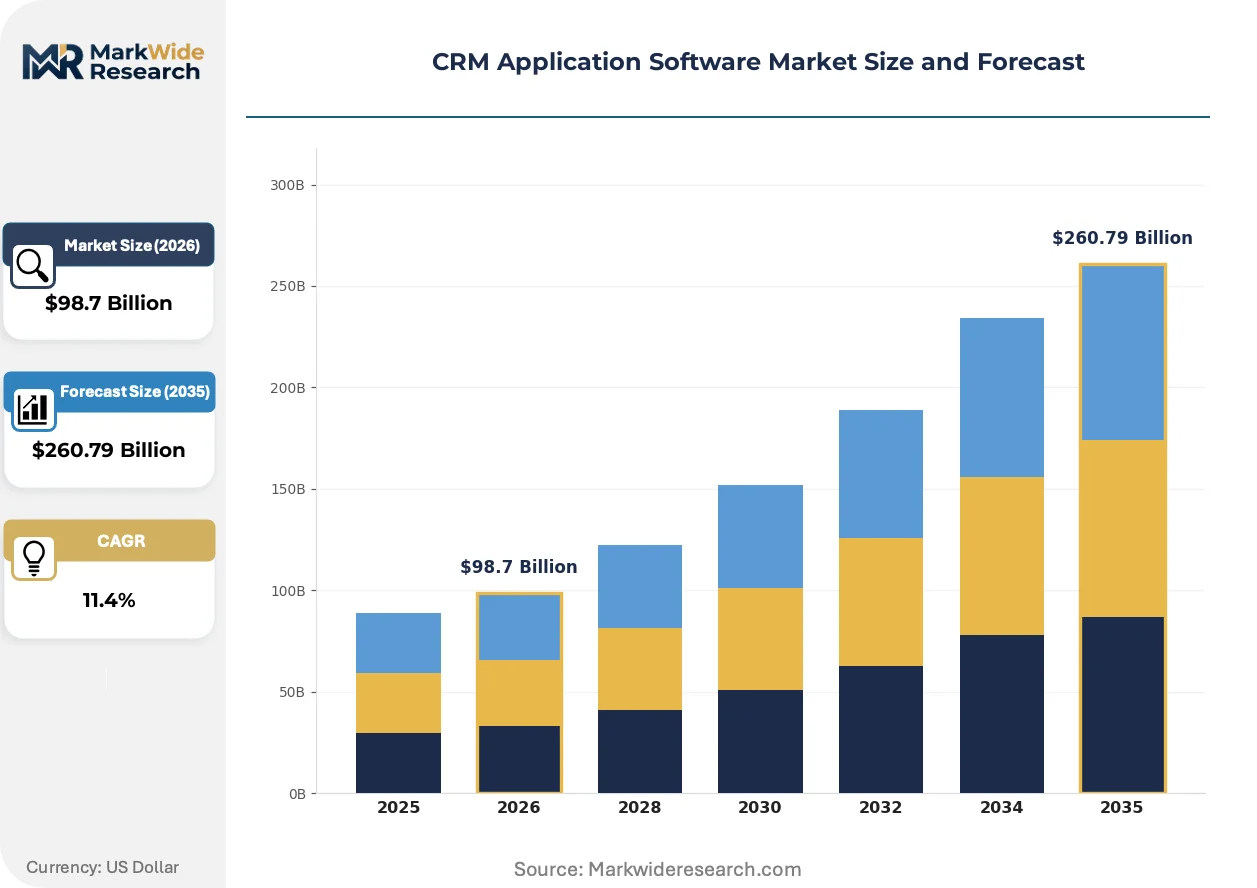
Market Dynamics
Cloud migration mandates under the EU AI Act and GDPR compliance requirements are accelerating replacement cycles for legacy on-premises systems, forcing vendors to rebuild architectures around algorithmic transparency and consent management.
Growth Catalysts
- GDPR and EU AI Act mandates:European data residency and algorithmic disclosure rules compel enterprises to upgrade from legacy on-premises CRM stacks to compliant cloud-native platforms.
- Wealth management data unification:Financial services firms deploy CRM systems to consolidate customer profiles across retail banking and investment advisory operations.
- Freemium pricing models:Low-code configuration tools and tiered entry pricing expand CRM access to small business segments previously priced out of enterprise platforms.
Market Restraints
- Healthcare data residency requirements:HIPAA constraints and state-level privacy statutes in the United States block cloud migration for providers requiring on-premises data control.
- Integration complexity with ERP systems:API connectivity failures between CRM platforms and enterprise resource planning tools extend implementation timelines and inflate professional services costs.
- Third-party cookie deprecation:Browser-level tracking restrictions degrade lead-scoring accuracy and force rebuilds of customer profiling workflows.
Strategic Opportunities
- Predictive churn analytics convergence:Machine learning pipelines integrated with communication tools enable real-time intervention before contract cancellations.
- Vertical-specific customization:Industry-tailored modules for regulated sectors command premium pricing and reduce competitive pressure from horizontal platforms.
- India's digital infrastructure expansion:Cloud data center investments and SMB digitization programs create new addressable markets for mid-market CRM vendors.
Industry Challenges
- Consent-management workflow redesign:GDPR and CCPA granular opt-in requirements force re-architecture of automated recommendation engines and marketing automation sequences.
- Multi-tenant security certification delays:FedRAMP and ISO 27001 audit timelines stretch 12-18 months, gating public sector and enterprise deployments.
- Legacy database migration friction:On-premises Oracle and SQL Server estates resist extraction without substantial data cleansing and schema transformation investments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | CRM Application Software Market |
| Market Size in 2026 | $98.7 Billion |
| Market Size in 2035 | $260.79 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cloud-Based, On-Premises, Hybrid, Open Source Deployment Model: Single Tenant, Multi-Tenant, Dedicated Server, Virtual Private Cloud End User: Small Businesses, Medium Enterprises, Large Corporations, Non-Profits Industry Vertical: Retail, Healthcare, Finance, Telecommunications |
| Companies Covered | Salesforce, Microsoft Dynamics, Oracle, SAP CRM, Adobe, HubSpot, Zoho, SugarCRM, Pipedrive, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
CRM Application Software Market Emerging Trajectories
Artificial intelligence is rewriting core CRM workflows, with vendors racing to embed generative capabilities into sales automation while regulators scramble to impose guardrails on algorithmic decision-making.
Generative AI for sales content and email sequencing is migrating from experimental pilots to standard deployment in technology and professional services verticals. Mid-market SaaS buyers now expect native AI writing assistants as table stakes, compressing differentiation timelines for vendors without embedded large language models. The technology is migrating from point-solution wrappers to core platform architecture, forcing incumbents to acquire or build native capabilities.
The EU AI Act's risk-based classification system imposes documentation and human oversight obligations on CRM systems deploying automated customer scoring. Vendors must now maintain technical files proving algorithmic transparency for high-risk use cases in credit and insurance. European financial services firms are responding by demanding vendor-provided audit trails and model cards as procurement prerequisites.
Enterprise buyers now unbundle implementation services from software subscriptions, preferring fixed-scope system integrator contracts over vendor professional services. This pattern concentrates in the United States, where Fortune 500 procurement teams negotiate direct SI relationships to reduce platform-switching costs. Value-added resellers capture margin previously retained by software vendors, reshaping channel economics across the ecosystem.
CRM Application Software Market Segmentation
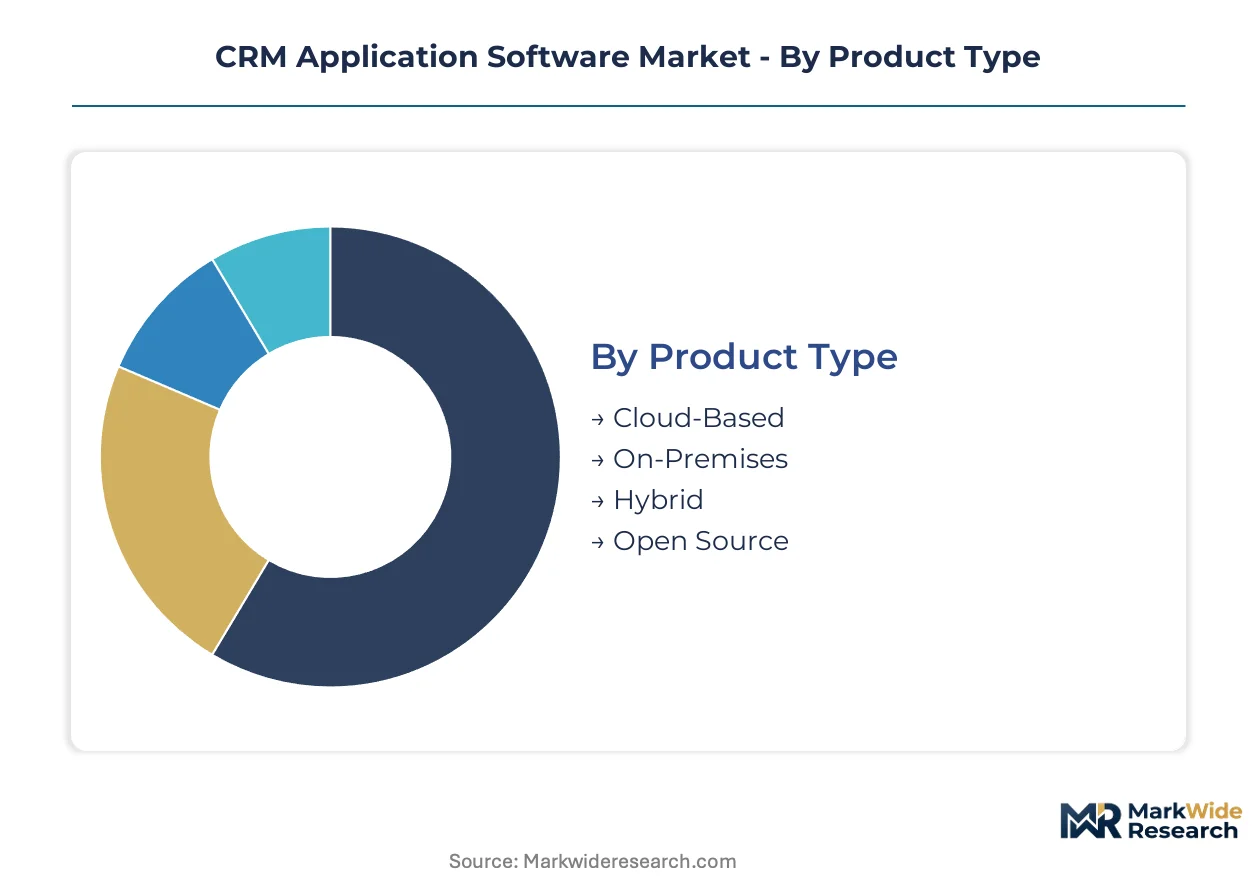
CRM platforms fragment across deployment architectures and buyer profiles that dictate renewal velocity and professional services attach rates. Understanding segment-level replacement cycles reveals where vendors capture recurring revenue versus one-time implementation fees.
Product Type:
Cloud-based deployments compress sales cycles to weeks while on-premises installations stretch across quarters of security review and infrastructure provisioning.
- Cloud-Based:Multi-tenant SaaS architectures with API-first design patterns dominate new bookings among enterprises migrating from legacy stacks. Financial services firms in Germany and France accelerate adoption as GDPR and EU AI Act compliance mandates force algorithmic transparency upgrades.
- On-Premises:Single-tenant installations running on customer-controlled hardware persist where HIPAA and state-level privacy statutes in the United States govern data residency. Healthcare providers in Texas and California maintain these deployments despite higher total cost of ownership.
- Hybrid:Split architectures synchronize sensitive data on-premises with analytics workloads in public cloud environments.
- Open Source:Community-edition platforms with modular plugin ecosystems attract cost-constrained mid-market buyers.
Cloud-Based anchors the volume base while Open Source gains share at the steepest rate among digitizing small businesses.
Deployment Model:
Cost tiers separate enterprise buyers seeking isolation guarantees from mid-market purchasers prioritizing per-seat economics.
- Multi-Tenant:Shared infrastructure pools deliver lowest unit costs and automatic patch propagation across subscriber bases. Technology vendors in Bangalore and SaaS startups in Austin standardize on this model for rapid scaling without capital expenditure.
- Single Tenant:Dedicated instance-per-customer architectures satisfy security audit requirements in regulated industries. Insurance carriers in Zurich and wealth managers in Singapore procure these deployments for FedRAMP and ISO 27001 certification pathways.
- Dedicated Server:Physical hardware assignments for customers with throughput or latency constraints.
- Virtual Private Cloud:Logically isolated network segments within hyperscaler environments balancing cost and control.
Multi-Tenant captures the highest transaction volume while Virtual Private Cloud climbs fastest among compliance-sensitive European financial institutions.
End User:
Customer maturity determines feature utilization depth and expansion revenue potential across the account lifecycle.
- Large Corporations:Fortune 500 procurement teams demand enterprise-grade SLAs, custom object modeling, and dedicated customer success management. Manufacturing conglomerates in Stuttgart and pharmaceutical headquarters in Basel deploy these platforms across thousands of seats with ERP integration requirements.
- Small Businesses:Freemium-tier entrants with sub-fifty-employee headcounts represent the expansion frontier. Restaurant groups in Mumbai and professional services firms in Melbourne adopt low-code configuration tools without IT departments.
- Medium Enterprises:Hundred-to-thousand-employee organizations with formalized sales operations but limited integration complexity.
- Non-Profits:Donor-management-focused deployments with discounted pricing and grant-tracking modules.
Large Corporations anchor the revenue base while Small Businesses expand most quickly as self-service onboarding reduces acquisition costs.
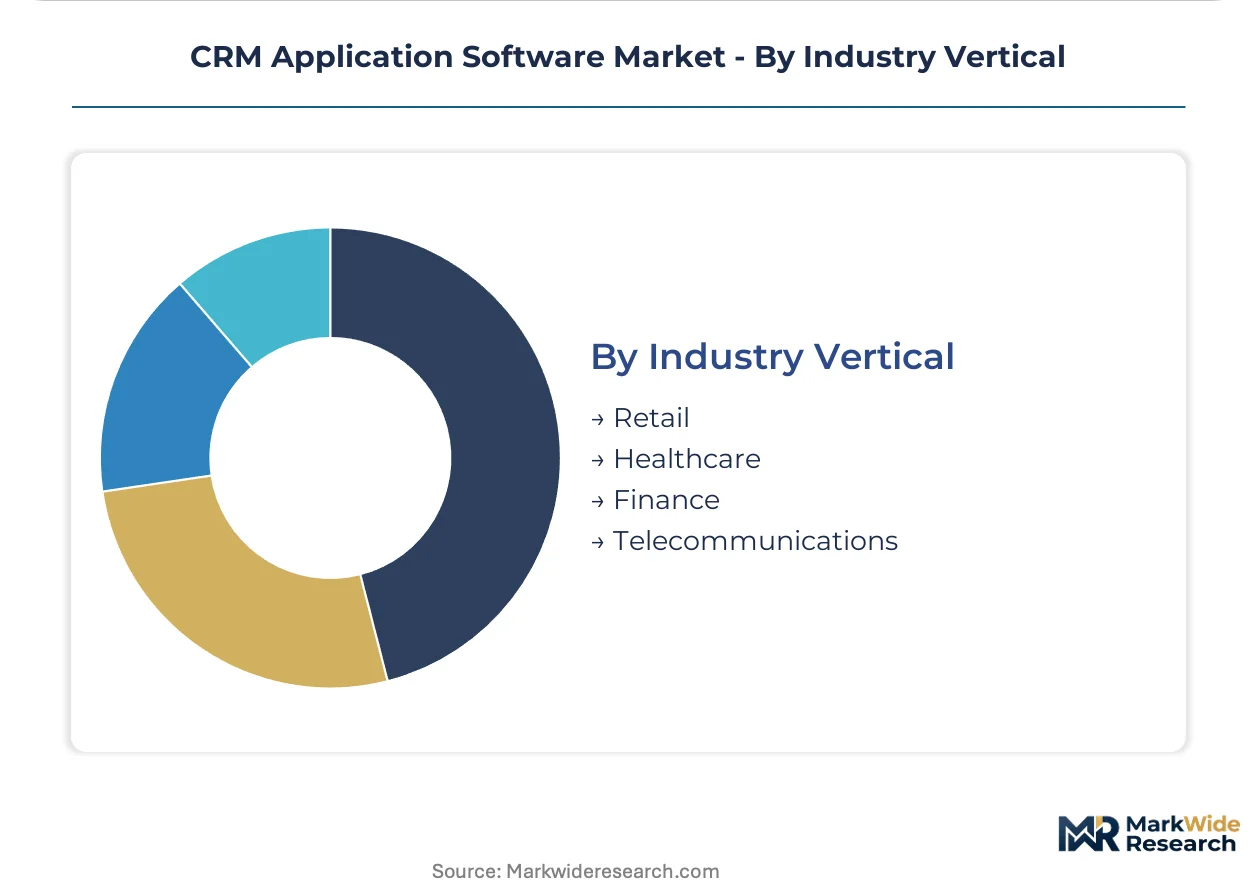
Industry Vertical:
Application-specific workflows differentiate commodity horizontal platforms from premium vertical solutions.
- Finance:Wealth management and retail banking unification drives demand for customer-360 profiling with audit trails. Universal banks in London and private wealth advisors in Geneva require algorithmic transparency documentation under EU AI Act risk classifications.
- Healthcare:Patient relationship management with HIPAA-compliant consent workflows and electronic health record integration. Hospital networks in Illinois and specialty clinics in Florida maintain strict on-premises or single-tenant requirements.
- Retail:Omnichannel order history and loyalty program orchestration across digital and physical touchpoints.
- Telecommunications:Subscriber lifecycle management with churn prediction and upsell campaign automation.
Finance anchors the premium pricing tier while Healthcare shows the steepest expansion trajectory as post-pandemic patient engagement digitization accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The transatlantic fiber optic cable corridors linking Frankfurt, London, and New York underpin the CRM software trade's geographic architecture, with data gravity shifting toward compliance-certified cloud regions.
United States
Enterprise SaaS procurement from Fortune 500 manufacturers in Detroit and pharmaceutical headquarters in Boston drives premium platform adoption. HIPAA and state-level privacy statutes including the California Consumer Privacy Act constrain cross-border data architectures. The Austin-San Antonio corridor hosts rapid-growth SaaS startups deploying multi-tenant CRM stacks for mid-market expansion.
Germany
Universal banks in Frankfurt and industrial conglomerates in Stuttgart demand customer-360 profiling with algorithmic transparency documentation. GDPR and the EU AI Act mandate cloud migration from legacy on-premises systems, with KBA oversight extending to automated credit-scoring workflows. The Bavarian software cluster around Munich anchors vertical-specific customization for automotive supply chains.
United Kingdom
Wealth managers in the City of London and fintech startups in Shoreditch deploy CRM systems for retail banking unification. The Information Commissioner's Office enforces consent-management standards that reshape marketing automation sequences. The Cambridge-Oxford technology arc incubates AI-native CRM challengers targeting professional services verticals.
India
Cloud data center investments in Mumbai and Bangalore support SMB digitization programs creating new addressable markets. RBI guidelines on data localization influence vendor selection for financial services deployments. The Hyderabad software corridor attracts mid-market CRM vendors establishing delivery centers for Asia-Pacific expansion.
Japan
Manufacturing exporters in Nagoya and Tokyo-based trading houses integrate CRM platforms with ERP systems for distributor network management. METI's data governance frameworks shape procurement requirements for automated customer scoring. The Osaka-Kobe industrial zone maintains hybrid deployments balancing cloud analytics with on-premises data residency.
CRM Application Software Market Vendor Landscape
Platform integrators command the system tier; component specialists sit upstream in API middleware and consent-management modules. The vendor base concentrates around three horizontal stacks serving Fortune 500 accounts, with mid-market penetration contested by vertical-focused challengers. Strategic archetypes span cloud-native SaaS incumbents, database-anchored enterprise vendors, and open-source community platforms. Competitive moves center on acquisition of AI-native startups and expansion of value-added reseller networks to capture implementation margin.
Within the cloud-native tier, Salesforce and Microsoft exemplify platform-scale deployment models, while Oracle occupies a position among database-anchored vendors serving regulated industries. These three anchors represent divergent architectural bets: API-first ecosystem expansion, native productivity suite integration, and data residency certification pathways respectively.
| Leading Market Players |
|---|
| Salesforce |
| Microsoft Dynamics |
| Oracle |
| SAP CRM |
| Adobe |
| HubSpot |
| Zoho |
| SugarCRM |
| Pipedrive |
| Others |
Supply Flow & Price Mechanics
Undercapacity in GDPR-certified cloud infrastructure across Frankfurt and Dublin regions is compressing implementation timelines and elevating premium-tier pricing for compliant deployments. Vendors respond by prioritizing multi-tenant capacity additions while channel partners capture margin previously retained through professional services bundling.
Pricing Analysis
Volume-discount tiering structures anchor CRM software economics, with three-tier pricing separating enterprise SLA guarantees from mid-market standard editions and freemium small-business entry points. Price differentiation rests on FedRAMP certification grade and vertical-specific customization depth, with healthcare and finance buyers absorbing premiums for HIPAA-compliant single-tenant architectures. Cost compression in the mid-market tier is intensifying because Microsoft and Salesforce are converging feature parity at lower price points. Small businesses exhibit highest price sensitivity, while Fortune 500 procurement teams prioritize total cost of ownership over per-seat rates.
Supply Chain Analysis
Export-control regimes limiting AI chip flows to Chinese hyperscalers are reshaping where cloud infrastructure capacity concentrates. Geographic supply concentration centers on the United States, Ireland, and Singapore for compliant data center operations serving regulated industries. Raw material dependencies include NVIDIA GPU clusters, specialized cooling systems, and fiber optic interconnect hardware. Single-source vulnerability in AI accelerator supply creates implementation bottlenecks for vendors deploying generative CRM features. Distribution runs through value-added resellers and systems integrators rather than direct vendor sales teams.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
CRM software penetration remains in early-cycle expansion, with small-business digitization programs and EU compliance mandates creating durable tailwinds for replacement demand. Cloud-native platforms are displacing legacy on-premises estates faster than prior technology cycles.
For Market Incumbents: Harden defensive moats by acquiring consent-management workflow specialists before EU AI Act enforcement tightens. Deepen backward integration into AI model training infrastructure to reduce dependency on third-party API providers. Channel control through exclusive SI partnerships protects margin against unbundling trends in Fortune 500 procurement.
For New Entrants and Emerging Players: Pursue white-space opportunities in India's SMB digitization programs, where localized pricing and Hindi-language interfaces remain underdeveloped. Target professional services verticals in the United Kingdom with AI-native contract intelligence modules. A vertical-specific go-to-market angle through industry associations accelerates trust formation against horizontal incumbents.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among vertical-focused vendors serving regulated industries with sticky compliance requirements. Long-term viability favors platforms with native AI architecture rather than wrapper implementations vulnerable to feature commoditization. Acquisition target archetype: mid-market vendors with ISO 27001 certification and existing healthcare or finance customer bases. The signal to monitor is FedRAMP authorization timelines, which gate public-sector expansion and predict enterprise sales velocity.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Native embedding with Microsoft 365 and Azure reduces switching costs for mid-market buyers. |
| Acquisition of Specialist Firm | Consent-management startups address GDPR and CCPA workflow gaps in marketing automation. |
| Geographic Expansion | Cloud data center investments in Mumbai and Bangalore capture India's SMB digitization wave. |
| Strategic Partnership | Systems integrator alliances redirect implementation margin from vendor professional services. |
| Product Launch | Generative AI sales assistants compress differentiation timelines for laggard vendors. |
Methodological Framework
A standing panel of CRM platform engineers, IT procurement officers at Fortune 500 manufacturers, channel partner account executives, and systems integrator delivery leads provided ongoing calibration throughout the study period. Primary interview data combined with secondary validation from SEC SaaS company filings, hyperscaler capex disclosures, EU regulatory impact assessments, and hospital procurement databases. Bottom-up seat-count modeling and top-down enterprise spend analysis triangulated market sizing across deployment architectures.
Scenario-bracketing framed projections across the analysis window, with segmentation modeling spanning cloud versus on-premises deployment, organization size tiers, industry verticals, and regional compliance clusters. CAGRs derived from replacement cycle velocity analysis and expansion revenue per account trajectories. Forecast inputs incorporated EU AI Act implementation timelines and third-party cookie deprecation impacts on lead-scoring accuracy.
Sensitivities concentrate around FedRAMP authorization delays, AI chip export control expansions, and state-level privacy statute proliferation in the United States. Forecasts reflect documented assumptions regarding cloud migration elasticity and vertical-specific customization pricing power. Material shifts in GDPR enforcement patterns or generative AI regulatory classification would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Customer Relationship Management (CRM)
US Customer Relationship Management Market
Customer Relationship Management (CRM)
Global Customer Relationship Management Market
Customer Relationship Management (CRM)
Complaint Management Software Market
Customer Relationship Management (CRM)
Client Onboarding Solutions Market
Customer Relationship Management (CRM)
Ipad CRM Market
Customer Relationship Management (CRM)
Enterprise Feedback Management Market
Customer Relationship Management (CRM)
Global Contact Center Solution Market
Customer Relationship Management (CRM)
Mobile CRM Market
Customer Relationship Management (CRM)
Contact Centers Speech Applications Market
Customer Relationship Management (CRM)
Mortgage CRM Software Market
Customer Relationship Management (CRM)
Thailand CRM Market
Customer Relationship Management (CRM)
APAC Loyalty Management Market
Customer Relationship Management (CRM)
Global Customer Reference Management Software Market
Customer Relationship Management (CRM)
Global Customer Engagement Solutions Market
Customer Relationship Management (CRM)
Social CRM Market
Customer Relationship Management (CRM)
Telecom CRM Market