
 Thailand CRM Market | 2026-2036
Thailand CRM Market Size, Share, and Industry Trends Forecast 2026-2036
Thailand CRM Market Insights
Bangkok's cloud infrastructure build-out is narrowing the gap between enterprise and mid-market access to advanced CRM capabilities. Salesforce leverages its partner ecosystem to sustain dominance in financial services verticals. Microsoft Dynamics anchors its position through tight integration with Office 365 and Azure stacks already prevalent in Thai corporations. Zanroo differentiates by specializing in localized social CRM tools that navigate Thailand's unique LINE-centric consumer behavior.
Customer relationship management software orchestrates sales pipelines, service interactions, and marketing campaigns through centralized databases with API connectivity to ERP and e-commerce platforms. Cloud-based deployment leads current uptake as Thai firms prioritize remote accessibility and reduced capital expenditure over on-premises maintenance. Sales Automation functionality captures the deepest margin pools by cutting lead-to-close cycles for manufacturing and banking end users. Analytics functionality is expanding fastest as Thai retailers demand predictive churn models and real-time campaign attribution.
Thailand's Personal Data Protection Act and Ministry of Digital Economy and Society guidelines constrain cross-border data flows, forcing vendors to localize hosting or establish domestic data centers. BIS-adjacent standards for software reliability and the country's national cybersecurity framework shape procurement requirements for state-affiliated enterprises. Stakeholders must weigh compliance costs against localization mandates when selecting deployment architectures and vendor partnerships.
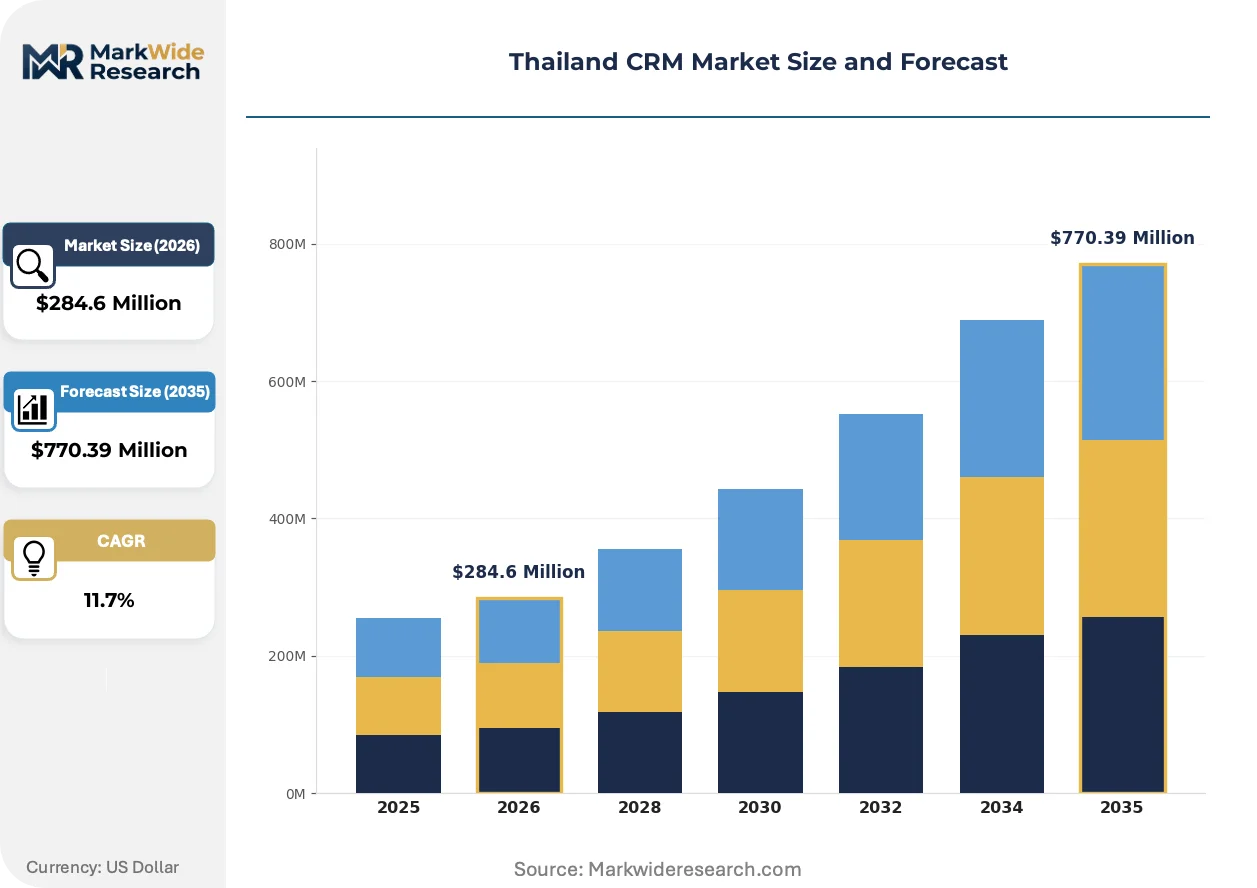
Market Dynamics
Thailand's Personal Data Protection Act is compressing vendor timelines for domestic data center deployment while banking institutions accelerate cloud migration to unify fragmented customer databases.
Growth Catalysts
- PDPA Compliance Mandates:Thailand's Personal Data Protection Act forces enterprises to replace offshore-hosted CRM instances with localized deployments, creating immediate replacement demand across financial services and retail verticals.
- LINE Ecosystem Dominance:Thailand's LINE-centric consumer behavior drives specialized social CRM module adoption, with vendors embedding native chat commerce and official account management into core platforms.
- Manufacturing Digitalization:Thai automotive and electronics exporters deploy sales automation to compress lead-to-close cycles for just-in-time procurement relationships with Japanese and German OEM buyers.
Market Restraints
- Cross-Border Data Friction:Thailand's PDPA restrictions on international data transfers force multinational vendors to absorb capital costs for domestic hosting infrastructure or cede ground to local competitors.
- Legacy System Entrenchment:State-affiliated enterprises and family-owned conglomerates maintain decades-old on-premises ERP architectures that resist API-based CRM integration without expensive middleware layers.
- Specialized Talent Scarcity:Bangkok's labor market lacks sufficient CRM architects fluent in both Thai regulatory requirements and Salesforce or Dynamics technical certification tracks.
Strategic Opportunities
- Eastern Economic Corridor Expansion:Industrial zones around Rayong and Chonburi present greenfield CRM deployment opportunities as Japanese and Chinese manufacturers establish new facilities with cloud-first IT mandates.
- AI-Powered Predictive Analytics:Convergence of machine learning models with LINE messaging data enables Thai retailers to build real-time churn prediction and personalized campaign orchestration capabilities.
- SME Segment Penetration:Thailand's mid-market enterprises remain underserved by enterprise-grade CRM vendors, creating white space for vertical-specific SaaS offerings priced below multinational subscription tiers.
Industry Challenges
- Integration Complexity:Thai banks struggle to reconcile cloud CRM platforms with core banking systems running on legacy IBM mainframe architectures, extending implementation timelines and inflating professional services costs.
- Certification Bottlenecks:BIS-adjacent software reliability standards and national cybersecurity framework compliance requirements delay procurement approvals for state-affiliated enterprises by six to twelve months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Thailand CRM Market |
| Market Size in 2026 | $284.6 Million |
| Market Size in 2035 | $770.39 Million |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: On-Premises, Cloud-Based, Hybrid, Mobile End User: Retail, Manufacturing, Banking, Healthcare Functionality: Sales Automation, Customer Support, Marketing Automation, Analytics Solution: Contact Management, Lead Management, Campaign Management, Integration Tools |
| Companies Covered | Salesforce, Microsoft Dynamics, Oracle, SAP, Zoho CRM, HubSpot, Freshworks, Pipedrive, Zanroo, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Thailand CRM Market Trends and Innovations
Thai enterprises are abandoning monolithic CRM suites in favor of composable architectures that embed social commerce and predictive intelligence directly into customer-facing workflows.
Composable CRM architecture is collapsing the traditional boundary between sales automation and customer data platforms. Thai retailers and banks are adopting API-first modules that embed LINE messaging, payment gateways, and loyalty systems within unified interfaces. This convergence eliminates the need for separate point solutions while compressing vendor consolidation timelines from multi-year roadmaps to quarterly sprints.
Thailand's Personal Data Protection Act enforcement is reshaping vendor infrastructure strategies. The Ministry of Digital Economy and Society guidelines now require explicit consent management and localized audit trails for all customer data processing. Financial services institutions face the steepest compliance burdens, with most accelerating domestic private cloud or sovereign-hosted deployments to avoid regulatory penalties and reputational exposure.
Subscription fatigue among Thai mid-market enterprises is driving preference for usage-based pricing models over per-seat licenses. Manufacturing and logistics buyers now negotiate contracts tied to transaction volumes or API call thresholds rather than named user counts. This shift is most visible in Bangkok's industrial zones, where ERP-integrated CRM procurement increasingly favors outcome-aligned commercial structures over traditional SaaS pricing.
Thailand CRM Market Segmentation
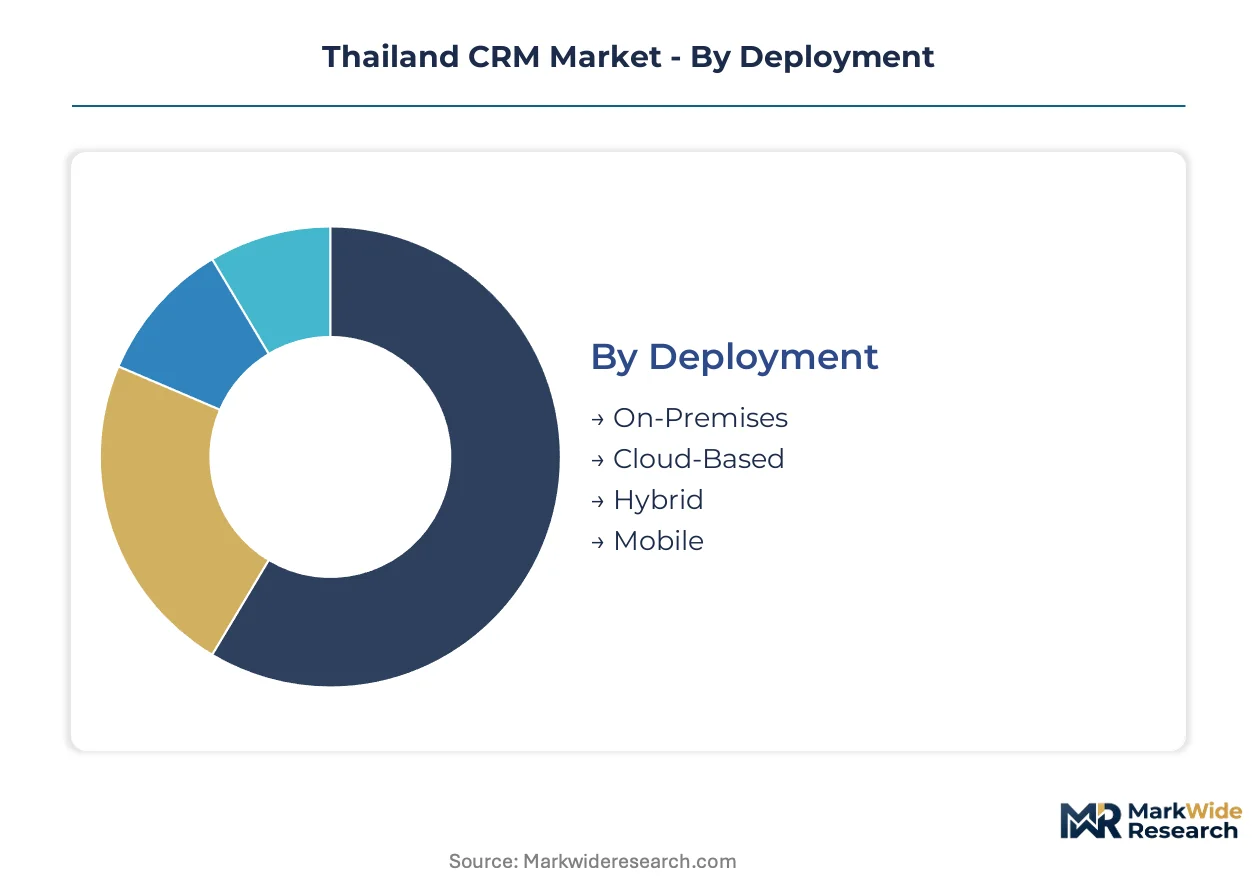
Thailand's CRM market fragments across deployment architectures, vertical applications, functional modules, and solution types. Each dimension carries distinct procurement criteria shaped by PDPA compliance burdens, LINE ecosystem integration requirements, and legacy system constraints.
Deployment:
Cost tier determines accessibility and compliance posture for Thai enterprises navigating data localization mandates.
- Cloud-Based:Multi-tenant SaaS platforms deliver elastic compute with automatic scaling for Bangkok's banking and retail sectors. Thai financial institutions concentrate procurement here to compress capital expenditure while satisfying PDPA audit trail requirements through domestic availability zones.
- On-Premises:Dedicated hardware installations within enterprise data centers grant full sovereignty over customer records. State-affiliated enterprises and defense contractors in Nonthaburi maintain this architecture to satisfy national cybersecurity framework certification timelines.
- Hybrid:Split workloads balance sensitive data on local servers against elastic front-end processing in cloud environments. Thai automotive suppliers deploying just-in-time sales pipelines favor this model for ERP integration flexibility.
- Mobile:Native iOS and Android applications extend CRM capabilities to field sales teams across Eastern Economic Corridor industrial zones. Manufacturing buyers prioritize offline synchronization for Rayong and Chonburi facility visits.
Cloud-Based commands the established base. The steepest expansion runs through Hybrid as compliance-conscious enterprises seek architectural compromise.
End User:
Application-specific workflows dictate module selection and integration complexity across Thai verticals.
- Banking:Core banking system integration dominates procurement criteria for universal banks headquartered in Bangkok's Silom district. PDPA-mandated consent management and cross-selling compliance consume implementation budgets.
- Retail:LINE Official Account synchronization and loyalty program orchestration define platform selection. Bangkok mall operators and provincial chain stores demand real-time campaign attribution across physical and digital touchpoints.
- Manufacturing:Japanese and German OEM procurement relationship management drives sales automation adoption. Automotive and electronics exporters in Pathum Thani deploy lead-to-close compression tools for just-in-time supply contracts.
- Healthcare:Patient relationship management and appointment scheduling integrate with hospital information systems. Private hospital groups in Sukhumvit and Chiang Mai prioritize HIPAA-aligned data handling for medical tourism workflows.
Banking retains the deepest installed base. Retail gains share fastest through LINE-commerce convergence.
Functionality:
Maturity curves separate foundational automation from advanced intelligence layers in Thai procurement.
- Sales Automation:Pipeline management, forecasting, and territory assignment anchor CRM deployments across manufacturing and banking verticals. Thai enterprises treat this as table stakes, with vendor differentiation concentrating on mobile offline capabilities.
- Analytics:Predictive churn modeling and customer lifetime value scoring expand rapidly as retailers demand real-time decisioning. Machine learning integration with LINE messaging data creates specialized demand in Bangkok's consumer-facing sectors.
- Customer Support:Ticket routing, knowledge bases, and omnichannel case management serve B2B industrial buyers and utilities. State enterprises prioritize BIS-adjacent reliability certifications for mission-critical service desk operations.
- Marketing Automation:Campaign orchestration, A/B testing, and journey mapping remain underpenetrated outside multinational subsidiaries. Mid-market Thai firms cite subscription fatigue and implementation complexity as adoption barriers.
Sales Automation captures the revenue concentration. Analytics climbs the fastest as predictive use cases mature.
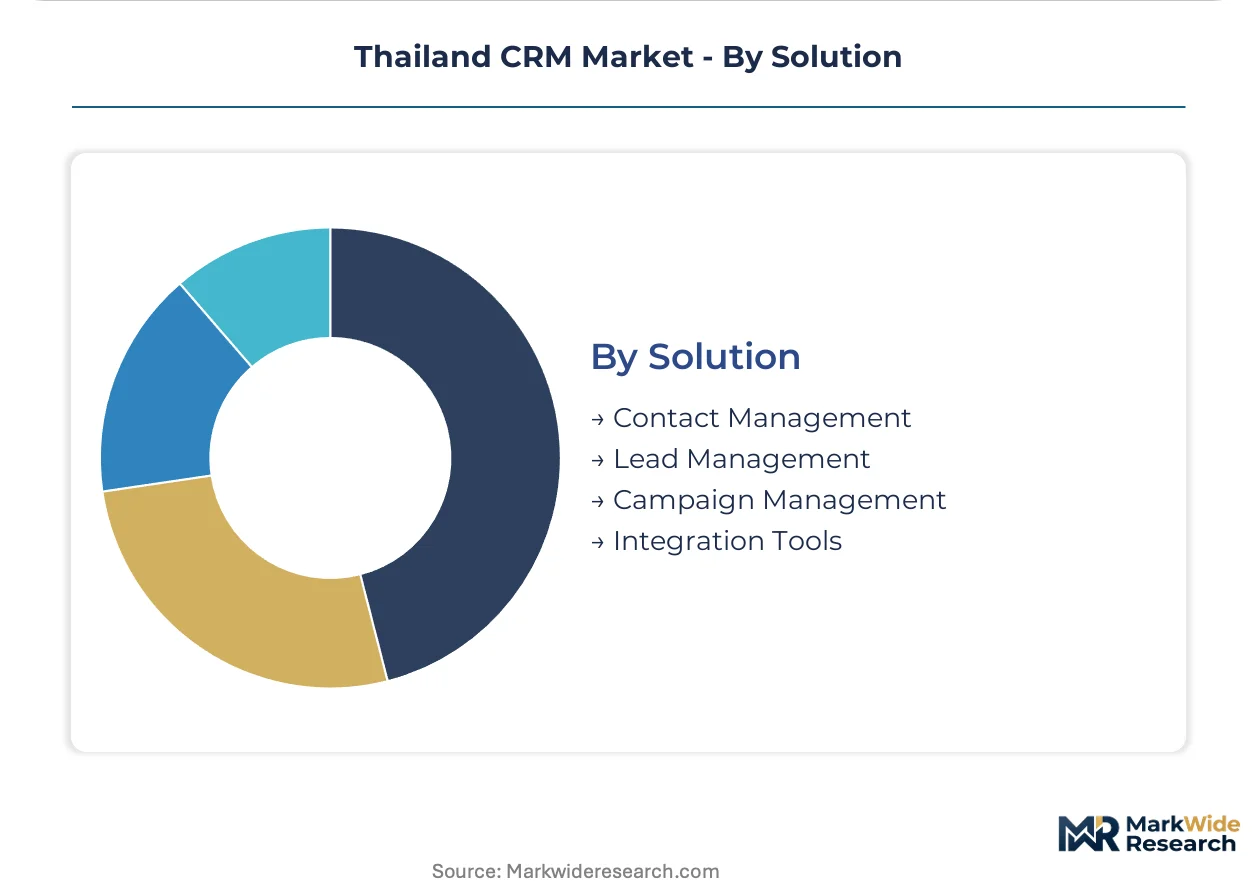
Solution:
Supply concentration among platform vendors shapes bundling strategies and point-solution viability.
- Contact Management:Centralized customer record databases with deduplication and enrichment capabilities form the foundational layer. Thai SMEs in provincial cities deploy standalone solutions before graduating to full-suite platforms.
- Lead Management:Capture, scoring, and distribution workflows integrate LINE, Facebook, and web form inputs. Manufacturing exporters in Samut Prakan prioritize Japanese-language lead routing for Tokyo and Osaka headquarters coordination.
- Campaign Management:Multi-channel execution and performance tracking modules compete with specialized marketing clouds. Retail banking teams in Bangkok evaluate native LINE messaging integration against best-of-breed alternatives.
- Integration Tools:API middleware, pre-built connectors, and custom development frameworks bridge CRM with ERP and e-commerce stacks. System integrators in Ladprao district monetize SAP and Oracle connector deployments for conglomerate clients.
Contact Management holds the legacy footprint. Integration Tools expand most quickly as composable architectures displace monolithic suites.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Eastern Economic Corridor's high-speed rail link to Bangkok underwrites Thailand's CRM demand concentration, connecting Rayong and Chonburi industrial zones to metropolitan enterprise software procurement channels.
Greater Bangkok Metropolitan Region
Silom and Sathorn financial districts drive banking CRM replacement cycles as universal banks migrate from legacy IBM mainframes. Thailand's Personal Data Protection Act mandates localized hosting, compressing procurement timelines for domestic private cloud deployments. System integrators in Ladprao district specialize in SAP and Oracle connector implementations for conglomerate clients.
Eastern Economic Corridor
Japanese and Chinese manufacturers establishing automotive and electronics facilities demand cloud-first CRM architectures with offline mobile synchronization. The Ministry of Digital Economy and Society's cybersecurity framework shapes procurement criteria for greenfield deployments. Rayong and Chonburi industrial zones concentrate sales automation adoption for just-in-time supply contract management.
Northern Thailand
Chiang Mai's medical tourism sector drives patient relationship management adoption among private hospital groups. Thailand's PDPA enforcement requires HIPAA-aligned data handling certifications for healthcare CRM procurement. Sukhumvit hospital operators extend branch systems to northern provinces, standardizing on centralized cloud platforms.
Central Plains Manufacturing Belt
Pathum Thani and Samut Prakan automotive exporters deploy lead management modules for Japanese-language coordination with Tokyo and Osaka OEM headquarters. The Board of Investment's digitalization incentives accelerate ERP-CRM integration projects. Manufacturing buyers negotiate usage-based pricing tied to transaction volumes rather than per-seat licenses.
Southern Coastal Provinces
Phuket and Krung Thep logistics hubs adopt mobile CRM extensions for field sales teams serving tourism and shipping verticals. Thailand's national cybersecurity framework delays state-affiliated enterprise approvals by six to twelve months. Provincial SME clusters remain underserved by enterprise-grade vendors, creating white space for vertical-specific SaaS offerings.
Thailand CRM Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in the integration layer. The vendor base separates into three concentrations: multinational cloud suites with domestic availability zones, regional system integrators with regulatory certification expertise, and local social CRM specialists embedding LINE ecosystem capabilities. Consolidation pressure runs highest among mid-market SaaS providers facing subscription fatigue from Thai enterprises. Competitive moves concentrate on domestic data center build-outs to satisfy PDPA mandates and API-first composable architectures displacing monolithic deployments.
Within the multinational platform tier, Salesforce and Microsoft Dynamics anchor enterprise procurement through partner ecosystems and Office 365 integration respectively. Zanroo occupies a distinct position representing the localized specialist archetype, embedding native LINE chat commerce and official account management into core platforms. These three exemplify the structural division between global scale advantages and regional behavioral adaptation requirements.
| Leading Market Players |
|---|
| Salesforce |
| Microsoft Dynamics |
| Oracle |
| SAP |
| Zoho CRM |
| HubSpot |
| Freshworks |
| Pipedrive |
| Zanroo |
| Others |
Pricing and Supply Chain Analysis
Undercapacity in domestic cloud infrastructure across Bangkok and the Eastern Economic Corridor is forcing multinational vendors to absorb capital costs for localized data centers, compressing margins while elevating pricing power for compliant domestic hosting providers serving PDPA-constrained enterprises.
Pricing Analysis
Thailand's Personal Data Protection Act dictates the pricing tier structure across the CRM market, with compliance-certified deployments commanding premium positioning over offshore-hosted alternatives. Three-tier pricing structure across premium, standard, and economy levels separates sovereign-hosted enterprise suites from multi-tenant SaaS and entry-level provincial SME offerings. Price differentiation rests on certification grade and vertical integration depth, with banking-grade PDPA compliance adding substantial cost layers. Pricing pressure stems from subscription fatigue among mid-market manufacturers negotiating usage-based contracts tied to transaction volumes rather than per-seat licenses. Provincial SME clusters exhibit the highest price sensitivity, while Bangkok-headquartered universal banks prioritize compliance assurance over cost minimization.
Supply Chain Analysis
Cross-border data friction between Thailand and Singaporean hyperscaler regions dominates supply chain risk calculations for CRM vendors serving financial services clients. Geographic supply concentration centers on Singapore, Japan, and domestic Thai facilities for cloud infrastructure, with software development talent pools distributed across Bangalore, Ho Chi Minh City, and Bangkok. Raw material dependencies include specialized API middleware, LINE ecosystem integration modules, and IBM mainframe connectivity components for legacy banking system reconciliation. Single-source vulnerability runs through LINE Corporation's messaging infrastructure, which anchors social CRM functionality for Thai retailers. Distribution runs through system integrators in Ladprao district and direct enterprise sales teams targeting Silom financial districts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbent CRM vendors face substitution pressure from composable, API-first platforms that collapse traditional boundaries between sales automation and customer data platforms, requiring defensive repositioning around integration depth and regulatory certification moats.
For Market Incumbents: Harden domestic data center footprints in Bangkok and Rayong to satisfy PDPA mandates before compliance deadlines eliminate offshore-hosted alternatives from financial services procurement shortlists. Deepen vertical integration into LINE messaging infrastructure through exclusive partnership structures that lock out emerging social CRM specialists. Prioritize certification investment in BIS-adjacent software reliability standards to maintain position in state-affiliated enterprise segments where procurement timelines already stretch six to twelve months. For New Entrants and Emerging Players: Mid-market manufacturing exporters in Pathum Thani and Samut Prakan represent the most penetrable entry point, with Japanese-language lead routing capabilities and usage-based pricing models that bypass incumbent per-seat license structures. Provincial SME clusters in Chiang Mai and Phuket remain dramatically underserved by enterprise-grade vendors, creating white space for vertical-specific SaaS offerings priced below multinational subscription tiers. Go-to-market execution should anchor on channel partnerships with Ladprao-based system integrators already embedded in ERP-CRM integration projects. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across domestic cloud infrastructure build-outs as PDPA compliance mandates force localization investments that compress vendor margins. Long-term viability favors platform consolidators with existing sovereign hosting capabilities rather than pure-play SaaS providers facing escalating compliance burdens. Acquisition target archetypes include LINE-integrated social CRM specialists with established Thai banking relationships and regional system integrators holding BIS certification expertise. The signal to watch is Ministry of Digital Economy and Society enforcement actions against non-compliant offshore data processing, which would accelerate replacement demand and validate domestic infrastructure bets.| Strategic Initiative | Industry Significance |
|---|---|
| Domestic Data Center Build-out | PDPA compliance mandates eliminate offshore hosting from financial services procurement shortlists. |
| LINE Ecosystem Integration | Native chat commerce capabilities capture Thailand's dominant consumer messaging platform. |
| API-First Composable Architecture | Modular deployment collapses vendor consolidation timelines from years to quarterly sprints. |
| Usage-Based Pricing Transition | Transaction-volume contracts align with manufacturing buyer preferences in industrial zones. |
| BIS Certification Investment | Software reliability standards unlock state-affiliated enterprise procurement channels. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with CRM vendor executives, system integrators in Ladprao district, and IT procurement officers at Bangkok-headquartered banks, alongside secondary validation through Ministry of Digital Economy and Society regulatory filings, Salesforce and Microsoft hyperscaler capex disclosures, and Thai Board of Investment incentive databases. Bottom-up triangulation across deployment model, vertical application, and functional module segmentation was cross-checked against top-down market sizing derived from vendor revenue disclosures and partner ecosystem estimates.
Forecast inputs considered PDPA compliance timeline acceleration, LINE ecosystem penetration curves, and Eastern Economic Corridor industrial zone expansion patterns across the analysis window. Segmentation dimensions modeled include deployment architecture, end-user vertical, functional module maturity, and solution type concentration. CAGRs were derived from elasticity-adjusted adoption curves weighted by compliance-driven replacement cycles and greenfield manufacturing facility deployments. Industry-specific inputs incorporated IBM mainframe integration complexity premiums and BIS certification delay factors.
Practitioners should monitor PDPA enforcement action intensity and Ministry of Digital Economy and Society guideline revisions for early signals of forecast deviation. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Customer Relationship Management (CRM)
Smart Customer Service System Market
Customer Relationship Management (CRM)
Global Customer Relationship Management Market
Customer Relationship Management (CRM)
South East Asia CRM Market
Customer Relationship Management (CRM)
CRM Analytics Market
Customer Relationship Management (CRM)
Cloud CRM Market
Customer Relationship Management (CRM)
Contact Center Software Market
Customer Relationship Management (CRM)
Ipad CRM Market
Customer Relationship Management (CRM)
Customer Relationship Management in Healthcare Market
Customer Relationship Management (CRM)
Key Opinion Leader Management Market
Customer Relationship Management (CRM)
Global CRM197 Market
Customer Relationship Management (CRM)
Enterprise Feedback Management Market
Customer Relationship Management (CRM)
Loyalty Management Market
Customer Relationship Management (CRM)
Global Partner Relationship Management Market
Customer Relationship Management (CRM)
Global Customer Engagement Solutions Market
Customer Relationship Management (CRM)
Retail CRM Software Market
Customer Relationship Management (CRM)
Contact Centers Speech Applications Market