
 APAC Loyalty Management Market | 2026-2036
APAC Loyalty Management Market Size, Share, and Industry Trends Forecast 2026-2036
APAC Loyalty Management Market Outlook
Airlines and hotel chains across Southeast Asia is recalibrating how loyalty currency gets issued and burned, shifting from static point accrual toward dynamic, activity-based earn models. Capillary Technologies dominates the India-Southeast Asia corridor through its merchant coalition network, while Oracle Corporation leverages cloud-native architecture to serve large financial services clients across Singapore and Hong Kong. IBM Corporation competes on AI-driven predictive redemption engines that anticipate member behavior before purchase intent forms.
Loyalty management encompasses the design, operation, and optimization of structured reward programs that use data analytics to influence repeat purchase behavior and customer lifetime value, typically deploying cloud-based platforms with real-time API connectivity to point-of-sale systems and mobile wallets. The technology stack splits into cloud-based solutions, which anchor enterprise-grade deployments for retail and banking clients requiring elastic compute for transaction spikes, and AI analytics, where margin pools concentrate as vendors charge premium fees for predictive churn and next-best-action modeling. Mobile applications represent the fastest-growing delivery layer, particularly in Indonesia and Vietnam where smartphone-first consumers bypass traditional card-based enrollment.
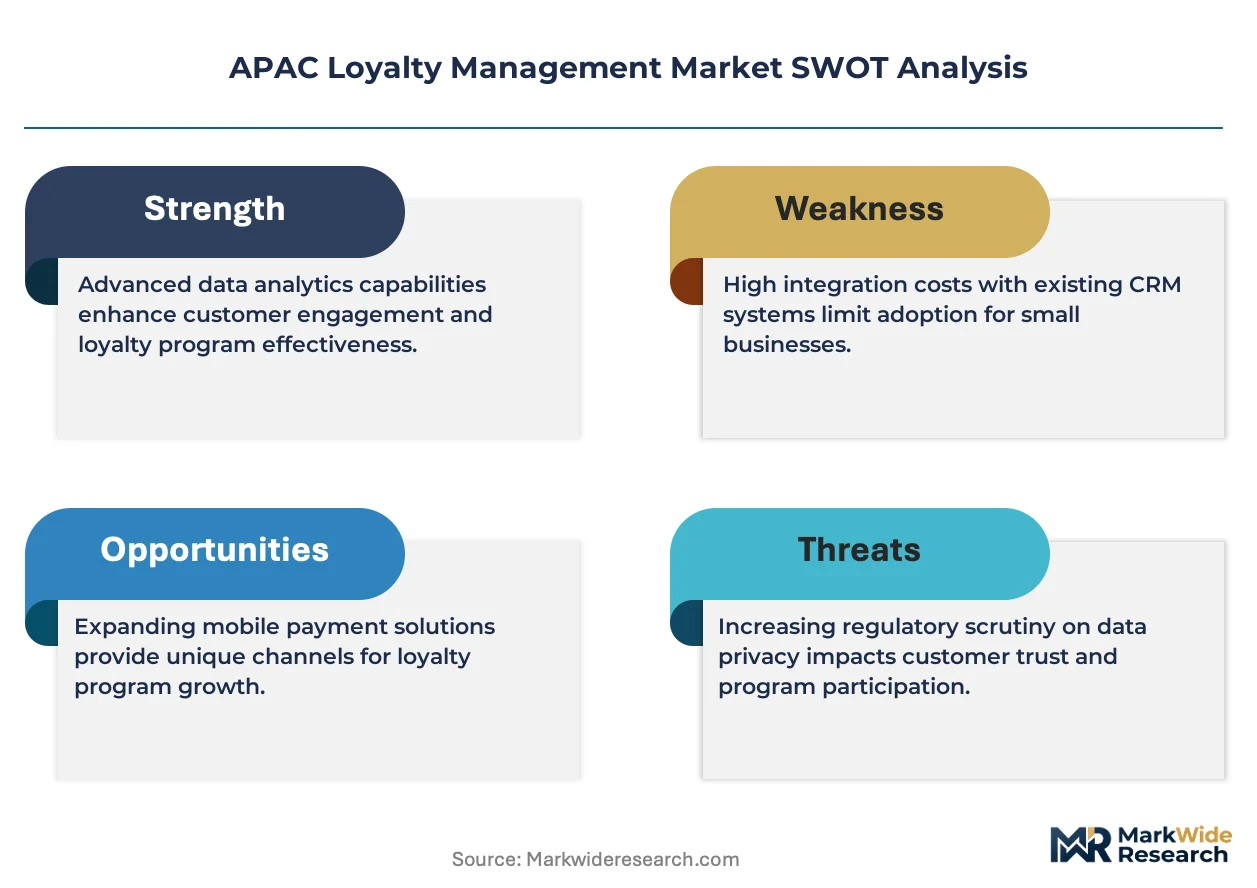
India's RBI mandates data localization for payment systems, compelling loyalty platforms to maintain domestic server infrastructure and reshaping vendor selection criteria for foreign entrants. Australia's ACCC scrutinizes coalition program data-sharing practices, while Singapore's PDPA imposes consent-layer requirements on cross-border member data flows that elevate compliance costs for regional program operators. Stakeholders must weigh whether to build proprietary redemption marketplaces or embed into super-app ecosystems controlled by dominant consumer internet platforms.
Market Dynamics
Coalition loyalty networks across Southeast Asia are fragmenting into closed-loop ecosystems controlled by super-apps, forcing standalone program operators to choose between platform subordination and marginalization. This structural tension between open interoperability and walled-garden retention mechanics is redrawing competitive boundaries.
Growth Catalysts
- RBI's UPI Integration Mandate:India's real-time payment rails enable instant reward redemption at merchant point-of-sale, eliminating settlement friction that previously delayed point-burn transactions.
- Travel Expenditure Rebound:Airlines and hotel chains across Thailand, Singapore, and Indonesia are expanding cross-brand earning partnerships to capture pent-up leisure and business travel demand.
- AI Analytics Layer:Predictive churn modeling and next-best-action engines are converting loyalty programs from cost centers into revenue-generating customer intelligence platforms.
Market Restraints
- Data Localization Requirements:India's RBI mandates domestic server infrastructure for payment-adjacent loyalty data, elevating capital costs for foreign platform entrants.
- Super-App Platform Control:Grab, Gojek, and Alipay+ ecosystems in Southeast Asia restrict third-party loyalty API access, compressing independent program operator margins.
- Consent-Layer Compliance:Singapore's PDPA imposes granular opt-in requirements on cross-border member data flows, increasing operational complexity for regional coalition operators.
Strategic Opportunities
- Vietnam's Smartphone-First Market:Mobile-native consumers bypass traditional card enrollment, creating greenfield opportunity for app-only loyalty deployments without legacy infrastructure drag.
- Australia's Banking Consolidation:Major banks are unifying fragmented card-linked offer platforms into single digital wallets, opening vendor replacement cycles.
- Embedded Finance Convergence:Integration of loyalty points with buy-now-pay-later and micro-insurance products is creating new redemption liquidity pools.
Industry Challenges
- Legacy System Integration:Core banking and airline reservation systems built on 1990s architectures resist real-time API connectivity, forcing expensive middleware development.
- Specialized Talent Scarcity:Shortage of engineers fluent in both payment protocol compliance and machine learning operations constrains platform scaling.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | APAC Loyalty Management Market |
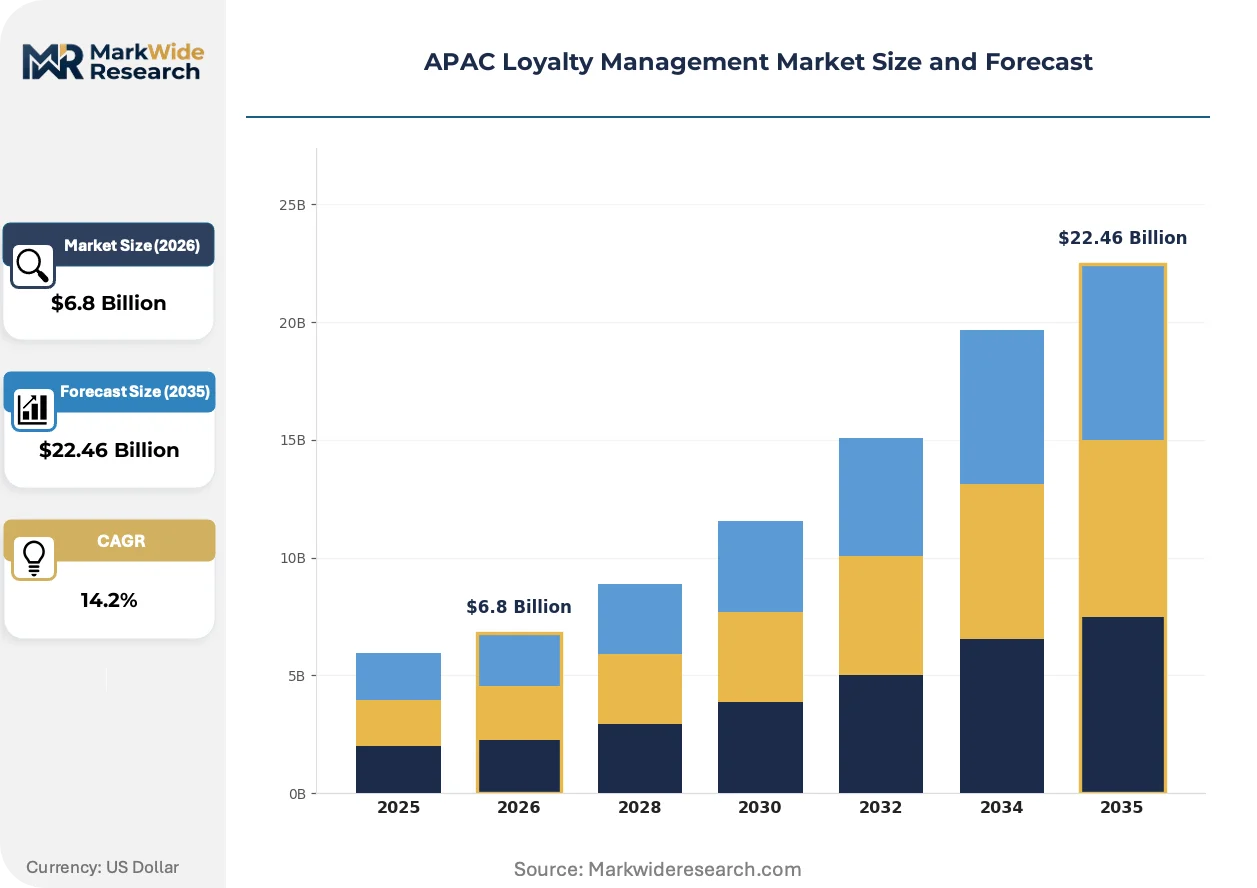
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $22.46 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Customer Type: Individuals, Corporations, Retailers, Restaurants Service Type: Consulting, Technology Implementation, Program Management, Data Analytics Industry Vertical: Retail, Travel & Hospitality, Financial Services, Healthcare Technology: Cloud-Based Solutions, Mobile Applications, CRM Integration, AI Analytics |
| Companies Covered | Epsilon Data Management LLC, Capillary Technologies, Aimia Inc., IBM Corporation, Oracle Corporation, Edenred SA, Maritz Holdings Inc., TIBCO Software Inc., Comarch SA, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
APAC Loyalty Management Market Strategic Shifts
Program architectures are pivoting from static point accrual toward dynamic, behavior-triggered reward mechanics that respond to real-time transaction context and predicted future value.
Blockchain-based point tokenization is integrating with existing loyalty infrastructure to enable cross-program liquidity and fractional redemption. Singaporean banks and Australian retailers are piloting interoperable token standards that allow members to consolidate fragmented balances across competing programs. This technology is integrating previously siloed reward currencies into unified digital asset layers, compressing the technical barriers that historically prevented coalition expansion.
Australia's ACCC is scrutinizing data-sharing practices within coalition loyalty programs, particularly how member transaction histories flow between non-competing retail partners. The regulator's focus on consumer transparency is forcing program operators to restructure consent frameworks and disclosure mechanisms. Banking and grocery retail sectors are responding by unilaterally publishing data-sharing protocols to preempt enforcement action.
Indonesian and Vietnamese consumers are bypassing traditional enrollment channels entirely, demanding instant program access through embedded wallet interfaces rather than standalone applications. This channel shift is displacing card-based acquisition models and forcing program operators to distribute through super-app marketplaces. Quick-service restaurant and ride-hailing verticals are experiencing the most acute pressure to embed loyalty mechanics directly into payment completion flows.
APAC Loyalty Management Market Segmentation
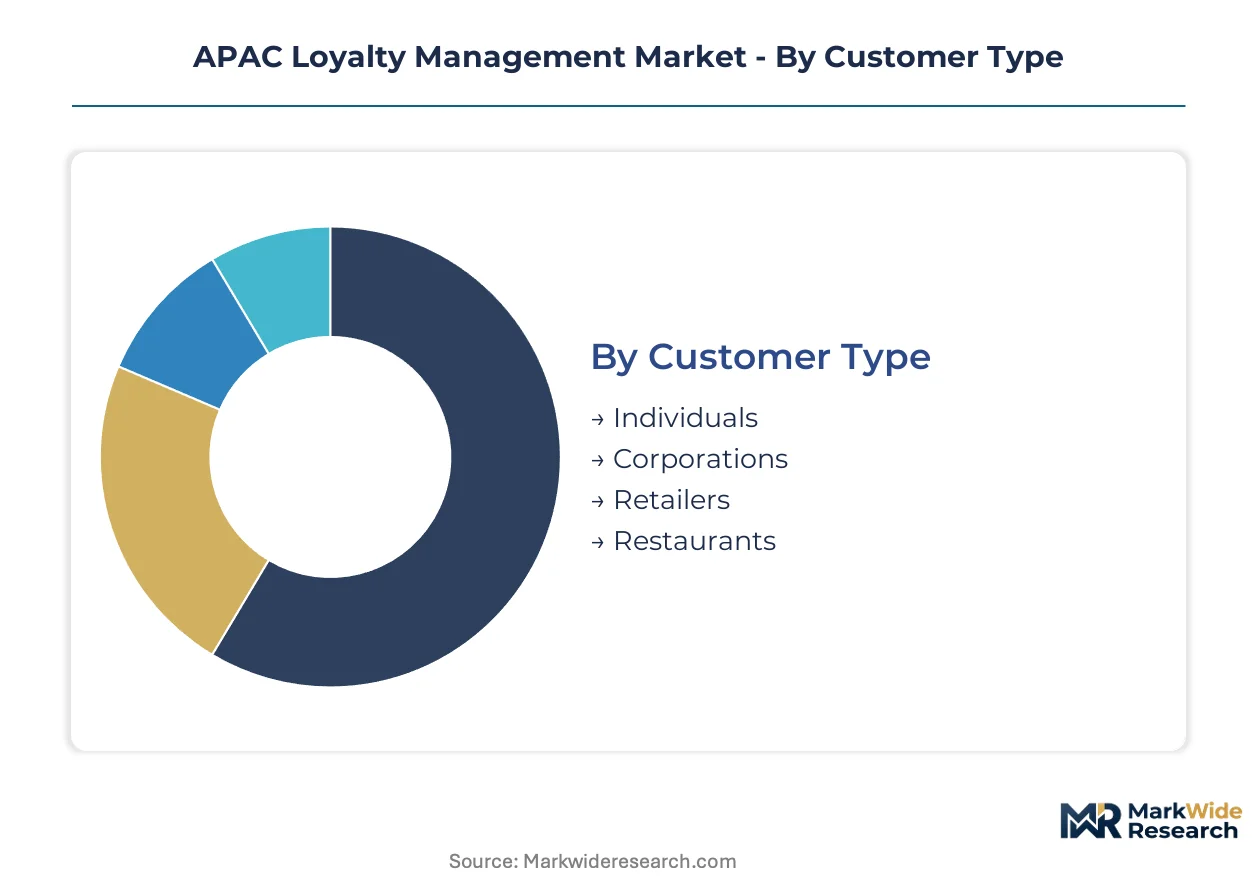
APAC loyalty management platforms serve divergent integration requirements across standalone deployments and embedded super-app ecosystems. Customer sophistication and regulatory complexity determine whether buyers prioritize modular toolkits or fully managed service bundles.
Customer Type:
Integration depth varies sharply: individuals interact through wallet-embedded interfaces while enterprises demand API-native infrastructure for proprietary control.
- Individuals:Smartphone-first consumers in Indonesia and Vietnam access loyalty mechanics through embedded wallet interfaces rather than standalone applications. This channel shift compresses acquisition costs for program operators but cedes data ownership to super-app platforms.
- Corporations:Enterprise procurement teams negotiate API-level integrations with existing expense management systems, prioritizing real-time reconciliation and consolidated billing across multiple markets.
- Retailers:Mid-market chains favor white-label coalition participation over proprietary program development, reducing capital expenditure while accessing pooled member bases.
- Restaurants:Quick-service operators embed loyalty triggers directly into payment completion flows, capturing transaction context without requiring separate app downloads.
Individuals lead volumes today; corporations are gaining share fastest as procurement centralization accelerates across multinational accounts.
Service Type:
Margin concentration follows capability scarcity: specialized engineering talent commands premium pricing in technology implementation while program management commoditizes.
- Consulting:Advisory services concentrate on coalition architecture design and regulatory compliance navigation for entrants to India and Singapore markets. FSSAI and RBI mandates elevate demand for localization expertise.
- Technology Implementation:Systems integrators bridge legacy core banking and airline reservation platforms with cloud-native loyalty engines, commanding fees proportional to middleware complexity.
- Program Management:Outsourced operations cover member communications, reward fulfillment, and partner settlement, typically priced on transaction volume rather than fixed retainer.
- Data Analytics:Predictive churn modeling and next-best-action engines convert loyalty programs from cost centers into revenue-generating customer intelligence platforms.
Technology implementation leads volumes today; data analytics is expanding most quickly as banks and airlines prioritize predictive capabilities.
Industry Vertical:
Application intensity determines deployment architecture: travel and hospitality demand real-time currency conversion while retail prioritizes SKU-level attribution.
- Retail:Grocery and department store chains deploy card-linked offer platforms with unified digital wallets, consolidating fragmented legacy systems into single customer views.
- Travel & Hospitality:Airlines and hotel chains across Thailand, Singapore, and Indonesia expand cross-brand earning partnerships to capture rebounding leisure and business travel expenditure.
- Financial Services:Australia's major banks unify fragmented card-linked offer platforms, opening vendor replacement cycles for integrated loyalty-wallet solutions.
- Healthcare:Pharmacy retail and wellness providers pilot behavior-triggered reward mechanics tied to prescription adherence and preventive care milestones.
Retail leads volumes today; financial services is climbing the fastest as banking consolidation accelerates across Australia and Southeast Asia.
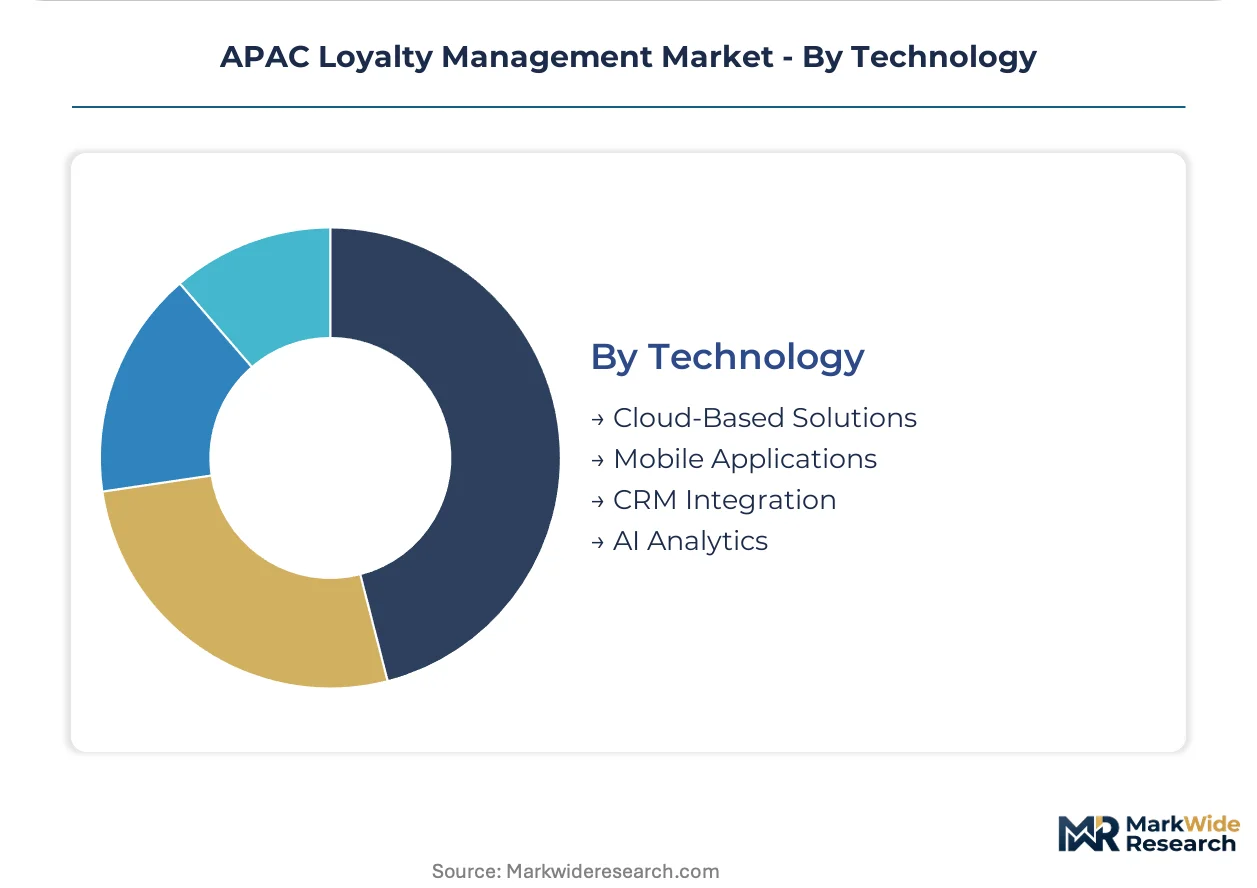
Technology:
Maturity gradients separate proven infrastructure from emerging capabilities: cloud and mobile anchor current deployments while AI analytics captures expanding margin pools.
- Cloud-Based Solutions:Enterprise-grade deployments for retail and banking clients require elastic compute for transaction spikes, with data localization mandates compelling domestic server infrastructure in India.
- Mobile Applications:Smartphone-first consumers in Indonesia and Vietnam bypass traditional card-based enrollment entirely, creating greenfield opportunity for app-only loyalty deployments.
- CRM Integration:Synchronization with existing customer data platforms enables unified identity resolution across online and offline touchpoints, though legacy system resistance elevates implementation cost.
- AI Analytics:Predictive redemption engines anticipate member behavior before purchase intent forms, charging premium fees for churn prevention and lifetime value optimization.
Cloud-based solutions lead volumes today; mobile applications are gaining share fastest as super-app distribution displaces standalone enrollment channels.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Singapore's fintech corridor anchors APAC loyalty management demand, hosting regional headquarters for coalition program operators and cloud-native platform vendors serving Southeast Asian markets.
India
RBI's UPI integration mandate and data localization requirements for payment-adjacent systems are reshaping vendor selection criteria for foreign entrants. Domestic server infrastructure investments concentrate in Mumbai and Bengaluru, where Capillary Technologies maintains merchant coalition networks. The National Payments Corporation of India processes real-time reward redemptions at merchant point-of-sale, eliminating settlement friction that previously delayed point-burn transactions.
Australia
ACCC scrutiny of coalition program data-sharing practices is forcing restructuring of consent frameworks and disclosure mechanisms. Sydney and Melbourne host banking sector consolidation efforts, with major institutions unifying fragmented card-linked offer platforms into single digital wallets. The regulator's focus on consumer transparency has prompted unilateral publication of data-sharing protocols in grocery retail and financial services sectors.
Singapore
PDPA consent-layer requirements on cross-border member data flows elevate compliance costs for regional program operators. The Monetary Authority of Singapore licenses digital banking frameworks that embed loyalty mechanics into payment completion flows. Marina Bay and Raffles Place financial districts host pilot programs for blockchain-based point tokenization enabling cross-program liquidity.
Indonesia
Smartphone-first consumers in Jakarta and Surabaya bypass traditional card-based enrollment entirely, demanding instant program access through embedded wallet interfaces. Super-app distribution channels displace standalone enrollment, compressing acquisition costs for program operators while ceding data ownership to dominant consumer internet platforms. Quick-service restaurant and ride-hailing verticals experience acute pressure to embed loyalty triggers directly into payment flows.
Vietnam
Mobile-native consumers in Ho Chi Minh City and Hanoi create greenfield opportunity for app-only loyalty deployments without legacy infrastructure drag. The State Bank of Vietnam's digital payment push enables real-time reward issuance through domestic wallet providers. Quick-service operators embed loyalty mechanics into payment completion flows, capturing transaction context without requiring separate application downloads.
APAC Loyalty Management Market Competitive Environment
Strategic partnerships dominate the current landscape as platform vendors seek super-app distribution channels and banks pursue unified wallet solutions. The vendor base organizes around three tiers: cloud-native specialists serving mid-market retail, enterprise systems integrators bridging legacy infrastructure, and AI analytics boutiques commanding premium fees for predictive capabilities. Competitive moves concentrate on API-level integrations with existing expense management systems and embedded finance convergence with buy-now-pay-later products.
Within the enterprise systems integration tier, IBM Corporation and Oracle Corporation anchor competing approaches to predictive redemption engines and cloud-native architecture for financial services clients. Capillary Technologies occupies a distinct position across the India-Southeast Asia corridor through merchant coalition network density. These three exemplify how geographic specialization and technology stack differentiation create defensible market positions against super-app platform consolidation pressures.
| Leading Market Players |
|---|
| Epsilon Data Management LLC |
| Capillary Technologies |
| Aimia Inc. |
| IBM Corporation |
| Oracle Corporation |
| Edenred SA |
| Maritz Holdings Inc. |
| TIBCO Software Inc. |
| Comarch SA |
| Others |
Value Chain & Pricing Dynamics
Horizontal integration across cloud infrastructure and merchant acquisition networks anchors pricing power for loyalty platform vendors serving Southeast Asian markets. This consolidation pattern compresses margins for standalone operators while enabling integrated providers to capture premium fees for AI analytics capabilities.
Pricing Analysis
Input-cost pass-through from data localization mandates and specialized engineering talent elevates pricing for foreign entrants to India and Singapore markets. Three-tier pricing structure across enterprise, mid-market, and self-serve levels dominates, with differentiation driven by API call volume and predictive analytics depth. Cost compression in mid-market SaaS tiers is intensifying because super-app platform fees absorb distribution margins. Retail banking procurement teams exhibit highest price sensitivity, while airline loyalty divisions prioritize capability over cost.
Supply Chain Analysis
Direct-to-enterprise channels handle hyperscale buyer demand across Australia's banking consolidation and Singapore's fintech corridor. Software development concentrates in India, cloud infrastructure in Singapore, and merchant network operations across Indonesia and Vietnam. Platform delivery draws from API gateway services, machine learning operations tooling, and payment rail integrations. Single-source vulnerability runs through dominant super-app distribution channels. Distribution runs through systems integrators and direct sales teams.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Quality specifications are hardening as enterprise buyers demand real-time predictive capabilities and regulatory-compliant data architectures. This late-cycle shift favors vendors with proven AI analytics layers and domestic infrastructure investments.
For Market Incumbents: Anchor defensive positioning through backward integration into proprietary merchant coalitions and captive AI analytics development. Super-app platform consolidation threatens margin capture; counter by deepening direct API relationships with Australia's major banks and India's National Payments Corporation infrastructure.
For New Entrants and Emerging Players: Begin with Vietnam's smartphone-first market and Indonesia's quick-service restaurant verticals, where legacy infrastructure drag is minimal and super-app embedding requirements remain negotiable. White-label program management for mid-market retail chains offers the most penetrable entry path.
For Investors and Strategic Acquirers: Consolidation pressure builds where AI analytics boutiques lack cloud-native infrastructure scale and merchant network density. Long-term viability hinges on cross-program interoperability capabilities and regulatory compliance automation. Watch blockchain-based point tokenization pilots in Singapore as inflection signal for technical architecture shifts.
| Strategic Initiative | Industry Significance |
|---|---|
| AI Analytics Layer Investment | Predictive churn engines convert loyalty programs from cost centers into revenue-generating intelligence platforms. |
| Domestic Infrastructure Deployment | RBI data localization mandates require Mumbai and Bengaluru server investments for payment-adjacent operations. |
| Super-App API Partnership | Embedded wallet distribution in Grab and Gojek ecosystems compresses acquisition costs but cedes data ownership. |
| Blockchain Tokenization Pilot | Singaporean banks test interoperable standards for cross-program liquidity and fractional redemption mechanics. |
| Banking Sector Consolidation Play | Australia's major banks unify fragmented card-linked offer platforms, opening vendor replacement cycles. |
Study Parameters
Direct dialogue with loyalty platform CTOs, airline revenue management directors, bank digital wallet product heads, and merchant coalition network operators grounded qualitative findings. Secondary validation drew from RBI circulars, Singapore PDPA guidance, ACCC enforcement notices, and NPCI transaction disclosures. Bottom-up modeling of vendor deployments triangulated against top-down market sizing from cloud infrastructure spend and payment rail volumes.
Segmented outputs across customer type, service tier, industry vertical, and technology stack populated the analytical framework across the projection horizon. Deployment architecture, regulatory compliance burden, and merchant network density served as industry-specific forecast inputs. CAGRs derived from elasticity modeling of technology adoption curves and procurement cycle timing.
Several conditions sit outside the modeled scope, including geopolitical disruption to cross-border data flows, super-app platform acquisition by global technology conglomerates, and central bank digital currency integration mandates. Forecasts reflect documented assumptions about UPI expansion velocity and airline travel recovery trajectories. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Customer Relationship Management (CRM)
Global Partner Relationship Management Market
Customer Relationship Management (CRM)
CRM Outsourcing Market
Customer Relationship Management (CRM)
Retail CRM Software Market
Customer Relationship Management (CRM)
Loyalty Management Solutions Market
Customer Relationship Management (CRM)
Ipad CRM Market
Customer Relationship Management (CRM)
Call Center Market
Customer Relationship Management (CRM)
Indonesia CRM Software Market
Customer Relationship Management (CRM)
CRM Application Software Market
Customer Relationship Management (CRM)
Loyalty Management Market
Customer Relationship Management (CRM)
Contact Centers Speech Applications Market
Customer Relationship Management (CRM)
Global Customer Engagement Solutions Market
Customer Relationship Management (CRM)
Global Customer Success Platforms Market
Customer Relationship Management (CRM)
Cloud CRM Market
Customer Relationship Management (CRM)
Europe Cloud CRM Market
Customer Relationship Management (CRM)
Global CRM197 Market
Customer Relationship Management (CRM)
CRM Analytics Market