
 Pharmaceutical Customer Relationship Management (CRM) Software Market | 2026-2036
Pharmaceutical Customer Relationship Management (CRM) Software Market Size, Share, and Industry Trends Forecast 2026-2036
Pharmaceutical Customer Relationship Management (CRM) Software Market Analytics
Buyer concentration among mid-sized specialty pharmaceutical manufacturers is restructuring how vendors allocate R&D resources and field support capacity. Salesforce leverages its healthcare-specific data architecture to sustain multi-tenant scalability across diverse therapeutic portfolios. Veeva Systems anchors its competitive position through deep compliance tooling purpose-built for life sciences engagement tracking. Oracle competes by extending enterprise resource planning integration paths that unify commercial and clinical data streams.
Pharmaceutical Customer Relationship Management (CRM) Software constitutes a regulated information system that manages stakeholder interactions across the drug commercialization lifecycle, incorporating audit trails, consent management, and territory alignment algorithms to satisfy pharmacovigilance and promotional compliance mandates. Cloud-based deployments now lead new installations as manufacturers prioritize elastic infrastructure over capital-intensive on-premise maintenance, while hybrid architectures retain traction among organizations managing multi-country data residency requirements. Medical representatives represent the fastest-growing customer type as field forces demand mobile-first engagement analytics synchronized with healthcare provider prescribing patterns.
FDA 21 CFR Part 11, HIPAA privacy safeguards, and EMA's pharmacovigilance guidelines collectively elevate compliance infrastructure from feature checklist to procurement gatekeeper across North American and European deployments. The EU AI Act introduces emerging obligations for algorithmic transparency in physician targeting and next-best-action recommendation engines. Stakeholders must monitor how divergent data localization requirements between FDA jurisdiction and emerging Asian regulatory frameworks reshape cloud architecture decisions and vendor qualification timelines.
Market Dynamics
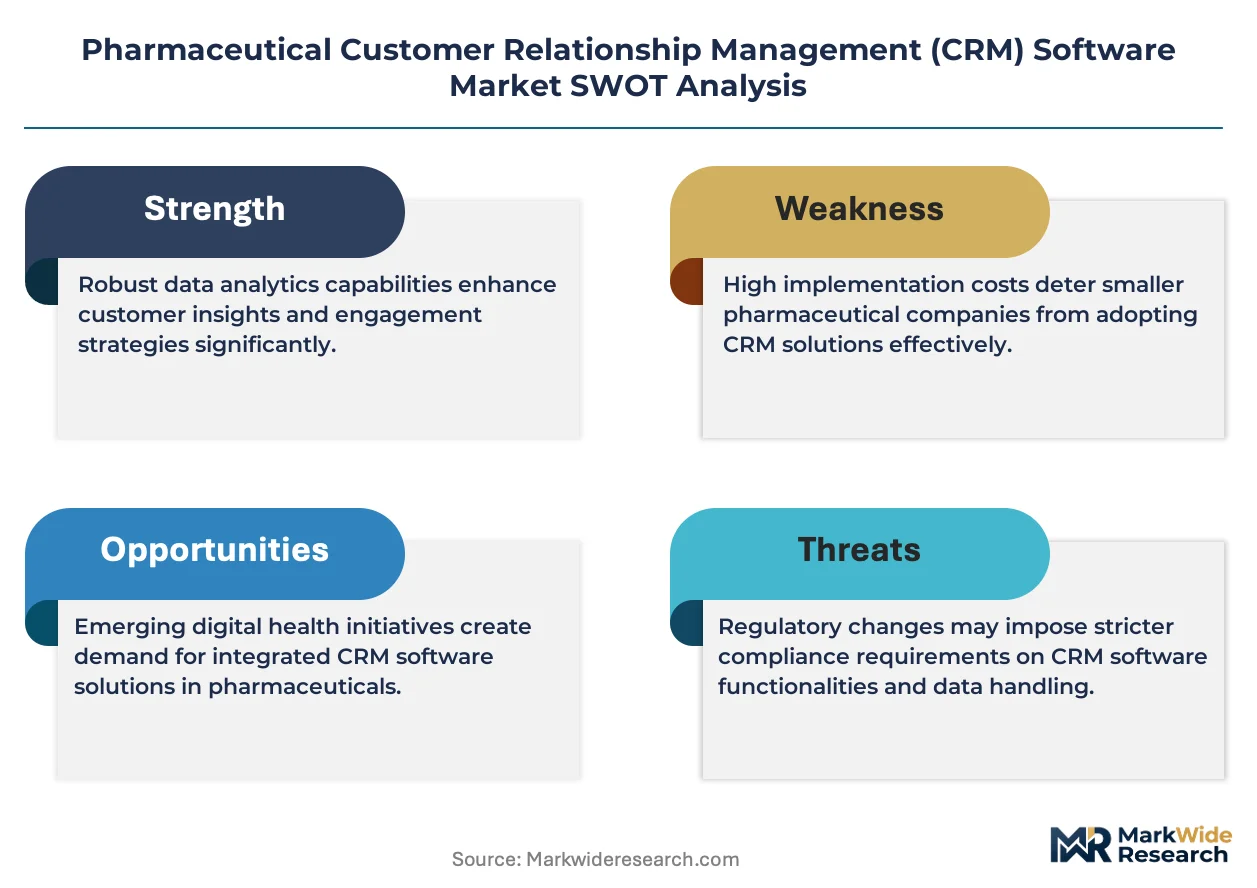
Cloud-native architectures are compressing deployment timelines for pharmaceutical CRM systems while FDA 21 CFR Part 11 validation protocols force parallel infrastructure investments that strain mid-sized manufacturer budgets.
Growth Catalysts
- Specialty pharmaceutical expansion:Complex physician networks in oncology and rare disease portfolios require sophisticated territory alignment algorithms that legacy systems cannot support.
- EMA pharmacovigilance integration:European safety reporting mandates now require bidirectional CRM-to-vigilance data flows, creating upgrade urgency across continental deployments.
- Mobile-first field force requirements:Medical representatives demand real-time prescribing pattern synchronization with offline capability in low-connectivity hospital environments.
Market Restraints
- Multi-tenant data residency conflicts:Divergent localization requirements between FDA jurisdiction and China's NMPA fragment cloud architecture strategies.
- Validation cost escalation:Computerized system validation for 21 CFR Part 11 compliance consumes 18-24 month implementation windows regardless of vendor selection.
- Legacy ERP entrenchment:Deep integration dependencies with on-premise Oracle and SAP installations slow cloud migration timelines for established manufacturers.
Strategic Opportunities
- AI-driven next-best-action engines:Algorithmic physician targeting remains underdeveloped in emerging markets where first-mover vendors capture standardization advantages.
- Real-world evidence linkage:Convergence of CRM engagement data with patient registry platforms enables outcome-based contracting with integrated delivery networks.
- Brazil's ANVISA digital transformation:Latin America's largest pharmaceutical market is modernizing promotional oversight, creating compliance tooling demand without entrenched vendor relationships.
Industry Challenges
- Cross-functional talent scarcity:Professionals combining life sciences domain knowledge with cloud architecture expertise command premium compensation that mid-sized manufacturers struggle to match.
- Hybrid integration complexity:Synchronizing cloud CRM with on-premise clinical trial management systems requires custom middleware development that extends project timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pharmaceutical Customer Relationship Management (CRM) Software Market |
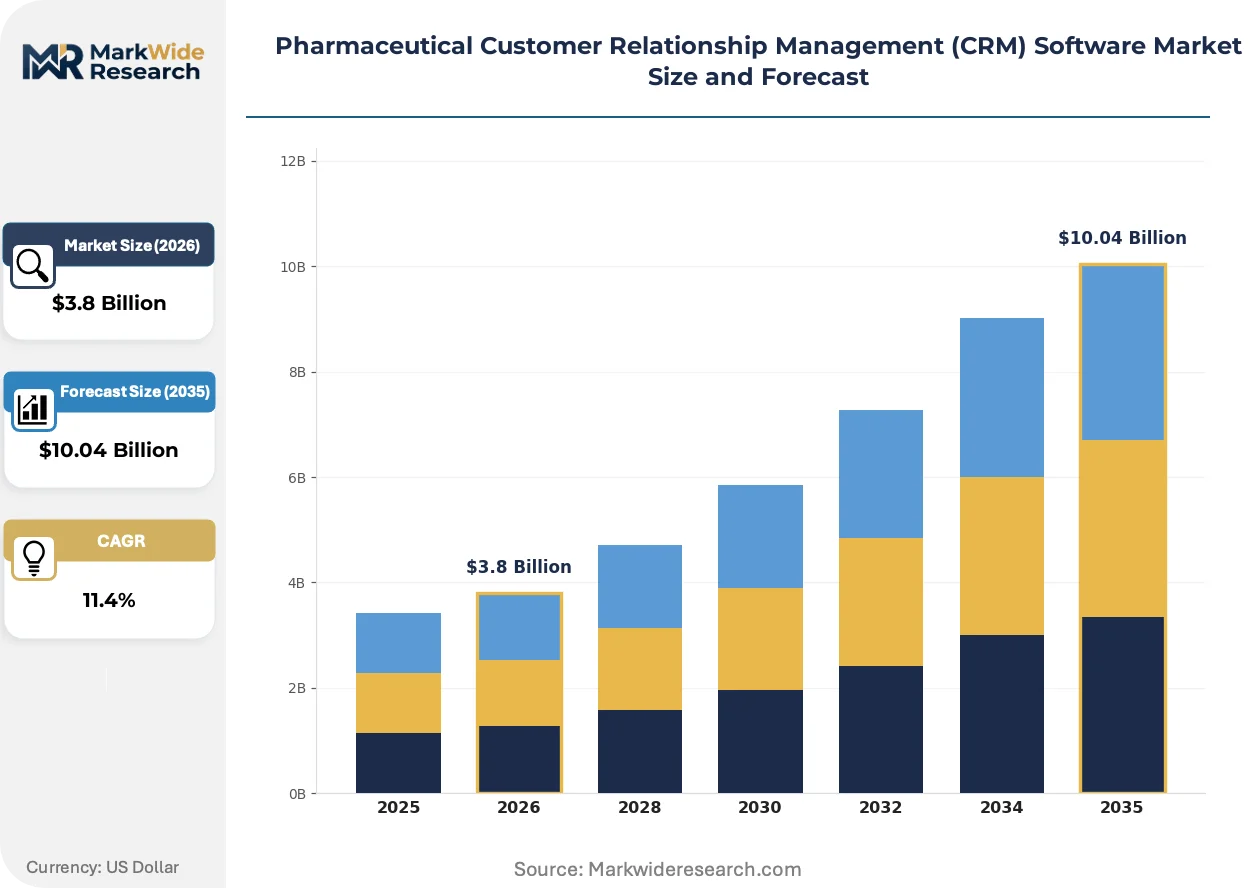
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $10.04 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: On-Premise, Cloud-Based, Hybrid, Mobile End User: Pharmaceutical Manufacturers, Distributors, Wholesalers, Healthcare Providers Deployment Model: Public Cloud, Private Cloud, Community Cloud, Hybrid Cloud Customer Type: Direct Sales Teams, Marketing Agencies, Customer Support, Medical Representatives |
| Companies Covered | Salesforce, SAP, Oracle, Microsoft, Veeva Systems, Kapture, Exeevo, Medsimo Technologies, Actis Sales Technologies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pharmaceutical Customer Relationship Management (CRM) Software Market Evolving Landscape
Artificial intelligence is penetrating core CRM workflows while regulatory frameworks evolve to govern algorithmic decision-making in physician engagement.
Natural language processing is automating call note transcription and sentiment analysis for medical representative interactions. Specialty pharmaceutical manufacturers deploying field forces exceeding 500 representatives are adopting these tools at accelerated rates. The technology is automating compliance documentation that previously required manual quality assurance review.
The EU AI Act's risk classification system now governs physician targeting algorithms deployed within European Economic Area boundaries. High-risk designations trigger conformity assessment obligations that extend procurement cycles by four to six months. Veeva Systems and Salesforce are restructuring their European recommendation engines to satisfy algorithmic transparency requirements.
Subscription-based pricing models are displacing perpetual license structures across enterprise pharmaceutical deployments. Procurement functions within top-20 manufacturers now mandate consumption-based contracts that align vendor compensation with active user counts. This shift is most visible in United States commercial operations where quarterly renegotiation cycles have become standard practice.
Pharmaceutical Customer Relationship Management (CRM) Software Market Segmentation
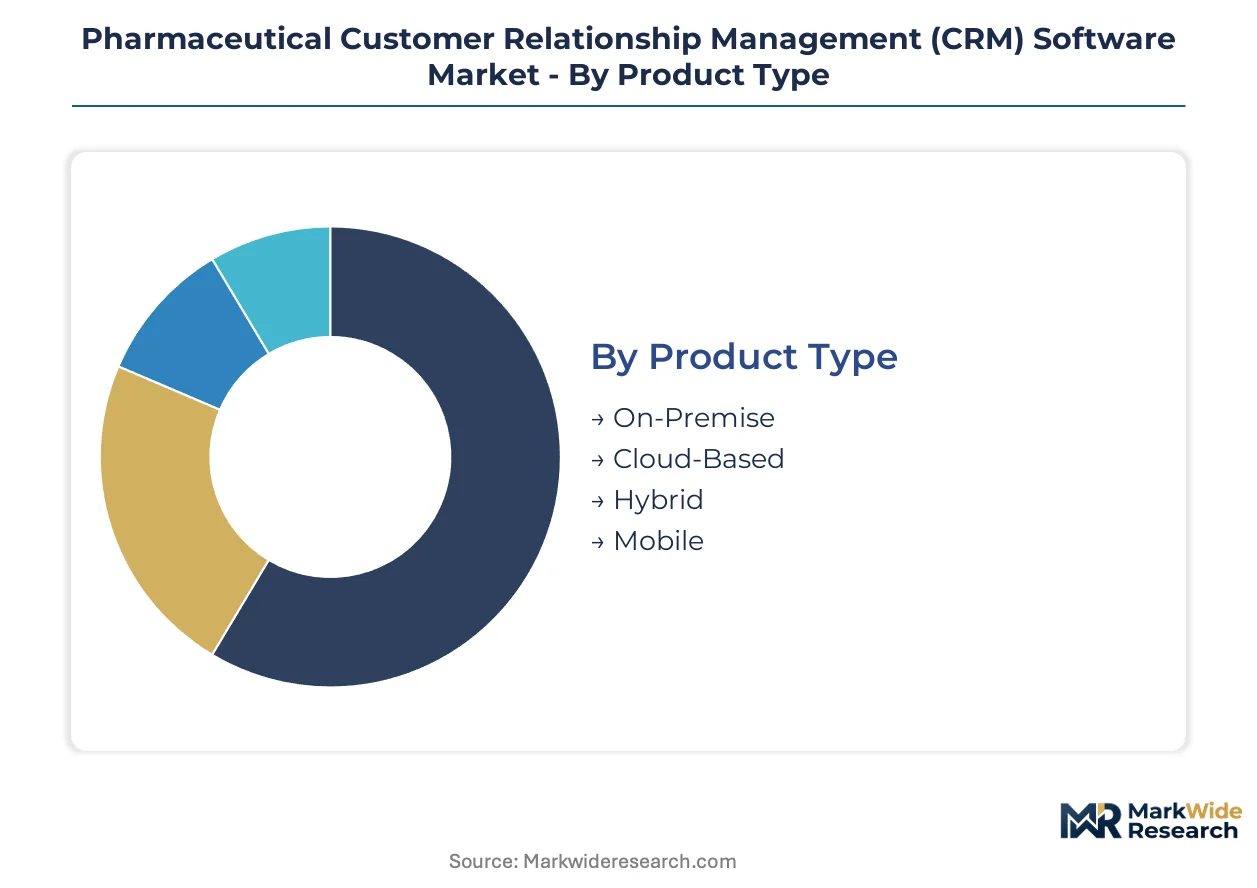
CRM segmentation in pharmaceutical markets reflects divergent compliance burdens and infrastructure maturity across manufacturer tiers. Deployment choices directly determine validation timelines, data residency capabilities, and integration complexity with existing enterprise systems.
Product Type:
Standalone deployments dominate regulated environments requiring isolated audit trails, while embedded configurations proliferate in digitally native specialty manufacturers seeking rapid implementation.
- Cloud-Based:Multi-tenant architectures with elastic compute provisioning serve mid-sized manufacturers prioritizing operational expenditure models over capital deployment. Demand clusters among oncology and rare disease specialists in Boston and San Francisco where territory alignment algorithms require continuous recalibration. FDA 21 CFR Part 11 validation protocols still impose 18-24 month implementation windows despite vendor-managed infrastructure.
- On-Premise:Dedicated hardware installations maintain complete data sovereignty for manufacturers managing multi-country pharmacovigilance reporting. Large established pharmaceutical companies with deep Oracle and SAP integration dependencies retain these configurations to minimize disruption to clinical trial management system linkages. Capital intensity and internal IT staffing requirements constrain adoption among emerging manufacturers.
- Hybrid:Split architectures segregate promotional content in cloud environments while retaining patient-level data on local servers. This configuration addresses EMA pharmacovigilance data localization requirements without sacrificing field force mobility tools.
- Mobile:Native applications with offline synchronization capabilities support medical representatives in low-connectivity hospital environments. Touch-optimized interfaces dominate field force equipment refresh cycles.
Volume placements concentrate in Cloud-Based configurations; the faster expansion belongs to Mobile deployments.
End User:
Cost tier differentiation separates enterprise manufacturers investing in full-suite platforms from downstream intermediaries adopting modular point solutions.
- Pharmaceutical Manufacturers:Enterprise-grade deployments with integrated consent management and territory alignment engines serve commercial operations exceeding 500 field representatives. Specialty pharmaceutical expansion in immunology and gene therapy portfolios drives sophisticated physician network mapping requirements. These implementations demand bidirectional CRM-to-vigilance data flows satisfying EMA safety reporting mandates.
- Healthcare Providers:Integrated delivery networks and hospital systems deploy lightweight engagement tracking for formulary committee interactions. Academic medical centers in New Jersey and Pennsylvania prioritize outcome-based contracting analytics over promotional campaign management.
- Distributors:Inventory-aware CRM modules linking commercial engagement with supply chain visibility serve wholesale purchasing cooperative networks. Margin compression in generic pharmaceutical distribution limits investment scope.
- Wholesalers:Transaction-focused systems emphasizing account profitability and rebate management predominate. These deployments rarely require FDA validation protocols given minimal direct healthcare provider engagement.
Revenue concentration sits with Pharmaceutical Manufacturers; Healthcare Providers are climbing the fastest as value-based care models deepen engagement tracking requirements.
Deployment Model:
Application criticality determines infrastructure isolation levels, with promotional compliance systems demanding stricter segmentation than internal analytics platforms.
- Private Cloud:Single-tenant environments with dedicated physical infrastructure serve top-20 manufacturers managing multi-therapeutic portfolio data segregation. These deployments satisfy China's NMPA data residency requirements without sacrificing European accessibility. Premium pricing reflects customized validation documentation and dedicated support entitlements.
- Public Cloud:Shared infrastructure with logical tenant separation dominates emerging market entries and mid-cap specialty manufacturers. Brazil's ANVISA digital transformation creates first-mover opportunities without entrenched vendor relationships. Consumption-based pricing aligns vendor compensation with active user counts.
- Community Cloud:Industry-specific multi-tenant architectures pre-validated for FDA 21 CFR Part 11 reduce implementation timelines for consortium members. These configurations appeal to mid-sized manufacturers lacking internal validation expertise.
- Hybrid Cloud:Dynamic workload placement between private and public infrastructure responds to fluctuating computational demands during product launch periods. Complexity management requires specialized cloud architecture talent commanding premium compensation.
Contract value concentrates in Private Cloud engagements; Public Cloud deployments are gaining share fastest among digitally transforming mid-market entrants.
Customer Type:
Maturity differentiation separates established field forces with legacy workflow expectations from emerging customer support functions adopting AI-first engagement tools.
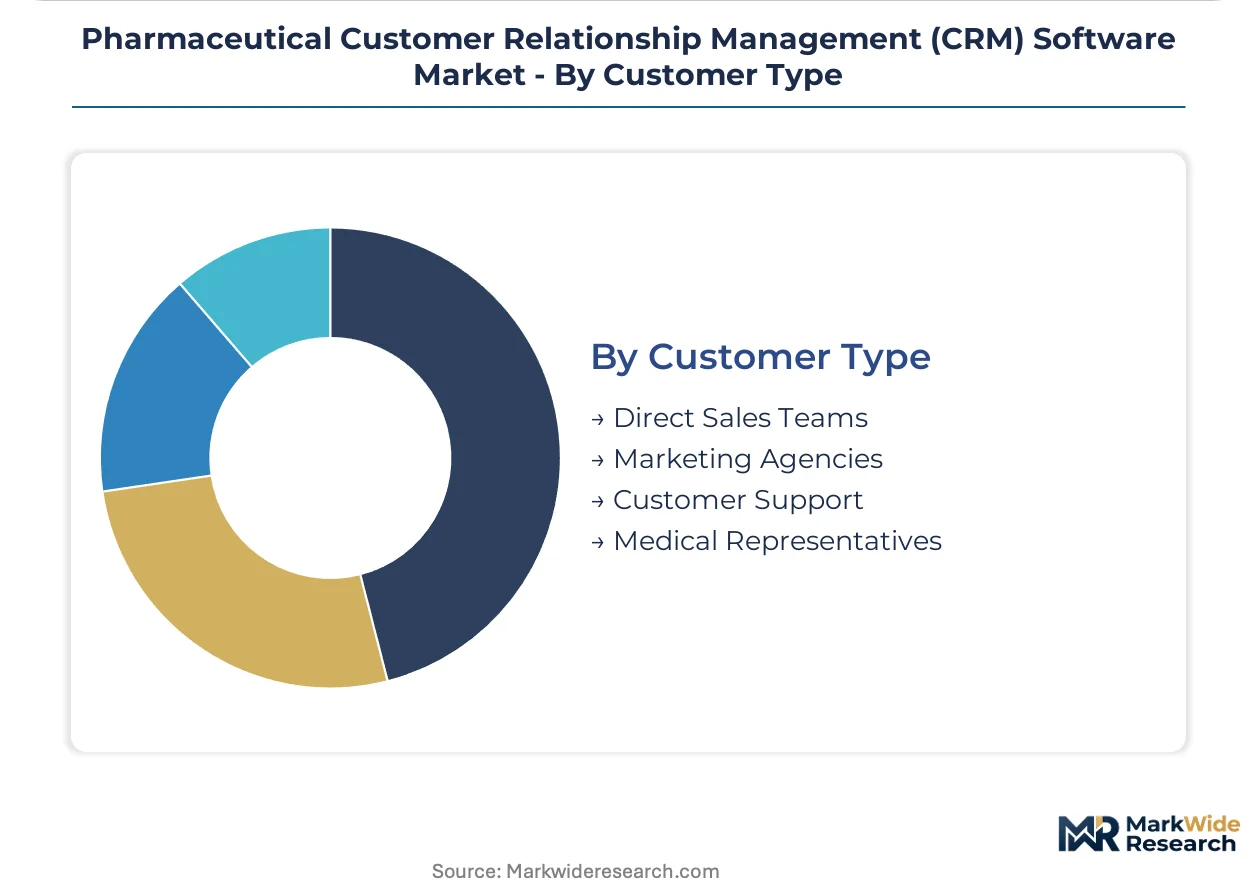
- Medical Representatives:Field-deployed professionals requiring real-time prescribing pattern synchronization represent the steepest expansion trajectory. Natural language processing automates call note transcription and sentiment analysis for compliance documentation. Specialty pharmaceutical manufacturers deploying forces exceeding 500 representatives adopt these mobile-first tools at accelerated rates.
- Direct Sales Teams:Account executives managing key opinion leader relationships utilize territory alignment algorithms optimizing physician engagement frequency. These users demand seamless offline capability during hospital access restrictions.
- Marketing Agencies:External promotional partners access restricted CRM modules through federated identity systems. Data residency constraints limit cross-border campaign management capabilities.
- Customer Support:Pharmacovigilance case intake and medical information request handling functions integrate with CRM engagement histories. AI-driven next-best-action engines remain underdeveloped in this segment.
User volume concentrates in Direct Sales Teams; Medical Representatives show the steepest expansion trajectory as field forces digitize engagement analytics.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Enterprise pharma clusters in the United States absorb the largest CRM deployment volumes, though regulatory divergence between FDA, EMA, and NMPA jurisdictions is fragmenting cloud architecture strategies across multinational manufacturers.
United States
Specialty pharmaceutical manufacturers in Boston and San Francisco drive sophisticated territory alignment algorithm demand for complex physician networks. FDA 21 CFR Part 11 validation protocols impose 18-24 month implementation windows regardless of vendor selection. The New Jersey corridor anchors enterprise-grade deployments with integrated consent management systems serving commercial operations exceeding 500 field representatives.
Germany
Mid-sized specialty manufacturers prioritize elastic infrastructure over capital-intensive on-premise maintenance for pharmacovigilance reporting. EMA guidelines mandate bidirectional CRM-to-vigilance data flows, creating upgrade urgency across continental deployments. The Baden-Württemberg pharmaceutical cluster concentrates hybrid cloud adoption addressing data localization without sacrificing field force mobility tools.
China
NMPA data residency requirements fragment multi-tenant cloud strategies for manufacturers managing multi-country operations. Domestic specialty pharma expansion in oncology portfolios requires mobile-first engagement analytics synchronized with healthcare provider prescribing patterns. The Yangtze River Delta biotech corridor anchors private cloud investments satisfying strict sovereignty mandates.
Brazil
ANVISA digital transformation of promotional oversight creates compliance tooling demand without entrenched vendor relationships. Consumption-based pricing models align vendor compensation with active user counts among emerging market entrants. The São Paulo pharmaceutical distribution hub concentrates public cloud adoption for digitally transforming mid-market manufacturers.
India
CDSCO regulatory modernization drives validation protocol investments among contract research organizations expanding commercial operations. Cost-tier differentiation separates enterprise manufacturers investing in full-suite platforms from downstream intermediaries adopting modular point solutions. The Hyderabad-Visakhapatnam corridor anchors mobile-first deployments supporting medical representatives in low-connectivity hospital environments.
Pharmaceutical Customer Relationship Management (CRM) Software Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue AI-driven next-best-action specialization and regional compliance tooling. The vendor base concentrates around three strategic archetypes: cloud-native multi-tenant platforms, compliance-first life sciences specialists, and enterprise resource planning integrators. Consolidation pressure intensifies as subscription pricing models displace perpetual license structures. Dominant competitive moves include strategic partnerships with clinical data platforms and vertical capability acquisitions filling pharmacovigilance integration gaps.
Within the compliance-first archetype, Veeva Systems and Salesforce exemplify divergent approaches to regulated life sciences deployment. Oracle anchors the ERP-integration vector, extending enterprise resource planning paths that unify commercial and clinical data streams. These three occupy positions reflecting distinct infrastructure assumptions: multi-tenant elasticity, purpose-built validation tooling, and legacy system consolidation respectively.
| Leading Market Players |
|---|
| Salesforce |
| SAP |
| Oracle |
| Microsoft |
| Veeva Systems |
| Kapture |
| Exeevo |
| Medsimo Technologies |
| Actis Sales Technologies |
| Others |
Value Network & Pricing Analysis
FDA 21 CFR Part 11 validation mandates gate qualified supply and premium-tier pricing access, compressing margins for vendors lacking pre-validated infrastructure while rewarding compliance-first architectures with pricing power in enterprise pharmaceutical procurement cycles.
Pricing Analysis
Volume placements concentrate in consumption-based SaaS tiers while margins concentrate in private cloud engagements with dedicated validation documentation. Pricing stratifies across enterprise-grade configurations with full pharmacovigilance integration, mid-market multi-tenant deployments, and modular point solutions for downstream intermediaries. Cost compression in public cloud tiers is intensifying because procurement functions now mandate quarterly renegotiation cycles aligned to active user counts. Contract research organizations and emerging market entrants exhibit the highest price sensitivity; top-20 manufacturers with integrated delivery network contracts demonstrate the lowest.
Supply Chain Analysis
Single-source vulnerability sits with hyperscaler infrastructure providers dominating elastic compute provisioning for multi-tenant pharmaceutical CRM deployments. Software development concentrates in the United States, India, and Ireland; professional services and validation documentation production centers on Germany and Switzerland. Raw material dependencies include cloud compute capacity, specialized life sciences domain talent, and pre-validated compliance framework libraries. Regulatory divergence between FDA, EMA, and NMPA jurisdictions fragments architecture standardization. Distribution runs through direct enterprise sales organizations supplemented by systems integrators with life sciences vertical expertise.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents a consolidation play as subscription pricing models displace perpetual license structures and procurement functions mandate consumption-based contracts that favor vendors with scale economics.
For Market Incumbents: Anticipate margin compression in standardized multi-tenant tiers from emerging AI-native entrants by deepening pharmacovigilance integration capabilities and extending platform stickiness through clinical data platform partnerships. Prioritize backward integration into specialized validation documentation production to accelerate implementation timelines for mid-sized manufacturers. Defend enterprise relationships by embedding territory alignment algorithms that synchronize with healthcare provider prescribing patterns.
For New Entrants and Emerging Players: Channel partner ecosystems targeting Brazil's ANVISA digital transformation offer the most penetrable entry vector without entrenched vendor relationships. White-space opportunities concentrate in AI-driven next-best-action engines for emerging Asian markets and real-world evidence linkage modules for outcome-based contracting with integrated delivery networks. Pursue vertical capability acquisitions filling pharmacovigilance integration gaps to accelerate credibility in regulated procurement cycles.
For Investors and Strategic Acquirers: EMA pharmacovigilance bidirectional data flow mandates taking effect across continental European deployments is the leading indicator that compliance tooling specialists will command acquisition premiums over generic CRM platforms. Long-term viability favors vendors with validated multi-tenant architectures capable of satisfying divergent data residency requirements without architectural fragmentation. Target acquisition candidates with pre-built FDA 21 CFR Part 11 documentation libraries and established channel relationships in the Baden-Württemberg pharmaceutical cluster.
| Strategic Initiative | Industry Significance |
|---|---|
| Pharmacovigilance Integration Partnership | Bidirectional CRM-to-vigilance data flows satisfy EMA safety reporting mandates across continental deployments. |
| AI-Driven Next-Best-Action Engine Launch | Algorithmic physician targeting captures standardization advantages in emerging markets lacking entrenched vendors. |
| Private Cloud Infrastructure Expansion | Single-tenant environments with dedicated physical infrastructure address China's NMPA data residency requirements. |
| Mobile-First Field Force Platform Development | Native applications with offline synchronization support medical representatives in low-connectivity hospital environments. |
| Real-World Evidence Linkage Module | Convergence of CRM engagement data with patient registry platforms enables outcome-based contracting with integrated delivery networks. |
Research Methodology
Independent corroboration across primary interviews with commercial operations executives, regulatory affairs leads, medical information system directors, and field force operations managers underwrites the qualitative findings. Secondary validation draws from FDA 21 CFR Part 11 guidance documents, EMA pharmacovigilance submissions, clinical trial management system integration specifications, and enterprise pharmaceutical SEC filings. Bottom-up sizing of deployment counts by manufacturer tier and top-down validation against aggregate software spending patterns ensure cross-method consistency.
Rate-of-change decomposition across the analysis window separates volume expansion from price-mix effects and technology substitution dynamics. Segmentation dimensions modeled include deployment architecture, organization size by field force count, therapeutic portfolio complexity, regional regulatory cluster, and integration depth with clinical trial management systems. CAGRs were derived from fitted growth curves anchored to observable implementation pipeline data and procurement cycle timing. Forecast inputs incorporate EMA guideline revision schedules and specialty pharmaceutical manufacturer expansion trajectories in oncology and rare disease portfolios.
Inputs from regulatory filing databases and enterprise procurement disclosures were available through the study window; gaps in emerging market implementation timelines introduce uncertainty bands around penetration rate assumptions. Forecasts reflect documented assumptions regarding cloud migration velocity and validation protocol harmonization. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Customer Relationship Management (CRM)
Retail CRM Software Market
Customer Relationship Management (CRM)
Canada Customer Relationship Management Market
Customer Relationship Management (CRM)
Client Onboarding Solutions Market
Customer Relationship Management (CRM)
Social CRM Market
Customer Relationship Management (CRM)
Mortgage CRM Software Market
Customer Relationship Management (CRM)
Ipad CRM Market
Customer Relationship Management (CRM)
Smart Customer Service System Market
Customer Relationship Management (CRM)
Online CRM Software Market
Customer Relationship Management (CRM)
Global Customer Relationship Management Market
Customer Relationship Management (CRM)
Customer Relationship Management in Healthcare Market
Customer Relationship Management (CRM)
Android CRM Software Market
Customer Relationship Management (CRM)
Global Customer Engagement Solutions Market
Customer Relationship Management (CRM)
Complaint Management Software Market
Customer Relationship Management (CRM)
Global CRM197 Market
Customer Relationship Management (CRM)
Global Customer Experience Management Software Market
Customer Relationship Management (CRM)
Call Center Market