
 Germany Content Services Platform Market | 2026-2036
Germany Content Services Platform Market Size, Share, and Industry Trends Forecast 2026-2036
Germany Content Services Platform Market Insights
Enterprise software distribution through value-added resellers and systems integrators is reconfiguring as vendors bypass traditional intermediaries for direct cloud subscriptions. Microsoft leverages its Azure ecosystem to anchor large-account relationships across German manufacturing hubs. Hyland competes through specialized document-management capabilities in regulated sectors. OpenText sustains dominance in archival and records-management segments through deep compliance functionality.
A content services platform integrates document capture, workflow automation, records management, and intelligent information retrieval within a unified architecture, typically supporting REST APIs, metadata taxonomies, and federated search across distributed repositories. Its primary purpose centers on transforming unstructured content into actionable, governable business assets. Cloud deployment models now capture the fastest expansion as German enterprises migrate legacy on-premises ECM estates, while hybrid configurations retain stronghold status among financial services and public-sector buyers balancing sovereignty with scalability. The enterprise customer segment commands the deepest margin pools due to complex customization and integration requirements, whereas SMB adoption accelerates through standardized SaaS offerings.
The Federal Office for Information Security (BSI) imposes stringent IT-Grundschutz baseline protection requirements that shape vendor certification roadmaps and procurement eligibility for German public-sector contracts. The EU AI Act, enforced through Germany's national supervisory structures, introduces algorithmic transparency mandates that affect platforms deploying automated content classification and extraction. Stakeholders must weigh BSI compliance investments against the operational agility gains of multi-cloud architectures as regulatory fragmentation between federal and Länder procurement rules intensifies.
Market Dynamics
German automotive manufacturers are accelerating platform adoption to manage compliance documentation under tightening EU regulatory scrutiny. The Federal Office for Information Security (BSI) imposes IT-Grundschutz baseline protection requirements that reshape procurement eligibility for public-sector contracts.
Growth Catalysts
- EU AI Act enforcement:Germany's national supervisory structures mandate algorithmic transparency for automated content classification, compelling enterprises to upgrade legacy systems with auditable AI governance capabilities.
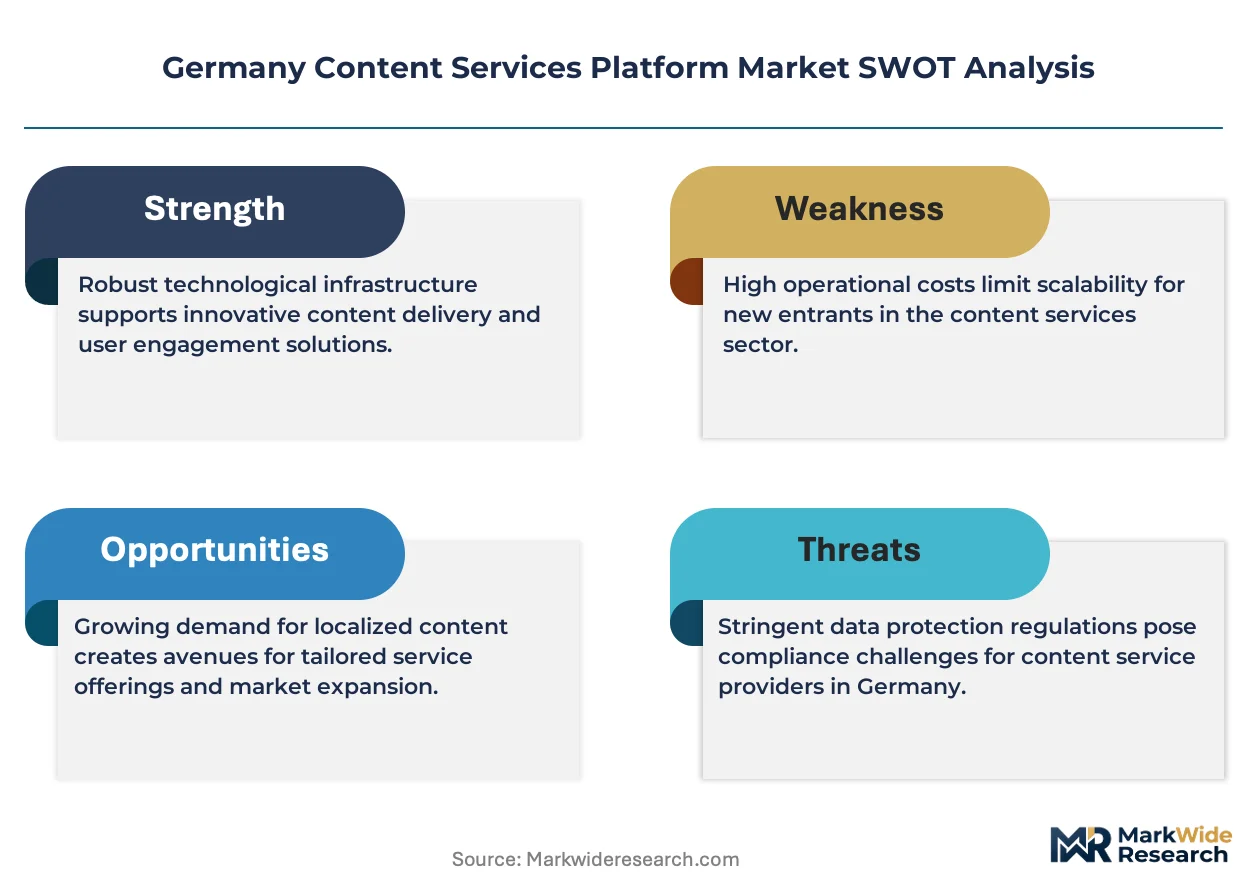
- Bavaria's industrial corridor concentration:Munich-based manufacturing conglomerates drive hybrid deployment requirements, creating clustered demand for platforms balancing on-premises sovereignty with cloud scalability.
- Automotive compliance documentation:German OEMs require integrated platforms to manage supplier audits, material declarations, and regulatory filings across complex multi-tier supply chains.
Market Restraints
- BSI certification timelines:IT-Grundschutz compliance processes extend vendor qualification periods by 12-18 months, delaying revenue recognition for platform providers targeting public-sector buyers.
- Technical debt in legacy ECM estates:Decades-old on-premises installations create migration friction, with complex custom workflows resisting straightforward cloud lift-and-shift approaches.
- Substitution by point solutions:Specialized workflow automation and contract lifecycle management vendors capture discrete use cases, fragmenting budget allocation away from unified platforms.
Strategic Opportunities
- Baden-Württemberg manufacturing belt:Stuttgart-region automotive suppliers remain underpenetrated relative to Bavaria, offering expansion potential for vendors with automotive-specific compliance templates.
- AI-powered content extraction convergence:Integration of large language models with traditional capture engines enables automated contract analysis and regulatory mapping previously requiring manual legal review.
- BSI cloud certification pathway:The federal agency's emerging criteria for sovereign cloud deployments creates first-mover advantage for platforms achieving early compliance designation.
Industry Challenges
- Integration complexity with SAP ecosystems:German enterprises run deeply customized SAP installations that resist standard API connections, demanding expensive professional services for platform deployment.
- Data residency skill scarcity:Shortage of architects qualified to design multi-cloud configurations satisfying both BSI requirements and operational agility needs constrains implementation velocity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Germany Content Services Platform Market |
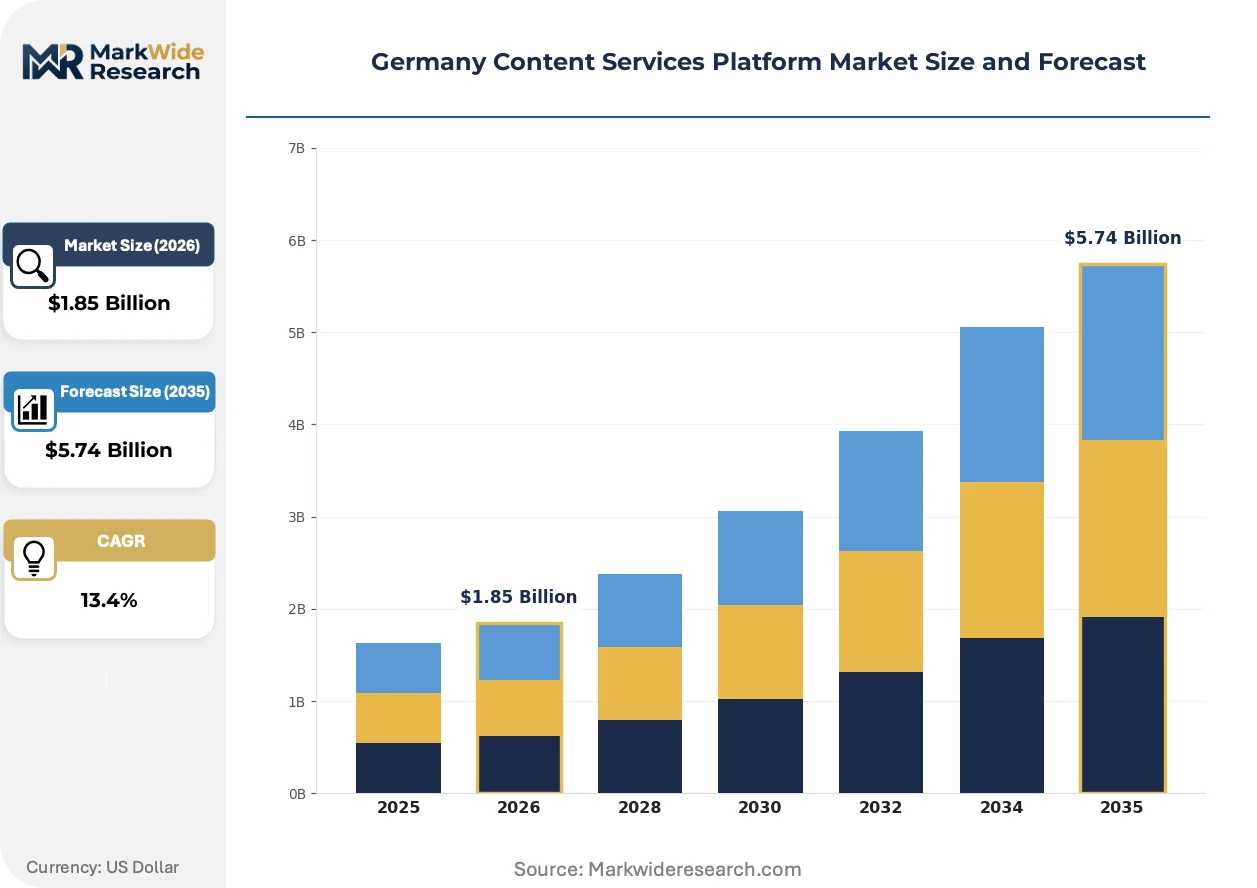
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $5.74 Billion |
| CAGR (2026 – 2036) | 13.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment Model: On-Premises, Cloud, Hybrid, Multi-Cloud Content Type: Text, Video, Audio, Image Customer Segment: SMBs, Enterprises, Government, Education Integration Level: API, Native, Custom, Third-Party |
| Companies Covered | Oracle, Hyland, Microsoft, M-Files, Alfresco, OpenText, Box, Nuxeo, IBM, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Germany Content Services Platform Market Trends and Innovations
Platform architectures are fragmenting as vendors compete to embed AI governance capabilities while preserving audit trails required by German supervisory authorities. The competitive frontier centers on who can deliver transparent automation without sacrificing the procedural rigor that regulators demand.
Intelligent document capture is hybridizing across German financial services, combining optical character recognition with transformer-based language models to extract structured data from unstructured contracts and correspondence. Major insurers in Frankfurt and Munich are piloting these systems for claims processing and policy administration. This convergence is compressing the traditional separation between capture vendors and analytics platforms, forcing incumbents to acquire or build AI capabilities rapidly.
The EU AI Act's risk-based classification system imposes documentation burdens on platforms deploying automated decision-making for content routing and access control. German data protection authorities interpret these provisions strictly, requiring human-in-the-loop safeguards for high-risk deployments. Financial institutions and healthcare providers face the steepest compliance ramps, with many freezing AI feature rollouts pending regulatory clarity on auditability standards.
Buyer concentration among large manufacturing conglomerates is reshaping vendor go-to-market economics, with direct enterprise sales displacing traditional value-added reseller networks for deals above certain thresholds. Systems integrators that built practices around on-premises ECM implementations face margin compression as cloud-native platforms reduce customization requirements. This shift is most visible in North Rhine-Westphalia's industrial regions, where Düsseldorf and Cologne headquarters of major conglomerates centralize procurement decisions.
Germany Content Services Platform Market Segmentation
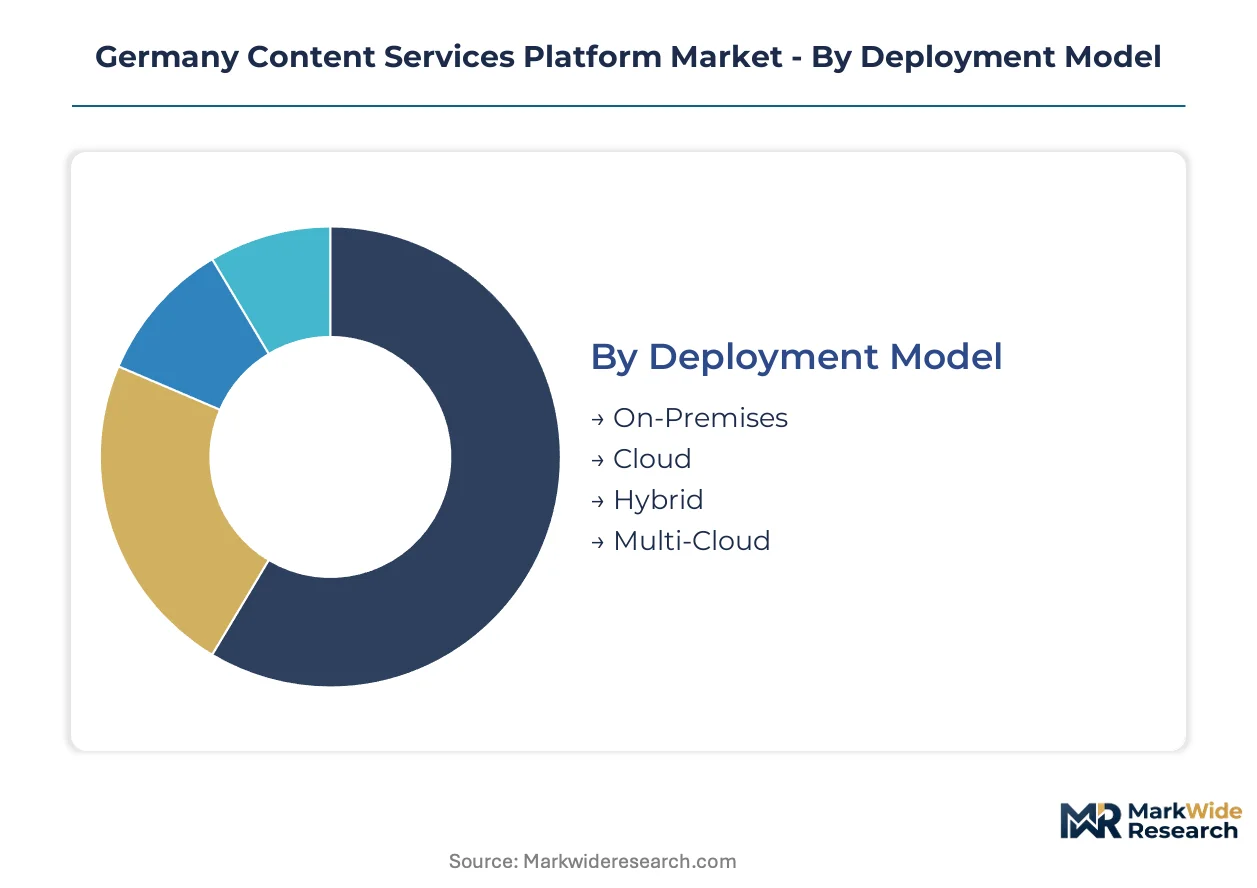
German procurement patterns fragment sharply across deployment sovereignty requirements, content complexity tiers, and integration depth with legacy ERP estates. Understanding these segment boundaries clarifies where vendor investments in BSI certification and automotive-specific templates yield returns.
Deployment Model:
Mature on-premises installations dominate legacy estates, while emerging multi-cloud architectures attract new platform investments from sovereignty-conscious enterprises.
- On-Premises:Complete infrastructure control within client data centers satisfies BSI IT-Grundschutz baseline requirements without third-party dependency. Bavarian automotive suppliers and Frankfurt financial institutions maintain these configurations for audit trail sovereignty, though hardware refresh cycles compress as cloud alternatives mature.
- Cloud:Fully managed SaaS delivery eliminates capital expenditure and accelerates feature access, appealing to mid-market manufacturers in North Rhine-Westphalia seeking rapid deployment. Data residency guarantees from Frankfurt-region hyperscaler zones address residual sovereignty concerns.
- Hybrid:Federated architectures split sensitive records on-premises while routing collaborative workflows through cloud tiers. Munich-based conglomerates drive this pattern, balancing supplier audit documentation on local servers with cloud-based contract negotiation portals.
- Multi-Cloud:Distributed workloads across competing hyperscalers mitigate vendor lock-in and satisfy emerging BSI sovereign cloud certification criteria. Early adopters include federal agencies piloting disaster-resilient architectures.
On-Premises handles the majority of throughput; Multi-Cloud is the fastest mover on share.
Content Type:
Processing intensity and regulatory exposure vary dramatically across content modalities, with text demanding governance rigor and video driving storage scale.
- Text:Structured documents, contracts, and compliance filings constitute the core workload, with German automotive OEMs generating massive supplier documentation streams. AI-powered extraction engines process material declarations and audit certificates under EU AI Act transparency mandates.
- Video:Training materials, inspection recordings, and telematics footage expand storage footprints exponentially. Stuttgart-region manufacturers accumulate production line video for quality traceability, creating archival cost pressures.
- Audio:Call center recordings and voice-based compliance documentation require transcription and sentiment analysis. Financial services in Frankfurt pilot automated dispute resolution workflows from audio sources.
- Image:Engineering schematics, defect photography, and scanned legacy documents demand OCR and visual classification. Industrial quality assurance drives concentrated demand in Baden-Württemberg manufacturing belts.
Text commands absolute volume leadership; Video is expanding most quickly as Industry 4.0 visual documentation proliferates.
Customer Segment:
Procurement sophistication and customization tolerance separate enterprise buyers from price-sensitive smaller accounts.
- SMBs:Standardized SaaS subscriptions with minimal configuration meet document management needs for regional suppliers and professional services firms. Pre-configured compliance templates for GDPR and GoBD reduce implementation friction.
- Enterprises:Complex multi-site deployments with deep SAP integration and custom workflow development characterize DAX-listed manufacturers and insurers. These accounts generate the deepest professional services revenue pools.
- Government:Federal and Länder agencies mandate BSI certification and IT-Grundschutz compliance, extending sales cycles but securing long-term maintenance contracts. Procurement centralization in Berlin and Munich headquarters concentrates vendor attention.
- Education:Universities and research institutions manage research data repositories and administrative records with moderate compliance exposure. Budget constraints favor open-source alternatives or consortia purchasing.
Enterprises absorb the dominant share of vendor resources; Government is climbing the fastest as digital administration initiatives accelerate.
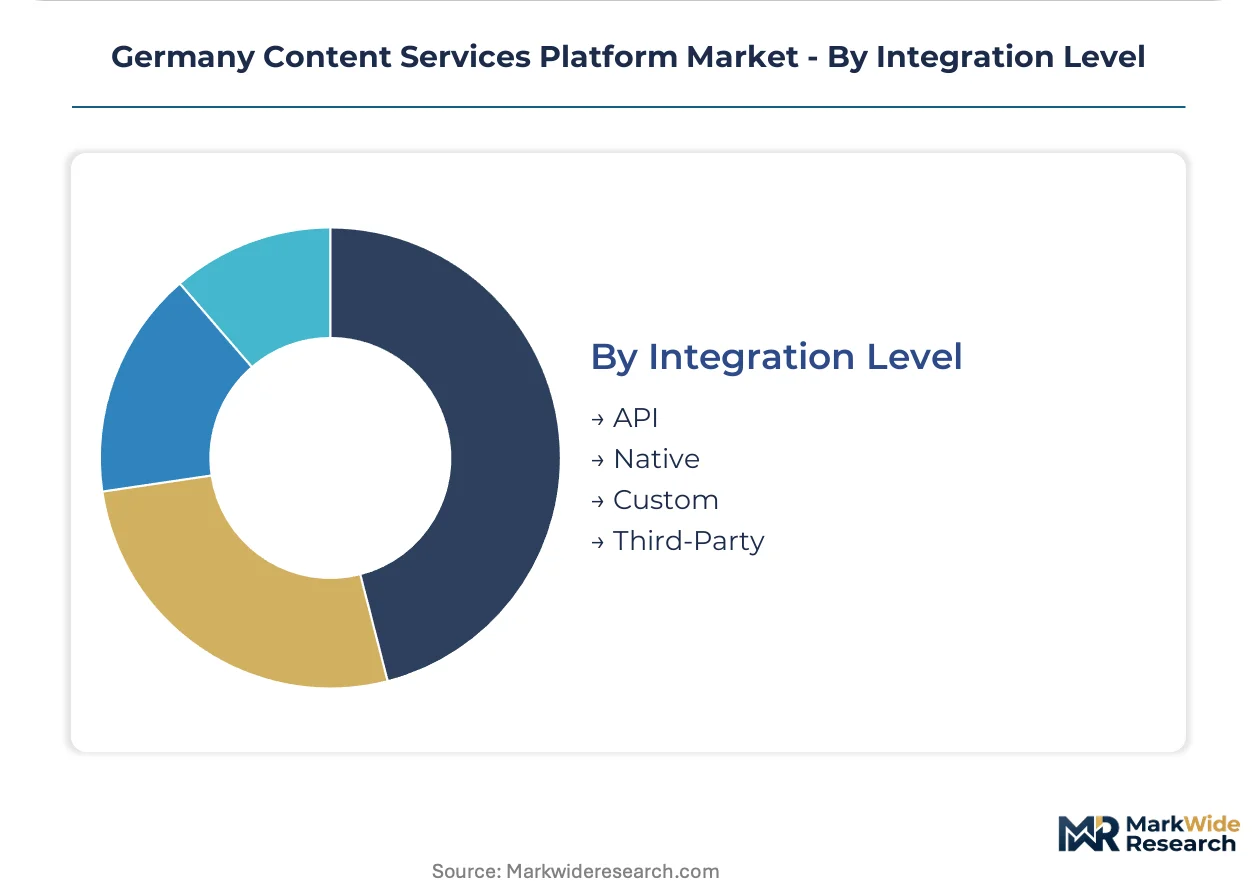
Integration Level:
Technical architecture choices determine implementation cost and operational flexibility across German enterprise technology estates.
- API:RESTful and GraphQL interfaces enable loose coupling with existing systems, preferred by IT departments modernizing legacy estates without forklift replacements. Standardized connectors reduce custom development for common ERP and CRM platforms.
- Native:Deep embedding within specific vendor ecosystems—particularly Microsoft 365 and SAP—streamlines user experience but creates dependency. Large manufacturing conglomerates in North Rhine-Westphalia favor this path for workforce familiarity.
- Custom:Bespoke integration code addresses idiosyncratic legacy systems and specialized industry applications prevalent in deeply customized German SAP installations. Professional services margins concentrate here.
- Third-Party:Pre-built connectors from integration-platform-as-a-service vendors accelerate deployment for mid-market buyers lacking internal development capacity. This pattern is expanding most quickly among SaaS-native SMBs.
Native integration captures the largest existing commitment; Third-Party is gaining share fastest as iPaaS ecosystems mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Bavaria commands premium pricing for hybrid platform deployments while North Rhine-Westphalia absorbs cost-competitive cloud migrations. This asymmetry reflects divergent industrial structures and regulatory exposure across German federal states.
Bavaria
Munich-headquartered automotive OEMs and aerospace conglomerates generate concentrated demand for sovereign-hybrid architectures. The state's data protection authority enforces strict interpretations of GDPR Article 44 for cross-border data transfers. Ingolstadt and Munich industrial parks host supplier ecosystems requiring IT-Grundschutz-certified document repositories for audit defense.
North Rhine-Westphalia
Düsseldorf and Cologne-based insurers drive cloud-native adoption for claims digitization and policy administration workflows. The Länder procurement office has streamlined SaaS purchasing frameworks for mid-market manufacturers. The Ruhr industrial belt's legacy steel and chemical operations resist full migration, creating bifurcated demand between greenfield cloud and heritage system integration.
Baden-Württemberg
Stuttgart-region automotive suppliers remain underpenetrated relative to Bavarian peers, with Tier-2 and Tier-3 manufacturers lagging in platform consolidation. The state economic ministry's Industrie 4.0 funding programs subsidize digital documentation infrastructure for SME suppliers. Karlsruhe's cybersecurity research cluster feeds talent into platform vendors seeking BSI certification expertise.
Hesse
Frankfurt's banking and insurance concentration demands highest-grade compliance functionality for MiFID II and Solvency II documentation retention. The regional financial supervisory authority coordinates with BaFin on audit trail standards for algorithmic content classification. Eschborn and Frankfurt TechQuartier host fintechs piloting AI-powered contract analysis before enterprise-scale deployment.
Berlin-Brandenburg
Federal agencies and Länder administration offices concentrate procurement decisions for standardized platform deployments. The IT Planning Council's interoperability mandates shape vendor selection for cross-agency document exchange. Potsdam's public-sector innovation labs test sovereign cloud configurations before nationwide rollout decisions.
Germany Content Services Platform Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream supplying capture engines, AI classification modules, and compliance verification tools. The German market exhibits consolidated leadership at the enterprise tier alongside fragmented mid-market competition. Three archetypes dominate: hyperscale cloud ecosystems with native content services, European specialists emphasizing GDPR-sovereign architectures, and legacy ECM vendors defending installed bases through hybrid migration programs. Competitive intensity centers on BSI certification achievement and SAP integration depth as primary differentiation vectors.
Within the European specialist tier, Hyland and OpenText exemplify compliance-first positioning, while Microsoft anchors the hyperscale ecosystem play. Hyland occupies a position emphasizing regulated-sector document management, OpenText exemplifies archival and records-management heritage, and Microsoft represents the cloud-native platform integration archetype leveraging existing enterprise relationships. Each sits within distinct procurement evaluation frameworks based on buyer sovereignty requirements and legacy system exposure.
| Leading Market Players |
|---|
| Oracle |
| Hyland |
| Microsoft |
| M-Files |
| Alfresco |
| OpenText |
| Box |
| Nuxeo |
| IBM |
| Others |
Pricing and Supply Chain Analysis
US hyperscaler infrastructure concentration in Frankfurt-region data centers anchors downstream margin pools for German platform vendors, with sovereign cloud certification investments now commanding premium pricing tiers against standard SaaS subscriptions.
Pricing Analysis
The customization-premium spread separates configured-to-order enterprise deployments from standardized SaaS tiers. Subscription-based pricing with volume-scaled tiers dominates, with BSI IT-Grundschutz certification level and SAP integration depth as primary differentiation drivers. Pricing pressure stems from mid-market buyers migrating toward pre-configured SaaS offerings with reduced professional services dependency. SMB segments exhibit highest price sensitivity, while DAX-listed manufacturers tolerate substantial customization premiums for audit-trail sovereignty.
Supply Chain Analysis
EU export-control regimes on dual-use encryption and AI acceleration hardware constrain component flows for on-premises security modules. Supply chains draw from US hyperscaler infrastructure, Irish data center equipment manufacturing, and Taiwanese semiconductor fabrication for AI inference chips. Single-source vulnerability concentrates in Frankfurt-region cloud availability zones. Distribution runs through direct enterprise sales for large accounts and systems integrator channels for mid-market penetration.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
German content services platforms represent a service-attach opportunity where managed compliance monitoring and BSI certification maintenance contracts expand faster than base platform subscriptions.
For Market Incumbents: Harden defensive moats through exclusive BSI certification partnerships with federal agencies and deep SAP S/4HANA native integration investments. Vertical integration into automotive-specific compliance template libraries counters emerging workflow automation point solutions. Channel control through certified systems integrator networks preserves margin capture against direct hyperscaler competition.
For New Entrants and Emerging Players: Baden-Württemberg's Tier-2 automotive supplier belt offers concentrated white-space opportunity with lower competitive intensity than Bavaria. Industrie 4.0 subsidy qualification as a go-to-market angle accelerates procurement access for SME manufacturers. AI-powered contract extraction capabilities differentiate against legacy capture vendors in this underpenetrated segment.
For Investors and Strategic Acquirers: Capital is best deployed toward European specialists with existing BSI compliance roadmaps and established automotive vertical expertise. Long-term viability hinges on regulatory certification durability rather than feature velocity alone. The signal to watch is BSI sovereign cloud certification designation timing as an inflection indicator for public-sector contract eligibility.
| Strategic Initiative | Industry Significance |
|---|---|
| BSI Certification Investment | Unlocks federal and Länder procurement eligibility under IT-Grundschutz baseline requirements. |
| SAP Native Integration | Captures DAX-listed manufacturers with deeply customized ERP estates resisting standard API approaches. |
| Automotive Compliance Templates | Addresses OEM supplier audit documentation demands under tightening EU regulatory scrutiny. |
| AI Governance Capability Buildout | Satisfies EU AI Act algorithmic transparency mandates for automated content classification systems. |
| Hybrid Architecture Development | Balances Munich-headquartered conglomerate requirements for on-premises sovereignty with cloud scalability. |
Research Methodology
Operator-level perspectives from platform engineering directors, federal procurement officers, automotive compliance managers, and systems integrator practice leads anchored the qualitative base. Secondary validation drew from BSI certification registries, federal IT procurement databases, SAP partner ecosystem directories, and EU AI Act implementation guidance. Bottom-up deployment model sizing and top-down vendor revenue triangulation converged on segment-level estimates.
Scenario-bracketing framed the analytical approach across the projection horizon. Segmentation dimensions modeled include deployment sovereignty tier, content complexity modality, customer scale segment, and SAP integration depth. CAGRs derived from deployment velocity curves weighted by BSI certification pipeline visibility and automotive OEM platform refresh cycles.
Macroeconomic conditions sit as an overlay; deviation in German industrial capital expenditure cycles or federal digitalization budget allocations would shift the trajectory. Material shifts in BSI sovereign cloud certification criteria or EU AI Act enforcement stringency would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Solutions
Global Space Planning Software Market
Digital Solutions
Business As a Service Market
Digital Solutions
Location As a Service Market
Digital Solutions
Digital User Experience Solutions Market
Digital Solutions
IT As a Service Market
Digital Solutions
Defense IT Spending Market
Digital Solutions
Global Interactive Voice Response Market
Digital Solutions
Express Digitizer Market
Digital Solutions
Demand Side Platform (DSP) Market
Digital Solutions
Social Employee Recognition Systems Market
Digital Solutions
Cognitive Supply Chain Market
Digital Solutions
Global Unified Endpoint Management Market
Digital Solutions
Labor Management System in Retail Market
Digital Solutions
Mobile Command and Control Solutions Market
Digital Solutions
Asia Pacific Smart Card Market
Digital Solutions
Global Data Quality Tool Market