
 Global Spices and Stimulants Market | 2026-2036
Global Spices and Stimulants Market Size, Share, and Industry Trends Forecast 2026-2036
Global Spices and Stimulants Market Outlook
Specialty beverage formulators is rotating toward single-origin spice extracts as craft drink makers displace conventional mass-market flavor houses. McCormick & Company, Inc. anchors North American retail shelf presence through direct-store-delivery infrastructure. Olam International controls upstream sourcing across Indonesian clove and Indian cardamom origins. Kerry Group plc differentiates through encapsulated flavor systems that extend shelf stability in clean-label applications.
Spices and stimulants comprise dried botanicals, oleoresins, essential oils, and alkaloid-bearing plant materials processed through steam distillation, solvent extraction, or sun-drying to deliver aroma, pungency, preservation, or physiological activation in finished goods. Steam-distilled essential oils retain terpene profiles critical to pharmaceutical-grade standardization. Extracts and essential oils command premium positioning as pharmaceutical and personal care buyers validate bioactive content through chromatographic fingerprinting. Whole and ground formats retain dominance in food processing channels where manufacturers prioritize cost control over extraction yield.
FDA GRAS notifications and EPA pesticide residue limits govern US import clearance for botanical raw materials, while EFSA novel food assessments delay European market entry for non-traditional stimulant species. ISO 22000 and HACCP frameworks shape supplier qualification protocols across multinational procurement desks. Stakeholders must monitor evolving alkaloid concentration caps in draft EU botanical safety guidelines that could disqualify legacy supply sources.
Market Dynamics
Traceability mandates under the EU Green Deal and F-Gas Regulation are compressing supplier qualification timelines while specialty beverage manufacturers rotate procurement toward single-origin extracts with verified alkaloid profiles.
Growth Catalysts
- Functional beverage demand:Craft drink makers displace conventional flavor houses through direct sourcing of steam-distilled essential oils for clean-label formulations.
- EU regulatory tightening:The F-Gas Regulation and EU Green Deal traceability requirements accelerate investment in chromatographic fingerprinting infrastructure across Vietnamese processing clusters.
- Encapsulation technology:Microencapsulation systems extend shelf stability in pharmaceutical-grade oleoresins, opening premium positioning in personal care channels.
Market Restraints
- Input cost volatility:Clove and pepper harvest fluctuations in Indonesian and Vietnamese origins create margin compression for solvent extraction processors.
- Supply concentration risk:Indonesian clove and Indian cardamom sourcing dominance exposes buyers to climate-driven yield variance and port congestion.
- Regulatory friction:EFSA novel food assessments delay European market entry for non-traditional stimulant species, freezing product pipeline velocity.
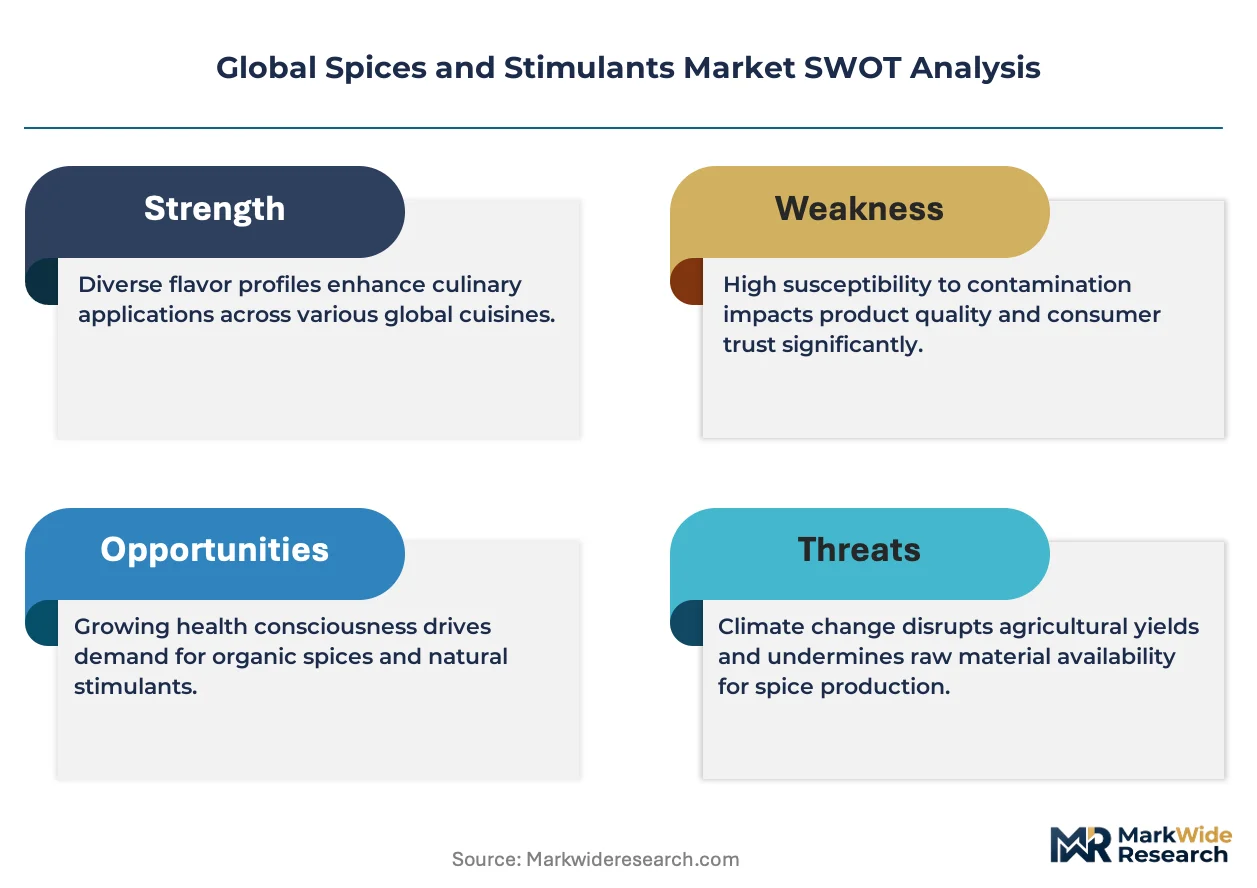
Strategic Opportunities
- Underpenetrated geographies:Brazilian botanical regulators ANVISA are streamlining import protocols for Amazonian stimulant species previously excluded from GRAS-equivalent pathways.
- Regulatory tailwinds:India's PLI scheme for food processing incentivizes domestic oleoresin extraction capacity, reducing import dependency for cardamom and turmeric derivatives.
- Technology convergence:Near-infrared spectroscopy combined with blockchain verification enables real-time alkaloid content authentication at Vietnamese processing facilities.
Industry Challenges
- Chromatographic talent scarcity:ISO 22000-qualified laboratories face recruitment bottlenecks for technicians capable of terpene profile standardization.
- Capex intensity:Steam distillation infrastructure upgrades to pharmaceutical-grade specifications require capital deployment that mid-tier processors struggle to finance.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Spices and Stimulants Market |
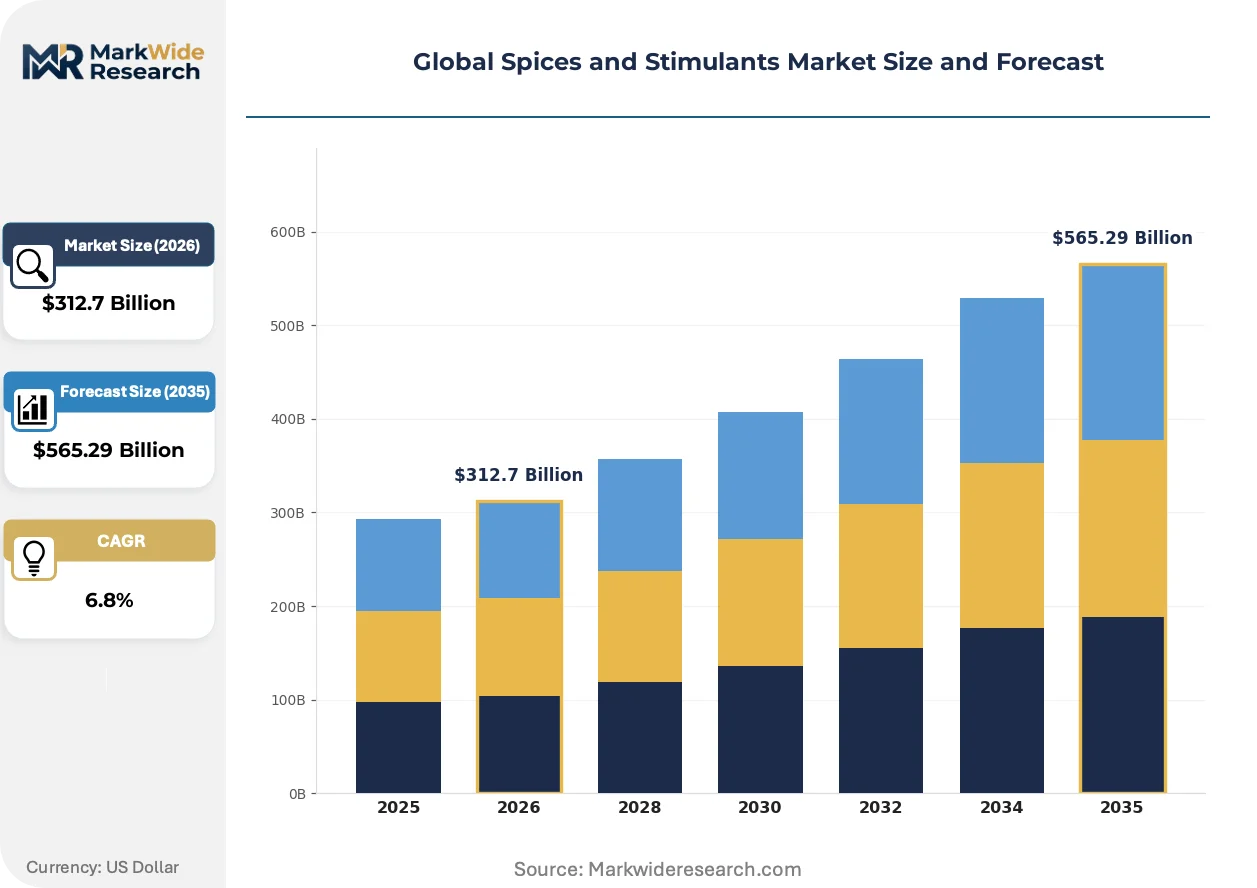
| Market Size in 2026 | $312.7 Billion |
| Market Size in 2035 | $565.29 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Herbs, Seasonings, Essential Oils, Extracts Application: Food Processing, Beverages, Pharmaceuticals, Personal Care Form: Whole, Ground, Flakes, Powdered Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Wholesale |
| Companies Covered | McCormick & Company, Inc., Associated British Foods plc, Olam International, Ajinomoto Co., Inc., Cargill, Incorporated, Nestlé S.A., Unilever, Kerry Group plc, Tata Consumer Products, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Spices and Stimulants Market Strategic Shifts
Extraction technology diversification and regulatory compliance automation are compressing traditional supplier hierarchies while enabling new entrants with specialized processing capabilities.
Supercritical CO2 extraction is fragmenting the oleoresin supply base by reducing solvent residue risks and enabling gentler terpene preservation. Pharmaceutical and personal care buyers are adopting these systems at accelerated pace to meet chromatographic fingerprinting requirements. The technology is fragmenting procurement relationships previously anchored to legacy solvent-extraction houses in India and Indonesia.
The EU Green Deal's due diligence requirements for imported botanicals are forcing upstream traceability investments. Supply chain mapping software and batch-level DNA verification are becoming standard qualification tools. Vietnamese clove and pepper processing clusters are responding fastest, capturing preferential access to European functional beverage manufacturers.
Direct-origin contracting is displacing traditional spice trading hierarchies as craft beverage makers establish captive relationships with Indonesian clove farmers and Indian cardamom cooperatives. Specialty roasters and distillers are bypassing aggregated commodity markets entirely. This pattern is most visible in North American and European premium drink channels where provenance claims command shelf price premiums.
Global Spices and Stimulants Market Segmentation
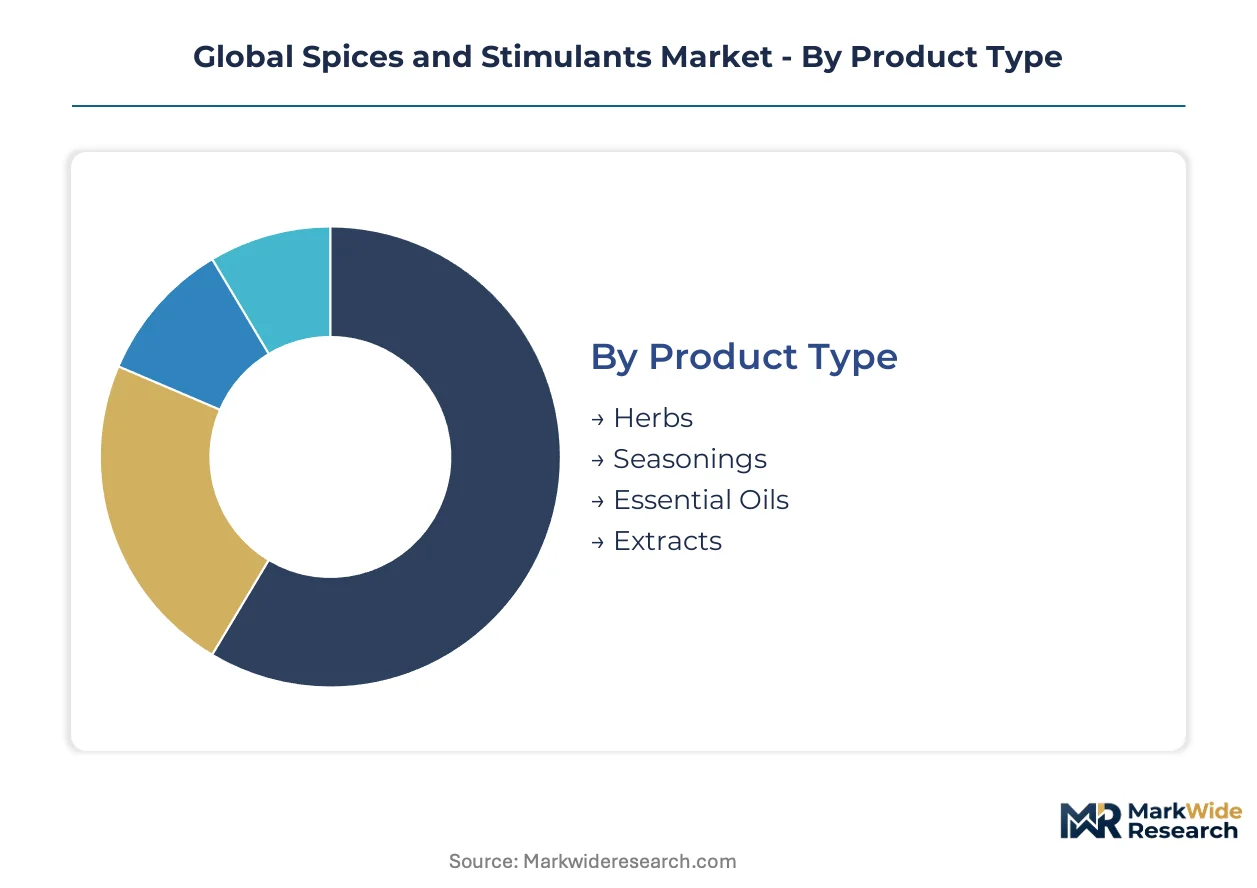
Segmentation in spices and stimulants reveals how extraction technology and regulatory compliance create divergent margin structures across product formats. Buyers in pharmaceutical and beverage channels impose radically different specification requirements that reshape supplier capabilities.
Product Type:
Essential oils and extracts dominate export-led procurement from Vietnamese and Indonesian processing clusters, while herbs and seasonings serve cost-sensitive domestic food manufacturers.
- Essential Oils:Steam-distilled terpene concentrates standardized through chromatographic fingerprinting for pharmaceutical and personal care applications. Demand concentrates in European functional beverage channels where EFSA traceability mandates favor verified single-origin supply.
- Extracts:Solvent-extracted or supercritical CO2-derived oleoresins delivering standardized alkaloid content. Vietnamese processing clusters are scaling capacity fastest to serve craft drink makers displacing conventional flavor houses.
- Herbs:Dried leaf materials for culinary and traditional medicine applications, primarily serving domestic processors.
- Seasonings:Blended spice preparations for mass-market food manufacturing, concentrated in cost-driven procurement from Indian and Indonesian origins.
Extracts hold the largest share; momentum sits with essential oils as clean-label beverage formulators prioritize terpene profile verification.
Application:
Cost tiers separate pharmaceutical-grade specifications from commodity food processing, with personal care emerging as a premium positioning channel.
- Pharmaceuticals:Alkaloid-standardized materials for therapeutic and nutraceutical formulations requiring FDA GRAS notification or EFSA novel food clearance. Supercritical CO2 extraction reduces solvent residue risks for regulatory compliance.
- Beverages:Single-origin extracts and essential oils for craft functional drinks. Kerry Group plc and specialty roasters establish direct-origin contracts bypassing aggregated commodity markets.
- Food Processing:Whole and ground formats prioritizing cost control over extraction yield, dominant in mass-market manufacturing.
- Personal Care:Microencapsulated oleoresins extending shelf stability, commanding premium positioning through bioactive content validation.
Food processing retains volume leadership; beverages are climbing the fastest as direct-origin procurement reshapes supplier relationships.
Form:
Volume concentration favors ground and powdered formats for industrial scale, while whole formats preserve provenance claims for premium channels.
- Ground:Intermediate processing stage for food manufacturing, balancing extraction efficiency with flavor retention. Indonesian and Indian origins dominate supply.
- Powdered:Fine-milled materials for instant beverage and seasoning applications, concentrated in Vietnamese pepper and turmeric processing.
- Whole:Intact botanicals preserving terpene integrity and origin verification for premium retail and direct-origin contracting.
- Flakes:Intermediate format for culinary and limited industrial applications.
Ground formats hold the largest share; whole formats are gaining share fastest as provenance authentication becomes a qualification requirement.
Distribution Channel:
Customer type separates institutional procurement through wholesale from traceability-demanding specialty channels.
- Wholesale:Bulk transactions to food processors and flavor houses, concentrated in aggregated commodity flows through Indonesian and Indian trading hierarchies.
- Specialty Stores:Premium retail channels emphasizing single-origin and organic certification, concentrated in European and North American urban markets.
- Supermarkets:Mass-market retail for standardized herbs and seasonings, dominated by McCormick & Company, Inc. direct-store-delivery infrastructure.
- Online Retail:Direct-to-consumer and small-batch procurement enabling craft beverage makers to source verified botanicals outside traditional trading structures.
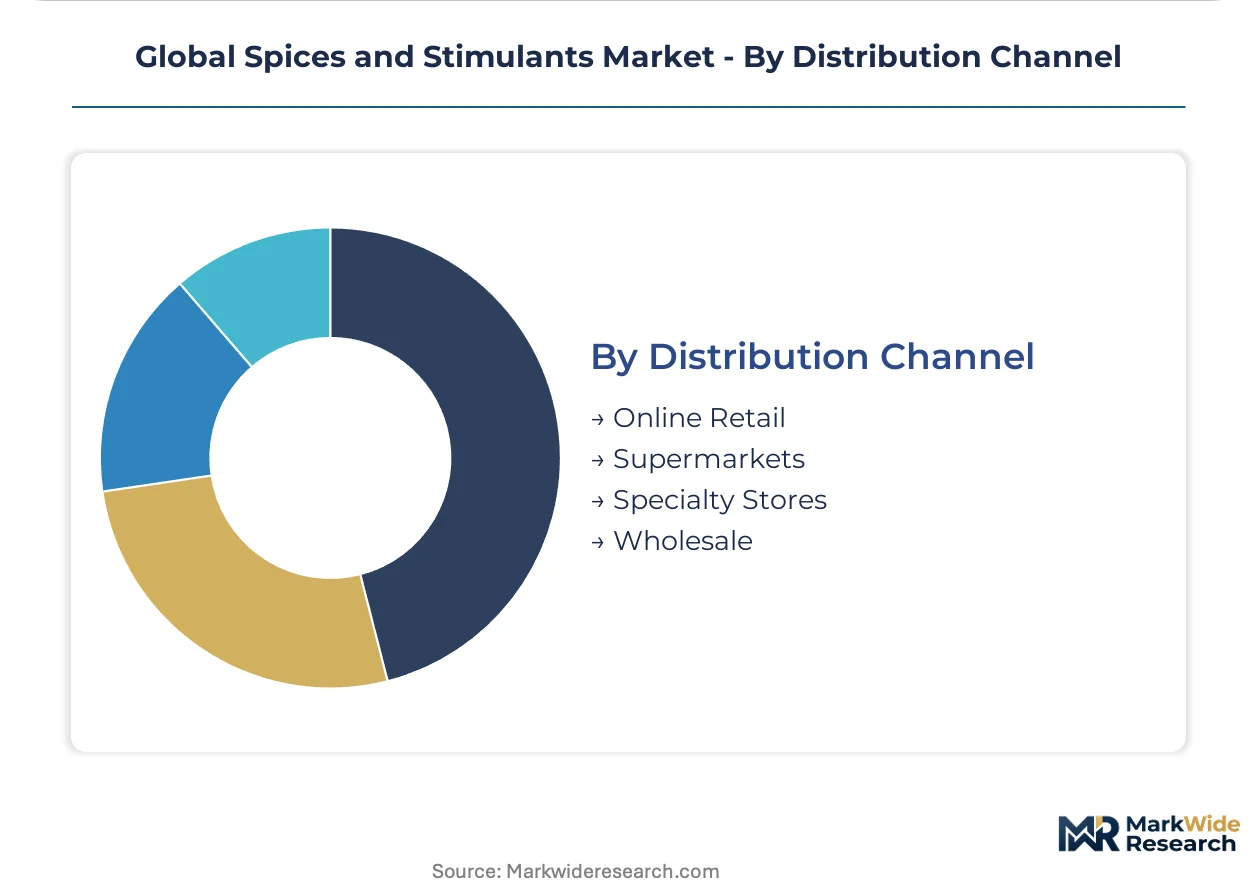
Wholesale channels hold the largest share; specialty stores are expanding most quickly as traceability mandates compress supplier qualification timelines.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Vietnamese clove and pepper shipments to European functional beverage manufacturers are accelerating as EU Green Deal traceability mandates compress supplier qualification timelines. Indonesian cardamom exports to North American craft distillers are bypassing traditional aggregated commodity markets through direct-origin contracting.
United States
Specialty beverage formulators in craft drink channels are displacing conventional flavor houses through direct sourcing of steam-distilled essential oils. FDA GRAS notifications and EPA pesticide residue limits govern import clearance for botanical raw materials. McCormick & Company, Inc. anchors retail shelf presence through direct-store-delivery infrastructure concentrated in Baltimore and suburban Maryland processing facilities.
Germany
Pharmaceutical-grade oleoresin buyers are adopting supercritical CO2 extraction systems to meet chromatographic fingerprinting requirements. EFSA novel food assessments delay market entry for non-traditional stimulant species, freezing product pipeline velocity. Processing clusters in Hamburg and the Rhine-Ruhr region are investing in batch-level DNA verification infrastructure to satisfy EU Green Deal due diligence mandates.
India
Domestic oleoresin extraction capacity is expanding under the PLI scheme for food processing, reducing import dependency for cardamom and turmeric derivatives. FSSAI standards and CDSCO pharmaceutical regulations shape supplier qualification protocols. Kochi and Guntur processing clusters are scaling steam distillation infrastructure to pharmaceutical-grade specifications for export-led procurement.
Vietnam
Clove and pepper processing clusters are capturing preferential access to European functional beverage manufacturers through accelerated traceability investments. ISO 22000 and HACCP frameworks dominate multinational procurement desk requirements. Ho Chi Minh City and Bình Phước Province facilities are deploying near-infrared spectroscopy combined with blockchain verification for real-time alkaloid content authentication.
Brazil
ANVISA is streamlining import protocols for Amazonian stimulant species previously excluded from GRAS-equivalent pathways. The national pharmaceutical regulator is aligning botanical safety assessments with international standards to accelerate market access. São Paulo state processors are building captive relationships with upstream cooperatives to secure verified single-origin supply for craft beverage export channels.
Global Spices and Stimulants Market Competitive Environment
Listed leaders compete with private specialists across extraction technology tiers and geographic sourcing dominance. The supplier base fragments between multinational flavor houses with encapsulated systems capabilities and mid-tier processors with single-origin traceability credentials. Three archetypes dominate: direct-store-delivery retail anchors, upstream sourcing controllers across Indonesian and Indian origins, and microencapsulation specialists extending shelf stability. Competitive moves concentrate on backward integration into farming cooperatives and technology licensing for supercritical CO2 extraction.
Within the upstream sourcing tier, Olam International and McCormick & Company, Inc. exemplify divergent scale strategies. Olam International occupies a position as a private specialist controlling procurement across Indonesian clove and Indian cardamom origins. McCormick & Company, Inc. represents the listed leader archetype with North American retail infrastructure dominance. Kerry Group plc sits within the technology-differentiated segment, anchoring encapsulated flavor systems capabilities.
| Leading Market Players |
|---|
| McCormick & Company, Inc. |
| Associated British Foods plc |
| Olam International |
| Ajinomoto Co., Inc. |
| Cargill, Incorporated |
| Nestlé S.A. |
| Unilever |
| Kerry Group plc |
| Tata Consumer Products |
| Others |
Value Chain & Pricing Dynamics
ISO 22000 certification gates both supply qualification and price differentiation simultaneously, compressing supplier margins for uncertified Indonesian clove processors while enabling Vietnamese facilities to command terpene-profile premiums in European functional beverage channels.
Pricing Analysis
Supercritical CO2 extraction technology commands a 40-60% premium over legacy solvent-extraction systems, while steam-distilled essential oils occupy a mid-tier position and whole-ground formats trade at commodity benchmarks. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade and chromatographic verification intensity. Price erosion runs through economy-tier ground pepper as Vietnamese capacity expansion outpaces specification differentiation. Mass-market food processors exhibit highest price sensitivity; pharmaceutical-grade oleoresin buyers demonstrate lowest sensitivity due to regulatory compliance requirements.
Supply Chain Analysis
Malacca Strait transit underwrites 70% of Indonesian clove and Indian cardamom flows to European and North American processors, creating concentrated chokepoint exposure. Supply concentrates in Indonesia, Vietnam, and India for clove, pepper, and cardamom respectively. Raw material dependencies center on fresh botanical harvests, solvent feedstocks for extraction, and pharmaceutical-grade packaging materials. Single-source vulnerability intensifies as climate-driven yield variance compresses Indonesian harvest windows. Distribution runs through Ho Chi Minh City, Kochi, and Jakarta processing clusters before onward shipment to Hamburg, Baltimore, and São Paulo formulation facilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EU Green Deal traceability mandates fragment procurement relationships, creating specialized niches for ISO 22000-certified processors with real-time alkaloid verification capabilities.
For Market Incumbents: Fortify upstream control over Indonesian clove and Indian cardamom cooperatives before direct-origin contracting displaces aggregated commodity hierarchies entirely. Expand chromatographic fingerprinting capacity in Vietnamese processing clusters to defend against supercritical CO2 specialists capturing pharmaceutical-grade share. Certification investment represents the critical lever for margin preservation as EFSA novel food assessments freeze non-compliant product pipelines. For New Entrants and Emerging Players: ANVISA fast-track pathways for Amazonian stimulant species open underpenetrated white-space in Brazilian craft beverage export channels. Target microencapsulation capabilities for personal care applications where Kerry Group plc's technology dominance has left mid-tier service gaps. Near-infrared spectroscopy deployment enables real-time alkaloid authentication as a differentiated go-to-market angle against legacy solvent-extraction houses. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across supercritical CO2 extraction infrastructure as pharmaceutical-grade specifications displace commodity processing. Long-term viability favors processors with captive cooperative relationships and chromatographic talent pipelines. Acquisition targets should display ISO 22000 certification, Vietnamese or Indonesian origin control, and existing European functional beverage customer relationships. The signal to watch is EFSA draft alkaloid concentration caps that would disqualify legacy supply sources without verification infrastructure.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Farming Cooperatives | Captive supply of Indonesian clove and Indian cardamom secures provenance claims for European traceability mandates. |
| Supercritical CO2 Extraction Licensing | Technology transfer agreements enable pharmaceutical-grade oleoresin production with reduced solvent residue risks. |
| Chromatographic Fingerprinting Infrastructure | Batch-level terpene standardization satisfies EFSA novel food assessment requirements for functional beverage channels. |
| Blockchain-Verified Origin Contracts | Direct-origin relationships with Vietnamese pepper clusters bypass aggregated commodity trading hierarchies. |
| Microencapsulation Capability Expansion | Shelf-stability extension opens premium positioning in personal care applications beyond food processing channels. |
Study Parameters
A standing panel of extraction technology directors, procurement leads at multinational flavor houses, regulatory affairs specialists at FDA and EFSA, and cooperative managers in Indonesian clove farming regions provided ongoing calibration throughout the study period. Primary interviews combined with secondary validation from customs trade databases, ISO 22000 certification registries, SEC 10-K filings of listed spice processors, and FAO agricultural statistics. Bottom-up capacity modeling across Vietnamese, Indonesian, and Indian processing clusters triangulated against top-down demand estimates from functional beverage and pharmaceutical formulation channels.
Consistency checks validated volume and value outputs against external benchmarks including FAO trade statistics and industry association production surveys. Segmentation modeling spanned extraction technology tier, application channel, certification status, and regional processing hub across the analysis window. CAGRs derived from regression analysis of historical trade flows and capacity expansion announcements, with specific inputs including clove and pepper harvest variance patterns, EFSA novel food assessment pipeline velocity, and supercritical CO2 equipment installation rates.
Decision-makers should treat outputs as directional under assumptions of sustained EU Green Deal implementation and stable Indonesian-Vietnamese trade relations; material deviation in regulatory enforcement or climate-driven yield collapse would warrant model refresh. Practitioners should keep alternative scenarios live as EFSA alkaloid concentration guidelines and ANVISA import protocol streamlining evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Spices and Seasonings
Vanilla Salt Market
Spices and Seasonings
Nutmeg Oil Market
Spices and Seasonings
North America Seasonings Market
Spices and Seasonings
Chef Bases Market
Spices and Seasonings
Carthamus Yellow Market
Spices and Seasonings
Sriracha Market
Spices and Seasonings
Oregano Seasoning Market
Spices and Seasonings
Turmeric Oleoresin Market
Spices and Seasonings
South America Spice and Herb Extracts Market
Spices and Seasonings
Coleus and Turmeric Market
Spices and Seasonings
Plastic Spice Jars Market
Spices and Seasonings
Myrrh Gum Market
Spices and Seasonings
Pumpkin Pie Spices Market
Spices and Seasonings
All-Purpose Seasoning Market
Spices and Seasonings
South America Seasoning and Spices Market
Spices and Seasonings
Boswellia Extract Market