
 Middle East and Africa Aroma Chemicals Market | 2026-2036
Middle East and Africa Aroma Chemicals Market Size, Share, and Industry Trends Forecast 2026-2036
Middle East and Africa Aroma Chemicals Market Foresight
Fine fragrance formulation is recalibrating toward higher synthetic content as oud-inspired luxury perfumes gain share across Gulf retail channels. Symrise AG leverages its regional compounding infrastructure to supply customized bases for Middle Eastern perfumers. Givaudan SA anchors its position through captive biotechnology capabilities in vanillin and captive musk synthesis. Takasago International Corporation differentiates via asymmetric catalysis expertise applied to high-value chiral aroma molecules.
Aroma chemicals comprise isolated or synthesized volatile organic compounds—typically esters, aldehydes, terpenes, or alcohols with defined boiling points, refractive indices, and odor thresholds—engineered to replicate or enhance natural scent profiles in industrial formulations. These molecules serve as the functional core of perfumery, flavor systems, and scented consumer goods where consistency, cost efficiency, and supply security override reliance on botanical extraction. Esters dominate volume throughput in food and beverage applications where fruity top-notes command broad formulation utility. Terpenes capture expanding share in cleaning product matrices as manufacturers reformulate around limonene and pinene derivatives for perceived natural positioning. Aldehydes concentrate margin pools in fine fragrance where C8-C14 straight-chain variants deliver signature floral brightness at low inclusion rates.
South Africa's National Regulator for Compulsory Specifications enforces fragrance allergen labeling under adapted EU REACH principles, while Gulf Standards Organization member states apply SASO technical regulations to imported aroma chemical consignments. Saudi Food and Drug Authority and Emirates Authority for Standardization and Metrology both mandate compliance documentation for cosmetic-grade aroma chemicals entering their respective markets, creating differentiated entry protocols across the region. Stakeholders must monitor divergence between Gulf harmonization efforts and South Africa's closer alignment with European Chemicals Agency frameworks when configuring regulatory submission strategies.
Market Dynamics
Synthetic musk procurement for oud-based perfumery is compressing natural extraction dependencies across Gulf Cooperation Council formulation houses, while South Africa's allergen labeling mandates force disclosure architecture investments.
Growth Catalysts
- Dubai's Jebel Ali free zone:Concentrated flavor and fragrance compounding operations serve re-export corridors into Sub-Saharan Africa and South Asia, amplifying regional throughput.
- SASO technical regulations:Gulf Standards Organization harmonization reduces multi-market compliance friction for aroma chemical consignments entering Saudi Arabia, UAE, and Kuwait.
- Chiral catalysis platforms:Asymmetric synthesis capabilities unlock high-value terpene derivatives for fine fragrance houses seeking molecular precision at commercial scale.
Market Restraints
- Natural feedstock volatility:Limonene and pinene supply from citrus processing fluctuates with Mediterranean harvest cycles, compressing margin predictability for cleaning product formulators.
- Regulatory divergence:South Africa's National Regulator for Compulsory Specifications applies adapted EU REACH allergen thresholds, while Gulf states maintain SASO frameworks, fragmenting compliance pathways.
- Substitution pressure:Biotechnology-derived vanillin from microbial fermentation threatens synthetic vanillin price floors in food and beverage applications.
Strategic Opportunities
- Ethiopian manufacturing:Underdeveloped aroma chemical production infrastructure creates first-mover positioning for specialty ester and aldehyde manufacturing serving East African markets.
- Biotechnology convergence:Integration of CRISPR-edited yeast strains with traditional chemical synthesis opens captive routes to rare musk molecules previously dependent on animal sources.
- Emirates Authority for Standardization and Metrology:Streamlined cosmetic-grade import documentation protocols reduce time-to-market for compliant aroma chemical suppliers targeting UAE formulation houses.
Industry Challenges
- Asymmetric catalysis expertise scarcity:Limited regional availability of chemists trained in chiral molecule synthesis constrains high-value product pipeline development.
- Dual certification timelines:Simultaneous Gulf Standards Organization and South African Bureau of Standards compliance processes extend product launch cycles by 8-14 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle East and Africa Aroma Chemicals Market |
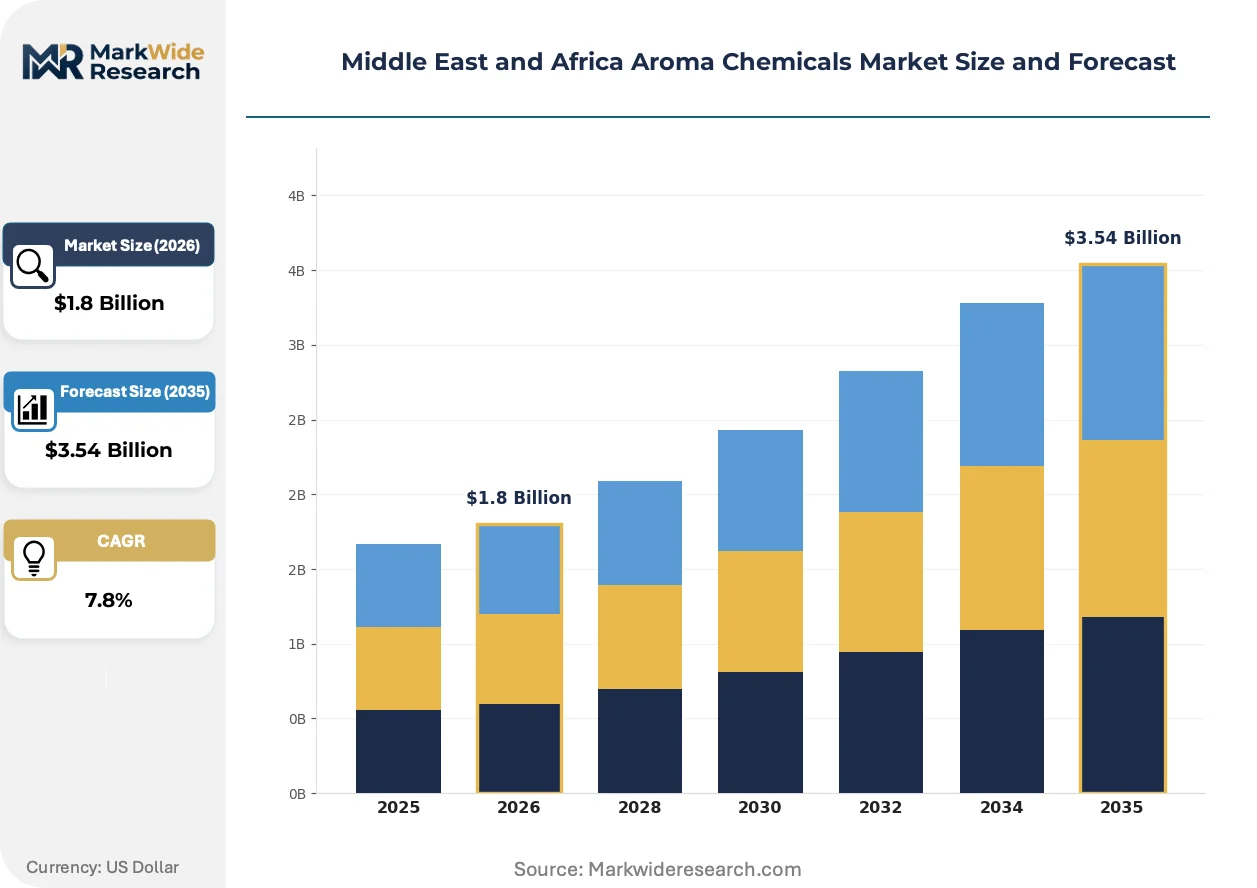
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.54 Billion |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Esters, Alcohols, Aldehydes, Terpenes Application: Perfumery, Food & Beverages, Cosmetics, Cleaning Products End User: Manufacturers, Retailers, Laboratories, Distributors Sales Channel: Online, Offline, Wholesale, Direct |
| Companies Covered | Symrise AG, Takasago International Corporation, Givaudan SA, Takamol, DSM, Firmenich SA, BASF SE, Al Haramain Perfumes, International Flavors & Fragrances Inc., Others |
| Regions Covered | Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle East and Africa Aroma Chemicals Market Shifts & Advancements
Biotechnology platforms and regulatory disclosure mandates are restructuring how aroma molecules reach industrial formulators, with supply security and traceability now commanding premium positioning.
Enzymatic biotransformation routes to terpene oxides and esters are consolidating as the preferred production method for limonene-derived cleaning product actives. South African household chemical manufacturers are adopting these biocatalytic pathways to meet natural-positioning claims without sacrificing batch consistency. The technology is consolidating synthetic chemistry capacity into integrated biorefinery operations that co-locate fermentation and downstream processing.
South Africa's Department of Health updated cosmetic ingredient disclosure rules now mandate granular labeling for 26 allergenic fragrance compounds, mirroring European Chemicals Agency frameworks. This regulatory alignment forces Gulf exporters to reconfigure product dossiers for dual-market entry. Fine fragrance houses operating across both jurisdictions are consolidating formulation architectures around pre-screened base accords that satisfy both SASO and South African compliance thresholds.
Direct procurement relationships between UAE-based fragrance compounding operations and specialty chemical distributors are displacing traditional multi-tier import channels. Dubai's Jebel Ali free zone operators now source synthetic musks and vanillin variants through captive supply agreements with biotechnology producers, bypassing European trading houses. This channel compression is most visible in oud-inspired luxury perfume manufacturing, where formulation houses prioritize supply security over historical supplier relationships.
Middle East and Africa Aroma Chemicals Market Segmentation
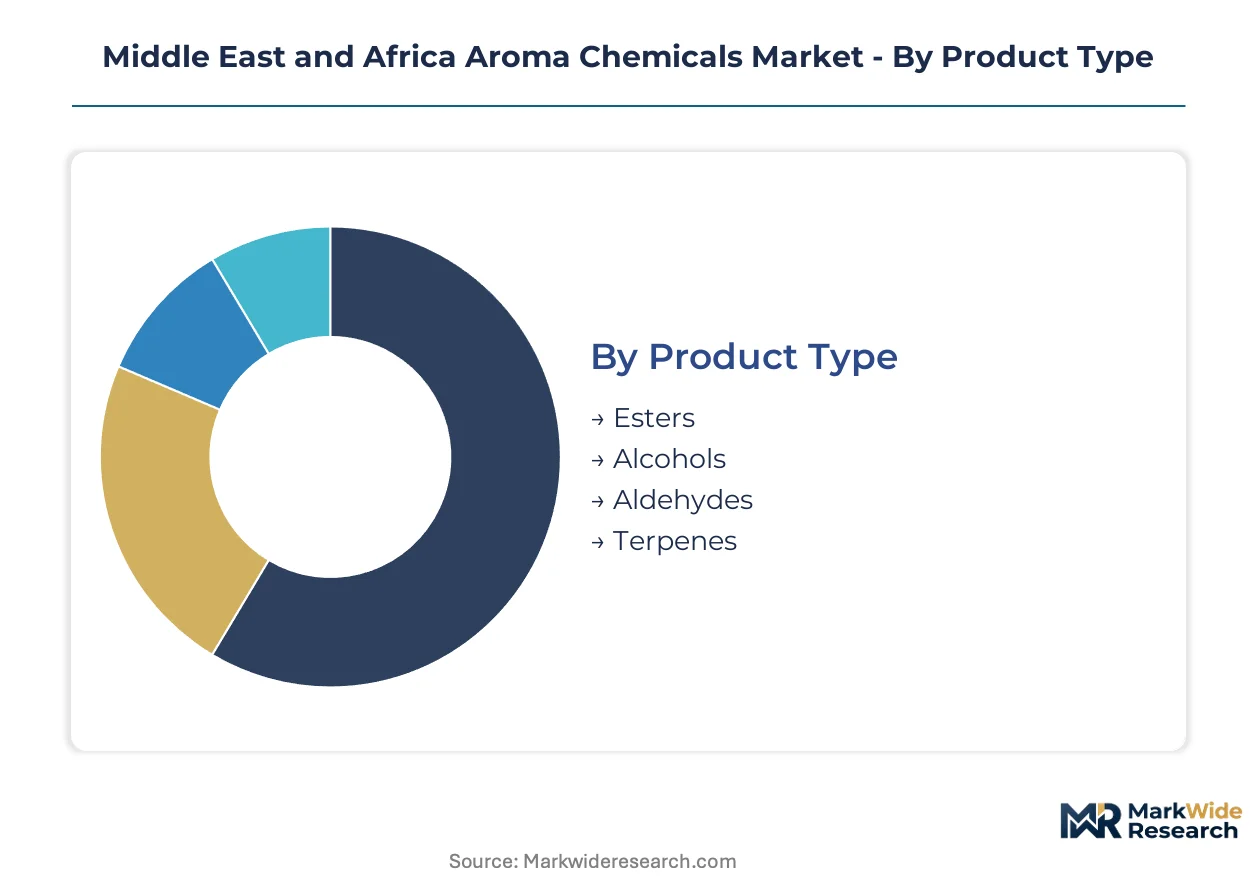
Aroma chemicals serve distinct functional roles across formulation architectures, with integration depth determining whether molecules operate as standalone fragrance systems or embedded components within complex bases. Segmentation reveals where procurement concentrates and where specification requirements diverge.
Product Type:
Integration depth varies sharply across molecular classes, with some compounds functioning as finished fragrance accords while others require compounding into proprietary bases.
- Esters:These fruity, sweet-scented molecules dominate food and beverage applications where ethyl acetate and isoamyl acetate deliver consistent flavor profiles. Demand concentrates in Saudi Arabia's soft drink manufacturing corridor, where SASO-compliant formulations require precise volatility specifications.
- Aldehydes:C8-C14 straight-chain variants provide signature floral brightness at low inclusion rates. Fine fragrance houses across the United Arab Emirates specify these molecules for oud-based luxury perfumes where molecular precision commands premium positioning.
- Alcohols:Benzyl alcohol and phenethyl alcohol serve as solvents and fragrance carriers in cosmetic formulations. South African personal care manufacturers source these through Jebel Ali re-export channels.
- Terpenes:Limonene and pinene derivatives anchor natural-positioned cleaning products. Ethiopian household chemical formulators increasingly specify biocatalytic terpene oxides for regional distribution networks.
Volume placements concentrate in Esters; the faster expansion belongs to Aldehydes.
Application:
Cost tier stratification separates commodity-scale food systems from precision-engineered fine fragrance architectures.
- Perfumery:Fine fragrance formulation demands chiral purity and batch consistency for oud-inspired luxury products. Dubai-based compounding operations source synthetic musks through direct biotechnology producer agreements, bypassing traditional European trading tiers.
- Food & Beverages:Flavor systems require GRAS-compliant esters with documented safety profiles. Saudi Food and Drug Authority mandates traceability documentation for all aroma chemicals entering food-contact applications.
- Cosmetics:South Africa's updated allergen disclosure rules force reformulation around pre-screened base accords. Manufacturers serving both Gulf and South African markets face dual certification timelines.
- Cleaning Products:Natural-positioned formulations drive limonene and pinene derivative procurement. South African household chemical producers adopt enzymatic biotransformation routes to satisfy eco-label requirements.
Revenue margins peak in Perfumery; the steepest volume climb occurs in Cleaning Products.
End User:
Customer type determines specification intensity, with laboratories demanding analytical-grade purity while manufacturers prioritize supply security.
- Manufacturers:Fragrance and flavor houses across the Gulf Cooperation Council consolidate procurement through Jebel Ali free zone compounding operations. These stakeholders prioritize captive supply agreements for synthetic musks and vanillin variants.
- Retailers:Specialty chemical distributors serving Sub-Saharan Africa source through Dubai re-export corridors. Ethiopian and Kenyan markets remain underdeveloped, creating first-mover positioning opportunities.
- Laboratories:Analytical and quality control facilities require reference-grade materials with documented certificates of analysis. South African Bureau of Standards certification adds compliance layers for imported consignments.
- Distributors:Regional trading houses manage multi-market logistics across divergent regulatory frameworks. Gulf Standards Organization harmonization reduces friction for Saudi Arabia, UAE, and Kuwait entries.
Procurement scale concentrates in Manufacturers; the expanding service intensity belongs to Laboratories.
Sales Channel:
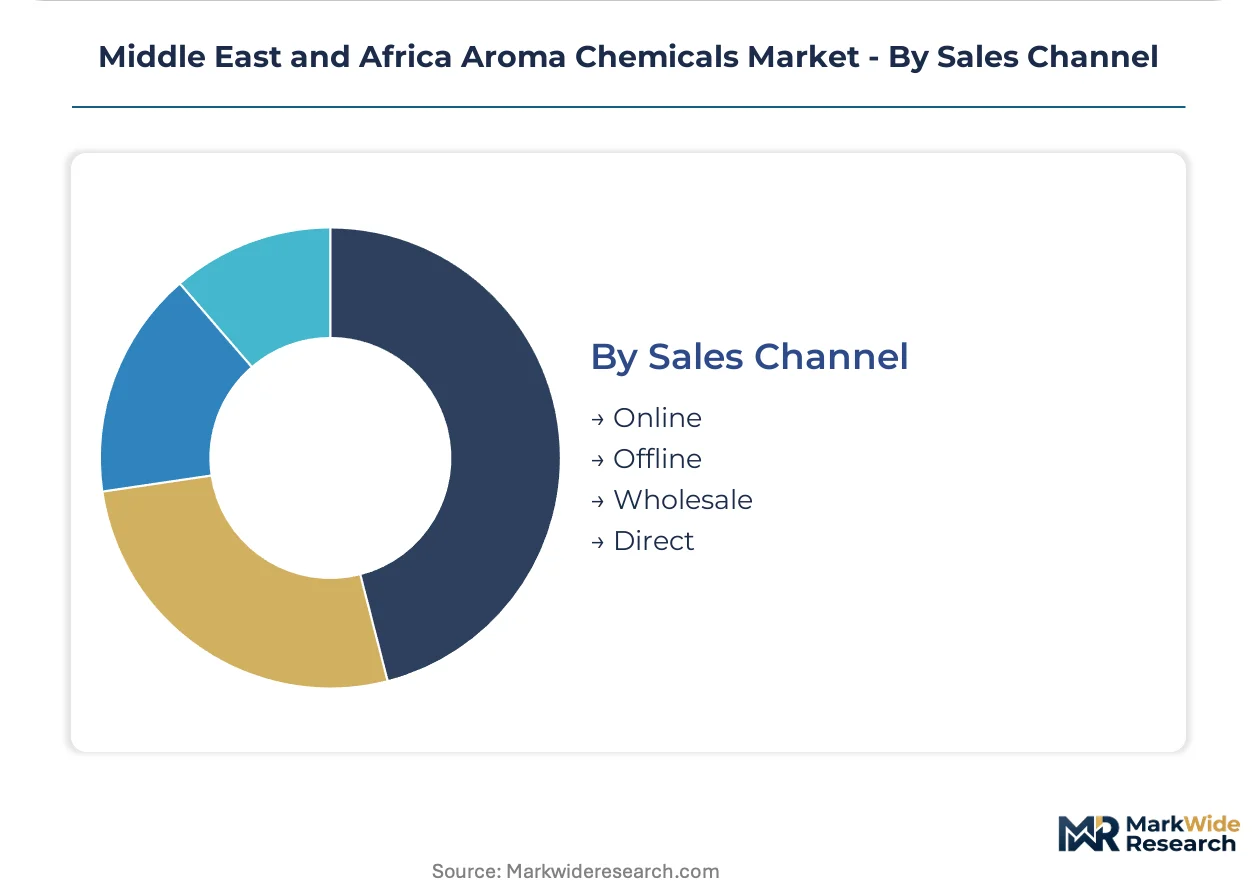
Supply concentration shapes channel selection, with bulk commodities flowing through wholesale tiers while specialty molecules favor direct relationships.
- Online:Digital procurement platforms serve small-batch laboratory and specialty formulator needs. Limited regional e-commerce infrastructure constrains penetration outside South Africa and the United Arab Emirates.
- Offline:Traditional distributor networks dominate commodity ester and alcohol movements. Physical presence remains essential for regulatory documentation and customs clearance support.
- Wholesale:Bulk terpenes and standard-grade aldehydes move through consolidated trading houses. Jebel Ali operators leverage wholesale aggregation for Sub-Saharan African re-export.
- Direct:Biotechnology producers of synthetic musks and vanillin establish captive supply relationships with major Gulf fragrance houses. Channel compression eliminates intermediary margins and secures batch traceability.
Transaction volume concentrates in Wholesale; the most rapid channel shift occurs in Direct.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Dubai's Jebel Ali free zone concentrates aroma chemical compounding operations serving re-export corridors across Sub-Saharan Africa and South Asia. This tax-advantaged cluster anchors regional supply security for fragrance houses and flavor manufacturers.
United Arab Emirates
Fine fragrance formulation houses in Dubai source synthetic musks through direct biotechnology producer agreements. Emirates Authority for Standardization and Metrology mandates compliance documentation for cosmetic-grade imports. Jebel Ali free zone operators bypass European trading tiers through captive supply relationships with vanillin and musk producers.
Saudi Arabia
Soft drink manufacturing corridors in Riyadh and Jeddah drive ester procurement for flavor systems. Saudi Food and Drug Authority requires traceability documentation for all aroma chemicals entering food-contact applications. Eastern Province industrial zones host concentrated procurement from Gulf Standards Organization-compliant suppliers.
South Africa
Household chemical manufacturers in Johannesburg and Cape Town adopt enzymatic biotransformation routes for limonene-derived cleaning actives. National Regulator for Compulsory Specifications enforces fragrance allergen labeling mirroring EU REACH thresholds. Durban chemical processing clusters face dual certification timelines for Gulf and domestic market entry.
Ethiopia
Underdeveloped aroma chemical production infrastructure creates first-mover positioning for specialty ester manufacturing. The country's national industrial regulator applies emerging standards for chemical imports. Addis Ababa distribution networks serve expanding East African markets with limited local compounding capacity.
Israel
Specialty chemical distributors in Tel Aviv supply analytical-grade reference materials for quality control laboratories. The national standards institute maintains certification protocols aligned with European frameworks. Haifa chemical processing zones concentrate on high-purity alcohols for cosmetic and pharmaceutical applications.
Middle East and Africa Aroma Chemicals Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with biotechnology-derived molecules commanding premium positioning against commodity synthetics. The vendor base clusters around three archetypes: integrated fragrance houses with captive synthesis capabilities, specialty chemical distributors serving re-export markets, and regional compounding operations leveraging free-zone tax advantages. Dominant competitive moves include direct procurement relationships eliminating intermediary tiers and backward integration into fermentation-based production routes.
Within the integrated fragrance house tier, Symrise AG and Givaudan SA exemplify archetypes combining regional compounding infrastructure with biotechnology capabilities. Takasago International Corporation occupies a distinct position through asymmetric catalysis expertise applied to chiral aroma molecules. These three entities anchor competitive dynamics across Gulf Cooperation Council formulation markets.
| Leading Market Players |
|---|
| Symrise AG |
| Takasago International Corporation |
| Givaudan SA |
| Takamol |
| DSM |
| Firmenich SA |
| BASF SE |
| Al Haramain Perfumes |
| International Flavors & Fragrances Inc. |
| Others |
Supply & Pricing Matrix
Citrus-derived limonene spot prices cascade through Middle East and Africa aroma chemical supply chains, compressing margin pools for cleaning product formulators while amplifying pricing power for synthetic musk producers serving Gulf fragrance houses. This raw material volatility stratifies procurement costs across three distinct buyer tiers, with Jebel Ali free zone operators capturing arbitrage advantages through captive biotechnology agreements.
Pricing Analysis
Short lead time premiums command 15-25% markups over standard contract pricing as Dubai-based fragrance houses prioritize supply security for oud-based formulations. Three-tier pricing structure across premium, standard, and economy levels separates chiral-grade aldehydes from standard esters and bulk terpenes, with certification grade and volume scale as primary differentiation drivers. Cost compression in synthetic vanillin intensifies because microbial fermentation routes displace traditional chemical synthesis. Small-batch laboratory buyers exhibit highest price sensitivity; integrated fragrance houses demonstrate lowest sensitivity due to captive supply agreements.
Supply Chain Analysis
Freight cost differentials between Mediterranean citrus processing hubs and Jebel Ali consolidation points add 8-12% to landed terpene costs for East African distributors. Supply concentrates in the United Arab Emirates, Saudi Arabia, and South Africa, with raw material dependencies on Mediterranean limonene, Chinese synthetic musk intermediates, and Indian vanillin precursors. Single-source vulnerability in biotechnology-derived musk molecules threatens formulation continuity for luxury perfumers. Distribution runs through Dubai re-export corridors into Sub-Saharan Africa, bypassing traditional European trading tiers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a cost-of-compliance story where South Africa's National Regulator for Compulsory Specifications allergen disclosure mandates erect barrier-to-entry moats favoring pre-certified suppliers with dual-market dossiers.
For Market Incumbents: Deploy backward integration into CRISPR-edited yeast fermentation platforms to secure captive synthetic musk supply chains against biotechnology substitution threats. Consolidate regulatory affairs capabilities to compress dual certification timelines for Gulf Standards Organization and South African Bureau of Standards compliance. Channel control through Jebel Ali free zone compounding infrastructure locks out trading-tier competitors. For New Entrants and Emerging Players: Begin with Ethiopian specialty ester manufacturing targeting underdeveloped East African distribution networks where local compounding capacity remains absent. Penetrate the biocatalytic terpene oxide segment serving South African eco-label cleaning product reformulators. A direct procurement relationship model with Addis Ababa-based distributors bypasses wholesale margin extraction. For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-scale chiral synthesis specialists in Israel with asymmetric catalysis expertise transferable to Gulf fine fragrance markets. Long-term viability hinges on biotechnology convergence capabilities over the next decade. Watch for Emirates Authority for Standardization and Metrology documentation streamlining as inflection signal for UAE market entry acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Fermentation | Captive synthetic musk production eliminates European trading house dependencies for Dubai fragrance compounders. |
| Dual Certification Investment | Simultaneous Gulf Standards Organization and South African Bureau of Standards compliance compresses product launch cycles. |
| Direct Procurement Relationships | Biotechnology producer agreements bypass intermediary margins and secure batch traceability for oud-based formulations. |
| Ethiopian Manufacturing Footprint | First-mover specialty ester production captures East African markets with limited local compounding infrastructure. |
| Enzymatic Biotransformation Adoption | South African household chemical manufacturers satisfy natural-positioning claims without sacrificing batch consistency. |
Research Methodology
Document review covered customs and trade data, Gulf Standards Organization technical regulations, South African Bureau of Standards certification protocols, and SEC filings from integrated fragrance houses, complemented by interviews with fragrance house procurement directors, Jebel Ali free zone compounding operators, South African household chemical plant managers, and Ethiopian distribution channel partners. Secondary validation drew from Emirates Authority for Standardization and Metrology import documentation, Saudi Food and Drug Authority traceability requirements, and biotechnology producer capacity disclosures. Bottom-up volume modeling and top-down value triangulation anchored forecast integrity.
Segment-level projections across the analysis window reflect molecular class stratification, application intensity tiers, and regional regulatory cluster divergence, with CAGR derivation incorporating synthetic substitution elasticities and compliance cost pass-through assumptions. Chiral purity specifications and allergen disclosure threshold alignment served as industry-specific forecast inputs.
Underlying measurement precision varies by segment; synthetic musk and chiral aldehyde categories carry tighter precision than commodity terpene derivatives due to concentrated supplier bases. Forecasts reflect assumptions regarding biotechnology adoption curves and regulatory harmonization progress that could shift materially. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Flavor and Fragrance Chemicals
Citral Market
Flavor and Fragrance Chemicals
Ferulic Acid Market
Flavor and Fragrance Chemicals
Synthetic Cinnamaldehyde Market
Flavor and Fragrance Chemicals
Sensory Modifiers Market
Flavor and Fragrance Chemicals
India Aroma Chemicals Market
Flavor and Fragrance Chemicals
Arborvitae Oil Market
Flavor and Fragrance Chemicals
Citronellol Market
Flavor and Fragrance Chemicals
Cedrol Methyl Ether Market
Flavor and Fragrance Chemicals
Tangerine Oil Market
Flavor and Fragrance Chemicals
United States Aroma Chemicals Market
Flavor and Fragrance Chemicals
Fragrance Ingredients Market
Flavor and Fragrance Chemicals
Immortelle Oil Market
Flavor and Fragrance Chemicals
Fragrance Wax Melts Market
Flavor and Fragrance Chemicals
Hydroxycitronellal Market
Flavor and Fragrance Chemicals
Limonene Market
Flavor and Fragrance Chemicals
Massoia Bark Essential Oil Market