
 United States Aroma Chemicals Market | 2026-2036
United States Aroma Chemicals Market Size, Share, and Industry Trends Forecast 2026-2036
United States Aroma Chemicals Market Intelligence
Specialty chemical producers along the Gulf Coast is repositioning capacity toward higher-margin fragrance intermediates. BASF SE leverages integrated petrochemical feedstocks to sustain cost advantages in bulk synthetic aroma molecules. Symrise AG anchors its North American operations through R&D intensity in natural extraction technologies. Vigon International Inc competes on formulation services and custom blending capabilities for mid-tier fragrance houses.
Aroma chemicals constitute volatile and semi-volatile organic compounds—including esters, aldehydes, terpenes, and ketones—synthesized or extracted for olfactory functional performance at concentrations measured in parts per million. These materials serve as the foundational building blocks in perfumes, flavored formulations, and scented consumer products where sensory consistency and regulatory compliance determine commercial viability. Synthetic aroma molecules dominate volume flows due to supply security and batch-to-batch uniformity, though natural extracts command premium positioning in clean-label personal care segments. Food & Beverage applications concentrate demand for GRAS-certified flavor compounds, while Pharmaceutical-grade aroma chemicals face the most stringent purity thresholds and documentation requirements.
FDA oversight through Food Additive Regulations and FEMA GRAS determinations governs ingestible aroma chemical approvals, while EPA TSCA Section 5 premanufacture notifications constrain novel synthetic introductions. OSHA Permissible Exposure Limits for volatile organic compounds shape workplace handling protocols and capital equipment requirements at compounding facilities. Stakeholders must monitor pending FDA guidance on natural flavor labeling and state-level green chemistry initiatives that could redirect formulation investments.
Market Dynamics
Bio-based aroma molecule production is concentrating investment in New Jersey's chemical corridor, where fragrance houses reposition supply chains to meet personal care brands' clean-label procurement mandates while navigating EPA TSCA Section 5 premanufacture notification delays.
Growth Catalysts
- Clean-label personal care procurement:Personal care brands are expanding specifications for naturally derived aroma chemicals, pulling volume toward bio-based extraction technologies and GRAS-certified flavor compounds.
- FEMA GRAS pathway efficiency:Food and beverage manufacturers leverage existing FEMA GRAS determinations to accelerate new flavor compound adoption, reducing regulatory friction for ingestible aroma chemical introductions.
- Gulf Coast capacity repositioning:Specialty chemical producers are redirecting petrochemical infrastructure toward higher-margin fragrance intermediates, capturing margin expansion in synthetic aroma molecule production.
Market Restraints
- EPA TSCA Section 5 timeline extension:New chemical substance registrations require extended premanufacture notification reviews, stretching development cycles for domestic formulators introducing novel synthetic molecules.
- Natural feedstock supply concentration:Botanical extraction depends on concentrated agricultural sourcing regions, exposing natural aroma chemical production to climate volatility and crop yield fluctuations.
- Petrochemical input cost pass-through:Synthetic aroma molecule margins compress when integrated feedstock advantages erode during energy price spikes, particularly affecting bulk ester and terpene production economics.
Strategic Opportunities
- Pharmaceutical-grade purity tier expansion:Aroma chemical producers can capture premium positioning by meeting USP-grade documentation and purity thresholds for therapeutic and nutraceutical applications.
- State-level green chemistry procurement mandates:California and New York clean chemistry initiatives are redirecting institutional purchasing toward bio-based formulations, creating preferential market access for compliant suppliers.
- Biotechnology-fermentation convergence:Microbial synthesis platforms combined with traditional extraction are enabling novel molecule production pathways that bypass agricultural feedstock constraints.
Industry Challenges
- Flavor chemist talent scarcity:Specialized formulation expertise in natural extraction and sensory evaluation functions faces recruitment bottlenecks as demand for clean-label product development accelerates.
- Multi-jurisdictional compliance documentation:OSHA Permissible Exposure Limits for volatile organic compounds require capital-intensive workplace handling infrastructure, particularly at compounding facilities serving multiple regulatory zones.
- Batch-to-batch natural variability management:Botanical sourcing inconsistency demands sophisticated quality control systems to maintain sensory uniformity in premium fragrance and flavor formulations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States Aroma Chemicals Market |
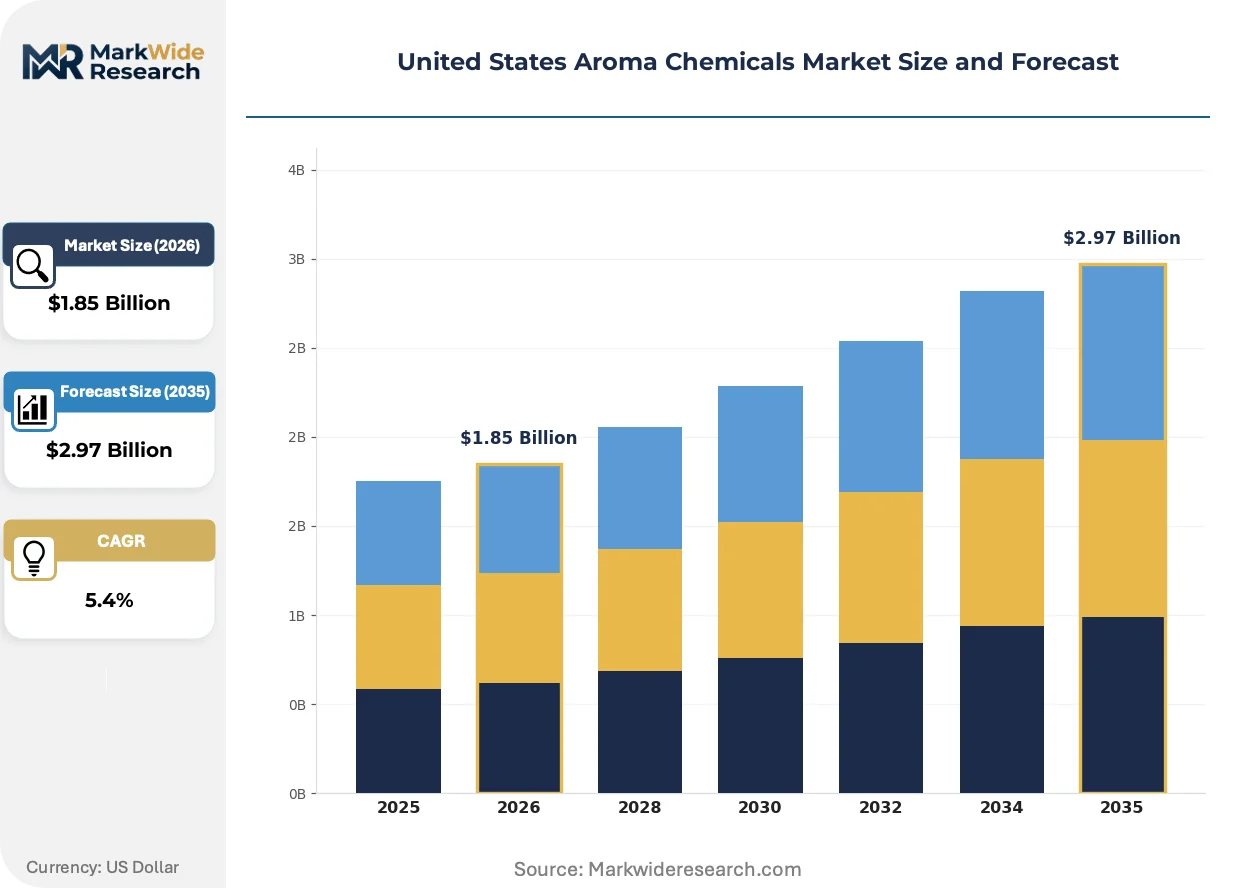
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $2.97 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Natural, Synthetic, Aroma Extracts, Flavor Compounds Application: Food & Beverage, Personal Care, Household Products, Pharmaceuticals End User: Food Manufacturers, Cosmetic Brands, Cleaning Companies, Drug Manufacturers Distribution Channel: Online Retailers, Direct Sales, Distributors, Specialty Stores |
| Companies Covered | BASF SE, Symrise AG, Vigon International Inc, Solvay, Takasago International Corp, SH Kelkar & Company Ltd, Prinova Group LLC, JNC Corporation, Kao Corporation, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States Aroma Chemicals Market Strategic Shifts & Innovations
Biotechnology platforms are rewriting competitive boundaries in aroma chemical production, displacing traditional extraction and petrochemical synthesis with microbial fermentation routes that reduce agricultural dependency and enable novel molecular architectures.
Precision fermentation using engineered yeast strains is rewriting how specialty esters and terpenoids reach commercial scale. Fragrance houses and flavor compounders are integrating these biomanufactured molecules into formulations at accelerating rates, compressing the traditional agricultural-to-shelf timeline from seasons to weeks.
EPA enforcement priorities under TSCA Section 5 are tightening scrutiny of persistent, bioaccumulative, and toxic substances in fragrance applications. This regulatory pressure is forcing reformulation investments across personal care segments, with mid-tier fragrance houses facing the steepest compliance cost burdens relative to integrated multinational competitors.
Direct procurement relationships between personal care brands and biotechnology producers are shortening traditional distribution channels. Fragrance houses are responding by embedding formulation scientists within customer R&D facilities, particularly in California and New Jersey where clean-label product development concentrates, converting transactional supply relationships into co-development partnerships.
United States Aroma Chemicals Market Segmentation
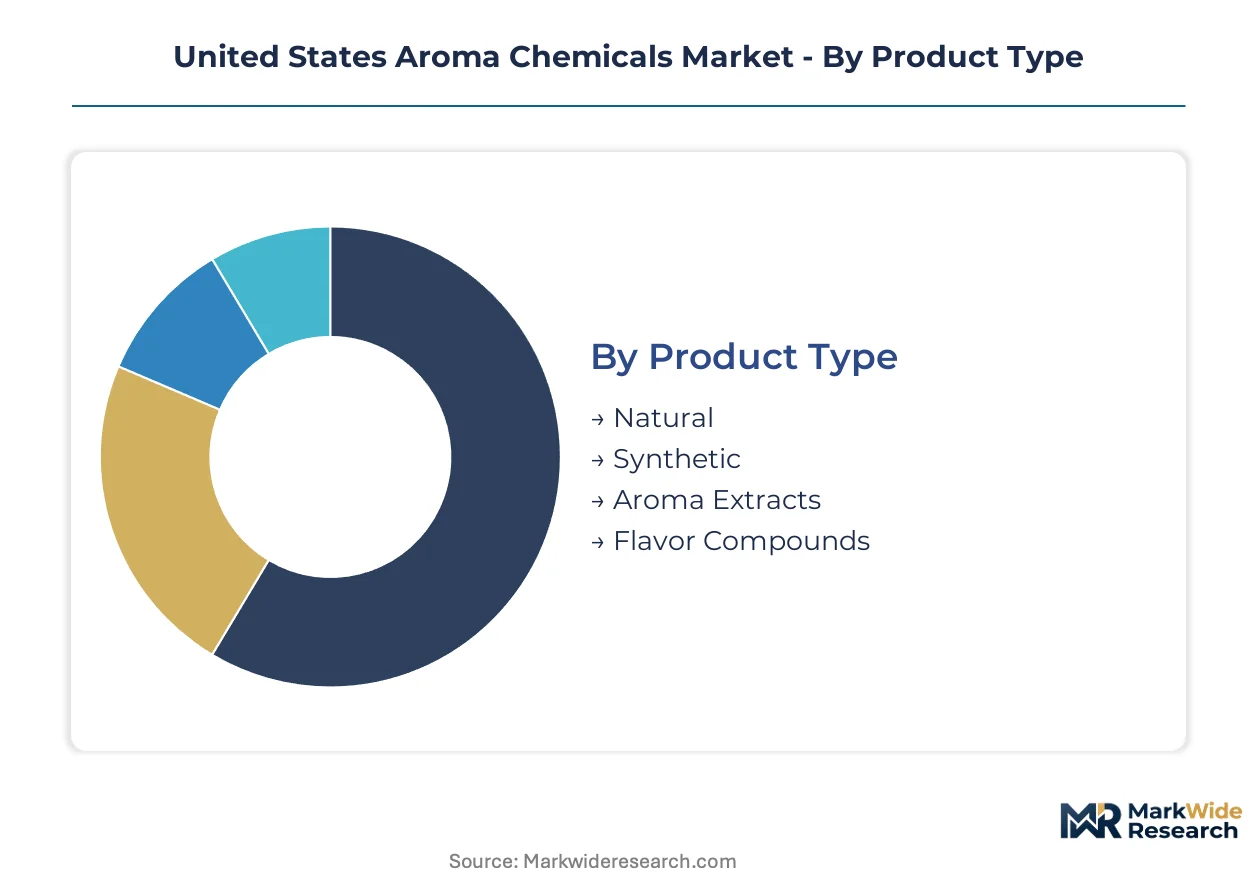
Segmentation in the United States aroma chemicals market reveals how formulation specifications, regulatory pathways, and procurement relationships fragment commercial opportunity across distinct technology and customer clusters. Each axis carries unique margin profiles and compliance burdens that reshape competitive positioning for domestic suppliers.
Product Type:
Synthetic versus natural molecular architectures define the core technical divide, with extraction methods and petrochemical feedstock dependencies creating divergent cost structures and regulatory exposure for domestic producers.
- Synthetic:Petrochemical-derived esters, aldehydes, and terpenes manufactured through catalytic synthesis deliver batch-to-batch uniformity essential for mass-market fragrance formulations. Demand concentrates in New Jersey's chemical corridor where integrated producers leverage Gulf Coast feedstock access to serve high-volume personal care brands with price-stable supply contracts.
- Natural:Botanical extracts and essential oils sourced from concentrated agricultural regions face climate-driven yield volatility that demands sophisticated quality control systems. Clean-label procurement mandates from California and New York personal care brands are pulling volume toward GRAS-certified natural molecules despite premium pricing and EPA TSCA notification complexities for novel extraction derivatives.
- Aroma Extracts:Concentrated volatile fractions from plant material requiring solvent or steam distillation processes.
- Flavor Compounds:GRAS-certified molecules governed by FDA Food Additive Regulations and FEMA determinations for ingestible applications.
Mature deployment sits with Synthetic molecules in bulk fragrance intermediates. Newer deployment is concentrated in Natural extracts for clean-label personal care positioning.
Application:
End-use specifications create tiered purity and documentation requirements, with pharmaceutical and food applications imposing the most stringent compliance thresholds on domestic formulators.
- Personal Care:Fragrance formulations for cosmetics, skincare, and hair care products where sensory consistency and regulatory safety documentation determine supplier selection. Procurement is shifting toward bio-based molecules as brands respond to state-level green chemistry mandates, particularly in California where clean-label product development concentrates.
- Food & Beverage:Ingestible flavor compounds requiring FDA GRAS certification or FEMA determinations, with manufacturers leveraging existing regulatory pathways to accelerate new compound adoption. Volume flows through New Jersey compounding clusters maintaining proximity to major food manufacturing customers.
- Household Products:Functional fragrances for cleaners and air care where cost efficiency dominates formulation decisions.
- Pharmaceuticals:USP-grade aroma chemicals for therapeutic and nutraceutical applications commanding premium positioning through documentation intensity.
Volume leadership belongs to Personal Care applications. Steepest expansion trajectory is emerging in Pharmaceuticals-grade purity tiers.
End User:
Customer scale and technical capability determine whether procurement flows through fragrance house intermediaries or direct biotechnology producer relationships.
- Cosmetic Brands:Mid-tier and multinational personal care companies embedding formulation scientists within supplier R&D facilities to compress development timelines.
- Food Manufacturers:Processed food and beverage producers leveraging FEMA GRAS pathways for rapid flavor compound integration.
- Cleaning Companies:Household product formulators prioritizing cost-stable synthetic molecule supply for functional fragrance applications.
- Drug Manufacturers:Pharmaceutical companies demanding USP-grade documentation and purity thresholds for therapeutic applications.
Established relationships dominate Food Manufacturers. Emerging direct procurement patterns are reshaping Cosmetic Brands supplier engagement.
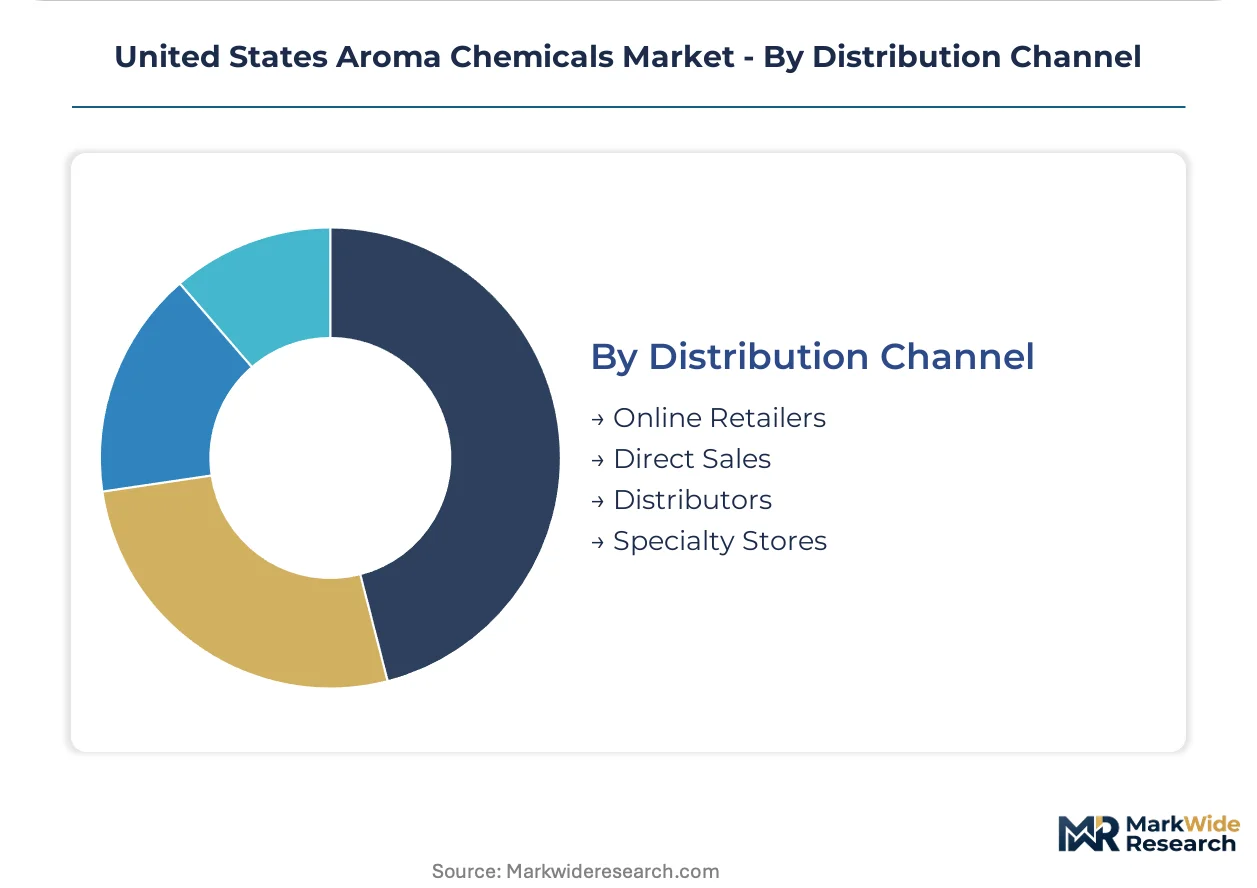
Distribution Channel:
Channel selection reflects order scale, technical service requirements, and geographic proximity to compounding infrastructure.
- Distributors:Regional chemical distributors maintaining inventory positions for mid-tier fragrance houses and smaller formulators requiring technical support and blended product access.
- Direct Sales:Large-volume relationships between integrated producers and multinational personal care or food brands bypassing intermediaries.
- Online Retailers:E-commerce platforms serving small-batch formulators and specialty product developers with catalog-standard molecules.
- Specialty Stores:Niche suppliers catering to artisan fragrance creators and natural product formulators with curated extraction portfolios.
Volume concentration rests with Direct Sales. Channel experimentation is accelerating through Online Retailers serving fragmented demand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Petrochemical feedstock access along the Gulf Coast anchors United States production capacity for synthetic aroma molecules. State-level clean chemistry mandates in coastal markets are redirecting procurement patterns toward bio-based extraction clusters. Regulatory fragmentation between EPA TSCA enforcement and California Air Resources Board standards creates compliance complexity for multi-state suppliers.
Gulf Coast Region
Specialty chemical producers leverage integrated refinery infrastructure to manufacture bulk esters and terpenes for high-volume personal care contracts. EPA TSCA Section 5 premanufacture notifications constrain novel molecule introductions from Texas and Louisiana facilities. Houston-area compounding sites serve multinational fragrance houses with price-stable synthetic supply agreements.
New Jersey Chemical Corridor
Fragrance houses concentrate R&D and formulation operations to maintain proximity to pharmaceutical and food manufacturing customers. FDA Food Additive Regulations and FEMA GRAS determinations govern ingestible compound approvals processed through Princeton and Edison facilities. Newark-Elizabeth port infrastructure enables efficient botanical extract importation for natural molecule production.
California
Personal care brands headquartered in Los Angeles and San Francisco drive clean-label procurement specifications for bio-based aroma molecules. California Air Resources Board volatile organic compound regulations exceed federal OSHA Permissible Exposure Limits, requiring capital-intensive handling equipment at compounding facilities. Bay Area biotechnology firms pioneer microbial fermentation platforms for novel terpenoid synthesis.
Midwest Manufacturing Belt
Food and beverage manufacturers in Illinois and Ohio leverage existing FEMA GRAS pathways for rapid flavor compound integration. USDA agricultural inspection protocols govern botanical feedstock quality for natural extraction operations near Chicago. Cincinnati-area distributors maintain inventory positions serving mid-tier fragrance houses across the Ohio River Valley.
Pacific Northwest
Premium personal care brands in Seattle and Portland prioritize sustainably sourced natural extracts for positioning in clean beauty segments. Washington State Department of Ecology enforcement of green chemistry procurement mandates creates preferential market access for compliant bio-based suppliers. Portland-area specialty stores cater to artisan fragrance creators with curated botanical portfolios.
United States Aroma Chemicals Market Key Industry Players
Established producers occupy the standard tier; emerging entrants pursue biotechnology-fermentation convergence and direct-to-brand supply relationships. The market exhibits tiered concentration with integrated multinational chemical conglomerates commanding bulk synthetic volumes while regional specialists capture premium natural extraction niches. Strategic archetypes include petrochemical-integrated manufacturers, botanical extraction specialists, and microbial synthesis platforms. Dominant competitive moves encompass backward integration into captive feedstock supply and co-development partnerships embedding formulation scientists within customer R&D facilities.
Within the integrated multinational tier, BASF SE and Symrise AG occupy positions exemplifying divergent feedstock strategies—petrochemical integration versus natural extraction intensity. Vigon International Inc represents the mid-tier formulation services archetype competing on custom blending capabilities. These three entities anchor the competitive structure without exhaustive market coverage.
| Leading Market Players |
|---|
| BASF SE |
| Symrise AG |
| Vigon International Inc |
| Solvay |
| Takasago International Corp |
| SH Kelkar & Company Ltd |
| Prinova Group LLC |
| JNC Corporation |
| Kao Corporation |
| Others |
Cost & Logistics Intelligence
Petrochemical feedstock volatility propagates through synthetic ester and terpene production, compressing margins at Gulf Coast bulk manufacturers while premium natural extracts command stable pricing through scarcity-driven procurement from California personal care brands.
Pricing Analysis
Service bundling separates formulation support from molecule supply, with integrated fragrance houses embedding technical consultants within customer R&D facilities to justify premium positioning. Three-tier pricing structure across pharmaceutical-grade, FEMA GRAS-certified, and industrial-synthetic levels reflects documentation intensity and purity thresholds. Cost compression in bulk synthetic molecules intensifies as Gulf Coast petrochemical advantages erode during energy price spikes. Mid-tier fragrance houses exhibit acute price sensitivity, while pharmaceutical drug manufacturers prioritize USP-grade documentation over unit economics.
Supply Chain Analysis
Direct-to-brand channels handle hyperscale personal care procurement, bypassing traditional fragrance house intermediaries for microbial fermentation-derived molecules. Supply concentrates in Texas and Louisiana for petrochemical synthesis, New Jersey for compounding and formulation, and California for biotechnology platforms. Raw material dependencies span Gulf Coast refinery outputs, agricultural botanicals from concentrated growing regions, and engineered yeast strains from Bay Area biotech facilities. Single-source vulnerability in natural feedstock supply exposes production to climate-driven crop failures. Distribution runs through regional chemical distributors for mid-tier formulators and direct sales relationships for multinational brands.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
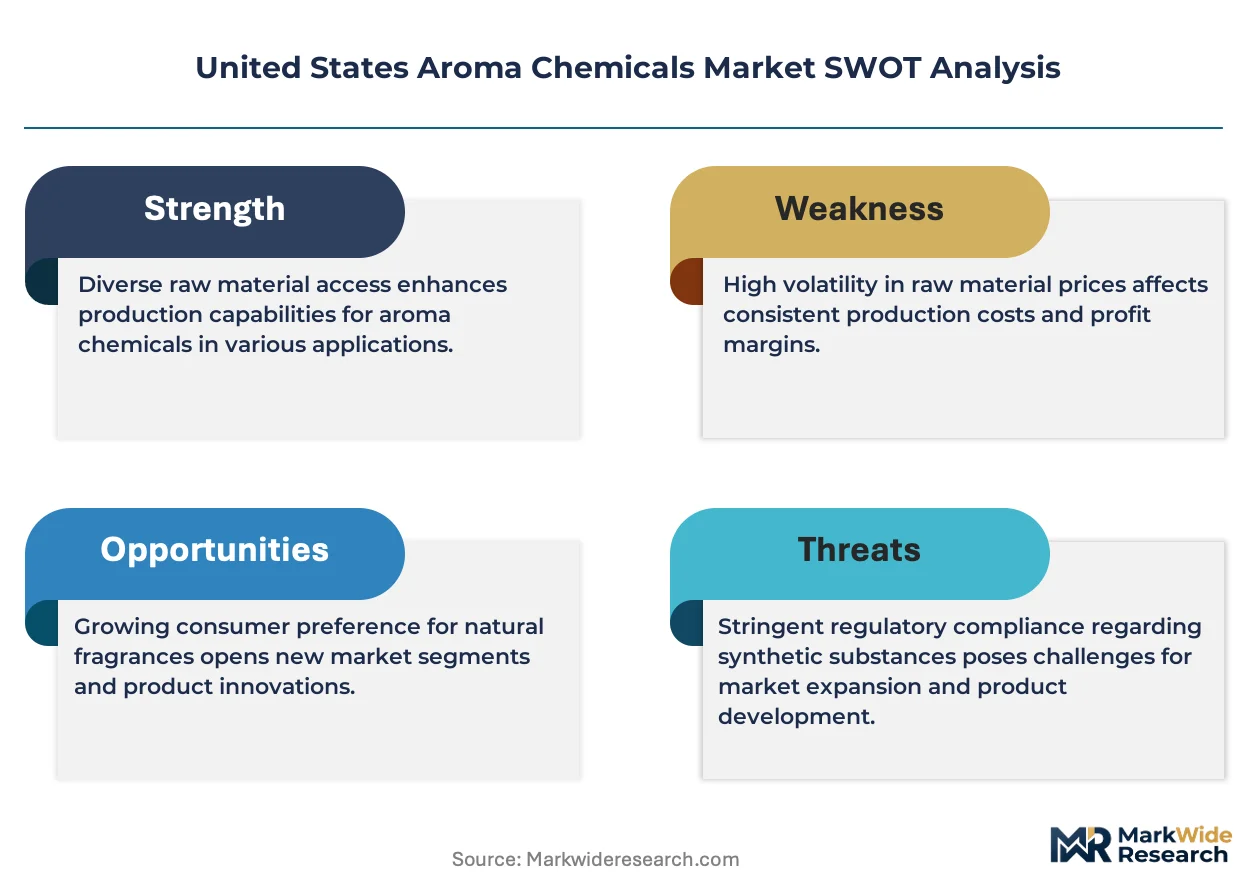
EPA TSCA Section 5 premanufacture notification requirements erect substantial compliance barriers, creating durable moats for incumbent producers with established regulatory affairs infrastructure and documented substance portfolios.
For Market Incumbents: Cement market position by deepening backward integration into captive petrochemical feedstock supply along the Gulf Coast and accelerating certification investments for pharmaceutical-grade purity tiers. Biotechnology-fermentation entrants threaten traditional extraction economics; defend by embedding formulation scientists within California and New Jersey customer R&D facilities to convert transactional supply into co-development partnerships. For New Entrants and Emerging Players: Begin with white-space targeting of pharmaceutical-grade aroma chemicals where USP documentation requirements deter commodity competitors and premium positioning sustains margin recovery. Pacific Northwest clean beauty brands present the most penetrable demand cluster for sustainably sourced natural extracts. Pursue direct procurement relationships with mid-tier personal care brands frustrated by fragrance house intermediaries. For Investors and Strategic Acquirers: California Air Resources Board enforcement actions tightening volatile organic compound standards are the leading indicator that regulatory compliance capabilities will determine acquisition premiums. Five-to-ten-year viability favors targets with established EPA notification portfolios and biotechnology fermentation platforms. Acquire specialists with microbial synthesis capabilities and GRAS-certified natural molecule libraries.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Captive Feedstock | Gulf Coast producers secure price-stable supply against energy volatility. |
| Pharmaceutical-Grade Certification Investment | USP documentation opens therapeutic and nutraceutical premium tiers. |
| Biotechnology-Fermentation Platform Development | Microbial synthesis reduces agricultural dependency and accelerates timelines. |
| Co-Development Partnership Embedding | Fragrance houses convert transactional supply into sticky R&D relationships. |
| State-Level Green Chemistry Compliance | California and New York mandates create preferential procurement access. |
Research Approach
Trade association data, regulatory filings, and customs records anchored secondary inputs, cross-referenced with primary interviews involving fragrance house procurement directors, FDA regulatory affairs specialists, personal care brand formulation scientists, and Gulf Coast plant operations managers. EPA TSCA premanufacture notification databases, FEMA GRAS determination records, SEC 10-K disclosures from listed chemical producers, and regional customs import data for botanical extracts supplied quantitative foundations. Bottom-up volume modeling triangulated against top-down market sizing from industry association aggregates.
Segment-level granularity modeled synthetic versus natural molecule architectures, pharmaceutical-grade versus FEMA GRAS versus industrial purity tiers, and personal care versus food versus pharmaceutical end-use applications across the projection horizon. CAGRs derived from regression analysis of historical volume flows projected against regulatory timeline assumptions and biotechnology adoption curves. Feedstock cost indices, clean-label procurement mandate adoption rates, and EPA enforcement priority shifts informed scenario weightings.
Underlying measurement precision varies by segment; synthetic aroma chemicals with established petrochemical supply chains carry tighter precision than novel biotechnology-fermentation molecules with unproven scale trajectories. Forecasts reflect assumptions regarding EPA review timeline durations, agricultural yield stability, and state-level green chemistry mandate expansion. Periodic stress-testing of base assumptions against regulatory enforcement patterns and energy price volatility is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Flavor and Fragrance Chemicals
Fragrance Wax Melts Market
Flavor and Fragrance Chemicals
Cedrol Methyl Ether Market
Flavor and Fragrance Chemicals
Aromatics Market
Flavor and Fragrance Chemicals
North America Aroma Chemicals Market
Flavor and Fragrance Chemicals
Dihydrocitronellol Market
Flavor and Fragrance Chemicals
Europe Flavors and Fragrances Market
Flavor and Fragrance Chemicals
Perfumes and Deodorants Market
Flavor and Fragrance Chemicals
Tannic Acid Market
Flavor and Fragrance Chemicals
Carnosic Acid Market
Flavor and Fragrance Chemicals
Musk Aroma Chemicals Market
Flavor and Fragrance Chemicals
Global Perfume Ingredients Chemicals Market
Flavor and Fragrance Chemicals
Spearmint Oil Market
Flavor and Fragrance Chemicals
Neryl Acetate Market
Flavor and Fragrance Chemicals
Perillaldehyde Market
Flavor and Fragrance Chemicals
Cedarwood Oil Market
Flavor and Fragrance Chemicals
Aroma Chemicals Market