
 Citronellol Market | 2026-2036
Citronellol Market Size, Share, and Industry Trends Forecast 2026-2036
Citronellol Market Outlook
Pharma-grade specification upgrades are rotating procurement priorities across the citronellol value chain. BASF SE leverages its integrated aroma chemicals platform to sustain supply security for high-purity grades. Privi Speciality Chemicals Limited anchors India's position in natural citronellol extraction through captive geraniol processing. International Flavours & Fragrances Inc. differentiates via biotechnology routes that reduce batch-to-batch odor variation.
Citronellol is a monoterpene alcohol with the molecular formula C10H20O, typically occurring as a colorless liquid with a rose-like odor and a specific gravity near 0.855; manufacturers derive it from citronella oil via fractional distillation or synthesize it from geraniol through catalytic hydrogenation for use as a fragrance intermediate and insect repellent active. Natural citronellol commands premium positioning among European cosmetic manufacturers seeking biodegradability credentials, while synthetic grades dominate volume flows to household products. Fragrance applications retain the largest margin pool, though insect repellent formulations represent the fastest-expanding demand segment as DEET alternatives gain regulatory traction.
REACH registration requirements in Europe impose purity and safety documentation burdens that filter out small traders, while FDA oversight in the United States governs citronellol use in topical repellents through efficacy and tolerability standards. India's BIS quality marks and China's GB standards for flavoring agents create additional compliance layers for exporters. Stakeholders must monitor regulatory divergence between fragrance-grade and biocide-grade classifications to anticipate reformulation costs and market access barriers.
Market Dynamics
REACH registration costs are consolidating the citronellol supplier base, as documentation burdens for purity and safety data filter out small traders and redirect procurement budgets toward certified-grade producers with integrated compliance capabilities.
Growth Catalysts
- EU Green Deal sourcing mandates:Fragrance houses in Germany and France face binding biodegradability requirements that accelerate natural citronellol procurement.
- DEET regulatory displacement:EPA and ECHA biocide reclassifications favor citronellol-based repellents in topical applications.
- Catalytic hydrogenation advances:Improved geraniol-to-citronellol conversion yields are expanding synthetic grade availability for household products.
Market Restraints
- Feedstock concentration risk:Natural citronellol extraction depends on citronella oil supplies concentrated in Southeast Asian plantations.
- REACH compliance cost escalation:ECHA registration fees and safety testing requirements impose fixed cost burdens that scale disproportionately for small volume producers.
- Batch odor variation:Natural extraction yields inconsistent organoleptic profiles that complicate fragrance formulation standardization.
Strategic Opportunities
- Biotechnology production routes:Microbial fermentation platforms enable citronellol biosynthesis with reduced batch-to-batch variation and bypass agricultural feedstock constraints.
- India BIS quality mark penetration:Exporters leveraging domestic geraniol processing capacity can capture premium positioning in regulated Asian markets.
- Insect repellent biocide registration:EPA 25(b) exempt product pathways and EU BPR streamlined procedures accelerate citronellol-based DEET alternatives.
Industry Challenges
- Fragrance-biocide classification divergence:Stakeholders must maintain dual compliance documentation for REACH fragrance-grade and BPR biocide-grade specifications.
- Fractional distillation capex requirements:High-purity natural citronellol production demands specialized equipment for separating optical isomers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Citronellol Market |
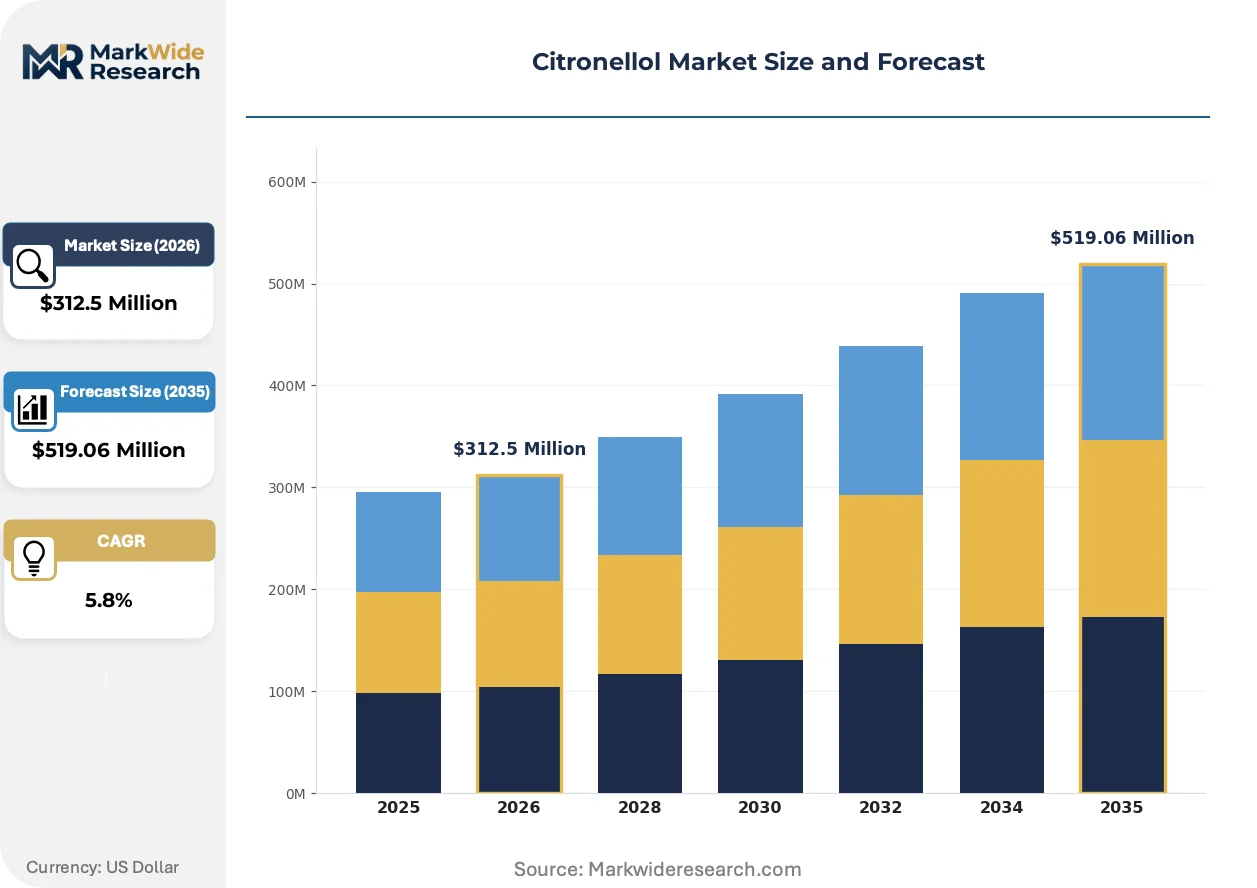
| Market Size in 2026 | $312.5 Million |
| Market Size in 2035 | $519.06 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Natural, Synthetic, Blends, Isolates Application: Fragrances, Insect Repellents, Cosmetics, Flavoring End User: Cosmetic Manufacturers, Household Products, Food Industry, Pharmaceutical Firms Distribution Channel: Online Retail, Specialty Stores, Distributors, B2B |
| Companies Covered | BASF SE, Privi Speciality Chemicals Limited, International Flavours & Fragrances Inc., Takasago International Corporation, Zhejiang NHU Co. Ltd, Capot Chemical Co., Ltd, Crescent Fragrances Private Limited, Guangzhou Baihua Flavors and Fragrances Co., Ltd., Emerald Performance Materials, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Citronellol Market Strategic Shifts
Biotechnology platforms and regulatory reclassifications are compressing traditional extraction economics while rerouting procurement toward certified supply chains with integrated compliance documentation.
Enzymatic biotransformation routes for citronellol production are miniaturizing the capital footprint required for commercial-scale output. Specialty chemical producers in Germany and the Netherlands are piloting continuous fermentation systems that reduce facility scale requirements by an order of magnitude. This technology is miniaturizing the barrier to entry for regional production, enabling distributed manufacturing closer to European fragrance clusters.
ECHA's 2023 updated REACH guidance on fragrance allergens imposes expanded labeling and concentration limits for citronellol in cosmetic formulations. Manufacturers must reformulate existing product lines or source reduced-sensitizing grades. Premium skincare brands in France are responding by demanding certified low-allergen citronellol with full supply chain traceability documentation.
Direct contracting between fragrance houses and extraction facilities is displacing traditional distributor intermediaries in European procurement. German and French perfumery clusters now source natural citronellol through multi-year offtake agreements with Malaysian and Indonesian processors. This channel consolidation is most pronounced in high-purity grades where batch consistency and documentation reliability outweigh spot-price flexibility.
Citronellol Market Segmentation
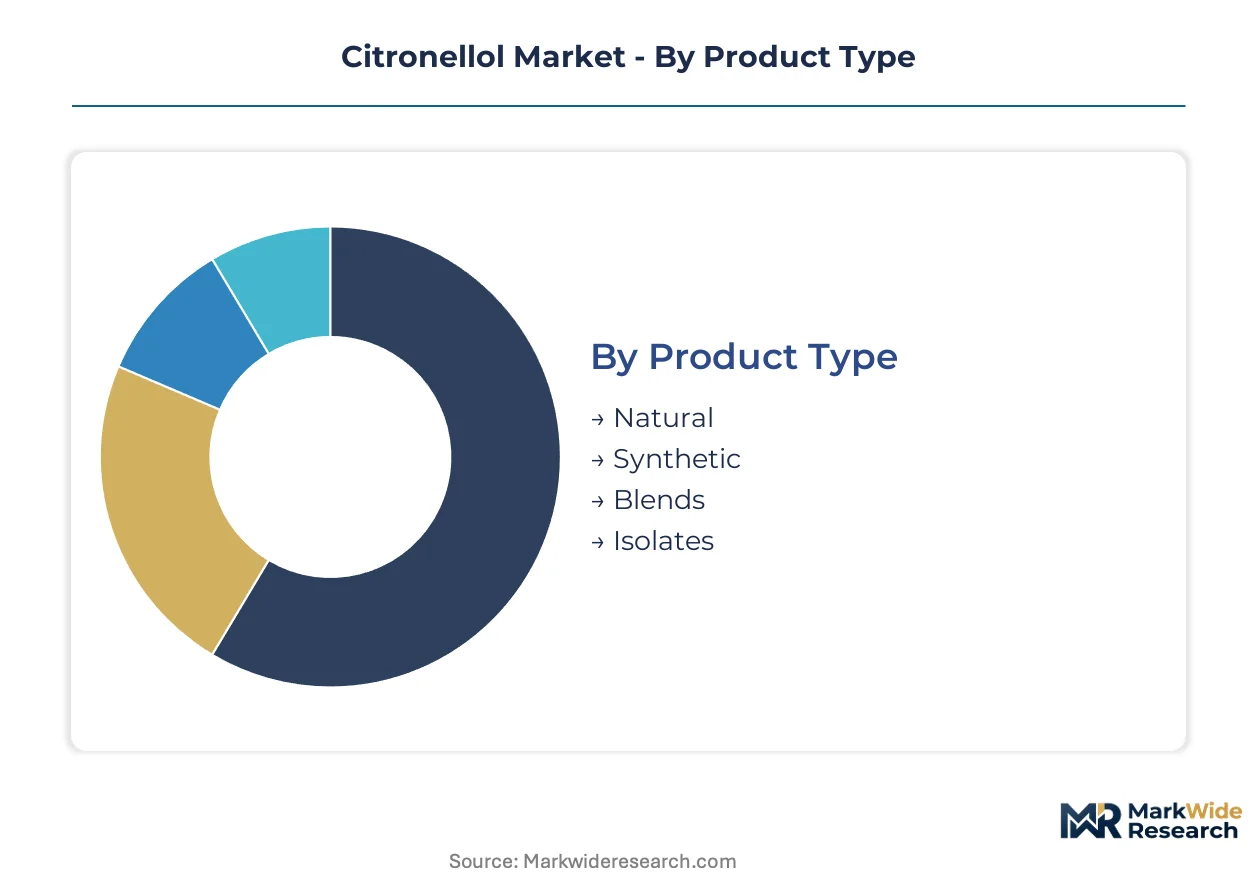
Citronellol procurement patterns diverge sharply across product grades and end-use specifications. Regulatory compliance requirements and formulation standards reshape how buyers segment their supplier base and allocate sourcing budgets.
Product Type:
Natural extraction dominates European domestic consumption, while synthetic grades flow primarily to export markets in Asia and the Americas.
- Natural:Derived from citronella oil via fractional distillation, this grade carries premium positioning for EU Green Deal biodegradability credentials. German and French fragrance houses concentrate procurement here to satisfy REACH documentation and allergen labeling requirements.
- Synthetic:Manufactured through catalytic hydrogenation of geraniol, synthetic citronellol offers batch consistency and lower unit costs. Household product manufacturers in the United States and Brazil source this grade for volume formulations where odor standardization outweighs natural claims.
- Blends:Hybrid formulations combining natural and synthetic fractions balance cost performance with partial biodegradability positioning.
- Isolates:High-purity optical isomer separations serve specialized pharmaceutical and fine fragrance applications demanding precise organoleptic profiles.
Natural citronellol commands the established base. The steepest expansion runs through synthetic grades as hydrogenation yields improve.
Application:
Cost tier differentiation separates premium fragrance formulations from mass-market functional applications.
- Fragrances:Fine perfumery and personal care products absorb the highest-margin citronellol grades, with European houses specifying full supply chain traceability. ECHA fragrance allergen limits are forcing reformulation toward reduced-sensitizing isolates.
- Insect Repellents:Topical DEET alternatives represent the volume growth frontier, with EPA 25(b) exempt pathways and EU BPR streamlined procedures accelerating product registration. Efficacy testing standards govern tolerability thresholds.
- Cosmetics:Skincare and color cosmetic applications demand certified low-allergen grades with expanded safety documentation under REACH cosmetic regulation.
- Flavoring:Food-grade specifications under EFSA and FDA oversight require purity thresholds distinct from fragrance applications, limiting supplier qualification.
Fragrance applications retain margin leadership. Insect repellent formulations are climbing the fastest as biocide reclassifications favor citronellol-based actives.
End User:
Customer type determines volume scale and specification stringency, from bulk household product manufacturers to specialized pharmaceutical compounders.
- Cosmetic Manufacturers:Premium skincare and color cosmetic brands in France and Germany drive demand for certified natural grades with full documentation chains.
- Household Products:Surface cleaners and air care brands purchase synthetic citronellol in bulk volumes, prioritizing price stability over optical purity.
- Food Industry:Flavor houses require food-grade certifications under national safety frameworks, with India's BIS marks and China's GB standards creating additional compliance layers for exporters.
- Pharmaceutical Firms:Drug manufacturers source pharma-grade isolates for topical formulations, with FDA and EMA specifications governing impurity profiles.
Cosmetic manufacturers anchor the premium tier. Pharmaceutical firms are gaining share fastest as topical repellent drug approvals expand.
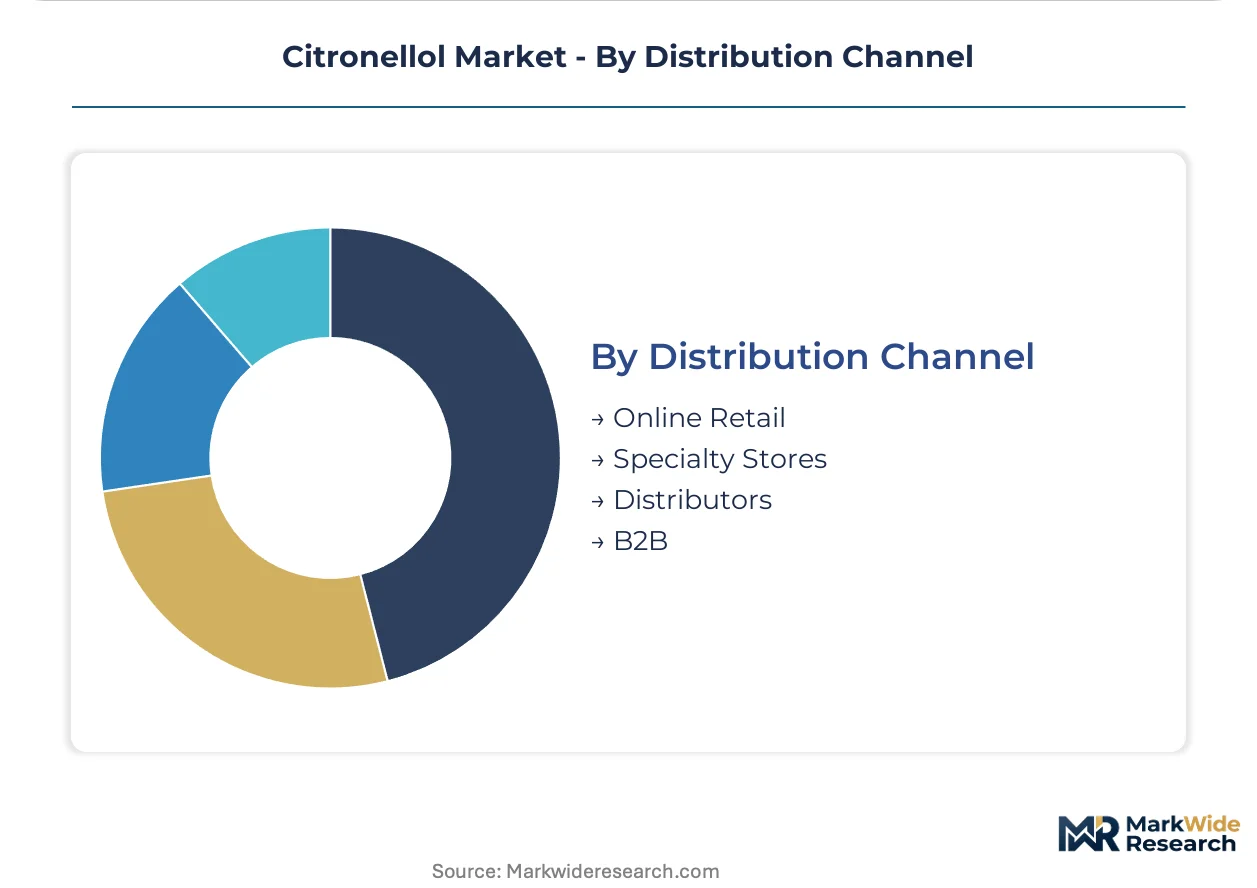
Distribution Channel:
Supply concentration shapes channel selection, with direct contracting displacing intermediaries in high-purity segments.
- Online Retail:Small-volume specialty chemical purchasers access standard grades through digital platforms, though documentation reliability varies.
- Specialty Stores:Regional fragrance ingredient suppliers in Grasse and Munich serve formulators requiring rapid sample turnaround and technical consultation.
- Distributors:Traditional intermediaries retain position in spot-market synthetic grades where price flexibility outweighs batch consistency.
- B2B:Direct multi-year offtake agreements between fragrance houses and Malaysian or Indonesian extraction facilities now dominate natural citronellol procurement for premium applications.
B2B contracting commands the established base. Online retail channels are expanding most quickly for standard-grade spot purchases.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Extraction facilities in Indonesia and Malaysia supply the majority of natural citronellol feedstock, while German and French fragrance houses dominate premium-grade consumption. This geographic split between raw material origin and value-added processing shapes procurement strategies across the value chain.
Germany
Perfumery clusters in Hamburg and Munich drive demand for certified natural grades with full REACH documentation. ECHA registration requirements filter supplier qualification toward integrated compliance providers. BASF SE anchors synthetic production through its Ludwigshafen aroma chemicals platform.
France
Grasse-based fragrance houses concentrate procurement of high-purity isolates for fine perfumery applications. ANSM cosmetic safety standards intersect with EU Green Deal biodegradability mandates. Premium skincare brands in Paris demand reduced-sensitizing grades with supply chain traceability.
United States
Household product manufacturers in New Jersey and California purchase synthetic citronellol in bulk volumes for surface cleaners and air care formulations. EPA 25(b) exempt pathways accelerate citronellol-based insect repellent registrations. FDA topical repellent standards govern tolerability thresholds for DEET alternatives.
India
Privi Speciality Chemicals Limited anchors natural extraction through captive geraniol processing in Maharashtra. BIS quality marks create premium positioning for exports to regulated Asian markets. Mumbai-based flavor houses serve domestic food-grade specifications under FSSAI oversight.
China
Zhejiang province hosts catalytic hydrogenation facilities producing synthetic grades for export to Brazil and Southeast Asia. GB standards for flavoring agents impose purity thresholds distinct from fragrance applications. Guangzhou-based compounders supply household product manufacturers with cost-optimized blends.
Citronellol Market Competitive Environment
Technology leadership and cost leadership are held by different player archetypes, creating a tiered competitive structure. Integrated chemical majors dominate synthetic production through captive feedstock access, while specialty extractors anchor natural supply chains. Three archetypes define positioning: integrated aroma chemical platforms, regional extraction specialists, and biotechnology innovators. Capacity expansion and strategic partnerships represent the dominant competitive moves, with direct offtake agreements displacing traditional distributor relationships.
Within the integrated platform tier, BASF SE and Zhejiang NHU Co. Ltd exemplify scale-driven synthetic production, while Privi Speciality Chemicals Limited occupies a distinctive position in natural extraction through backward integration into geraniol processing. International Flavours & Fragrances Inc. sits within the biotechnology frontier, representing fermentation-based routes that reduce agricultural feedstock dependence.
| Leading Market Players |
|---|
| BASF SE |
| Privi Speciality Chemicals Limited |
| International Flavours & Fragrances Inc. |
| Takasago International Corporation |
| Zhejiang NHU Co. Ltd |
| Capot Chemical Co., Ltd |
| Crescent Fragrances Private Limited |
| Guangzhou Baihua Flavors and Fragrances Co., Ltd. |
| Emerald Performance Materials |
| Others |
Value Chain & Pricing Dynamics
Synthetic citronellol displacement of natural grades in household product formulations simultaneously shifts production geography toward Chinese hydrogenation facilities and compresses pricing economics for Southeast Asian extraction operations. This substitution dynamic concentrates margin capture with catalytic process licensors while fragmenting procurement leverage among fragrance houses.
Pricing Analysis
REACH registration dictates the pricing tier structure across European citronellol procurement, separating certified-grade producers with integrated compliance documentation from uncertified traders. Three-tier pricing structure across premium, standard, and economy levels reflects certification depth, with pharma-grade isolates commanding the highest tier and bulk synthetic grades occupying the lowest. Cost compression in standard grades intensifies because Chinese hydrogenation capacity expansion outpaces demand growth. Household product manufacturers exhibit the greatest price sensitivity, while French fine fragrance houses absorb premium tier premiums for traceability documentation.
Supply Chain Analysis
Container availability fluctuations on the Singapore-Rotterdam trade lane expose inbound logistics cost volatility for European fragrance houses sourcing from Malaysian and Indonesian extraction facilities. Geographic supply concentration centers on Indonesia, Malaysia, and China, with natural extraction anchored in Southeast Asian plantations and synthetic production clustered in Zhejiang province. Raw material dependencies rest on citronella oil, geraniol feedstock, and specialized catalysts for hydrogenation. Single-source vulnerability runs through Southeast Asian plantation concentration exposed to climate disruption. Distribution runs through direct multi-year offtake agreements displacing traditional distributor intermediaries in premium segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Regulatory entrenchment creates a durable defensive moat in the citronellol market, as REACH documentation burdens and ECHA registration costs erect structural barriers that filter out marginal competitors and consolidate procurement relationships with integrated compliance providers.
For Market Incumbents: Shield market position by deepening backward integration into captive geraniol processing and securing multi-year offtake agreements with Malaysian extraction facilities. Biotechnology fermentation platforms represent an emerging entrant threat that demands preemptive R&D investment to maintain specification leadership. Certification investment in reduced-allergen isolates provides a channel control lever against reformulation mandates from Paris-based premium skincare brands. For New Entrants and Emerging Players: Lead with EPA 25(b) exempt insect repellent registrations as the most penetrable application segment, where biocide reclassification tailwinds lower regulatory barriers relative to fragrance-grade REACH compliance. India's BIS quality mark penetration offers a geographic white-space opportunity with domestic geraniol processing infrastructure. A direct-to-formulator go-to-market angle bypasses entrenched distributor relationships in European procurement channels. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors integrated aroma chemical platforms with captive feedstock access and compliance documentation capabilities. Long-term viability over the next decade hinges on biotechnology production scale-up and regulatory divergence between fragrance and biocide classifications. The signal to watch as an inflection indicator is ECHA guidance expansion on fragrance allergen concentration limits forcing accelerated reformulation cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Geraniol Processing | Captive feedstock access insulates margin pressure from Southeast Asian plantation volatility. |
| Biotechnology Fermentation Scale-Up | Microbial platforms bypass agricultural constraints and reduce batch-to-batch odor variation. |
| REACH Certification Investment | Integrated compliance documentation filters out small traders and secures European fragrance house procurement. |
| EPA 25(b) Exempt Product Registration | Streamlined pathways accelerate citronellol-based DEET alternative market entry. |
| Direct Offtake Agreement Structuring | Multi-year contracts with Malaysian processors displace distributor intermediaries in premium segments. |
Study Parameters
Cross-validation between primary interviews with fragrance house procurement directors and secondary customs trade data anchors the qualitative findings on supply chain restructuring. Plant managers at hydrogenation facilities, technical R&D directors at aroma chemical platforms, and distribution channel partners in Hamburg and Grasse provided operational perspective. FDA filings on topical repellent registrations, ECHA REACH submission databases, SEC 10-K disclosures from integrated chemical majors, and ACC sector reports furnished secondary validation. Bottom-up volume modeling triangulated against top-down value estimates derived from trade flow analysis.
Sensitivity analysis tested forecast robustness across feedstock price volatility scenarios and regulatory implementation timelines. The analytical framework segments by product grade tier, end-use application, customer type, and regional production hub across the analysis window. CAGRs were derived from trend extrapolation adjusted for substitution elasticity between natural and synthetic grades. Catalytic hydrogenation yield improvements and ECHA allergen limit enforcement timelines served as key forecast inputs.
The analysis sits within stated boundaries; outcomes outside sustained EU Green Deal implementation or abrupt REACH fee restructuring would require recalibration. Forecasts reflect documented assumptions on biotechnology scale-up timelines and plantation yield stability. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Flavor and Fragrance Chemicals
Carnosic Acid Market
Flavor and Fragrance Chemicals
Guaiacwood Oil Market
Flavor and Fragrance Chemicals
Fragrance Wax Melts Market
Flavor and Fragrance Chemicals
Europe Deodorants Market
Flavor and Fragrance Chemicals
Tannic Acid Market
Flavor and Fragrance Chemicals
Limonene Market
Flavor and Fragrance Chemicals
Hydroxycitronellal Market
Flavor and Fragrance Chemicals
Coumarin Market
Flavor and Fragrance Chemicals
Aromatics Market
Flavor and Fragrance Chemicals
Ethylidene Norbornene Market
Flavor and Fragrance Chemicals
Guaiacwood Essential Oil Market
Flavor and Fragrance Chemicals
Anisic Aldehyde Market
Flavor and Fragrance Chemicals
Alpha Ionone Market
Flavor and Fragrance Chemicals
Scent Eliminators Market
Flavor and Fragrance Chemicals
Spearmint Oil Market
Flavor and Fragrance Chemicals
Massoia Bark Essential Oil Market