
 Hydroxycitronellal Market | 2026-2036
Hydroxycitronellal Market Size, Share, and Industry Trends Forecast 2026-2036
Hydroxycitronellal Market Outlook
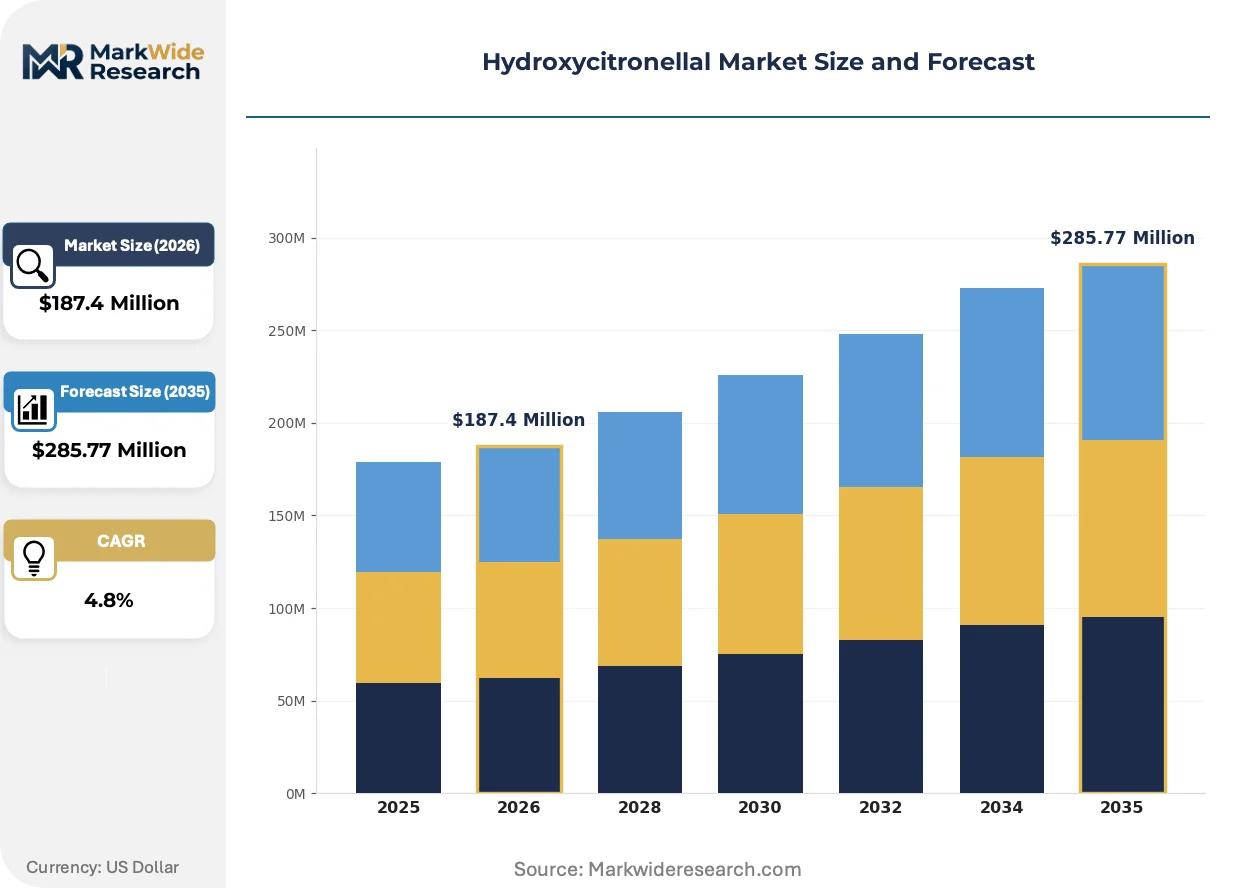
Multi-source procurement among European fragrance houses is restructuring supply security for Hydroxycitronellal as geopolitical volatility disrupts citronella oil flows from Southeast Asia. Symrise AG leverages captive botanical extraction in Germany to sustain consistent feedstock access. BASF competes through petrochemical synthesis routes that reduce agricultural dependency. Privi Specialty Chemicals Limited anchors South Asian supply with integrated essential oil processing in India.
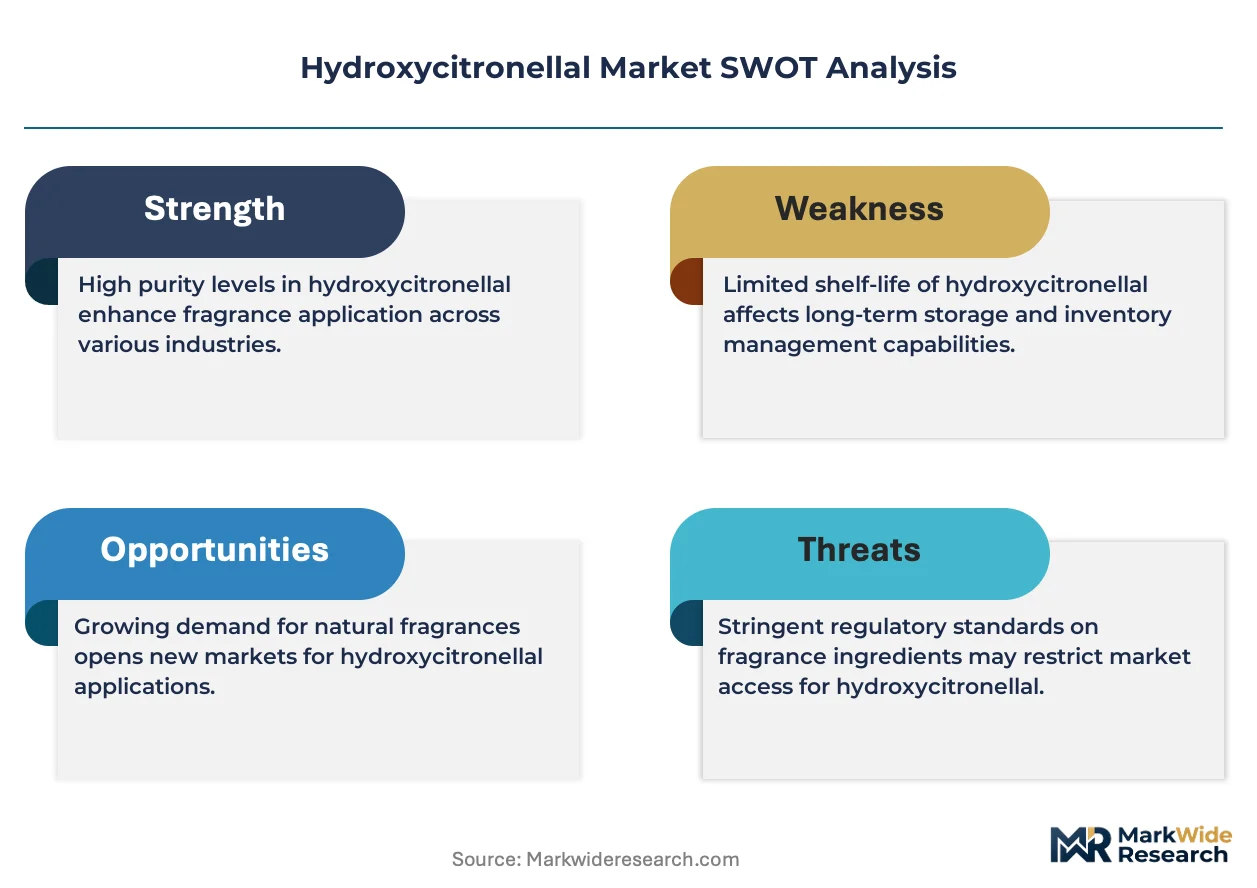
Hydroxycitronellal is a synthetic fragrance aldehyde derived from citronellal through hydration, typically presenting as a colorless to pale yellow liquid with a lily-of-the-valley odor profile and molecular formula C10H20O2; manufacturers deploy it primarily as a floral fixative in fine perfumes and functional fragrances where substantivity and bloom characteristics matter. Fragrances remains the dominant application segment, with luxury perfume houses capturing the deepest margin pools through proprietary compound formulations. Personal Care represents the fastest-growing application as clean-label positioning drives reformulation away from restricted allergens toward IFRA-compliant alternatives. Liquid form dominates industrial handling, though powder variants are gaining traction in solid cosmetic formats where alcohol-free claims support brand differentiation.
EU REACH registration requirements and IFRA Code of Practice standards constrain which synthesis pathways and impurity profiles gain market access across European formulation facilities. FDA fragrance ingredient labeling rules under the Fair Packaging and Labeling Act shape disclosure obligations for products entering US retail channels. China's GB standards for cosmetic raw materials, administered by NMPA, dictate import testing protocols that foreign suppliers must navigate. Stakeholders must monitor regulatory divergence between fragrance self-regulation and emerging government-mandated disclosure regimes when allocating R&D budgets across regional compliance frameworks.
Market Dynamics
EU REACH registration deadlines for fragrance aldehydes are compressing formulation timelines while IFRA 51st Amendment restrictions on synthetic allergens redirect R&D budgets toward compliant Hydroxycitronellal derivatives.
Growth Catalysts
- REACH compliance deadlines:European fragrance houses accelerate reformulation programs to meet ECHA registration requirements for existing aldehyde portfolios, expanding captive demand for pre-registered Hydroxycitronellal grades.
- Personal care clean-label mandates:Premium skincare brands in France and Germany eliminate restricted allergens from leave-on products, creating substitution pull for IFRA-compliant floral fixatives.
- Biotechnology process maturation:Enzymatic hydration pathways for citronellal conversion achieve industrial scale, reducing energy intensity versus traditional acid-catalyzed routes.
Market Restraints
- Citronella oil supply volatility:Indonesian and Sri Lankan harvest disruptions from erratic monsoon patterns transmit price shocks through natural-derived feedstock channels.
- Petrochemical route carbon intensity:BASF's synthetic pathway faces Scope 3 emissions scrutiny under EU Green Deal reporting frameworks, constraining capacity expansion approvals.
- Alternative floral aldehydes:Lyral (Hydroxyisohexyl 3-cyclohexene carboxaldehyde) maintains cost advantages in mass-market fabric care despite its own regulatory restrictions.
Strategic Opportunities
- India personal care penetration:Domestic fragrance compounders serving Mumbai and Bangalore beauty brands represent underdeveloped demand for premium floral accords.
- Solid cosmetic formats:Powder-grade Hydroxycitronellal enables alcohol-free perfume stick formulations targeting Japanese and South Korean clean beauty segments.
- Biomass-derived feedstocks:EU Green Deal sustainable carbon certification creates premium pricing tiers for bio-attributed citronellal sourced from certified plantations.
Industry Challenges
- Fragrance chemist specialization gaps:European compounders report shortages of formulators trained in aldehyde stability management under accelerated oxidation testing protocols.
- REACH data sharing disputes:Lead registrant consortia for Hydroxycitronellal impose cost allocation conflicts that delay dossier submissions and market access timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hydroxycitronellal Market |
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $285.77 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Application: Fragrances, Personal Care, Household Products, Cosmetics Form: Liquid, Powder, Gel, Aerosol End User: Manufacturers, Retailers, Distributors, Wholesalers Packaging Type: Drums, Bottles, Pouches, Bulk |
| Companies Covered | Takasago, Symrise AG, BASF, Privi Specialty Chemicals Limited, International Flavors & Fragrances Inc., Zhejiang NHU Co., Givaudan, Mane SA, Vigon, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hydroxycitronellal Market Strategic Shifts
Continuous processing technology and regulatory disclosure mandates are compressing traditional batch manufacturing and opacity-based competitive moats across fragrance aldehyde supply chains.
Flow chemistry reactor systems for citronellal hydration are rewriting capital efficiency benchmarks in Hydroxycitronellal production. German specialty chemical operators deploy microreactor arrays that cut residence times from hours to minutes. This technology is rewriting the geographic logic of production scale, enabling distributed manufacturing near formulation centers rather than centralized tropical feedstock processing.
EU F-Gas Regulation phase-down schedules indirectly pressure solvent choices in fragrance extraction and purification stages. Manufacturers face reformulation of cleaning and crystallization protocols to eliminate restricted fluorinated solvents. Fine perfume houses in Grasse and Geneva accelerate investment in supercritical CO2 infrastructure to maintain extraction capabilities without regulatory exposure.
Direct sourcing contracts between fragrance houses and plantation cooperatives are displacing spot-market citronella oil procurement. LVMH and Kering-owned perfume brands negotiate multi-year offtake agreements with Indonesian suppliers, bypassing traditional essential oil traders. This pattern concentrates most visibly in French luxury houses seeking supply chain transparency for ESG disclosure requirements.
Hydroxycitronellal Market Segmentation
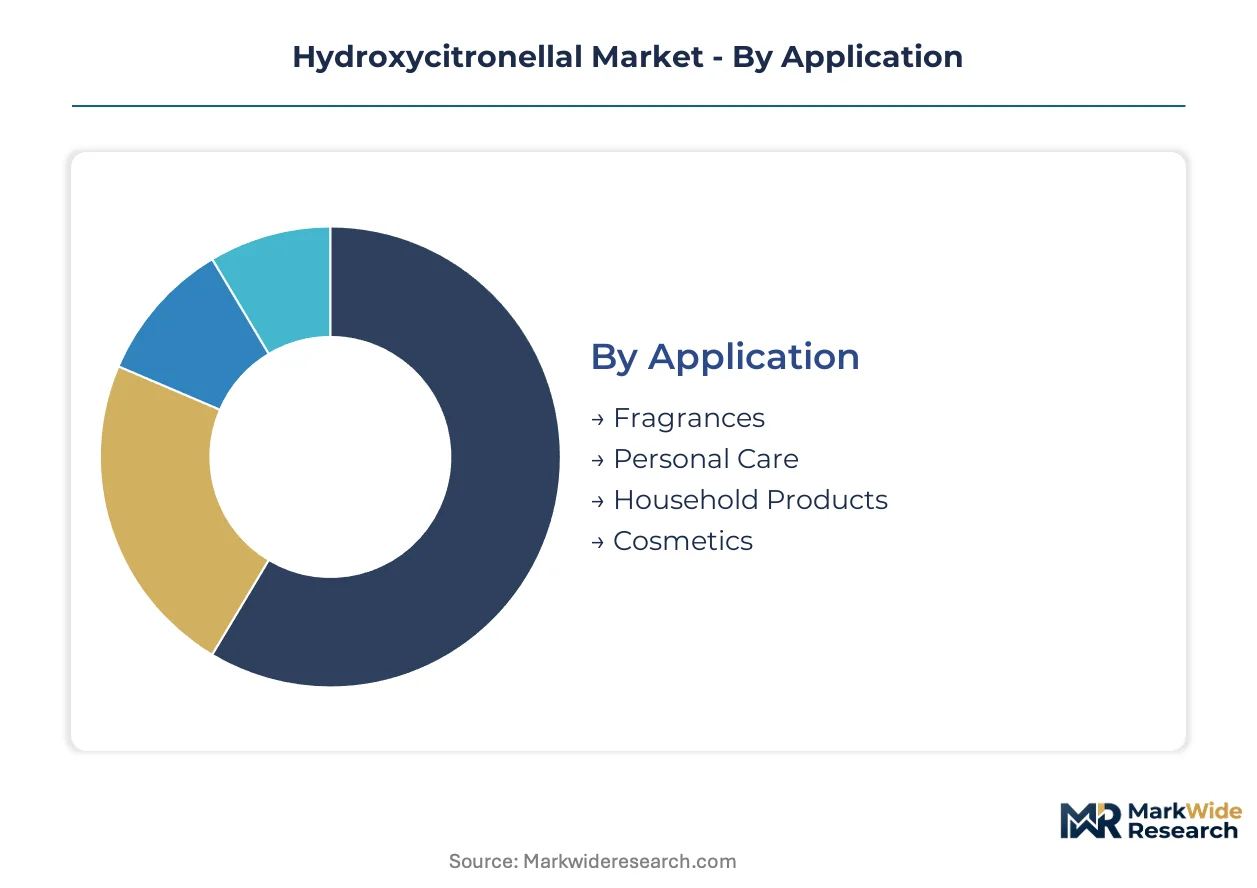
Segmentation in Hydroxycitronellal procurement reflects divergent regulatory burdens across fragrance compounding, personal care formulation, and industrial channels. Buyers select grades based on IFRA compliance tiers, REACH registration status, and end-product disclosure obligations.
Application:
Fragrances carries the heaviest certification load, requiring full IFRA Code of Practice adherence and EU REACH registration for aldehyde content above threshold limits. Personal Care demands additional safety assessments under FDA fragrance labeling rules and China's NMPA cosmetic raw material standards.
- Fragrances:Fine perfume houses in France and Switzerland specify high-purity grades with documented impurity profiles for proprietary compound formulations. Luxury fragrance manufacturers capture premium pricing through captive supply agreements with German extraction specialists.
- Personal Care:Premium skincare brands in Germany and South Korea drive reformulation toward IFRA-compliant floral fixatives as clean-label mandates eliminate restricted allergens from leave-on products. This segment expands most quickly as regulatory pressure accelerates substitution cycles.
- Household Products:Functional fragrance applications in fabric care and air fresheners prioritize cost-optimized grades with standardized odor profiles.
- Cosmetics:Color cosmetic and hair care formulators seek low-irritant variants meeting EU Cosmetics Regulation safety thresholds.
Fragrances sits at the top of the volume ranking, with Personal Care climbing the fastest.
Form:
Physical state determines handling infrastructure requirements and directly shapes logistics costs across formulation facilities. Liquid form dominates capital investment in storage and metering systems, while solid variants enable novel product architectures.
- Liquid:Standard industrial handling format compatible with existing fragrance compounding equipment in Grasse and Geneva production facilities. Bulk liquid procurement minimizes packaging waste for high-volume fragrance houses.
- Powder:Enables alcohol-free perfume stick formulations targeting Japanese and South Korean clean beauty segments where solid cosmetic formats gain shelf space. Encapsulation technologies protect aldehyde stability in powder matrices.
- Gel:Specialized viscosity grades for suspension-type personal care products requiring controlled release characteristics.
- Aerosol:Propellant-compatible formulations for spray fragrance and household product applications with specific volatility requirements.
Liquid maintains the dominant share by tonnage, though Powder gains share fastest in premium positioning channels.
End User:
Procurement sophistication varies sharply between integrated manufacturers and intermediaries, with direct buyers commanding stricter specification control and audit rights over supply chains.
- Manufacturers:Integrated fragrance compounders and personal care formulators in France, Germany, and India negotiate direct contracts with extraction specialists or petrochemical producers. These buyers demand full traceability documentation for ESG disclosure requirements.
- Retailers:Private-label beauty brands and mass-market distributors source through fragrance houses with established IFRA compliance programs. Retail procurement emphasizes standardized grades with predictable pricing.
- Distributors:Regional chemical distributors stock technical grades for mid-tier formulators lacking direct supplier relationships.
- Wholesalers:Spot-market traders handle surplus volumes and non-standard specifications for price-sensitive applications.
Manufacturers command the largest procurement volumes, with Retailers expanding their direct sourcing capabilities most aggressively.
Packaging Type:
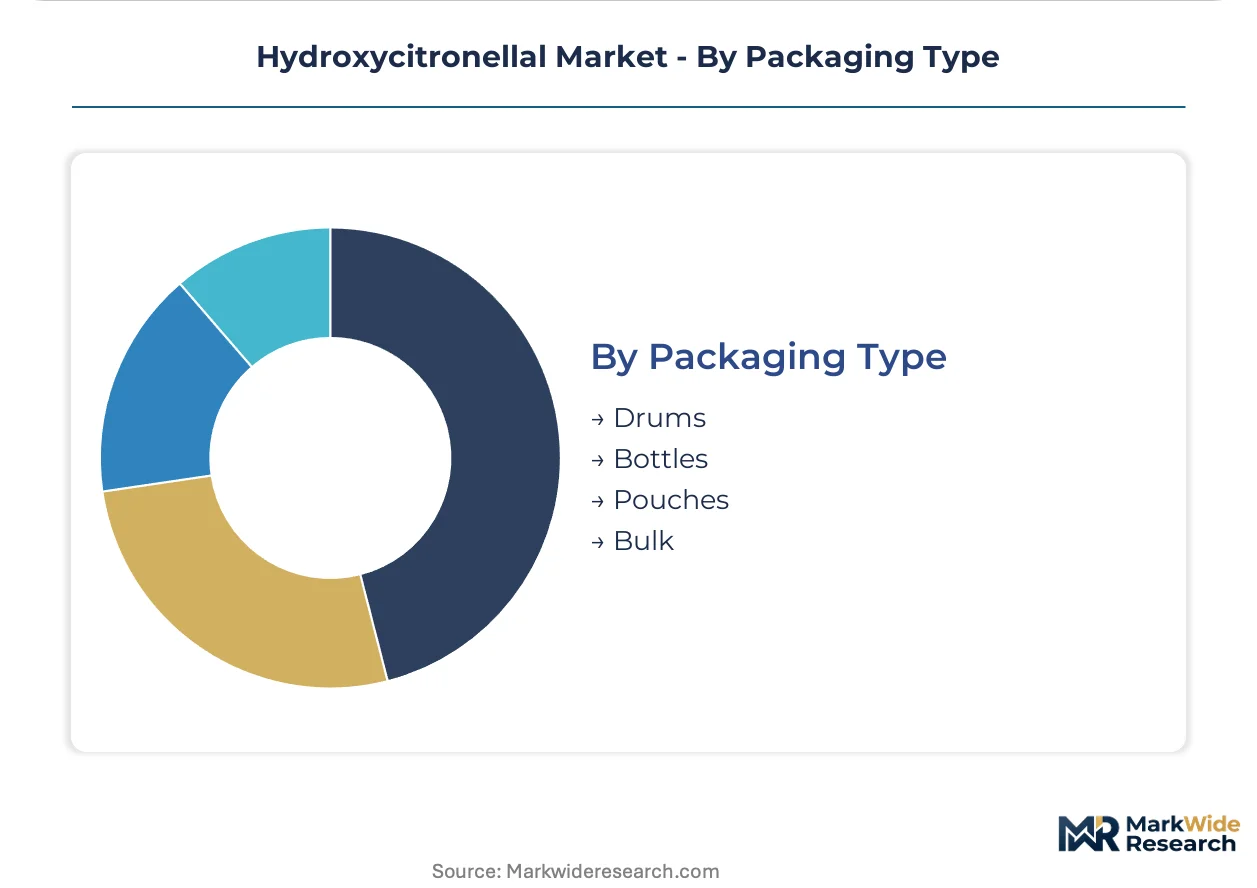
Packaging selection reflects order scale, handling automation, and contamination risk tolerance across fragrance compounding and personal care manufacturing environments.
- Drums:Standard 200-liter steel or HDPE containers for medium-batch fragrance compounding operations in European formulation facilities. Drum specifications must meet UN transport regulations for flammable liquid classification.
- Bottles:Smaller-format packaging for sample development, pilot production, and artisan perfumery operations requiring frequent material changes.
- Pouches:Flexible packaging for powder-grade Hydroxycitronellal reducing storage footprint in solid cosmetic manufacturing lines.
- Bulk:Tanker or ISO-tank deliveries for high-volume fragrance houses with dedicated storage infrastructure and automated transfer systems.
Bulk deliveries serve the largest accounts by volume, with Pouches showing the steepest expansion trajectory in solid format applications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are redirecting Hydroxycitronellal production toward jurisdictions with lower compliance burdens, as EU REACH registration costs and IFRA disclosure requirements widen cost-of-compliance gaps between European and Asian manufacturing bases.
Germany
Symrise AG maintains captive botanical extraction facilities that supply fragrance houses in Holzminden and Hamburg with consistent citronellal feedstocks. ECHA registration deadlines for existing aldehyde portfolios compress formulation timelines for domestic compounders. The Rhine-Main industrial corridor hosts BASF's petrochemical synthesis operations, which reduce agricultural dependency through alternative production routes.
France
Fine perfume houses in Grasse drive premium-grade demand for proprietary floral compound formulations. ANSM cosmetic safety assessments align with EU Cosmetics Regulation thresholds for aldehyde content in leave-on products. The Provence-Alpes-Côte d'Azur cluster concentrates formulation expertise, with LVMH and Kering-owned brands negotiating direct sourcing contracts for supply chain transparency.
India
Privi Specialty Chemicals Limited anchors South Asian supply through integrated essential oil processing in Maharashtra. BIS standards for fragrance raw materials create import testing protocols that domestic producers navigate more efficiently than foreign competitors. Mumbai and Bangalore beauty brands represent underdeveloped demand channels for premium floral accords in personal care applications.
China
Zhejiang NHU Co. exemplifies scale-oriented producers serving both domestic fragrance compounders and export markets. NMPA cosmetic raw material standards administered under GB protocols dictate documentation requirements for Hydroxycitronellal shipments entering Chinese formulation facilities. The Yangtze River Delta concentrates personal care manufacturing capacity that absorbs increasing volumes of IFRA-compliant floral fixatives.
United States
FDA fragrance ingredient labeling rules under the Fair Packaging and Labeling Act shape disclosure obligations for products entering retail channels. International Flavors & Fragrances Inc. occupies a position among domestic compounders navigating state-level cosmetic safety legislation. The New Jersey-Pennsylvania chemical corridor maintains fragrance compounding infrastructure serving mass-market and prestige brand portfolios.
Hydroxycitronellal Market Competitive Environment
Established producers occupy the standard tier; emerging entrants pursue biotechnology-derived alternatives and regional market penetration. The supplier base consolidates around three maturity tiers: integrated multinational extractors with captive feedstock access, mid-scale regional compounders leveraging geographic proximity to formulation centers, and specialty chemical operators deploying flow chemistry for distributed manufacturing. Competitive positioning hardens through backward integration into citronella plantation networks, strategic partnerships with luxury fragrance houses for co-development agreements, and capacity expansion in low-compliance-cost jurisdictions.
Among European-based operators, Symrise AG and BASF exemplify divergent feedstock strategies—botanical extraction versus petrochemical synthesis—that define competitive archetypes in aldehyde supply. Takasago anchors Japanese production expertise in stereoselective catalysis for fragrance applications. Privi Specialty Chemicals Limited represents integrated South Asian supply with plantation-to-compounder traceability documentation.
| Leading Market Players |
|---|
| Takasago |
| Symrise AG |
| BASF |
| Privi Specialty Chemicals Limited |
| International Flavors & Fragrances Inc. |
| Zhejiang NHU Co. |
| Givaudan |
| Mane SA |
| Vigon |
| Others |
Value Chain & Pricing Dynamics
Fragrance chemist concentration in Grasse and Geneva compounds labor-cost premiums that widen spreads between REACH-registered premium grades and standard technical tiers. This workforce scarcity forces European compounders to absorb higher formulation costs or offshore blending operations to lower-cost jurisdictions.
Pricing Analysis
Distributor markups on spot-market citronella oil shipments compress margins for mid-tier fragrance houses lacking direct plantation contracts. Three-tier pricing structure across premium, standard, and economy levels separates IFRA-certified grades from industrial technical variants and mass-market fabric care inputs. Price differentiation hinges on REACH registration completeness and documented impurity profiles. Cost compression in standard tiers is intensifying because Indonesian harvest volatility transmits through spot channels. Mass-market household product manufacturers exhibit highest price sensitivity; luxury perfume houses capture lowest sensitivity through captive supply agreements.
Supply Chain Analysis
Direct-to-compounder channels handle hyperscale demand from integrated fragrance houses in France and Germany, bypassing traditional essential oil traders. Supply concentrates in Indonesia, India, and Germany as primary feedstock and processing nodes. Raw material flows draw from citronella oil, petrochemical intermediates, and enzymatic catalyst stocks. Single-source vulnerability in Indonesian plantation networks exposes buyers to monsoon-driven harvest disruptions. Distribution runs through long-term offtake agreements for premium grades and spot markets for technical variants.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Hydroxycitronellal demand is shifting toward premium REACH-registered grades as clean-label mandates eliminate restricted allergens from personal care formulations. This quality migration favors suppliers with documented traceability and ECHA-compliant dossiers.
For Market Incumbents: Acquire plantation processing assets in Indonesian or Sri Lankan source regions to secure captive citronella oil flows against harvest volatility. Consolidate formulation expertise in Grasse and Geneva through targeted hiring of aldehyde stability specialists to defend against biotechnology-derived substitute entrants. Backward integration into certified biomass feedstocks creates defensible margin pools under EU Green Deal carbon accounting rules. For New Entrants and Emerging Players: EU REACH registration deadlines in 2026-2027 open a window for pre-registered Hydroxycitronellal grades to capture reformulation demand from European fragrance houses accelerating compliance programs. Target underpenetrated personal care compounders in Mumbai and Bangalore with IFRA-compliant floral fixatives for premium skincare brands. Pursue co-development agreements with Japanese solid cosmetic manufacturers seeking powder-grade variants for alcohol-free perfume sticks. For Investors and Strategic Acquirers: Valuations sit cheapest among mid-scale regional compounders with geographic proximity to formulation centers but lacking REACH registration completeness. Long-term viability centers on feedstock security and regulatory compliance capabilities rather than scale alone. Watch for biotechnology process maturation announcements as inflection signals that could disrupt traditional acid-catalyzed production economics.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Plantation Networks | Symrise AG's captive botanical extraction in Germany insulates against Indonesian supply disruptions. |
| Flow Chemistry Manufacturing Scale-Up | Microreactor arrays cut residence times and enable distributed production near European formulation hubs. |
| REACH Registration Consortium Participation | Lead registrant status in ECHA dossiers secures market access timelines for premium grade supply. |
| Biotechnology Process Licensing | Enzymatic hydration pathways reduce energy intensity and attract EU Green Deal sustainable carbon certification. |
| Direct Sourcing Contracts with Luxury Houses | LVMH and Kering-owned brands negotiate multi-year offtake agreements for ESG disclosure compliance. |
Study Parameters
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with fragrance compounders, essential oil processors, regulatory affairs specialists at ECHA, and procurement leads at personal care manufacturers with secondary validation. Secondary sources included customs and trade flow databases, IFRA compliance disclosure filings, SEC 10-K extracts from listed fragrance houses, and REACH registration dossiers published through ECHA's dissemination portal. Bottom-up demand modeling from end-use applications was cross-checked against top-down supply capacity assessments across extraction and petrochemical synthesis routes.
Segment-weighting applied differential growth assumptions across fragrance, personal care, household products, and cosmetics applications, with form factors and end-user procurement sophistication as secondary stratification dimensions. CAGRs were derived from slope analysis of historical trajectory and elasticity-adjusted demand projections across the modeling period. Forecast inputs incorporated REACH registration timeline impacts, biotechnology process adoption curves, and clean-label reformulation velocity in premium skincare segments.
Revisions become necessary when REACH data sharing disputes delay dossier submissions, biotechnology scale-up exceeds anticipated timelines, or Indonesian harvest disruptions persist across multiple monsoon cycles. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Flavor and Fragrance Chemicals
Natural Vanillin Market
Flavor and Fragrance Chemicals
Tannic Acid Market
Flavor and Fragrance Chemicals
Asia Pacific Essential Oils Market
Flavor and Fragrance Chemicals
Carnosic Acid Market
Flavor and Fragrance Chemicals
Flavors for Pharmaceutical and Healthcare Applications Market
Flavor and Fragrance Chemicals
Synthetic Cinnamaldehyde Market
Flavor and Fragrance Chemicals
Smoke Ingredients Market
Flavor and Fragrance Chemicals
Perillaldehyde Market
Flavor and Fragrance Chemicals
Citral Market
Flavor and Fragrance Chemicals
Europe Essential Oils Market
Flavor and Fragrance Chemicals
North America Aroma Chemicals Market
Flavor and Fragrance Chemicals
Guaiacwood Oil Market
Flavor and Fragrance Chemicals
Cinnamic Aldehyde Market
Flavor and Fragrance Chemicals
Guaiacwood Essential Oil Market
Flavor and Fragrance Chemicals
Neryl Acetate Market
Flavor and Fragrance Chemicals
Fragrance Concentrates Market