
 Fragrance Ingredients Market | 2026-2036
Fragrance Ingredients Market Size, Share, and Industry Trends Forecast 2026-2036
Fragrance Ingredients Market Analysis
Asset-light contract manufacturing and third-party tolling arrangements is rewriting competitive entry in fragrance ingredients, allowing niche botanical suppliers to challenge integrated incumbents without capital-intensive distillation infrastructure. Givaudan SA leverages captive sourcing from Grasse-region growers to secure rare raw material streams. Symrise AG anchors its position through backward integration into vanilla cultivation in Madagascar and sustainable patchouli programs in Indonesia. International Flavors & Fragrances Inc. competes via biotechnology platforms that ferment fragrance molecules without agricultural land use.
Fragrance ingredients comprise volatile aromatic compounds—natural essential oils extracted through steam distillation or solvent extraction, and aroma chemicals synthesized via Friedel-Crafts alkylation, Grignard reactions, or biotechnological fermentation—formulated to deliver olfactory performance in consumer products. Essential oils command premium positioning in fine fragrance and clean-label personal care, while synthetic fragrances dominate volume in mass-market household products where cost stability matters. Aroma chemicals represent the fastest-expanding product category as perfumers seek reproducible, allergen-controlled alternatives to naturals with harvest volatility. The cosmetics application segment captures the deepest margin pools, particularly in skin-safe and hypoallergenic formulations where regulatory scrutiny intensifies.
REACH in Europe mandates full ingredient disclosure and restricts specific sensitizers, while the FDA in the United States maintains fragrance allergen labeling guidance under the Fair Packaging and Labeling Act. China's SAMR enforces GB standards for cosmetic fragrance safety that diverge from Western allergen lists, fragmenting compliance architectures. India's BIS certification for essential oil purity and the EU Green Deal's biobased content thresholds are reshaping supplier qualification criteria. Stakeholders must monitor divergence between regional fragrance allergen regulations and invest in modular formulation platforms that adapt to jurisdiction-specific restricted substance lists without full product redesign.
Market Dynamics
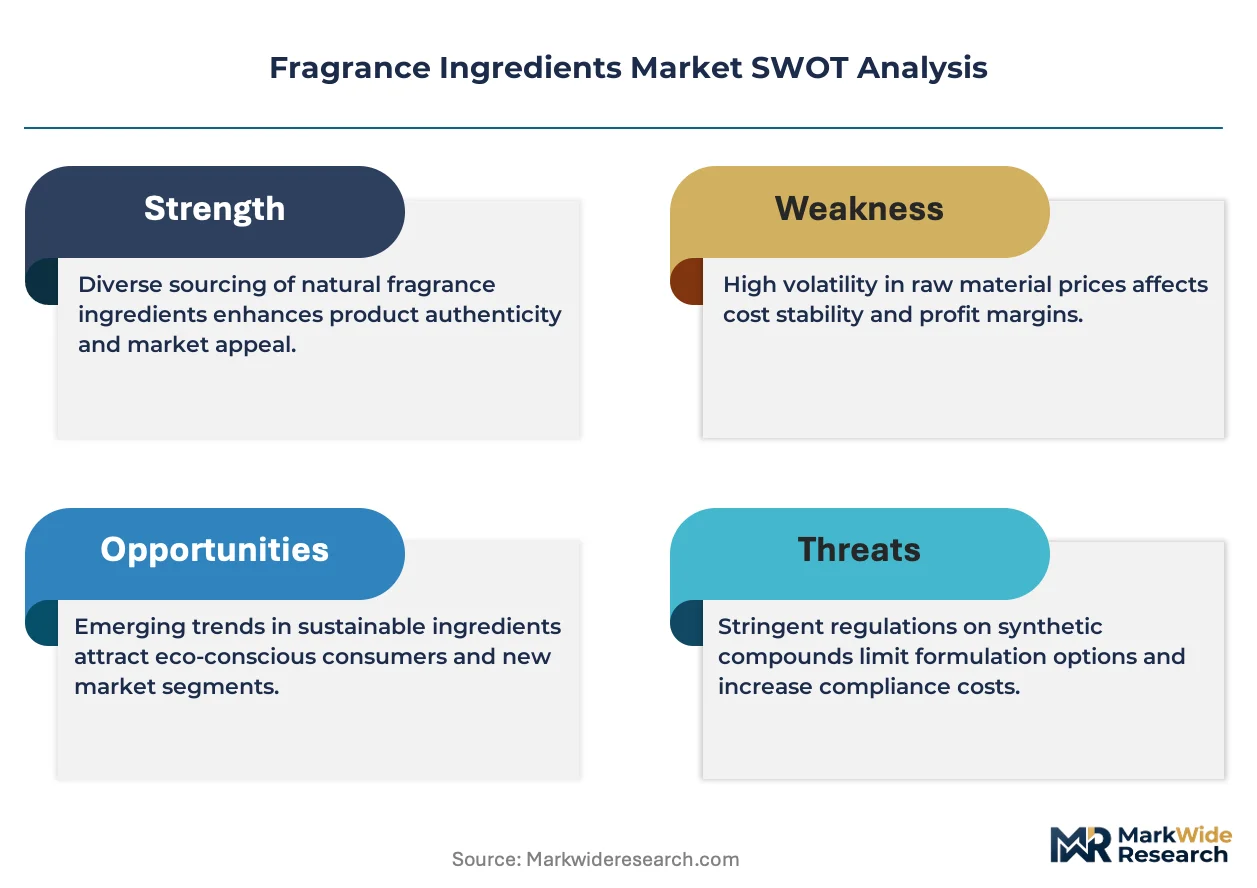
REACH compliance and the EU Green Deal are compressing disclosure timelines for synthetic aroma chemicals while biotech fermentation platforms erode the cost advantage of traditional agricultural extraction, forcing suppliers to requalify entire formulation portfolios.
Growth Catalysts
- Clean-label personal care:Consumer preference for transparent ingredient lists drives reformulation toward natural essential oils in skin-safe cosmetics.
- China's domestic brand expansion:Local perfume houses scaling manufacturing are localizing supply chains and concentrating procurement within domestic borders.
- Sustainable sourcing mandates:The EU Green Deal's biobased content thresholds incentivize backward integration into certified cultivation programs.
Market Restraints
- Harvest volatility:Weather-driven supply fluctuations in Indonesian patchouli and Madagascan vanilla concentrate input cost risk.
- Allergen restriction divergence:China's SAMR enforces GB standards that fragment compliance architectures against Western allergen lists.
- Synthetic substitution ceiling:Fine fragrance houses maintain rigid specifications for rare natural molecules that biotechnology cannot yet replicate.
Strategic Opportunities
- Modular formulation platforms:Jurisdiction-adaptive production systems enable single-SKU compliance across REACH, FDA, and SAMR regimes.
- Biotech molecule licensing:Fermentation-derived aroma compounds bypass agricultural land use constraints and secure supply against climate volatility.
- Third-party tolling networks:Asset-light contract manufacturing allows botanical specialists to challenge integrated incumbents without distillation infrastructure.
Industry Challenges
- Cross-functional compliance expertise:Talent scarcity spans toxicology, regulatory affairs, and bioprocess engineering simultaneously.
- Dual certification timelines:BIS essential oil purity standards and REACH dossier preparation extend product launch cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fragrance Ingredients Market |
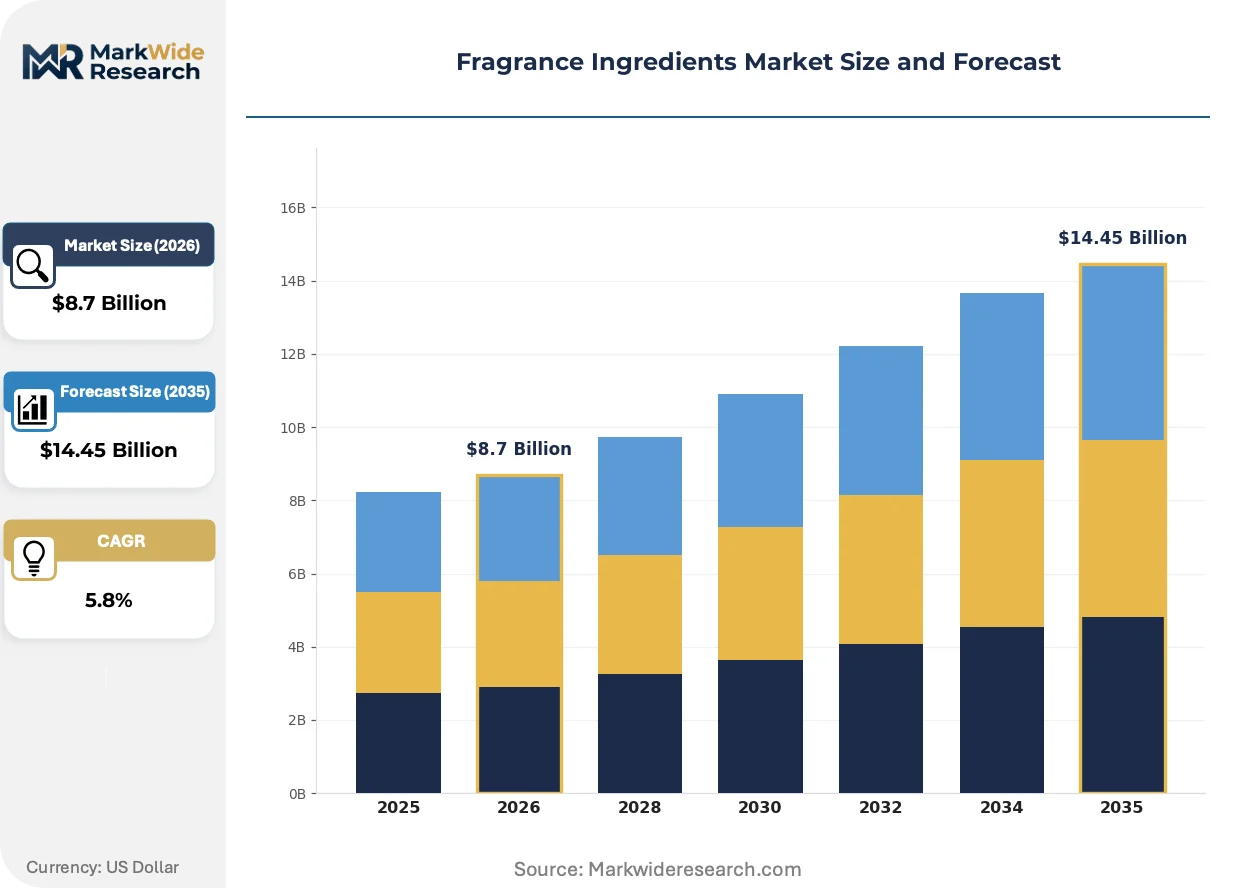
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $14.45 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Essential Oils, Aroma Chemicals, Abs-solutes, Synthetic Fragrances Application: Cosmetics, Household Products, Personal Care, Air Care Form: Solid, Liquid, Gel, Powder End User: Manufacturers, Retailers, Wholesalers, Distributors |
| Companies Covered | Givaudan SA, Symrise AG, International Flavors & Fragrances Inc., BASF SE, Firmenich SA, Mane SA, Takasago International Corporation, Robertet Group, Sensient Technologies Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fragrance Ingredients Market Emerging Trajectories
Digital molecular design and precision fermentation are compressing the innovation cycle for fragrance ingredients, while regulatory fragmentation forces simultaneous investment in multiple compliance pathways.
Biotechnology platforms are virtualizing fragrance molecule production. Precision fermentation converts sugar feedstocks into aroma chemicals without agricultural cultivation. Fine fragrance houses and mass-market personal care brands are adopting these bio-identical molecules to secure supply continuity. This virtualization is collapsing the traditional link between harvest geography and raw material availability.
REACH authorization requirements are tightening disclosure obligations for synthetic sensitizers. ECHA's candidate list expansion forces reformulation of legacy fragrance compounds. Cosmetics applications face the steepest compliance burden, with perfumers accelerating substitution programs for restricted substances.
Direct sourcing contracts between fragrance houses and cultivation cooperatives are displacing commodity spot markets. Grasse-region growers and Indonesian patchouli farmers now negotiate multi-year supply agreements with fixed pricing. This channel consolidation is most advanced in France and Madagascar, where captive sourcing secures rare raw material streams against intermediation.
Fragrance Ingredients Market Segmentation
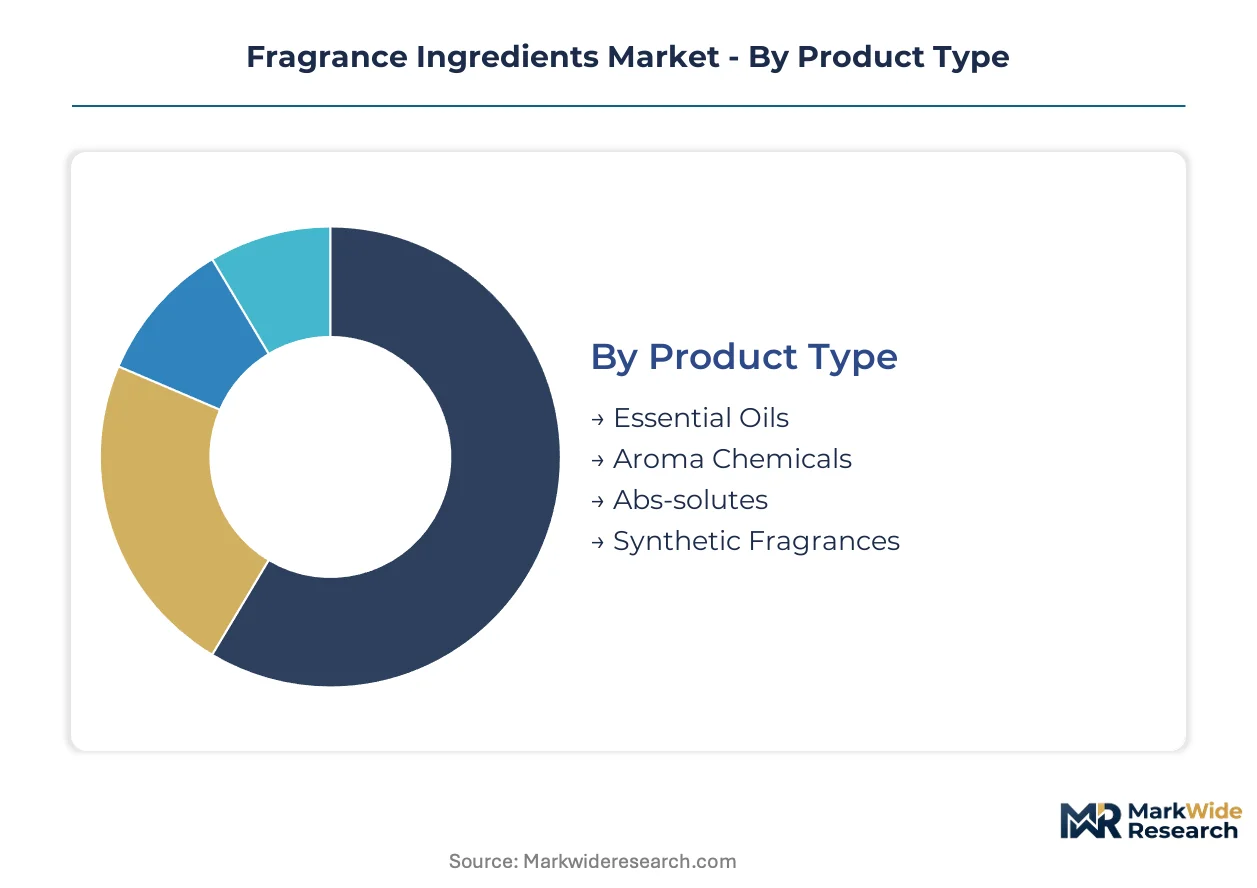
Fragrance ingredients segment across multiple axes that determine pricing power, regulatory exposure, and supply chain configuration. Product chemistry and application end-use create the deepest strategic fault lines for procurement and formulation decisions.
Product Type:
Mature extraction methods anchor essential oils and synthetics, while biotechnology platforms are accelerating aroma chemical production.
- Essential Oils:Steam-distilled or solvent-extracted volatile compounds from botanical sources. Fine fragrance houses in France concentrate procurement here for olfactory complexity that synthesis cannot replicate.
- Aroma Chemicals:Synthesized via Friedel-Crafts alkylation, Grignard reactions, or precision fermentation. Mass-market household brands in China source these for cost stability and allergen-controlled reproducibility.
- Absolutes:Solvent-extracted concentrated aromatic materials from delicate flowers. Limited commercial scale due to extraction complexity and raw material fragility.
- Synthetic Fragrances:Laboratory-engineered aromatic compounds designed to mimic naturals. REACH disclosure requirements are compressing formulation timelines for this segment.
Essential oils retain volume leadership; aroma chemicals hold the steepest expansion curve.
Application:
Margin structure varies sharply across end-use channels, with regulatory intensity scaling from household products through skin-contact formulations.
- Cosmetics:Skin-safe and hypoallergenic formulations face the steepest compliance burden under REACH and SAMR GB standards. Clean-label brands reformulate toward natural essential oils here.
- Household Products:Mass-market volume driver where synthetic fragrances dominate for cost predictability. Chinese domestic manufacturers localize supply chains aggressively in this segment.
- Personal Care:Intermediate regulatory scrutiny with growing transparency demands. EU Green Deal biobased thresholds reshape supplier qualification.
- Air Care:Functional fragrance delivery with lower skin-contact safety requirements. Innovation concentrates in controlled-release gel and solid formats.
Household products command absolute volume; cosmetics delivers the deepest margin pools.
Form:
Physical state determines manufacturing equipment compatibility, shipping economics, and formulation flexibility across customer types.
- Liquid:Standard carrier for most fragrance compounds, enabling precise dosing in automated production lines. Dominates fine fragrance compounding.
- Solid:Encapsulated or wax-based formats for controlled release in air care and personal care sticks. Growing share in travel-friendly cosmetics.
- Gel:Thickened aqueous or alcohol systems for plug-in air fresheners and shower products. Specialized rheology requirements limit supplier base.
- Powder:Spray-dried or absorbed fragrances for laundry and dry shampoo applications. Handling complexity constrains adoption outside industrial-scale buyers.
Liquid forms dominate manufacturing throughput; solid formats are climbing fastest on portability trends.
End User:
Channel position shapes procurement scale, technical service requirements, and price negotiation leverage.
- Manufacturers:Integrated fragrance houses and consumer product companies with captive formulation capabilities. Direct sourcing contracts with cultivation cooperatives concentrate here.
- Retailers:Private-label brands and specialty stores requiring tolling arrangements and modular formulation support. Asset-light contract manufacturing serves this tier.
- Wholesalers:Intermediate distributors aggregating volume across smaller buyers. Declining share as direct sourcing displaces commodity spot markets.
- Distributors:Regional logistics specialists with limited technical added value. Consolidation pressure from backward-integrated suppliers.
Manufacturers anchor procurement volume; retailers are expanding fastest on private-label fragrance growth.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
France and the United States remain net exporters of high-value fragrance compounds, while China and India scale domestic production to reduce import dependency. The EU Green Deal and REACH authorization timelines are compressing supplier qualification windows across European markets. Procurement patterns in each geography reflect divergent regulatory architectures and end-use concentration.
United States
Fine fragrance houses in New York and Los Angeles drive demand for rare botanical extracts and biotechnology-derived aroma molecules. FDA maintains fragrance allergen labeling guidance under the Fair Packaging and Labeling Act without REACH-equivalent restriction lists. The New Jersey chemical corridor hosts concentrated flavor and fragrance R&D operations serving North American cosmetics manufacturers.
France
Grasse-region growers anchor global supply of rose, jasmine, and lavender absolutes for luxury perfume houses. REACH compliance and ECHA candidate list expansion force systematic reformulation of legacy synthetic compounds. The Provence-Alpes-Côte d'Azur cluster concentrates distillation infrastructure and direct sourcing contracts with cultivation cooperatives.
China
Domestic perfume brands in Shanghai and Guangzhou localize supply chains and concentrate procurement within national borders. SAMR enforces GB standards for cosmetic fragrance safety that diverge from Western allergen lists. The Yangtze River Delta hosts expanding manufacturing capacity for synthetic aroma chemicals serving household product exporters.
Germany
Industrial fragrance applications in North Rhine-Westphalia drive demand for cost-stable synthetic compounds in cleaning and air care products. EU Green Deal biobased content thresholds reshape supplier qualification criteria for personal care formulations. The Cologne-Düsseldorf corridor concentrates contract manufacturing and third-party tolling arrangements for mid-tier brands.
India
Essential oil extraction in Karnataka and Tamil Nadu supplies global demand for sandalwood, jasmine, and spice-derived aromatics. BIS certification requirements for essential oil purity extend product launch timelines for export markets. The Mumbai-Pune industrial belt hosts formulation facilities serving domestic personal care brands and Middle Eastern re-exporters.
Fragrance Ingredients Market Vendor Landscape
Platform integrators command the system tier; component specialists sit upstream in captive cultivation and biotechnology licensing. The supplier base stratifies between backward-integrated majors with dedicated agricultural operations and asset-light tolling networks serving private-label brands. Three archetypes dominate: cultivation-integrated houses securing rare raw material streams, fermentation-platform operators bypassing agricultural constraints, and modular formulation providers enabling jurisdiction-adaptive compliance. Competitive intensity concentrates on direct sourcing contract negotiations and biotech molecule patent positions.
Within the integrated cultivation tier, Givaudan SA and Symrise AG exemplify upstream control strategies through dedicated grower relationships in specialized geographies. International Flavors & Fragrances Inc. occupies a position representing biotechnology-forward platforms that ferment fragrance molecules without land-based agriculture. These three Swiss and US-based entities anchor distinct competitive vectors: botanical rarity, sustainable sourcing certification, and precision fermentation scale.
| Leading Market Players |
|---|
| Givaudan SA |
| Symrise AG |
| International Flavors & Fragrances Inc. |
| BASF SE |
| Firmenich SA |
| Mane SA |
| Takasago International Corporation |
| Robertet Group |
| Sensient Technologies Corporation |
| Others |
Supply Flow & Price Mechanics
Harvest volatility in Indonesian patchouli and Madagascan vanilla determines both tiered pricing spreads across essential oil grades and the geographic shape of fragrance ingredient supply chains. Fine fragrance houses absorb premium costs for rare botanicals while mass-market brands shift toward synthetic alternatives when agricultural inputs spike.
Pricing Analysis
Industrial OEM buyers anchor contract-based long-term offtake pricing for synthetic aroma chemicals, with three-tier pricing structure across premium, standard, and economy levels differentiated by certification grade and volume scale. Price differentiation reflects REACH compliance tier and backward integration status. Cost compression in standard-grade synthetics is intensifying because Chinese domestic manufacturers scale fermentation capacity. Mass-market household product brands exhibit highest price sensitivity; luxury perfume houses demonstrate lowest sensitivity for rare absolutes.
Supply Chain Analysis
Third-party tolling networks in Germany, France, and China hold concentrated contract-manufacturing capacity for fragrance ingredient formulation. Raw material flows draw from Grasse-region rose cultivation, Indonesian patchouli cooperatives, and Madagascan vanilla estates. Single-source vulnerability concentrates in Madagascan vanilla supply. Distribution runs through direct sourcing contracts between fragrance houses and cultivation cooperatives, displacing traditional commodity spot markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragrance ingredients are recovering from cyclical agricultural input compression as biotechnology platforms mature and normalize supply continuity against weather-driven harvest disruptions.
For Market Incumbents: Harden direct sourcing contracts with Grasse-region and Madagascar cultivation cooperatives against biotech fermentation entrants. Invest in REACH dossier preparation capacity to accelerate reformulation cycles as ECHA expands restricted substance lists. Backward integration into certified vanilla and patchouli programs secures raw material streams that synthetic substitutes cannot yet replicate. For New Entrants and Emerging Players: Mid-market clean-label personal care brands in China represent the most penetrable entry point, as domestic manufacturers seek localized essential oil suppliers outside established fragrance house networks. Asset-light tolling arrangements with German contract manufacturers enable compliance-adaptive production without distillation infrastructure investment. Target modular formulation platforms that bridge REACH and SAMR GB standard divergence. For Investors and Strategic Acquirers: The market sits at a technology substitution phase that favors precision fermentation platform operators with patent-protected molecule libraries. Long-term viability over the next decade hinges on supply virtualization capabilities that decouple production from agricultural geography. Watch biotech licensing deal velocity as the inflection indicator for synthetic-to-natural substitution acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Cultivation | Captive sourcing from Madagascar and Indonesia secures rare raw material streams against climate volatility. |
| Precision Fermentation Scale-Up | Biotechnology platforms in the New Jersey corridor bypass agricultural land use constraints for aroma chemical production. |
| Modular Formulation Platform Development | Jurisdiction-adaptive systems enable single-SKU compliance across REACH, FDA, and SAMR regulatory regimes. |
| Direct Sourcing Contract Expansion | Multi-year agreements with Grasse-region growers displace commodity intermediation in fine fragrance supply chains. |
| Green Certification Program Investment | EU Green Deal biobased thresholds reshape supplier qualification criteria for personal care formulations. |
Methodological Framework
Desk research of customs trade data, ECHA regulatory filings, and SEC 10-K disclosures preceded structured interviews with fragrance house procurement directors, essential oil distillation plant managers, cosmetic brand regulatory affairs leads, and third-party tolling network operators. Primary fieldwork combined with secondary validation from customs records and industry association reports. Bottom-up volume estimates and top-down value triangulation anchored market sizing.
Assumptions held fixed include REACH authorization timelines and EU Green Deal biobased content thresholds, while variables included Chinese domestic brand expansion rates and biotechnology platform scale-up velocity. Segmentation modeling spanned product chemistry, application end-use, physical form, and channel position across the projection horizon. CAGRs derived from weighted average growth across essential oil extraction, synthetic aroma chemical synthesis, and precision fermentation adoption curves. Forecast inputs incorporated harvest yield volatility indices and regulatory restriction list expansion schedules.
Practitioners should monitor ECHA candidate list additions, Chinese SAMR GB standard revisions, and Madagascar vanilla harvest reports for early signals of forecast deviation. Quarterly review of biotech licensing deal flow, REACH dossier submission rates, and Indonesian patchouli spot price indices is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Flavor and Fragrance Chemicals
Global Perfume Ingredients Chemicals Market
Flavor and Fragrance Chemicals
Aromatic Compounds Market
Flavor and Fragrance Chemicals
Guaiacwood Oil Market
Flavor and Fragrance Chemicals
Camphor Market
Flavor and Fragrance Chemicals
Scent Eliminators Market
Flavor and Fragrance Chemicals
India Aroma Chemicals Market
Flavor and Fragrance Chemicals
Middle East and Africa Deodorants Market
Flavor and Fragrance Chemicals
Asia-Pacific Aroma Chemicals Market
Flavor and Fragrance Chemicals
Dihydrocitronellol Market
Flavor and Fragrance Chemicals
Global Terpene Market
Flavor and Fragrance Chemicals
Linalool Market
Flavor and Fragrance Chemicals
Natural Fragrance Ingredients Market
Flavor and Fragrance Chemicals
Perfumes and Deodorants Market
Flavor and Fragrance Chemicals
Arborvitae Oil Market
Flavor and Fragrance Chemicals
Tangerine Oil Market
Flavor and Fragrance Chemicals
Estragole Market