
 Tangerine Oil Market | 2026-2036
Tangerine Oil Market Size, Share, and Industry Trends Forecast 2026-2036
Tangerine Oil Market Analytics
Pharmaceutical-grade specification tiers is reorganizing competitive dynamics in tangerine oil supply. Young Living Essential Oils leverages its captive distillery network across multiple citrus-growing zones to secure raw material consistency. Symrise AG sustains large-scale extraction infrastructure that anchors European flavor-house supply chains. Mountain Rose Herbs differentiates through certified organic positioning and direct-to-practitioner channel control in North America.
Tangerine oil is a cold-pressed or steam-distilled essential oil extracted from Citrus reticulata peel, containing 90-95% limonene with trace gamma-terpinene and alpha-pinene; it functions primarily as a natural flavoring agent, fragrance component, and topical active in cosmetic formulations. Cold-pressed grades command premium positioning in cosmetics and aromatherapy applications where terpene integrity drives efficacy claims, while distilled variants serve cost-sensitive cleaning product manufacturers seeking standardized odor profiles. Food flavoring applications represent a mature volume pool with stable offtake from beverage and confectionery manufacturers, whereas organic certification across all product types is extracting margin premiums from clean-label buyers in retail and wholesale channels.
USDA organic standards and FDA food additive regulations govern product claims and market access in the United States, while REACH registration and ECHA classification requirements in the European Union constrain synthetic substitute penetration and elevate documentation burdens for importers. Brazil's national agricultural regulator enforces phytosanitary export protocols that directly shape shipment eligibility to major destination markets. Stakeholders must monitor evolving residue limits and certification harmonization between major import jurisdictions to protect supply continuity and pricing power.
Market Dynamics
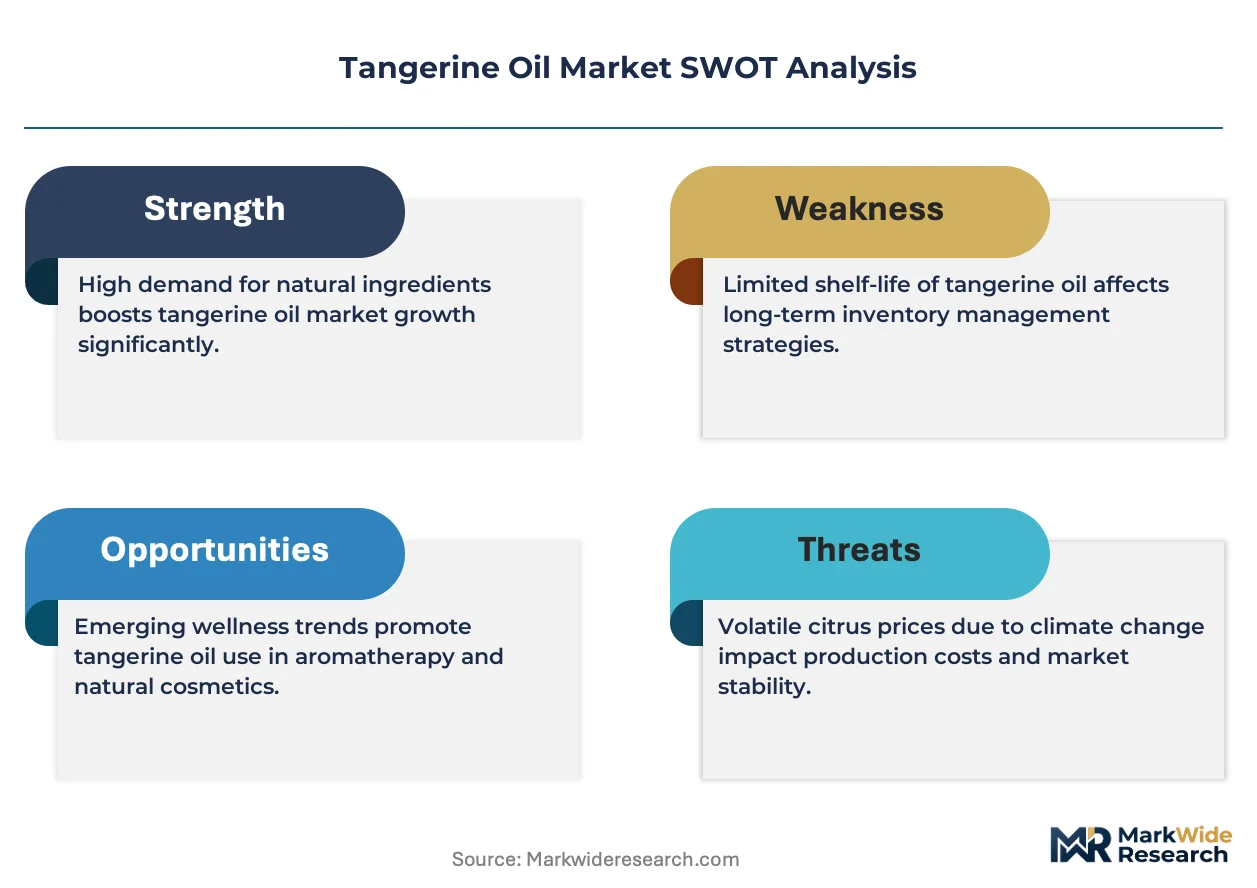
REACH compliance across the European Union is tightening residual solvent limits, forcing distillers to abandon conventional extraction methods and migrate toward certified organic processes that preserve terpene integrity while satisfying documentation burdens.
Growth Catalysts
- Cold-pressed grade premiumization:Cosmetics manufacturers in France and Germany are expanding procurement of cold-pressed tangerine oil for premium skincare formulations where terpene integrity drives efficacy claims and commands margin premiums.
- REACH solvent restrictions:The European Union's tightening residual solvent limits under REACH registration requirements are accelerating adoption of certified organic distillation methods that satisfy import documentation standards.
- Brazilian feedstock concentration:São Paulo state processors supply concentrated citrus peel feedstock to North American and European blenders, anchoring supply security for downstream fragrance and flavor house operations.
Market Restraints
- Citrus greening disease pressure:Huanglongbing pathogen spread across Florida and São Paulo groves is constraining raw peel availability and elevating input cost volatility for cold-pressed grade producers.
- Synthetic limonene substitution:Petroleum-derived limonene from turpentine fractionation offers cost-competitive odor standardization, threatening natural tangerine oil penetration in mass-market cleaning product formulations.
- Organic certification timeline:USDA organic and EU organic conversion periods impose multi-year field transition requirements that freeze supply expansion from conventional citrus groves seeking premium positioning.
Strategic Opportunities
- Direct-to-practitioner channels:Certified organic positioning through practitioner-focused distribution in North America is extracting margin premiums from aromatherapy and clinical herbalism segments seeking traceability documentation.
- Pharmaceutical-grade specification tiers:Specification differentiation between cosmetic, food-grade, and pharmaceutical tiers creates white space for processors investing in analytical testing infrastructure and GMP-compliant facilities.
- Clean-label beverage innovation:Natural flavoring claims in zero-sugar and functional beverage categories are pulling distilled tangerine oil into new product development pipelines seeking citrus top-notes without synthetic alternatives.
Industry Challenges
- Analytical chemist scarcity:Gas chromatography-mass spectrometry expertise for terpene profiling and adulteration detection is concentrated among legacy flavor houses, constraining quality assurance scaling for mid-size processors.
- Multi-jurisdiction certification complexity:Harmonization gaps between USDA organic, EU organic, and Brazil's national agricultural regulator phytosanitary protocols force duplicate testing and documentation burdens that extend shipment clearance timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Tangerine Oil Market |
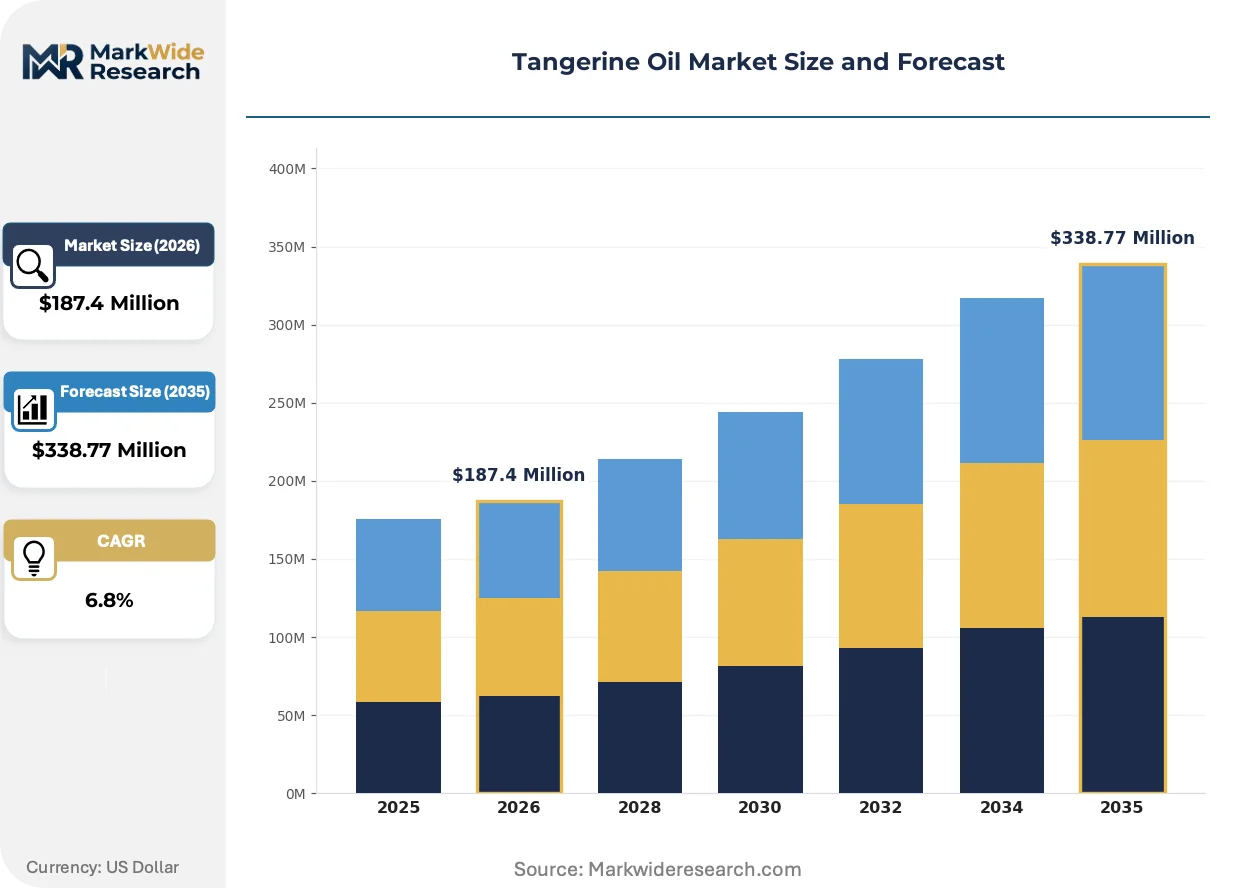
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cold Pressed, Distilled, Organic, Synthetic Application: Cosmetics, Aromatherapy, Food Flavoring, Cleaning Products End User: Manufacturers, Retail, Wholesalers, Individual Consumers Packaging Type: Glass Bottles, Plastic Containers, Bulk Packaging, Vials |
| Companies Covered | Young Living Essential Oils, doTERRA International, Mountain Rose Herbs, Eden Botanicals, Citrus and Allied Essences Ltd, NOW Foods, Plant Therapy Essential Oils, Vigon International, Symrise AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Tangerine Oil Market Evolving Landscape
Extraction technology convergence with analytical quality control systems is compressing batch-to-batch variation and enabling specification-grade differentiation that separates cosmetic, pharmaceutical, and industrial applications.
Supercritical carbon dioxide extraction systems are miniaturizing from industrial-scale installations to mid-capacity skid-mounted units that processors in São Paulo and Florida are deploying for selective terpene recovery. Mid-size distillers are adopting these systems to capture premium cold-pressed equivalent grades without mechanical pressing infrastructure. This technology diffusion is compressing capital barriers between artisan and industrial production tiers while elevating baseline quality consistency.
REACH registration requirements in the European Union are mandating full substance dossiers for fragrance allergens including limonene oxidation products, compelling importers to invest in supply chain documentation systems that trace geographic origin and harvest date. Fragrance houses are responding by consolidating supplier bases toward vertically integrated Brazilian processors with captive laboratory testing capabilities. The regulatory burden is accelerating documentation automation investments across European distribution networks.
Practitioner and small-batch formulators are consolidating purchasing through cooperative buying groups and direct-import arrangements that bypass traditional flavor house distribution tiers. These channel innovations are most visible in North American aromatherapy and natural cosmetics segments where certified organic documentation commands price premiums. Regional blender networks in California and Oregon are establishing direct relationships with São Paulo state cooperatives to secure harvest-lot traceability.
Tangerine Oil Market Segmentation
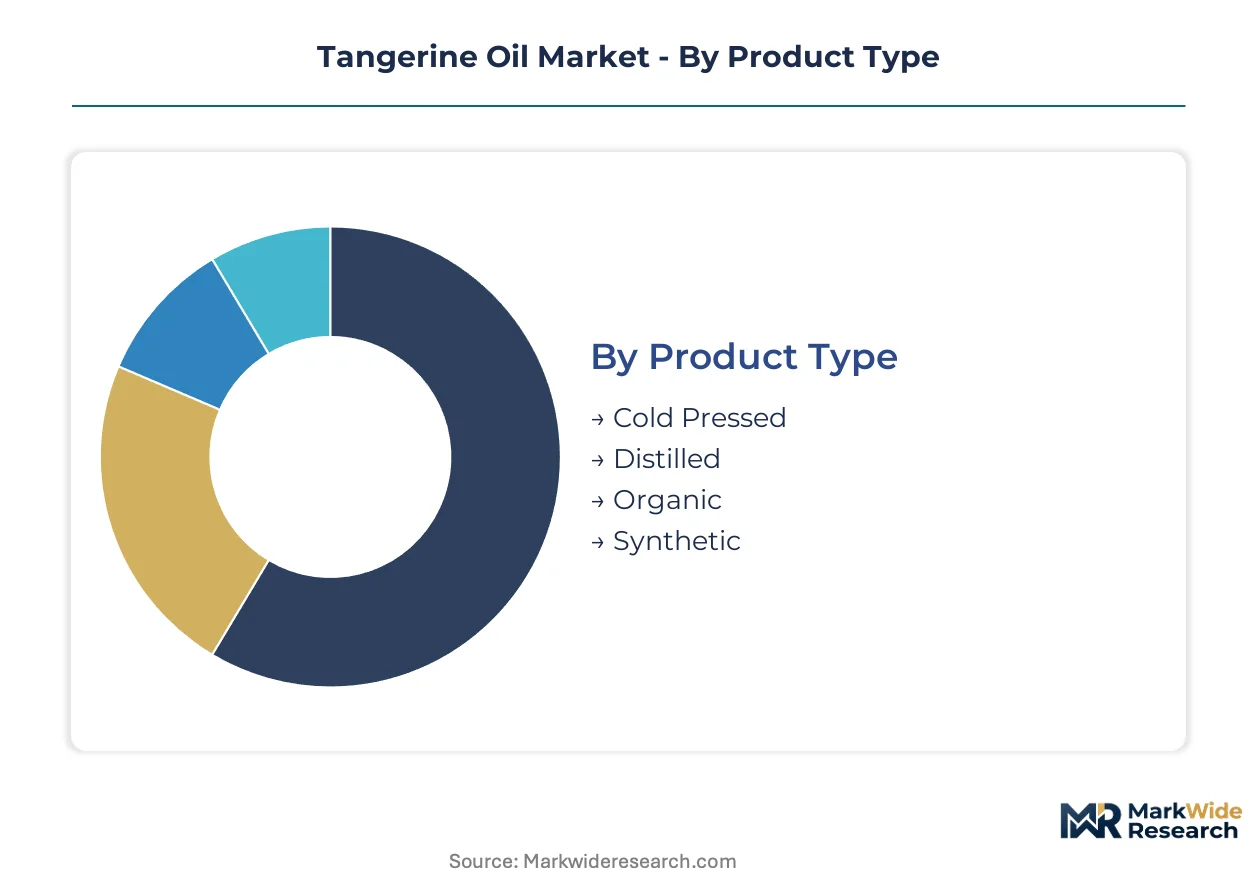
Tangerine oil pricing stratifies sharply across extraction methods and certification tiers, with cold-pressed and organic grades commanding substantial premiums over distilled alternatives. Understanding segment boundaries reveals where procurement budgets concentrate and where supply constraints create margin pressure for downstream buyers.
Product Type:
Cold-pressed and organic grades capture the deepest margin pools within this category, while distilled volumes anchor baseline revenue stability.
- Cold Pressed:Mechanical extraction at ambient temperature preserves 90-95% limonene content with intact terpene profiles essential for cosmetic efficacy claims. French and German skincare manufacturers are expanding procurement of this grade for premium formulations where terpene integrity justifies price premiums.
- Organic:USDA and EU organic certification requires multi-year field transition and residue-free processing, extracting margin premiums from clean-label buyers in North American retail channels. São Paulo state cooperatives are investing in certification infrastructure to access this tier.
- Distilled:Steam-distilled variants serve cost-sensitive cleaning product manufacturers seeking standardized odor profiles with lower capital intensity.
- Synthetic:Petroleum-derived limonene from turpentine fractionation offers odor standardization at reduced cost, threatening natural oil penetration in mass-market applications.
The dominant share belongs to Distilled, while Organic is closing the gap fastest as certification infrastructure matures in Brazilian supply zones.
Application:
Volume concentration varies dramatically by use case, with cosmetics and food flavoring anchoring distinct procurement patterns.
- Cosmetics:Cold-pressed grades dominate premium skincare and fragrance formulations where terpene integrity supports natural positioning claims. REACH registration requirements for fragrance allergens are consolidating supplier bases toward Brazilian processors with captive laboratory capabilities.
- Aromatherapy:Practitioner-focused distribution channels in California and Oregon extract premiums through certified organic positioning and harvest-lot traceability direct from São Paulo cooperatives.
- Food Flavoring:Beverage and confectionery manufacturers pull stable volumes of distilled oil for citrus top-notes in zero-sugar and functional product lines.
- Cleaning Products:Synthetic limonene substitution pressure is strongest here, with petroleum-derived alternatives threatening natural oil penetration in odor-standardized formulations.
Food Flavoring retains the largest volume footprint, though Cosmetics is expanding most quickly as clean-label skincare claims proliferate.
End User:
Procurement scale and documentation requirements fragment sharply across buyer types in this category.
- Manufacturers:Flavor houses and cosmetics formulators drive specification-grade demand with batch-to-batch consistency requirements and multi-jurisdiction certification documentation.
- Retail:Clean-label positioning commands premium shelf pricing for certified organic SKUs in natural products channels.
- Wholesalers:Regional blender networks in North America are establishing direct-import arrangements that bypass traditional distribution tiers.
- Individual Consumers:Cooperative buying groups consolidate practitioner and small-batch formulator demand for traceability documentation.
Manufacturers control the deepest procurement volumes, while Retail is gaining share fastest through clean-label SKU expansion.
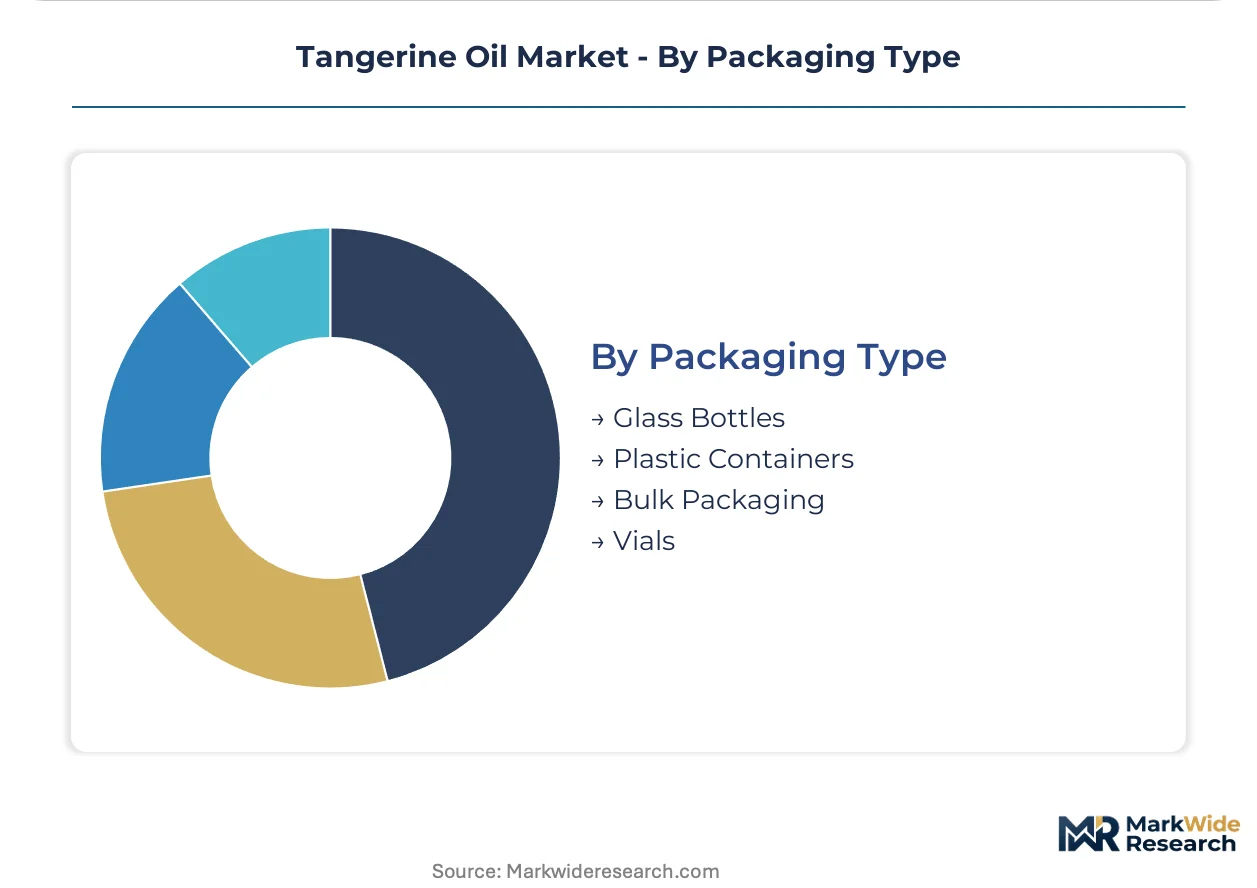
Packaging Type:
Packaging selection tracks application value density and shelf-life requirements across downstream segments.
- Glass Bottles:Premium cosmetics and aromatherapy applications favor amber glass for UV protection and shelf stability.
- Plastic Containers:Cost-sensitive industrial and cleaning product applications accept HDPE for volume-scale distribution.
- Bulk Packaging:Drum and tote formats serve flavor house and cosmetics manufacturer procurement at industrial scale.
- Vials:Sample and practitioner-tier distribution favors small-format packaging for direct-to-consumer channels.
Bulk Packaging anchors manufacturer procurement volumes, though Glass Bottles are climbing fastest alongside premium cosmetics expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in mass-market cleaning formulations remain highly price-sensitive to synthetic limonene substitution, while cosmetics manufacturers in France and Germany absorb substantial premiums for cold-pressed terpene integrity.
United States
California and Oregon practitioner networks are establishing direct-import arrangements with São Paulo cooperatives for certified organic harvest-lot traceability. FDA food additive regulations and USDA organic standards govern product claims and market access. Florida groves face citrus greening disease pressure that constrains raw peel availability for domestic cold-pressed production.
Brazil
São Paulo state processors supply concentrated citrus peel feedstock to North American and European fragrance and flavor house operations. ANVISA enforces phytosanitary export protocols that directly shape shipment eligibility to major destination markets. The state's citrus belt is investing in certification infrastructure to access organic premium tiers.
Germany
Cosmetics manufacturers are expanding procurement of cold-pressed grades for premium skincare formulations where terpene integrity drives efficacy claims. REACH registration and ECHA classification requirements constrain synthetic substitute penetration and elevate documentation burdens for importers. The country's flavor houses anchor European supply chain consolidation.
France
Premium skincare formulators command margin premiums through natural positioning claims backed by cold-pressed terpene profiles. REACH compliance is tightening residual solvent limits and pushing distillers toward certified organic processes. The country's cosmetics cluster maintains deep procurement relationships with Brazilian processors.
China
Beverage manufacturers are pulling distilled tangerine oil into zero-sugar and functional product development pipelines for citrus top-notes. SAMR and national GB standards govern food additive safety and labeling requirements. Processing capacity in coastal provinces is expanding to serve domestic flavoring demand.
Tangerine Oil Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the tangerine oil market. Vertically integrated processors with captive laboratory capabilities capture premium-tier value through specification-grade differentiation and multi-jurisdiction certification documentation. The competitive terrain separates into three strategic archetypes: global flavor houses with large-scale extraction infrastructure, certified organic specialists with direct-to-practitioner channel control, and mid-size processors deploying supercritical carbon dioxide systems for selective terpene recovery. Dominant competitive moves include backward integration into Brazilian citrus belt feedstock sourcing and portfolio diversification across pharmaceutical-grade specification tiers.
Among North American certified organic specialists, Mountain Rose Herbs and Young Living Essential Oils exemplify the practitioner-focused distribution archetype extracting margin premiums through traceability documentation. Symrise AG occupies a position representing the European flavor house consolidation pattern with large-scale extraction infrastructure anchoring downstream supply chains. These three companies illustrate how geographic origin and channel strategy map to distinct competitive positioning within the market's tiered structure.
| Leading Market Players |
|---|
| Young Living Essential Oils |
| doTERRA International |
| Mountain Rose Herbs |
| Eden Botanicals |
| Citrus and Allied Essences Ltd |
| NOW Foods |
| Plant Therapy Essential Oils |
| Vigon International |
| Symrise AG |
| Others |
Value Network & Pricing Analysis
Petroleum-derived limonene substitution from turpentine fractionation is compressing margins in mass-market cleaning formulations while simultaneously pushing natural tangerine oil procurement toward Brazilian supply zones where São Paulo state processors command pricing power through concentrated feedstock availability.
Pricing Analysis
After-sales documentation and certification services drive lifetime value for premium-grade suppliers. Three-tier pricing structure across organic-certified, cold-pressed standard, and distilled economy levels anchors market segmentation. Price differentiation rests on terpene integrity metrics and REACH-compliant solvent documentation. Cost compression in distilled grades is intensifying because synthetic limonene offers odor standardization at lower input cost. Cleaning product manufacturers exhibit highest price sensitivity, while French and German cosmetics formulators absorb substantial premiums for cold-pressed terpene profiles.
Supply Chain Analysis
Santos port congestion and phytosanitary clearance bottlenecks in São Paulo state constrain feedstock flow to North American and European blenders. Supply concentration centers on Brazil, the United States, and France as primary production and processing nodes. Raw material dependencies include Citrus reticulata peel feedstock, mechanical pressing equipment, and supercritical carbon dioxide extraction systems. Single-source vulnerability runs through São Paulo state cooperatives supplying concentrated peel to downstream fragrance houses. Distribution feeds from processor-direct arrangements toward flavor house consolidation and practitioner cooperative networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents face a substitution defense imperative against petroleum-derived limonene penetration in cost-sensitive applications, requiring strategic repositioning toward certification-protected premium tiers.
For Market Incumbents: Secure backward integration into São Paulo state citrus belt feedstock sourcing to anchor supply continuity against citrus greening disease volatility. Deepen captive laboratory capabilities for terpene profiling and REACH documentation to defend margin position against mid-size processors deploying supercritical systems. Certification investment represents the critical lever for extracting premiums from clean-label buyer consolidation.
For New Entrants and Emerging Players: USDA organic certification fast-track through São Paulo state cooperative partnerships opens practitioner-channel white space in California and Oregon aromatherapy segments. Target pharmaceutical-grade specification tiers where analytical testing infrastructure scarcity constrains incumbent scaling. Direct-to-practitioner distribution with harvest-lot traceability documentation offers the most penetrable go-to-market angle against established flavor house networks.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed mid-size processors in Florida and São Paulo deploying supercritical carbon dioxide extraction for selective terpene recovery. Long-term viability frames around certification infrastructure ownership and multi-jurisdiction documentation automation. Acquisition targets should show captive Brazilian feedstock relationships and GMP-compliant analytical facilities. Watch REACH solvent limit tightening trajectory as the signal for organic process investment inflection.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Brazilian Feedstock | São Paulo state peel concentration anchors supply security against citrus greening disease pressure. |
| Supercritical CO2 Extraction Deployment | Mid-capacity skid-mounted systems compress capital barriers between artisan and industrial production tiers. |
| Multi-Jurisdiction Certification Automation | REACH documentation requirements accelerate investment in supply chain traceability systems across European distribution networks. |
| Pharmaceutical-Grade Specification Tier Entry | GMP-compliant facilities and analytical testing infrastructure capture margin premiums from specification differentiation. |
| Direct-to-Practitioner Channel Development | Cooperative buying groups in California and Oregon extract premiums through harvest-lot traceability documentation. |
Research Methodology
The analysis maps cold-pressed grade extraction, certified organic processing, distilled volume production, and synthetic substitution dynamics, each validated through flavor house procurement directors, cosmetics formulator R&D leads, São Paulo state cooperative managers, and aromatherapy practitioner network organizers. Primary interviews with these stakeholders combined with secondary validation from FDA food additive filings, USDA organic certification databases, ANVISA phytosanitary export records, and REACH registration dossiers. Bottom-up volume modeling and top-down value triangulation cross-checked against customs trade data and ECHA substance registration trends.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. The analytical framework segmented by extraction method, certification tier, application end-use, and geographic supply zone. CAGRs derived from normalized historical baselines and forward-looking input cost assumptions. Industry-specific forecast inputs incorporated citrus greening disease incidence trajectories and synthetic limonene price spread dynamics.
Decision-makers should treat outputs as directional under sustained Brazilian feedstock concentration and stable REACH regulatory trajectory assumptions; material deviation in phytosanitary protocol stringency or petroleum-derived substitute pricing would warrant model refresh. Practitioners should keep alternative scenarios live as organic certification infrastructure buildout and supercritical technology diffusion evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Flavor and Fragrance Chemicals
Linalool Market
Flavor and Fragrance Chemicals
Synthetic Musk Market
Flavor and Fragrance Chemicals
Coumarin Market
Flavor and Fragrance Chemicals
Ethyl Vanillin Market
Flavor and Fragrance Chemicals
Sulphite Ammonia Caramel Market
Flavor and Fragrance Chemicals
Bio-Based Flavors and Fragrances Market
Flavor and Fragrance Chemicals
Essential Oil Blends Market
Flavor and Fragrance Chemicals
Global Cinnamaldehyde Market
Flavor and Fragrance Chemicals
Europe Flavors and Fragrances Market
Flavor and Fragrance Chemicals
Europe Aroma Chemicals Market
Flavor and Fragrance Chemicals
Fragrance Ingredients Market
Flavor and Fragrance Chemicals
Synthetic Cinnamaldehyde Market
Flavor and Fragrance Chemicals
Citral Market
Flavor and Fragrance Chemicals
Asia-Pacific Deodorants Market
Flavor and Fragrance Chemicals
Flavor and Fragrance Market
Flavor and Fragrance Chemicals
India Essential Oils Market