
 Geochemical Services Market | 2026-2036
Geochemical Services Market Size, Share, and Industry Trends Forecast 2026-2036
Geochemical Services Market Intelligence
The divergence in capital investment between automated, high-throughput laboratories and smaller, specialized analytical firms is redrawing the competitive landscape. Large-scale providers like SGS SA and Bureau Veritas leverage their global network of accredited labs to service major mining and environmental projects. In contrast, specialists such as Activation Laboratories differentiate through proprietary analytical techniques for specific elements.
Geochemical services involve the systematic measurement of chemical elements in earth materials like rock, soil, and water. These services utilize techniques such as Inductively Coupled Plasma (ICP) analysis to determine elemental concentrations with parts-per-billion precision. The primary purpose is to identify mineral deposits, assess environmental contamination, and support resource exploration. Within applications, mineral exploration constitutes the largest demand segment, driven by the search for energy transition metals. For service types, while sample analysis generates the most volume, data interpretation and consulting services command higher margins.
Environmental regulations enforced by agencies like the US EPA and frameworks such as the EU's REACH directive mandate stringent soil and water quality testing, creating consistent demand for analytical services. Separately, mining codes in Australia and Canada require geochemical surveys as part of the exploration and permitting process, ensuring market stability. Stakeholders must now decide whether to invest in advanced analytical technologies for trace element detection or to specialize in high-volume, standardized testing for environmental compliance.
Market Dynamics
The global energy transition acts as the central organizing force for the geochemical services market. Surging demand for critical minerals, essential for batteries and renewable energy infrastructure, is fundamentally reorienting service demand toward resource definition and accelerating the adoption of high-throughput analytical technologies.
Growth Catalysts
- Energy Transition Mandates:Policy frameworks like the EU Green Deal and national critical mineral strategies in Canada and Australia directly stimulate mineral exploration. These policies create sustained demand for geochemical surveys to identify new deposits of lithium, cobalt, and rare earth elements.
- Precision Agriculture Adoption:The agricultural sector increasingly uses detailed soil chemistry analysis to optimize fertilizer application and improve crop yields. This creates a new and expanding application for soil geochemical services beyond traditional environmental testing and mineral exploration.
- Advances in Analytical Precision:The commercialization of more sensitive Inductively Coupled Plasma (ICP) techniques allows for detection at ultra-trace levels. This enhanced capability enables the identification of lower-grade, previously undetectable mineral deposits, expanding the scope of viable exploration targets.
Market Restraints
- High Capital Expenditure:Establishing and maintaining an accredited, high-throughput geochemical laboratory requires substantial investment in advanced instrumentation like ICP-MS and automated sample preparation systems. This high initial cost acts as a significant barrier to entry for new competitors.
- Proprietary Methodologies:Certain advanced analytical techniques for specific or difficult-to-measure elements are proprietary to specialized firms. This limits wider market access to these methods and can create vendor lock-in for clients requiring these specific analyses.
- Sample Logistics Complexity:The transportation of geological and environmental samples across international borders is subject to complex customs regulations and quarantine protocols. These logistical hurdles can introduce significant delays and costs, particularly for projects in remote locations.
Strategic Opportunities
- Geochemical Data Integration:There is a significant opportunity in developing platforms that integrate geochemical data with satellite imagery and machine learning algorithms. This convergence can create powerful predictive models for mineral targeting and environmental risk assessment, moving beyond simple analysis.
- Seafloor Mineral Exploration:As terrestrial deposits become more challenging to find, exploration for seafloor massive sulfides and polymetallic nodules represents a new frontier. This requires the development of specialized underwater sampling techniques and analytical protocols.
- Environmental Forensics:Advanced isotopic and elemental fingerprinting can be used to trace the source of pollutants in soil and groundwater. This emerging application in environmental litigation and remediation provides a high-value niche for specialized geochemical services.
Industry Challenges
- Data Standardization and Comparability:A lack of universal standards for data formatting and analytical methods makes it difficult to compare or merge geochemical datasets from different laboratories or historical surveys. This fragmentation impedes the development of large-scale regional models.
- Skilled Personnel Shortage:The industry faces a shortage of qualified geochemists, data scientists, and instrument technicians capable of operating sophisticated equipment and interpreting complex datasets. This talent gap can constrain growth and limit the adoption of new technologies.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Geochemical Services Market |
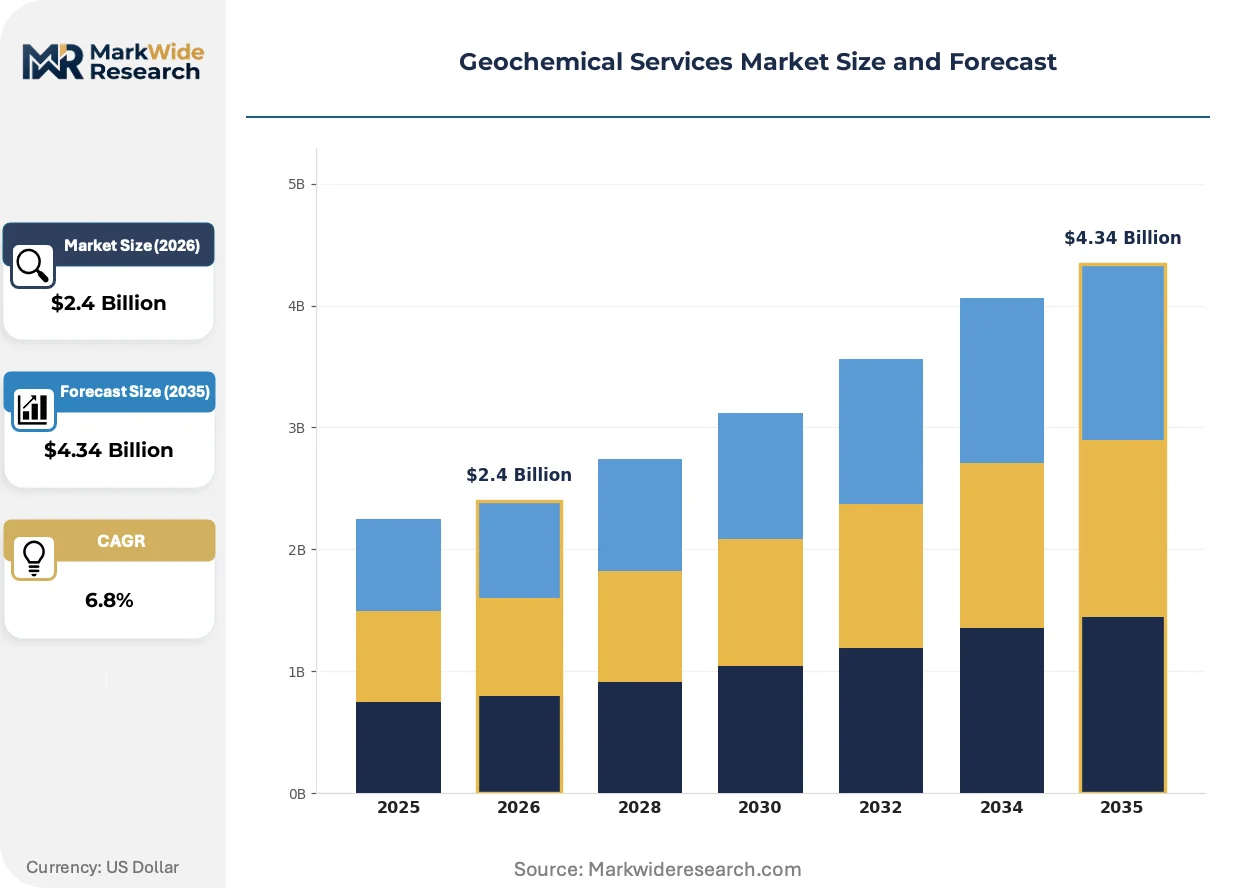
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $4.34 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Sample Analysis, Data Interpretation, Field Sampling, Consulting, Risk Assessment Application: Environmental Monitoring, Mineral Exploration, Soil Testing, Water Quality Assessment, Oil & Gas Exploration Technology: X-Ray Fluorescence, Inductively Coupled Plasma, Mass Spectrometry, Atomic Absorption Spectroscopy, Chromatography Client Type: Mining Companies, Environmental Agencies, Research Institutions, Energy Producers, Construction Firms |
| Companies Covered | SGS SA, Bureau Veritas, Intertek Group, ALS Limited, Fugro, Activation Laboratories, Schlumberger, Chinook Consulting Services, Geochemic Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Geochemical Services Market Strategic Shifts & Innovations
The industrialization of analytical workflows is transforming geochemical services from a specialized scientific practice into a scalable, data-driven industrial process. Automation in sample preparation and the integration of AI in data interpretation are central to this shift, enabling higher throughput and more predictive insights.
In-field analytical technologies like portable X-ray fluorescence (pXRF) provide real-time elemental data directly at the exploration or environmental site. Exploration geologists are rapidly adopting these tools for immediate sample screening and drill-core logging. This immediate feedback capability is decomposing the linear, batch-based process of sample collection and centralized lab analysis into a more dynamic and iterative field decision-making cycle.
The European Union's Critical Raw Materials Act is setting new precedents for resource security policies. The act compels member states to build domestic capacity for mineral exploration, processing, and recycling to reduce reliance on external supply chains. Consequently, mineral exploration firms and environmental consultancies in countries like Sweden and Finland are experiencing a direct increase in demand for geochemical surveys required for new mining permits.
Client purchasing behavior is evolving from transactional, test-by-test orders to a demand for integrated data solutions. This disrupts the traditional laboratory model, which focused solely on delivering analytical results, in favor of a consultative approach that provides interpreted data within a geological context. This trend is most pronounced in major mining jurisdictions like Australia, where resource companies seek comprehensive data packages to inform their complex 3D geological models.
Geochemical Services Market Segmentation
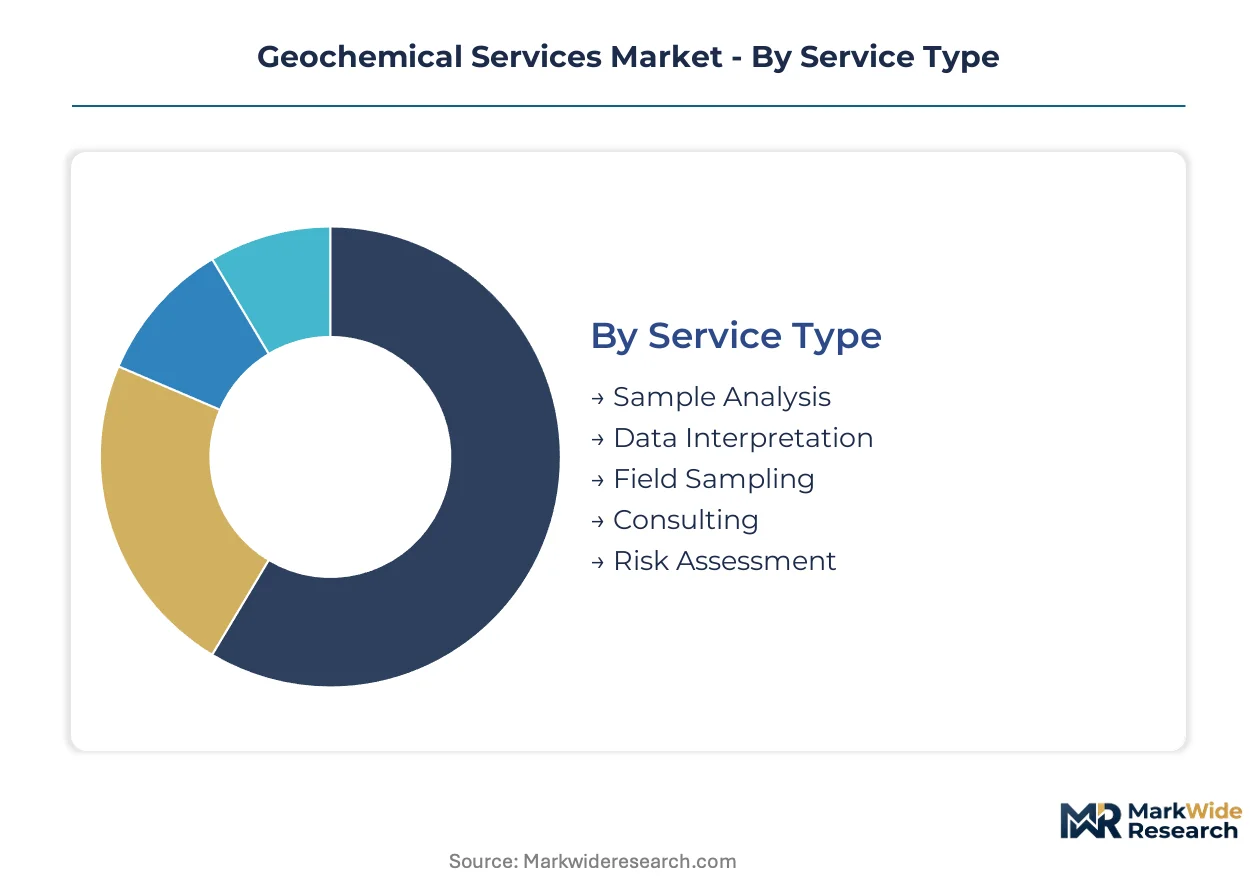
Segmentation provides a granular view of the geochemical services market, delineating demand patterns and competitive dynamics. Understanding these distinct segments allows stakeholders to tailor service offerings and strategic investments. Market segmentation reveals where value accrues and where specialized expertise drives differentiation.
Service Type:
The geochemical services market segments by service type, where traditional sample analysis faces substitution pressure from integrated data solutions and in-field technologies.
- Sample Analysis:This foundational service involves laboratory-based determination of elemental concentrations using techniques like ICP. Demand concentrates in major mining jurisdictions like Australia and Canada, driven by exploration and compliance volumes.
- Data Interpretation:This high-value service translates raw analytical results into actionable insights, integrating with geological models and machine learning. Demand concentrates in advanced exploration and complex environmental remediation, especially in the European Union where policy frameworks require comprehensive assessments.
- Field Sampling:Geochemists collect representative samples from earth materials, ensuring data integrity from the source.
- Consulting:Specialized geochemical consultants provide expert advice on survey design, data interpretation, and regulatory compliance.
- Risk Assessment:This service evaluates potential environmental hazards from contaminants, supporting remediation planning and regulatory reporting for agencies like the US EPA.
Sample Analysis anchors the volume base while Data Interpretation gains share at the steepest rate.
Application:
Volume concentration within geochemical services applications reflects the global energy transition's influence on resource demand.
- Mineral Exploration:This application identifies new mineral deposits and assesses existing resources, crucial for critical metals like lithium and cobalt. Demand concentrates in resource-rich nations such as Chile and Australia, driven by global mandates for renewable energy infrastructure.
- Environmental Monitoring:This segment assesses contaminant levels in soil and water, ensuring compliance with regulations enforced by agencies like the US EPA and the EU's REACH directive. Demand remains consistent across industrialized nations, reflecting ongoing regulatory scrutiny.
- Soil Testing:Agricultural specialists use detailed soil chemistry analysis to optimize nutrient management, improving crop yields.
- Water Quality Assessment:This application determines chemical composition of water bodies, monitoring for pollutants and ensuring potable water standards.
- Oil & Gas Exploration:Geochemical techniques identify hydrocarbon indicators, guiding drilling decisions and reducing exploration risks.
Mineral Exploration generates the highest revenue, while Environmental Monitoring provides consistent, regulation-driven demand.
Technology:
The maturity curve of analytical technologies influences their adoption rates and precision capabilities across diverse geochemical applications.
- Inductively Coupled Plasma:ICP techniques (ICP-OES, ICP-MS) offer ultra-trace elemental detection with parts-per-billion precision. Demand is strong in critical mineral exploration and environmental forensics, where high sensitivity is paramount for identifying low-grade deposits or pollutant sources.
- Mass Spectrometry:This advanced technique provides isotopic analysis and elemental fingerprinting, enabling precise source identification for contaminants and complex geological mapping. Demand expands in specialized environmental forensics and academic research, particularly for distinguishing pollution sources.
- X-Ray Fluorescence:Portable XRF (pXRF) provides rapid, non-destructive elemental analysis in the field for immediate decision-making in exploration and environmental screening.
- Atomic Absorption Spectroscopy:AAS measures the concentration of specific metallic elements in samples, offering a cost-effective method for routine analysis in environmental laboratories.
- Chromatography:This separation technique analyzes organic compounds and specific ions in water and soil, crucial for detecting pesticides and environmental contaminants.
Inductively Coupled Plasma techniques dominate precision analysis, with Mass Spectrometry expanding capabilities for complex elemental matrices.
Client Type:
Demand concentration from various client types influences the scale and specialization of geochemical service providers.
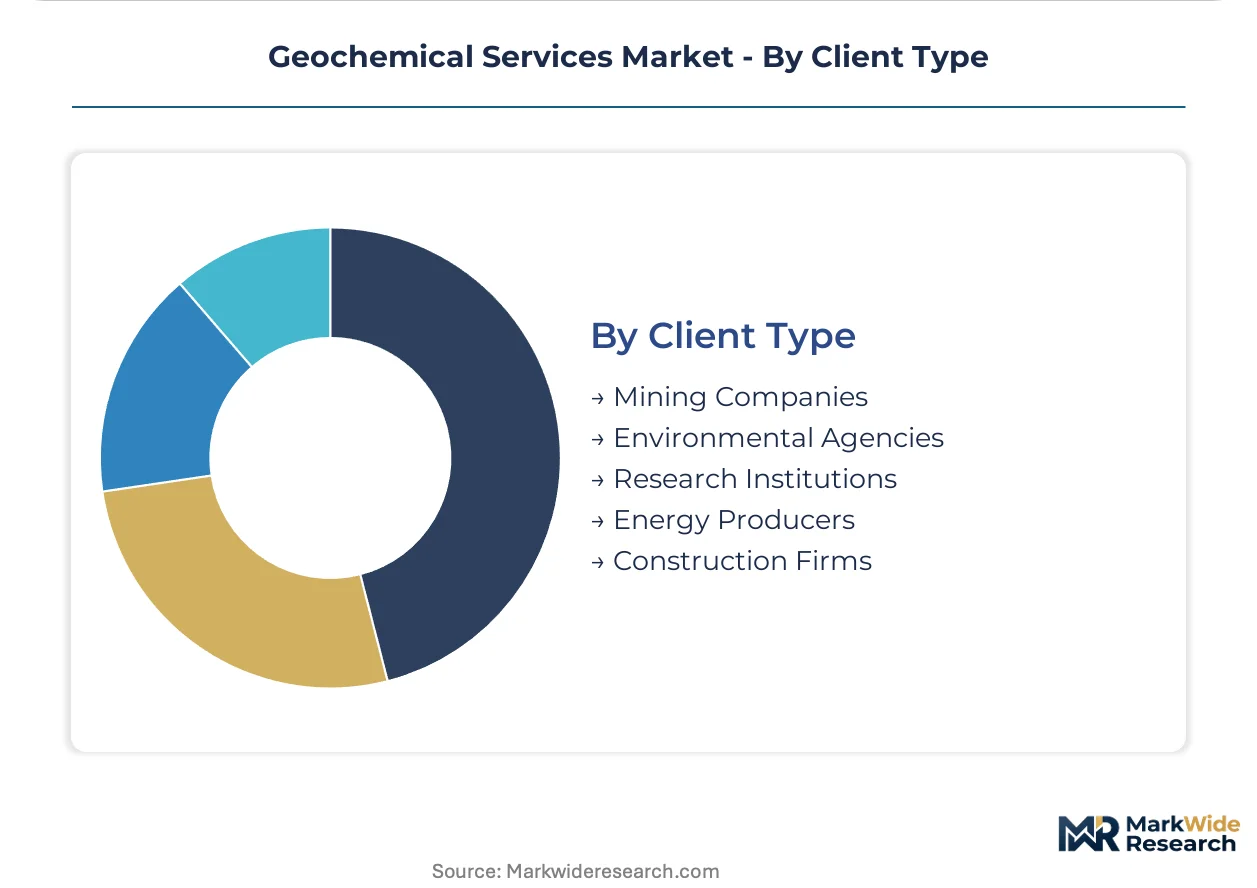
- Mining Companies:These clients require extensive geochemical surveys for mineral exploration, resource definition, and operational environmental monitoring. Demand is particularly high in established mining regions like Canada and Australia, driven by continuous search for new deposits and compliance with national mining codes.
- Environmental Agencies:Government bodies and regulatory authorities utilize geochemical services for soil and water quality testing, pollution source identification, and compliance verification. Demand is consistent across developed economies, underpinned by stringent regulations from entities such as the US EPA and the EU's environmental directives.
- Research Institutions:Universities and scientific organizations employ geochemical services for academic studies, geological mapping, and new analytical methodology development.
- Energy Producers:Oil and gas companies use geochemical analysis for exploration, reservoir characterization, and environmental impact assessments.
- Construction Firms:These clients require soil and groundwater analysis for site assessment, contamination screening, and compliance with environmental regulations.
Mining Companies represent the largest client segment, driving demand for exploration services, while Environmental Agencies ensure consistent regulatory compliance testing.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The global energy transition creates a significant imbalance in critical mineral supply and demand. Resource-rich nations like Australia and Canada are intensifying exploration to meet this global need. This drives substantial demand for geochemical services to identify and delineate new deposits effectively.
Australia
Demand for geochemical services in Australia centers on critical mineral exploration. National mining codes require extensive geochemical surveys for new permits. Major mining regions like Western Australia are experiencing increased activity in lithium and nickel exploration.
Canada
Canadian mineral exploration for battery metals like cobalt and graphite fuels geochemical service demand. The national Critical Minerals Strategy mandates detailed resource assessment. The Abitibi Greenstone Belt in Quebec and Ontario sees sustained geochemical surveying for new discoveries.
Chile
Geochemical services in Chile are essential for copper and lithium exploration, driven by global electrification. The country's mining legislation requires environmental baseline studies. The Atacama Desert region is a hotspot for extensive geochemical sampling in brine and hard rock deposits.
Sweden
Swedish demand for geochemical services stems from the EU Green Deal's push for domestic raw materials. The Swedish Geological Survey (SGU) promotes exploration initiatives. Northern Sweden, particularly the Norrbotten region, is a focus for rare earth element and iron ore geochemical surveys.
United States
Environmental monitoring and mineral exploration drive geochemical service demand in the United States. The US EPA mandates stringent soil and water quality testing. The Mountain West states, including Nevada and Arizona, see significant geochemical activity for copper and lithium projects.
Geochemical Services Market Key Industry Players
Concentration sits with large, globally networked analytical firms. These firms leverage extensive accreditation and high-throughput laboratories. Smaller, specialized analytical firms also hold significant market share by focusing on niche techniques. Strategic archetypes include global generalists, regional specialists, and technology-focused niche players. Key competitive moves involve geographic expansion and advanced analytical technology investment.
Within the global generalist tier, SGS SA and Bureau Veritas exemplify providers offering comprehensive geochemical services. These entities operate vast networks of accredited laboratories across numerous jurisdictions. In contrast, Activation Laboratories represents the specialized segment. This firm differentiates through proprietary analytical techniques for specific elements, catering to clients with unique or complex analytical requirements. These companies anchor different ends of the service spectrum, from high-volume standardized testing to bespoke, advanced analyses.
| Leading Market Players |
|---|
| SGS SA |
| Bureau Veritas |
| Intertek Group |
| ALS Limited |
| Fugro |
| Activation Laboratories |
| Schlumberger |
| Chinook Consulting Services |
| Geochemic Ltd. |
Cost & Logistics Intelligence
Typical sample processing lead times, extending to several weeks for complex analyses, directly influence pricing power for high-throughput laboratories and shape client procurement strategies. This lead time variability highlights the logistical complexities inherent in the geochemical services supply chain.
Pricing Analysis
Configured-to-order pricing for advanced isotopic analysis commands a significant premium over standardized elemental determination. The dominant pricing structure blends per-unit transactional fees for routine sample analysis with project-based agreements for complex consulting engagements. Price differentiation stems from the customization level required for specialized techniques and the certification level of accredited laboratories like SGS SA. Pricing softness for high-volume, standardized testing reflects increasing automation, while data interpretation services command higher margins. Research institutions exhibit the highest price sensitivity due to budget constraints, unlike environmental agencies driven by regulatory compliance.
Supply Chain Analysis
Australia and Canada, as major mineral exploration hubs, generate substantial sample volumes requiring processing. The geochemical services supply chain relies heavily on specialized analytical reagents and high-purity gases, such as argon for Inductively Coupled Plasma (ICP) instruments. A significant structural risk involves the complex customs regulations and quarantine protocols for transporting geological samples across international borders. Distribution flows predominantly through a global network of accredited laboratories, exemplified by Bureau Veritas, or through specialized regional analytical hubs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The geochemical services market is experiencing a cyclical recovery, driven by the intensifying global energy transition and the resulting surge in critical mineral exploration.
For Market Incumbents: Shield core market share by investing in next-generation analytical technologies and integrating AI-driven data interpretation platforms. Expand global laboratory networks to service major mining and environmental projects across diverse jurisdictions. This strategy mitigates the threat from smaller, specialized firms with proprietary methodologies. Focus on certification investment, such as ISO 17025, to maintain regulatory compliance advantages.
For New Entrants and Emerging Players: Anchor in high-value, underserved niches like environmental forensics or specialized trace element detection. Target regions with nascent exploration activity or specific applications where existing solutions are inadequate. A strong go-to-market angle involves offering integrated data solutions that combine proprietary analytical techniques with advanced interpretation, providing a comprehensive context for clients.
For Investors and Strategic Acquirers: Carve-out targets emerge from larger environmental consulting firms seeking to divest non-core analytical assets. The long-term viability of this market remains strong, propelled by sustained demand for critical minerals and stringent environmental regulations. Target specialized analytical firms possessing unique intellectual property in advanced characterization techniques or robust data integration capabilities. A signal to watch is increased M&A activity in firms offering AI/ML data integration for geochemical datasets.
| Strategic Initiative | Industry Significance |
|---|---|
| Invest in AI for Data Interpretation | Enhances predictive modeling for mineral targeting and environmental risk assessment. |
| Expand Global Network of Accredited Labs | Services major mining and environmental projects across diverse jurisdictions. |
| Develop Specialized Seafloor Sampling Techniques | Unlocks new exploration frontiers for critical minerals in marine environments. |
| Integrate In-field Analytical Technologies | Provides real-time elemental data for immediate decision-making at sites. |
| Pursue Strategic Partnerships for Data Integration | Combines geochemical data with satellite imagery for powerful predictive models. |
Research Approach
Demand-side practitioners and supply-side operators were both consulted, including mining company geologists, environmental consultants, laboratory directors, and government regulators from agencies like the US EPA. Primary interviews were triangulated with extensive secondary research from national geological surveys such as the Swedish Geological Survey, national mining codes in Australia, and environmental directives like the EU's REACH. This approach ensured a robust bottom-up and top-down validation of market sizing and trends.
The forecast modeling period spans a comprehensive analytical window, integrating various market dynamics. Segmentation dimensions modeled include service type, application, technology, client type, and regional regulatory frameworks. Compound annual growth rates were derived from historical growth trends and projected demand drivers. Key industry-specific forecast inputs included critical mineral demand projections and global energy transition investment forecasts.
Decision-makers should treat outputs as directional under current critical mineral demand and regulatory stability assumptions; material deviation would warrant model refresh. Forecasts reflect a blend of quantitative modeling and qualitative expert insights. Unforeseen shifts in critical mineral policy or rapid technological obsolescence represent key risk factors. Recalibration cycles align with material shifts in named drivers.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Testing Equipment
Global Circular Dichroism (CD) Spectrometers Market
Testing Equipment
Global Ion Chromatography Market
Testing Equipment
PFAS Ultra-Trace Water Analysis Test Instruments Market
Testing Equipment
Gas Calorimeter Market
Testing Equipment
Liquid Chromatography Market
Testing Equipment
Global Trace Metal Analysis Market
Testing Equipment
Global Liquid Process Analyzer Market
Testing Equipment
Global Chromatography Columns Market
Testing Equipment
Carbon Black Content Tester Market
Testing Equipment
Abrasion Tester Market
Testing Equipment
Global Film Thickness Measurement Market
Testing Equipment
Chemical Detector Market
Testing Equipment
Next-Generation Titrators Market
Testing Equipment
Oxidation Stability Analyzer Market
Testing Equipment
Solid Density Tester Market
Testing Equipment
Laboratory Filtration Equipment and Supplies Market