
 Service Analytics Market | 2026-2036
Service Analytics Market Size, Share, and Industry Trends Forecast 2026-2036
Service Analytics Market Analysis
A widening capability gap between hyperscale platform operators and point-solution vendors is redrawing competitive boundaries in service analytics. Microsoft Corporation leverages its Azure data infrastructure to bundle analytics with existing enterprise subscriptions. Oracle Corporation anchors its position through database-to-application integration that locks in service data workflows. SAS Institute differentiates via specialized statistical engines that process high-velocity telemetry streams.
Service analytics encompasses software systems that ingest, process, and visualize operational data from customer support, field service, and IT service management functions, typically employing real-time streaming architectures with sub-second query latency to enable intervention before service degradation affects end users. Cloud-based deployment leads structural momentum as enterprises retire on-premises data centers, while predictive analytics within the solution layer captures the fastest expansion due to its direct linkage with cost-avoidance outcomes. The support segment of service type maintains mature margin pools because renewal contracts carry lower customer acquisition overhead than new consulting engagements.
FDA guidelines on software-as-a-medical-device and HIPAA security rule provisions shape how healthcare end users procure analytics with audit trails and access controls. The EU AI Act introduces conformity obligations for automated decision systems that classify service tickets or route customer complaints, forcing vendors to document algorithmic logic. Stakeholders must weigh regulatory certification timelines against first-mover advantages in vertical-specific predictive models.
Market Dynamics
Cloud migration is compressing deployment cycles while forcing vendors to re-architect for real-time streaming architectures that process telemetry at sub-second latency. Enterprises retiring on-premises data centers demand analytics stacks that integrate with existing SaaS subscriptions without custom engineering.
Growth Catalysts
- GDPR audit mandates:EU enterprises migrating to cloud infrastructure must deploy analytics with documented data lineage and access controls, creating procurement urgency for compliance-ready platforms.
- Predictive maintenance modules:Telecom operators deploy churn-reduction algorithms that flag at-risk accounts before contract expiration, directly linking analytics spend to retention ROI.
- Healthcare telemetry expansion:FDA guidelines on software-as-a-medical-device require audit trails for patient-facing analytics, expanding addressable spend in hospital IT budgets.
Market Restraints
- Algorithmic conformity costs:EU AI Act documentation requirements for automated ticket classification systems add 12-18 month certification timelines that delay vendor revenue recognition.
- Specialized talent scarcity:Real-time streaming architecture expertise concentrates in cloud-native engineering hubs, inflating implementation costs for enterprise buyers outside technology clusters.
- Legacy system entanglement:Oracle database-to-application integration locks service data workflows, raising switching costs that slow competitive displacement.
Strategic Opportunities
- Field service unification:Industrial equipment manufacturers in Germany seek platforms that correlate sensor telemetry with technician dispatch records, creating white space for vertical-specific modules.
- API-first distribution:Embedded analytics via marketplace integrations allows vendors to capture spend within existing procurement workflows rather than standalone RFP processes.
- HIPAA-aligned healthcare expansion:Security rule provisions for access controls create tailwinds for vendors that pre-certify audit-ready stacks for hospital procurement committees.
Industry Challenges
- Multi-cloud integration complexity:Enterprises operating across Azure, AWS, and private infrastructure demand consistent query performance, forcing vendors to maintain parallel optimization paths.
- Statistical engine specialization:High-velocity telemetry processing requires rare expertise in streaming algorithms, constraining vendor scaling and inflating support costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Service Analytics Market |
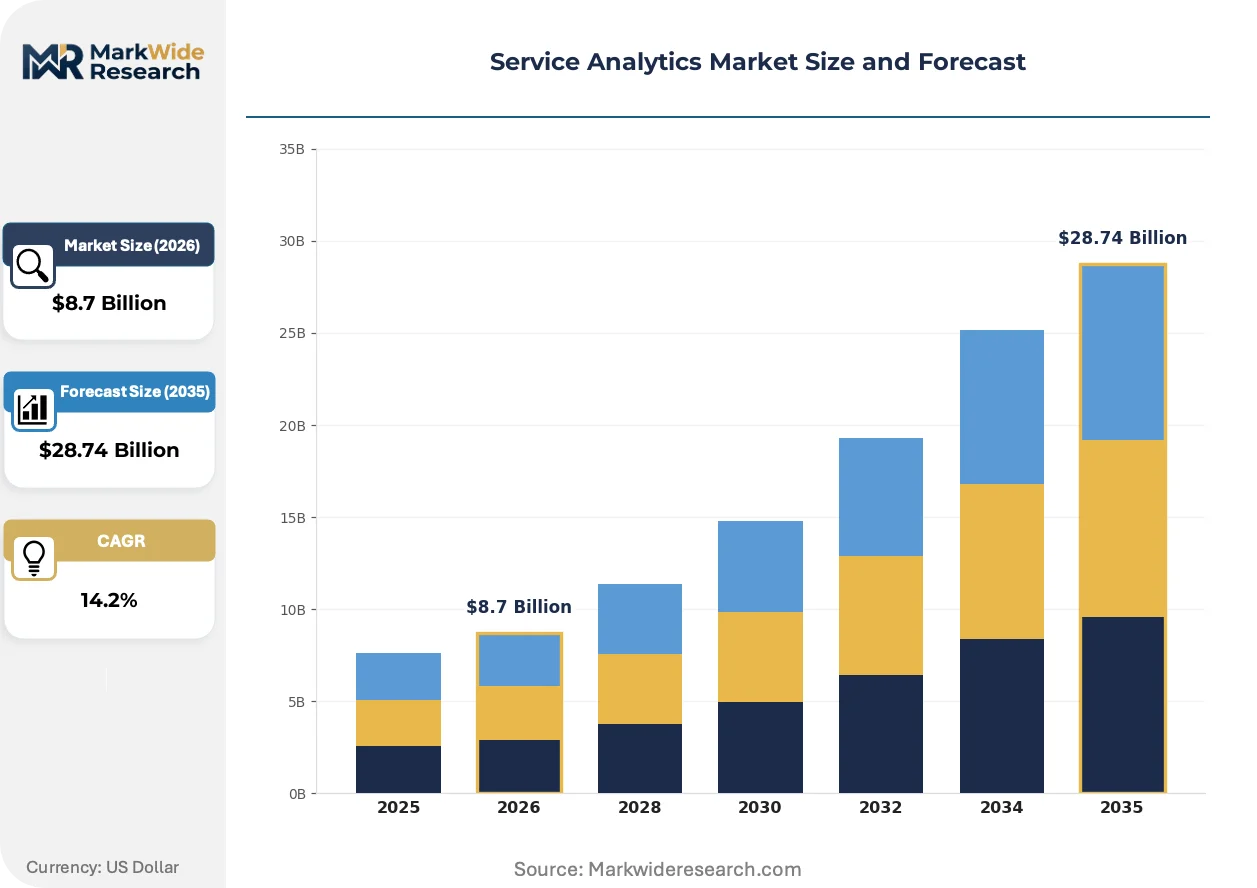
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $28.74 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: On-Premises, Cloud-Based, Hybrid, SaaS Service Type: Consulting, Integration, Support, Maintenance End User: Retail, Telecommunications, Healthcare, BFSI Solution: Reporting, Performance Management, Predictive Analytics, Dashboards |
| Companies Covered | Microsoft Corporation, Oracle Corporation, SAP SE, Salesforce, ServiceNow, IBM Corporation, Cloudera, SAS Institute, Adobe, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Service Analytics Market Emerging Trajectories
Real-time streaming architectures are compressing the window between data ingestion and actionable insight, enabling intervention before service degradation affects end users. This shift demands fundamental re-engineering of query engines and storage layers.
Edge-deployed inference engines are supplanting centralized cloud processing for latency-sensitive use cases. Manufacturing facilities in Japan deploy on-premise nodes that classify equipment anomalies without round-trip data transmission. This topology is compressing vendor margins by reducing cloud compute attach rates while raising hardware certification burdens.
EU AI Act conformity obligations for automated decision systems now require documented algorithmic logic for service ticket routing and complaint classification. Vendors serving European enterprises must maintain technical documentation that traces model training data through deployment. Healthcare and financial services verticals face the steepest compliance ramps as they operate under overlapping sector-specific frameworks.
Subscription bundling now dominates enterprise procurement, with buyers expecting analytics capabilities embedded within existing SaaS relationships rather than procured through separate vendor evaluations. IT departments in United States enterprises prioritize platforms that activate through existing identity providers and data lakes. This pattern concentrates purchasing authority within platform ecosystem owners and marginalizes standalone point solutions.
Service Analytics Market Segmentation
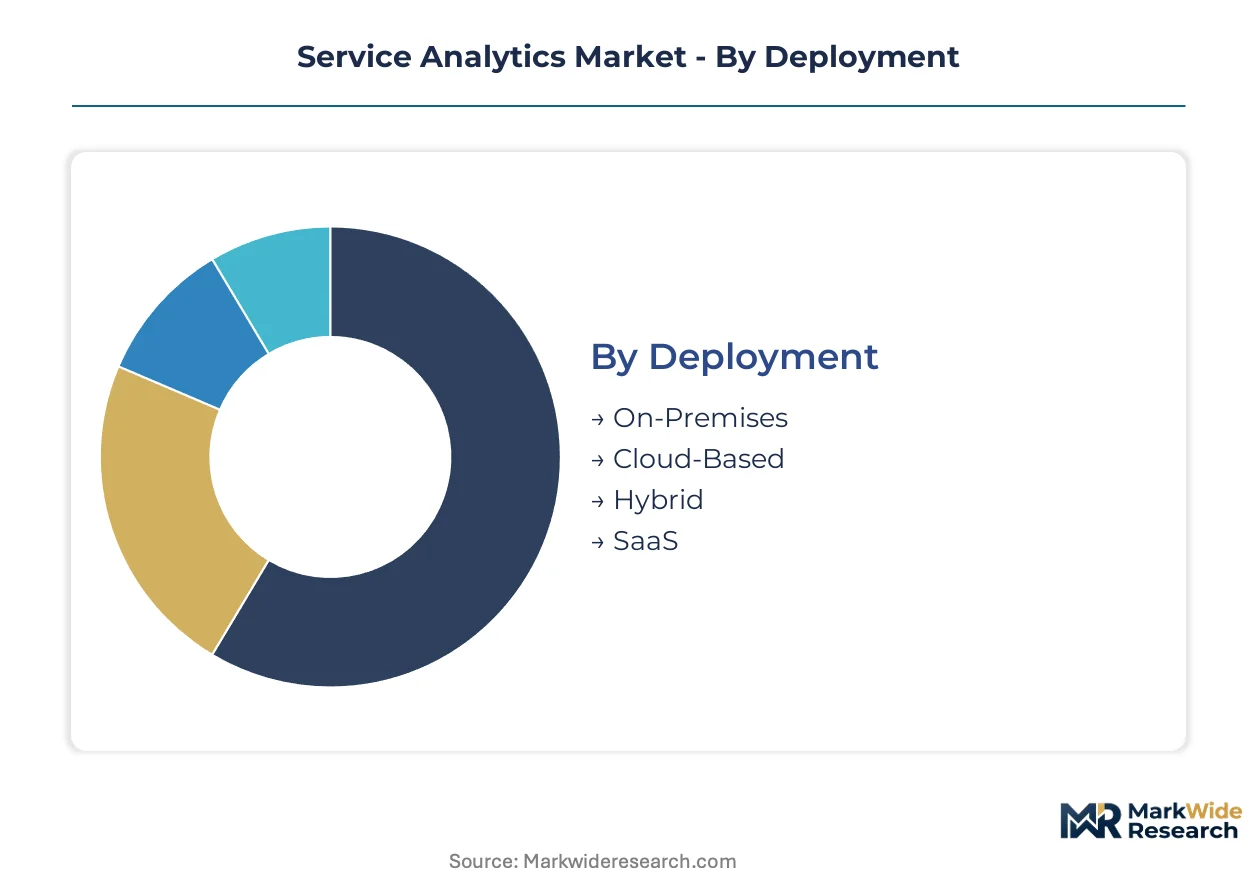
Deployment models and solution architectures in service analytics carry distinct regulatory footprints across jurisdictions. End-user verticals impose specialized compliance requirements that reshape platform specifications and procurement timelines.
Deployment:
Cloud-based configurations dominate cross-border enterprise rollouts, while on-premises installations persist in data-sovereignty-sensitive sectors.
- Cloud-Based:Multi-tenant architectures with auto-scaling compute pools enable sub-second query latency for real-time telemetry streams. Financial services firms in Singapore and healthcare networks in Germany deploy these configurations to satisfy GDPR and HIPAA audit mandates without capital-intensive infrastructure builds.
- SaaS:Subscription-native delivery embeds analytics within existing procurement workflows, reducing standalone RFP cycles. United States enterprises prioritize identity provider integration and pre-built connectors to data lakes.
- On-Premises:Air-gapped installations serve defense contractors and classified government facilities requiring physical data control.
- Hybrid:Split architectures process sensitive workloads locally while bursting analytics compute to public cloud during peak demand.
Cloud-based deployments anchor the installed base. SaaS delivery is climbing the fastest as procurement committees favor bundled subscription economics.
Service Type:
Margin profiles diverge sharply between high-touch consulting engagements and automated support renewals.
- Support:Renewal contracts carry lower customer acquisition overhead than new consulting engagements, sustaining mature margin pools. Telecom operators in South Korea and retail chains in Australia prioritize 24/7 incident response with guaranteed mean-time-to-resolution clauses.
- Consulting:Custom implementation projects demand specialized talent in streaming architecture and statistical engine configuration. European system integrators command premium day rates for EU AI Act documentation and algorithmic conformity assessments.
- Integration:API-first deployment connects analytics stacks to existing SaaS subscriptions without custom engineering.
- Maintenance:Patch management and version upgrades ensure audit-ready platform states for regulated verticals.
Support services command the established revenue base. Consulting engagements are expanding most quickly as compliance complexity drives demand for specialized implementation expertise.
End User:
Vertical-specific regulatory frameworks reshape platform requirements and certification timelines.
- Healthcare:FDA software-as-a-medical-device guidelines and HIPAA security rule provisions mandate audit trails and access controls. Hospital procurement committees in the United States pre-certify vendors with documented data lineage capabilities.
- Telecommunications:Predictive maintenance modules reduce subscriber churn by flagging at-risk accounts before contract expiration. Operators in Japan and Germany deploy these algorithms with direct linkage to retention ROI metrics.
- BFSI:Real-time fraud detection and transaction monitoring demand sub-second latency with explainable model outputs for regulatory examination.
- Retail:Customer journey analytics correlate digital touchpoints with inventory systems to optimize fulfillment routing.
Healthcare anchors the established base. Telecommunications is gaining share fastest as 5G infrastructure investments expand addressable telemetry volumes.
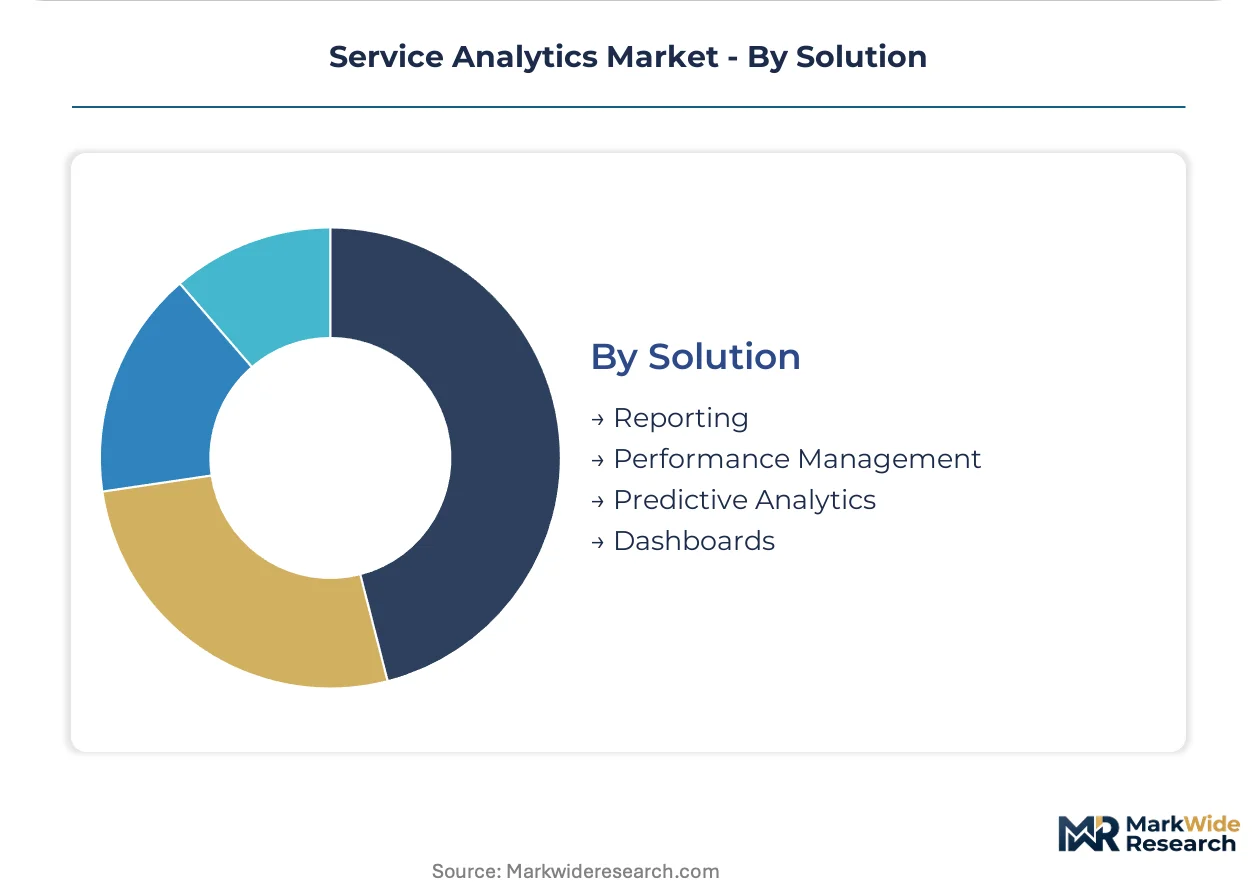
Solution:
Functional modules compete for budget allocation based on time-to-value and measurable cost avoidance.
- Predictive Analytics:Machine learning pipelines process high-velocity telemetry streams to forecast equipment failures and service degradation. Manufacturing facilities in Japan deploy edge-deployed inference engines that classify anomalies without round-trip cloud transmission.
- Performance Management:Real-time dashboards track service level agreement compliance with automated escalation triggers. Cloud migration across the EU triggers investments in these modules as enterprises retire on-premises monitoring tools.
- Reporting:Scheduled and ad-hoc query tools satisfy audit documentation requirements with exportable data lineage.
- Dashboards:Visualization layers aggregate multi-source metrics for executive consumption and operational drill-down.
Performance Management commands the established base. Predictive Analytics is expanding most quickly due to its direct linkage with cost-avoidance outcomes and retention ROI.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Service analytics platforms flow toward jurisdictions with stringent data governance and high cloud penetration. The United States runs a substantial surplus in software exports, while Germany and Japan import implementation expertise to bridge compliance gaps.
United States
FDA software-as-a-medical-device guidelines and HIPAA security rule provisions mandate audit trails for hospital procurement committees. Enterprise IT refresh cycles accelerate SaaS transitions, embedding analytics within existing subscriptions. The Boston-Cambridge corridor concentrates healthcare analytics specialists serving hospital networks.
Germany
Industrial equipment manufacturers seek platforms correlating sensor telemetry with technician dispatch records. EU AI Act conformity obligations for automated ticket classification add documentation burdens. The Munich-Stuttgart axis hosts automotive and machinery producers deploying predictive maintenance modules.
Japan
Manufacturing facilities deploy edge-deployed inference engines classifying equipment anomalies without cloud transmission. METI industrial digitization programs subsidize smart factory analytics adoption. The Nagoya-Toyota industrial corridor leads deployment of latency-sensitive telemetry processing.
Singapore
Financial services firms deploy multi-tenant architectures with auto-scaling compute pools for sub-second fraud detection latency. The Monetary Authority of Singapore mandates explainable model outputs for algorithmic trading surveillance. The Marina Bay financial district anchors regional headquarters for analytics vendors serving Southeast Asian banks.
United Kingdom
Telecom operators deploy churn-reduction algorithms flagging at-risk accounts before contract expiration. The Information Commissioner's Office enforces GDPR-aligned data lineage requirements for cloud migrations. London's Canary Wharf cluster houses BFSI analytics teams prioritizing real-time transaction monitoring.
Service Analytics Market Vendor Landscape
Concentration sits with hyperscale platform operators bundling analytics within existing enterprise subscriptions. The vendor base separates into three tiers: cloud-native ecosystems, database-anchored incumbents, and specialized statistical engine providers. Consolidation pressure intensifies as procurement committees favor bundled economics over standalone evaluations. Dominant competitive moves include API-first distribution partnerships and vertical-specific module development.
Among database-anchored incumbents, Oracle Corporation exemplifies workflow lock-in through deep application integration. Microsoft Corporation occupies a position within the cloud-native ecosystem tier, leveraging infrastructure breadth. SAS Institute represents the specialized statistical engine archetype, serving high-velocity telemetry use cases where streaming algorithm expertise commands premium positioning.
| Leading Market Players |
|---|
| Microsoft Corporation |
| Oracle Corporation |
| SAP SE |
| Salesforce |
| ServiceNow |
| IBM Corporation |
| Cloudera |
| SAS Institute |
| Adobe |
| Others |
Supply Flow & Price Mechanics
Cloud infrastructure substitution for on-premises data centers simultaneously redistributes supply geography toward hyperscale regions and compresses pricing economics through subscription bundling. Industrial OEM buyers anchor tiered pricing structures across premium, standard, and economy levels, with differentiation driven by HIPAA certification tiers and vertical-specific customization depth. Cost compression in the standard tier is intensifying because EU AI Act documentation requirements extend vendor delivery timelines without commensurate price premiums. Healthcare procurement committees exhibit the lowest price sensitivity due to audit trail mandates, while mid-market retailers demonstrate acute sensitivity to per-seat licensing costs.
Pricing Analysis
Industrial OEM buyers anchor three-tier pricing structures across premium, standard, and economy levels, with differentiation driven by HIPAA certification tiers and vertical-specific customization depth. Cost compression in the standard tier is intensifying because EU AI Act documentation requirements extend vendor delivery timelines without commensurate price premiums. Healthcare procurement committees exhibit the lowest price sensitivity due to audit trail mandates, while mid-market retailers demonstrate acute sensitivity to per-seat licensing costs.
Supply Chain Analysis
Cloud region concentration in the United States, Germany, and Singapore underwrites latency-sensitive service delivery for real-time telemetry processing. Software development draws from open-source streaming frameworks, proprietary statistical engines, and certified compliance documentation layers. Single-source vulnerability concentrates in hyperscale infrastructure providers, with tariff exposure minimal but regulatory restriction risk elevated across EU data sovereignty requirements. Distribution runs through API-first marketplace integrations and direct enterprise sales channels serving hospital networks and telecom operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Service analytics sits at an early-cycle expansion phase that favors vendors with pre-certified compliance stacks, as GDPR audit mandates and FDA software-as-a-medical-device guidelines accelerate procurement urgency for documented data lineage capabilities.
For Market Incumbents: Shield installed base relationships through deeper database-to-application integration that elevates switching costs for enterprise buyers. Prioritize EU AI Act certification investment ahead of competitor timelines to capture compliance-driven replacement cycles in European healthcare and financial services verticals. Channel control through existing identity provider partnerships reinforces contract renewal rates against emerging API-first entrants. For New Entrants and Emerging Players: Field service unification for German industrial equipment manufacturers represents an under-served white space where incumbent platforms lack vertical-specific sensor-to-dispatch correlation modules. Embedded analytics via marketplace integrations offers the most penetrable go-to-market angle, capturing procurement spend within existing SaaS workflows rather than standalone RFP processes. Target mid-market telecommunications operators in Southeast Asia with churn-reduction algorithms priced on retention-outcome metrics. For Investors and Strategic Acquirers: The market sits at a platform consolidation phase that favors acquirers with vertical certification expertise and hyperscale infrastructure access. Long-term viability over the next decade hinges on regulatory moats rather than feature differentiation, positioning specialized statistical engine providers as attractive targets. Watch FDA software-as-a-medical-device submission volumes as an inflection indicator for healthcare analytics adoption acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Microsoft Azure data infrastructure bundles analytics with existing enterprise subscriptions, concentrating purchasing authority. |
| Vertical Module Development | German automotive producers deploy predictive maintenance modules correlating sensor telemetry with technician dispatch records. |
| Regulatory Certification Investment | EU AI Act documentation requirements add 12-18 month timelines that pre-certified vendors exploit for competitive displacement. |
| API-First Distribution | Embedded marketplace integrations capture spend within existing procurement workflows rather than standalone RFP processes. |
| Acquisition of Specialist Firm | SAS Institute's streaming algorithm expertise commands premium positioning in high-velocity telemetry processing segments. |
Methodological Framework
Findings reconcile primary fieldwork against secondary review of SEC filings, hyperscaler capex disclosures, and EU regulatory databases. Interviews with CTOs, IT procurement officers, platform engineers, and integration specialists informed demand-side assumptions. Bottom-up triangulation across deployment model adoption curves and top-down validation against enterprise SaaS spend aggregates anchored value estimates.
Segmentation dimensions modeled span cloud-based, SaaS, on-premises, and hybrid deployment configurations; support, consulting, integration, and maintenance service types; healthcare, telecommunications, BFSI, and retail end-user verticals; and predictive analytics, performance management, reporting, and dashboard solution modules. CAGRs were derived from elasticity-adjusted adoption curves across the projection horizon, with telemetry volume expansion from 5G infrastructure investments and edge-deployed inference engine penetration serving as industry-specific forecast inputs.
Underlying assumptions cover sustained cloud migration momentum and regulatory certification timeline stability, with deviation risk concentrated in EU AI Act enforcement intensity and healthcare procurement committee budget prioritization shifts. Practitioners should keep alternative scenarios live as GDPR audit mandate scope and FDA software-as-a-medical-device guideline interpretations evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Analytics
Hadoop Big Data Analytics Solution Market
Analytics
Data Mining Tools Market
Analytics
Text Analytics Market
Analytics
Embedded Business Intelligence Market
Analytics
Embedded Analytics Market
Analytics
FMCG Spending on Analytics Market
Analytics
Global Telecom Analytics Market
Analytics
Sales Intelligence Market
Analytics
Data Analytics Outsourcing Market
Analytics
Global Web Analytics Software Market
Analytics
Italy ICT Market
Analytics
Global Hadoop Big Data Analytics Market
Analytics
Global Recommendation Engine Market
Analytics
Global in-Memory Analytics Market
Analytics
Assortment Analytics Market
Analytics
Global Business Intelligence and Analytics Market