
 Mariculture Market | 2026-2036
Mariculture Market Size, Share, and Industry Trends Forecast 2026-2036
Mariculture Market Foresight
The capital-intensity gap between integrated offshore operators and coastal cage farmers is collapsing as recirculating aquaculture system costs decline. Mowi ASA leverages its Norwegian breeding program and full value-chain control to sustain margin capture across Atlantic salmon markets. Cooke Aquaculture anchors North American supply through vertically integrated hatchery-to-processing operations in Canada and the United States. Thai Union competes on scale, using its Bangkok-based seafood trading infrastructure to dominate Asia-Pacific distribution channels for farmed species.
Mariculture denotes the cultivation of marine organisms in seawater environments, encompassing finfish raised in submerged cages, shellfish grown on suspended longlines, and seaweed propagated on offshore ropes with salinity tolerance thresholds typically between 28 and 35 parts per thousand. Its primary purpose centers on producing protein and biomass for human consumption, industrial extracts, and coastal ecosystem services. Finfish commands the largest revenue pool given salmonid premium pricing, while seaweed represents the fastest-expanding category as carrageenan and alginate demand from food processors accelerates. Offshore systems attract capital inflows due to lower disease pressure and higher carrying capacity compared to nearshore cage configurations.
Norway's Food Safety Authority and the EU's Aquaculture Regulation shape product standards for farmed seafood entering European retail channels, with ESG disclosure rules under CSRD now requiring large operators to report marine feed sourcing and antibiotic usage. The US FDA and NOAA enforce HACCP protocols and marine spatial planning restrictions that limit new site approvals in federal waters. Stakeholders must monitor how evolving marine protected area designations interact with lease expansion timelines and feed ingredient certification schemes.
Market Dynamics
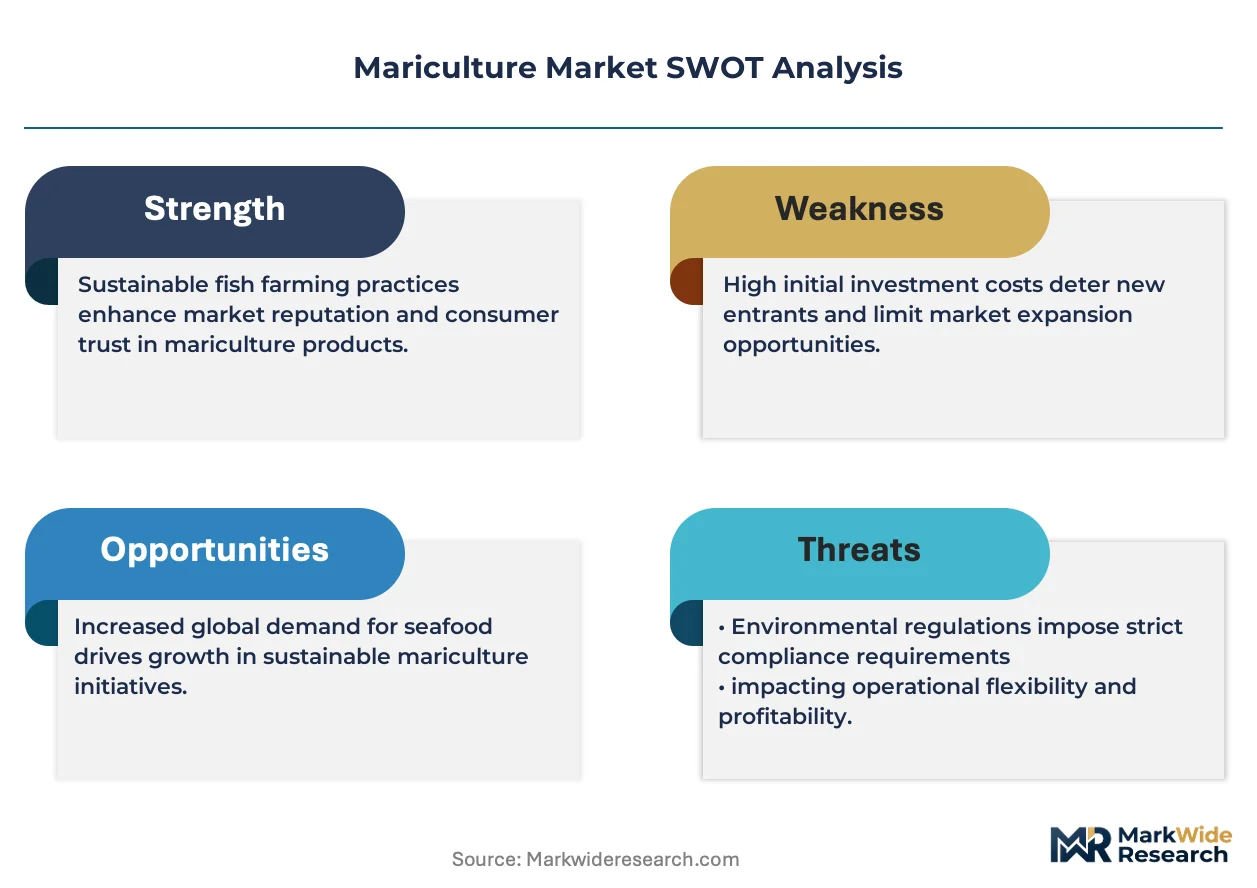
Offshore cage system deployment is decomposing the traditional nearshore production model as Norwegian lease approvals accelerate and capital flows toward deeper-water infrastructure with lower disease transmission risk.
Growth Catalysts
- EU CSRD disclosure mandates:Large operators must now report marine feed sourcing and antibiotic usage, creating competitive separation for certified sustainable producers entering European retail channels.
- Recirculating aquaculture system cost compression:Hardware and energy efficiency gains are collapsing the capital-intensity gap between integrated offshore operators and coastal cage farmers.
- China coastal province expansion:Integrated multi-trophic aquaculture operations in Fujian and Shandong are scaling premium shellfish and finfish output for domestic and export markets.
Market Restraints
- Marine ingredient supply concentration:Fishmeal and fish oil procurement depends on Peruvian and Chilean anchovy harvest quotas subject to El Niño volatility.
- US federal water access restrictions:NOAA marine spatial planning and FDA HACCP protocols limit new site approvals in federal waters off California and the Gulf Coast.
- Nearshore carrying capacity ceilings:Coastal eutrophication and benthic impact thresholds constrain expansion in sheltered Norwegian fjords and Scottish sea lochs.
Strategic Opportunities
- Seaweed biorefinery feedstock demand:Carrageenan and alginate processors are contracting dedicated offshore rope cultivation for food stabilizer and cosmetic extract supply.
- Indian Ocean rim underpenetration:Madagascar and Mozambique offer extensive suitable coastline with limited incumbent infrastructure for industrial-scale cage development.
- Feed ingredient certification tailwinds:Aquaculture Stewardship Council and GlobalGAP standards are creating price premiums for certified producers in German and Dutch retail.
Industry Challenges
- Offshore operations talent scarcity:Remote site technicians with combined marine engineering and biological husbandry skills command premium compensation and retention costs.
- Multi-jurisdictional lease complexity:Operators spanning Norwegian, Scottish, and Canadian waters face fragmented regulatory timelines for environmental impact assessments and stocking permits.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mariculture Market |
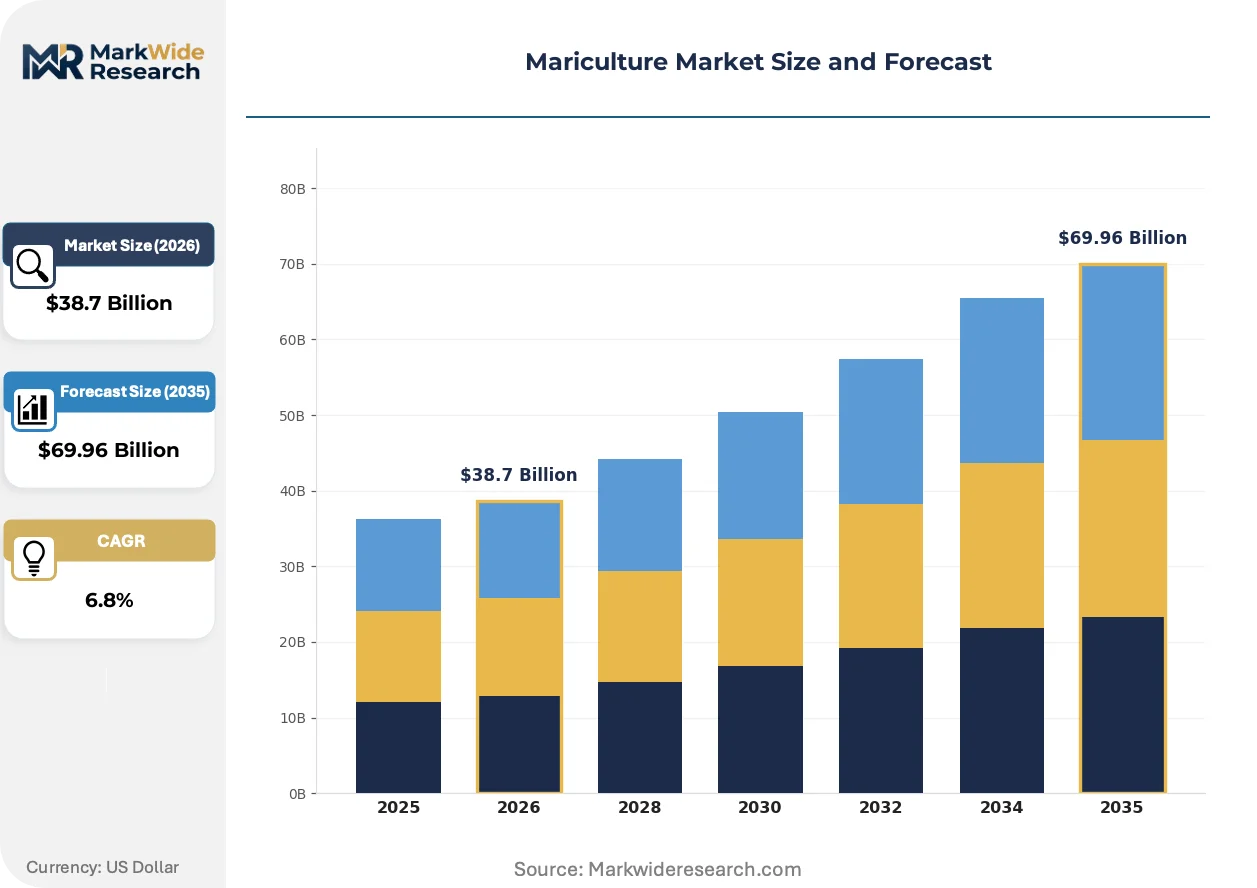
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $69.96 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Shellfish, Finfish, Seaweed, Mollusks Technology: Recirculating Aquaculture Systems, Offshore Systems, Integrated Multi-Trophic Aquaculture, Cage Aquaculture End User: Food Processing, Retail, Restaurants, Seafood Exporters Distribution Channel: Direct Sales, Online Sales, Wholesale, Supermarkets |
| Companies Covered | Mowi ASA, Cooke Aquaculture Inc., Cermaq Group AS, Thai Union Group PCL, SalMar ASA, Lerøy Seafood Group ASA, Tassal Group Ltd., Maruha Nichiro Corporation, Huon Aquaculture Group Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mariculture Market Shifts & Advancements
Biological monitoring systems and alternative protein feed formulations are actively restructuring production economics and environmental compliance obligations across marine farming operations.
Sensor-integrated feeding platforms are decomposing the manual distribution model that has dominated Atlantic salmon farming for decades. Norwegian and Scottish producers are deploying camera-guided pellet dispensers that adjust rationing based on real-time appetite detection. This technology is decomposing feed conversion ratio variance and labor dependency while compressing operational expenditure structures at offshore sites.
CSRD sustainability reporting rules are mandating granular disclosure of marine ingredient provenance and veterinary treatment records for all farmed seafood sold through EU retail channels. Large operators must now audit and document feed supply chains back to fishery source. Norwegian exporters with established traceability systems are capturing shelf space as German and French supermarkets enforce compliance deadlines.
Certification-driven procurement is restructuring buyer-supplier contracting across European foodservice and retail channels. Restaurant chains and supermarket private labels are requiring Aquaculture Stewardship Council or GlobalGAP certification as a condition of volume contracts, displacing uncertified product from mid-market positioning. Dutch and Belgian distributors report the tightest certification compliance timelines as procurement teams consolidate supplier panels ahead of 2025 sourcing renewals.
Mariculture Market Segmentation
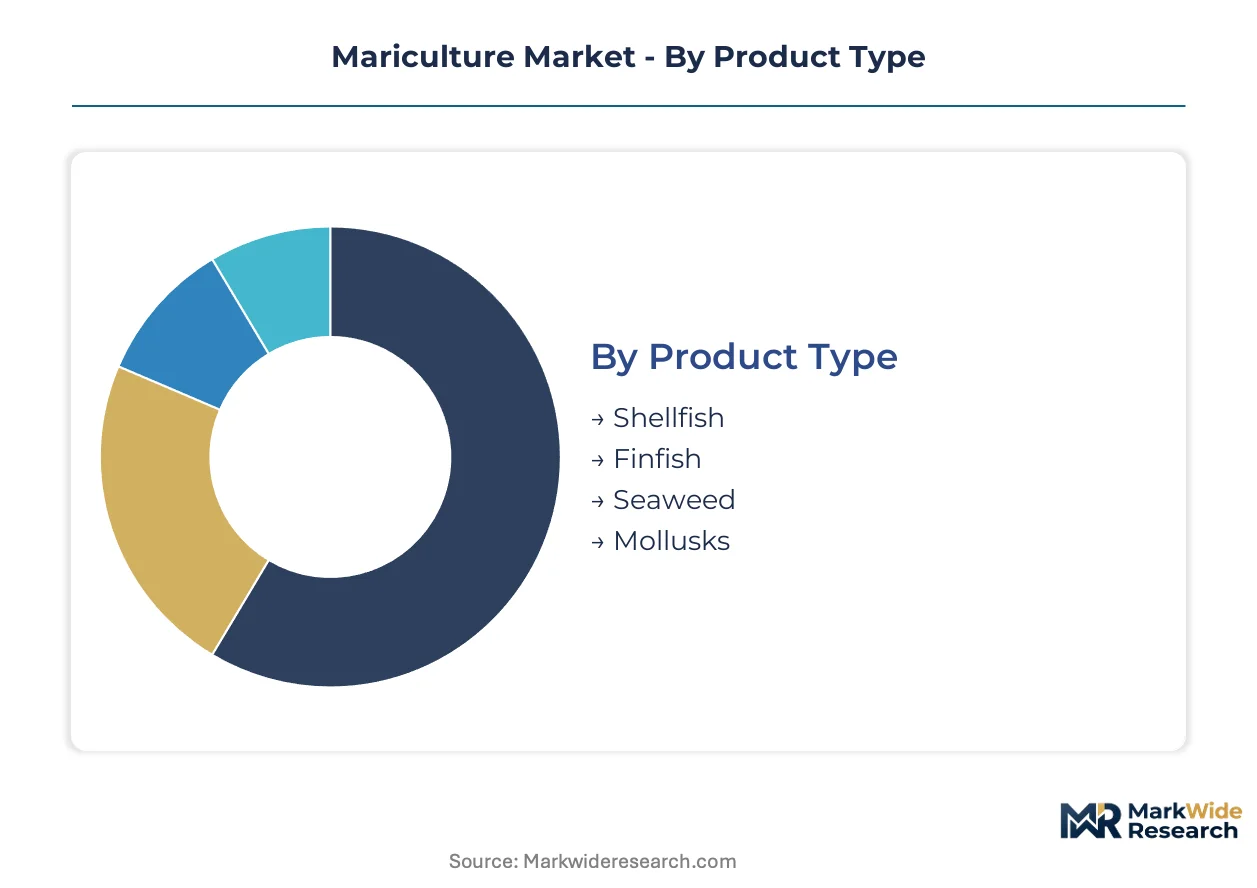
Mariculture segmentation reveals how production technology, species selection, and channel strategy determine margin capture and geographic reach. Understanding these divisions exposes where capital flows concentrate and which configurations face regulatory or biological constraints.
Product Type:
Finfish dominates export-led procurement while shellfish and seaweed serve more localized demand patterns with distinct certification requirements.
- Finfish:Salmonids and other marine finfish require controlled temperature regimes and high-protein feed formulations. Norwegian and Scottish producers command premium export channels into German and French retail, constrained by CSRD traceability mandates and marine ingredient sourcing audits.
- Seaweed:Kelp and macroalgae cultivation deploys offshore rope systems with minimal input costs. Carrageenan and alginate processors in Ireland and France are contracting dedicated supply for food stabilizer and cosmetic extract production.
- Shellfish:Oysters and mussels filter-feed on natural plankton, reducing operational expenditure.
- Mollusks:Abalone and sea cucumber operations target East Asian luxury markets.
Finfish commands the established base. The steepest expansion runs through seaweed biorefinery feedstock contracting.
Technology:
Capital deployment splits between closed-loop precision systems and open-water infrastructure, with cost trajectories diverging sharply.
- Offshore Systems:Submersible cages and deep-water platforms operate beyond coastal disease transmission zones. Norwegian lease approvals for exposed sites are accelerating as operators seek carrying capacity beyond fjord limits.
- Recirculating Aquaculture Systems:Land-based closed-loop facilities control water chemistry and waste streams completely. RAS hardware costs are compressing through energy recovery and automation, eroding the capital gap with cage operations.
- Cage Aquaculture:Nearshore net pens remain the volume backbone in sheltered Scottish and Canadian waters.
- Integrated Multi-Trophic Aquaculture:Co-cultivation of finfish, shellfish, and seaweed recycles nutrients across trophic levels.
Offshore systems attract the largest capital commitments. RAS is climbing the fastest as cost curves shift.
End User:
Channel concentration determines certification burden and price realization, with foodservice and retail imposing diverging compliance standards.
- Seafood Exporters:Consolidated traders manage cold-chain logistics from production origin to destination market. Thai Union and comparable operators leverage Bangkok and Singapore infrastructure to aggregate farmed supply across Asia-Pacific.
- Retail:Supermarket private labels and branded programs enforce Aquaculture Stewardship Council certification as a contract condition. Dutch and Belgian distributors maintain the tightest compliance timelines ahead of sourcing renewals.
- Restaurants:Foodservice procurement prioritizes consistent sizing and supply reliability.
- Food Processing:Industrial buyers contract for standardized raw material inputs.
Seafood exporters command the established base. The steepest expansion runs through retail certification-driven procurement restructuring.
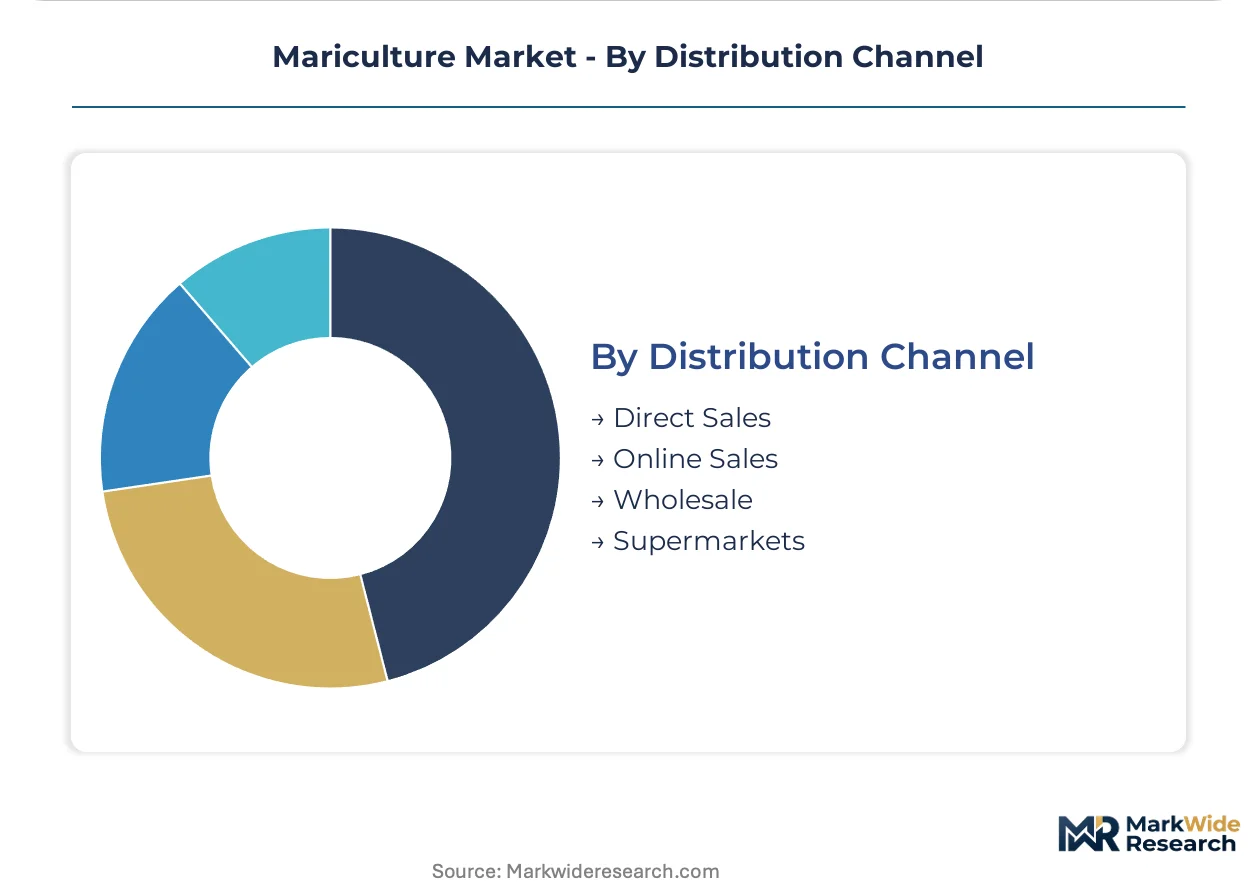
Distribution Channel:
Channel selection reflects product perishability, buyer scale, and the regulatory documentation burden for cross-border movement.
- Wholesale:Aggregators and traders consolidate harvest from multiple farms for onward sale to processors and retailers. This channel handles the majority of volume in Norway, Scotland, and Chile, with price discovery tied to spot market indices.
- Direct Sales:Large integrated operators contract directly with retail chains and foodservice groups, bypassing intermediary margins. Mowi ASA and Cooke Aquaculture leverage captive processing to serve major European and North American accounts.
- Supermarkets:Controlled atmosphere distribution centers manage fresh counter and packaged seafood logistics.
- Online Sales:E-commerce platforms for frozen and value-added products are gaining traction in urban China and South Korea.
Wholesale commands the established base. The steepest expansion runs through direct sales as vertical integration deepens.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Norwegian producers command premium export pricing into German and French retail channels, while Chinese coastal operations capture volume-driven domestic procurement at compressed margins. This pricing-power asymmetry reflects divergent regulatory burdens and certification requirements across Atlantic and Pacific basin markets.
Norway
Offshore lease approvals for exposed sites are accelerating as operators seek carrying capacity beyond fjord limits. The Norwegian Food Safety Authority enforces strict marine ingredient sourcing audits and antibiotic usage reporting aligned with EU CSRD disclosure mandates. Bergen and Trondheim anchor the Atlantic salmon breeding and processing cluster where Mowi ASA and SalMar ASA maintain integrated hatchery-to-export operations.
China
Fujian and Shandong provinces are scaling integrated multi-trophic aquaculture for premium shellfish and finfish output serving domestic and export markets. The Ministry of Ecology and Environment (MEE) monitors coastal water quality thresholds under national dual carbon goals that shape site licensing decisions. Qingdao and Xiamen host the dominant seaweed rope cultivation and abalone farming concentrations where state-backed provincial development funds channel capital into offshore infrastructure.
United States
NOAA marine spatial planning restrictions limit new site approvals in federal waters off California and the Gulf Coast, constraining industrial-scale expansion. The FDA enforces HACCP protocols for all farmed seafood entering interstate commerce and retail distribution. Maine and Washington State sustain the nearshore Atlantic salmon and shellfish farming clusters where Cooke Aquaculture operates vertically integrated hatchery-to-processing facilities.
Canada
British Columbia and Atlantic Canada maintain sheltered sea loch and coastal bay production for Atlantic salmon and mussel cultivation serving North American and Asian export channels. Health Canada and the Department of Fisheries and Oceans coordinate environmental impact assessments and lease tenure renewals. Newfoundland and New Brunswick host the integrated finfish operations where Cooke Aquaculture anchors supply through captive breeding programs and processing infrastructure.
Japan
Domestic demand for premium marine finfish and luxury mollusk species drives coastal prefecture investment in offshore cage and longline systems. The Ministry of Economy, Trade and Industry (METI) supports aquaculture technology exports and domestic productivity enhancement under regional revitalization frameworks. Nagasaki and Mie prefectures concentrate the amberjack and sea cucumber farming operations where Maruha Nichiro Corporation maintains integrated supply chain presence.
Mariculture Market Competitive Landscape
Concentration sits with integrated Atlantic salmon operators commanding breeding program control and full value-chain capture. The competitive terrain splits between Norwegian offshore leaseholders, North American vertically integrated processors, and Asia-Pacific trading conglomerates. Three archetypes dominate: genetics-led breeders with proprietary strain development, geography-anchored processors with captive hatchery supply, and scale-driven traders aggregating farmed output across multiple origins. M&A activity targets breeding program acquisition and offshore lease portfolio expansion, while strategic partnerships concentrate on feed ingredient certification and retail channel compliance.
Among Norwegian integrated operators, Mowi ASA and SalMar ASA exemplify the genetics-led archetype with full value-chain control from breeding to retail. Cooke Aquaculture anchors the North American processor category through vertically integrated hatchery-to-processing operations spanning Canada and the United States. Thai Union Group PCL occupies the scale-driven trader position, leveraging Bangkok-based seafood trading infrastructure to aggregate farmed supply across Asia-Pacific distribution channels.
| Leading Market Players |
|---|
| Mowi ASA |
| Cooke Aquaculture Inc. |
| Cermaq Group AS |
| Thai Union Group PCL |
| SalMar ASA |
| Lerøy Seafood Group ASA |
| Tassal Group Ltd. |
| Maruha Nichiro Corporation |
| Huon Aquaculture Group Ltd. |
| Others |
Supply & Pricing Matrix
Alternative protein feed formulations displacing marine-derived fishmeal simultaneously redraw procurement geography toward soybean and insect-meal processing hubs while compressing input cost variance across Norwegian and Scottish salmon operations. This substitution dynamic reallocates margin pressure from volatile Peruvian anchovy harvests toward agricultural commodity markets, reshaping how integrated operators negotiate long-term offtake terms with feed suppliers.
Pricing Analysis
The customization-premium spread separates ASC-certified Atlantic salmon contracted to German retail chains from uncertified spot-market volume moving through Bangkok trading houses. Three-tier pricing structure across premium, standard, and economy levels tracks certification grade and traceability depth, with Dutch supermarket private labels commanding the widest spreads. Cost compression in standard-tier cage production is intensifying because RAS hardware efficiencies erode the capital-cost barrier that protected nearshore operators. Seafood exporters exhibit the highest price sensitivity, while integrated Norwegian breeders with captive genetics programs maintain the most pricing power.
Supply Chain Analysis
Inventory lead times for marine ingredient concentrates stretch from Peruvian catch seasons through European compound feed mills to Norwegian offshore cage sites. Supply concentrates in Norway, Scotland, and Chile for Atlantic salmon; China and Indonesia for seaweed extracts; Vietnam and Ecuador for shrimp feed processing. The chain draws from fishmeal and fish oil, soy protein concentrate, and single-cell proteins as core inputs. Single-source vulnerability sits with Peruvian anchovy quotas subject to El Niño disruption. Distribution runs through wholesale aggregators in Bergen, Bangkok, and Singapore before retail channel consolidation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The mariculture sector approaches a platform-economics inflection as sensor-integrated feeding platforms and traceability data layers create interoperability standards that reward ecosystem orchestrators over pure producers.
For Market Incumbents: Consolidate breeding program control and offshore lease portfolios before RAS cost compression democratizes access to precision production. Norwegian operators should acquire Scottish and Canadian hatchery assets to secure genetic exclusivity against emerging land-based competitors. Deepen certification investment to capture German and Dutch retail shelf space as CSRD disclosure mandates harden compliance deadlines.
For New Entrants and Emerging Players: Differentiate on integrated multi-trophic production models that recycle finfish waste through shellfish and seaweed cultivation, capturing sustainability premiums unavailable to monoculture operators. Madagascar and Mozambique offer the most penetrable coastline for industrial-scale cage development with limited incumbent infrastructure. Target direct supply contracts with European biorefinery processors seeking dedicated seaweed feedstock rather than competing in saturated salmon commodity channels.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed mid-cap Scottish salmon farmers lacking offshore lease depth or captive breeding programs. Long-term viability across the analysis window favors operators controlling genetics and exposed-site permits rather than trading-dependent aggregators. Watch feed ingredient certification penetration in German retail as the inflection signal for margin compression among uncertified volume players.
| Strategic Initiative | Industry Significance |
|---|---|
| Offshore Lease Portfolio Expansion | Norwegian Food Safety Authority approvals for exposed sites extend carrying capacity beyond fjord eutrophication limits. |
| Alternative Protein Feed Partnership | Insect-meal and single-cell protein sourcing reduces El Niño exposure in Peruvian anchovy supply chains. |
| ASC Certification Acceleration | Dutch and Belgian distributor compliance timelines displace uncertified product from mid-market positioning. |
| Integrated Multi-Trophic Deployment | Fujian and Shandong provincial funds channel capital into nutrient-recycling operations spanning finfish, shellfish, and seaweed. |
| Sensor-Integrated Platform Rollout | Camera-guided pellet dispensers decompose manual feeding models and compress feed conversion ratios at Norwegian offshore sites. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of regulatory filings, trade flow databases, and industry association harvest statistics. The research combined structured interviews with Norwegian salmon breeding program directors, Asian seafood trading house procurement heads, European retail category buyers, and marine feed compounders with validation against EU CSRD disclosure drafts, NOAA marine spatial planning records, and Chinese provincial aquaculture development fund allocations. Bottom-up site-level capacity assessments triangulated against top-down trade value estimates across the analysis window.
Segmentation dimensions modeled include product type, production technology, end-user channel, and distribution format, with species-specific biological growth parameters and regional regulatory compliance tiers as cross-cutting variables. CAGRs were derived from fitted growth curves applied to disclosed harvest volumes and trade values throughout the forecast period. Industry-specific forecast inputs incorporated fishmeal price volatility indices, offshore lease approval velocity, and certification penetration rates in German retail.
The analysis sits within stated boundaries; outcomes outside sustained Norwegian lease approval momentum, stable Peruvian anchovy harvest quotas, or continued CSRD enforcement would require recalibration. Forecasts reflect documented assumptions about technology cost trajectories and regulatory implementation timelines. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aquaculture Innovations
China Shrimp Market
Aquaculture Innovations
Brazil Fisheries and Aquaculture Market
Aquaculture Innovations
Global Precision Aquaculture Market
Aquaculture Innovations
Asia Pacific Aqua Feed Market
Aquaculture Innovations
Perch Market
Aquaculture Innovations
Global Aquafeed and Aquaculture Additives Market
Aquaculture Innovations
Crab Market
Aquaculture Innovations
GCC Fish Farming Market
Aquaculture Innovations
Salmon Feed Market
Aquaculture Innovations
Thailand Aquafeed Market
Aquaculture Innovations
Fish Breeding Tank Market
Aquaculture Innovations
Ornamental Tropical Fish Feed Market
Aquaculture Innovations
Aquaculture Water Quality and Biomass Monitoring Test Equipment Market
Aquaculture Innovations
Shrimp Feed Market
Aquaculture Innovations
North America Shrimp Feed Market
Aquaculture Innovations
Fish Farming Equipment Market