
 Blockchain AI Market | 2026-2036
Blockchain AI Market Size, Share, and Industry Trends Forecast 2026-2036
Blockchain AI Market Analysis
Multi-source procurement of AI training infrastructure is restructuring how blockchain AI firms secure computational capacity. Bitmain leverages its ASIC manufacturing scale to dominate hardware supply for proof-of-work networks integrated with machine learning pipelines. Nvidia sustains technology leadership in GPU-accelerated consensus mechanisms that underpin enterprise blockchain deployments. Cipher Mining anchors geographic positioning through energy-intensive mining operations co-located with AI model training facilities.
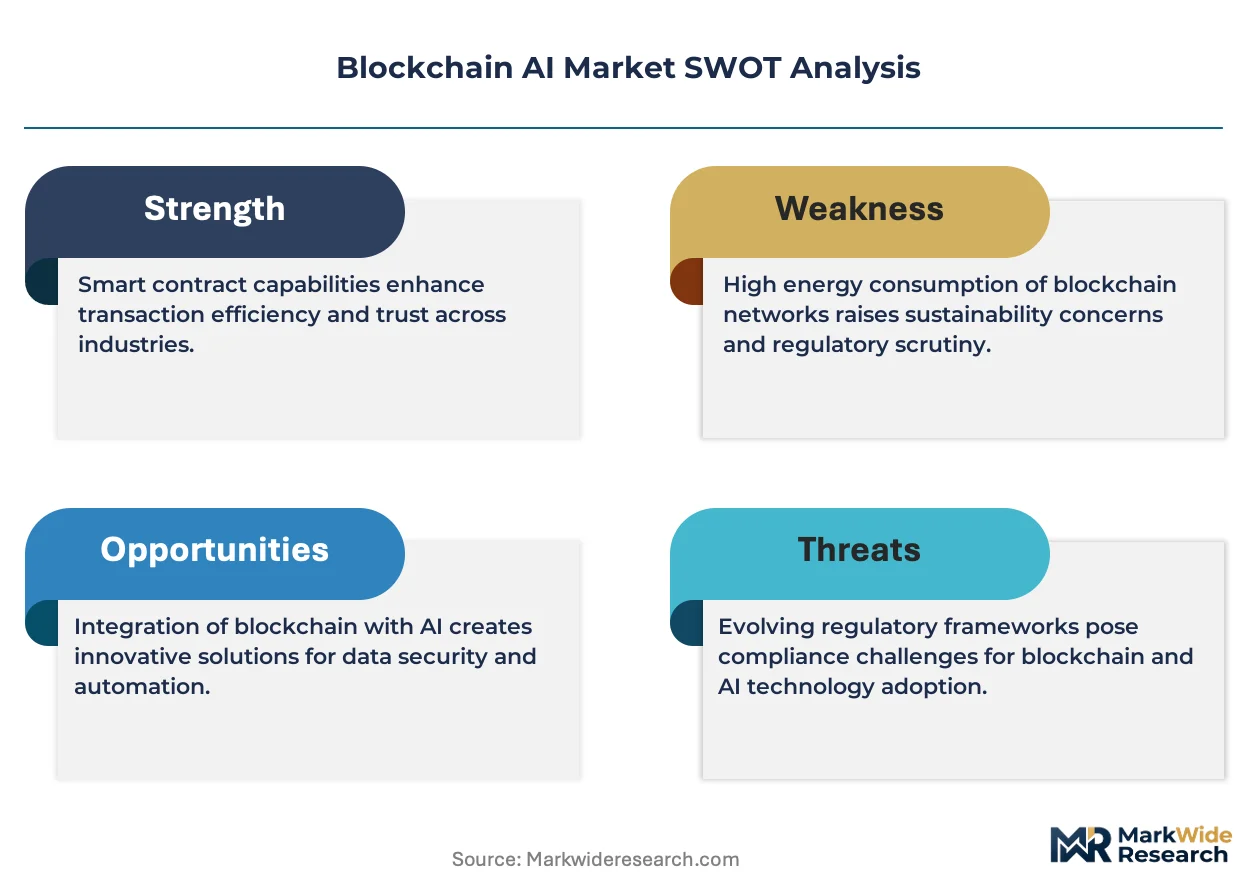
Blockchain AI denotes the convergence of distributed ledger architectures with machine learning algorithms, typically employing cryptographic hashing, zero-knowledge proofs, and federated learning protocols to enable tamper-evident model training and inference across untrusted nodes. Its primary purpose centers on creating verifiable, censorship-resistant AI systems where training data provenance and model outputs remain auditable without centralized intermediaries. Platform and solutions segments occupy the dominant revenue position as enterprises seek pre-integrated stacks rather than bespoke assembly of consensus and inference layers. Smart contract applications attract disproportionate investment growth as self-executing agreements embed machine learning oracles for automated settlement. Public cloud deployment models lead volume while hybrid configurations capture margin pools from regulated industries requiring on-premises data sovereignty with elastic burst capacity.
The EU AI Act imposes conformity assessment requirements on high-risk AI systems, pushing blockchain AI vendors toward decentralized architectures that satisfy explainability mandates without exposing proprietary training data. FDA oversight of AI-enabled medical devices and SEC disclosure rules for algorithmic trading systems further shape product standards and market access conditions across North America and Europe. Stakeholders must monitor evolving liability frameworks that assign accountability between model developers, node operators, and end users in permissionless networks.
Market Dynamics
Financial institutions are driving blockchain AI deployment through algorithmic trading and fraud detection mandates, while the EU AI Act's conformity assessments force vendors toward decentralized architectures that satisfy explainability without exposing proprietary training data.
Growth Catalysts
- EU AI Act compliance mandates:High-risk AI systems require auditable model provenance, accelerating demand for tamper-evident training pipelines using cryptographic hashing and federated learning protocols.
- Algorithmic trading expansion:SEC disclosure rules for automated trading systems push hedge funds and broker-dealers toward smart contract oracles that embed machine learning for real-time settlement verification.
- Zero-knowledge proof maturation:Cryptographic techniques enabling model inference without data exposure are attracting healthcare and defense contractors seeking HIPAA-compliant predictive analytics.
Market Restraints
- GPU supply concentration:Nvidia's dominance in AI-accelerated consensus mechanisms creates bottlenecks for enterprise blockchain deployments requiring specialized hardware.
- Energy cost volatility:Proof-of-work networks integrated with machine learning pipelines face input cost instability from fluctuating electricity tariffs in mining-intensive jurisdictions.
- Regulatory fragmentation:Divergent FDA oversight of AI-enabled medical devices versus SEC algorithmic trading rules forces vendors to maintain multiple compliance architectures.
Strategic Opportunities
- Hybrid cloud penetration:Regulated industries in Germany and France require on-premises data sovereignty with elastic burst capacity, creating margin pools for integrated platform vendors.
- Digital identity verification:Self-sovereign identity systems combining biometric inference with immutable credential storage are gaining traction in government procurement.
- Cross-border data trusts:GDPR Article 46 transfer mechanisms are driving demand for federated learning protocols that train models across jurisdictions without raw data movement.
Industry Challenges
- Cryptographic engineering scarcity:The intersection of distributed systems design and differential privacy implementation requires talent pools concentrated in academic and national laboratory settings.
- Model audit standardization delays:Absence of ISO/IEC standards for blockchain-verified AI training logs forces vendors to negotiate bespoke certification timelines with each enterprise buyer.
- Legacy system integration friction:Mainframe-dependent financial institutions face capex burdens when retrofitting smart contract automation into core banking infrastructure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Blockchain AI Market |
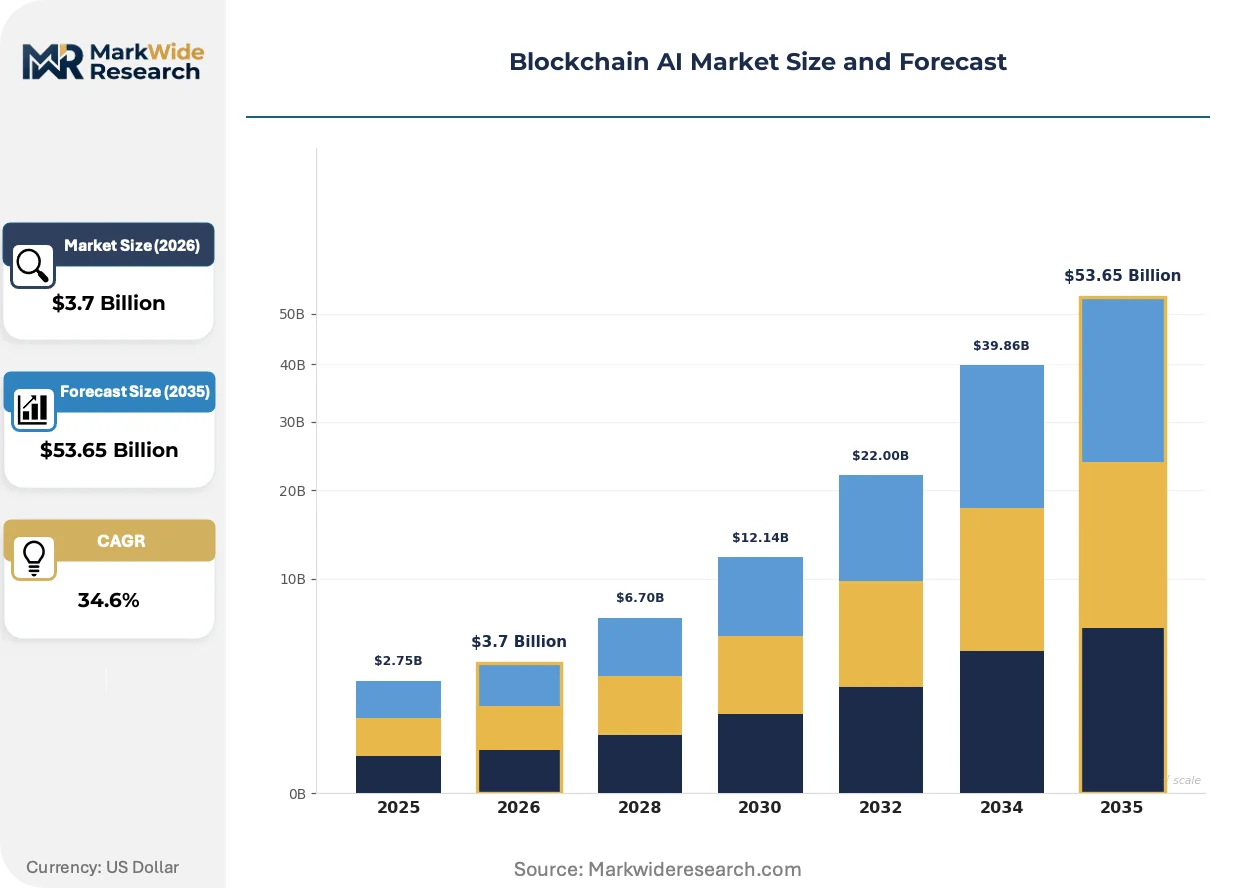
| Market Size in 2026 | $3.7 Billion |
| Market Size in 2035 | $53.65 Billion |
| CAGR (2026 – 2036) | 34.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Platforms, Solutions, Tools, Frameworks Application: Cryptocurrency, Supply Chain, Smart Contracts, Digital Identity End User: Enterprises, Startups, Government Agencies, Developers Deployment Model: Public Cloud, Private Cloud, Hybrid Cloud, On-Premises |
| Companies Covered | Bitmain, Block, Nvidia, Cipher Mining, Galaxy Digital, Coinbase Global, MicroStrategy, Bitfarms, Core Scientific, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Blockchain AI Market Emerging Trajectories
Blockchain AI architectures are fragmenting into composable layers as vendors race to separate consensus mechanisms from inference engines, enabling buyers to swap components without rebuilding entire stacks.
Zero-knowledge machine learning is modularizing model verification workflows by allowing auditors to confirm training data integrity and output correctness without accessing underlying datasets. Pharmaceutical manufacturers evaluating AI-enabled drug discovery tools are adopting these protocols to protect compound libraries while satisfying FDA pre-submission requirements. The structural consequence is compression of vendor evaluation cycles from multi-year pilots to six-month proof-of-concept deployments.
The EU AI Act's conformity assessment framework is forcing high-risk system deployers to maintain immutable model version histories with cryptographic attestation of training data provenance. Medical device manufacturers must now demonstrate that algorithm updates do not degrade safety profiles through blockchain-anchored regression testing logs. Cardiology AI vendors targeting the European market are responding by embedding automated compliance documentation into their continuous integration pipelines.
Enterprise buyers are consolidating vendor relationships around pre-integrated platform stacks rather than assembling consensus and inference layers from separate suppliers. Procurement teams at North American financial services firms now require unified SLAs covering both smart contract execution and model inference latency. This concentration is most visible in the United States, where three-tier RFP structures—separating infrastructure, middleware, and application layers—are displacing point-solution acquisitions.
Blockchain AI Market Segmentation
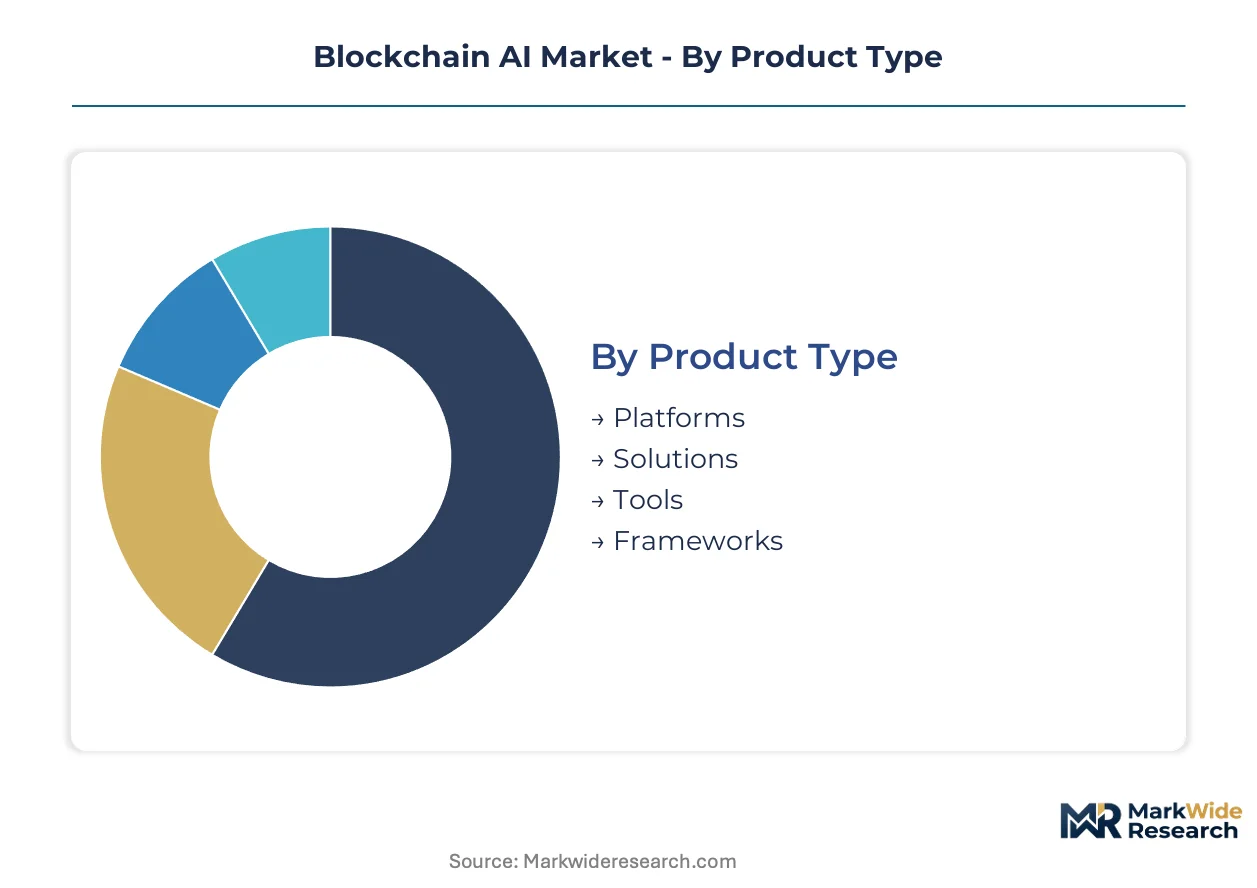
Blockchain AI vendors structure offerings around four intersecting dimensions that determine procurement complexity and integration depth. Product architecture choices constrain deployment flexibility, while end-user sophistication shapes pricing tolerance and support requirements.
Product Type:
Supply concentration in AI training infrastructure is restructuring how buyers evaluate pre-integrated stacks versus modular components.
- Platforms:Unified stacks combining consensus mechanisms, model training pipelines, and smart contract execution environments. Financial services firms in the United States are consolidating procurement around these bundles to secure single-vendor SLAs covering both inference latency and settlement finality.
- Solutions:Pre-configured applications addressing specific use cases such as fraud detection or credential verification. EU AI Act compliance mandates are accelerating demand for solutions with built-in audit trails and cryptographic attestation of model provenance.
- Tools:Specialized utilities for model versioning, data provenance tracking, or zero-knowledge proof generation. These attract defense contractors and pharmaceutical manufacturers seeking HIPAA-compliant predictive analytics without full platform commitments.
- Frameworks:Open-source libraries and SDKs enabling custom assembly of distributed learning protocols. Developer communities and research institutions drive adoption where customization outweighs time-to-market considerations.
Today's leader: Platforms. Tomorrow's challenger: Solutions.
Application:
End-use concentration in regulated industries is elevating compliance documentation from feature to procurement gate.
- Cryptocurrency:Algorithmic trading systems leveraging machine learning oracles for price prediction and automated settlement. SEC disclosure rules for automated trading systems are pushing hedge funds toward blockchain-verified model audit trails.
- Supply Chain:Immutable provenance tracking combined with demand forecasting across multi-tier supplier networks. German automotive manufacturers are deploying these systems to satisfy CSRD supply chain due diligence requirements.
- Smart Contracts:Self-executing agreements embedding ML oracles for conditional settlement based on real-world data feeds. These are expanding fastest among North American broker-dealers seeking real-time collateral verification.
- Digital Identity:Biometric inference combined with immutable credential storage for self-sovereign identity systems. Government procurement in France and Germany is driving demand for systems meeting eIDAS regulatory standards.
Smart Contracts are climbing the fastest as financial institutions retrofit core banking infrastructure.
End User:
Budget authority and technical staffing levels create distinct purchasing patterns across buyer categories.
- Enterprises:Fortune 500 financial services and healthcare organizations with dedicated AI ethics boards and procurement committees. These buyers require ISO/IEC certification and negotiate bespoke compliance architectures.
- Startups:Venture-backed firms prioritizing time-to-market over customization, typically selecting public cloud deployments with consumption-based pricing. Their procurement cycles compress vendor evaluation from multi-year pilots to quarterly renewals.
- Government Agencies:National laboratories and defense departments with classified data handling requirements. These buyers mandate on-premises deployment with FedRAMP or equivalent security accreditation.
- Developers:Individual practitioners and academic researchers experimenting with federated learning protocols. This segment sustains open-source framework development through grant funding and cloud credits.
Enterprises currently dominate contract value. Government Agencies represent the steepest expansion trajectory as NATO members increase defense AI spending.
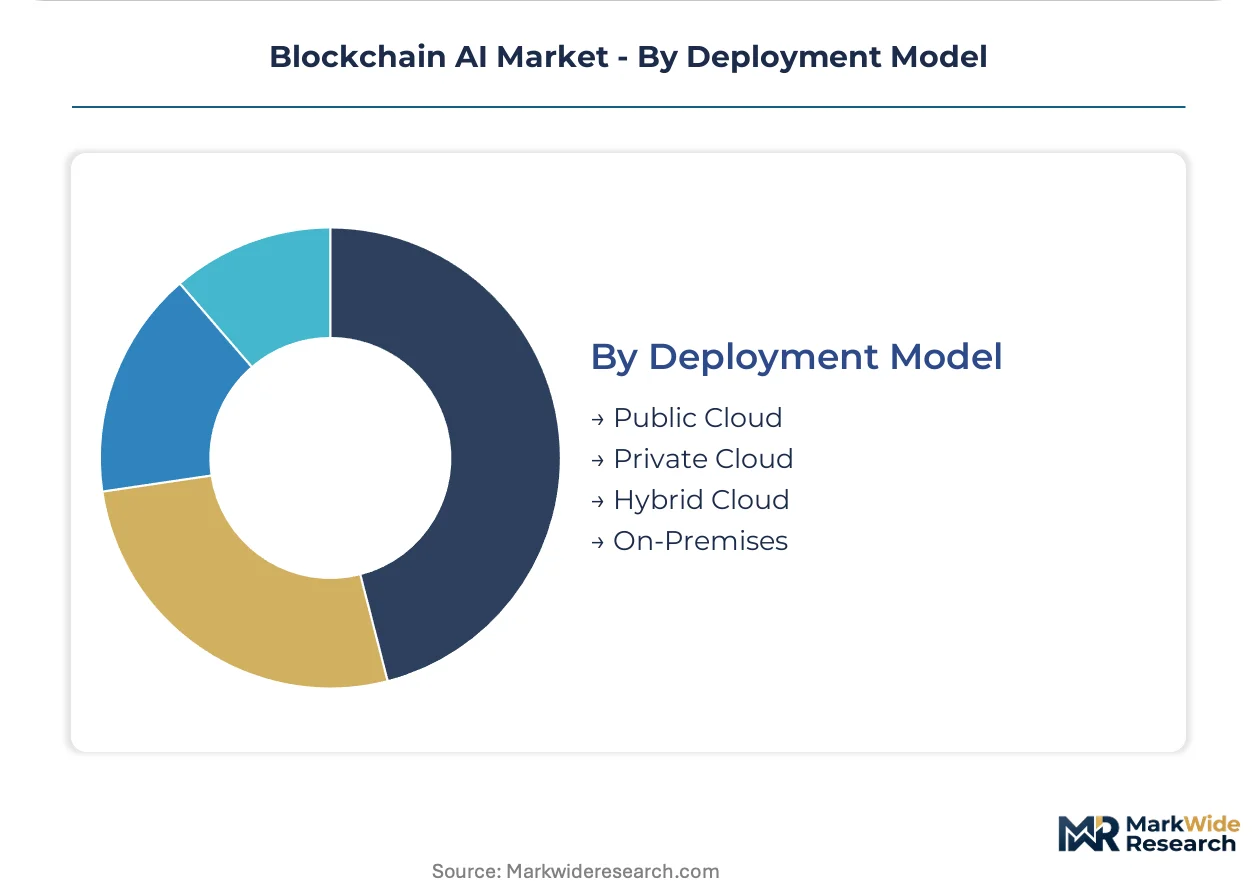
Deployment Model:
Data sovereignty requirements and latency sensitivity are fragmenting infrastructure choices across regulated and unregulated use cases.
- Public Cloud:Shared infrastructure with elastic scaling and pay-per-use economics. Startups and developers favor this model for training pipeline experimentation without capital commitment.
- Private Cloud:Single-tenant environments with dedicated compute resources. Healthcare systems in the United States select this model to maintain HIPAA control while avoiding on-premises hardware maintenance.
- Hybrid Cloud:Burst capacity configurations combining on-premises data sovereignty with cloud-based training scale. German and French regulated industries require this architecture to satisfy GDPR Article 46 transfer mechanism constraints.
- On-Premises:Fully captive infrastructure for air-gapped environments handling classified or export-controlled data. Government agencies and defense contractors mandate this deployment for models trained on sensitive intelligence or military operational data.
Hybrid Cloud configurations are gaining share fastest as multinational enterprises navigate jurisdictional data fragmentation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The San Francisco Bay Area anchors enterprise blockchain AI deployment through its concentration of venture capital and hyperscaler engineering talent. Regulatory divergence across jurisdictions is fragmenting vendor compliance architectures and reshaping procurement patterns.
United States
SEC disclosure rules for algorithmic trading systems are accelerating demand for smart contract oracles with machine learning capabilities. The FDA's oversight of AI-enabled medical devices pushes healthcare vendors toward blockchain-verified training logs. New York financial services firms dominate contract value as hedge funds retrofit core banking infrastructure with automated settlement verification.
Germany
Automotive manufacturers in Baden-Württemberg deploy blockchain AI for CSRD supply chain due diligence across multi-tier supplier networks. The EU AI Act's conformity assessment requirements force vendors to maintain immutable model version histories with cryptographic attestation. Munich's enterprise software cluster is consolidating procurement around pre-integrated platform stacks with unified SLAs.
France
Government procurement of self-sovereign identity systems combines biometric inference with immutable credential storage to satisfy eIDAS standards. GDPR Article 46 transfer mechanisms drive demand for federated learning protocols that train models without raw data movement. Paris fintech clusters are attracting venture investment for hybrid cloud configurations balancing data sovereignty with elastic scaling.
United Kingdom
London's algorithmic trading ecosystem embeds machine learning oracles into smart contracts for real-time collateral verification. The Financial Conduct Authority's scrutiny of automated trading systems pushes broker-dealers toward auditable model provenance. Cambridge research institutions anchor open-source framework development for federated learning protocols.
China
MIIT standards for blockchain interoperability shape enterprise AI deployment in the Yangtze River Delta manufacturing corridor. Dual carbon goals are pressuring proof-of-work networks integrated with machine learning pipelines to relocate energy-intensive operations. Shenzhen's hardware ecosystem supplies ASIC manufacturing scale for consensus mechanisms supporting distributed model training.
Blockchain AI Market Vendor Landscape
Global majors compete with regional champions across hardware supply and cloud infrastructure dimensions, creating a tiered structure where scale advantages concentrate in semiconductor fabrication and energy procurement. The vendor base separates into three strategic archetypes: ASIC manufacturers leveraging captive silicon design, GPU-accelerated platform providers, and vertically integrated mining operators co-locating with AI training facilities. Dominant competitive moves include strategic partnerships between hardware suppliers and cloud hyperscalers, plus geographic expansion into jurisdictions with favorable electricity tariffs.
Within the hardware-centric tier, Bitmain and Nvidia occupy positions representing divergent approaches to computational infrastructure supply. Bitmain exemplifies the ASIC-specialist archetype through its manufacturing scale dominance for proof-of-work networks. Nvidia anchors the GPU-accelerated consensus segment underpinning enterprise blockchain deployments. Cipher Mining represents the energy-integrated operator model, situating mining operations adjacent to AI model training facilities to capture operational synergies.
| Leading Market Players |
|---|
| Bitmain |
| Block |
| Nvidia |
| Cipher Mining |
| Galaxy Digital |
| Coinbase Global |
| MicroStrategy |
| Bitfarms |
| Core Scientific |
| Others |
Supply Flow & Price Mechanics
Enterprise procurement consolidation around unified platform stacks is forcing vendors to absorb GPU hardware cost volatility while maintaining fixed-price SaaS contracts. This demand-side pressure compresses margins for providers lacking captive silicon supply or energy-integrated operations.
Pricing Analysis
Input-cost pass-through from ASIC and GPU procurement dominates pricing structures, with subscription tiers anchored to computational throughput guarantees. Price differentiation separates FedRAMP-accredited government deployments from standard enterprise licenses, while startup segments exhibit highest sensitivity to per-inference metering. Pricing pressure intensifies as hyperscaler cloud credits subsidize training costs for venture-backed entrants.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale buyer demand for pre-integrated hardware-software bundles, bypassing distributor markups. Manufacturing concentrates in Taiwan for advanced semiconductor fabrication, China for ASIC assembly, and Malaysia for packaging operations. The chain draws from specialized silicon wafers, high-bandwidth memory modules, and liquid cooling systems. Single-source vulnerability in EUV lithography equipment creates structural risk for node operators scaling training clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion potential concentrates with vendors capturing energy cost advantages through co-located mining and training operations, while premium-tier shifts toward FedRAMP and EU AI Act-certified deployments sustain pricing power.
For Market Incumbents: Anchor market position through backward integration into captive ASIC design and foundry partnerships that insulate against Nvidia supply bottlenecks. Defend against emerging verticalized challengers by embedding automated compliance documentation into continuous integration pipelines for EU AI Act and FDA pre-submission requirements. For New Entrants and Emerging Players: Mid-tier healthcare systems in the United States represent an underserved buyer archetype seeking HIPAA-compliant predictive analytics without full platform commitments. Penetrate this segment through modular zero-knowledge proof tools with consumption-based pricing, bypassing incumbent RFP cycles. For Investors and Strategic Acquirers: Asymmetric upside sits with vertically integrated operators combining energy procurement scale with AI training facility co-location. Long-term viability favors acquisition targets with secured electricity offtake agreements and demonstrated regulatory certification velocity. Watch hyperscaler capex allocation shifts as the inflection signal for infrastructure demand cycles.| Strategic Initiative | Industry Significance |
|---|---|
| ASIC Design Partnership | Secures silicon supply autonomy against Nvidia GPU bottlenecks for proof-of-work consensus integration. |
| Energy Co-location Expansion | Captures operational synergies by situating mining operations adjacent to AI model training facilities. |
| EU AI Act Compliance Automation | Embeds cryptographic attestation and immutable model versioning into continuous integration pipelines. |
| Hybrid Cloud Configuration | Addresses GDPR Article 46 constraints for German and French regulated industry procurement requirements. |
| Federated Learning Protocol Development | Enables cross-border model training without raw data movement for pharmaceutical and defense contractors. |
Methodological Framework
Bottom-up enterprise procurement modeling reconciled against top-down hardware shipment tracking forms the analytical core of this study. Primary interviews with CTOs at financial services firms, AI ethics board directors, hyperscaler platform engineers, and government procurement officers combined with secondary validation against SEC algorithmic trading disclosures, FDA pre-submission databases, EU AI Act conformity assessment registries, and hyperscaler capex filings. Triangulation across these sources ensures segmentation integrity.
Historical trendline analysis of smart contract deployment velocity and model training infrastructure spend established baseline growth patterns across the projection horizon. Segmentation dimensions modeled include product architecture, application use case, deployment model, and regulatory compliance tier. CAGRs derive from regression analysis of adoption curves against constraint variables including GPU supply elasticity and energy tariff trajectories. Forecast inputs incorporate EU AI Act implementation timelines and SEC disclosure rule enforcement intensity.
Underlying measurement precision varies by segment; public cloud deployment estimates carry tighter precision than on-premises government installations due to disclosure requirements. Forecasts reflect assumptions regarding regulatory harmonization pace and semiconductor supply normalization. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Blockchain Technology
Blockchain Retail Market
Blockchain Technology
Managed Blockchain Services Market
Blockchain Technology
Bitcoin Technology Market
Blockchain Technology
Blockchain in Aviation Market
Blockchain Technology
Global Blockchain in Telecom Market
Blockchain Technology
Blockchain in Mining Market
Blockchain Technology
Blockchain Technology in Healthcare Market
Blockchain Technology
Blockchain Device Market
Blockchain Technology
Blockchain-As-A-Service (Baas) Market
Blockchain Technology
Smart Contracts on Blockchain Market
Blockchain Technology
Blockchain Messaging Apps Market
Blockchain Technology
Blockchain Gaming Market
Blockchain Technology
Pharmaceutical Blockchain Market
Blockchain Technology
Aviation Transaction Blockchain Market
Blockchain Technology
Blockchain in Sports Market
Blockchain Technology
Global Blockchain Software Market