
 Tokenization Market | 2026-2036
Tokenization Market Size, Share, and Industry Trends Forecast 2026-2036
Tokenization Market Intelligence
A shortage of smart contract auditors and blockchain infrastructure engineers is unwinding across the tokenization sector, delaying enterprise rollout timelines and inflating implementation costs. BlackRock leverages its institutional distribution network to anchor tokenized fund products for qualified investors. Securitize competes through end-to-end digital securities infrastructure spanning issuance to secondary trading. Fireblocks sustains market presence with custody and token transfer rails that banks and asset managers integrate directly.
Tokenization replaces sensitive data elements with non-sensitive surrogate values, typically employing format-preserving algorithms that maintain original data length and structure for downstream processing compatibility. Its primary commercial purpose is to reduce breach exposure in payment ecosystems while preserving analytical utility for fraud detection and customer analytics. Cloud tokenization is capturing disproportionate investment as financial institutions exit capital-intensive on-premise hardware security module estates. Payment processing applications dominate current revenue, though digital identity verification is emerging as the fastest-expanding use case as governments pilot blockchain-based credential systems.
The SEC regulates tokenized securities offerings under existing investment contract frameworks, while the EU MiCA regime establishes uniform licensing requirements for crypto-asset service providers across member states. PCI DSS compliance mandates continue to drive replacement cycles for legacy payment tokenization infrastructure in retail and hospitality sectors. Stakeholders must monitor how central bank digital currency interoperability standards reshape settlement layer requirements for private tokenization networks.
Market Dynamics
The tokenization sector faces a structural talent compression where qualified smart contract auditors and blockchain infrastructure engineers remain acutely scarce, forcing financial institutions to extend deployment timelines and absorb premium labor costs.
Growth Catalysts
- EU Markets in Crypto-Assets (MiCA):The framework establishes uniform licensing requirements for crypto-asset service providers across member states, reducing regulatory fragmentation that previously deterred cross-border tokenized securities issuance.
- Cloud infrastructure migration:Financial institutions are accelerating exit from capital-intensive on-premise hardware security module estates, redirecting capital toward scalable cloud-native tokenization architectures.
- Institutional payment networks:Enterprise deployment demand concentrates among qualified investors and payment processors seeking settlement efficiency through programmable digital assets.
Market Restraints
- Specialized labor scarcity:The shortage of blockchain infrastructure engineers inflates implementation costs and extends enterprise rollout timelines beyond initial projections.
- Regulatory friction:The SEC applies existing investment contract frameworks to tokenized securities, creating compliance uncertainty that slows product structuring decisions.
- Legacy system integration:Format-preserving tokenization algorithms must maintain compatibility with downstream fraud detection and customer analytics systems, constraining architectural flexibility.
Strategic Opportunities
- Digital identity verification:Governments are piloting blockchain-based credential systems, creating the fastest-expanding use case beyond payment processing applications.
- Central bank digital currency interoperability:Emerging settlement layer standards for private tokenization networks will reshape infrastructure requirements for early movers.
- PCI DSS compliance replacement cycles:Mandates continue to drive infrastructure refresh in retail and hospitality sectors with dated tokenization estates.
Industry Challenges
- Smart contract audit capacity:The unwinding shortage of qualified auditors delays security validation for enterprise tokenized fund products.
- Distributed ledger infrastructure complexity:Banks and asset managers face integration friction when embedding custody and token transfer rails into existing operational workflows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Tokenization Market |
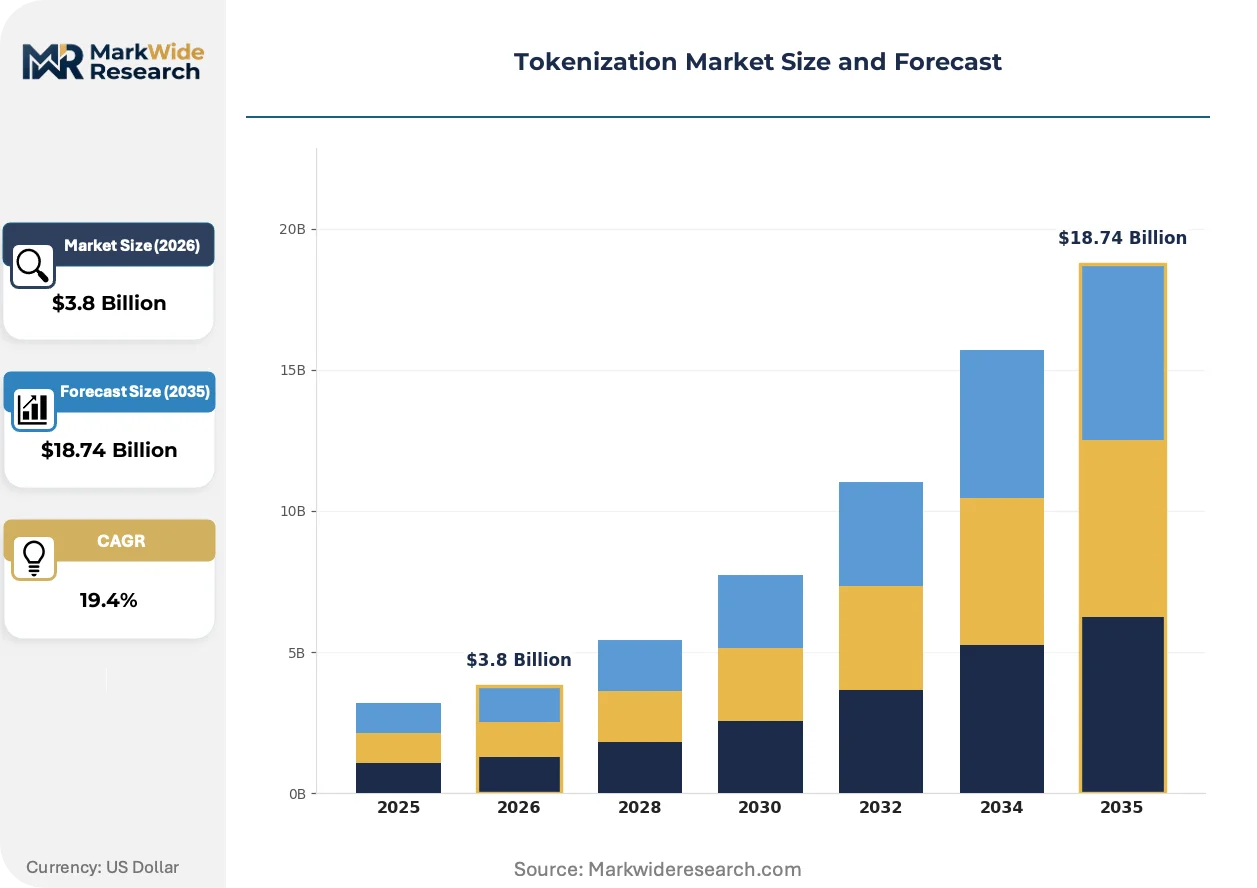
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $18.74 Billion |
| CAGR (2026 – 2036) | 19.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Hardware Security Module, Software-based Tokenization, Cloud Tokenization, API Tokenization, On-Premise Tokenization Application: Payment Processing, Data Privacy, Fraud Prevention, Customer Authentication, Digital Identity Verification End User Industry: BFSI, Telecommunications, Government Agencies, E-commerce Platforms, Travel & Hospitality Deployment Model: Public Cloud, Private Cloud, Hybrid Cloud, Managed Services, Community Cloud |
| Companies Covered | BlackRock, Ondo Finance, Tokeny, Securitize, Centrifuge, Fireblocks, BlockchainX, Polymath, InvestaX, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Tokenization Market Strategic Shifts & Innovations
Format-preserving encryption architectures are actively displacing legacy tokenization methods as financial institutions prioritize downstream processing compatibility alongside security posture.
Zero-knowledge proof implementations are bifurcating the tokenization technology stack. These cryptographic protocols enable transaction validation without exposing underlying sensitive data. Asset managers and payment processors in Switzerland and Singapore are adopting these methods for cross-border settlement use cases. The structural consequence is compressing the traditional trade-off between analytical utility and breach exposure that has constrained tokenization architecture decisions for a decade.
The EU AI Act introduces risk-based classification requirements for automated decision systems processing tokenized identity credentials. Financial institutions deploying blockchain-based verification must now document algorithmic transparency and human oversight protocols. Digital identity pilots in France and Germany face expanded compliance timelines as national regulators interpret conformity assessment procedures.
Enterprise buyers are consolidating vendor relationships around end-to-end digital securities infrastructure spanning issuance through secondary trading. Single-point solutions for custody, transfer rails, or compliance tooling face displacement as asset managers prioritize unified operational workflows. This preference shift is most visible among qualified investor funds in the United States seeking to reduce counterparty fragmentation across the tokenized asset lifecycle.
Tokenization Market Segmentation
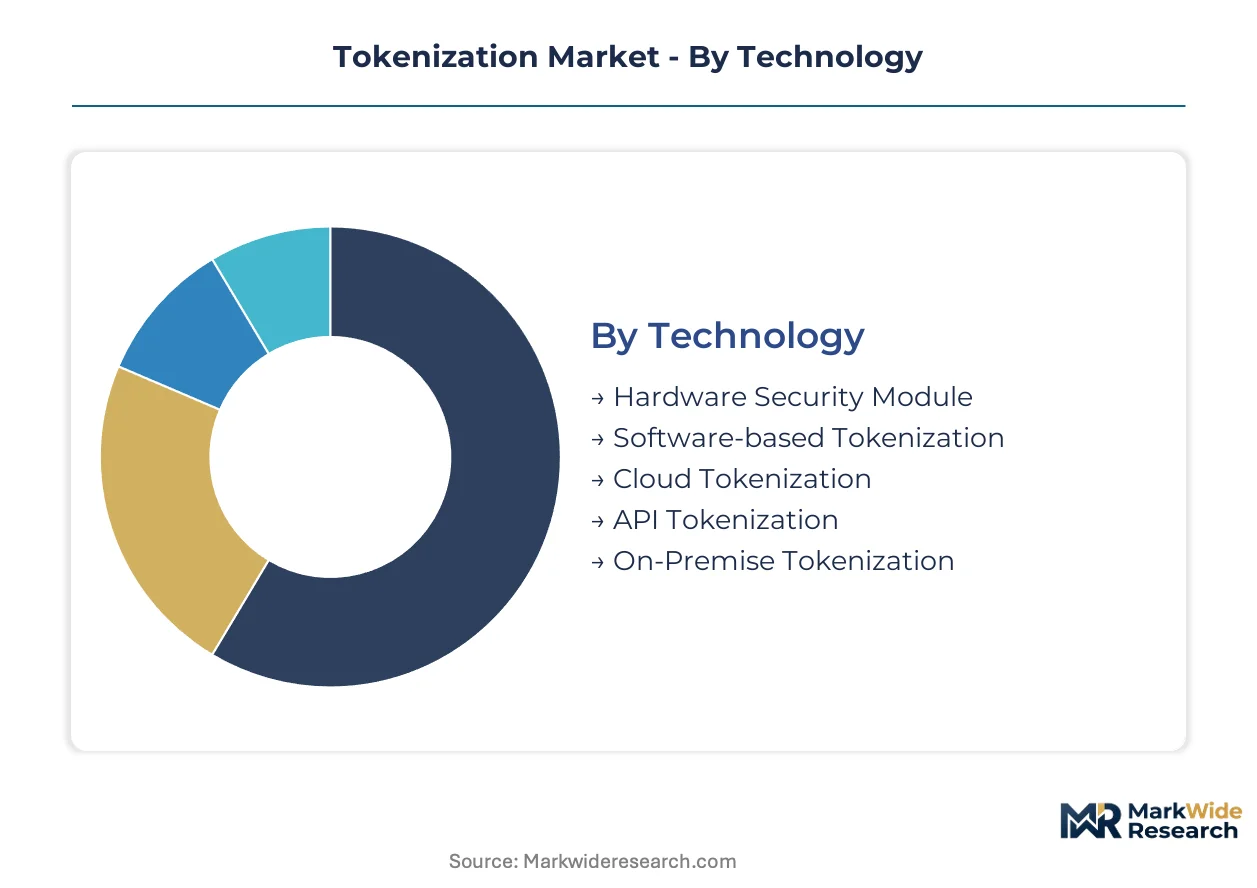
Tokenization architectures diverge sharply across deployment modes, application contexts, and compliance requirements. Technology choices determine capital intensity and audit complexity. End-user industries impose sector-specific regulatory constraints that reshape vendor selection criteria.
Technology:
Cloud-native architectures are displacing hardware-dependent alternatives as financial institutions exit capital-intensive on-premise estates.
- Cloud Tokenization:Scalable infrastructure eliminates hardware refresh cycles and enables elastic capacity for transaction volume spikes. US payment processors and European neobanks are consolidating procurement around multi-tenant cloud stacks to reduce operational overhead.
- Hardware Security Module:Physical cryptographic processors maintain compliance with strict data residency mandates in regulated jurisdictions. German and Swiss asset managers retain HSM deployments for qualified investor fund custody where regulatory interpretation favors air-gapped security boundaries.
- Software-based Tokenization:Algorithmic token generation runs on standard compute without specialized hardware. Retail merchants with limited IT budgets adopt these solutions for PCI DSS compliance at lower entry cost.
- API Tokenization:Embedded token services integrate directly into application workflows through RESTful interfaces. E-commerce platforms favor this model for rapid deployment without infrastructure overhaul.
- On-Premise Tokenization:Self-managed deployments persist where data sovereignty laws prohibit cross-border cloud processing. Government agencies in jurisdictions with restrictive data localization requirements maintain captive infrastructure.
Cloud Tokenization anchors the volume base while API Tokenization gains share at the steepest rate.
Application:
Payment use cases dominate current revenue, though identity verification is climbing the fastest as governments pilot blockchain credential systems.
- Payment Processing:Card-not-present transactions require real-time token substitution to reduce breach exposure. US acquiring banks and merchant processors deploy format-preserving algorithms that preserve downstream fraud detection compatibility.
- Digital Identity Verification:Blockchain-based credential systems enable self-sovereign identity without centralized data repositories. France and Germany are expanding national pilot programs despite EU AI Act compliance timelines.
- Data Privacy:Tokenization replaces sensitive data elements in analytics pipelines while preserving statistical utility. Healthcare and insurance sectors apply these methods to share patient records across institutional boundaries.
- Fraud Prevention:Surrogate values enable transaction monitoring without exposing primary account numbers. Retail banks integrate tokenized data streams into machine learning models for anomaly detection.
- Customer Authentication:Biometric and behavioral tokens reduce reliance on static passwords. Telecommunications providers deploy these methods for subscriber verification in high-risk transaction scenarios.
Payment Processing anchors the volume base while Digital Identity Verification expands most quickly.
End User Industry:
Capital allocation intensity varies dramatically, with BFSI absorbing premium pricing for audit-grade infrastructure while e-commerce prioritizes throughput economics.
- BFSI:Banks, insurers, and asset managers face layered compliance from PCI DSS, SEC custody rules, and MiCA licensing. Tokenization investments concentrate on qualified investor products and cross-border settlement rails.
- E-commerce Platforms:High-velocity transaction environments demand sub-second token generation with minimal latency overhead. Marketplace operators prioritize API-first solutions that scale with seasonal demand spikes.
- Government Agencies:National credential systems and tax administration require sovereign infrastructure with domestic data residency. Pilot programs in France and Germany are expanding procurement for blockchain-based identity verification.
- Telecommunications:Subscriber databases and mobile payment wallets require tokenization for regulatory compliance and fraud reduction. Carriers in competitive markets differentiate through security certifications.
- Travel & Hospitality:PCI DSS mandates drive replacement cycles for legacy payment infrastructure at hotel chains and airlines. Franchise operators face consolidation pressure as corporate parents mandate unified tokenization standards.
BFSI anchors the volume base while Government Agencies climb the fastest.
Deployment Model:
Hybrid configurations are gaining traction as organizations balance elasticity requirements against data residency constraints.
- Public Cloud:Shared infrastructure delivers lowest unit economics for standardized tokenization workloads. US payment processors and European fintechs consolidate on hyperscaler platforms to accelerate time-to-market.
- Hybrid Cloud:Split architectures place sensitive operations in private environments while burst capacity leverages public resources. Asset managers in Switzerland and Singapore adopt this model for cross-border fund administration.
- Private Cloud:Dedicated single-tenant infrastructure satisfies strict audit and data localization requirements. German banks and French government agencies maintain these deployments where regulatory interpretation favors isolation.
- Managed Services:Outsourced operations transfer operational burden to specialized providers. Mid-market institutions without internal blockchain engineering capacity favor this model to bypass talent scarcity constraints.
- Community Cloud:Shared infrastructure among consortium members enables collective compliance without individual capital outlay. Industry-specific deployments are emerging among payment network participants.
Public Cloud anchors the volume base while Hybrid Cloud gains share at the steepest rate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply by geography. US institutions prioritize qualified investor fund products, while European deployment concentrates on MiCA-compliant cross-border infrastructure. Asian markets emphasize central bank digital currency interoperability and sovereign credential systems.
United States
Institutional investors and payment networks drive enterprise tokenization deployment. The SEC applies existing investment contract frameworks to tokenized securities, creating compliance uncertainty that slows product structuring. New York and San Francisco financial clusters absorb premium pricing for audit-grade smart contract infrastructure.
Germany
Asset managers retain hardware security module deployments for qualified investor fund custody where regulatory interpretation favors air-gapped security boundaries. BaFin licensing requirements and data residency mandates shape procurement decisions. Frankfurt and Munich banking centers pilot blockchain-based settlement rails for cross-border fund administration.
Singapore
Asset managers and payment processors adopt zero-knowledge proof methods for cross-border settlement use cases. The Monetary Authority of Singapore's regulatory sandbox enables controlled experimentation with programmable digital assets. The city-state's financial district serves as Asia-Pacific infrastructure hub for hybrid cloud tokenization architectures.
Switzerland
FINMA guidance on digital assets attracts asset managers seeking regulatory clarity for tokenized fund structures. Swiss banks maintain private cloud deployments for strict audit and data localization requirements. Zurich and Geneva financial centers specialize in custody and token transfer rails for cross-border wealth management.
France
National regulators interpret EU AI Act conformity assessment procedures, expanding compliance timelines for digital identity pilots. The ANSM and CNIL shape risk-based classification requirements for automated decision systems processing tokenized credentials. Paris anchors government procurement for blockchain-based credential systems.
Tokenization Market Key Industry Players
A small set of integrated leaders sits above a broader specialist tier in the tokenization sector. The upper tier combines end-to-end digital securities infrastructure with institutional distribution networks. Specialist players concentrate on custody rails, compliance tooling, or issuance platforms. Dominant competitive moves include strategic partnerships with payment processors and portfolio diversification into adjacent identity verification verticals.
Within the integrated infrastructure tier, BlackRock and Securitize exemplify contrasting approaches to institutional market access. BlackRock leverages its asset management scale to anchor tokenized fund products for qualified investors. Securitize occupies a position spanning issuance through secondary trading, reducing counterparty fragmentation for asset managers. Fireblocks sits within the custody and transfer rail specialization, serving banks and asset managers seeking direct integration paths.
| Leading Market Players |
|---|
| BlackRock |
| Ondo Finance |
| Tokeny |
| Securitize |
| Centrifuge |
| Fireblocks |
| BlockchainX |
| Polymath |
| InvestaX |
| Others |
Cost & Logistics Intelligence
Capacity reservation contracts with cloud hyperscalers lock in both infrastructure access and predictable unit economics for tokenization service providers, binding financial institutions to multi-year commitments that insulate against spot-price volatility in compute resources while constraining architectural flexibility.
Pricing Analysis
Long-term offtake agreements dominate enterprise procurement, with subscription-based SaaS tiers scaling by transaction volume and compliance certification level. Three-tier pricing structure across premium, standard, and economy levels separates audit-grade smart contract infrastructure from API-only solutions. Cost compression in the standard tier intensifies because cloud-native entrants compete on elastic capacity pricing. Mid-market asset managers exhibit highest price sensitivity, while qualified investor funds absorb premium pricing for end-to-end digital securities infrastructure.
Supply Chain Analysis
Port congestion on Asia-Pacific trade lanes elevates inbound logistics costs for hardware security module manufacturers sourcing cryptographic processors from Taiwan and South Korea. The tokenization technology stack draws from specialized semiconductor foundries, cloud compute infrastructure, and blockchain protocol development talent pools. Single-source vulnerability concentrates in smart contract audit capacity, where qualified engineers remain acutely scarce. Distribution runs through direct enterprise sales channels and strategic partnerships with payment processors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation across deployment models and compliance jurisdictions creates niche entry points for specialized vendors, as divergent regulatory interpretations in Germany, Singapore, and the United States splinter demand for unified tokenization architectures.
For Market Incumbents: Compound market position through backward integration into smart contract audit capacity and captive cloud infrastructure development. Acquire specialist compliance tooling providers to close gaps in EU AI Act documentation workflows. The talent scarcity threat demands vertical consolidation before labor costs erode margin structures. For New Entrants and Emerging Players: Anchor in digital identity verification pilots where government procurement timelines favor agile vendors over incumbent financial infrastructure providers. France and Germany offer the most penetrable regulatory environments for blockchain-based credential systems. Pursue managed services positioning to bypass direct competition with BlackRock's institutional distribution network. For Investors and Strategic Acquirers: Cloud-native tokenization platforms with existing MiCA licensing pathways represent the most defensible acquisition archetype. Long-term viability hinges on interoperability positioning for central bank digital currency settlement standards. Monitor regulatory sandbox graduation rates in Singapore as the primary inflection indicator for enterprise adoption velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Smart Contract Audit Capacity Expansion | Addresses acute talent scarcity delaying enterprise tokenized fund launches. |
| MiCA Licensing Pathway Completion | Unlocks cross-border tokenized securities issuance across EU member states. |
| Zero-Knowledge Proof Integration | Enables Swiss and Singaporean asset managers to validate transactions without data exposure. |
| Hybrid Cloud Architecture Deployment | Balances elasticity requirements against German and French data residency mandates. |
| Digital Identity Pilot Partnership | Positions vendors for French government procurement of blockchain credential systems. |
Research Approach
Cross-validation between primary interviews and regulatory filing analysis anchors the qualitative findings in documented compliance frameworks. The research team conducted structured conversations with smart contract auditors, blockchain infrastructure engineers, asset manager technology officers, and MiCA licensing consultants. Secondary validation drew from SEC no-action letters, BaFin circulars, MAS sandbox disclosures, and FINMA guidance documents. Bottom-up transaction volume estimates triangulate against top-down capital allocation surveys from institutional investors.
Sensitivity analysis around regulatory timeline assumptions shapes the forecast confidence intervals across the projection horizon. The analytical framework segments by deployment model, application context, end-user industry, and regional regulatory cluster. CAGRs derive from elasticity-adjusted adoption curves fitted to pilot program graduation data and enterprise procurement pipeline visibility. Smart contract audit capacity constraints and cloud infrastructure migration timelines represent the primary industry-specific forecast inputs.
Underlying assumptions cover MiCA implementation adherence, SEC enforcement continuity, and central bank digital currency interoperability standardization, with deviation risk concentrated in regulatory interpretation divergence across member states. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Blockchain Technology
Blockchain Technology in Healthcare Market
Blockchain Technology
Decentralized Identity Market
Blockchain Technology
Global Blockchain Market
Blockchain Technology
Europe Blockchain Market
Blockchain Technology
Aviation Transaction Blockchain Market
Blockchain Technology
Bitcoin Technology Market
Blockchain Technology
Blockchain in Manufacturing Market
Blockchain Technology
Global Blockchain in Telecom Market
Blockchain Technology
Global Blockchain for Non-Profits Market
Blockchain Technology
Aviation Record-Keeping Blockchain Market
Blockchain Technology
Global Blockchain in Healthcare Market
Blockchain Technology
Blockchain in Smart Home Market
Blockchain Technology
Blockchain Technology in Energy Market
Blockchain Technology
Global Blockchain in Energy Market
Blockchain Technology
Blockchain in Energy Utilities Market
Blockchain Technology
Global Blockchain in Logistics Market