
 Europe Blockchain Market | 2026-2036
Europe Blockchain Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Blockchain Market Intelligence
The divergence between enterprise-grade, private blockchain solutions and standardized public ledger components is repositioning the competitive landscape in Europe. Bitcoin Suisse specializes in crypto-finance and asset management solutions, targeting high-value clients in the Swiss financial sector. Consensys leverages its deep expertise in the Ethereum ecosystem to build custom enterprise applications. Meanwhile, Polygon competes by offering scaling solutions that enhance the performance and reduce costs on public blockchains.
Blockchain technology is a distributed ledger system that records transactions in immutable, cryptographically linked blocks, ensuring data integrity through decentralization. Its core commercial function is to enable secure, transparent asset tracking and the automated execution of smart contracts without a central authority. The financial services sector leads adoption, primarily using private blockchain technology for enhanced security and regulatory compliance. Supply chain management applications represent the fastest-growing segment, often utilizing hybrid models to share data selectively with network partners.
The regulatory environment in Europe is shaped by frameworks like the General Data Protection Regulation (GDPR) and the Markets in Crypto-Assets (MiCA) regulation. These rules establish stringent requirements for data privacy, consumer protection, and asset classification, influencing platform design choices. Stakeholders must now focus on developing solutions that are not only technologically advanced but also compliant by design to secure a position in the market.
Market Dynamics
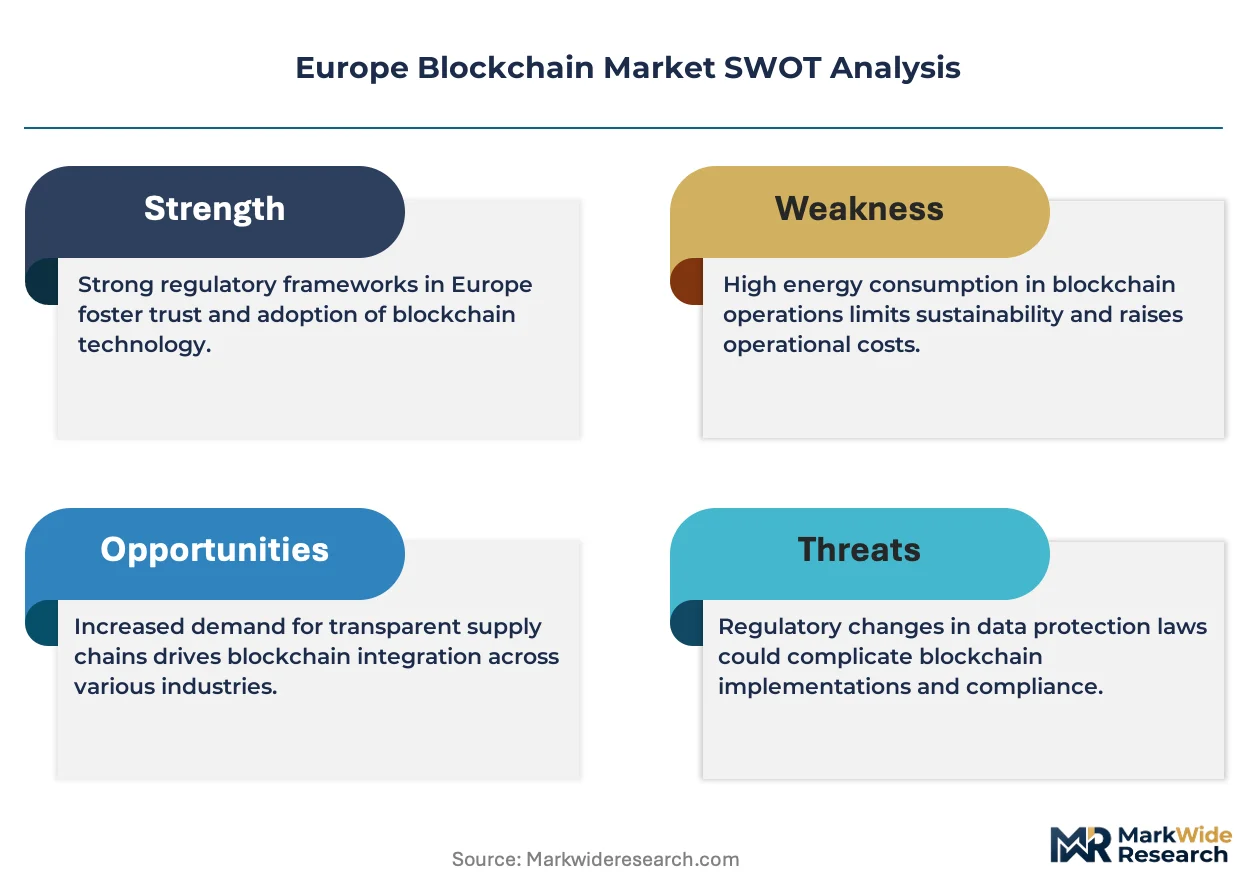
The European blockchain market is being fundamentally shaped by regulatory pressure for compliant data management and asset traceability. Mandates like GDPR and the forthcoming MiCA framework are pushing enterprises toward private and permissioned ledgers that offer greater control and auditability than public alternatives.
Growth Catalysts
- Regulatory Compliance:The General Data Protection Regulation (GDPR) compels organizations to adopt solutions with immutable audit trails for data access and processing, directly benefiting blockchain platforms designed for privacy and transparency.
- Financial Services Innovation:The Swiss financial sector, a key European hub, is driving adoption for asset tokenization and streamlined management of complex securities, leveraging blockchain for enhanced settlement efficiency and compliance.
- Supply Chain Modernization:Demand for verifiable provenance in the food and pharmaceutical industries is accelerating the use of blockchain to ensure product integrity and meet stringent EU import and safety standards.
Market Restraints
- Interoperability Barriers:A lack of standardized protocols between major blockchain platforms, such as Hyperledger Fabric and Ethereum, creates friction and increases the complexity of building cross-chain applications for enterprises.
- Legal and Jurisdictional Ambiguity:The legal status and enforceability of smart contracts vary significantly across EU member states, creating uncertainty for businesses operating in multiple jurisdictions and slowing cross-border deployments.
- High Implementation Costs:The significant upfront investment required for custom enterprise-grade blockchain development, integration with legacy systems, and specialized talent acquisition remains a substantial barrier for many small and medium-sized enterprises.
Strategic Opportunities
- Digital Identity Solutions:There is a significant opportunity to develop self-sovereign identity platforms for public sector and e-commerce applications, particularly in markets like Estonia and Germany that are exploring national digital ID frameworks.
- Tokenization of Illiquid Assets:Blockchain technology enables the fractionalization and trading of previously illiquid assets like real estate, fine art, and private equity, creating new investment vehicles and enhancing market liquidity.
- ESG Reporting and Verification:The Corporate Sustainability Reporting Directive (CSRD) creates demand for blockchain-based systems to transparently track and verify environmental, social, and governance metrics across complex European supply chains.
Industry Challenges
- Specialized Talent Scarcity:A persistent shortage of developers and architects with dual expertise in specific protocols like Solidity for Ethereum and the requirements of enterprise-grade systems integration hinders project execution and inflates development costs.
- Legacy System Integration:Integrating decentralized ledger technology with existing centralized enterprise resource planning (ERP) and customer relationship management (CRM) systems without disrupting operations or creating data inconsistencies is a major technical hurdle.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Blockchain Market |
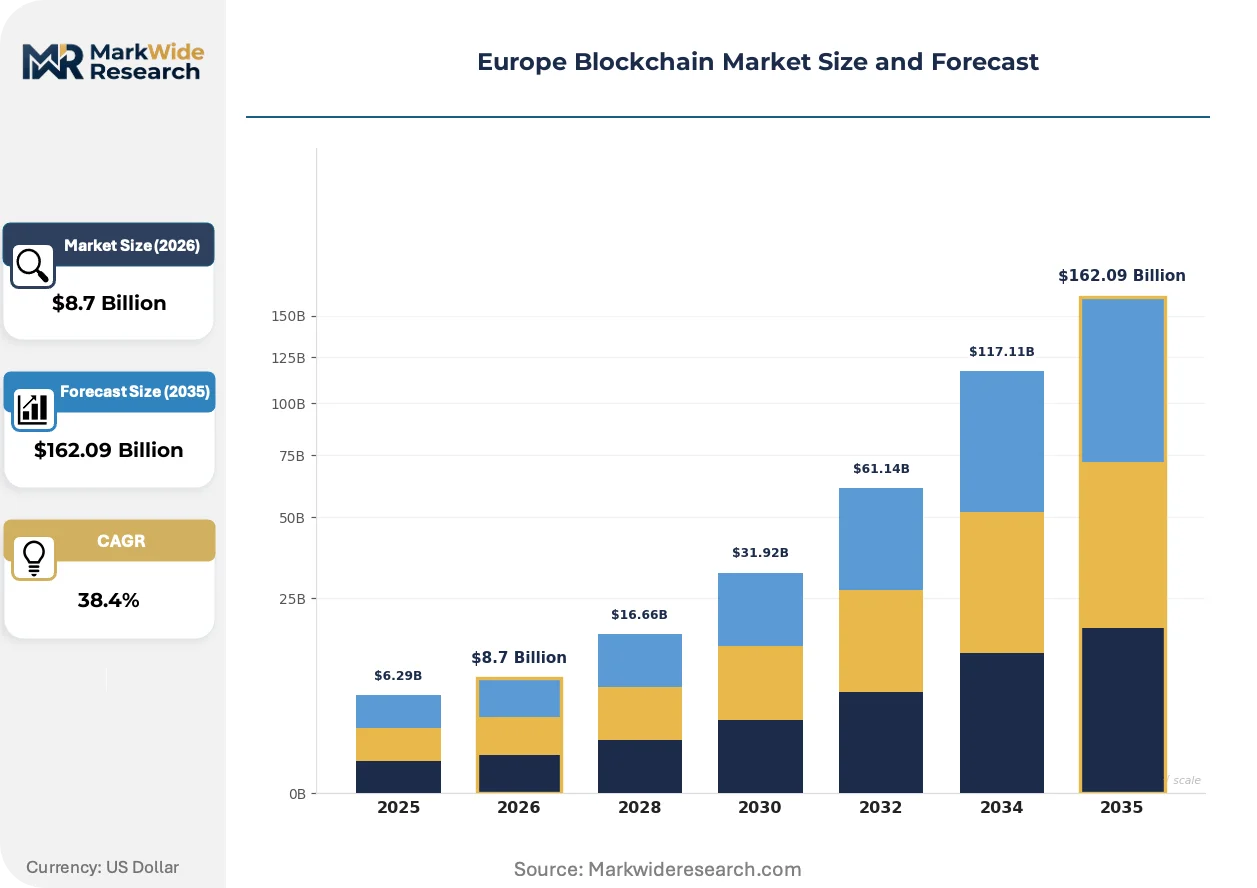
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $162.09 Billion |
| CAGR (2026 – 2036) | 38.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Application: Supply Chain Management, Digital Identity, Payment Processing, Voting Systems, Asset Management, Compliance Tracking Technology: Public Blockchain, Private Blockchain, Hybrid Blockchain, Consortium Blockchain, Distributed Ledger Technology, Smart Contracts End User Industry: Financial Services, Government Agencies, Manufacturing Firms, Healthcare Providers, Telecommunications Firms, Energy Operators Deployment Model: Cloud-Based Solutions, On-Premises Implementation, Platform as a Service, Infrastructure as a Service, Software as a Service, Hosted Services |
| Companies Covered | IdeaSoft, Polygon, Ripple, Bitcoin Suisse, Consensys, Blockstream, LimeChain, SKALE Labs, ChainSafe, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Blockchain Market Strategic Shifts & Innovations
The market is shifting from speculative exploration to pragmatic implementation, with a clear focus on solving specific business problems related to compliance, security, and operational efficiency. This maturation is driven by clear regulatory guardrails and a growing understanding of where distributed ledger technology delivers tangible value.
Zero-Knowledge Proofs (ZKPs) are cryptographic protocols that enable transaction verification without revealing the underlying confidential data. Financial services and healthcare organizations are actively piloting ZKPs on permissioned ledgers to comply with strict data privacy rules. This privacy-enhancing technology is converging with public ledger components, enabling new hybrid architectures that offer both security and selective transparency.
The Markets in Crypto-Assets (MiCA) regulation introduces a harmonized legal framework for digital assets and service providers across the European Union. The directive imposes rigorous requirements for authorization, governance, and consumer protection, similar to traditional financial regulations. Consequently, the stablecoin and crypto-exchange segments are re-architecting their platforms and operational models to achieve compliance and secure access to the unified EU market.
A notable shift in enterprise strategy involves moving from isolated, single-company pilot projects to forming industry-specific blockchain consortia. This collaborative procurement model reduces individual development costs and risks while fostering network effects and common standards. This trend is particularly advanced within the European automotive and logistics sectors, where consortia are building shared platforms for parts traceability and trade finance.
Europe Blockchain Market Segmentation
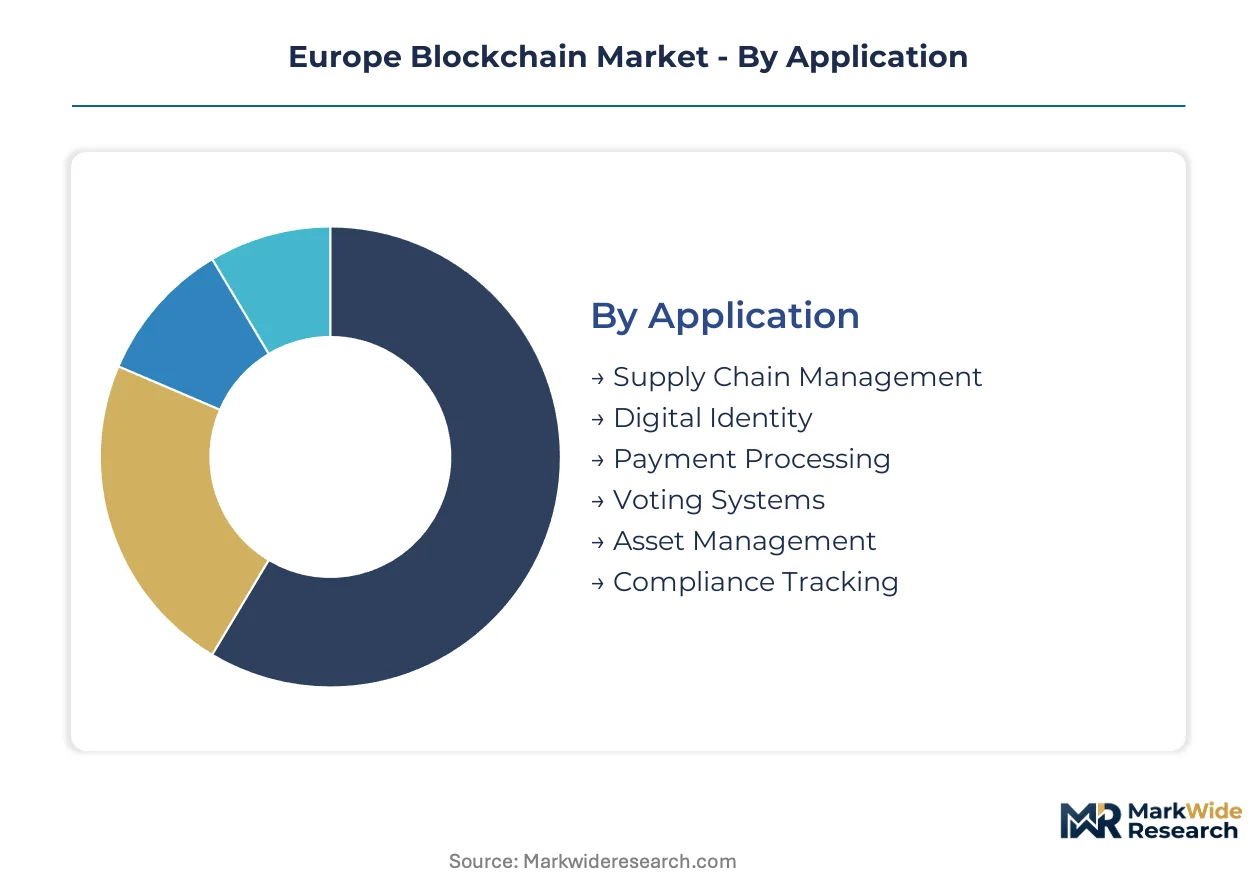
Understanding varied adoption patterns across the European blockchain market requires detailed segmentation analysis. Distinct organizational needs drive specific choices in blockchain application, underlying technology, industry focus, and deployment strategy. This granular view reveals where current value resides and future expansion opportunities concentrate.
Application:
European buyers differentiate by the specific operational problems blockchain solutions are designed to address.
- Supply Chain Management:This application tracks goods across complex networks, ensuring provenance and authenticity for products. Demand for verifiable product integrity accelerates in the EU, driven by stringent import and safety standards.
- Asset Management:This segment includes tokenization of real-world assets and streamlined management of complex securities. The Swiss financial sector leverages blockchain for enhanced settlement efficiency and regulatory compliance.
- Digital Identity:This application creates secure, verifiable digital identities for individuals, relevant for public sector services in Estonia.
- Payment Processing:Blockchain facilitates faster, more secure cross-border payments with reduced intermediaries, attracting European fintech firms.
- Compliance Tracking:Organizations use blockchain for immutable audit trails of data access and processing, supporting adherence to GDPR.
- Voting Systems:This application explores secure, transparent electronic voting mechanisms, enhancing trust and auditability in electoral processes.
Volume sits with Payment Processing; growth tilts toward Supply Chain Management.
Technology:
Technology choices are driven by application requirements, balancing privacy with decentralization and control.
- Private Blockchain:These permissioned networks restrict participation, offering enhanced control, privacy, and auditability for corporate use cases. European enterprises, especially in financial services, favor private blockchain for sensitive data management.
- Smart Contracts:These self-executing agreements automate processes based on predefined conditions, eliminating intermediaries. Smart contracts are central to tokenization and automated compliance within the European financial sector.
- Public Blockchain:Open, decentralized networks like Ethereum allow any participant to join, primarily used for cryptocurrencies and broad decentralized applications.
- Hybrid Blockchain:These solutions combine public and private blockchain elements, allowing selective data sharing and maintaining privacy for transactions.
- Consortium Blockchain:Managed by pre-selected organizations, these semi-decentralized networks foster collaboration among industry partners with governance.
- Distributed Ledger Technology:This foundational technology underpins all blockchain types, providing a decentralized database across multiple nodes.
Enterprise adoption concentrates on Private Blockchain solutions, while Smart Contracts are expanding rapidly for automation.
End User Industry:
Customer type segmentation highlights distinct industry-specific needs and regulatory landscapes driving blockchain adoption.
- Financial Services:This sector leads blockchain adoption for asset tokenization, secure payment processing, and enhanced regulatory compliance. The Swiss financial sector is a prominent hub for these innovations.
- Manufacturing Firms:These companies leverage blockchain for supply chain transparency, product traceability, and complex logistics networks. Demand for verifiable provenance in European automotive and aerospace is significant.
- Government Agencies:Public sector entities explore blockchain for digital identity, land registries, and secure data management in Estonia.
- Healthcare Providers:This industry investigates blockchain for secure patient data, pharmaceutical supply chain integrity, and clinical trial verification.
- Telecommunications Firms:Blockchain applications include identity management, fraud prevention, and secure billing systems across mobile networks.
- Energy Operators:This sector uses blockchain for peer-to-peer energy trading, grid management, and tracking renewable energy credits.
Financial Services drives current market value; future expansion stems from Manufacturing Firms.
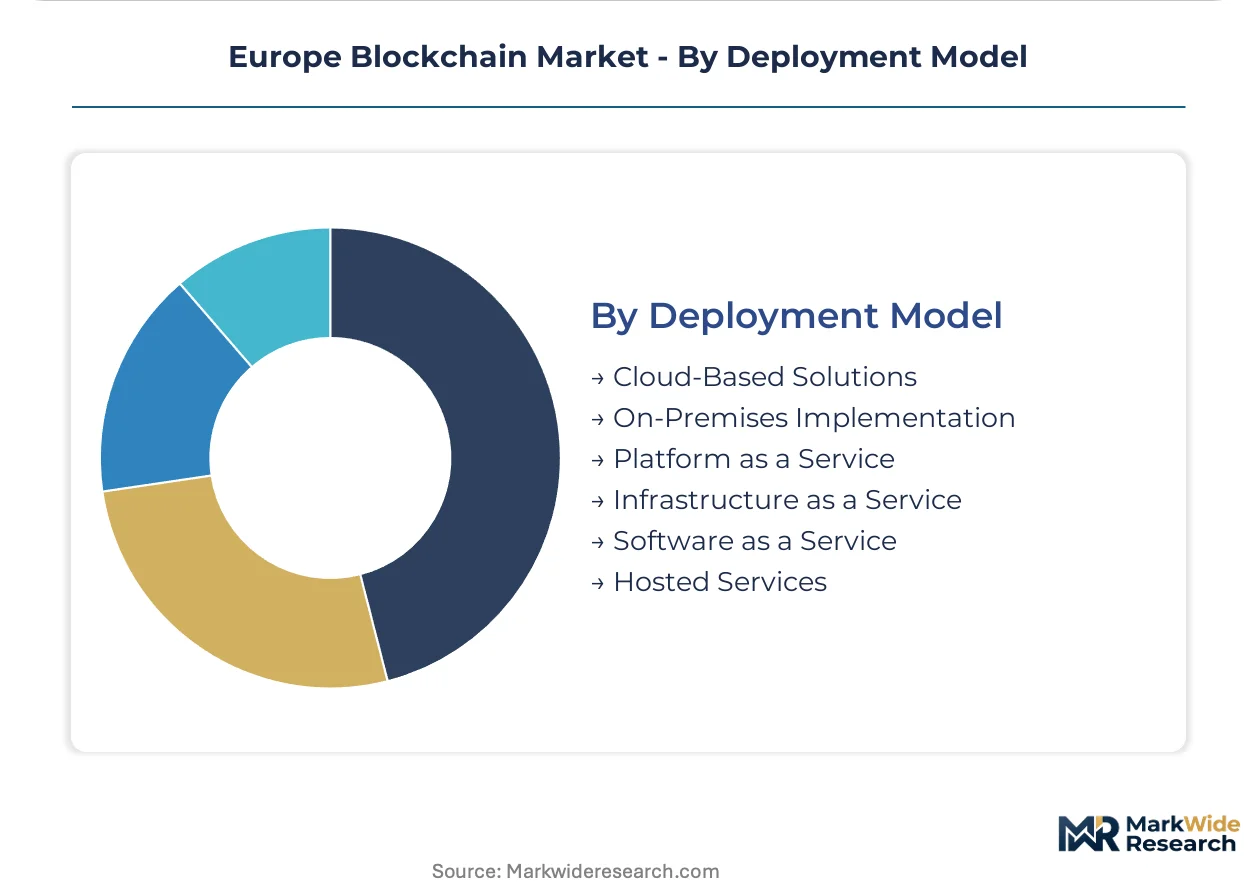
Deployment Model:
Deployment model choices reflect organizational maturity regarding infrastructure control, scalability, and operational expenditure.
- Cloud-Based Solutions:These models offer flexible, scalable blockchain services hosted by third-party providers, reducing upfront infrastructure costs. Cloud solutions accelerate deployment timelines and lower maintenance burdens.
- Platform as a Service:PaaS provides a complete development and deployment environment for blockchain applications, abstracting infrastructure management. This model supports rapid application development and iteration for European tech firms.
- On-Premises Implementation:Organizations host blockchain nodes in their own data centers, providing maximum control and security for sensitive operations.
- Infrastructure as a Service:IaaS offers virtualized computing resources over the internet, allowing companies to build and manage their own blockchain networks.
- Software as a Service:SaaS delivers pre-built blockchain applications over the web, requiring minimal setup and offering immediate utility.
- Hosted Services:Third-party providers manage and operate blockchain networks for clients, balancing control with outsourced management.
Enterprises prioritize Cloud-Based Solutions for immediate needs; Platform as a Service gains traction for scalability.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Swiss financial sector, a prominent European hub, drives significant blockchain adoption, particularly for asset tokenization. This sector leverages distributed ledger technology for streamlining complex securities management. Regulatory frameworks like MiCA further influence compliant platform design across the region, fostering specialized innovation.
Switzerland
Switzerland's financial sector actively pioneers blockchain for high-value asset tokenization and secure payment processing. Swissmedic and FINMA regulations guide the development of compliant crypto-finance solutions, attracting significant investment. Zurich and Geneva remain key centers for fintech innovation, concentrating specialized asset management and high-net-worth client solutions.
Germany
Germany's industrial sector demands verifiable provenance for complex supply chains and manufacturing processes. GDPR compels organizations to adopt blockchain solutions with immutable audit trails for transparent data processing and access. Bavaria and North Rhine-Westphalia are hubs for enterprise-grade platform development, particularly within the automotive and logistics sectors.
United Kingdom
The United Kingdom's financial services industry explores blockchain for enhanced settlement efficiency and capital markets modernization. Regulatory sandboxes from the FCA foster innovation in digital asset platforms and tokenization, supporting emerging fintechs. London remains a global fintech capital, attracting substantial investment in blockchain-based financial infrastructure and distributed ledger research.
France
France exhibits strong interest in digital identity solutions and public sector applications of blockchain technology. GDPR compliance requirements influence the design of secure data management systems for French enterprises and government initiatives. Paris is a growing center for blockchain research and development, particularly in areas like e-governance and verifiable digital credentials.
Europe Blockchain Market Key Industry Players
Premium-margin players sit above commodity-margin players across the solution complexity and customization dimension. The market exhibits a tiered structure, with specialized protocol developers and enterprise solution providers occupying the higher end. Strategic archetypes include core protocol developers, application layer integrators, and industry-specific platform builders focused on compliance. Dominant competitive moves involve strategic partnerships for ecosystem expansion and technology licensing to broaden market adoption.
Specialists in crypto-finance and enterprise blockchain solutions anchor various market segments, catering to distinct client needs across Europe. Bitcoin Suisse exemplifies a crypto-finance and asset management specialist, targeting high-value clients within the demanding Swiss financial sector with bespoke offerings. Consensys represents a key player leveraging deep expertise in the Ethereum ecosystem to build custom enterprise applications for diverse industries requiring robust infrastructure. Meanwhile, Polygon occupies a position as a provider of scaling solutions, enhancing transaction performance and significantly reducing costs on public blockchains for broader accessibility and developer engagement.
| Leading Market Players |
|---|
| IdeaSoft |
| Polygon |
| Ripple |
| Bitcoin Suisse |
| Consensys |
| Blockstream |
| LimeChain |
| SKALE Labs |
| ChainSafe |
| Others |
Cost & Logistics Intelligence
European financial services institutions increasingly demand enterprise-grade private blockchain solutions, which significantly shapes the project-based pricing models prevalent in this market. This concentration of high-value buyers allows for premium service offerings.
Pricing Analysis
Value-based pricing anchors many blockchain solutions, particularly for complex compliance tracking and asset management. Project-based and subscription-tiered models dominate, reflecting the customization level and integration complexity required for enterprise deployment. Price differentiation stems from regulatory compliance certifications like GDPR adherence and the availability of specialized talent. Pricing softness stems from increasing competition from open-source alternatives and scaling solutions, making small and medium-sized enterprises the most price-sensitive buyers.
Supply Chain Analysis
Direct distribution channels manage the supply of specialized blockchain solutions across Europe, particularly for large financial institutions and industrial firms. Key development hubs concentrate in Switzerland for fintech, Germany for industrial applications, and the UK for capital markets infrastructure. The supply chain relies on a steady stream of specialized software developers, robust cloud infrastructure, and advanced cryptographic libraries. Talent scarcity presents a significant structural risk, alongside evolving regulatory frameworks and interoperability barriers between platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Europe blockchain market is supply-constrained, with specialized talent scarcity and high implementation costs acting as key capacity bottlenecks that prop up pricing for custom solutions.
For Market Incumbents: Anchor existing market share by deepening strategic partnerships with cloud providers and enterprise software vendors for integrated solutions. Invest in R&D for privacy-enhancing technologies like Zero-Knowledge Proofs to address GDPR and MiCA compliance. Expand technology licensing to broaden market adoption and establish industry standards against open-source threats.
For New Entrants and Emerging Players: A price-point gap exists between premium enterprise solutions and basic public ledger services, offering opportunities for agile new entrants. Target digital identity solutions for public sector applications in markets like Estonia, focusing on ease of integration. Penetrate the ESG reporting and verification segment with cost-effective, SaaS-based platforms tailored for European supply chains.
For Investors and Strategic Acquirers: The window for entry favors strategic acquirers consolidating fragmented expertise in specific blockchain applications or regional markets. Long-term viability for investments hinges on companies demonstrating verifiable compliance and delivering operational efficiencies over the next decade. Watch for successful large-scale deployment of cross-border, multi-jurisdictional blockchain applications.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Enhance interoperability across diverse blockchain networks for seamless data exchange. |
| Strategic Partnership | Extend market reach and co-develop industry-specific solutions with established enterprises. |
| Technology Licensing | Broaden adoption of proprietary scaling solutions for public and private blockchains. |
| Acquisition of Specialist Firm | Gain expertise in Zero-Knowledge Proofs or digital identity solutions for compliance. |
| Geographic Expansion | Target underserved European regions with specific regulatory or industrial compliance needs. |
Research Approach
Industry reports, academic journals, and government publications formed the secondary backbone, complemented by primary interviews. We engaged blockchain architects, financial regulators like FINMA and FCA, supply chain managers, and IT procurement officers across Europe. This approach ensured a balanced perspective, triangulating bottom-up market insights with top-down strategic validation.
A bottom-up aggregation of segment data, validated through top-down market sizing, defined the forecast framework across the analysis window. Segmentation dimensions included application type, technology, end-user industry, deployment model, and regional regulatory environment. CAGRs were derived from historical growth rates, projected market drivers, expert consensus, and regulatory enforcement timelines for MiCA.
Inputs from industry reports and expert interviews were available through the study window; gaps in specific real-world deployment data introduce uncertainty bands. Forecasts reflect assumptions regarding regulatory stability and technological adoption rates. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Blockchain Technology
Blockchain in Mining Market
Blockchain Technology
Global Blockchain Software Market
Blockchain Technology
Managed Blockchain Services Market
Blockchain Technology
Global Blockchain for Non-Profits Market
Blockchain Technology
Decentralized Identity Market
Blockchain Technology
Global Blockchain Government Market
Blockchain Technology
Blockchain in Smart Home Market
Blockchain Technology
Blockchain AI Market
Blockchain Technology
Global Blockchain in Energy Market
Blockchain Technology
Global Blockchain Supply Chain Market
Blockchain Technology
Global Blockchain IoT Market
Blockchain Technology
Global Blockchain in Telecom Market
Blockchain Technology
Blockchain Technology in Energy Market
Blockchain Technology
Bitcoin Technology Market
Blockchain Technology
Global Blockchain in Agriculture and Food Supply Chain Market
Blockchain Technology
Automotive Blockchain Market