
 Global Blockchain in Energy Market | 2026-2036
Global Blockchain in Energy Market Size, Share, and Industry Trends Forecast 2026-2036
Global Blockchain in Energy Market Foresight
The gap between enterprise-grade blockchain infrastructure and lightweight commodity protocols is broadening. IBM Corporation leverages its Hyperledger fabric to anchor high-assurance grid management contracts for major European utilities. Power Ledger differentiates through specialized peer-to-peer energy trading architectures optimized for prosumer microgrids. Microsoft Corporation competes by extending Azure-based blockchain services that integrate with existing utility ERP systems.
Blockchain in energy refers to cryptographically secured distributed ledger systems that record immutable transaction chains across decentralized nodes, typically achieving consensus through proof-of-stake or Byzantine fault-tolerant mechanisms optimized for high-throughput metering data. These platforms enable automated settlement, provenance verification, and disintermediated asset registration across electricity markets. Smart contracts within energy trading applications are capturing the fastest margin expansion as automated execution reduces counterparty risk and settlement latency. Private blockchain deployments dominate current utility procurement due to stringent data sovereignty requirements, though consortium models are gaining traction among regional grid operators seeking shared infrastructure without full public exposure.
The EU Green Deal and F-Gas Regulation shape European utility blockchain roadmaps by mandating granular emissions traceability that only distributed ledgers can cost-effectively deliver. In the United States, FERC Order 2222 and state-level net metering reforms are forcing grid operators to adopt transparent settlement mechanisms for aggregated distributed energy resources. India's CEA and BIS are developing blockchain-integrated standards for renewable energy certificate issuance to combat double-counting fraud. Stakeholders must weigh whether to build captive ledger infrastructure or subscribe to emerging utility consortium networks as regulatory granularity tightens.
Market Dynamics
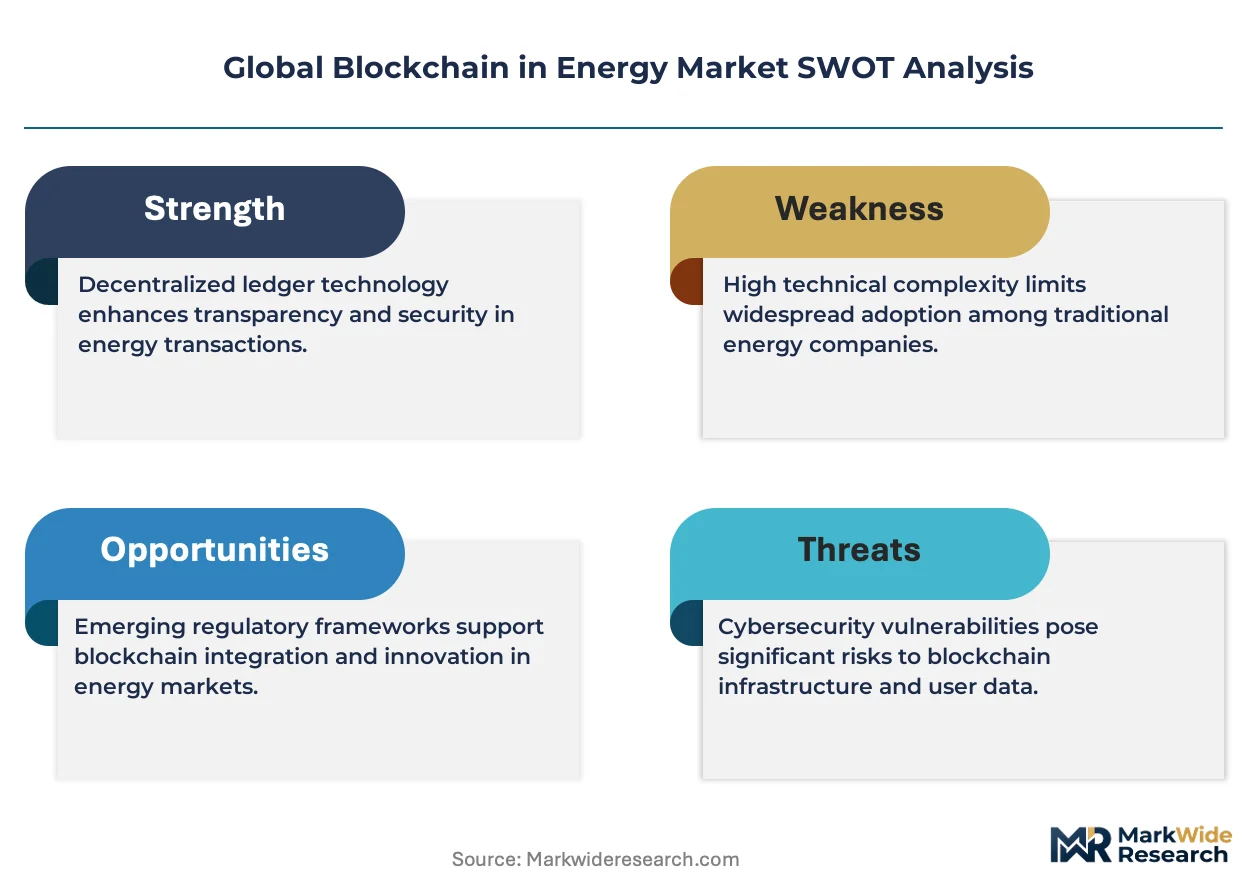
Utility procurement of private blockchain infrastructure is concentrating around emissions traceability mandates, with the EU Green Deal's granular reporting requirements forcing distributed ledger adoption faster than legacy database upgrades can accommodate.
Growth Catalysts
- EU Green Deal emissions reforms:The trading system overhaul mandates immutable carbon accounting that only blockchain-integrated metering can deliver cost-effectively.
- Prosumer microgrids in Germany:Peer-to-peer energy exchange platforms are drawing capital from residential solar-battery clusters seeking automated settlement.
- FERC Order 2222 in the United States:The rule forces grid operators to adopt transparent mechanisms for aggregated distributed energy resource compensation.
Market Restraints
- High-assurance infrastructure costs:Enterprise-grade Byzantine fault-tolerant nodes require specialized hardware that commodity cloud instances cannot replicate.
- Data sovereignty fragmentation:India's CEA and BIS standards conflict with GDPR storage location rules, complicating cross-border certificate verification.
- Legacy SCADA integration friction:Decades-old grid management systems lack API architectures compatible with smart contract triggers.
Strategic Opportunities
- South Korea's renewable certificate market:KEPCO's blockchain pilot programs create first-mover advantage for ledger providers specializing in anti-fraud issuance.
- Convergence of IoT metering with edge computing:Real-time consensus at the device level reduces latency for automated demand-response contracts.
- Australia's prosumer networks:Regulatory sandboxes in Victoria and Queensland permit experimental peer-to-peer trading architectures outside standard retail frameworks.
Industry Challenges
- Cryptographic talent scarcity:Utilities compete with fintech for engineers skilled in zero-knowledge proof implementations for privacy-preserving settlement.
- Interoperability standard delays:ISO and IEC working groups have yet to finalize cross-chain communication protocols, freezing procurement decisions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Blockchain in Energy Market |
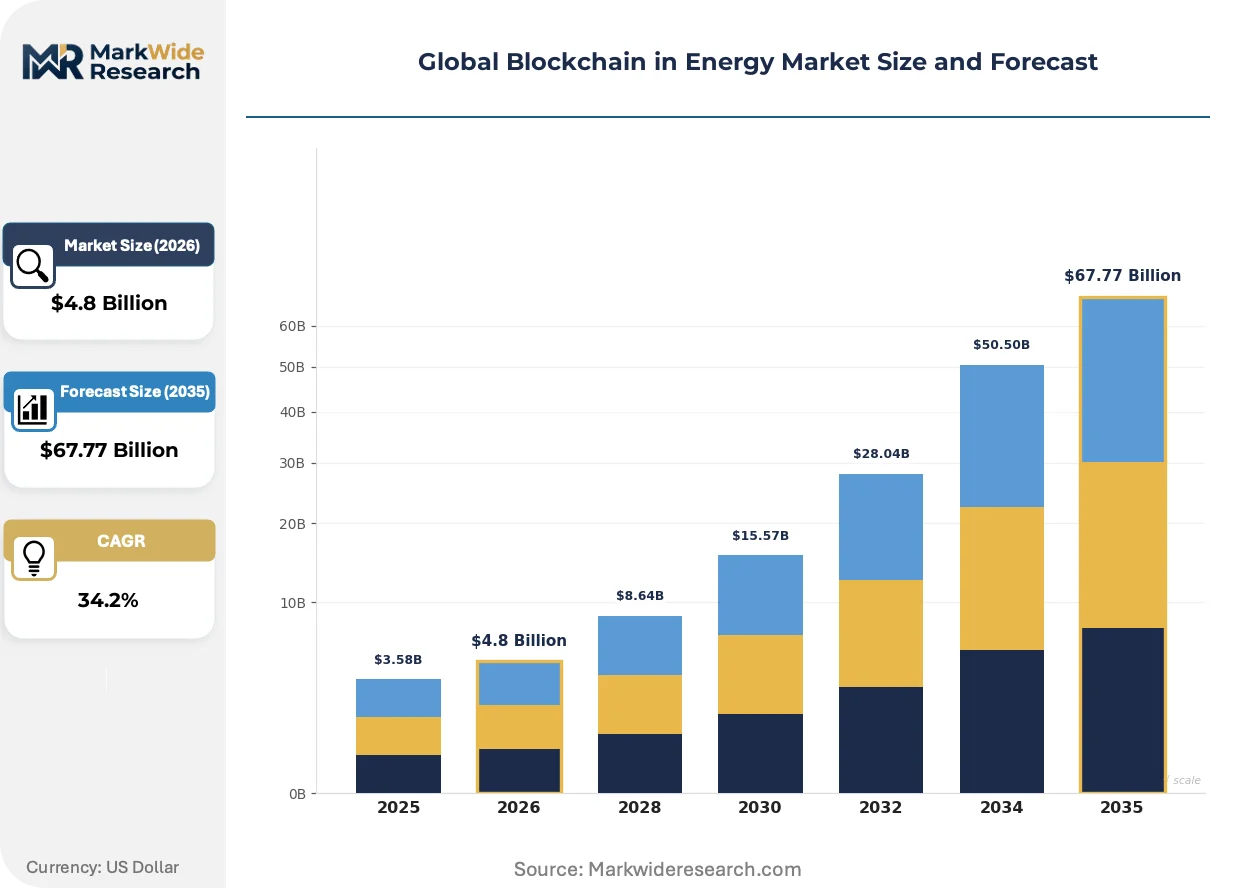
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $67.77 Billion |
| CAGR (2026 – 2036) | 34.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Solution Offering: Distributed Ledger Technology, Smart Contracts, Identity Management, Tokenization, Data Analytics, Asset Tracking Application: Energy Trading, Grid Management, Renewable Integration, Peer-to-Peer Energy Exchange, Regulatory Compliance, Supply Chain Transparency Customer Type: Utility Operators, Energy Producers, Grid Operators, Prosumer Networks, Energy Retailers, Technology Providers Deployment Model: Public Blockchain, Private Blockchain, Consortium Blockchain, Hybrid Blockchain |
| Companies Covered | IBM Corporation, SAP SE, Accenture PLC, Power Ledger, LO3 Energy Inc., Microsoft Corporation, Oracle Corporation, Electron, WePower, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Blockchain in Energy Market Shifts & Advancements
Smart contract automation is compressing settlement cycles from weeks to minutes, while regulatory pressure for supply-chain transparency accelerates ledger deployment beyond pilot phases.
Proof-of-stake consensus mechanisms optimized for high-throughput metering data are rewriting competitive positioning among platform providers. European utilities deploying these architectures achieve sub-second finality for prosumer transactions. The shift is compressing margins for traditional settlement intermediaries while expanding addressable market size for automated contract vendors.
The EU F-Gas Regulation's traceability mandates are forcing refrigerant-intensive grid assets onto immutable ledgers. Industrial consequence includes mandatory upstream documentation for SF6-insulated switchgear across transmission networks. German and French operators are responding fastest, with consortium blockchain procurement outpacing captive infrastructure builds.
Certificate-driven preference shifts are disrupting renewable energy procurement patterns. Corporate buyers in India and the United States now demand blockchain-verified provenance for scope 2 emissions claims. This behavior is most visible among data center operators facing investor pressure for granular hourly carbon matching rather than annualized offsets.
Global Blockchain in Energy Market Segmentation
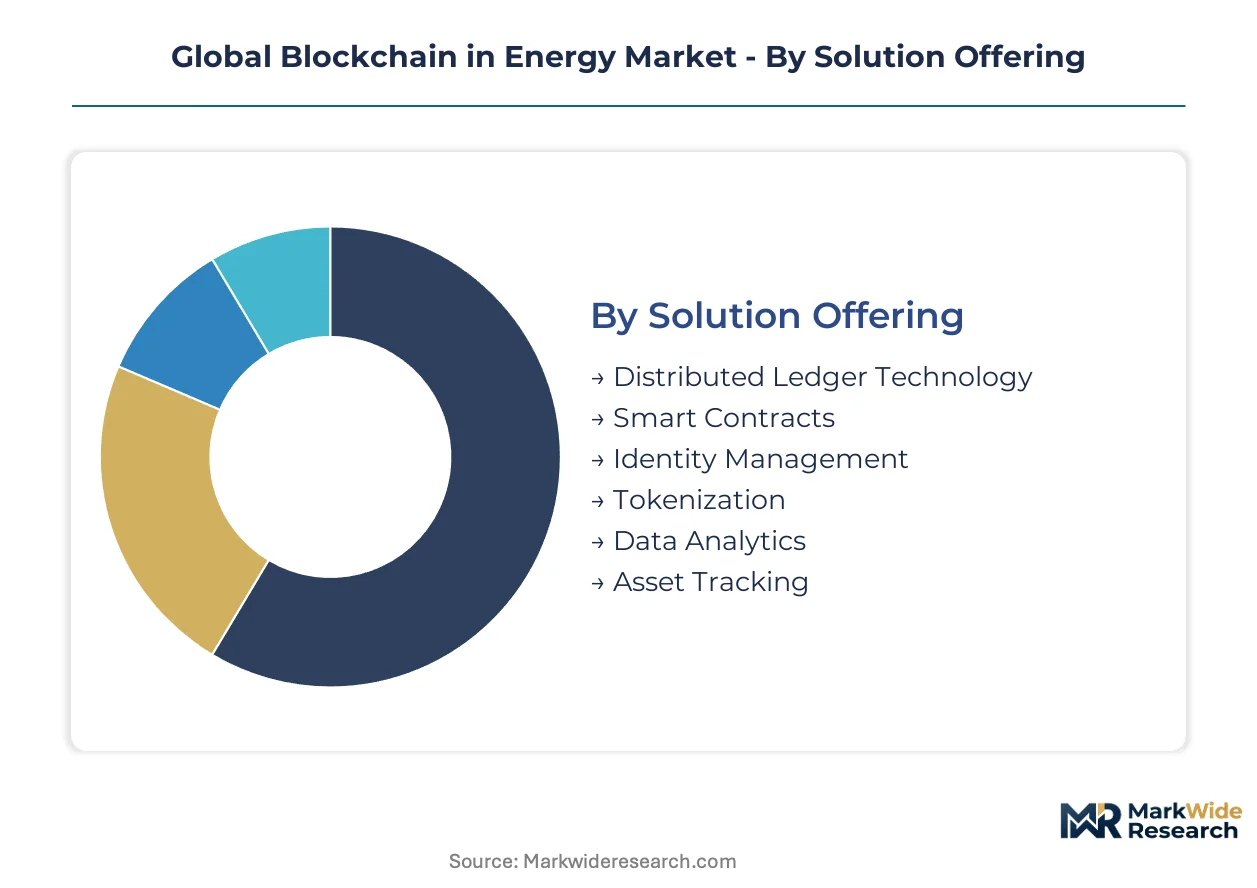
Blockchain in energy deploys across fundamentally different integration depths. Standalone distributed ledger platforms anchor wholesale trading floors, while embedded smart contract modules slot into existing SCADA architectures with minimal disruption.
Solution Offering:
Integration depth varies sharply: distributed ledgers operate as independent infrastructure layers, whereas tokenization and analytics embed as software modules within legacy utility stacks.
- Distributed Ledger Technology:Core infrastructure layer maintaining immutable transaction records across decentralized nodes using Byzantine fault-tolerant consensus. Demand concentrates in German and French transmission utilities facing EU Green Deal emissions traceability mandates with legacy database replacement timelines too slow for regulatory deadlines.
- Smart Contracts:Self-executing code automating settlement, metering verification, and demand-response triggers without intermediary intervention. Australian prosumer networks in Victoria and Queensland deploy these for peer-to-peer energy exchange outside standard retail frameworks, drawn by automated execution reducing counterparty risk.
- Identity Management:Cryptographic credentialing systems for device and participant authentication across permissioned networks.
- Tokenization:Digital representation of physical energy assets and renewable certificates enabling fractional ownership and automated transfer.
- Data Analytics:On-chain aggregation and pattern recognition for grid optimization and predictive maintenance.
- Asset Tracking:Provenance verification for grid infrastructure components and SF6-insulated switchgear under F-Gas Regulation documentation requirements.
Distributed Ledger Technology leads volumes today; Smart Contracts is gaining share fastest.
Application:
Cost tier differentiation separates high-infrastructure trading platforms from lightweight compliance modules.
- Energy Trading:Wholesale and retail transaction settlement platforms replacing centralized exchange infrastructure. South Korean utilities under KEPCO blockchain pilots prioritize these for renewable certificate markets seeking anti-fraud issuance systems.
- Grid Management:Real-time coordination of distributed energy resources, frequency regulation, and outage response. United States grid operators responding to FERC Order 2222 deploy these for transparent compensation mechanisms aggregating residential solar-battery clusters.
- Renewable Integration:Intermittency management and curtailment optimization for wind and solar assets.
- Peer-to-Peer Energy Exchange:Direct prosumer trading architectures bypassing traditional retailer intermediation.
- Regulatory Compliance:Automated reporting and audit trails for emissions and certificate verification.
- Supply Chain Transparency:Upstream documentation for grid equipment procurement and refrigerant-intensive assets.
Grid Management dominates procurement spend currently; Peer-to-Peer Energy Exchange shows steepest expansion trajectory.
Customer Type:
Volume concentration sits with large asset owners, while margin expansion follows specialized network operators.
- Utility Operators:Vertically integrated generation, transmission, and distribution companies deploying private blockchain for internal settlement and regulatory reporting. Indian utilities under CEA and BIS standards development prioritize these for renewable energy certificate issuance to combat double-counting fraud.
- Energy Producers:Independent power producers and renewable developers seeking automated offtake contracting and green attribute monetization.
- Grid Operators:Regional transmission organizations and distribution system operators managing network stability and DER aggregation.
- Prosumer Networks:Residential and commercial clusters with behind-the-meter generation and storage participating in peer-to-peer markets.
- Energy Retailers:Competitive suppliers differentiating through transparent sourcing and automated billing.
- Technology Providers:Platform vendors and systems integrators building captive infrastructure or consortium networks.
Utility Operators anchor current deployment volumes; Prosumer Networks is climbing the fastest.
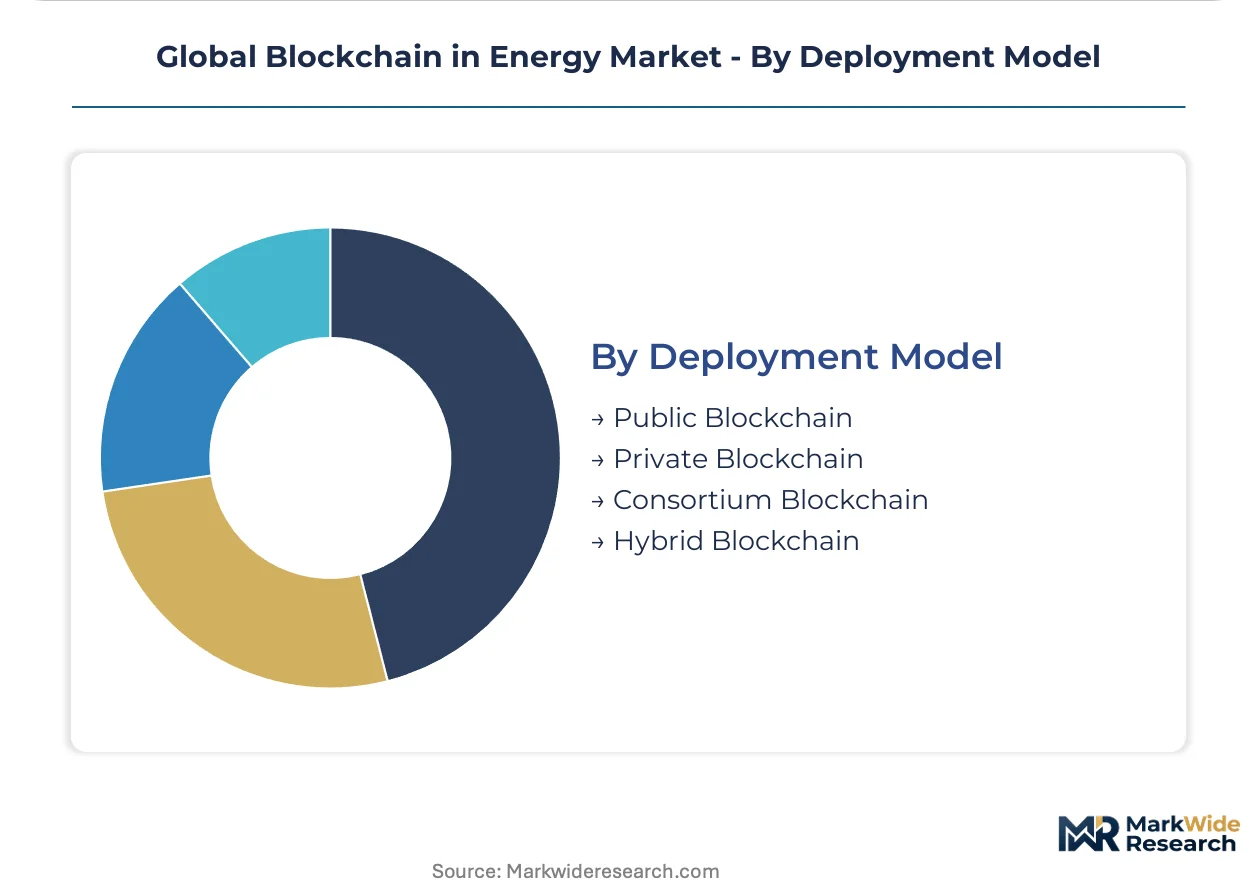
Deployment Model:
Maturity stage determines adoption sequencing: private deployments dominate procurement today as consortium architectures prove interoperability.
- Private Blockchain:Permissioned networks with single-entity governance and restricted node participation. European utilities facing GDPR data sovereignty requirements and granular emissions reporting mandates under EU Green Deal procurement concentrate here, accepting higher infrastructure costs for control assurance.
- Consortium Blockchain:Shared infrastructure with multi-party governance among non-competing grid operators. Regional operators in Germany and France favor these for shared metering data exchange without full public ledger exposure.
- Public Blockchain:Fully decentralized networks with open participation and token-based consensus.
- Hybrid Blockchain:Architectures combining private transaction processing with public settlement anchoring for selective transparency.
Private Blockchain leads procurement decisions today; Consortium Blockchain is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Blockchain engineering talent clusters in Germany, the United States, and South Korea anchor deployment capacity for utility-scale distributed ledger projects. Regulatory pressure for emissions traceability and automated settlement drives procurement decisions across these markets.
United States
Grid operators in Texas and California deploy blockchain architectures for aggregated distributed energy resource compensation under FERC Order 2222. State-level net metering reforms in New York and Massachusetts accelerate transparent settlement mechanism adoption. The PJM Interconnection territory concentrates pilot programs for automated demand-response contracts.
Germany
Residential solar-battery clusters in Bavaria and North Rhine-Westphalia drive peer-to-peer energy exchange platform demand. The EU Green Deal's granular emissions reporting mandates force transmission utilities toward immutable carbon accounting systems. Berlin hosts consortium blockchain procurement for shared metering data exchange among regional grid operators.
South Korea
KEPCO's blockchain pilot programs create procurement concentration for renewable certificate anti-fraud issuance systems. The country's renewable portfolio standards tighten traceability requirements for corporate power purchase agreements. Seoul Capital Area utilities lead deployment of proof-of-stake consensus optimized for high-throughput metering data.
Australia
Prosumer networks in Victoria and Queensland operate experimental peer-to-peer trading architectures outside standard retail frameworks. Regulatory sandboxes in Perth and Adelaide permit automated settlement for residential microgrids with behind-the-meter storage. The National Electricity Market's distributed energy resource integration roadmap accelerates ledger deployment.
India
The Central Electricity Authority and Bureau of Indian Standards develop blockchain-integrated renewable energy certificate standards to combat double-counting fraud. Gujarat and Karnataka utilities prioritize private ledger infrastructure for granular hourly carbon matching demanded by data center operators. Mumbai and Delhi distribution companies pilot automated settlement for corporate green tariff programs.
Global Blockchain in Energy Market Competitive Landscape
Top-tier vendors anchor enterprise-grade infrastructure, while specialized platform developers occupy the application layer. The market structures around three tiers: systems integrators with existing utility relationships, pure-play blockchain architects, and cloud hyperscalers extending energy-vertical services. Consolidation pressure favors vendors with pre-built SCADA interoperability and regulatory compliance modules. Strategic moves concentrate on consortium formation for shared infrastructure and vertical integration into metering hardware.
Within the systems integrator tier, IBM Corporation and Accenture PLC represent archetypes of captive infrastructure builders leveraging existing utility ERP relationships. SAP SE occupies a position bridging enterprise software stacks with ledger modules. Among specialized platform developers, Power Ledger exemplifies peer-to-peer energy trading architecture optimization for prosumer microgrids. Microsoft Corporation and Oracle Corporation sit within the cloud-extension archetype, competing through Azure and cloud-native blockchain services integrated with utility data lakes.
| Leading Market Players |
|---|
| IBM Corporation |
| SAP SE |
| Accenture PLC |
| Power Ledger |
| LO3 Energy Inc. |
| Microsoft Corporation |
| Oracle Corporation |
| Electron |
| WePower |
| Others |
Supply & Pricing Matrix
Enterprise-grade Hyperledger deployments versus commodity cloud protocols bifurcate cost structures across the blockchain energy stack, with high-assurance Byzantine fault-tolerant nodes commanding premiums that lightweight proof-of-stake alternatives cannot match. This tier divergence manifests in procurement patterns: European utilities facing EU Green Deal emissions mandates absorb infrastructure premiums for data sovereignty, while Australian prosumer networks in Victoria and Queensland prioritize cost-minimized edge consensus for peer-to-peer settlement.
Pricing Analysis
Bundled infrastructure-as-a-service contracts dominate enterprise utility procurement, while unbundled modular licensing serves prosumer microgrids seeking component flexibility. Three-tier pricing structure across premium, standard, and economy levels separates captive private ledger builds from consortium subscriptions and open-source adaptations. Cost compression in the standard tier intensifies as Microsoft Azure and Oracle Cloud extend energy-vertical blockchain services with pre-integrated ERP hooks. Data center operators in India and the United States demonstrate lowest price sensitivity, prioritizing blockchain-verified hourly carbon matching over licensing cost.
Supply Chain Analysis
Freight logistics for specialized cryptographic hardware—HSM modules, trusted execution environment chips, and edge consensus devices—draws from concentrated manufacturing clusters in Taiwan, Germany, and South Korea. Component dependencies rest on advanced semiconductor foundry capacity, rare earth magnet supply for metering hardware, and submarine cable infrastructure for cross-border node synchronization. Single-source vulnerability concentrates in Taiwanese chip fabrication for high-throughput metering ASICs. Distribution runs through systems integrators with pre-existing utility SCADA relationships rather than direct vendor-to-operator channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market compounds regulatory tailwinds into structural demand, with FERC Order 2222 and EU Green Deal emissions reforms forcing procurement decisions faster than legacy database migrations can accommodate.
For Market Incumbents: To counter cloud hyperscaler encroachment into utility blockchain services, IBM Corporation and SAP SE must deepen captive infrastructure moats through pre-certified regulatory compliance modules and hardened SCADA interoperability. Backward integration into specialized metering hardware strengthens node assurance claims that commodity cloud instances cannot replicate.
For New Entrants and Emerging Players: Regional grid operator consortiums in Germany and France represent the most penetrable channel partner type for shared infrastructure plays, given procurement freezes pending ISO/IEC cross-chain standard finalization. White-space concentrates in South Korean renewable certificate anti-fraud systems under KEPCO pilot programs and Indian CEA/BIS standards development for double-counting prevention.
For Investors and Strategic Acquirers: Asymmetric upside sits with pure-play platform developers possessing live prosumer network deployments and proven edge consensus optimization. Long-term viability hinges on regulatory granularity tightening rather than technology substitution risk. The signal to watch is ISO/IEC interoperability protocol finalization, which would unlock frozen procurement budgets and validate consortium model economics.
| Strategic Initiative | Industry Significance |
|---|---|
| Consortium Blockchain Formation | Shared infrastructure among German and French grid operators reduces redundant node deployment costs under GDPR constraints. |
| Edge Computing Convergence | Real-time consensus at the device level compresses latency for automated demand-response contracts in Australian prosumer networks. |
| Regulatory Compliance Module Pre-Certification | Pre-built EU Green Deal emissions traceability stacks accelerate procurement decisions for transmission utilities facing reporting deadlines. |
| SCADA Interoperability Investment | API architectures compatible with smart contract triggers unlock decades-old grid management systems for ledger integration. |
| Zero-Knowledge Proof Capability Buildout | Privacy-preserving settlement expertise addresses cryptographic talent scarcity competing with fintech recruitment pools. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary fieldwork with utility planning officers, IPP project developers, EPC contractors, and grid operators with secondary validation against FERC filings, IEA reports, EIA data, and EU emissions trading registry disclosures. Bottom-up segmentation modeling triangulated against top-down macroeconomic anchors to isolate blockchain-specific demand drivers from general utility IT spending trends.
Segment-weighting across the analysis window applied differential growth assumptions to private ledger deployments, consortium architectures, smart contract modules, and tokenization platforms, with regional regulatory framework maturity and grid operator procurement pipeline status serving as key forecast inputs. CAGRs derived from fitted adoption curves calibrated to historical distributed energy resource integration patterns and emissions compliance technology replacement cycles.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to ISO/IEC interoperability standard delays, cryptographic talent availability, and legacy SCADA upgrade budget allocations. A model refresh is warranted upon material change in EU Green Deal enforcement granularity or FERC Order 2222 implementation pace across United States regional transmission organizations.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Blockchain Technology
Blockchain Retail Market
Blockchain Technology
Web 3.0 Blockchain Market
Blockchain Technology
Blockchain AI Market
Blockchain Technology
Blockchain-As-A-Service (Baas) Market
Blockchain Technology
Blockchain Gaming Market
Blockchain Technology
Blockchain in Pharmaceutics Market
Blockchain Technology
Global Blockchain in Telecom Market
Blockchain Technology
Industrial Blockchain Technology Market
Blockchain Technology
Managed Blockchain Services Market
Blockchain Technology
Aviation Transaction Blockchain Market
Blockchain Technology
Automotive Blockchain Market
Blockchain Technology
Blockchain in Energy Utilities Market
Blockchain Technology
Blockchain in Sports Market
Blockchain Technology
Blockchain Game Market
Blockchain Technology
Blockchain in Smart Home Market
Blockchain Technology
Global Blockchain in Logistics Market