
 Europe Handbags Market | 2026-2036
Europe Handbags Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Handbags Market Foresight
Subscription-based care and authentication services is pivoting how European handbag houses monetize ownership beyond the initial sale. LVMH Moët Hennessy Louis Vuitton leverages its proprietary blockchain verification to sustain resale value and consumer trust across secondary markets. Kering anchors its competitive position through controlled vertical manufacturing in Italian tanneries. Chanel differentiates via exclusive atelier access that limits production scarcity.
A handbag constitutes a portable container constructed with stitched panels, reinforced bases, and closure mechanisms designed for personal item transport and aesthetic expression. European production emphasizes vegetable-tanned leather, precision saddle stitching, and metal hardware finishing that meets durability specifications exceeding 10,000 flex cycles. Tote Bags and Crossbody Bags capture the strongest momentum among urban commuters seeking hands-free utility. Leather commands the deepest margin pools due to scarcity of certified European hides and tannery capacity constraints, while Synthetic materials attract sustainability-focused Millennials through lower environmental footprints.
REACH and the EU Green Deal impose chemical disclosure and lifecycle carbon reporting obligations on handbag producers importing materials from outside the European Economic Area. ECHA substance restrictions on chromium VI in leather tanning are forcing reformulation of finishing processes across Italian and Spanish supply chains. France's national anti-waste law extends producer responsibility to repair services, creating compliance costs that favor houses with in-house atelier networks. Stakeholders must monitor how digital product passports under EU Circular Economy Action Plan reshape consumer transparency expectations and sourcing verification costs.
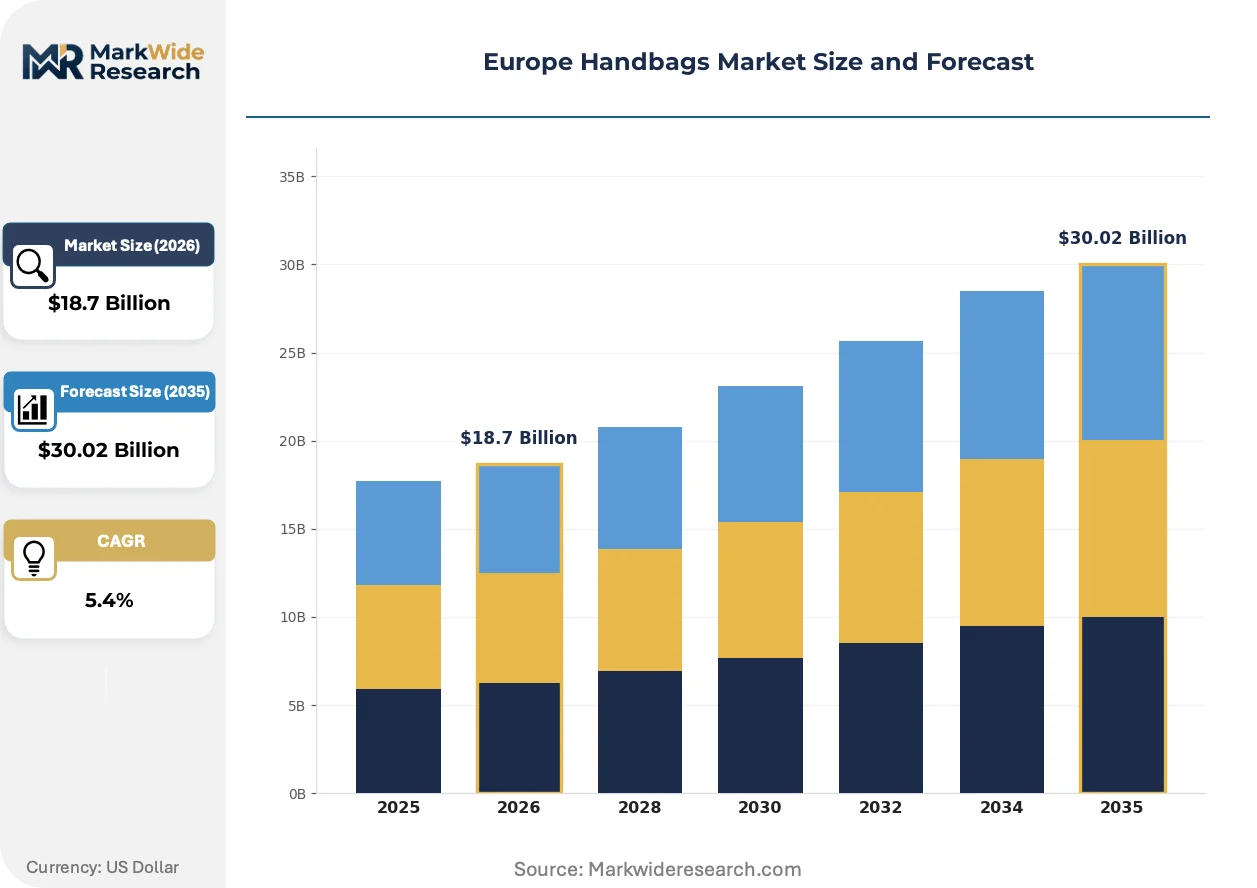
Market Dynamics
REACH chemical disclosure mandates and EU Green Deal carbon transparency requirements are forcing European handbag houses to reconfigure material sourcing and atelier operations. Legacy tannery clusters in Italy and Spain face reformulation pressures that favor vertically integrated houses with captive supply chains.
Growth Catalysts
- EU Circular Economy Action Plan:Digital product passport mandates are accelerating investment in traceability infrastructure. Houses with blockchain-enabled provenance systems capture resale market premiums.
- Vegetable-tanned leather scarcity:Certified European hide supply constraints are deepening margin pools for heritage ateliers with long-term tannery partnerships.
- France's anti-waste law:Extended producer responsibility for repair services creates competitive moats for houses operating in-house restoration networks.
Market Restraints
- Chromium VI restrictions:ECHA substance limitations are forcing Italian and Spanish tanneries to absorb reformulation costs or exit certified supply chains.
- Tannery capacity concentration:Vegetable-tanned leather production clusters in Tuscany and Veneto create geographic single-point vulnerability for premium houses.
- Synthetic material substitution:Bio-based alternatives from Scandinavian suppliers are capturing sustainability-driven Millennial demand at lower price points.
Strategic Opportunities
- Subscription authentication services:Blockchain-verified ownership records open recurring revenue streams beyond initial sale in secondary markets.
- Repair-atelier networks:France's national anti-waste compliance requirements favor houses expanding captive restoration capacity.
- Crossbody and tote specialization:Urban commuter demand for hands-free utility is electrifying growth in functional silhouettes over ceremonial occasion bags.
Industry Challenges
- Saddle-stitching skill scarcity:Precision leathercraft apprenticeship pipelines in France and Italy are failing to replenish retiring atelier artisans.
- Legacy system integration:Digital product passport data architecture must interface with decades-old ERP systems in heritage manufacturing facilities.
- Carbon accounting certification:EU Green Deal lifecycle reporting requirements demand new measurement capabilities across fragmented multi-tier supply chains.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Handbags Market |
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $30.02 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Clutches, Crossbody Bags, Tote Bags, Satchels Material: Leather, Synthetic, Canvas, Nylon Price Range: Luxury, Premium, Mid-range, Budget Customer Profile: Millennials, Working Professionals, Fashion Enthusiasts, Students |
| Companies Covered | Hermès International, Prada, LVMH Moët Hennessy Louis Vuitton, PVH Corp., Fossil Group, Kering, Burberry Group, Chanel, Tapestry, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Handbags Market Shifts & Advancements
Blockchain-enabled provenance verification is electrifying how European houses monetize ownership beyond point-of-sale. Material science advances and regulatory disclosure mandates are simultaneously reshaping sourcing decisions and consumer transparency expectations.
Near-field communication (NFC) chip embedding is electrifying authentication workflows across European luxury houses. Millennial and Gen-Z buyers in France and the United Kingdom are adopting tap-to-verify behaviors at accelerating rates. This hardware integration is electrifying secondary market liquidity by reducing counterparty verification friction.
REACH substance restrictions are compressing chrome-tanning capacity across Italian supply chains. ECHA enforcement of chromium VI limits is forcing tannery consolidation toward compliant facilities in Tuscany. Premium leather goods segments are absorbing reformulation costs while economy-positioned imports face market access barriers.
Direct-to-consumer digital channels are displacing wholesale dependency for heritage houses. Younger buyers in urban France and Germany are completing full-funnel journeys through proprietary apps. This channel compression is most visible among houses investing in augmented reality try-on and virtual atelier experiences.
Europe Handbags Market Segmentation
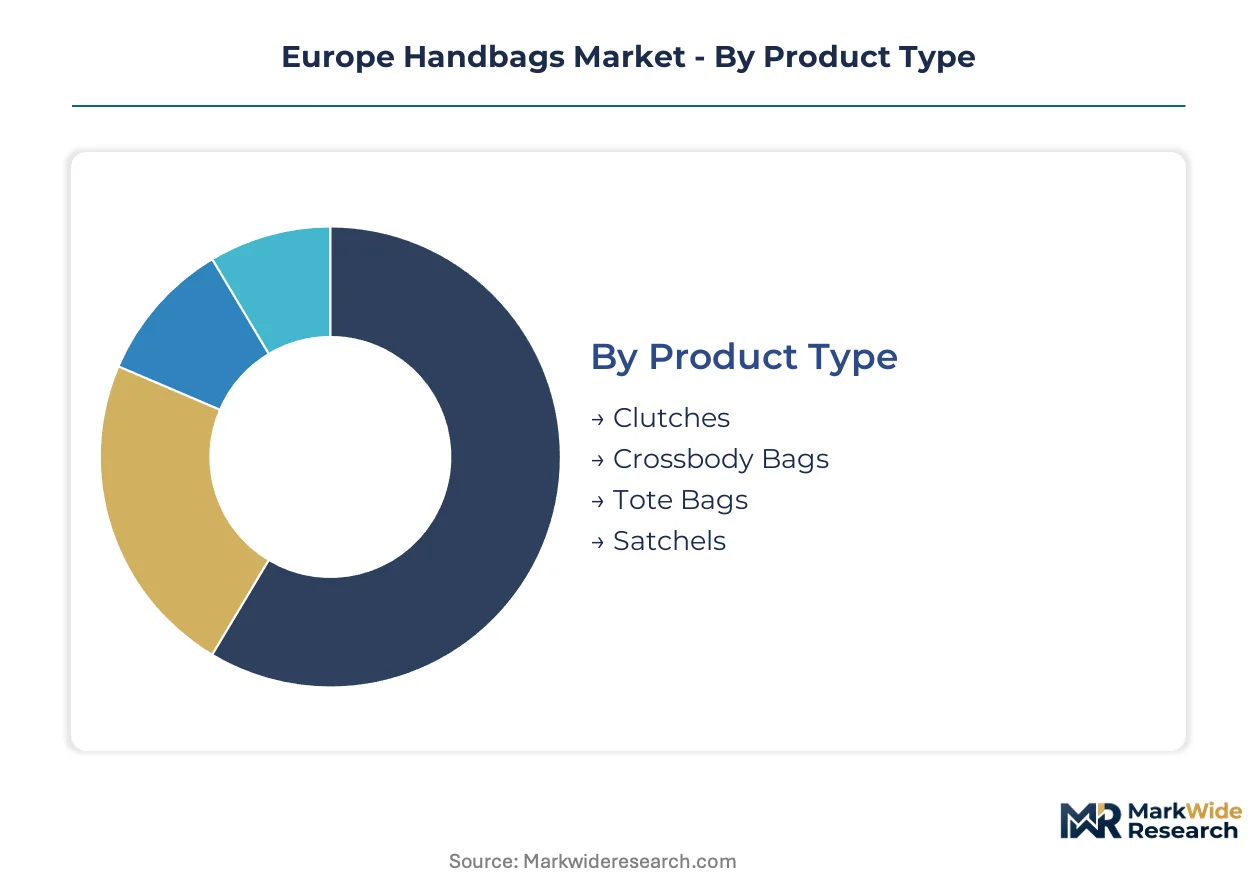
European handbag houses calibrate inventory depth and atelier capacity against distinct upgrade cycles across product silhouettes and price tiers. Replacement frequency varies dramatically between daily commuter pieces and ceremonial occasion bags, dictating margin architecture and resale service investments.
Product Type:
Upgrade cycles compress where urban mobility demands accelerate replacement of high-wear daily carriers.
- Tote Bags:Reinforced base construction and extended shoulder straps accommodate laptop transport and daily commuting loads. Demand concentrates among working professionals in Paris, London, and Milan where public transit dependency drives durability expectations exceeding five-year replacement windows. REACH-compliant hardware finishes add compliance costs absorbed by heritage houses with captive atelier networks.
- Crossbody Bags:Compact panel construction with adjustable webbing or chain straps enables hands-free navigation of dense urban environments. French and German Millennials are adopting these silhouettes fastest for bicycle commuting and festival attendance, prioritizing theft-resistant closure mechanisms over interior volume. NFC chip embedding is electrifying authentication workflows for secondary market liquidity.
- Clutches:Minimalist envelope construction with magnetic or frame closures serves evening and ceremonial occasions. Italian heritage ateliers dominate this segment through precision saddle-stitching.
- Satchels:Structured flap-over designs with buckle or turn-lock closures reference academic and professional heritage. British craft traditions anchor supply concentration in Northamptonshire leatherworking clusters.
Tote Bags sit at the top of the volume ranking, with Crossbody Bags climbing the fastest.
Material:
Cost tier stratification separates certified European supply chains from import-dependent volume production.
- Leather:Vegetable-tanned hides from Tuscan tanneries undergo chromium-free processing meeting ECHA substance restrictions. Scarcity of certified European hides deepens margin pools for houses with multi-decade tannery partnerships in Santa Croce sull'Arno and Arzignano. French anti-waste law repair mandates favor leather's restorability over synthetic alternatives.
- Synthetic:Bio-based polyurethane and recycled nylon formulations from Scandinavian suppliers attract sustainability-driven Millennial demand. Lower carbon footprints under EU Green Deal lifecycle reporting requirements reduce compliance burden for direct-to-consumer digital channels targeting German and Dutch urban buyers.
- Canvas:Woven cotton or linen constructions with coated finishes provide lightweight utility for seasonal collections. Belgian and Portuguese textile mills supply heritage houses seeking material diversification.
- Nylon:High-tenacity woven constructions with water-resistant coatings serve performance-oriented urban commuters. Italian technical fabric specialists in Como anchor supply.
Leather commands the deepest margin pools, with Synthetic materials gaining share fastest among sustainability-positioned entrants.
Price Range:
Customer lifetime value calculations diverge sharply across tiers, with luxury buyers generating recurring authentication revenue.
- Luxury:Hand-finished construction in captive ateliers with proprietary hardware and limited distribution. Houses leverage blockchain verification to sustain resale premiums in secondary markets.
- Premium:Machine-assisted production with hand-finished details and selective retail placement. Italian vertical manufacturing clusters serve this tier.
- Mid-range:Standardized construction with seasonal trend responsiveness and wholesale dependency. Spanish supply chains compete on speed-to-market.
- Budget:High-volume import-dependent sourcing with minimal compliance documentation. REACH enforcement creates market access barriers for non-certified producers.
Luxury sits at the top of the margin ranking, with Premium climbing fastest as houses compress wholesale dependency.
Customer Profile:
Maturity curves and digital channel adoption rates segment procurement patterns across generational cohorts.
- Millennials:Digital-native buyers completing full-funnel journeys through proprietary house apps. Augmented reality try-on and virtual atelier experiences drive conversion in French and German urban markets. Subscription authentication services monetize ownership beyond point-of-sale.
- Working Professionals:Function-first procurement prioritizing durability specifications and repair service availability. France's extended producer responsibility mandates align with this segment's longevity expectations.
- Fashion Enthusiasts:Trend-responsive purchasing with high churn and resale platform engagement. Secondary market liquidity depends on blockchain-verified provenance.
- Students:Price-sensitive demand concentrated in budget and mid-range tiers with synthetic material preference. Scandinavian bio-based alternatives capture this cohort's sustainability positioning.
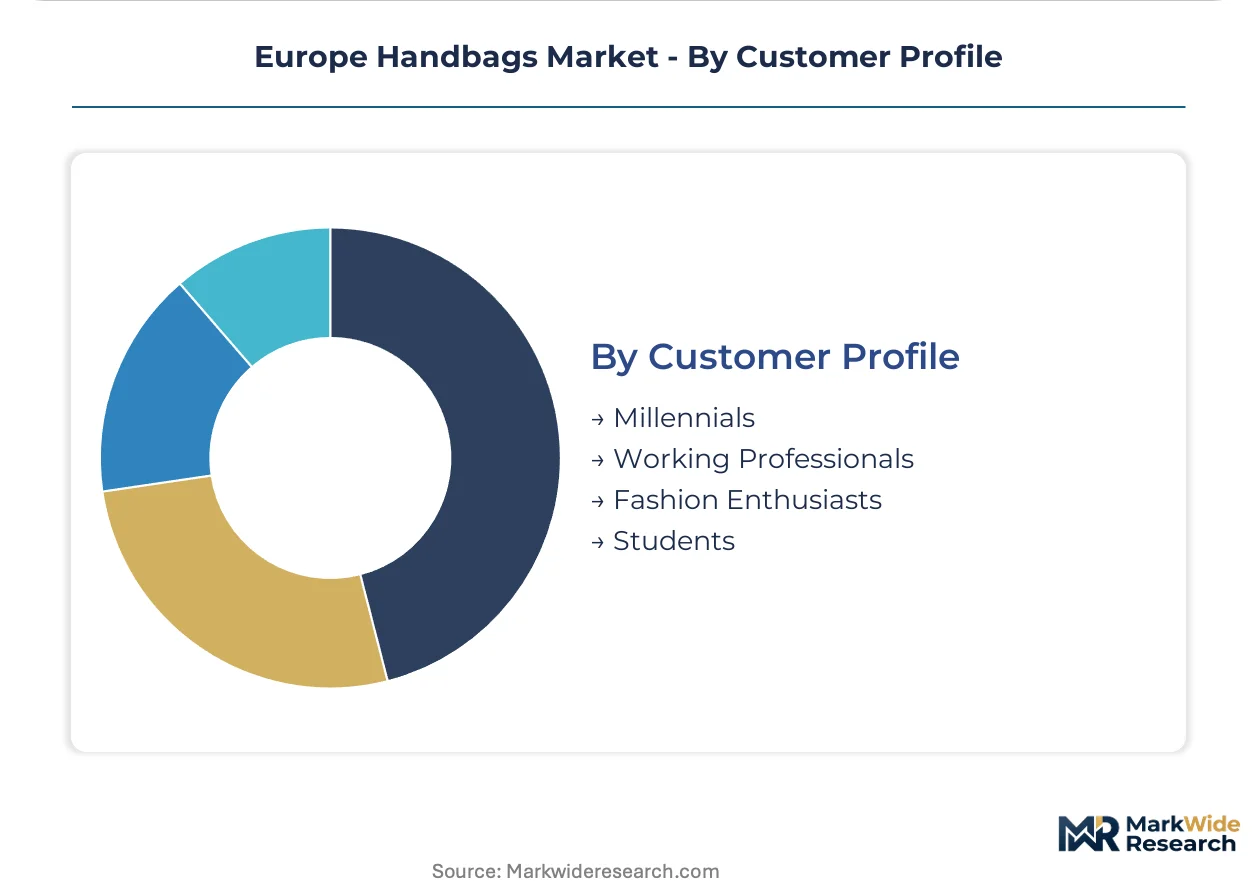
Working Professionals sit at the top of the volume ranking, with Millennials climbing fastest through digital channel migration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
France commands the deepest heritage atelier networks while Italy anchors vegetable-tanned leather production, creating divergent competitive moats across the two largest national markets.
France
Paris-based heritage houses drive demand through direct-to-consumer digital channels targeting Millennial buyers. The national anti-waste law mandates extended producer responsibility for repair services, favoring houses with captive atelier networks in the Île-de-France cluster.
Italy
Tuscan tannery concentration in Santa Croce sull'Arno and Arzignano supplies certified vegetable-tanned hides to premium manufacturers. ECHA enforcement of chromium VI restrictions is compressing compliant tanning capacity toward vertically integrated facilities in Tuscany and Veneto.
United Kingdom
London and Manchester urban commuters prioritize crossbody silhouettes for bicycle navigation and public transit. British craft traditions in Northamptonshire leatherworking clusters sustain satchel production for professional segments seeking heritage construction.
Germany
Berlin and Munich Millennials complete full-funnel purchases through proprietary house apps with augmented reality try-on features. EU Green Deal lifecycle carbon reporting requirements favor synthetic material adoption among sustainability-positioned digital-native buyers.
Spain
Barcelona and Madrid wholesale-dependent mid-range producers compete on speed-to-market for seasonal trend responsiveness. REACH compliance costs create market access barriers for non-certified import-dependent budget producers serving price-sensitive student demand.
Europe Handbags Market Competitive Landscape
Top-tier vendors anchor heritage craftsmanship with captive atelier networks, while mid-range players compete on wholesale speed-to-market. The vendor base stratifies across three strategic archetypes: vertically integrated luxury houses with proprietary tannery partnerships, digitally native direct-to-consumer specialists, and wholesale-dependent volume producers. Dominant competitive moves include backward integration into Tuscan tannery capacity and blockchain-enabled provenance infrastructure deployment.
Within the heritage house tier, Hermès International and LVMH Moët Hennessy Louis Vuitton exemplify vertically integrated positioning through multi-decade tannery partnerships and proprietary authentication systems. Kering occupies a position emphasizing controlled manufacturing clusters in Italian leatherworking regions. These three anchors represent divergent approaches to scarcity management and resale market monetization.
| Leading Market Players |
|---|
| Hermès International |
| Prada |
| LVMH Moët Hennessy Louis Vuitton |
| PVH Corp. |
| Fossil Group |
| Kering |
| Burberry Group |
| Chanel |
| Tapestry |
| Others |
Supply & Pricing Matrix
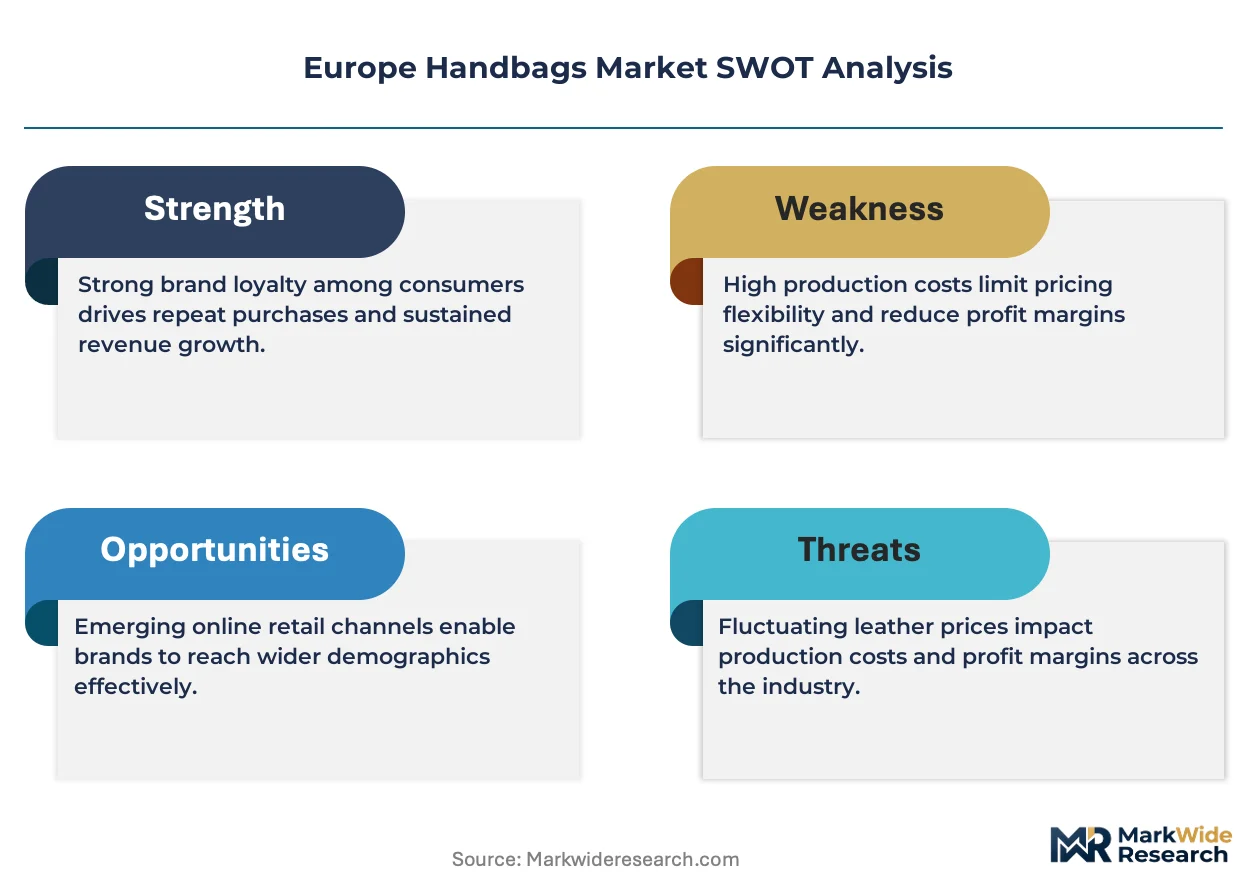
Heritage house procurement concentration in Paris and Milan anchors premium-mid-economy pricing differentiation across European atelier networks. REACH compliance costs and vegetable-tanned leather scarcity deepen margin stratification between captive supply chains and import-dependent volume producers.
Pricing Analysis
Capacity additions in Tuscan tannery clusters are reshaping price floors for certified vegetable-tanned leather segments. Three-tier pricing structure across heritage atelier, premium manufacturing, and economy import levels separates houses with multi-decade tannery partnerships from wholesale-dependent competitors. Cost compression in mid-range synthetic tiers intensifies because Scandinavian bio-based suppliers capture sustainability-driven Millennial demand. Students exhibit highest price sensitivity through budget-tier procurement, while luxury buyers demonstrate lowest sensitivity due to blockchain-verified resale premiums.
Supply Chain Analysis
Direct-to-consumer digital channels handle hyperscale Millennial demand through proprietary house apps with augmented reality integration. Geographic supply concentration centers on Italy for vegetable-tanned leather, France for heritage atelier finishing, and Spain for speed-to-market mid-range production. Raw material dependencies draw from Tuscan hide processors, Belgian textile mills, and Scandinavian bio-based polymer suppliers. Single-source vulnerability in Santa Croce sull'Arno tanning clusters threatens premium house output continuity. Distribution runs through controlled retail flagships, selective wholesale partnerships, and authenticated resale platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
European handbag margins are expanding through repair-service monetization under France's anti-waste law compliance requirements. Premium-tier shift toward subscription authentication services generates recurring revenue beyond point-of-sale.
For Market Incumbents: Acquire Tuscan tannery capacity to secure certified vegetable-tanned leather supply against ECHA chromium VI enforcement compression. Expand captive atelier restoration networks to capture France's extended producer responsibility repair mandates. Bio-based synthetic substitutes from Scandinavian entrants threaten mid-range leather positioning. For New Entrants and Emerging Players: Enter via German and Dutch urban Millennial segments through direct-to-consumer digital channels with EU Green Deal carbon transparency positioning. Target sustainability-credentialed synthetic material tiers where heritage houses maintain wholesale dependency. Augmented reality try-on integration offers differentiated conversion mechanics against legacy flagships. For Investors and Strategic Acquirers: Luxury conglomerates with vertical manufacturing footprints are the most active acquirer in this space. Five-to-ten year viability hinges on blockchain provenance infrastructure deployment and repair-atelier network density. Watch ECHA substance restriction expansion timelines as inflection indicator for tannery consolidation velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Tannery Backward Integration | Captive supply of REACH-compliant vegetable-tanned leather from Tuscan clusters secures margin pools against reformulation cost absorption. |
| Blockchain Provenance Deployment | NFC chip embedding and distributed ledger verification sustain resale premiums in secondary markets across French and British urban centers. |
| Repair-Atelier Network Expansion | In-house restoration capacity captures France's anti-waste law compliance requirements while generating recurring service revenue. |
| Direct-to-Consumer Channel Launch | Proprietary app ecosystems with augmented reality try-on displace wholesale dependency for Millennial acquisition in Berlin and Munich. |
| Sustainability Repositioning | Bio-based synthetic material adoption reduces EU Green Deal lifecycle carbon reporting burden for German and Dutch digital-native buyers. |
Research Methodology
Direct dialogue with heritage house supply chain directors, Tuscan tannery operators, French regulatory compliance officers, and German Millennial buyer panels grounded qualitative assessment. Secondary validation drew from ECHA substance restriction filings, EU Circular Economy Action Plan implementation guidance, French anti-waste law regulatory texts, and Italian leather industry association capacity reports. Bottom-up atelier capacity modeling triangulated against top-down national market value reconstruction.
Bottom-up volume estimates aggregated individual house production disclosures across luxury, premium, and mid-range tiers. Top-down value projections calibrated against national retail audit data and customs import records. Segmentation dimensions spanned product silhouette, material certification grade, price tier, and generational cohort adoption curve. CAGRs derived from fitted growth curves against historical replacement frequency patterns and digital channel penetration trajectories. Vegetable-tanned leather supply constraints and REACH compliance cost pass-through assumptions informed margin trajectory modeling.
Inputs from ECHA enforcement schedules and tannery partnership disclosure filings were available through the study window; gaps in private house atelier capacity utilization rates introduce uncertainty bands around premium tier volume allocations. Forecasts reflect documented assumptions on digital channel migration velocity and regulatory enforcement timelines. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Luxury Goods
China Luxury Goods Market
Luxury Goods
Germany Luxury Goods Market
Luxury Goods
GCC Luxury Goods Market
Luxury Goods
France Luxury Goods Market
Luxury Goods
Luxury Pen Market
Luxury Goods
India Watch Market
Luxury Goods
Russia Luxury Goods Market
Luxury Goods
Used Luxury Bags Trading Service Market
Luxury Goods
Spain Luxury Jewelry Market
Luxury Goods
UAE Luxury Jewelry Market
Luxury Goods
Pre-Owned Luxury Watches Market
Luxury Goods
Singapore Luxury Goods Market
Luxury Goods
GCC Secondhand Luxury Goods Market
Luxury Goods
Luxury Resale Platform Market
Luxury Goods
Spain Luxury Goods Market
Luxury Goods
Luxury Piano Market