
 India D2C E-Commerce Market | 2026-2036
India D2C E-Commerce Market Size, Share, and Industry Trends Forecast 2026-2036
India D2C E-Commerce Market Foresight
Digital marketing talent scarcity in tier-two cities is unwinding as vocational institutes and platform-led skilling programs expand graduate pipelines. Mamaearth leverages its in-house supply chain to control ingredient sourcing across Ayurveda-inspired personal care. Plum anchors its positioning through science-backed vegan formulations that sustain premium pricing. Atomberg competes on energy-efficient appliance design, dominating ceiling fan replacement cycles in urban Indian households.
India D2C E-Commerce denotes brands selling directly to end consumers through proprietary digital channels, bypassing traditional retail intermediaries, with operations dependent on integrated warehouse management systems, last-mile logistics APIs, and real-time inventory dashboards. The model's primary purpose is capturing full-margin transactions while accumulating first-party customer data for cohort-based retention marketing. Apparel and cosmetics command the deepest margin pools due to repeat purchase frequency and influencer-driven discovery, while electronics growth reflects rising local assembly under government incentive structures. Mobile App and Social Media sales channels are expanding fastest as vernacular short-video commerce reshapes conversion funnels, though Website transactions retain higher average order values from established customer segments.
BIS certification requirements for electronics and FSSAI labeling mandates for cosmetics shape product development timelines and market access thresholds for emerging D2C entrants. RBI's digital payment regulations and data localization norms further constrain cross-border platform architectures while privileging domestic fintech integrations. Stakeholders must monitor evolving DPDP Bill compliance obligations and state-level e-commerce taxation harmonization as these frameworks will determine customer acquisition cost structures and data monetization feasibility.
Market Dynamics
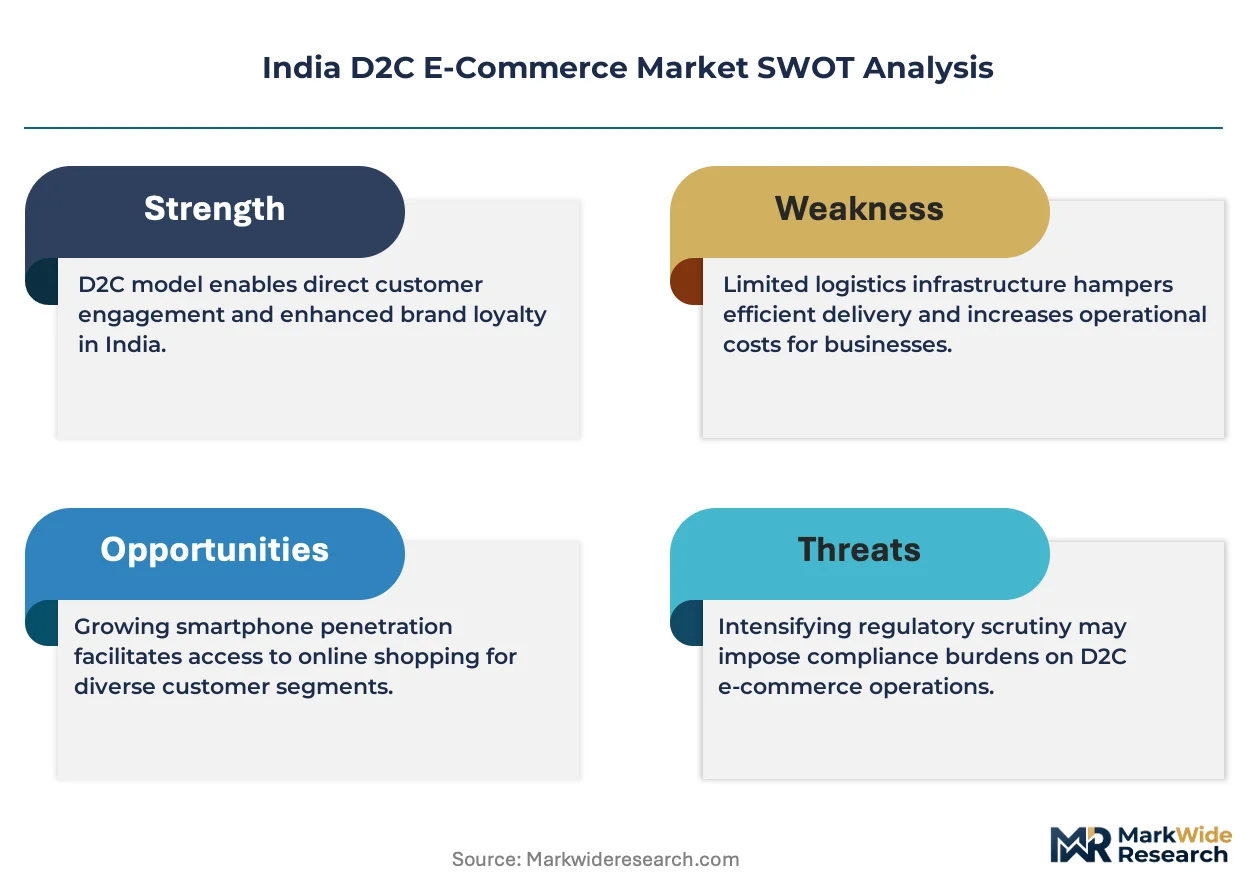
Smartphone-first discovery journeys in tier-two and tier-three cities are compressing traditional brand-building timelines while expanding addressable household penetration for direct-to-consumer operators.
Growth Catalysts
- PLI scheme for electronics manufacturing:Domestic assembly incentives under India's production-linked incentive framework are lowering landed costs for appliance and gadget D2C brands while shortening import-dependent supply chains.
- Vernacular short-video commerce:Reels and short-form video platforms in regional languages are collapsing upper-funnel discovery costs for beauty and personal care entrants targeting non-metro consumers.
- FSSAI labeling mandates:Tightened cosmetics disclosure requirements are accelerating compliance investments that favor organized D2C players with captive quality control over unbranded marketplace sellers.
Market Restraints
- Last-mile logistics cost volatility:Fuel price fluctuations and inter-state octroi variations compress margins for D2C operators serving pin codes beyond established fulfillment clusters in Maharashtra and Karnataka.
- Payment gateway concentration:Dominance of three domestic fintech aggregators creates single-point vulnerability for transaction processing during RBI-mandated maintenance windows or compliance updates.
- Return logistics friction:Apparel and cosmetics categories face elevated reverse logistics costs from sizing mismatches and shade variations, eroding unit economics in tier-three markets with sparse consolidation nodes.
Strategic Opportunities
- Assam and Northeast corridor:Underpenetrated D2C adoption in Guwahati and Imphal offers first-mover positioning as digital payment infrastructure expands through India Post Payments Bank partnerships.
- Ayurveda-inspired personal care:Regulatory tailwinds from AYUSH Ministry quality certifications enable premium positioning for ingredient-transparent brands sourcing from Madhya Pradesh and Uttarakhand herb clusters.
- WhatsApp Commerce API integration:Conversational checkout flows through Meta's business messaging platform are opening direct purchase channels that bypass search-dependent discovery entirely.
Industry Challenges
- Warehouse management system integration:Legacy ERP architectures at third-party logistics providers create inventory synchronization failures during flash sale volume spikes.
- BIS certification timelines:Electronics D2C entrants face six-to-eight month approval windows for safety testing that delay product launches against faster-imported alternatives.
- Data localization compliance:DPDP Bill storage requirements force re-architecture of customer analytics pipelines originally built on cross-border cloud infrastructure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | India D2C E-Commerce Market |
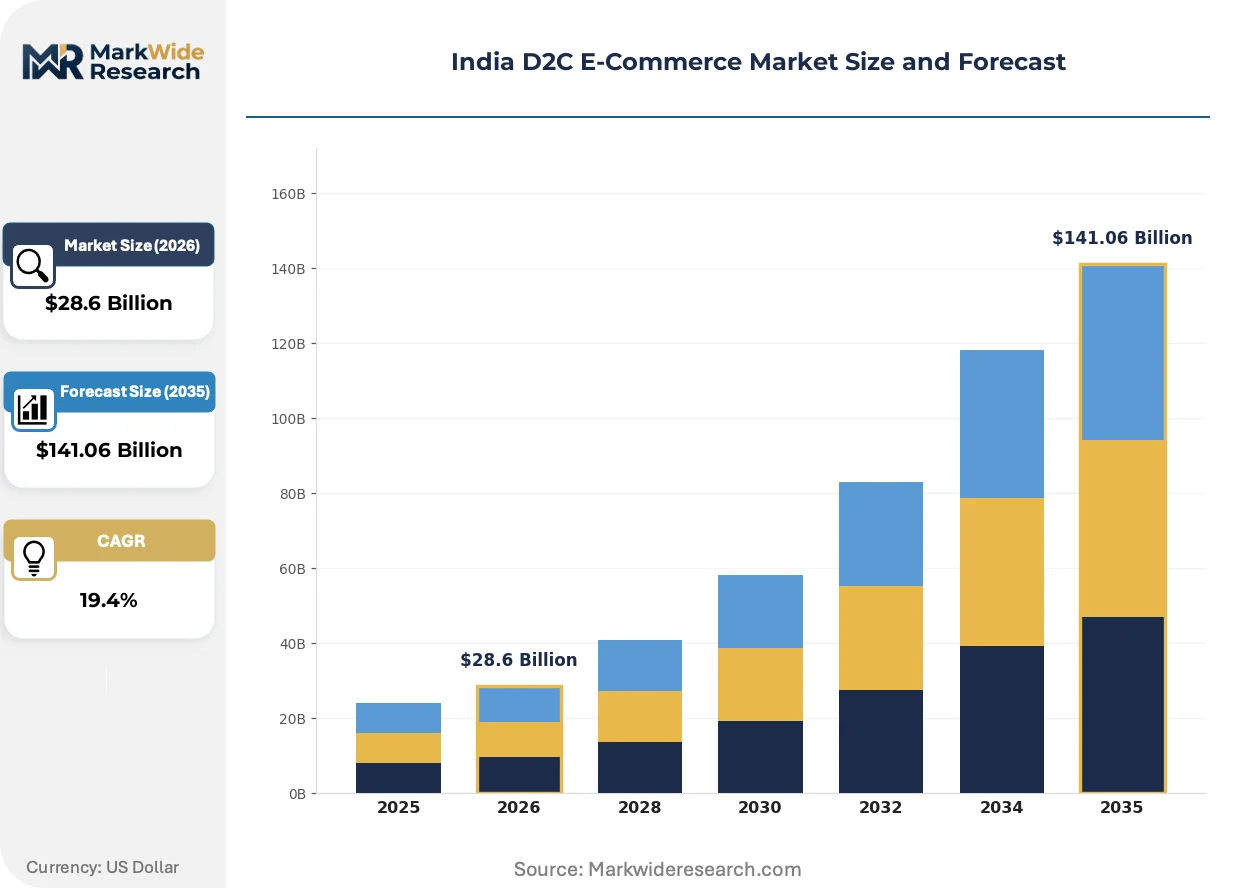
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $141.06 Billion |
| CAGR (2026 – 2036) | 19.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Apparel, Electronics, Home Goods, Cosmetics Sales Channel: Website, Mobile App, Social Media, Marketplace Customer Type: Millennials, Gen Z, Professionals, Households Delivery Model: Same-Day Delivery, Standard Shipping, Click and Collect, Subscription |
| Companies Covered | Lahori Zeera, Plum, Atomberg, MyGlamm, Mamaearth, Pilgrim, Mokobara, Bewakoof, SNITCH, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
India D2C E-Commerce Market Shifts & Advancements
Commerce infrastructure is fragmenting across proprietary apps, social platforms, and messaging interfaces, forcing D2C operators to architect omnichannel stacks rather than single-channel dependence.
AI-powered visual search is fragmenting text-based product discovery. Beauty and personal care shoppers in Delhi NCR and Bangalore now upload reference images to find shade matches and ingredient analogues. This compression of search friction is displacing traditional filter-based navigation, forcing catalog taxonomy redesigns across proprietary apps.
FSSAI's 2024 cosmetic labeling amendments mandate QR-code-linked ingredient provenance disclosure. Domestic D2C brands must retrofit packaging workflows and supplier documentation systems to comply. The regulation most affects Ayurveda-positioned personal care lines, which are accelerating blockchain-traceability pilots to substantiate farm-to-face claims.
Subscription-based replenishment models are displacing one-time purchase behavior in personal care and nutrition categories. Urban Indian households in Mumbai and Pune now favor auto-ship programs for consumables with predictable usage cycles. This shift compresses customer lifetime value realization timelines while elevating churn risk from payment method expiration in UPI-dominant wallets.
India D2C E-Commerce Market Segmentation
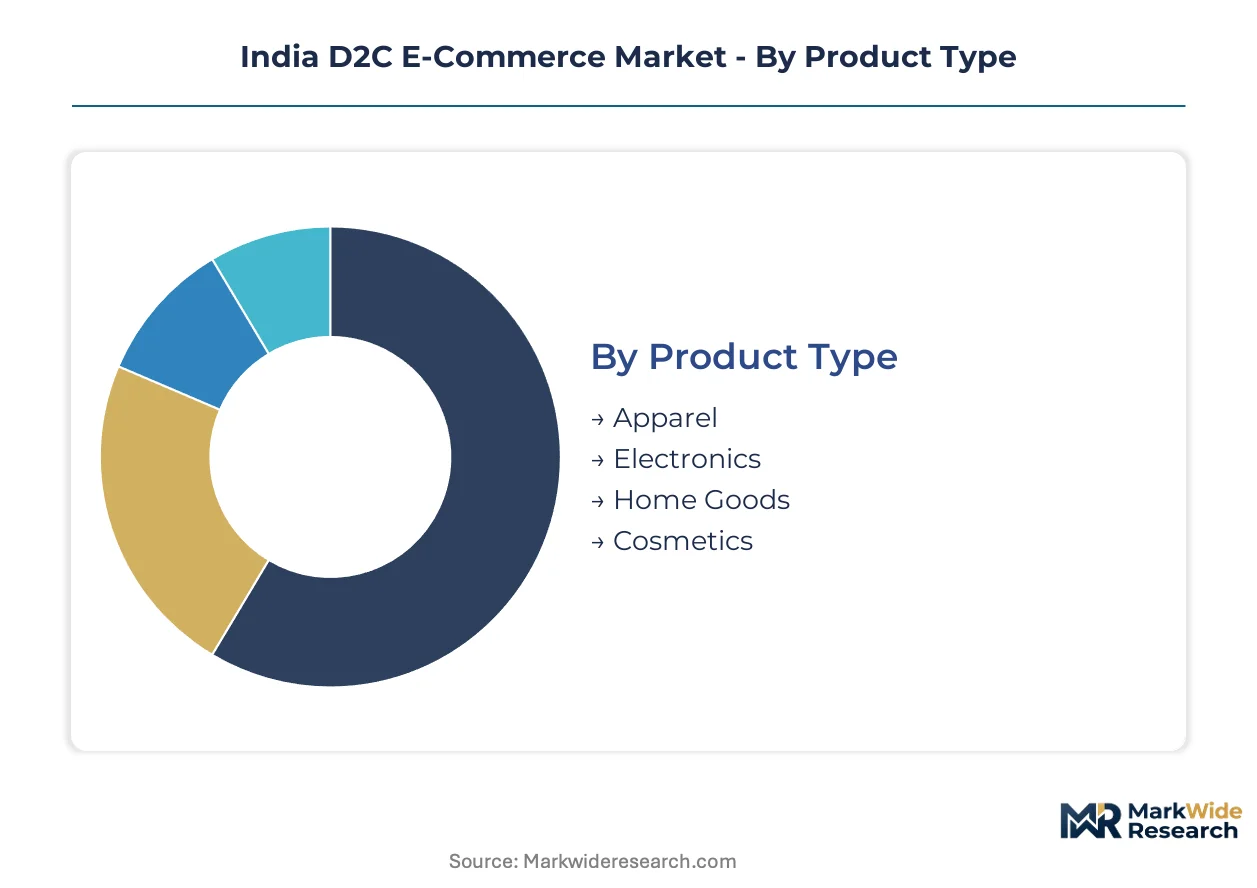
Segmentation in India's D2C landscape determines compliance pathways, logistics architecture, and customer acquisition cost structures. Each dimension carries distinct regulatory, operational, and margin implications for operators scaling across Maharashtra, Karnataka, and Delhi NCR.
Product Type:
BIS certification timelines and FSSAI labeling mandates create divergent product development cycles across categories.
- Apparel:Cotton, synthetic, and blended fabric SKUs dominate order volumes with sizing-dependent return rates. Demand concentrates in Mumbai and Pune where influencer-driven discovery sustains premium pricing for ethnic wear and athleisure lines.
- Electronics:Smartphone accessories, small appliances, and personal gadgets require BIS safety testing. PLI scheme incentives are accelerating domestic assembly for ceiling fans and kitchen appliances, shortening supply chains for D2C brands sourcing from Noida and Chennai manufacturing clusters.
- Home Goods:Kitchenware, decor, and furniture SKUs face elevated logistics costs due to dimensional weight pricing.
- Cosmetics:Ayurveda-inspired and science-backed formulations must comply with FSSAI's QR-code ingredient disclosure mandates.
Apparel handles the majority of throughput; Electronics is expanding most quickly on share.
Sales Channel:
Customer acquisition cost tiers separate owned-channel investments from platform-dependent discovery economics.
- Website:Proprietary domains capture highest average order values from established customer cohorts. Delhi NCR and Bangalore households drive premium transactions through desktop and mobile web interfaces.
- Mobile App:Push notification retention and in-app exclusive pricing sustain repeat purchase frequency. Tier-two city penetration deepens as vernacular interface localization reduces friction for first-time D2C adopters.
- Social Media:Instagram Reels and short-form video commerce compress upper-funnel discovery costs.
- Marketplace:Amazon and Flipkart listings provide scale but erode margin through commission structures and advertising auctions.
Mobile App commands the deepest customer lifetime value; Social Media is gaining share fastest.
Customer Type:
Payment method preferences and replenishment behaviors shape cohort profitability across generational segments.
- Millennials:Urban professionals aged 28-43 favor subscription models for personal care and nutrition. Auto-ship programs in Mumbai and Hyderabad reduce churn through UPI-mandate payment reliability.
- Gen Z:First-job entrants and students prioritize discovery through TikTok-style short video. Price sensitivity drives flash sale participation and influencer code redemption in tier-three cities.
- Professionals:Time-constrained buyers favor same-day delivery premiums for electronics and apparel.
- Households:Family units consolidate purchases across categories, elevating basket size through bundling.
Millennials sustain the highest subscription attach rates; Gen Z is climbing the fastest on transaction volume.
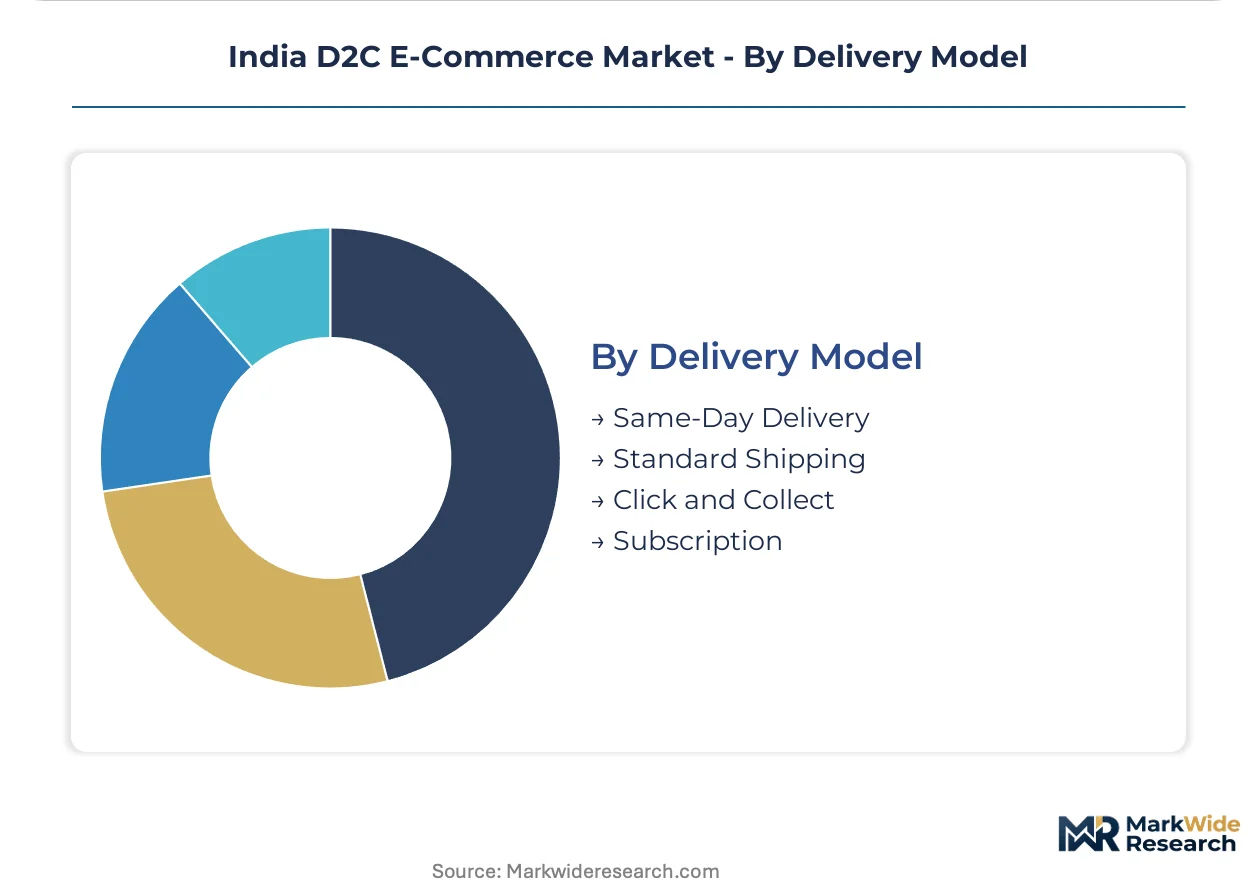
Delivery Model:
Fulfillment infrastructure density determines serviceable pin codes and margin compression per order.
- Same-Day Delivery:Hyperlocal warehouse positioning in Delhi NCR, Mumbai, and Bangalore enables two-hour windows for cosmetics and electronics. Inventory placement costs and delivery partner density requirements limit expansion to established clusters.
- Standard Shipping:Surface and air cargo consolidation through third-party logistics providers covers tier-three penetration. Fuel price volatility and inter-state octroi variations compress margins for Assam and Northeast corridor orders.
- Click and Collect:Partner retail pickup points reduce last-mile costs in dense urban localities.
- Subscription:Auto-replenishment locks in predictable demand for personal care and nutrition categories.
Standard Shipping handles the majority of pin code coverage; Subscription is the fastest mover on customer retention metrics.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
RBI's digital payment regulations and BIS certification requirements anchor Maharashtra's dominance in India D2C E-Commerce, while state-level fulfillment infrastructure investments concentrate demand across western and southern corridors.
Maharashtra
Mumbai and Pune households drive premium apparel and cosmetics transactions through vernacular short-video discovery. The state's FSSAI enforcement cells accelerate compliance investments for Ayurveda-positioned personal care brands. Navi Mumbai warehousing clusters now process same-day delivery volumes for electronics D2C operators sourcing from PLI-linked Noida assembly lines.
Karnataka
Bangalore's tech workforce sustains subscription attach rates for personal care auto-replenishment models. TRAI's broadband infrastructure mandates deepen smartphone-first penetration in tier-two hubs like Mysore and Mangalore. Whitefield and Electronic City fulfillment centers anchor hyperlocal delivery networks for appliance brands competing on energy-efficient design positioning.
Delhi NCR
Urban professionals in Gurgaon and Noida favor same-day delivery premiums for electronics and apparel categories. DGFT's import substitution policies accelerate domestic assembly for small appliances in neighboring Haryana manufacturing zones. Okhla and Bhiwandi logistics corridors consolidate surface cargo for Northeast corridor penetration.
Tamil Nadu
Chennai's manufacturing base supports BIS-certified electronics assembly for D2C appliance brands targeting replacement cycles. The state's AYUSH Ministry quality certification partnerships enable herb-cluster sourcing for personal care entrants. Coimbatore and Madurai tier-two markets deepen through India Post Payments Bank digital payment expansion.
Telangana
Hyderabad's pharmaceutical heritage shapes science-backed vegan formulation positioning for cosmetics D2C operators. RBI's UPI-mandate reliability supports subscription model payment retention for nutrition brands. Miyapur and Gachibowli warehouse positioning enables two-hour delivery windows for time-constrained professional segments.
India D2C E-Commerce Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across India's D2C E-Commerce structure, with proprietary supply chain control separating premium-positioned operators from marketplace-dependent entrants. The market fragments across four distinct tiers: vertically integrated personal care specialists, electronics design innovators, fashion-native digital brands, and vernacular-commerce challengers. Dominant competitive moves include backward integration into ingredient sourcing and captive manufacturing investments under PLI scheme incentives.
Among supply-chain-integrated personal care specialists, Mamaearth and Plum exemplify archetype differentiation through in-house quality control and science-backed formulation positioning respectively. Atomberg anchors the electronics design tier with energy-efficient appliance specialization. These three entities represent distinct competitive vectors: Ayurveda-inspired transparency, vegan premium positioning, and hardware efficiency engineering.
| Leading Market Players |
|---|
| Lahori Zeera |
| Plum |
| Atomberg |
| MyGlamm |
| Mamaearth |
| Pilgrim |
| Mokobara |
| Bewakoof |
| SNITCH |
| Others |
Supply & Pricing Matrix
PLI-linked assembly scale in Noida and Chennai manufacturing clusters compresses unit costs for appliance and electronics D2C brands while establishing price floors that unorganized imports cannot match. This scale concentration simultaneously elevates working capital requirements for quality certification and captive sourcing, filtering margin structures across premium and mass-market tiers.
Pricing Analysis
Maharashtra and Karnataka command 15-20% price premiums over Assam and Northeast corridor markets due to same-day delivery infrastructure density and established fulfillment clusters. Three-tier pricing structure across premium, standard, and economy levels separates Ayurveda-certified personal care from unbranded marketplace alternatives, with certification grade and after-sales service bundling as primary differentiation drivers. Cost compression in tier-three apparel segments is intensifying because of elevated reverse logistics friction from sizing mismatches. Gen Z flash-sale participants exhibit highest price sensitivity, while millennial subscription cohorts in Mumbai and Bangalore accept premium positioning for auto-replenishment reliability.
Supply Chain Analysis
Port congestion at Nhava Sheva and Mundra elevates inbound logistics costs for electronics components sourced from China, Vietnam, and Taiwan, compressing margins for D2C brands without PLI-linked domestic assembly. Supply rests on herb clusters in Madhya Pradesh and Uttarakhand for Ayurveda-positioned personal care, semiconductor components from East Asian manufacturing hubs, and cotton textiles from Gujarat and Maharashtra. Single-source vulnerability concentrates in payment gateway infrastructure, where three domestic fintech aggregators dominate transaction processing. Distribution runs through Navi Mumbai and Whitefield fulfillment centers for hyperlocal delivery, with surface cargo consolidation through Okhla-Bhiwandi corridors serving tier-three penetration.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
India D2C E-Commerce sits in early-cycle expansion as tier-two and tier-three smartphone penetration unlocks first-time household adoption beyond established metro corridors.
For Market Incumbents: Shield margin structures by accelerating backward integration into Madhya Pradesh herb clusters for Ayurveda-certified personal care, insulating against FSSAI compliance cost inflation. Fortify Navi Mumbai and Whitefield fulfillment density to defend same-day delivery premiums against emerging hyperlocal challengers. Prioritize WhatsApp Commerce API integration to bypass search-dependent discovery entirely. For New Entrants and Emerging Players: Differentiate on vernacular short-video commerce positioning in Guwahati and Imphal, where digital payment infrastructure expansion through India Post Payments Bank partnerships creates first-mover whitespace. Target underpenetrated Assam corridor adoption before established operators consolidate Northeast logistics. Anchor go-to-market through regional language Reels content with influencer code redemption mechanics. For Investors and Strategic Acquirers: Supply-chain-integrated personal care specialists with captive quality control and AYUSH Ministry certification pathways represent the most defensible acquisition archetype. Monitor DPDP Bill compliance investment intensity as the signal to watch for data monetization feasibility inflection. Long-term viability hinges on first-party customer data accumulation for cohort-based retention marketing across the projection horizon.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Herb Sourcing | Captive Madhya Pradesh and Uttarakhand supply secures AYUSH certification for premium Ayurveda positioning. |
| WhatsApp Commerce API Deployment | Meta's business messaging platform enables conversational checkout flows that bypass search-dependent discovery entirely. |
| PLI-Linked Domestic Assembly Investment | Noida and Chennai manufacturing clusters shorten electronics supply chains while qualifying for production-linked incentives. |
| Subscription Model Infrastructure Buildout | UPI-mandate reliability in Mumbai and Hyderabad reduces payment churn for personal care auto-replenishment programs. |
| Vernacular Interface Localization | Tier-two city penetration deepens as regional language app design reduces friction for first-time D2C adopters. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with D2C brand founders, supply chain directors, third-party logistics operators, and digital marketing heads; and secondary validation through RBI payment system reports, FSSAI regulatory filings, TRAI broadband infrastructure data, and PLI scheme disclosure documents. Bottom-up SKU-level demand modeling triangulated against top-down household penetration benchmarks across Maharashtra, Karnataka, Delhi NCR, and emerging Northeast corridors.
Across the analysis window, forecasts integrated product type segmentation by compliance pathway, sales channel economics by customer acquisition cost tier, and delivery model density by fulfillment infrastructure availability. CAGRs derived from logistic curve adoption modeling calibrated to smartphone penetration trajectories and digital payment wallet expansion rates. Industry-specific inputs included BIS certification timeline distributions, FSSAI labeling retrofit costs, and vernacular content consumption growth patterns from short-video platform analytics.
Decision-makers should treat outputs as directional under sustained PLI scheme continuity and stable fuel price assumptions; material deviation in either would warrant model refresh. Forecasts reflect adoption curve assumptions for tier-two and tier-three penetration that could compress if digital payment infrastructure deployment stalls. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
E-Commerce Solutions
Latin America E-Commerce Logistics Market
E-Commerce Solutions
Global Digital Commerce Market
E-Commerce Solutions
Spain E-Commerce Market
E-Commerce Solutions
Taiwan E-Commerce Market
E-Commerce Solutions
Belgium E-Commerce Market
E-Commerce Solutions
United States E-Commerce Logistics Market
E-Commerce Solutions
Saudi Arabia Delivery Apps Market
E-Commerce Solutions
North America FMCG B2B E-Commerce Market
E-Commerce Solutions
North America Dropshipping Market
E-Commerce Solutions
Romania E-Commerce Market
E-Commerce Solutions
Metaverse in E-Commerce Market
E-Commerce Solutions
Quiet Commerce Market
E-Commerce Solutions
South Korea Ecommerce Logistics Market
E-Commerce Solutions
Asia-Pacific Cross-Border B2C E-Commerce Market
E-Commerce Solutions
Cyprus E-Commerce Market
E-Commerce Solutions
Italy Dropshipping Market