
 United States E-Commerce Logistics Market | 2026-2036
United States E-Commerce Logistics Market Size, Share, and Industry Trends Forecast 2026-2036
United States E-Commerce Logistics Market Analytics
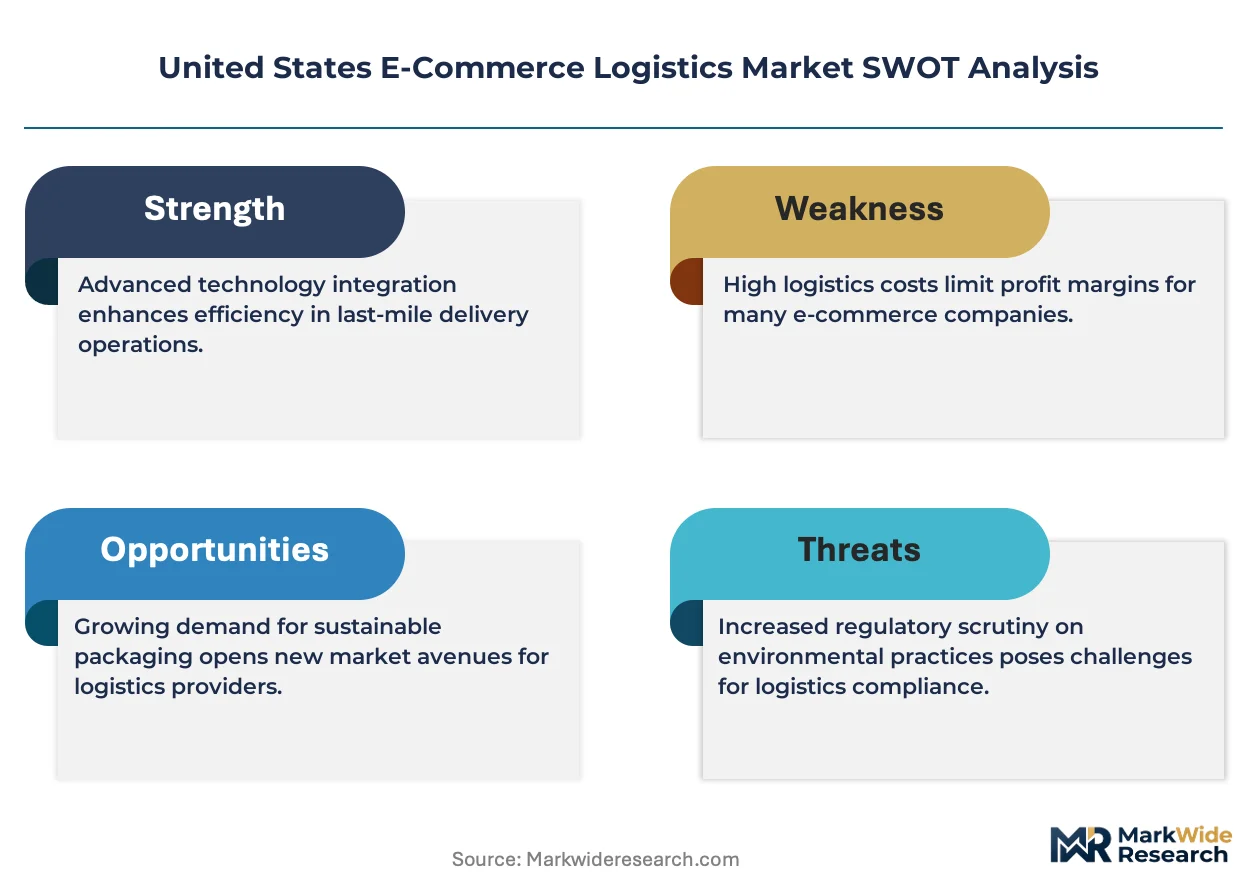
Same-day delivery tier is redrawing competitive boundaries across the United States e-commerce logistics landscape. Amazon Logistics leverages captive air and ground networks to compress transit windows for premium subscribers. FedEx anchors its position through dense sortation hub coverage across the Southeast and Midwest. UPS Supply Chain Solutions differentiates via healthcare-certified cold chain infrastructure serving pharmaceutical e-commerce.
United States e-commerce logistics encompasses the integrated movement, storage, and fulfillment of online retail orders through multimodal networks operating at parcel-level granularity, typically handling individual shipments under seventy pounds with tracking visibility at each node. Its primary commercial purpose is collapsing the temporal gap between digital purchase confirmation and physical product receipt to maximize conversion and retention. Last mile delivery commands the largest cost share within service type segmentation due to residential stop density challenges, while returns management grows fastest as apparel and footwear sellers absorb reverse logistics costs. Autonomous vehicles remain nascent in technology segmentation but attract disproportionate capital allocation as warehouse-to-hub middle mile applications mature.
FAA regulations govern commercial drone delivery trials, while DOT hours-of-service rules constrain driver availability and push shippers toward automated sortation. OSHA warehouse safety standards shape facility design and labor deployment across fulfillment centers. Stakeholders must weigh capital commitments between autonomous technology pilots and conventional network densification as labor availability tightens.
Market Dynamics
DOT hours-of-service enforcement is compressing driver availability and forcing capital redeployment toward automated sortation and middle-mile autonomy across the United States e-commerce logistics network.
Growth Catalysts
- Regulatory pressure on driver hours:DOT enforcement of stricter hours-of-service rules is accelerating warehouse automation investments as shippers seek to offset constrained trucking capacity.
- Apparel returns density:Reverse logistics infrastructure serving footwear and fashion e-commerce is expanding rapidly as sellers absorb free return costs to maintain conversion rates.
- California warehouse clustering:The Inland Empire corridor concentrates fulfillment square footage, creating network economies that pull inventory positioning westward.
Market Restraints
- Last-mile cost structure:Residential delivery density challenges keep per-stop costs elevated, with single-package drops to suburban addresses consuming disproportionate fuel and labor resources.
- FAA drone restrictions:Commercial unmanned aerial vehicle trials remain constrained by altitude, beyond-visual-line-of-sight, and payload regulations that limit suburban deployment.
- OSHA facility compliance:Warehouse safety standards governing aisle width, equipment guarding, and ergonomic design add construction cost and retrofit friction.
Strategic Opportunities
- Healthcare cold chain expansion:Pharmaceutical e-commerce is creating demand for temperature-validated parcel networks that command premium pricing and long-term contracts.
- Midwest sortation hub density:FedEx and regional carriers are building secondary hub capacity in Ohio and Tennessee to reduce reliance on coastal gateway congestion.
- Autonomous middle-mile pilots:Warehouse-to-hub autonomous vehicle trials on designated freight corridors offer path to 24-hour continuous transit without driver hour limits.
Industry Challenges
- Warehouse talent scarcity:Fulfillment center operators face acute shortages of certified forklift operators and maintenance technicians as facility expansion outpaces vocational training pipelines.
- Legacy WMS integration:Enterprise warehouse management system upgrades required for robotic piece-picking and real-time inventory visibility demand multi-year capital commitments with uncertain ROI timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States E-Commerce Logistics Market |
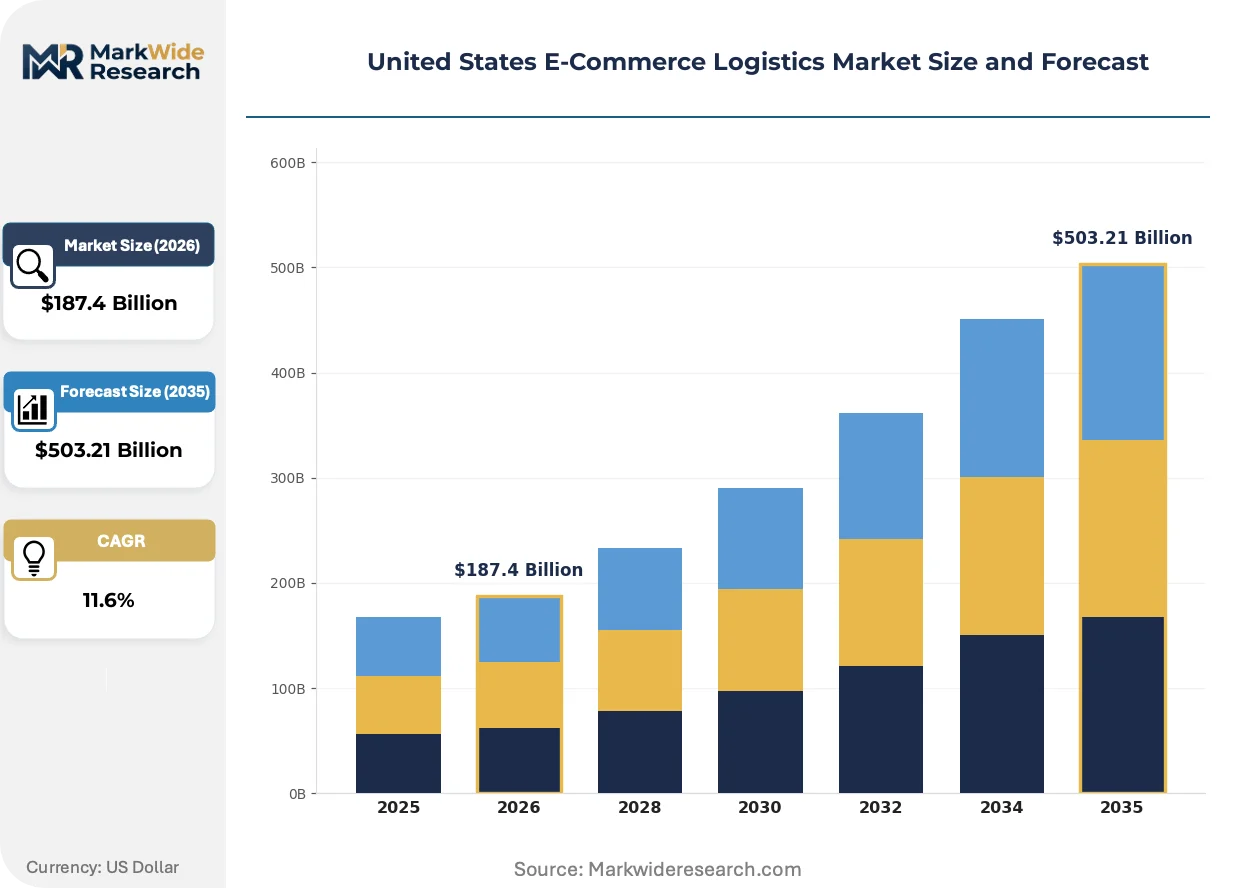
| Market Size in 2026 | $187.4 Billion |
| Market Size in 2035 | $503.21 Billion |
| CAGR (2026 – 2036) | 11.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Last Mile Delivery, Warehousing, Freight Transportation, Returns Management End User: Retailers, Direct-to-Consumer Brands, Marketplaces, Wholesalers Delivery Mode: Ground, Air, Sea, Same-Day Delivery Technology: Inventory Management Systems, Route Optimization, Tracking Software, Autonomous Vehicles |
| Companies Covered | UPS Supply Chain Solutions, FedEx, Amazon Logistics, USPS, DHL E-commerce, XPO Logistics, GXO Logistics, Kenco Group, CEVA Logistics, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States E-Commerce Logistics Market Evolving Landscape
Automated piece-picking robotics and predictive routing algorithms are compressing fulfillment cycle times while reshaping labor deployment across United States distribution networks.
Autonomous mobile robots equipped with computer vision and collaborative arm systems are displacing manual pick-and-pack operations in high-SKU apparel and electronics fulfillment centers. Mid-market third-party logistics providers are deploying these systems at 200,000-plus-square-foot facilities to maintain throughput during peak seasonal demand without proportional headcount expansion. The technology is displacing traditional zone-picking workflows and enabling dark warehouse configurations with minimal human presence.
FAA Part 135 certification pathways for drone delivery operators are creating regulatory frameworks for limited beyond-visual-line-of-sight operations in suburban Texas and North Carolina trial zones. The agency's incremental approach—expanding operational waivers based on safety case documentation—is channeling investment toward fixed-wing vertical-takeoff platforms over multirotor designs. Pharmaceutical and urgent medical supply categories are securing priority access to these air corridors due to payload-value density and time-critical delivery requirements.
Buy-side consolidation among direct-to-consumer brands is compressing third-party logistics contract renewal cycles and intensifying rate negotiation leverage. Merchants with $50 million-plus annual parcel spend are unbundling transportation from warehousing and adopting modular provider stacks rather than single-source fulfillment partnerships. This pattern is most pronounced among digitally native vertical brands headquartered in New York and Los Angeles that have achieved sufficient scale to justify dedicated network engineering teams.
United States E-Commerce Logistics Market Segmentation
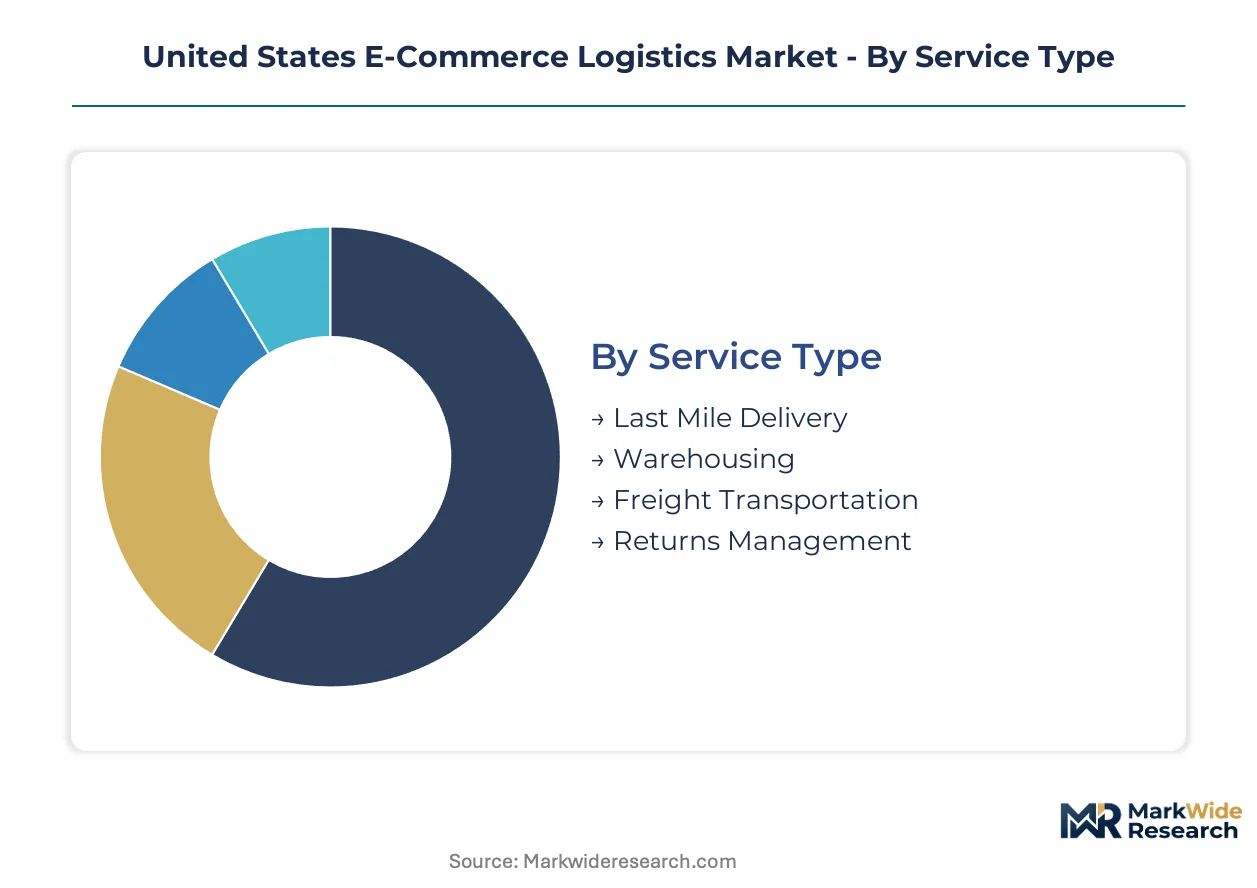
Service type segmentation determines capital allocation across the United States e-commerce logistics network, with distinct margin profiles and automation potential shaping provider strategy. Channel mix varies sharply: premium same-day flows concentrate through captive air networks, while bulk inventory positioning favors ground-based middle-mile corridors.
Service Type:
Last-mile and warehousing segments flow through fundamentally different channel economics, with the former capturing consumer-facing revenue premiums and the latter generating contracted facility fees.
- Last Mile Delivery:Final-leg parcel distribution to residential addresses operates through dense suburban route networks with high stop frequency and elevated per-unit labor costs. Demand concentrates in California's Inland Empire corridor and Texas metroplexes where single-family housing density supports route efficiency, though driver hour constraints under DOT rules compress daily throughput capacity.
- Warehousing:Fulfillment center operations encompass receiving, put-away, pick-and-pack, and cross-dock functions within climate-controlled facilities. Amazon Logistics and regional third-party providers are expanding square footage most aggressively in Phoenix and Atlanta submarkets where land availability and interstate access reduce drayage costs.
- Freight Transportation:Line-haul trucking and intermodal rail movements connect origin ports to regional distribution nodes.
- Returns Management:Reverse logistics processing for apparel and electronics sectors absorbs inspection, refurbishment, and restocking workflows.
By volume, Last Mile Delivery leads. By growth pace, Returns Management is climbing the fastest.
End User:
Customer type segmentation maps to order velocity and contract structure, with direct-to-consumer brands driving modular fulfillment demand while marketplaces enforce captive network compliance.
- Retailers:Omnichannel merchants with physical store footprints leverage ship-from-store capabilities and dark store conversions to collapse delivery windows. Macy's and Target anchor regional fulfillment networks in the Northeast and Midwest, integrating brick-and-mortar inventory pools with digital order routing.
- Direct-to-Consumer Brands:Digitally native vertical brands unbundle transportation from warehousing and adopt modular provider stacks. Allbirds and Warby Parker headquarters clusters in New York and Los Angeles generate concentrated demand for specialized apparel and eyewear fulfillment infrastructure.
- Marketplaces:Platform operators impose seller compliance standards and captive logistics requirements.
- Wholesalers:B2B volume shippers prioritize palletized freight and scheduled delivery windows over parcel granularity.
By revenue concentration, Retailers dominate. By contract innovation velocity, Direct-to-Consumer Brands are gaining share fastest.
Delivery Mode:
Modal selection reflects speed-cost tradeoffs and regulatory constraints, with same-day premium tiers commanding structural investment priority.
- Ground:Parcel and less-than-truckload networks handle the majority of e-commerce volume through hub-and-spoke sortation infrastructure. FedEx Ground and UPS Ground route density advantages concentrate in Ohio and Tennessee secondary hubs, reducing coastal gateway congestion exposure.
- Same-Day Delivery:Ultra-expedited fulfillment leverages micro-fulfillment centers and gig-economy courier pools to compress transit below four hours. Demand clusters in Manhattan, San Francisco, and Chicago dense urban cores where population density justifies facility placement costs.
- Air:Express networks serve time-definite commitments through captive freighter fleets.
- Sea:Containerized import movements feed West Coast port complexes ahead of inland distribution.
By shipment volume, Ground leads. By capital deployment priority, Same-Day Delivery shows the steepest expansion trajectory.
Technology:
Technology segmentation tracks automation maturity and integration depth, with autonomous systems attracting disproportionate investment relative to current deployment scale.
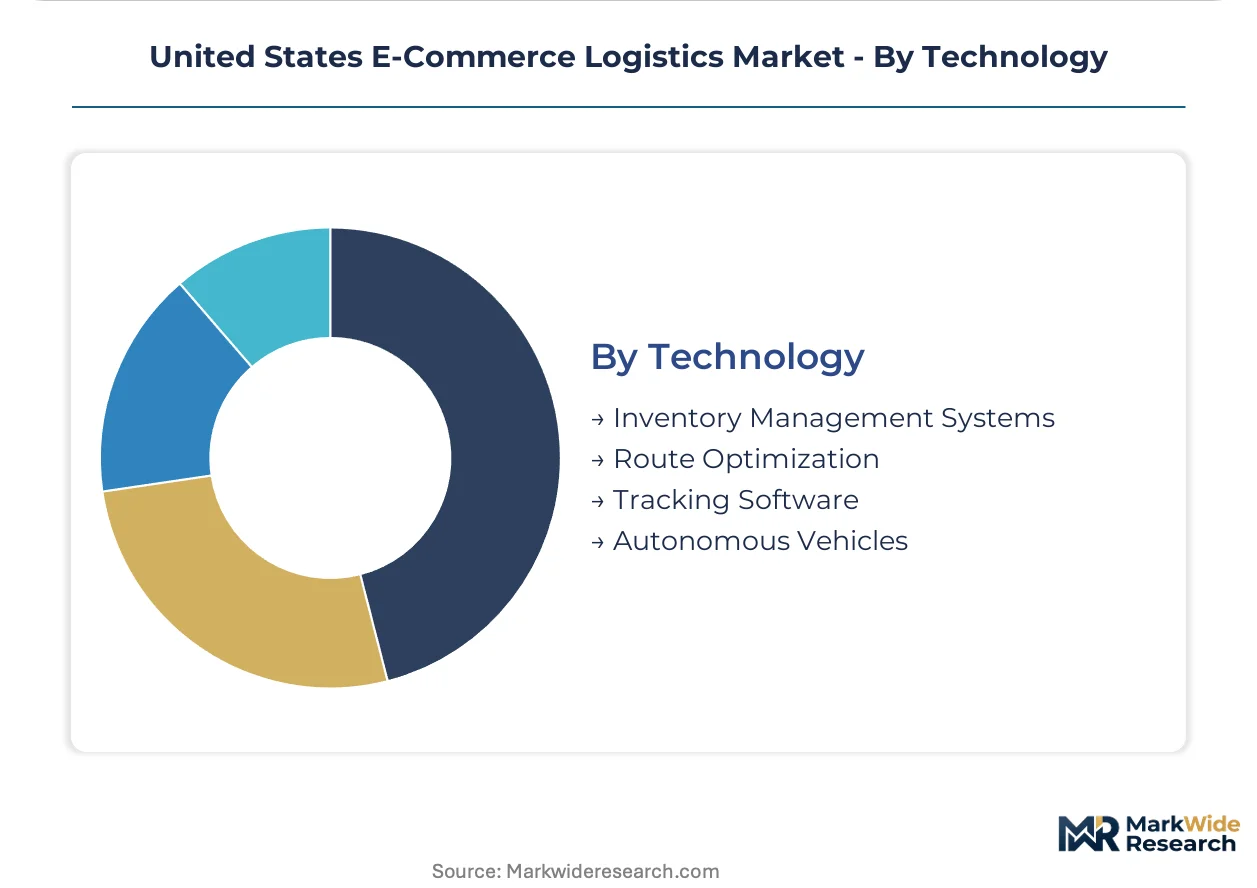
- Inventory Management Systems:Warehouse management platforms enable real-time SKU visibility and robotic orchestration across multi-client facilities. High-SKU apparel and electronics fulfillment centers in Pennsylvania and Georgia deploy these systems to maintain throughput during peak seasonal demand without proportional headcount expansion.
- Autonomous Vehicles:Warehouse-to-hub middle-mile trials on designated freight corridors offer 24-hour continuous transit without driver hour limits. Waymo and Kodiak Robotics pilot programs in Texas and Arizona freight corridors attract regulatory scrutiny under NHTSA autonomous vehicle guidelines.
- Route Optimization:Algorithmic dispatch systems reduce miles-per-stop through predictive traffic and delivery density modeling.
- Tracking Software:Parcel-level visibility platforms integrate carrier APIs and IoT sensor feeds for consumer-facing delivery predictions.
By installed base, Inventory Management Systems lead. By investment growth rate, Autonomous Vehicles are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Cross-border container flows from China feed West Coast port complexes before dispersing through inland distribution corridors to final-mile nodes across the continental United States.
California Inland Empire
E-commerce fulfillment square footage concentrates in Riverside and San Bernardino counties where land costs remain below Los Angeles basin levels. California Air Resources Board truck emissions rules accelerate fleet electrification timelines for drayage operators serving the Ports of Long Beach and Los Angeles. Amazon Logistics and regional third-party providers expand multi-million-square-foot facilities in Fontana and Redlands to capture last-mile density into Los Angeles, San Diego, and Phoenix corridors.
Texas Triangle
Dallas-Fort Worth, Houston, and Austin metroplexes absorb distribution capacity fleeing California cost pressures and coastal congestion. Texas Department of Transportation freight corridor investments expedite warehouse-to-hub movements along Interstate 35. GXO Logistics and XPO Logistics anchor fulfillment campuses in the AllianceTexas development north of Fort Worth, leveraging rail intermodal access to reach Chicago and Memphis within 48 hours.
Ohio River Valley
Ground transit time advantages to East Coast population centers drive sortation hub construction in Ohio, Kentucky, and Tennessee. Federal Motor Carrier Safety Administration enforcement of electronic logging device mandates constrains driver scheduling flexibility across Appalachian freight corridors. FedEx Ground operates its second-largest hub in Indianapolis with supplemental capacity in Memphis, while UPS maintains major air operations at Louisville Worldport.
Southeast Atlantic
Population migration to Florida and Georgia expands residential delivery density while port expansion at Savannah reduces West Coast import dependency. Georgia Department of Transportation infrastructure bonds fund interstate widening projects connecting the Port of Savannah to Atlanta distribution clusters. Kenco Group and CEVA Logistics operate multi-client fulfillment centers in Atlanta exurbs serving apparel and consumer electronics direct-to-consumer brands.
Northeast Corridor
Same-day delivery premiums concentrate demand in Manhattan, Boston, and Philadelphia urban cores where micro-fulfillment economics justify facility placement costs. New York State Department of Labor warehouse worker protection regulations mandate scheduling predictability and heat safety protocols for fulfillment center employees. USPS and Amazon Logistics deploy localized sortation facilities in Queens and Newark to compress transit windows for premium subscribers in dense metropolitan markets.
United States E-Commerce Logistics Market Competitive Landscape
Listed leaders compete with private specialists across capital access and operational flexibility dimensions. The vendor base stratifies into three tiers: integrated parcel carriers with captive air networks, asset-light third-party logistics platforms, and captive e-commerce fulfillment operations. Competitive moves center on hub densification in secondary markets and unbundled service offerings that separate warehousing contracts from transportation procurement.
Within the integrated carrier tier, UPS Supply Chain Solutions and FedEx exemplify scale-driven network economics with healthcare-certified infrastructure and dense ground sortation coverage. Amazon Logistics occupies a distinct position as a captive fulfillment arm serving proprietary marketplace volume while selectively opening capacity to third-party merchants. Among specialized third-party operators, GXO Logistics and Kenco Group represent modular fulfillment approaches that unbundle transportation from warehousing for mid-market direct-to-consumer brands.
| Leading Market Players |
|---|
| UPS Supply Chain Solutions |
| FedEx |
| Amazon Logistics |
| USPS |
| DHL E-commerce |
| XPO Logistics |
| GXO Logistics |
| Kenco Group |
| CEVA Logistics |
| Others |
Value Network & Pricing Analysis
Hub density in Ohio and Tennessee secondary markets generates network economies that compress per-unit handling costs while establishing regional price floors for ground parcel services. These scale advantages concentrate pricing power among integrated carriers with captive sortation infrastructure, forcing asset-light competitors toward modular service unbundling.
Pricing Analysis
Technology-generation pricing gaps separate legacy warehouse management systems from AI-enabled robotic orchestration platforms and emerging autonomous middle-mile solutions. Three-tier pricing structure across premium same-day, standard ground, and economy deferred delivery segments reflects speed guarantees and residential density economics. Pricing pressure stems from DOT hours-of-service constraints elevating driver costs and automated sortation capital recovery requirements. Small and mid-market direct-to-consumer brands exhibit highest price sensitivity, while pharmaceutical e-commerce shippers absorb premiums for healthcare-certified cold chain validation.
Supply Chain Analysis
Just-in-time inventory positioning dominates apparel and electronics fulfillment, while strategic stockpiling characterizes pharmaceutical cold chain and peak-season consumer goods buffers. Manufacturing concentration in China, Vietnam, and Bangladesh feeds West Coast port complexes before inland distribution to regional hubs. Semiconductor components, lithium-ion cells, and specialized packaging materials constitute critical input dependencies. Single-source vulnerability through the Panama Canal and Los Angeles-Long Beach corridor exposes networks to congestion risk. Distribution runs through hub-and-spoke sortation facilities before final-mile residential delivery.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Certified forklift operator and maintenance technician shortages constrain facility expansion velocity, creating a talent-acquisition bottleneck that favors providers with established vocational training pipelines and automation-first deployment strategies.
For Market Incumbents: Compound network density advantages through secondary hub construction in Indianapolis and Memphis corridors, offsetting coastal gateway congestion exposure. Deepen captive air fleet utilization for same-day premium tiers while accelerating warehouse-to-hub autonomous vehicle pilots on Texas and Arizona freight corridors to circumvent DOT driver hour constraints. Defend against modular unbundling by integrating real-time inventory visibility APIs for mid-market direct-to-consumer brands.
For New Entrants and Emerging Players: Differentiate on healthcare-certified cold chain infrastructure serving pharmaceutical e-commerce, a segment commanding premium pricing and long-term contract structures. Target returns management specialization for apparel and footwear verticals, where reverse logistics density is expanding fastest and incumbent coverage remains fragmented. Pursue white-label micro-fulfillment partnerships with grocery and convenience retailers in Manhattan and Chicago dense urban cores.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors warehouse automation specialists with proven robotic piece-picking deployments and dark warehouse configuration capabilities. Long-term viability hinges on providers bridging the gap between pilot-stage autonomous middle-mile trials and scaled regulatory approval. Acquisition candidates should demonstrate OSHA compliance track records and established relationships with California Air Resources Board regulatory frameworks. Watch FAA Part 135 certification expansion velocity as inflection indicator for drone delivery commercialization timelines.
| Strategic Initiative | Industry Significance |
|---|---|
| Secondary Hub Densification | FedEx and UPS expansion in Ohio and Tennessee reduces coastal congestion exposure and compresses ground transit windows to East Coast population centers. |
| Healthcare Cold Chain Certification | Temperature-validated parcel networks serving pharmaceutical e-commerce command premium pricing and secure multi-year contracts with FDA-registered distributors. |
| Autonomous Middle-Mile Pilots | Warehouse-to-hub autonomous vehicle trials on Texas freight corridors offer 24-hour continuous transit without DOT driver hour limitations. |
| Returns Management Infrastructure | Reverse logistics specialization for apparel and footwear absorbs inspection and refurbishment workflows as sellers maintain free return policies. |
| Micro-Fulfillment Urban Placement | Compact facilities in Manhattan and Chicago dense cores enable sub-four-hour delivery windows for premium same-day service tiers. |
Research Methodology
The analysis maps last-mile delivery networks, warehouse automation deployments, and reverse logistics infrastructure, each validated through fulfillment center operations directors, DOT compliance officers, and third-party logistics procurement leads. Primary interviews with certified forklift training program administrators and autonomous vehicle regulatory specialists combined with secondary validation against FMCSA electronic logging device mandate filings, FAA Part 135 certification records, and OSHA warehouse safety inspection databases. Bottom-up facility square footage aggregation and top-down parcel volume estimates underwent cross-referencing for consistency.
Consistency checks against Bureau of Transportation Statistics freight flow data and Census Bureau e-commerce sales indices validated projection outputs across the analysis window. Segmentation dimensions modeled include service type, end user category, delivery mode, and technology maturity tier. CAGRs derived from historical volume trajectories and capacity expansion announcements, with specific inputs incorporating California Air Resources Board fleet electrification timelines and Inland Empire warehouse construction permit flows.
Material uncertainties — regulatory acceleration in autonomous vehicle deployment, labor strike disruptions at West Coast ports, and fuel cost volatility — sit outside the modeled envelope. Forecasts reflect documented assumptions regarding DOT enforcement consistency and FAA waiver expansion velocity. Revision becomes warranted when autonomous middle-mile regulatory approval crosses commercial deployment thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
E-Commerce Solutions
Digital Coupons Market
E-Commerce Solutions
North America Dropshipping Market
E-Commerce Solutions
Portugal E-Commerce Market
E-Commerce Solutions
E-Commerce App Market
E-Commerce Solutions
Slovakia E-Commerce Market
E-Commerce Solutions
United States E-Commerce Market
E-Commerce Solutions
Courier Express and Parcel (CEP) Market
E-Commerce Solutions
North America FMCG B2B E-Commerce Market
E-Commerce Solutions
Europe E-Commerce Market
E-Commerce Solutions
South Korea Ecommerce Logistics Market
E-Commerce Solutions
Netherlands E-Commerce Market
E-Commerce Solutions
Hong Kong E-Commerce Market
E-Commerce Solutions
Europe E-Commerce Apparel Market
E-Commerce Solutions
United Kingdom E-Commerce Market
E-Commerce Solutions
Chile E-Commerce Market
E-Commerce Solutions
E-Commerce Lockers Market