
 United States Same-Day Delivery Market | 2026-2036
United States Same-Day Delivery Market Size, Share, and Industry Trends Forecast 2026-2036
United States Same-Day Delivery Market Analytics
The EPA's Phase 3 greenhouse gas standards for medium- and heavy-duty vehicles is broadening pressure on logistics fleets to electrify delivery operations. Amazon Logistics leverages its captive network of electric vans to sustain same-day density in top urban zones. UPS anchors its position through proprietary routing algorithms that compress delivery windows. FedEx competes by extending weekend and evening same-day options for healthcare and retail accounts.
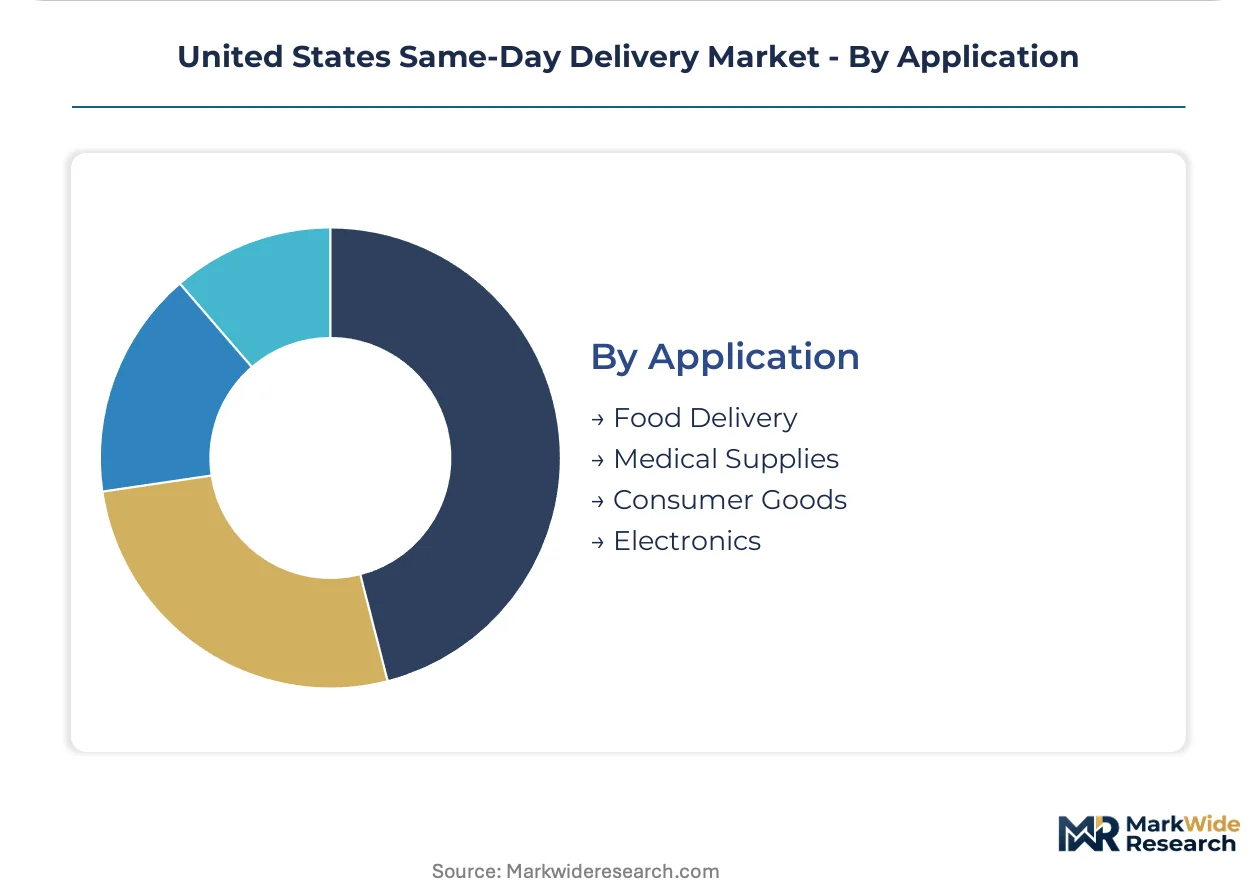
Same-day delivery denotes logistics fulfillment where goods move from seller to buyer within twenty-four hours of order placement, typically requiring real-time inventory positioning, dynamic route optimization, and localized warehousing within fifty miles of destination. On-demand delivery and express shipping segments dominate transaction volume, while drone delivery mode represents the fastest-growing structural category despite operational constraints. Medical supplies and food delivery applications command premium pricing due to temperature-control requirements and time-criticality, whereas consumer goods and electronics segments operate on thinner margins scaled through volume.
The Department of Transportation, FAA, and OSHA collectively govern vehicle safety, airspace access for unmanned aerial systems, and worker classification standards that directly shape fleet economics and service scalability. California's AB 5 framework and subsequent appellate rulings on independent contractor status continue forcing operational model recalibration across the industry. Stakeholders must monitor regulatory divergence between federal drone pathways and state-level labor classifications to anticipate compliance cost trajectories.
Market Dynamics
The EPA's Phase 3 greenhouse gas standards for medium- and heavy-duty vehicles is forcing fleet operators to electrify delivery vehicles or absorb penalty costs, reshaping capital allocation across last-mile networks.
Growth Catalysts
- California AB 5 Labor Classification:Reclassification rulings are pressuring platforms to convert gig workers to employees, raising operational costs but stabilizing workforce retention in dense urban corridors.
- Drone Integration Pathways:The FAA's evolving Part 135 waiver frameworks for unmanned aerial systems are opening regulatory airspace for pilot programs in suburban last-mile zones.
- Healthcare Logistics:Temperature-controlled pharmaceutical delivery commands premium pricing and dedicated cold-chain infrastructure, attracting specialized fleet investment.
Market Restraints
- Last-Mile Labor Cost Volatility:Driver wage compression in metropolitan markets is squeezing margins on standard parcel deliveries below sustainability thresholds.
- California Regulatory Concentration:AB 5 appellate uncertainty and state-level emissions mandates create compliance fragmentation that multiplies operational complexity for national networks.
- Battery Supply Constraints:Lithium-ion cell availability for electric van fleets remains bottlenecked by upstream mining and processing capacity limitations.
Strategic Opportunities
- Rural Corridor Penetration:Secondary metropolitan zones in Texas and Florida lack dedicated same-day infrastructure, offering first-mover density advantages.
- IRA Commercial Vehicle Credits:Federal tax incentives for electric fleet purchases are compressing total cost of ownership parity timelines against diesel alternatives.
- Autonomous Ground Vehicle Convergence:Lidar mapping and teleoperations platforms are maturing simultaneously, enabling supervised autonomous delivery in gated communities and industrial parks.
Industry Challenges
- Route Optimization Talent Scarcity:Operations research specialists capable of dynamic fleet dispatching command salaries that mid-tier logistics providers cannot match.
- OSHA Warehouse Safety Compliance:Automated fulfillment center robotics require retraining programs and facility retrofits that extend capital deployment cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States Same-Day Delivery Market |
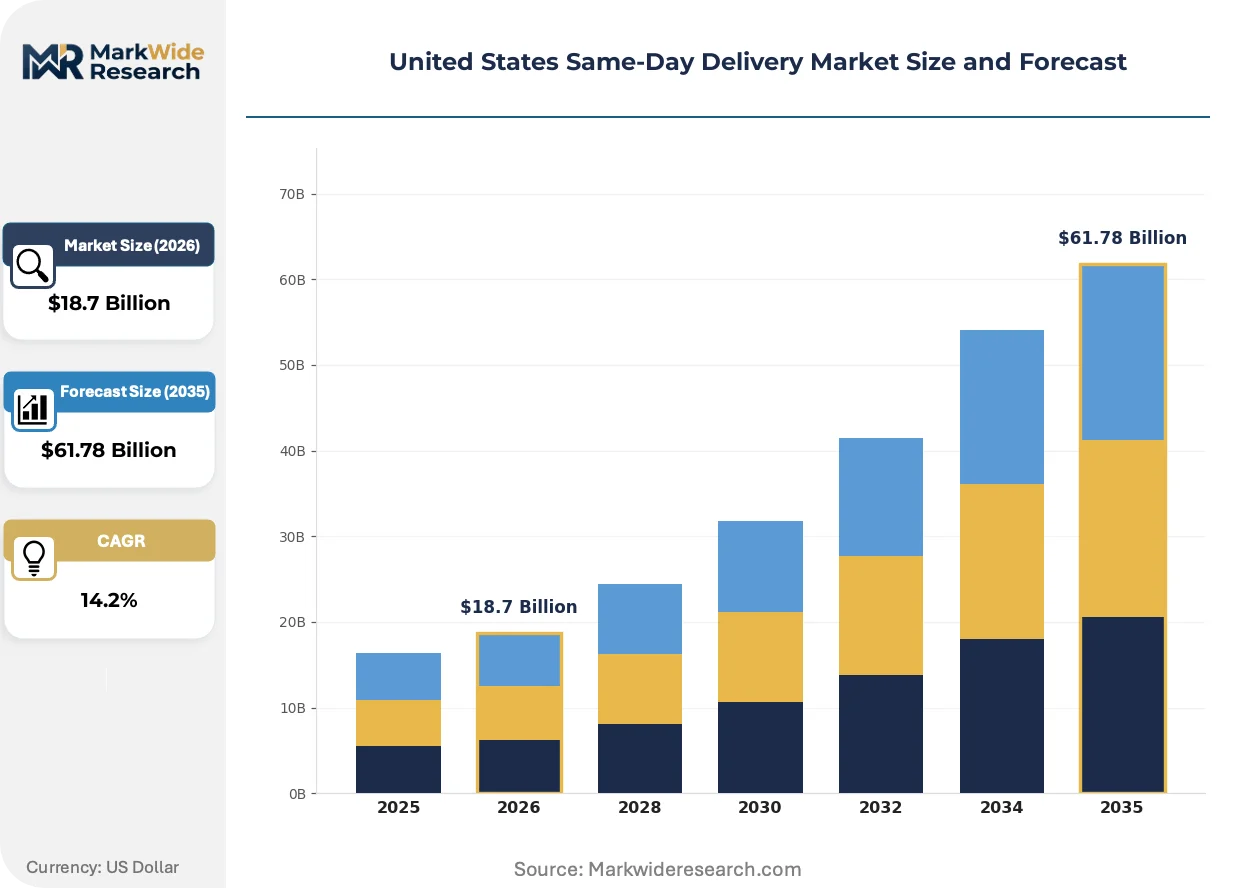
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $61.78 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Express Shipping, On-Demand Delivery, Cargo Courier, Same-Day Pickup End User: E-Commerce, Retail, Grocery, Pharmaceuticals Delivery Mode: Motorcycle, Van, Bicycle, Drone Application: Food Delivery, Medical Supplies, Consumer Goods, Electronics |
| Companies Covered | FedEx, United Parcel Service of America, Inc. (UPS), United States Postal Service (USPS), DHL Group, OnTrac, Amazon Logistics, Dropoff, Inc., Jet Delivery, Inc., Need It Now Delivers, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States Same-Day Delivery Market Evolving Landscape
Real-time inventory positioning and predictive demand algorithms are compressing fulfillment windows from hours to minutes, forcing infrastructure investment toward hyperlocal micro-fulfillment nodes.
Dynamic route optimization software is absorbing dispatch decision-making previously handled by human fleet managers. Grocery and pharmaceutical chains are deploying these platforms fastest, cutting average delivery intervals by eliminating manual routing delays. The technology is absorbing middle-management overhead while enabling same-hour service commitments previously structurally impossible.
The FAA's Part 135 drone waiver expansion is creating operational airspace for beyond-visual-line-of-sight deliveries. This regulatory shift permits automated aerial handoffs between suburban distribution hubs and residential drop zones. Healthcare specimen transport in Arizona and North Carolina pilot zones is adapting first, rewriting last-mile cost curves for time-critical biologics.
Subscription-based delivery memberships are displacing per-transaction pricing as the dominant consumer acquisition model. Retail platforms in New York and Los Angeles metropolitan areas are bundling same-day access with loyalty programs, locking in recurring revenue against competitor switching. Food and consumer electronics verticals show the fastest membership penetration, with household consolidation around two-to-three platform relationships.
United States Same-Day Delivery Market Segmentation
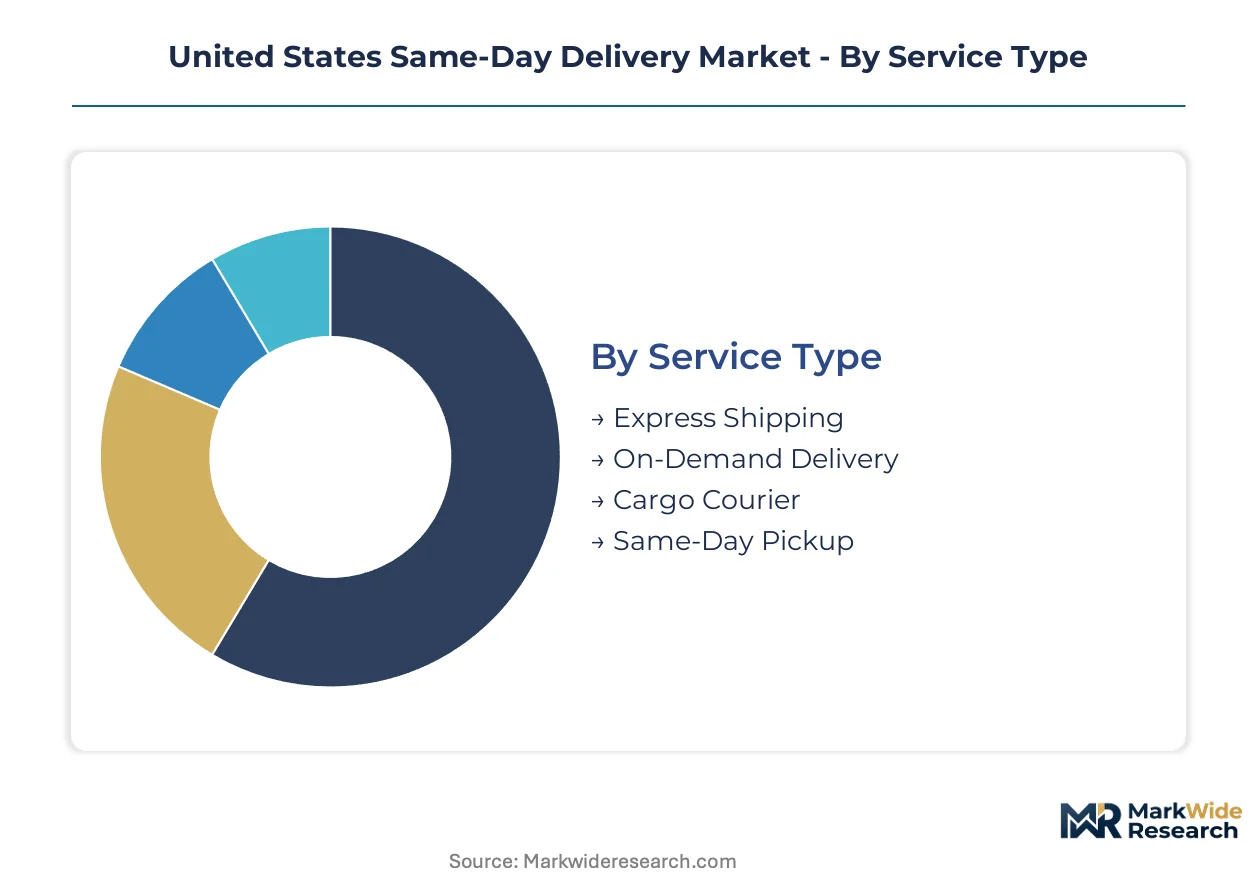
Same-day delivery segmentation reveals how infrastructure specialization divides operational economics. Service velocity, vehicle type, and end-use temperature requirements each dictate distinct capital deployment and margin structures across the United States.
Service Type:
Velocity-based service tiers separate committed capacity from variable-demand networks, with technology investment intensity scaling directly against promised delivery windows.
- Express Shipping:Scheduled same-day slots leverage pre-positioned inventory at urban micro-fulfillment nodes. E-commerce platforms in California and New York metropolitan corridors anchor volume commitments here, absorbing premium pricing for guaranteed arrival windows.
- On-Demand Delivery:Real-time dispatch platforms match latent driver supply with immediate consumer requests through dynamic pricing algorithms. Food and grocery verticals in Texas urban zones concentrate demand, though driver wage volatility compresses margins below express alternatives.
- Cargo Courier:B2B document and small parcel movements rely on dedicated motorcycle and bicycle fleets for downtown corridor penetration. Law firms and financial services in Manhattan and Chicago Loop districts sustain this segment.
- Same-Day Pickup:Consumer-directed retrieval from retail locations or lockers eliminates last-mile driver costs entirely. Big-box retailers in Florida suburban markets are expanding locker density to offset delivery labor inflation.
Mature deployment sits with Express Shipping. Newer deployment is concentrated in Same-Day Pickup.
End User:
Customer-type segmentation tracks how inventory ownership and temperature requirements reshape fleet composition and warehouse proximity decisions.
- E-Commerce:Platform-controlled fulfillment networks demand hyperlocal warehousing within fifty miles of dense demand clusters. Amazon and Walmart captive logistics in California, Texas, and New York justify dedicated electric van fleets through volume density.
- Retail:Brick-and-mortar stores repurposing inventory as distributed fulfillment nodes face SKU fragmentation challenges. Department store chains in Illinois and Ohio are retrofitting backrooms for ship-from-store capability.
- Grocery:Temperature-controlled totes and refrigerated vans add fifteen to twenty percent cost premiums over ambient delivery. Kroger and Albertsons operations in Arizona and Nevada pilot automated picking to offset labor intensity.
- Pharmaceuticals:Cold-chain compliance and chain-of-custody documentation require specialized credentialing and GPS-tracked vehicles. CVS and Walgreens distribution in Pennsylvania and New Jersey concentrates specimen and prescription delivery investment.
Platform-controlled networks dominate E-Commerce. Asset-heavy cold infrastructure is expanding fastest in Pharmaceuticals.
Delivery Mode:
Vehicle selection reflects trade-offs between payload capacity, traffic agility, regulatory permissibility, and energy cost structure across urban morphologies.
- Van:Electric and diesel vans carry eighty percent of parcel volume through dedicated route structures. EPA Phase 3 standards are accelerating fleet electrification timelines in California and Washington state markets.
- Motorcycle:Two-wheelers penetrate congestion-constrained downtown cores where parking scarcity eliminates van economics. Courier services in Miami and Atlanta deploy gasoline and electric scooters for document and small parcel urgency.
- Bicycle:Human-powered and e-bike delivery operates in zero-emission zones and pedestrian-priority districts. New York City and San Francisco municipal regulations are expanding protected lane networks that favor this mode.
- Drone:Unmanned aerial systems bypass surface congestion for lightweight, time-critical payloads. FAA Part 135 waiver expansion in Arizona and North Carolina is enabling beyond-visual-line-of-sight healthcare specimen transport pilots.
Van networks represent the established infrastructure base. Drone deployment is climbing the fastest as regulatory frameworks mature.
Application:
Use-case segmentation isolates margin and service-level requirements that determine acceptable cost structures and technology investment thresholds.
- Food Delivery:Hot and cold temperature maintenance through insulated bags and heated compartments sustains quality thresholds. DoorDash and Uber Eats platform density in Los Angeles and Chicago supports sub-thirty-minute commitments.
- Medical Supplies:Specimen integrity and pharmaceutical cold-chain compliance command premium pricing multiples above consumer goods. Hospital networks in Boston and Houston are contracting dedicated fleet capacity for STAT laboratory logistics.
- Consumer Goods:Apparel and home goods tolerate longer delivery windows and ambient conditions, enabling cost-optimized ground networks. Target and Costco same-day programs in Texas and Florida emphasize this segment for margin protection.
- Electronics:High-value, theft-sensitive products require signature capture and secure vehicle compartments. Apple and Best Buy fulfillment in Seattle and Denver metropolitan zones concentrates investment here.
Food Delivery commands the densest driver networks. Medical Supplies is gaining share fastest through specialized cold-chain infrastructure expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The New York metropolitan corridor anchors same-day delivery density through concentrated e-commerce demand and subway-adjacent micro-fulfillment nodes. Texas and California metropolitan clusters follow, each deploying distinct regulatory and infrastructure strategies.
California
Los Angeles and San Francisco Bay Area logistics networks absorb the nation's strictest commercial vehicle emissions mandates. The California Air Resources Board's Advanced Clean Trucks regulation is accelerating electric van fleet conversions ahead of federal timelines. Amazon Logistics and regional carriers are retrofitting Riverside and San Bernardino distribution hubs with charging infrastructure to maintain same-day service radii.
Texas
Dallas-Fort Worth and Houston metropolitan zones offer lower regulatory friction and abundant warehouse development land. The Texas Department of Transportation's freight corridor investments are reducing interstate congestion for last-mile feeder routes. Austin and San Antonio emerging as secondary same-day penetration targets where dedicated infrastructure remains underdeveloped.
New York
New York City's congestion pricing implementation and commercial vehicle restrictions are compressing delivery windows while elevating operational costs. The Metropolitan Transportation Authority's tolling framework is forcing fleet operators toward off-peak scheduling and bicycle courier augmentation. Brooklyn and Queens micro-fulfillment nodes are proliferating to sustain Manhattan same-hour commitments.
Florida
Miami and Tampa metropolitan corridors concentrate temperature-controlled pharmaceutical and grocery delivery investment. The Florida Department of Transportation's last-mile freight planning grants are subsidizing locker network expansion in suburban Orange and Broward counties. Orlando's tourism-driven retail density supports same-day pickup infrastructure deployment.
Illinois
Chicago's central rail and highway junction position enables Midwest same-day distribution hub functions. The Illinois Commerce Commission's commercial vehicle weight enforcement patterns are shaping fleet composition toward lighter electric vans. O'Hare corridor warehousing clusters are attracting pharmaceutical cold-chain operators serving hospital networks across the Great Lakes region.
United States Same-Day Delivery Market Competitive Landscape
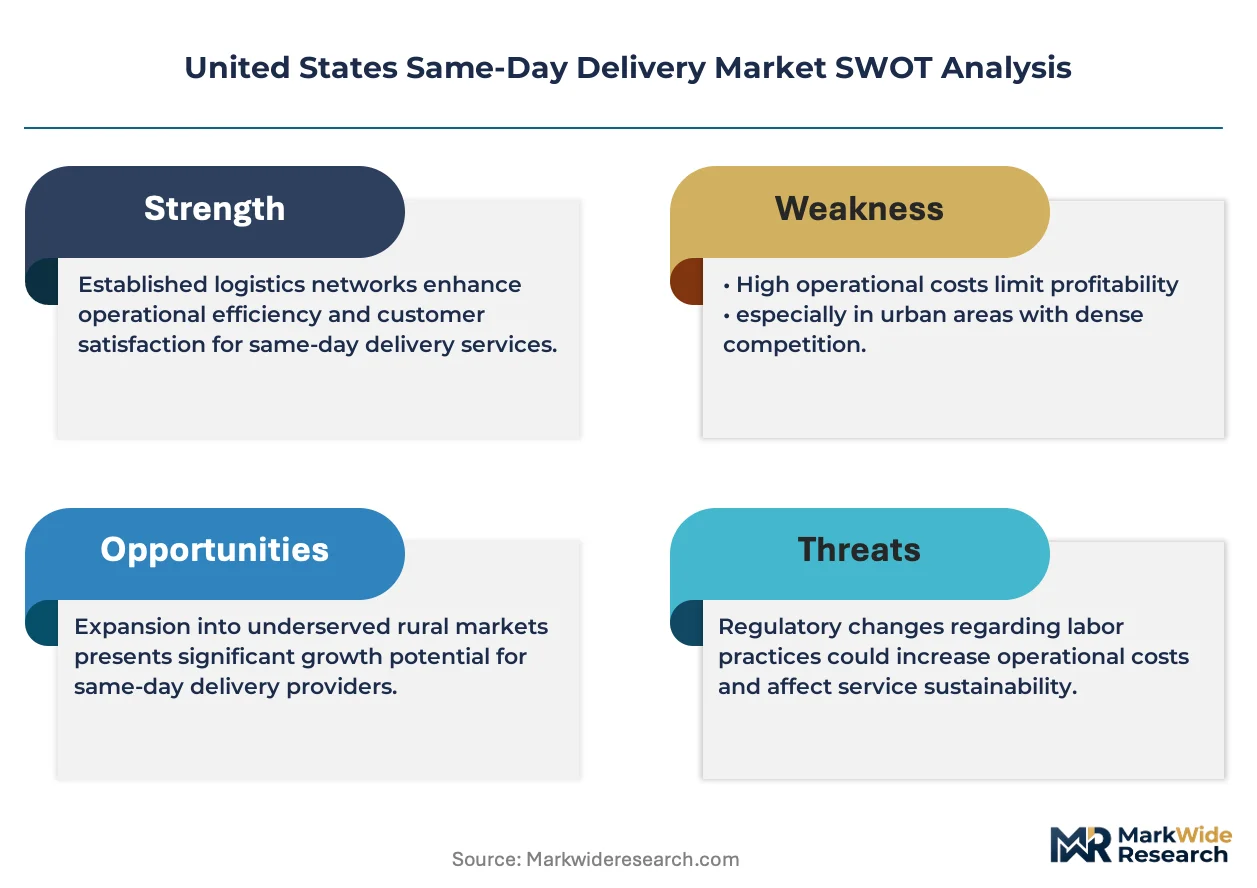
The competitive structure tilts toward integrated platform operators with captive logistics networks over pure-play carriers. National parcel incumbents defend position through proprietary routing technology and healthcare specialization. Three archetypes dominate: e-commerce-integrated platforms, legacy parcel carriers with same-day overlay, and regional specialists concentrating density in single metropolitan corridors. Capacity expansion and electric fleet conversion represent the primary competitive moves, with M&A activity targeting last-mile technology providers.
Among legacy parcel carriers, FedEx and United Parcel Service of America, Inc. exemplify the healthcare and premium commercial segment focus. Amazon Logistics occupies the platform-integrated archetype with captive demand and dedicated electric infrastructure. Regional density specialists include OnTrac and Dropoff, Inc., representing the metropolitan corridor concentration strategy where localized fleet deployment sustains cost discipline against national network overhead.
| Leading Market Players |
|---|
| FedEx |
| United Parcel Service of America, Inc. (UPS) |
| United States Postal Service (USPS) |
| DHL Group |
| OnTrac |
| Amazon Logistics |
| Dropoff, Inc. |
| Jet Delivery, Inc. |
| Need It Now Delivers |
| Others |
Value Network & Pricing Analysis
E-commerce platform concentration in California, Texas, and New York metropolitan corridors anchors subscription-based pricing as the dominant revenue model, with per-transaction alternatives losing share as merchants compete on fulfillment velocity rather than unit economics alone.
Pricing Analysis
Value-based pricing tied to delivery speed guarantees commands premium multiples in healthcare and pharmaceutical verticals, where specimen integrity and cold-chain compliance justify cost premiums over ambient consumer goods. Price differentiation rests on temperature-control requirements and time-criticality, with medical supplies and food delivery segments absorbing higher rates than electronics and apparel. Cost compression in standard parcel tiers intensifies as driver wage inflation in metropolitan markets squeezes margins below sustainability thresholds. Small and mid-sized regional carriers exhibit highest price sensitivity, while integrated platform operators with captive demand demonstrate lowest sensitivity due to volume-scale advantages.
Supply Chain Analysis
OSHA warehouse safety certification and FAA Part 135 airspace qualifications gate entry for automated fulfillment and drone delivery operations, concentrating supplier power among compliant infrastructure providers. Battery cell supply draws from China, South Korea, and Japan, with lithium-ion processing capacity limitations creating upstream bottlenecks for electric van fleet conversions. Electric drivetrain components and specialized cold-chain totes constitute critical input dependencies. Single-source vulnerability in semiconductor-based routing hardware exposes dispatch platforms to automotive and consumer electronics demand competition. Distribution feeds from hyperlocal micro-fulfillment nodes positioned within fifty miles of dense demand clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a vertical-integration race where captive control over electric vehicle fleets and last-mile routing algorithms separates margin-sustainable operators from cost-vulnerable competitors.
For Market Incumbents: Cement density advantages in California, Texas, and New York corridors through proprietary charging infrastructure deployment and exclusive micro-fulfillment node leases. Deepen backward integration into electric van manufacturing partnerships to offset battery supply constraints. Lock in healthcare and pharmaceutical accounts with dedicated cold-chain capacity before specialized entrants capture premium segments. For New Entrants and Emerging Players: Rural corridor specialists in secondary Texas and Florida metropolitan zones face limited dedicated same-day infrastructure and lower incumbent saturation. Target Austin and San Antonio emerging zones with autonomous ground vehicle pilots in gated communities and industrial parks. Pursue hospital network contracts for STAT laboratory logistics as the most penetrable premium segment. For Investors and Strategic Acquirers: Distressed-cycle entries favor regional density specialists with established fleet deployment in single metropolitan corridors and compliant OSHA safety records. Long-term viability hinges on electric fleet conversion completion and regulatory airspace access for drone expansion. Watch FAA Part 135 waiver expansion velocity as the primary inflection signal for autonomous aerial delivery economics.| Strategic Initiative | Industry Significance |
|---|---|
| Electric Fleet Conversion | EPA Phase 3 compliance and IRA commercial vehicle credits compress total cost of ownership parity timelines against diesel alternatives. |
| Micro-Fulfillment Node Expansion | Hyperlocal warehousing within fifty miles of destination enables same-hour service commitments previously structurally impossible. |
| Drone Delivery Pilot Scaling | FAA Part 135 waiver frameworks open beyond-visual-line-of-sight airspace for healthcare specimen transport in suburban zones. |
| Healthcare Cold-Chain Specialization | Temperature-controlled pharmaceutical delivery commands premium pricing multiples and dedicated fleet investment from hospital networks. |
| Dynamic Route Optimization Platform Acquisition | Algorithmic dispatch absorption eliminates manual routing delays and middle-management overhead in grocery and pharmaceutical verticals. |
Research Methodology
Independent corroboration across fleet operations executives, warehouse automation engineers, FAA regulatory affairs specialists, and hospital supply chain directors underwrites the qualitative findings. Primary interviews with logistics platform CTOs, electric vehicle procurement leads, and last-mile routing software architects combined with secondary validation from DOT freight statistics, FAA waiver filings, EPA emissions compliance databases, and OSHA workplace safety incident reports. Bottom-up volume estimates triangulate against top-down market sizing across service type, end user, delivery mode, and application dimensions.
Rate-of-change decomposition separates volume growth from pricing evolution across the projection horizon. Segmentation modeling incorporates service velocity tiers, vehicle type classifications, temperature requirements, and metropolitan density bands. CAGRs derive from trend extrapolation of e-commerce penetration curves, electric fleet adoption schedules, and regulatory airspace opening timelines. Forecast inputs include driver wage trajectory assumptions and lithium-ion cell supply expansion estimates.
Revisions become necessary when FAA drone integration rules accelerate or California AB 5 appellate rulings expand employee reclassification mandates beyond current boundaries. Forecasts reflect documented assumptions regarding infrastructure buildout rates and regulatory permissibility trajectories. A model refresh is warranted upon material change in federal commercial vehicle credit policy or battery supply chain concentration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
E-Commerce Solutions
Hungary E-Commerce Market
E-Commerce Solutions
Switzerland E-Commerce Market
E-Commerce Solutions
Multi-Channel E-Commerce Software Market
E-Commerce Solutions
Australia E-Commerce Market
E-Commerce Solutions
Hyperlocal Delivery App Market
E-Commerce Solutions
Global Digital Commerce Market
E-Commerce Solutions
Spain E-Commerce Logistics Market
E-Commerce Solutions
Express and Parcel Market
E-Commerce Solutions
Oman E-Commerce Market
E-Commerce Solutions
Italy E-Commerce Market
E-Commerce Solutions
Global B2B E-Commerce Market
E-Commerce Solutions
France E-Commerce Market
E-Commerce Solutions
North America B2B E-Commerce Market
E-Commerce Solutions
E-Commerce Fashion Accessories Market
E-Commerce Solutions
Automotive E-Commerce Market
E-Commerce Solutions
Pharmaceutical E-Commerce Market