
 Art Supplies Market | 2026-2036
Art Supplies Market Size, Share, and Industry Trends Forecast 2026-2036
Art Supplies Market Analysis
Hobbyist engagement through online tutorials and social media platforms is rebalancing the end-use vertical mix, pulling demand away from institutional procurement toward individual creators. Faber-Castell leverages its heritage in precision drawing instruments to sustain loyalty among professional illustrators and architects across European markets. Golden Artist Colors anchors its position in North America through intensive R&D in acrylic pigment chemistry and direct artist education programs. Crayola LLC dominates the juvenile segment with controlled distribution through mass retail and school procurement channels.
Art supplies encompass pigments, binders, substrates, and tools engineered for visual expression across painting, drawing, sculpting, and crafting applications, with acrylic emulsions typically containing 30-50% pigment volume concentration for optimal lightfastness and adhesion. These materials serve commercial illustrators, fine artists, educators, and recreational creators in producing durable, archivally stable works. The painting segment leads value generation due to premium pigment costs and recurring canvas consumption, while the online platforms distribution channel represents the fastest-growing structural pocket as algorithm-driven discovery and subscription replenishment models reshape artist purchasing behavior. The institutions end-user category remains mature with stable but price-sensitive volume, whereas the professionals segment commands the deepest margin pools through loyalty to branded, conservation-grade materials.
EPA oversight governs volatile organic compound limits in solvent-based mediums sold in the United States, while REACH restricts hazardous pigment classifications across European formulations, and California's Proposition 65 mandates explicit labeling for titanium dioxide and crystalline silica content in artist materials. These frameworks elevate compliance costs for imported formulations while creating market access barriers for uncertified producers. Stakeholders must monitor evolving chemical hazard classifications and channel-specific traceability requirements as regulatory divergence between jurisdictions intensifies sourcing complexity.
Market Dynamics
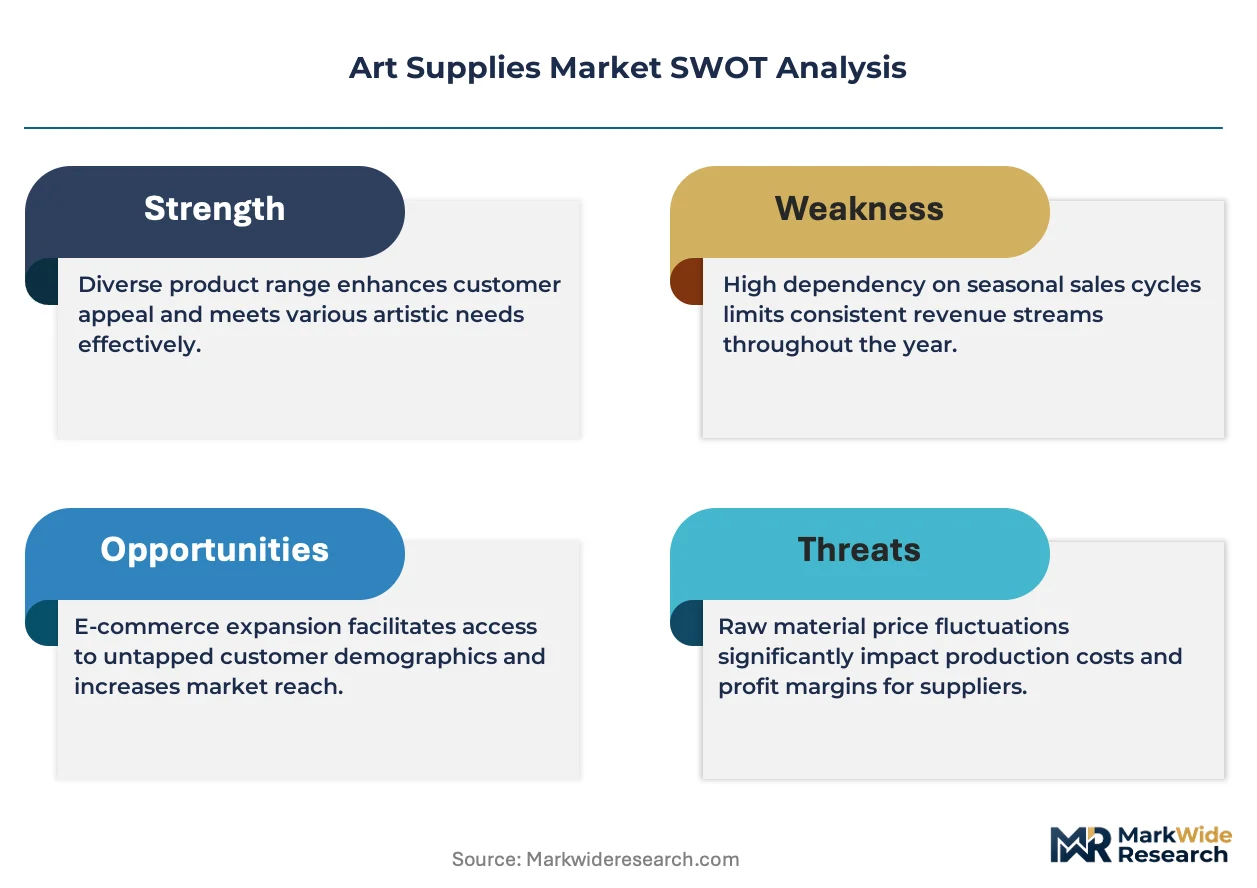
REACH compliance in Europe and EPA volatile organic compound limits in the United States are forcing pigment reformulation across solvent-based mediums, elevating R&D costs while compressing margins for imported formulations.
Growth Catalysts
- Social media-driven hobbyist expansion:Instagram and TikTok tutorials pull demand away from institutional procurement toward individual creators, expanding the consumer base beyond traditional school and museum buyers.
- E-commerce channel maturation:Direct-to-consumer platforms capture growing share of professional and amateur purchases through algorithm-driven discovery and subscription replenishment models.
- Acrylic emulsion chemistry advances:Intensive R&D in pigment volume concentration optimization improves lightfastness and adhesion, sustaining premium pricing for conservation-grade materials.
Market Restraints
- Pigment input cost volatility:Cadmium and cobalt compound prices fluctuate with mining supply disruptions, squeezing margin pools for professional-grade paint manufacturers.
- Regulatory friction from chemical hazard reclassification:ECHA's evolving titanium dioxide and crystalline silica classifications create labeling complexity and inventory obsolescence risk across European distribution.
- Digital art substitution threat:Procreate and Adobe Fresco adoption among commercial illustrators reduces recurring canvas and medium consumption for certain professional segments.
Strategic Opportunities
- Underpenetrated Indian amateur segment:Rising disposable income and urban craft culture expansion create white space for mid-premium watercolor and acrylic sets outside institutional procurement channels.
- EU Green Deal regulatory tailwind:Bio-based binder development incentives accelerate demand for plant-derived acrylic alternatives among environmentally conscious European hobbyists.
- Subscription box distribution innovation:Curated monthly pigment and substrate deliveries build predictable recurring revenue while reducing customer acquisition costs for direct-to-consumer brands.
Industry Challenges
- Conservation-grade certification timeline compression:ASTM D4236 and EN 71-3 testing protocols extend product launch cycles, delaying revenue recognition for reformulated pigment lines.
- Legacy ERP integration friction:Batch manufacturing systems struggle to accommodate made-to-order personalization demanded by online direct sales channels.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Art Supplies Market |
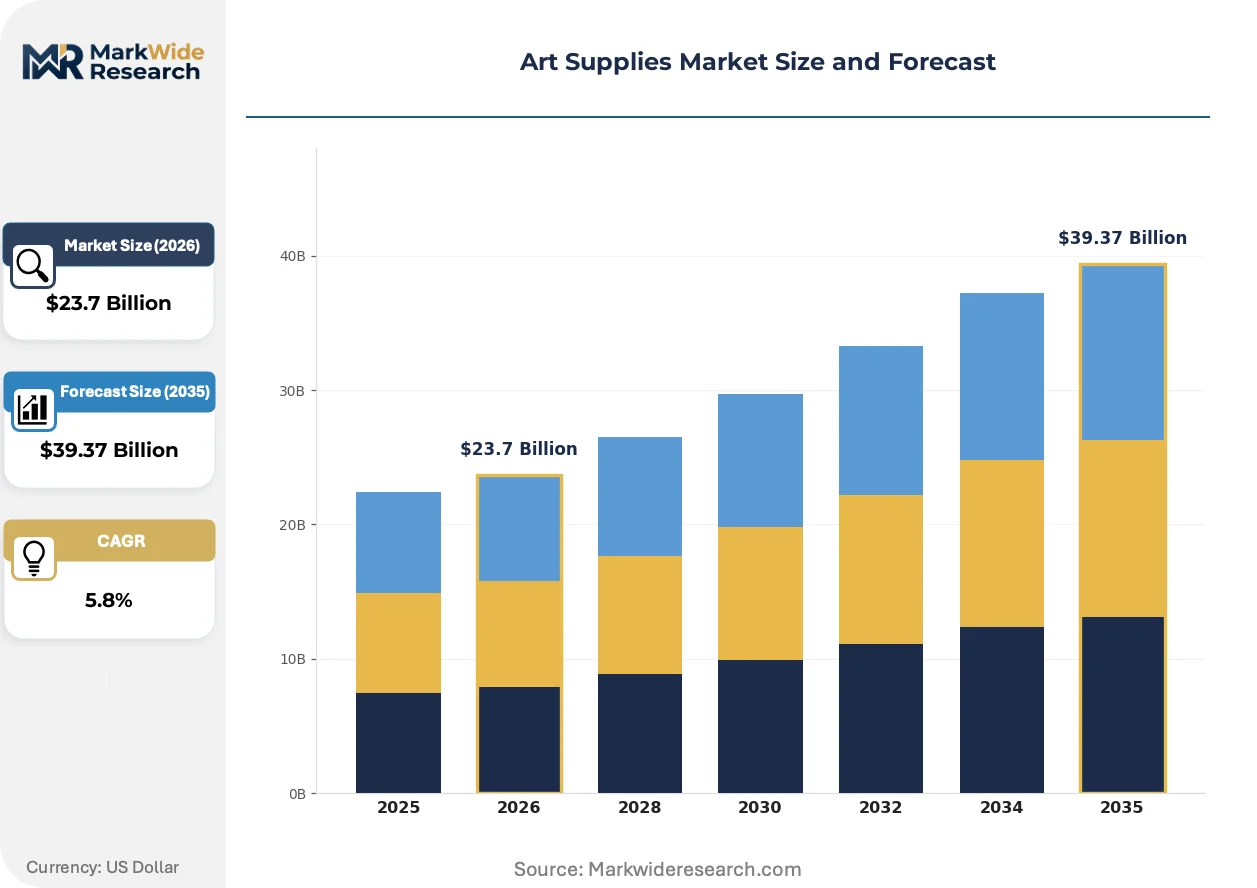
| Market Size in 2026 | $23.7 Billion |
| Market Size in 2035 | $39.37 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Painting, Drawing, Sculpting, Crafting Material: Paper, Canvas, Clay, Wood End User: Students, Professionals, Hobbyists, Institutions Distribution Channel: Retail Stores, Online Platforms, Direct Sales, Wholesalers |
| Companies Covered | Staedtler Mars GmbH & Co. KG, Colart International Ltd., Faber-Castell, Royal Talens, Winsor & Newton, Crayola LLC, Newell Brands, Golden Artist Colors Inc., F.I.L.A. Fabbrica Italiana Lapis ed Affini S.p.A., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Art Supplies Market Emerging Trajectories
Algorithmic content discovery and direct artist education programs are compressing traditional wholesale distribution layers while elevating technical performance expectations for amateur-grade materials.
Water-mixable oil mediums are overtaking traditional solvent-based formulations among urban studio artists constrained by ventilation limitations and residential lease restrictions. Hobbyists in dense European and East Asian cities adopt these binders fastest, eliminating mineral spirits handling while preserving blending characteristics. Gallery representation standards are adjusting as archival stability data accumulates, compressing the quality gap between water-mixable and conventional oil paint tiers.
California's Proposition 65 mandates explicit titanium dioxide and crystalline silica labeling for artist materials sold in the state, creating a template other jurisdictions are evaluating. Manufacturers serving the US market must maintain dual inventory streams or universal warning labels, elevating packaging complexity. Professional-grade suppliers absorb these costs most easily while economy-tier importers face market access barriers.
Subscription replenishment models now capture significant share of recurring substrate purchases from plein air painters and art educators. Direct-to-consumer platforms displace specialty retail for routine canvas and paper restocking, though brick-and-mortar retains importance for pigment testing and tactile evaluation. This behavioral shift concentrates most visibly in the United States, where fulfillment infrastructure and credit-card recurring payment adoption outpace other developed markets.
Art Supplies Market Segmentation
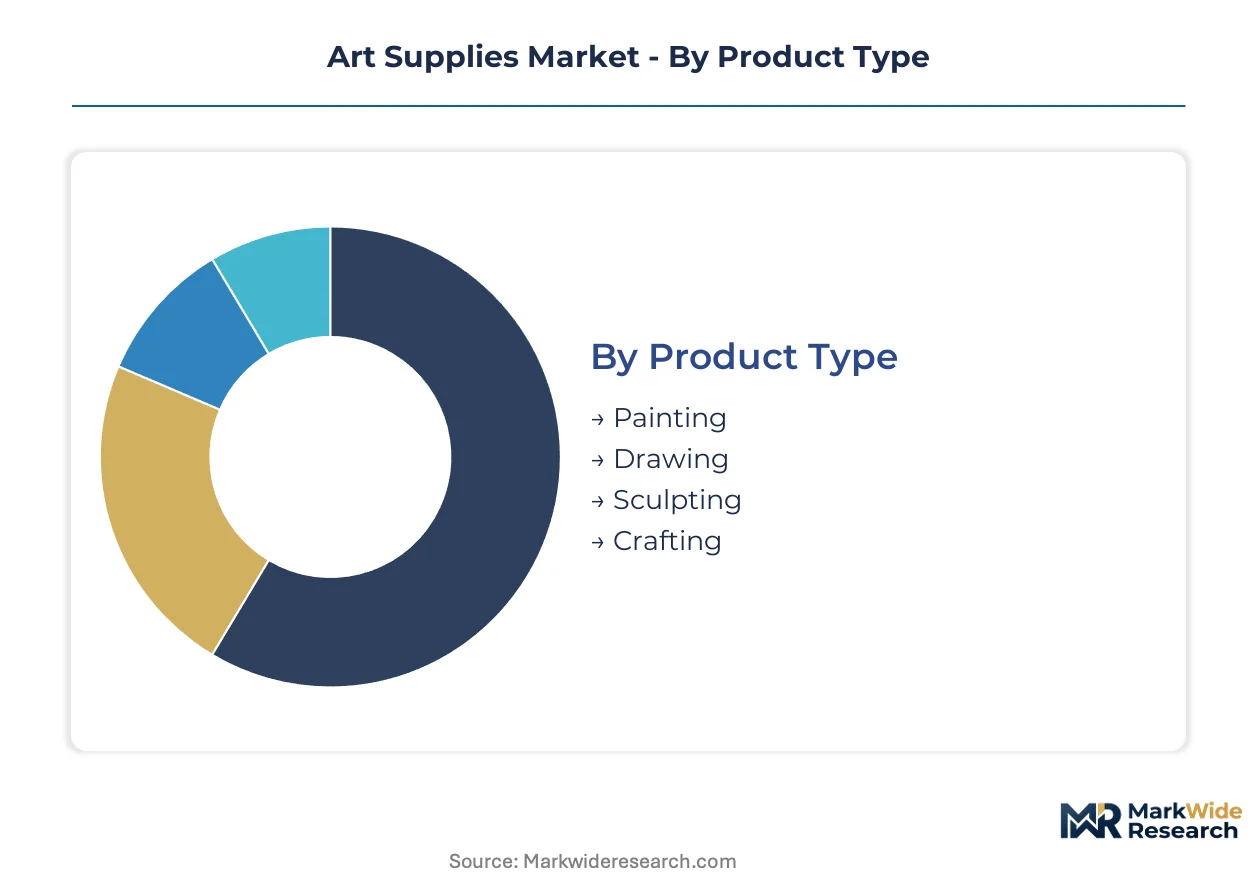
Art supplies segmentation reveals divergent margin structures across product chemistry, substrate engineering, and channel economics. Understanding these axes exposes where premium pricing endures versus where volume commoditization dominates procurement decisions.
Product Type:
Pigment chemistry and binder formulation sophistication separate professional-grade materials from mass-market alternatives.
- Painting:Acrylic emulsions with 30-50% pigment volume concentration command premium shelf space through conservation-grade lightfastness ratings. Demand concentrates among professional illustrators and architectural renderers in the United States, where direct-to-consumer subscription models capture recurring canvas and medium replenishment.
- Drawing:Precision graphite grading and lightfast ink formulations serve technical illustrators and fine artists requiring archival stability. European markets drive specification intensity through REACH-compliant pigment classifications that elevate R&D costs for imported formulations.
- Sculpting:Polymer clay and air-dry compounds target educational institutions and recreational creators with volume-driven procurement.
- Crafting:Mixed-media adhesives and embellishment materials serve hobbyist expansion fueled by Instagram and TikTok tutorial engagement.
Mature deployment sits with Drawing instruments. Newer deployment is concentrated in Crafting materials.
Material:
Substrate engineering determines archival performance and price positioning across conservation and economy tiers.
- Paper:Acid-free cotton rag and wood pulp formulations span sketching pads to museum-grade watercolor sheets. Japanese washi and European mould-made papers anchor premium positioning among printmakers and conservators.
- Canvas:Cotton duck and linen supports with acrylic or oil priming sustain professional studio consumption. United States plein air painters drive subscription replenishment models through algorithm-driven discovery platforms.
- Clay:Earthenware, stoneware, and polymer compounds serve ceramic studios and educational kiln programs with distinct firing requirements.
- Wood:Basswood panels and birch plywood supports target encaustic and mixed-media artists seeking rigid substrates.
Canvas substrates generate the steepest expansion trajectory in direct-to-consumer channels. Paper maintains institutional procurement dominance.
End User:
Customer sophistication and purchase frequency create distinct margin pools across amateur and professional cohorts.
- Professionals:Conservation-grade material loyalty sustains deepest margin pools through branded pigment lines and substrate certification. North American illustrators and gallery-represented artists absorb premium pricing for ASTM D4236-tested formulations.
- Hobbyists:Social media-driven tutorial engagement expands the consumer base beyond traditional procurement channels. Algorithmic content discovery on TikTok and Instagram pulls demand toward individual creators with mid-premium watercolor and acrylic sets.
- Students:Volume-sensitive educational procurement concentrates in mass retail and school district contracts.
- Institutions:Museums and university art programs maintain stable but price-sensitive volume with extended purchase cycles.
Professional-grade deployment commands premium positioning. Hobbyist deployment is expanding most quickly through digital channel maturation.
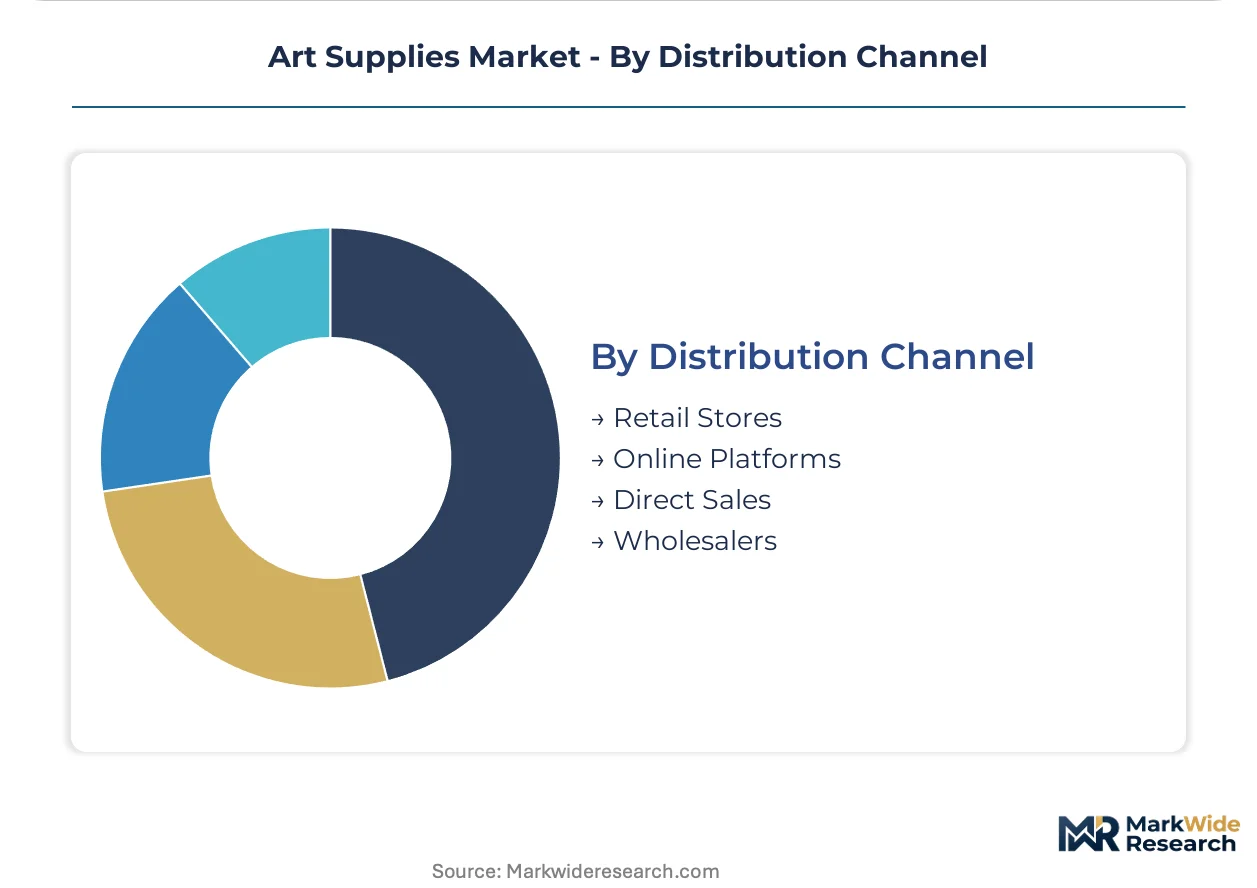
Distribution Channel:
Fulfillment infrastructure and customer acquisition economics determine channel viability across routine replenishment and tactile evaluation needs.
- Online Platforms:Algorithm-driven discovery and subscription replenishment models reshape artist purchasing behavior. United States fulfillment density and credit-card recurring payment adoption outpace other developed markets for canvas and paper restocking.
- Retail Stores:Specialty chains retain importance for pigment testing and tactile evaluation despite share erosion. European urban centers sustain boutique art supply presence through professional foot traffic.
- Direct Sales:Manufacturer-owned channels bypass wholesale margins for conservation-grade material loyalty programs.
- Wholesalers:Institutional procurement and educational contracts maintain volume throughput with compressed margins.
Wholesale deployment retains institutional lock-in. Online platform deployment is gaining share fastest through behavioral shifts in routine replenishment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Free-trade zones and creative-industry tax incentives in the United States, Germany, China, India, and Japan concentrate art supply manufacturing and distribution infrastructure. These jurisdictions deploy distinct regulatory frameworks governing chemical safety, e-commerce fulfillment, and cultural sector subsidies that reshape competitive access and pricing structures.
United States
Direct-to-consumer subscription models and algorithm-driven discovery platforms capture growing share of professional and amateur purchases. EPA volatile organic compound limits govern solvent-based medium formulations, elevating compliance costs for imported products. Brooklyn and Los Angeles anchor independent artist supply retail clusters where tactile evaluation retains importance despite online channel growth.
Germany
Precision drawing instrument manufacturing sustains export-oriented production through heritage craft certification programs. REACH compliance and ECHA hazard reclassifications force pigment reformulation across European-bound formulations, compressing margins for non-compliant imports. Nuremberg and Stuttgart concentrate specialist manufacturer headquarters and testing laboratory infrastructure.
China
Mass-market substrate and tool fabrication serves global private-label demand through integrated manufacturing zones. GB standards and MIIT industrial policy guide chemical safety compliance for domestic consumption and export certification. Shenzhen and Yiwu cluster e-commerce fulfillment infrastructure connecting factory output to cross-border direct-to-consumer platforms.
India
Rising disposable income and urban craft culture expansion create white space for mid-premium watercolor and acrylic sets outside institutional procurement. BIS certification requirements and DGFT import regulations shape competitive access for foreign pigment formulations. Mumbai and Delhi-NCR concentrate specialty retail and direct-to-consumer brand headquarters targeting amateur segment growth.
Japan
Traditional washi paper and sumi ink production sustains premium export positioning through intangible cultural heritage designation. METI standards and JIS certification protocols govern archival performance claims and chemical safety labeling. Kyoto and Tokyo anchor specialist manufacturer clusters where craft preservation intersects with contemporary artist education programming.
Art Supplies Market Vendor Landscape
Top-tier vendors anchor conservation-grade pigment chemistry and heritage brand loyalty, while mid-tier specialists and mass-market fabricators compete on volume and channel access. The vendor base stratifies across professional-grade certification holders, private-label manufacturers, and direct-to-consumer innovators. Three archetypes dominate: heritage European precision instrument makers, North American acrylic chemistry specialists, and Asian mass-market substrate producers. Competitive moves concentrate on direct-to-consumer platform development and regulatory compliance certification acceleration.
Within the heritage European tier, Staedtler Mars GmbH & Co. KG and Faber-Castell exemplify precision drawing instrument manufacturers sustaining professional loyalty through archival performance certification. Among North American conservation-grade specialists, Golden Artist Colors Inc. occupies a position representing intensive R&D investment in acrylic emulsion chemistry. F.I.L.A. Fabbrica Italiana Lapis ed Affini S.p.A. sits within the integrated European creative materials group archetype, spanning multiple product categories and price tiers.
| Leading Market Players |
|---|
| Staedtler Mars GmbH & Co. KG |
| Colart International Ltd. |
| Faber-Castell |
| Royal Talens |
| Winsor & Newton |
| Crayola LLC |
| Newell Brands |
| Golden Artist Colors Inc. |
| F.I.L.A. Fabbrica Italiana Lapis ed Affini S.p.A. |
| Others |
Supply Flow & Price Mechanics
Cadmium and cobalt compound price indices cascade through pigment formulation costs into three-tier pricing structure across premium, standard, and economy levels. REACH compliance investments and EPA volatile organic compound testing requirements compound input expenses, forcing manufacturers to absorb margin compression or pass costs downstream to institutional buyers and hobbyist segments with divergent price elasticity.
Pricing Analysis
Short lead-time premiums attach to conservation-grade acrylic emulsions and ASTM D4236-certified drawing instruments demanded by professional illustrators facing project deadlines. Spot inventory discounts emerge for economy-tier watercolor sets and student-grade substrates where brand loyalty remains thin. Price differentiation separates conservation-grade certification from uncertified alternatives, with pigment volume concentration and lightfastness ratings as primary tiering mechanisms. Pricing pressure stems from cadmium pigment substitution costs and crystalline silica labeling mandates, squeezing mid-tier manufacturers most acutely while premium suppliers absorb compliance investments through established artist loyalty programs.
Supply Chain Analysis
Single-source vulnerability sits with Chinese mass-market substrate fabrication and German precision instrument manufacturing, where heritage craft certification programs sustain irreplaceable technical capabilities. Raw material dependencies center on mined cadmium and cobalt compounds, cotton rag pulp for acid-free papers, and petroleum-derived acrylic polymer feedstocks. Tariff exposure runs through cross-border pigment formulations facing evolving ECHA hazard reclassifications and dual inventory requirements for California Proposition 65 labeling. Distribution runs through direct-to-consumer platforms for routine replenishment, specialty retail chains for tactile evaluation, and institutional procurement contracts for educational volume.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Consolidation pressure intensifies as regulatory compliance costs and R&D investment thresholds eliminate smaller pigment formulators unable to sustain dual certification pathways. REACH and EPA divergence forces capital allocation decisions that favor scaled operators with dedicated testing laboratory infrastructure.
For Market Incumbents: Lock in conservation-grade certification timelines by accelerating ASTM D4236 and EN 71-3 testing protocol completion ahead of reformulation deadlines. Secure backward integration into acrylic polymer feedstocks or cotton rag pulp supply to buffer cadmium price volatility and substrate cost fluctuations. Channel control through direct-to-consumer subscription platforms insulates against specialty retail erosion while capturing recurring revenue from plein air painters and art educators. For New Entrants and Emerging Players: EU Green Deal bio-based binder incentives in Germany and France open a window for plant-derived acrylic alternatives targeting environmentally conscious European hobbyists. Underpenetrated Indian amateur segments outside institutional procurement channels offer white-space entry for mid-premium watercolor and acrylic sets distributed through Mumbai and Delhi-NCR direct-to-consumer platforms. Algorithmic content discovery partnerships with TikTok and Instagram tutorial creators provide lower customer acquisition costs than traditional wholesale penetration. For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-cap specialists with captive certification capabilities in Nuremberg and Stuttgart manufacturing clusters. Long-term viability hinges on conservation-grade pigment chemistry R&D depth and direct-to-consumer platform infrastructure rather than volume-driven mass-market positioning. Watch for inflection signals in ECHA titanium dioxide reclassification enforcement severity, which would accelerate compliance-driven consolidation among uncertified importers.| Strategic Initiative | Industry Significance |
|---|---|
| Direct-to-Consumer Platform Development | Algorithm-driven discovery on Instagram and TikTok captures recurring subscription revenue from hobbyist expansion. |
| Bio-Based Binder R&D Investment | Plant-derived acrylic alternatives align with EU Green Deal incentives and REACH-compliant pigment reformulation pathways. |
| Conservation-Grade Certification Acceleration | ASTM D4236 and EN 71-3 testing completion creates market access barriers for uncertified competitors. |
| Subscription Replenishment Model Launch | Curated monthly pigment and substrate deliveries reduce customer acquisition costs for canvas and paper restocking. |
| Heritage Brand Education Programming | Direct artist education sustains professional loyalty among illustrators and architects across European markets. |
Methodological Framework
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis, cross-referenced with primary interviews involving pigment formulation chemists, specialty retail procurement managers, art education program directors, and direct-to-consumer platform operators. Secondary sources encompassed EPA volatile organic compound compliance databases, ECHA REACH registration dossiers, California Proposition 65 enforcement records, and customs import documentation for cadmium and cobalt compound flows. Bottom-up segmentation modeling triangulated against top-down market sizing from trade association revenue aggregates.
Data-stream reconciliation across product chemistry tiers, substrate engineering grades, end-user sophistication levels, and distribution channel economics generated volume and value estimates across the projection horizon. Segmentation dimensions encompassed pigment concentration tiers, archival certification status, professional versus amateur purchase frequency, and online versus tactile evaluation channel preference. CAGRs derived from historical growth rate analysis adjusted for regulatory intervention timing and social media platform adoption curves in hobbyist segments.
The model assumes a particular technology adoption path; alternative pathways for digital art substitution through Procreate and Adobe Fresco would alter the outlook for traditional canvas and medium consumption among commercial illustrators. Forecasts embed assumptions regarding ECHA hazard classification stability and EPA enforcement consistency that regulatory divergence could revise. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Crafts & Hobbies
Global Personalized Gifts Market
Crafts & Hobbies
Europe Handicrafts Market
Crafts & Hobbies
United States Handicrafts Market
Crafts & Hobbies
Macrame Products Market
Crafts & Hobbies
Global K-12 Arts and Crafts Material Market
Crafts & Hobbies
Art and Craft Tools Market
Crafts & Hobbies
Ironing Beads Market
Crafts & Hobbies
Water Color Palette Market
Crafts & Hobbies
North America Handicrafts Market
Crafts & Hobbies
Craft Supplies Market
Crafts & Hobbies
Daughter Craft Market
Crafts & Hobbies
Dibber Market
Crafts & Hobbies
Handicrafts Market
Crafts & Hobbies
Needlecraft Patterns Market