
 Global Keratometers Market | 2026-2036
Global Keratometers Market Size, Share, and Industry Trends Forecast 2026-2036
Global Keratometers Market Foresight
Refractive surgery clinics are bifurcating from general ophthalmology practices as the dominant buyer archetype for precision corneal topography instruments. Carl Zeiss Meditec leverages its vertical integration in optical component fabrication to sustain premium positioning across European and Asian markets. Topcon Corporation anchors its competitive stance through dense distribution networks in North American eye care centers. NIDEK Co., Ltd. specializes in compact automated platforms that compete effectively in space-constrained Japanese and Southeast Asian clinics.
Keratometers are ophthalmic diagnostic instruments that quantify anterior corneal curvature through reflected mire image analysis, typically resolving curvature radii from 5.5 mm to 9.0 mm with dioptric precision of 0.125 D. These devices serve as foundational tools for contact lens specification, intraocular lens power calculation, and preoperative screening in refractive and cataract procedures. Automated keratometers now lead volume shipments due to throughput advantages in high-patient-flow ophthalmology clinics, while Scheimpflug imaging platforms capture expanding margin pools by integrating tomographic data beyond simple curvature mapping. Handheld devices represent the fastest-growing product configuration, driven by portable deployment needs in mobile eye care programs and emerging-market optical retailers lacking fixed infrastructure.
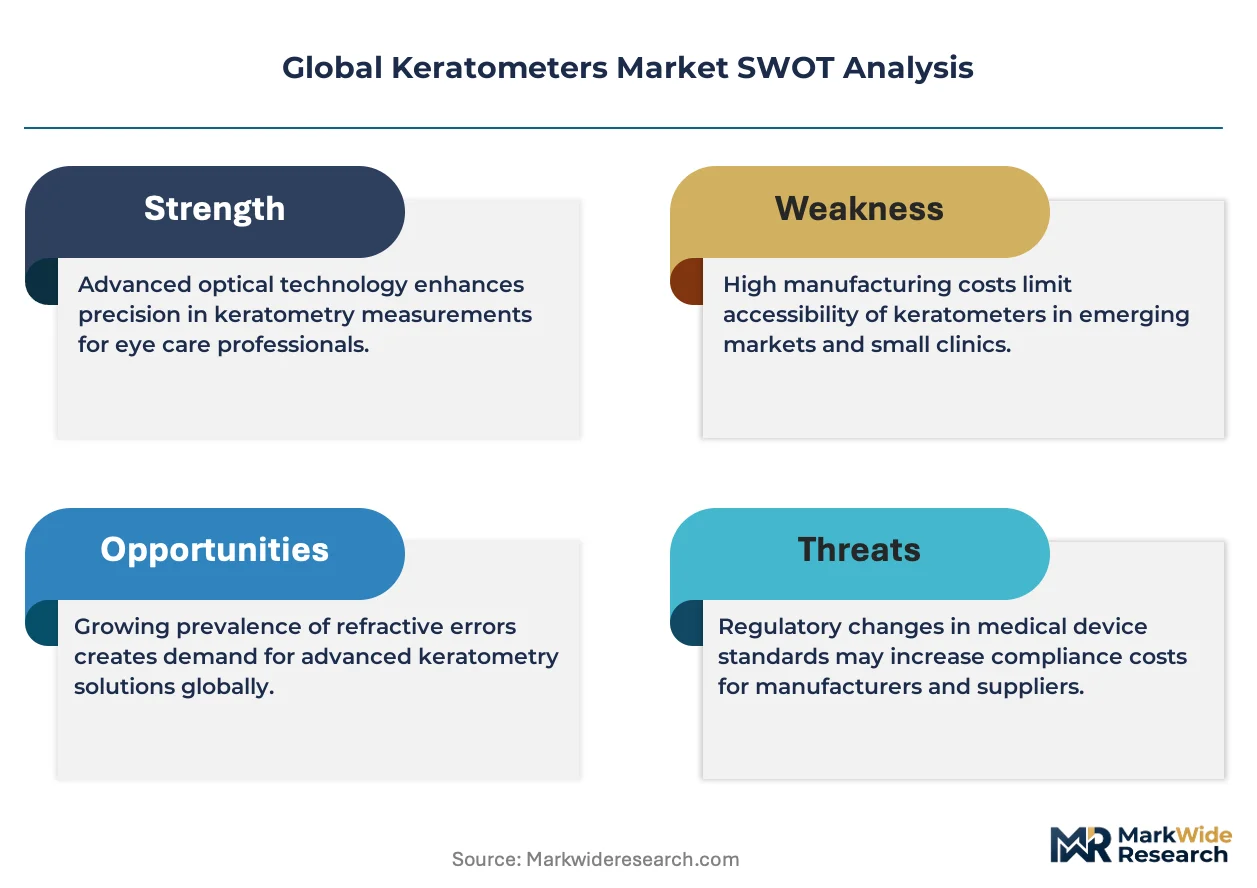
FDA 510(k) clearance pathways and EU MDR conformity requirements shape product development timelines and commercial access for keratometer manufacturers serving Western markets. ISO 10993 biocompatibility standards and IEC 60601-1 electrical safety protocols further constrain design choices for devices with patient-contact components. Stakeholders must monitor evolving regulatory divergence between FDA and notified body interpretations of software-as-a-medical-device classifications for AI-enhanced corneal analysis modules.
Market Dynamics
Automated keratometer platforms are displacing manual optical systems as refractive surgery clinics standardize on throughput-optimized diagnostic protocols under tightening FDA 510(k) scrutiny for ophthalmic device software.
Growth Catalysts
- EU MDR conformity expansion:Updated medical device regulations in Europe are accelerating replacement cycles for legacy keratometer inventories as clinics face notified body recertification deadlines.
- Scheimpflug-tomography convergence:Integration of anterior segment imaging with traditional curvature measurement is pulling upgrade demand from cataract surgery centers seeking consolidated diagnostic workstations.
- Mobile eye care deployment:Government-funded rural vision screening programs across India and Southeast Asia are generating portable device procurement volumes.
Market Restraints
- Precision optical component supply concentration:German and Japanese suppliers dominate high-grade lens fabrication, creating single-source vulnerability for mid-tier device assemblers.
- AI diagnostic module regulatory friction:Divergent FDA and notified body interpretations of software-as-a-medical-device classification are extending development timelines for algorithm-enhanced platforms.
- Optical coherence tomography substitution:OCT systems offering full corneal pachymetry mapping are compressing addressable market for standalone curvature-only instruments.
Strategic Opportunities
- Brazilian refractive surgery expansion:Underpenetrated private clinic networks in São Paulo and Rio de Janeiro present first-mover positioning for automated platform vendors.
- Tele-ophthalmology diagnostic nodes:Remote curvature screening protocols are creating demand for cloud-connected handheld units with embedded quality assurance algorithms.
- Japan METI medical device export incentives:Domestic manufacturers receive subsidized certification support for PMDA-compliant platforms targeting ASEAN markets.
Industry Challenges
- Biomedical optics engineering talent scarcity:Specialized expertise in Scheimpflug camera calibration and mire image processing is concentrating at Carl Zeiss Meditec and Topcon, constraining competitor R&D velocity.
- Legacy EMR integration complexity:Proprietary data formats from installed base keratometers resist interoperability with modern hospital information systems, delaying sales cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Keratometers Market |
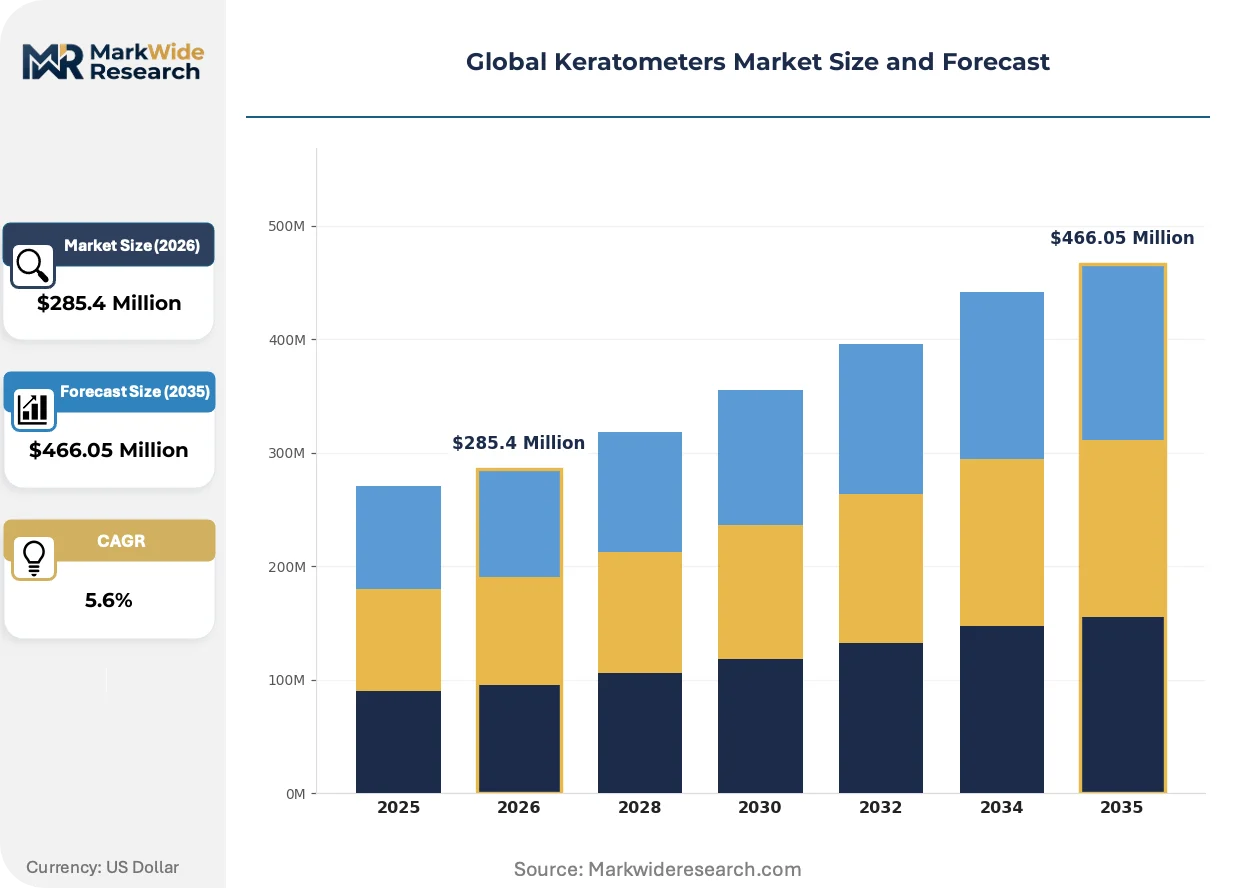
| Market Size in 2026 | $285.4 Million |
| Market Size in 2035 | $466.05 Million |
| CAGR (2026 – 2036) | 5.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Manual Keratometers, Automated Keratometers, Handheld Devices, Tabletop Devices Technology: Placido Disk, Scheimpflug Imaging, Optical Coherence Tomography, Slit-Scan Application: Corneal Curvature Measurement, Astigmatism Diagnosis, Preoperative Assessment, Contact Lens Fitting End User: Ophthalmology Clinics, Eye Care Centers, Research Institutes, Optical Retailers |
| Companies Covered | Carl Zeiss Meditec, Topcon Corporation, NIDEK Co., Ltd., Haag-Streit AG, Essilor International, Canon Inc., Reichert Inc., Luneau Technology, Oculus Optikgeräte GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Keratometers Market Shifts & Advancements
Device architectures are fragmenting between premium integrated workstations and stripped-down portable units as buyer segments diverge in technical requirements and capital deployment capacity.
Scheimpflug-based corneal tomography is bifurcating from conventional keratometry as the diagnostic standard in premium refractive surgery clinics. High-volume LASIK and SMILE centers in Germany and South Korea are adopting these platforms for combined curvature and elevation mapping. The technology is compressing margins for standalone keratometer manufacturers while expanding service revenue pools for integrated diagnostic suite vendors.
FDA 510(k) software documentation requirements are tightening evidentiary standards for algorithm-driven curvature analysis modules. Manufacturers must now submit comprehensive validation datasets for AI-enhanced measurement algorithms, extending premarket timelines by twelve to eighteen months. Early-stage developers without established quality management systems are retreating from US market entry to focus on CE-marked European launches.
Eye care equipment distributors are unbundling after-sales service contracts from hardware procurement agreements. Independent service organizations in North America are capturing calibration and maintenance revenue previously retained by original equipment manufacturers. This channel shift is most visible in California and Texas, where multi-site ophthalmology groups negotiate centralized third-party service arrangements across their clinic networks.
Global Keratometers Market Segmentation
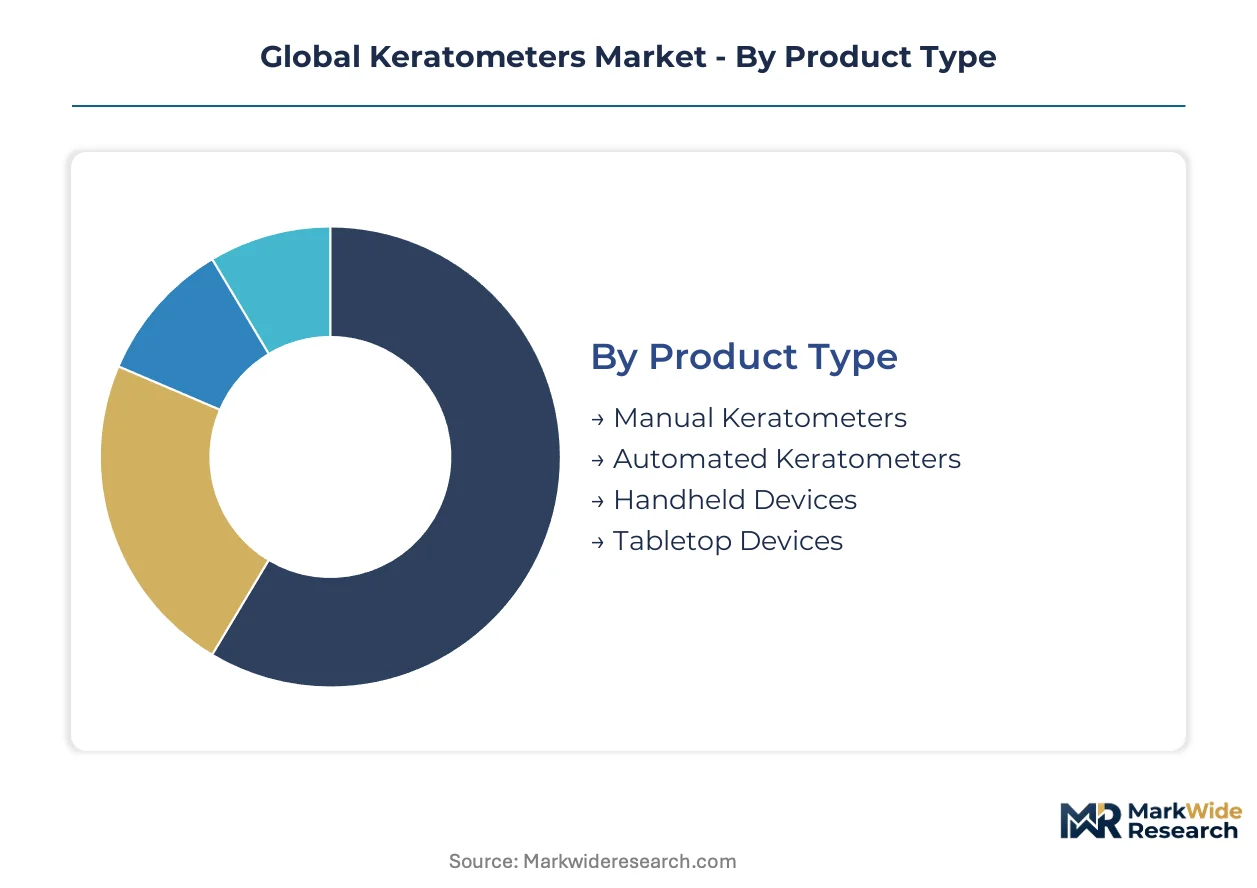
Keratometer procurement patterns diverge sharply across clinical settings. Channel economics and workflow constraints determine which product configurations dominate specific buyer segments.
Product Type:
Automated platforms flow through specialized ophthalmic distributors serving high-volume surgical centers. Manual and handheld units reach end users through optical retail channels and government tender programs.
- Manual Keratometers:Optical bench instruments requiring operator alignment of mire images through adjustable eyepieces. Demand concentrates in Indian and Southeast Asian optical colleges where training protocols emphasize hands-on refraction skills. Budget constraints in public hospital systems perpetuate procurement despite throughput limitations.
- Automated Keratometers:Motorized alignment systems with electronic mire detection and digital readout. German and South Korean refractive surgery clinics standardize on these platforms for LASIK screening protocols. FDA 510(k) software documentation requirements favor established vendors with quality management infrastructure.
- Handheld Devices:Battery-powered portable units with wireless data transmission for mobile screening programs. Indian government rural vision initiatives drive volume procurement.
- Tabletop Devices:Fixed-installation systems with integrated patient positioning and EMR connectivity. Japanese university hospitals prefer these for research-grade measurement stability.
Automated keratometers dominate installed base in Western surgical centers. Handheld devices are where expansion concentrates across emerging-market screening programs.
Technology:
Cost tiers separate premium tomographic platforms from basic curvature instruments. Scheimpflug and OCT systems command three-to-five-fold price multiples over Placido-based alternatives.
- Placido Disk:Concentric ring projection systems measuring anterior corneal curvature through reflected image analysis. Brazilian private clinics in São Paulo favor these for cost-contained cataract screening. Established supply chains from German optical component manufacturers support reliable sourcing.
- Scheimpflug Imaging:Rotating camera systems capturing cross-sectional corneal tomography with elevation and pachymetry data. South Korean SMILE surgery centers mandate these for combined diagnostic workstations. EU MDR conformity requirements accelerate replacement of legacy platforms lacking updated technical documentation.
- Optical Coherence Tomography:Interferometric depth-resolved imaging with sub-micron axial resolution. Research institutes in Japan and Germany deploy these for corneal biomechanics studies.
- Slit-Scan:Optical sectioning systems combining slit-lamp microscopy with curvature measurement. Italian ophthalmology clinics retain these for posterior corneal surface assessment.
Placido disk systems anchor volume shipments. Scheimpflug imaging is climbing the fastest as premium clinics consolidate diagnostic hardware.
Application:
Customer type determines specification requirements. Surgical centers demand multi-parameter integration while optical retailers prioritize speed and simplicity.
- Corneal Curvature Measurement:Foundational radius-of-curvature quantification for spherical and astigmatic power determination. German contact lens specialists require 0.125 diopter precision for orthokeratology fitting. ISO 10342 calibration standards govern metrological traceability.
- Astigmatism Diagnosis:Vector analysis of corneal toricity with axis orientation mapping. Indian cataract surgery camps utilize handheld units for rapid toric IOL selection in field conditions.
- Preoperative Assessment:Multi-modal screening protocols for refractive surgery candidacy. South Korean LASIK centers integrate these measurements with wavefront aberrometry and corneal thickness mapping.
- Contact Lens Fitting:Base curve selection and lens diameter specification for soft and rigid lens designs. Japanese optical retailers automate these calculations through cloud-connected handheld devices.
Corneal curvature measurement commands the broadest installed base. Preoperative assessment is gaining share fastest as refractive surgery volumes expand.
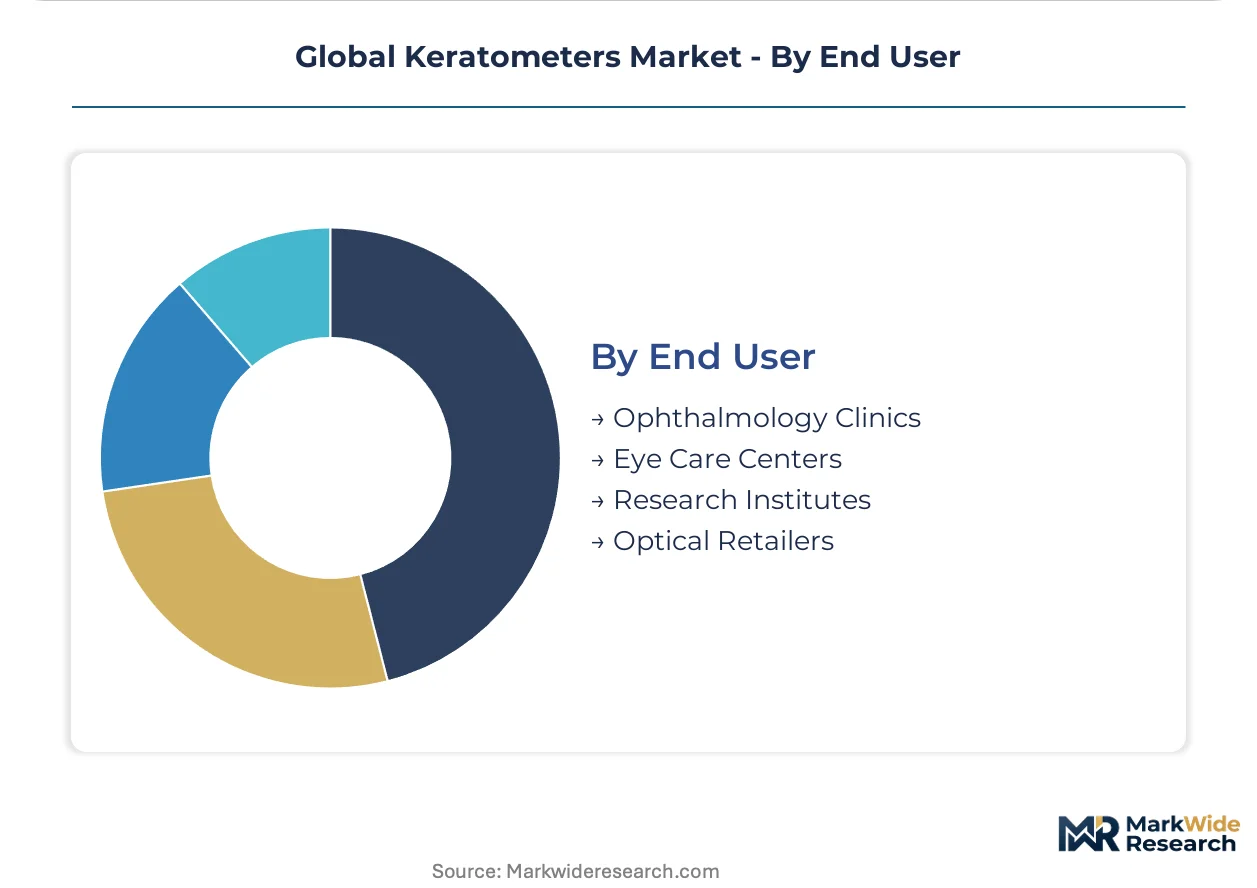
End User:
Procurement authority and capital deployment capacity vary dramatically across settings. Institutional buyers negotiate service-inclusive contracts while independent retailers prioritize upfront cost minimization.
- Ophthalmology Clinics:Physician-led diagnostic facilities performing comprehensive eye examinations and surgical planning. German group practices in Bavaria and North Rhine-Westphalia consolidate purchasing through multi-site procurement alliances. EMR integration requirements extend sales cycles for replacement decisions.
- Eye Care Centers:Dedicated refractive surgery facilities with high patient throughput and standardized protocols. Brazilian networks in Rio de Janeiro are expanding automated platform deployment.
- Research Institutes:Academic and clinical research organizations requiring traceable measurement uncertainty and raw data export. Japanese national university hospitals lead adoption of Scheimpflug-OCT hybrid platforms.
- Optical Retailers:Commercial eyewear vendors providing contact lens fitting without medical diagnosis. Indian urban chains in Mumbai and Delhi deploy handheld units for walk-in screening services.
Ophthalmology clinics retain the largest installed base. Eye care centers are where vendor expansion efforts concentrate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German and Japanese optical component fabricators anchor the upstream supply base for precision keratometer manufacturing. Device assembly clusters concentrate in Jena and Tokyo where captive lens production meets specialized biomedical engineering talent. National regulatory frameworks in the United States, Germany, Japan, India, and Brazil shape commercial access and procurement patterns across their respective markets.
United States
Refractive surgery chains in California and Texas drive automated platform procurement for high-throughput LASIK screening. FDA 510(k) software documentation requirements extend premarket timelines for algorithm-enhanced curvature analysis modules. Carl Zeiss Meditec and Reichert Inc. serve domestic surgical centers through established ophthalmic distribution networks.
Germany
Bavarian and North Rhine-Westphalian group practices consolidate purchasing through multi-site procurement alliances for diagnostic workstations. EU MDR conformity deadlines accelerate replacement cycles for legacy keratometer inventories lacking updated technical documentation. Jena hosts specialized manufacturing clusters where Carl Zeiss Meditec maintains vertical control over optical component fabrication.
Japan
Tokyo and Osaka university hospitals lead adoption of Scheimpflug-OCT hybrid platforms for research-grade corneal biomechanics studies. METI medical device export incentives provide subsidized certification support for PMDA-compliant platforms targeting ASEAN markets. NIDEK Co., Ltd. specializes in compact automated systems for space-constrained domestic clinics.
India
Maharashtra and Delhi-NCR optical retailers deploy handheld units for walk-in contact lens screening services. Government-funded rural vision initiatives generate portable device procurement volumes across underserved districts. Budget constraints in public hospital systems perpetuate manual keratometer procurement for training protocols in optical colleges.
Brazil
São Paulo and Rio de Janeiro private clinic networks present first-mover positioning opportunities for automated platform vendors. ANVISA medical device registration requirements shape product development timelines for manufacturers entering Latin America's largest refractive surgery market. Underpenetrated surgical center density supports vendor expansion efforts against established regional distributors.
Global Keratometers Market Competitive Landscape
Concentration sits with diversified ophthalmic instrument conglomerates possessing captive optical manufacturing capabilities. The vendor base stratifies across three tiers: premium integrated workstation specialists, mid-market automated platform assemblers, and economy handheld device fabricators. Dominant competitive moves include backward integration into precision lens production and geographic expansion through distributor acquisition in emerging markets.
Within the premium-tier segment, Carl Zeiss Meditec and Haag-Streit AG exemplify European-based conglomerates with Jena and Bern anchored manufacturing heritage. NIDEK Co., Ltd. occupies a specialist position among Japanese manufacturers focused on compact platform design for space-constrained clinical environments. These three entities represent distinct strategic archetypes: German vertical integration, Swiss precision engineering tradition, and Japanese miniaturization expertise.
| Leading Market Players |
|---|
| Carl Zeiss Meditec |
| Topcon Corporation |
| NIDEK Co., Ltd. |
| Haag-Streit AG |
| Essilor International |
| Canon Inc. |
| Reichert Inc. |
| Luneau Technology |
| Oculus Optikgeräte GmbH |
| Others |
Supply & Pricing Matrix
Scale economies in precision optical component fabrication concentrate supply among German and Japanese lens manufacturers, anchoring price floors for automated keratometer platforms while compressing margins for mid-tier assemblers lacking captive production. Volume procurement alliances among Bavarian group practices and California refractive surgery chains amplify buyer leverage, forcing tiered pricing concessions from vendors competing for multi-site diagnostic workstation contracts.
Pricing Analysis
Volume-discount tiering structures dominate automated keratometer procurement, with three-tier pricing separating Scheimpflug-integrated premium workstations from standard automated platforms and economy handheld units. Price differentiation rests on FDA 510(k) certification grade and after-sales service bundling, with German manufacturers commanding brand premiums for Jena-sourced optical components. Pricing pressure stems from OCT system substitution in premium clinics, eroding addressable market for standalone curvature instruments. Optical retailers in emerging markets exhibit highest price sensitivity, while German university hospitals prioritize measurement precision over upfront cost.
Supply Chain Analysis
Inbound logistics costs through Hamburg and Yokohama ports constrain just-in-time delivery schedules for high-grade lens shipments destined for device assembly facilities. Supply concentrates in Germany, Japan, and China, with Jena and Tokyo anchoring precision optics fabrication and Shenzhen supporting mid-tier electronic component sourcing. Raw material dependencies include germanium-doped glass substrates, precision-machined aluminum housings, and CMOS image sensors. Single-source vulnerability for Scheimpflug camera modules creates supply chain risk. Distribution runs through specialized ophthalmic equipment distributors serving hospital purchasing committees and multi-site clinic networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market sits in early-cycle expansion as refractive surgery protocols tighten diagnostic requirements and mobile eye care programs proliferate across underserved regions. Penetration tailwinds from government-funded rural vision screening in India and Southeast Asia are accelerating portable device procurement beyond traditional clinical settings.
For Market Incumbents: Fortify backward integration into precision lens production to defend margin position against OCT substitution threats. Carl Zeiss Meditec and Haag-Streit AG should expand Jena and Bern manufacturing capacity to capture EU MDR-driven replacement demand. Channel control through distributor acquisition in Brazil and India represents a critical lever for preempting emerging competitor entry.
For New Entrants and Emerging Players: FDA 510(k) fast-track pathways for software-as-a-medical-device modules offer regulatory arbitrage opportunities against established vendors with legacy quality systems. White-space targets include cloud-connected handheld units for tele-ophthalmology nodes and stripped-down automated platforms for Brazilian private clinic networks. Go-to-market execution should prioritize direct procurement relationships with Maharashtra optical retail chains over distributor-dependent models.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors Scheimpflug-tomography hybrid platform specialists with PMDA-compliant export capabilities. Long-term viability hinges on algorithm-enhanced diagnostic suites capable of integrating with hospital EMR systems. Acquisition targets should display captive optical manufacturing and ASEAN market access. The inflection signal to watch is ANVISA registration acceleration for automated platforms entering São Paulo clinic networks.
| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway Acceleration | EU MDR recertification deadlines compress replacement cycles for legacy keratometer inventories lacking updated technical documentation. |
| Hospital System Partnership | Bavarian and North Rhine-Westphalian group practices consolidate purchasing through multi-site procurement alliances for diagnostic workstations. |
| Software Companion Development | AI-enhanced curvature analysis modules face divergent FDA and notified body classifications, extending premarket timelines for algorithm-driven platforms. |
| FDA Submission Strategy | Refractive surgery chains in California and Texas demand 510(k)-cleared automated platforms for high-throughput LASIK screening protocols. |
| Reimbursement Strategy | Government-funded rural vision initiatives across India generate portable device procurement volumes with tender-based pricing constraints. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with ophthalmic equipment procurement managers, biomedical engineering directors, and GPO contracts specialists; and secondary validation through FDA 510(k) filings, EU MDR technical documentation databases, and hospital procurement records. Bottom-up triangulation across product configuration shipment data and top-down reconciliation against refractive surgery center census estimates anchored volume and value outputs.
The forecasting window spans the full projection horizon with segmentation across product type, technology platform, application protocol, and end-user setting. CAGRs were derived from fitted growth curves applied to installed base replacement cycles and expansion penetration rates. Industry-specific inputs included EU MDR recertification deadline schedules, METI export incentive program allocations, and ANVISA registration pipeline velocities.
Underlying assumptions cover refractive surgery volume trajectories and regulatory pathway stability, with deviation risk concentrated in AI diagnostic module classification rulings and optical component supply disruptions. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
LAMEA External Defibrillators Market
Medical Devices
Asia-Pacific Antimicrobial Coating for Medical Devices Market
Medical Devices
Wireless Surgical Cameras Market
Medical Devices
Global Veress Needle Market
Medical Devices
Oxygen Generator Market
Medical Devices
Annuloplasty Rings Market
Medical Devices
Walking Aids Market
Medical Devices
Cranial Navigation Systems Market
Medical Devices
Inferior Vena Cava Filters Market
Medical Devices
Global Electronic Stethoscope Market
Medical Devices
Stimulation Therapies Market
Medical Devices
Australia General Surgical Devices Market
Medical Devices
Medical Mobility Aid Market
Medical Devices
Global Non-Surgical Skin Tightening Devices Market
Medical Devices
North America Ablation Devices Market
Medical Devices
Global Robotic Nurse Assistant Market