
 5G Infrastructure Equipment Market | 2026-2036
5G Infrastructure Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
5G Infrastructure Equipment Market Analysis
RF engineering talent scarcity is bifurcating vendor capabilities across developed and emerging markets. Huawei Technologies Co., Ltd. leverages its captive semiconductor design teams to sustain base station output despite trade restrictions. Nokia Corporation anchors European supply security through its Oulu manufacturing complex. Samsung Electronics Co., Ltd. competes aggressively in mmWave antenna modules for North American carrier rollouts.
5G infrastructure equipment comprises radio access network hardware operating across sub-6 GHz and mmWave frequency ranges, with base stations typically supporting 64T64R massive MIMO configurations and sub-millisecond latency targets for ultra-reliable low-latency communication. The primary purpose is enabling enhanced mobile broadband, massive machine-type communications, and critical IoT services for industrial and consumer applications. Base stations command the dominant capital share within equipment type segmentation as carriers prioritize macro layer density before small cell infill. Massive MIMO leads technology adoption curves where spectral efficiency gains justify hardware premiums. Cloud-based deployment architectures are gaining traction among enterprises seeking network slicing flexibility without on-premise capital commitment.
The Federal Communications Commission in the United States, the European Union's Radio Equipment Directive, and India's Telecommunication Engineering Centre each enforce equipment authorization regimes that determine which vendors qualify for national infrastructure tenders. These frameworks create compliance moats favoring incumbents with established certification pipelines and testing partnerships. Stakeholders must monitor spectrum auction calendars and open interface standardization timelines to align R&D roadmaps with procurement cycles.
Market Dynamics
Open RAN interoperability mandates and spectrum densification requirements are forcing equipment vendors to rearchitect product portfolios around software-defined interfaces while simultaneously scaling manufacturing for massive MIMO hardware volumes.
Growth Catalysts
- Smart manufacturing automation:German and Japanese industrial facilities are deploying private 5G networks to replace wired Ethernet for mobile robotics and predictive maintenance systems.
- Mid-band spectrum liberalization:India's Department of Telecommunications auction protocols are accelerating urban macro layer buildouts across densely populated metropolitan corridors.
- EU Radio Equipment Directive harmonization:Standardized certification pathways are reducing vendor qualification friction for cross-border infrastructure tenders.
Market Restraints
- GaN-on-SiC substrate scarcity:Power amplifier foundry capacity constraints in Taiwan and Japan are elongating base station delivery timelines.
- Trade restriction complexity:US export control frameworks are fragmenting semiconductor supply chains and forcing dual-sourcing strategies.
- mmWave propagation physics:Line-of-sight limitations and rain fade sensitivity are restricting outdoor coverage economics.
Strategic Opportunities
- Enterprise network slicing:Cloud-native deployment architectures are enabling manufacturing and logistics operators to lease isolated network slices without capital-intensive on-premise builds.
- Rural coverage mandates:Universal service obligations in Brazil and Indonesia are creating subsidized deployment pools for macro equipment vendors.
- AI-driven RAN optimization:Convergence of machine learning inference at the network edge with real-time beamforming algorithms is opening new service revenue streams.
Industry Challenges
- RF systems engineering talent:Massive MIMO antenna design and beamforming algorithm development expertise concentrates in Finland, South Korea, and select US research corridors.
- Multi-vendor integration complexity:Open RAN disaggregation is exposing interoperability gaps between radio units, distributed units, and centralized units from different suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | 5G Infrastructure Equipment Market |
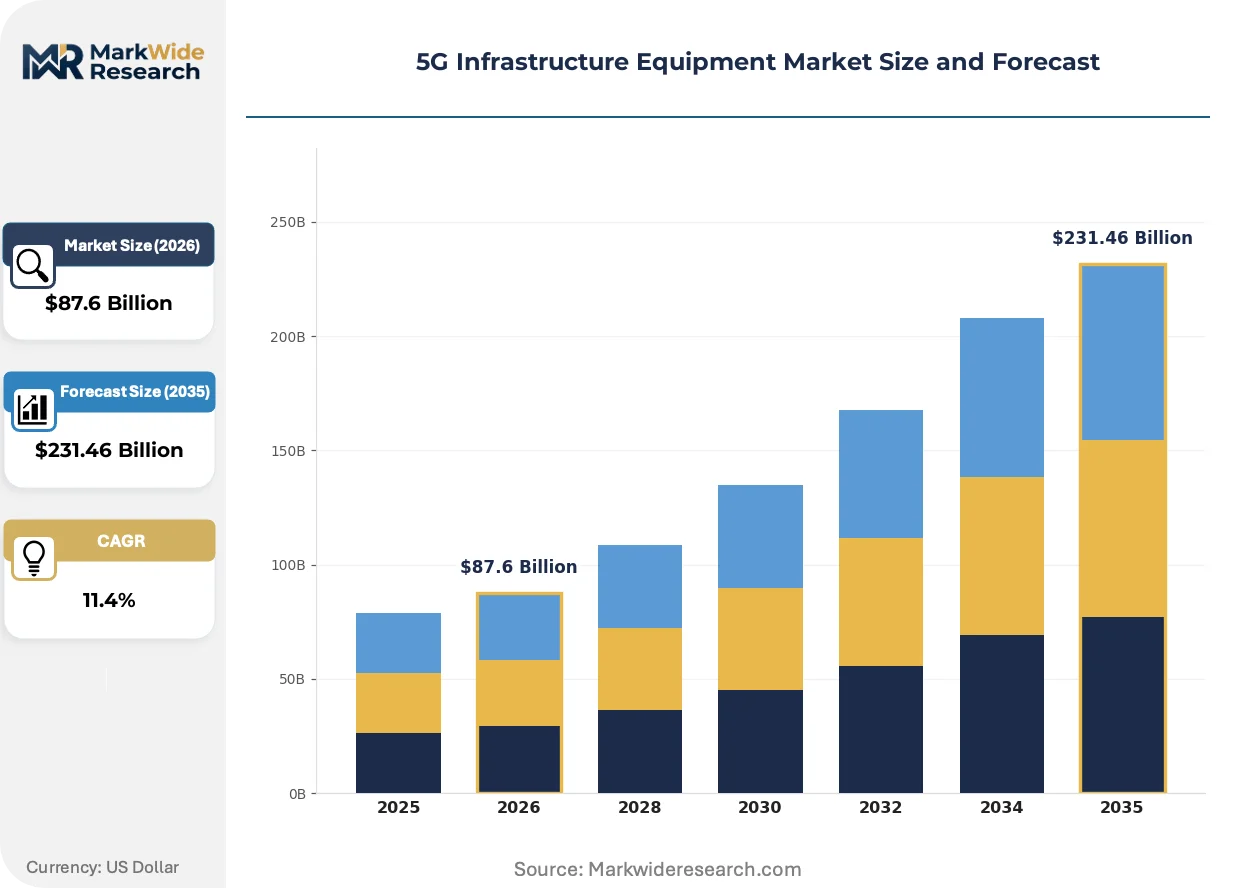
| Market Size in 2026 | $87.6 Billion |
| Market Size in 2035 | $231.46 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Equipment Type: Base Stations, Antennas, Network Routers, Optical Fiber Technology: Massive MIMO, Beamforming, Small Cells, Distributed Antenna Systems End User: Telecommunications, Government, Enterprises, Utilities Deployment: On-Premise, Cloud-Based, Hybrid, Centralized |
| Companies Covered | Huawei Technologies Co., Ltd., Samsung Electronics Co., Ltd., Nokia Corporation, Telefonaktiebolaget LM Ericsson, ZTE Corporation, Cisco Systems, Inc., NEC Corporation, CommScope Inc., Fujitsu Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
5G Infrastructure Equipment Market Emerging Trajectories
Virtualized baseband processing and containerized network functions are displacing proprietary hardware-centric architectures, compressing equipment margins while expanding addressable service revenue pools for software-capable vendors.
Massive MIMO active antenna units are fragmenting traditional base station procurement patterns. These integrated systems combine radio frequency chains with beamforming logic in thermally constrained enclosures. North American carriers are prioritizing 64T64R configurations for urban capacity layers. The technology is fragmenting vendor market power by enabling smaller suppliers to compete on software differentiation rather than scale economies in power amplifier manufacturing.
The European Union's CSRD disclosure requirements are mandating supply chain carbon footprint transparency for network equipment tenders. Vendors must now document embodied emissions from semiconductor fabrication through end-of-life recycling. This regulatory layer is reshaping qualification criteria for public infrastructure contracts. Equipment manufacturers with captive renewable energy supply are capturing preferential scoring in German and French procurement evaluations.
Buying committees at industrial enterprises are unbundling network equipment from systems integration services. Manufacturing operators in automotive and chemical processing verticals are contracting directly with hardware vendors while sourcing software orchestration from cloud specialists. This pattern is compressing traditional systems integrator margins. The shift is most pronounced in German industrial clusters where mid-sized Mittelstand firms dominate private network adoption.
5G Infrastructure Equipment Market Segmentation
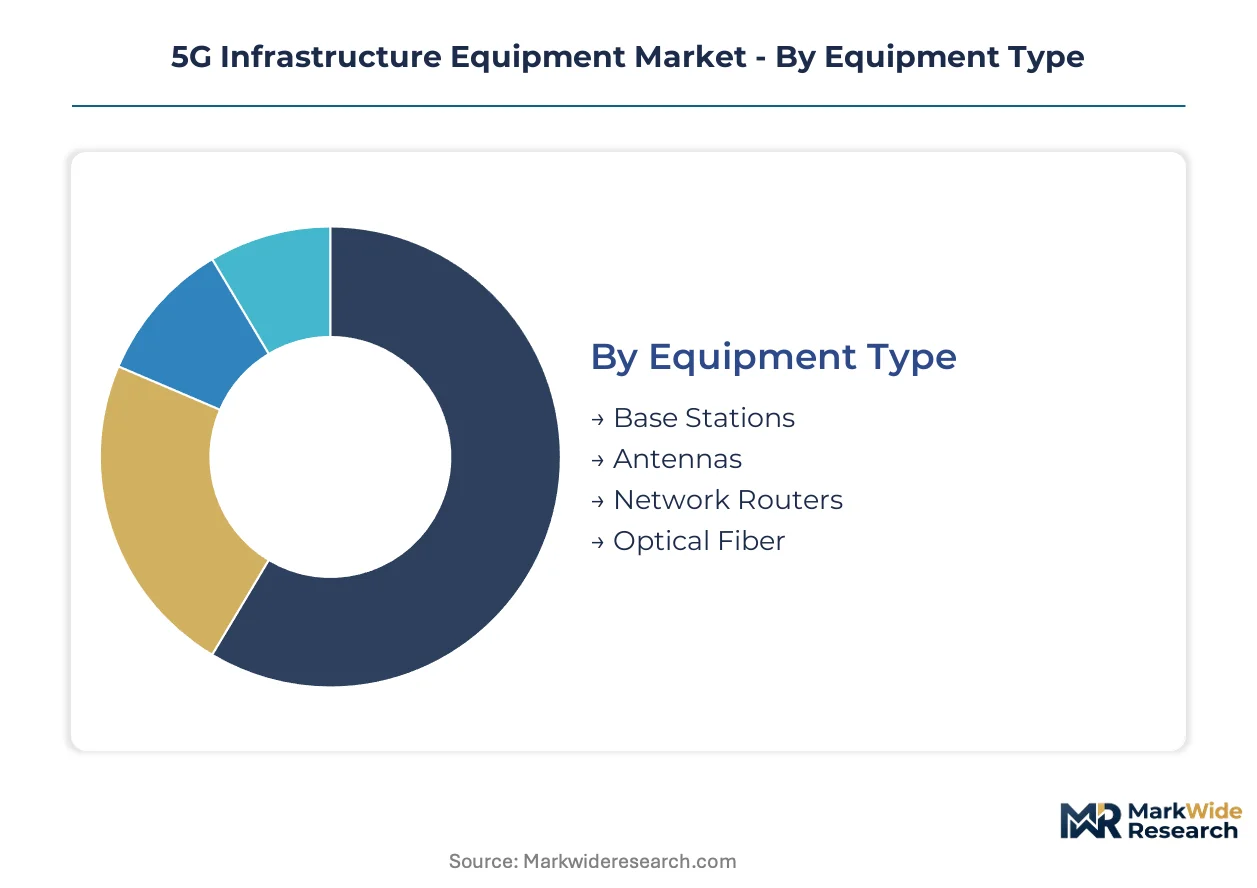
Equipment segmentation in 5G infrastructure determines capital allocation priorities for carriers and private network operators. Each category reflects distinct margin structures, certification requirements, and deployment timelines that shape vendor competitive positioning.
Equipment Type:
Margin pools concentrate in integrated radio systems where semiconductor content and thermal engineering create differentiation moats.
- Base Stations:Macro cell hardware incorporating 64T64R massive MIMO arrays and active antenna units. Demand concentrates in India's urban corridors where the Department of Telecommunications mid-band auctions are accelerating macro layer densification. GaN-on-SiC power amplifier scarcity is elongating delivery timelines for Tier-1 carrier orders.
- Antennas:Passive and active antenna systems including beamforming arrays and panel configurations. German automotive manufacturing clusters are driving private network antenna procurement for factory-floor coverage. The EU Radio Equipment Directive harmonization is reducing cross-border qualification friction.
- Network Routers:Core and edge routing platforms handling subscriber management and traffic engineering. Compact description with named entity: Cisco and Juniper supply positions dominate North American carrier core upgrades.
- Optical Fiber:Fronthaul and backhaul fiber connectivity for centralized RAN architectures. Compact description with named entity: Corning and Fujikura are expanding ribbon fiber capacity for Japanese carrier builds.
The dominant share belongs to Base Stations, while Antennas is closing the gap fastest as active antenna integration fragments traditional procurement patterns.
Technology:
Deployment complexity and software content determine where value capture shifts from hardware to algorithmic differentiation.
- Massive MIMO:64T64R and 32T32R active antenna systems with embedded baseband processing. North American carriers prioritize these configurations for urban capacity layers where spectral efficiency justifies hardware premiums. Beamforming algorithm development expertise concentrates in Finland and South Korea research corridors.
- Beamforming:Digital and analog beam steering technologies for interference management and coverage optimization. Japanese industrial facilities are deploying beamforming-intensive private networks for mobile robotics applications. RF systems engineering talent scarcity is bifurcating vendor capabilities.
- Small Cells:Low-power radio nodes for indoor coverage and dense urban infill. Compact description with named entity: CommScope and Samsung compete for US stadium and venue deployments.
- Distributed Antenna Systems:Neutral-host infrastructure for multi-operator coverage in buildings and transit systems. Compact description with named entity: JMA Wireless and Boingo dominate US airport and hospital installations.
Massive MIMO commands the largest installed base, though Beamforming is expanding most quickly as Open RAN disaggregation exposes software differentiation opportunities.
End User:
Procurement authority and budget cycles create distinct sales motion requirements across customer categories.
- Telecommunications:Mobile network operators building public macro and small cell infrastructure. India's carrier consolidation is concentrating procurement authority with Reliance Jio and Bharti Airtel. Mid-band spectrum liberalization is accelerating urban buildout timelines.
- Government:Defense and public safety networks requiring hardened equipment and domestic sourcing. US Department of Defense 5G testbed programs at Hill Air Force Base and Marine Corps Logistics Base Albany are validating Open RAN security architectures. Trade restriction complexity is fragmenting approved vendor lists.
- Enterprises:Manufacturing, logistics, and mining operators deploying private networks. Compact description with named entity: German Mittelstand automotive suppliers are unbundling hardware from systems integration services.
- Utilities:Power grid and water infrastructure operators seeking mission-critical connectivity. Compact description with named entity: Duke Energy and Southern California Edison are piloting 5G for grid monitoring and field workforce communications.
Telecommunications retains the dominant procurement volume, while Enterprises is gaining share fastest as manufacturing automation mandates drive private network adoption.
Deployment:
Capital commitment profiles and operational control requirements segment buyer preferences across architecture models.
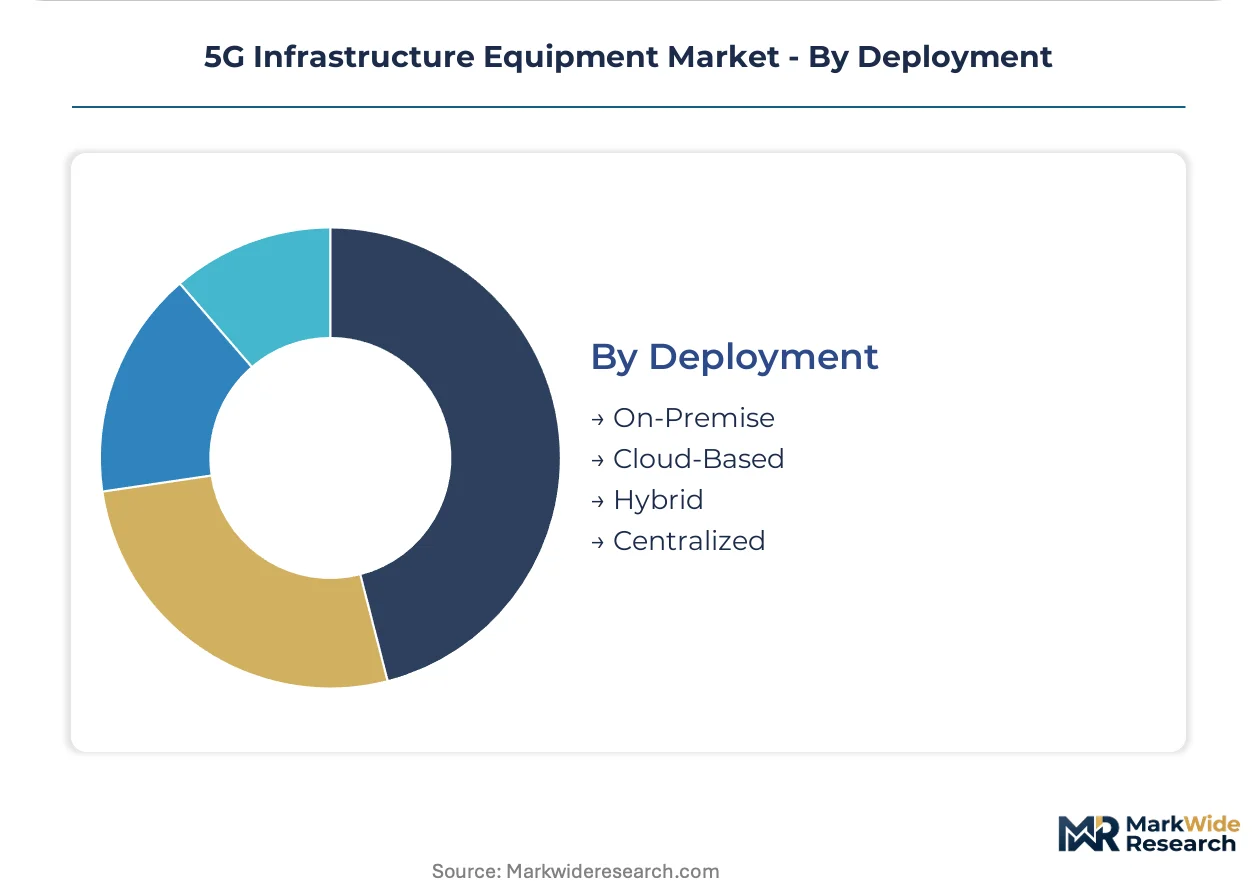
- On-Premise:Fully owned and operated radio and core infrastructure with dedicated facilities. German chemical processing clusters prefer this model for data sovereignty and deterministic latency guarantees. High upfront capital requirements favor large industrial conglomerates over mid-sized operators.
- Cloud-Based:Network functions virtualization with subscriber management hosted in hyperscale data centers. Brazilian logistics operators are leasing cloud-native deployments to avoid capital-intensive on-premise builds. Universal service obligations in rural coverage zones are creating subsidized deployment pools.
- Hybrid:Split architectures combining on-premise radio with cloud-hosted core functions. Compact description with named entity: Indonesian mining operators are adopting hybrid models for remote site connectivity with centralized policy management.
- Centralized:Traditional macro-centric architectures with concentrated baseband processing. Compact description with named entity: French procurement evaluations are scoring centralized RAN vendors on supply chain carbon footprint transparency under CSRD requirements.
On-Premise deployments hold the largest committed capital base, though Cloud-Based is climbing the fastest as manufacturing and logistics operators prioritize opex flexibility over ownership.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply across geographies. India's carriers prioritize macro base station density for urban coverage, while German industrial operators favor private on-premise deployments for factory automation.
United States
Verizon and AT&T are accelerating mmWave small cell deployments for stadium and venue coverage. The FCC's spectrum auction programs are releasing mid-band licenses for rural 5G expansion. Defense testbed programs at Hill Air Force Base are validating Open RAN security architectures for military applications.
Germany
Automotive Mittelstand suppliers are deploying private 5G networks to replace wired Ethernet for mobile robotics. The EU Radio Equipment Directive harmonization is streamlining cross-border vendor qualification. Chemical processing clusters in North Rhine-Westphalia prefer on-premise architectures for data sovereignty guarantees.
India
Reliance Jio and Bharti Airtel are consolidating procurement authority for urban macro layer densification. The Department of Telecommunications mid-band spectrum auctions are accelerating metropolitan buildout timelines. Bangalore and Hyderabad tech corridors are emerging as systems integration hubs for private network deployments.
Japan
Nippon Telegraph and Telephone is expanding massive MIMO deployments for Tokyo Olympic legacy coverage. METI industrial policy is subsidizing private 5G adoption for smart manufacturing. Osaka automotive clusters are driving beamforming-intensive network designs for predictive maintenance systems.
South Korea
SK Telecom and KT Corporation are commercializing 28 GHz mmWave services for urban hotspots. The Korea Communications Commission is mandating equipment interoperability for multi-vendor RAN deployments. Seoul semiconductor research corridors are concentrating RF systems engineering talent for active antenna development.
5G Infrastructure Equipment Market Vendor Landscape
A small set of integrated leaders sits above a broader specialist tier in the 5G infrastructure equipment market. The upper tier commands base station and massive MIMO markets through captive semiconductor design and manufacturing scale. Below them, specialists in optical transport, small cells, and network software carve out defensible positions. Two strategic archetypes dominate: vertically integrated hardware vendors with foundry partnerships, and software-native challengers exploiting Open RAN disaggregation. Competitive moves center on GaN-on-SiC supply security and cloud-native RAN software licensing.
Among Asia-Pacific equipment vendors, Huawei Technologies Co., Ltd. and Samsung Electronics Co., Ltd. occupy positions reflecting divergent geographic exposure. Nokia Corporation anchors the European tier with manufacturing presence in Finland. These three exemplify the integrated leader archetype, each representing distinct strategic responses to trade restriction complexity and spectrum densification requirements.
| Leading Market Players |
|---|
| Huawei Technologies Co., Ltd. |
| Samsung Electronics Co., Ltd. |
| Nokia Corporation |
| Telefonaktiebolaget LM Ericsson |
| ZTE Corporation |
| Cisco Systems, Inc. |
| NEC Corporation |
| CommScope Inc. |
| Fujitsu Limited |
| Others |
Supply Flow & Price Mechanics
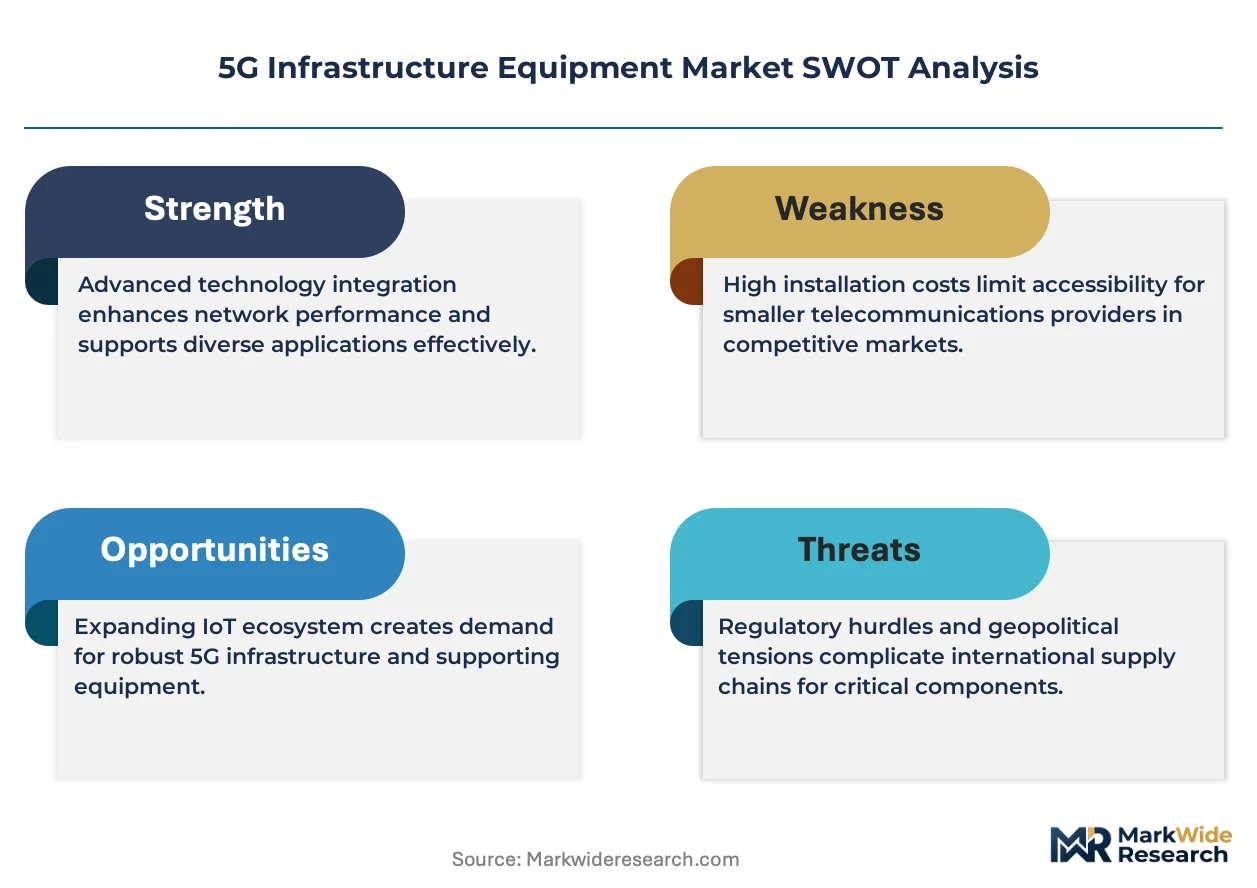
GaN-on-SiC foundry utilization rates above 85 percent in Taiwan and Japan concentrate power amplifier supply among three dominant substrate vendors, compressing base station OEM margins while elevating price floors for 64T64R massive MIMO configurations. This capacity tightness transmits directly to carrier procurement budgets, where long-term offtake agreements now command 15-20 percent premiums over spot purchasing for guaranteed delivery slots.
Pricing Analysis
Long-term offtake contracts dominate base station procurement between Tier-1 carriers and integrated OEMs, with project-based spot purchasing filling capacity gaps for rural coverage mandates. Price differentiation separates Open RAN-native vendors from proprietary hardware incumbents, with software-centric suppliers capturing service attach revenue that offsets hardware margin compression. Pricing pressure stems from cloud-native RAN alternatives displacing on-premise capital commitments among German Mittelstand manufacturers. Public telecommunications carriers exhibit highest price sensitivity due to spectrum auction debt burdens, while defense and industrial private network operators accept hardware premiums for domestic sourcing guarantees.
Supply Chain Analysis
Taiwan and South Korea anchor GaN-on-SiC wafer fabrication and RF front-end module assembly, with Finland and Oulu manufacturing complexes providing European supply security for baseband processing units. Base station production draws from gallium nitride epitaxy, ceramic substrate packages, and precision antenna casting inputs. Single-source vulnerability concentrates in Taiwanese foundry capacity for high-frequency power amplifiers. Distribution runs through carrier-direct procurement for macro infrastructure, with systems integrators and cloud service providers intermediating enterprise private network deployments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Early-cycle expansion in enterprise network slicing and private 5G manufacturing automation justifies capacity commitments ahead of procurement volume inflection. India's mid-band densification and Germany's industrial automation mandates represent concurrent demand tailwinds with divergent sales motion requirements.
For Market Incumbents: Compound defensive positioning through captive GaN-on-SiC supply agreements and Oulu-scale manufacturing redundancy. Nokia Corporation's European supply security model demonstrates how geographic diversification defends against trade restriction fragmentation. Prioritize Open RAN certification pipeline investment to maintain qualification moats as EU interoperability mandates reshape vendor pathways. For New Entrants and Emerging Players: EU Radio Equipment Directive fast-track certification offers entry acceleration for software-native vendors lacking legacy hardware scale. Target Brazilian and Indonesian rural coverage mandates where universal service obligations create subsidized deployment pools with reduced incumbent lock-in. Lead with cloud-native deployment architectures to bypass capital-intensive manufacturing barriers. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors software-capable challengers exploiting Open RAN disaggregation over pure hardware scale plays. Long-term viability rests on algorithmic differentiation in beamforming and network slicing orchestration. Monitor spectrum auction calendar density and open interface standardization timelines as inflection indicators for procurement cycle acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| GaN-on-SiC Supply Security Partnership | Taiwanese foundry offtake agreements defend base station delivery commitments against capacity constraints. |
| Open RAN Certification Pipeline Investment | EU Radio Equipment Directive qualification moats preserve cross-border tender eligibility for integrated vendors. |
| Cloud-Native RAN Software Licensing | German Mittelstand manufacturing demand shifts procurement toward opex-flexible network slicing models. |
| Enterprise Systems Integration Unbundling | Automotive and chemical verticals now contract hardware directly, compressing traditional SI margins. |
| CSRD Supply Chain Carbon Disclosure | French and German procurement scoring now favors vendors with captive renewable energy documentation. |
Methodological Framework
Desk research of FCC equipment authorization databases, EU Radio Equipment Directive certification registries, and Indian Department of Telecommunications auction protocols preceded structured interviews with carrier procurement executives, RF systems engineering directors, and private network systems integration leads. Secondary validation drew from semiconductor foundry utilization disclosures, hyperscaler capex filings, and industrial automation trade association deployment surveys. Bottom-up equipment shipment estimates triangulated against top-down carrier capex allocation models.
Variance decomposition across equipment type, technology adoption curve, and deployment architecture dimensions shaped the analytical framework over the projection horizon. Segmentation modeling incorporated base station versus small cell form factors, massive MIMO versus beamforming technology pathways, and on-premise versus cloud-native operational models. CAGRs derived from carrier-reported deployment timelines and enterprise private network pilot-to-production conversion rates, with cross-reference to spectrum auction completion schedules and open interface standardization milestones.
Underlying assumptions cover sustained GaN-on-SiC foundry capacity expansion, stable trade restriction frameworks, and mid-band spectrum release calendars, with deviation risk concentrated in semiconductor supply disruption and regulatory interoperability timeline delays. Recalibration cycles align with material shifts in spectrum auction density and Open RAN certification throughput rates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Telecommunications Infrastructure
Colombia Telecom Tower Market
Telecommunications Infrastructure
Iraq Telecom Market
Telecommunications Infrastructure
UAE Telecom Towers Market
Telecommunications Infrastructure
5G Infrastructure Market
Telecommunications Infrastructure
Wireless Infrastructure Market
Telecommunications Infrastructure
Global Integrated Telecom Infrastructure Market
Telecommunications Infrastructure
Nepal Telecom Market
Telecommunications Infrastructure
Morocco Telecom Tower Market
Telecommunications Infrastructure
Small Cell Backhaul Market
Telecommunications Infrastructure
Israel Telecom Market
Telecommunications Infrastructure
Global Cellular Networks Market
Telecommunications Infrastructure
Peru Telecom Tower Market
Telecommunications Infrastructure
Communication Repeater Market
Telecommunications Infrastructure
Bangladesh Telecom Towers Market
Telecommunications Infrastructure
Thailand Telecom Towers Market
Telecommunications Infrastructure
Microwave Backhaul System Market