
 Japan Camping Equipment Market | 2026-2036
Japan Camping Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Japan Camping Equipment Market Insights
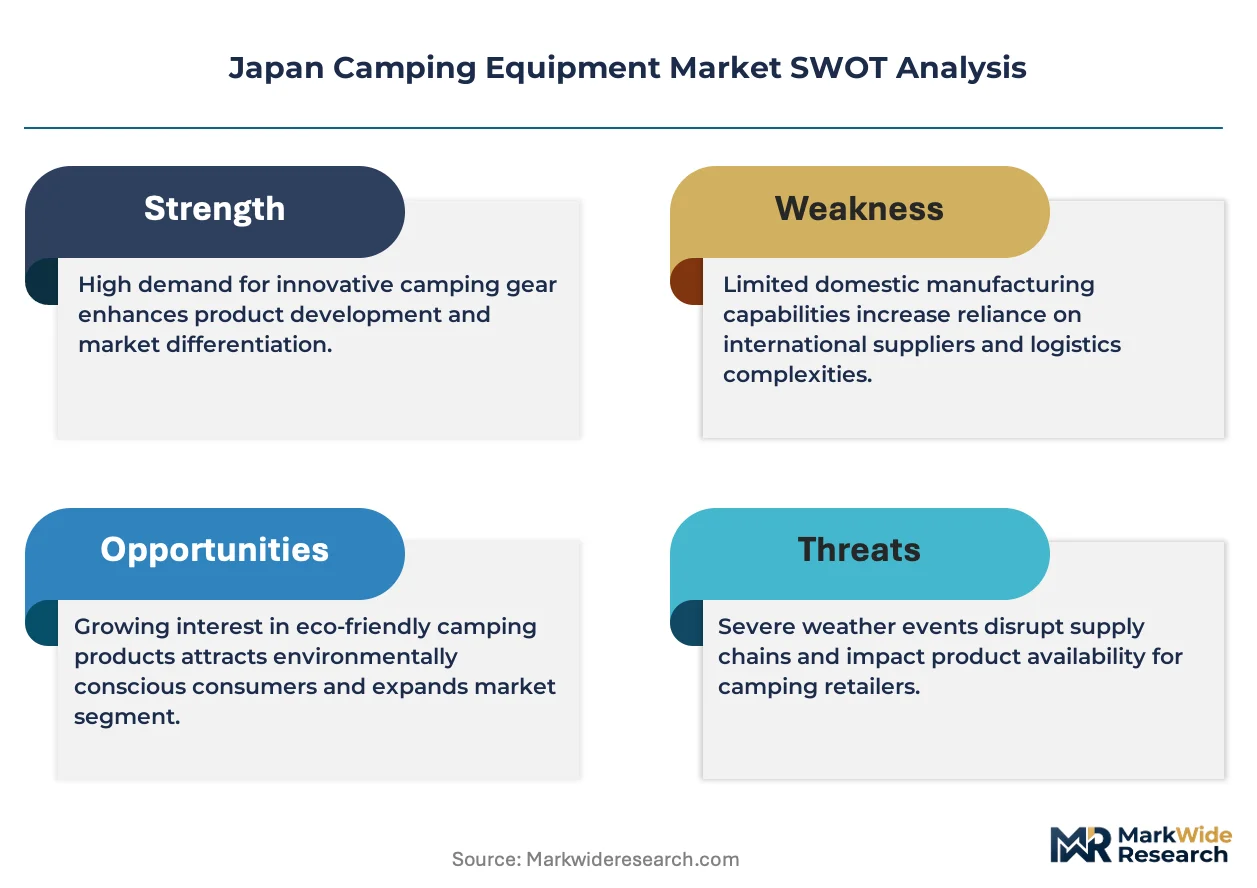
Specialized outdoor retail is reshaping how Japanese consumers discover and purchase camping gear, blending experiential showroom formats with digital fulfillment. Snow Peak leverages its vertically integrated domestic manufacturing to command premium positioning in titanium cookware and tent poles. Montbell sustains competitive intensity through ultralight material science developed at its Osaka R&D center. Columbia Sportswear navigates the market through licensed distribution partnerships rather than direct retail investment.
Japan camping equipment encompasses portable shelters, sleep systems, carrying solutions, and backcountry cooking apparatus engineered for temperate mountain conditions, with waterproof ratings typically exceeding 1,500mm hydrostatic head for three-season use. The primary commercial purpose centers on enabling safe overnight recreation across Japan's 34 national parks and extensive forest road network. Tents and sleeping bags built from nylon and polyester dominate volume, while aluminum-framed products capture disproportionate margin due to weight-sensitive demand from solo trekkers in the Northern Alps. Online retail channels are accelerating fastest among distribution modalities, though specialized stores retain decisive influence through seasonal gear fitting services.
METI product safety standards and JIS quality certifications govern flame-retardant treatments and structural load ratings for tent assemblies sold domestically. The national parks regulator and prefectural forestry bureaus restrict campsite locations and seasonal access, indirectly filtering equipment specifications toward compact, Leave-No-Trace-compatible designs. Stakeholders must track evolving fire-safety material bans and campsite capacity regulations as these will determine permissible product configurations and addressable recreation zones.
Market Dynamics
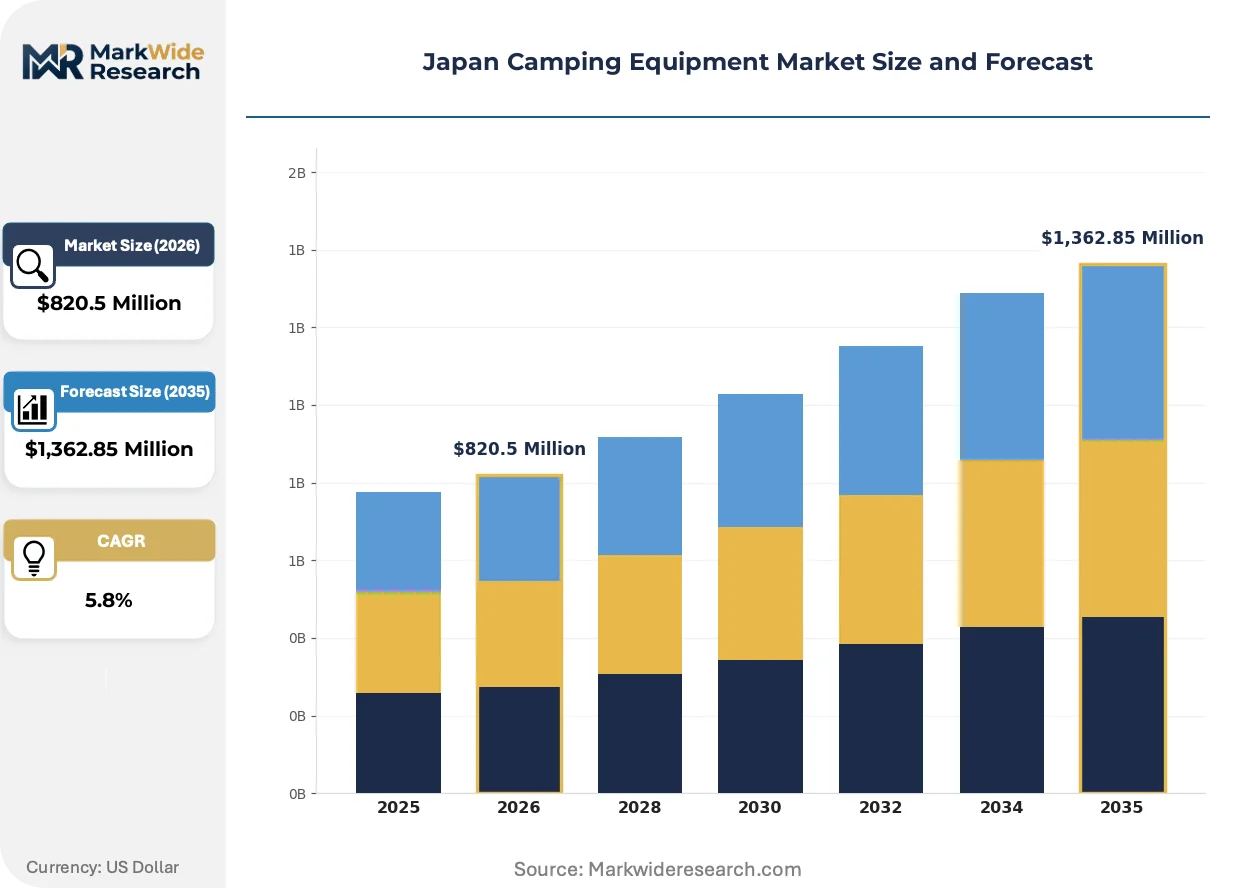
Domestic outdoor recreation participation among young urban professionals is broadening the customer base for Japan's camping equipment sector, while METI's regional tourism promotion policies and sustainable manufacturing guidelines redirect procurement standards toward compact, Leave-No-Trace-compatible designs.
Growth Catalysts
- METI regional tourism promotion:Prefectural subsidies for campsite infrastructure development in Yamanashi and Nagano are expanding addressable recreation zones for equipment vendors.
- Ultralight material science:Osaka-based R&D centers are advancing nylon ripstop and silicone-coated polyester fabrics that reduce pack weights for solo trekkers in the Northern Alps.
- Kanto demand concentration:Greater Tokyo's young professional cohort is driving premium tent and sleep system purchases through specialized retail channels.
Market Restraints
- Aluminum supply concentration:Tent pole and cookware manufacturers face input cost volatility tied to global aluminum smelter capacity constraints.
- JIS certification timelines:Flame-retardant treatment approvals for tent fabrics create extended product launch cycles that compress seasonal selling windows.
- Urban storage limitations:Tokyo and Osaka apartment dwellers substitute rental services for ownership, capping household equipment penetration rates.
Strategic Opportunities
- Online channel acceleration:Digital fulfillment platforms are capturing share from specialized retail through seasonal gear fitting video consultations.
- Prefectural forestry bureau partnerships:Collaborative campsite development in Hokkaido and Kyushu opens underpenetrated regional markets for shelter and cooking systems.
- Sustainable material mandates:METI guidelines on recycled polyester procurement create first-mover advantages for domestic manufacturers with circular supply chains.
Industry Challenges
- Fire-safety material compliance:Evolving bans on specific flame-retardant chemistries force rapid reformulation of tent coatings without compromising waterproof ratings.
- Seasonal demand compression:Three-season product cycles concentrate revenue into narrow Q2-Q3 windows, straining working capital for inventory-heavy SKUs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Japan Camping Equipment Market |
| Market Size in 2026 | $820.5 Million |
| Market Size in 2035 | $1,362.85 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Tents, Sleeping Bags, Backpacks, Cooking Gear Material: Polyester, Nylon, Aluminum, Wood End User: Individual Campers, Families, Outdoor Groups, Scouts Distribution Channel: Online Retail, Specialized Stores, General Retailers, Direct Sales |
| Companies Covered | Snow Peak, Montbell, Columbia Sportswear, Newell Brands, AMG Group, Dometic Group, Johnson Outdoors, Exxel Outdoors, Locus Gear, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Japan Camping Equipment Market Trends and Innovations
Specialized outdoor retail formats are blending experiential showroom environments with digital fulfillment infrastructure, reshaping how Japanese consumers discover and purchase camping gear across portable shelters, sleep systems, and backcountry cooking apparatus.
Titanium cookware manufacturing is collapsing the weight-performance tradeoff that previously segmented premium from standard offerings. Solo trekkers and fastpacking enthusiasts in the Northern Alps are adopting titanium pots and utensils at accelerating rates. This material shift is collapsing traditional price tier differentiation as mid-market brands source comparable alloys.
METI product safety standards and JIS quality certifications now govern flame-retardant treatments and structural load ratings for tent assemblies sold domestically. These regulations are forcing manufacturers to reformulate coatings and redesign pole architectures ahead of seasonal product cycles. Tent and shelter categories face the steepest compliance costs, with domestic producers accelerating in-house testing capabilities.
Young urban professionals in Greater Tokyo are compressing purchase decision cycles through social media discovery and peer recommendation systems. Specialized stores retain influence through seasonal gear fitting services, but online platforms are capturing transaction volume via same-day delivery promises. This channel rotation is most visible in the Kanto region, where convenience expectations override traditional retail loyalty for replacement purchases.
Japan Camping Equipment Market Segmentation
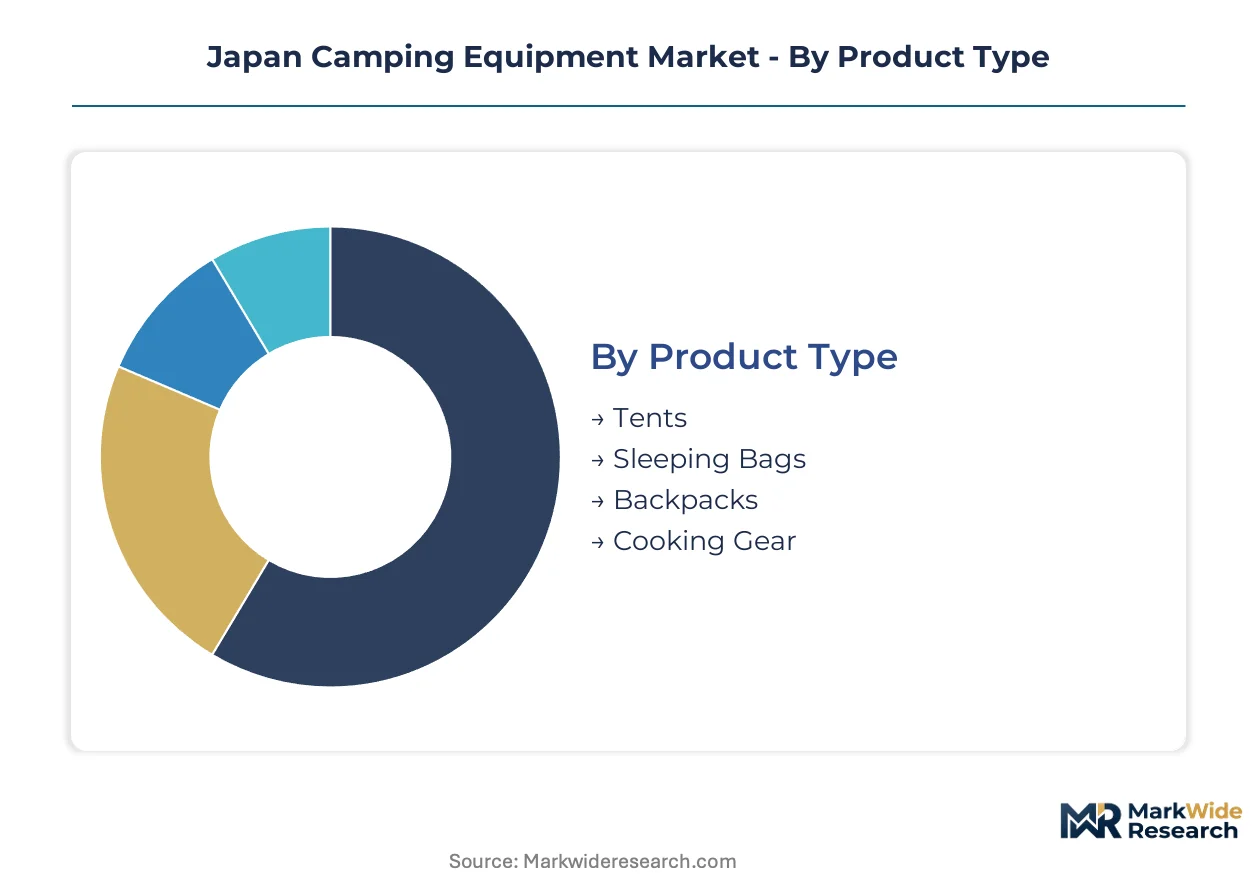
Product configuration in Japan's camping equipment sector follows distinct replacement cycles and usage intensity patterns. Understanding segment turnover rates enables inventory planning and margin optimization across seasonal selling windows.
Product Type:
Tents and cooking gear turn over fastest due to wear exposure and technology refresh cycles, while sleeping bags and backpacks demonstrate longer replacement intervals driven by durability expectations.
- Tents:Nylon and polyester fabric shelters with aluminum pole architectures, typically rated above 1,500mm hydrostatic head for temperate mountain conditions. Solo trekkers in the Northern Alps drive demand for sub-kilogram designs, with METI flame-retardant standards forcing annual coating reformulations that compress product lifecycles.
- Cooking Gear:Titanium and aluminum cookware systems engineered for weight-sensitive backcountry use. Osaka R&D centers advance alloy formulations that reduce pot weights by single-digit percentages annually, triggering replacement purchases among fastpacking enthusiasts before fabric degradation occurs.
- Sleeping Bags:Down and synthetic insulation systems with temperature ratings calibrated to Japan's three-season mountain conditions. Kanto region families prioritize durability over weight, extending replacement cycles beyond tent purchases.
- Backpacks:Internal-frame carrying solutions with ripstop nylon construction. Yamanashi Prefecture outdoor groups favor bombproof designs that withstand decade-long usage, slowing category velocity relative to shelter and cooking segments.
Tents anchor the volume base while cooking gear gains share at the steepest rate.
Material:
Input cost volatility and JIS certification requirements create divergent margin profiles across material categories, with lightweight metals commanding premium positioning against commodity synthetics.
- Polyester:Silicone-coated fabrics dominating tent flysheets and backpack bodies. Domestic manufacturers source recycled grades to meet METI sustainable procurement guidelines, though waterproof rating maintenance complicates reformulation cycles.
- Nylon:Ripstop weaves preferred for high-abrasion zones in backpacks and tent floors. Osaka material science centers advance denier reduction that preserves tear strength, enabling weight targets for solo alpine use.
- Aluminum:Aircraft-grade alloys for tent poles and cookware structural components. Global smelter capacity constraints inject price volatility that manufacturers absorb through seasonal contract structures.
- Wood:Traditional camp furniture and cooking accessories for established campgrounds. Nagano prefectural forestry partnerships sustain niche demand against synthetic substitution pressures.
Polyester underpins the volume base while aluminum expands most quickly on premium positioning.
End User:
Purchase frequency and basket composition vary sharply by group size and experience level, with institutional buyers demonstrating predictable procurement calendars against individual consumer spontaneity.
- Individual Campers:Solo trekkers and fastpacking enthusiasts prioritizing gram-scale weight reduction. Greater Tokyo young professionals compress decision cycles through social media discovery, driving premium titanium and ultralight nylon adoption.
- Families:Multi-person tent and sleep system purchasers emphasizing durability over technical specifications. Kanto region household storage constraints favor rental substitution for infrequent users.
- Outdoor Groups:Club-organized trekkers in the Northern Alps purchasing standardized equipment for liability coordination. Collective procurement concentrates demand into seasonal batch orders.
- Scouts:Youth organization chapters with mandated gear lists and budget ceilings. Prefectural education bureau partnerships create institutional sales channels with extended payment terms.
Individual campers anchor the volume base while outdoor groups climb the fastest on organized participation growth.
Distribution Channel:
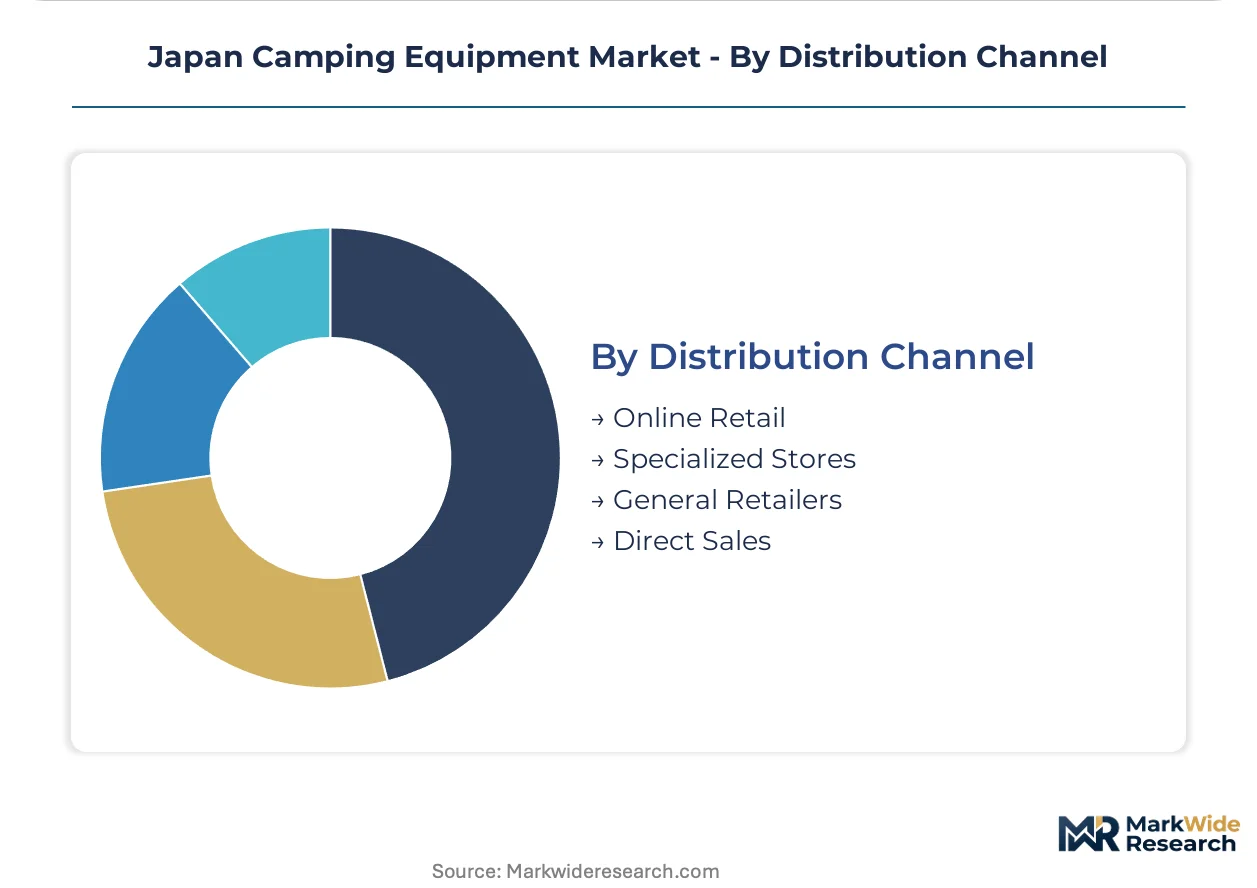
Fulfillment infrastructure investment and customer acquisition economics are restructuring channel share, with digital platforms capturing transaction volume while experiential retail retains discovery influence.
- Online Retail:Digital platforms with same-day delivery promises in the Kanto region. Video consultation services replicate seasonal gear fitting functions previously exclusive to physical showrooms.
- Specialized Stores:Experiential retail formats in Greater Tokyo and Yamanashi with on-site pitching areas. Staff expertise sustains influence for technical tent and sleep system purchases despite price premiums.
- General Retailers:Mass-market sporting goods chains with limited seasonal SKU depth. Convenience positioning captures replacement purchases of commodity cooking accessories.
- Direct Sales:Manufacturer-owned channels leveraging domestic production proximity. Snow Peak's vertically integrated model exemplifies margin capture through captive retail.
Specialized stores anchor the volume base while online retail gains share at the steepest rate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Chuo Shinkansen maglev corridor anchors domestic logistics capacity for camping equipment distribution across Japan's mountainous spine, compressing delivery timelines between manufacturing clusters in Greater Nagoya and consumption centers in the Tokyo-Osaka corridor.
Kanto/Tokyo
Young urban professionals in Shibuya and Shinjuku wards drive premium tent and titanium cookware purchases through experiential retail formats. METI's regional tourism promotion policies subsidize campsite infrastructure development in adjacent Yamanashi Prefecture. The Okutama and Tanzawa mountain gateways concentrate specialized store locations serving weekend trekkers.
Kansai/Osaka
Osaka-based R&D centers advance ultralight nylon ripstop and silicone-coated polyester fabrics for weight-sensitive alpine applications. JIS quality certification timelines for flame-retardant treatments create extended product launch cycles that compress seasonal selling windows. The Senri-Chuo retail corridor hosts flagship experiential showrooms blending digital fulfillment with on-site gear fitting.
Chubu/Nagoya
Manufacturing proximity to aluminum smelter networks in Aichi Prefecture supports tent pole and cookware fabrication. Prefectural forestry bureau partnerships in Gifu and Nagano expand addressable recreation zones for shelter vendors. The Komagane and Iida districts concentrate domestic production facilities for aircraft-grade alloy components.
Hokkaido
Extended camping seasons and wilderness trekking routes drive demand for four-season-rated sleep systems and bombproof shelter designs. Collaborative campsite development between prefectural authorities and equipment vendors opens underpenetrated regional markets. The Daisetsuzan and Shiretoko gateway towns anchor distribution infrastructure for backcountry-focused retailers.
Kyushu
METI sustainable manufacturing guidelines redirect procurement standards toward recycled polyester and circular supply chains among Fukuoka-based distributors. Aso-Kuju National Park and Yakushima UNESCO zones filter equipment specifications toward Leave-No-Trace-compatible compact designs. The Fukuoka-Hakata logistics hub connects domestic manufacturers to emerging demand in southern prefectures.
Japan Camping Equipment Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream capturing margin on material science and precision fabrication. The vendor base stratifies between vertically integrated domestic manufacturers and licensed distribution partners navigating market entry without direct retail investment. Three archetypes dominate: titanium alloy specialists leveraging in-house smelter relationships, ultralight fabric innovators with captive R&D facilities, and multi-brand distributors optimizing channel economics through partnership structures. Competitive moves concentrate on backward integration into aluminum supply and digital fulfillment infrastructure buildout.
Within the vertically integrated tier, Snow Peak exemplifies captive manufacturing of precision alloy components, while Montbell anchors the ultralight innovation vector through Osaka-based material science development. Columbia Sportswear occupies a licensed distribution position, navigating market access without direct retail capital deployment. These three patterns illustrate how domestic production proximity, R&D concentration, and partnership-based channel strategies segment competitive positioning across the Japanese camping equipment sector.
| Leading Market Players |
|---|
| Snow Peak |
| Montbell |
| Columbia Sportswear |
| Newell Brands |
| AMG Group |
| Dometic Group |
| Johnson Outdoors |
| Exxel Outdoors |
| Locus Gear |
| Others |
Pricing and Supply Chain Analysis
Aluminum smelter capacity utilization at Aichi Prefecture facilities drives both input cost volatility and supplier pricing power across tent pole and cookware manufacturers. METI sustainable manufacturing guidelines are compressing margins for domestic producers unable to source recycled polyester at scale, while Kanto region retailers absorb freight premiums through seasonal contract structures.
Pricing Analysis
Volume-discount tiering structures separate Snow Peak's captive titanium production from licensed distributors and mass-market sporting goods chains. Price differentiation rests on JIS certification grade and after-sales fitting service bundling, with specialized stores commanding premiums for technical consultation. Cost compression in standard nylon tent fabrics is intensifying because Osaka R&D centers advance denier reduction annually. Individual campers in Greater Tokyo show lowest price sensitivity for ultralight sub-kilogram designs, while families substitute rental services where storage constraints dominate.
Supply Chain Analysis
Export-control regimes on aircraft-grade aluminum alloys limit flows from domestic Aichi smelters to precision fabricators in Nagano and Yamanashi. Geographic supply concentration centers on Japan, Taiwan, and South Korea for silicone-coated polyester and ripstop nylon inputs. Raw material dependencies include titanium ore, aircraft-grade aluminum, and down insulation sourced from circular supply chains. Single-source vulnerability concentrates in aluminum pole architecture suppliers. Distribution runs through the Chuo Shinkansen maglev corridor connecting Greater Nagoya manufacturing to Tokyo-Osaka consumption centers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform economics are inflecting as video consultation services replicate specialized store fitting functions, collapsing discovery-transaction separation that previously anchored retail loyalty. Interoperability between digital fulfillment and experiential showroom infrastructure is reshaping customer acquisition economics.
For Market Incumbents: Harden JIS certification capabilities against evolving flame-retardant chemistry bans that compress product launch cycles. Deepen upstream control over aluminum supply through Aichi Prefecture smelter partnerships to defend margin position against global capacity constraints. Lock in seasonal batch contracts with Northern Alps outdoor groups before emerging ultralight specialists capture collective procurement volumes.
For New Entrants and Emerging Players: Build out direct-to-consumer digital infrastructure targeting Hokkaido and Kyushu prefectures where specialized retail penetration remains thin. Prefectural forestry bureau partnerships in underpenetrated regional markets offer the most penetrable entry vector. Launch with titanium cookware private-label manufacturing to bypass tent category compliance burdens while establishing brand recognition.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across ultralight fabric R&D as Osaka material science centers achieve scale economies in denier reduction. Long-term viability favors vertically integrated domestic manufacturers with captive smelter relationships and circular polyester supply chains. Acquisition target archetypes include precision alloy fabricators serving solo trekker demand. Watch for METI recycled content mandates tightening as the inflection signal for first-mover advantage revaluation.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Aluminum Supply | Captive Aichi smelter access insulates Snow Peak from global capacity volatility. |
| Digital Fulfillment Infrastructure Buildout | Same-day Kanto delivery promises capture transaction volume from experiential retail. |
| JIS Certification Acceleration | In-house flame-retardant testing compresses seasonal product launch timelines. |
| Prefectural Forestry Bureau Partnership | Collaborative Hokkaido campsite development opens underpenetrated regional shelter demand. |
| Sustainable Material Repositioning | Recycled polyester procurement aligns with METI guidelines for circular supply chains. |
Research Methodology
Desk research of METI regulatory filings, JIS certification databases, and prefectural tourism promotion records preceded structured interviews with titanium alloy procurement managers, ultralight fabric R&D directors, specialized retail category buyers, and prefectural forestry bureau planning officers. Secondary validation drew from customs trade data, national parks access records, and aluminum smelter capacity disclosures. Bottom-up demand modeling across product segments triangulated against top-down tourism expenditure flows.
Assumptions held fixed include METI regional tourism subsidy continuation and JIS flame-retardant standard stability, while aluminum price volatility and campsite capacity expansion rates varied across scenario branches. Segmentation dimensions modeled encompass product type, material grade, end-user group size, and distribution channel complexity. CAGRs were derived from replacement cycle analysis and participation rate elasticity across the projection horizon. Industry-specific inputs included solo trekker growth in the Northern Alps and rental service substitution rates among Tokyo apartment dwellers.
Sensitivities concentrate around aluminum supply disruptions, JIS chemistry ban accelerations, and prefectural campsite development delays. Forecasts reflect these assumptions without claiming predictive certainty. Material shifts in METI sustainable procurement mandates or maglev corridor logistics capacity would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Outdoor Gear
North America and Europe Leaf Blower Market
Outdoor Gear
Camping Gas Canister Market
Outdoor Gear
Inflatable Tents Market
Outdoor Gear
Shoulder Strap Insulated Cooler Market
Outdoor Gear
Sleeping Bag Market
Outdoor Gear
Canoe Paddles Market
Outdoor Gear
Europe Camping Equipment Market
Outdoor Gear
Camping Cooler Market
Outdoor Gear
Rooftop Tent Market
Outdoor Gear
Artificial Grass Turf Market
Outdoor Gear
Trail Running Bags Market
Outdoor Gear
Hiking Backpack Water Filters Market
Outdoor Gear
Wheeled Insulated Cooler Market
Outdoor Gear
Deer Hunting Blinds Market
Outdoor Gear
Rain Boots Market
Outdoor Gear
South Korea Camping Equipment Market