
 Global Inspection Management Software Market | 2026-2036
Global Inspection Management Software Market Size, Share, and Industry Trends Forecast 2026-2036
Global Inspection Management Software Market Foresight
Subscription-based project financing and asset-light SaaS leasing models are reshaping competitive entry barriers for inspection management platforms. SAP SE leverages its enterprise ERP install base to anchor cross-sell opportunities into quality workflows. Hexagon AB specializes in geospatial-measurement integration for construction and utilities inspection verticals. Intelex Technologies Inc. competes through purpose-built environmental health and safety modules that extend platform utility beyond core quality functions.
Inspection management software orchestrates field data capture, defect tracking, corrective action workflows, and audit trail generation across distributed physical assets, typically integrating IoT sensor feeds with mobile-native user interfaces. Cloud-based deployment leads solution type adoption as facility managers prioritize remote accessibility and elastic compute scaling over capital-intensive on-premises infrastructure. Workflow automation segments command margin concentration due to recurring integration services, while compliance management solutions sustain premium pricing from regulatory agencies and heavily regulated aerospace manufacturers requiring auditable inspection protocols.
FDA digital health guidance, EU AI Act conformity requirements for automated decision systems, and ISO 9001 quality management standards collectively mandate traceable inspection documentation and algorithmic accountability in regulated industries. OSHA workplace safety directives and FAA airworthiness certification rules further shape product specification requirements for safety inspectors and maintenance providers. Stakeholders must monitor evolving cross-border data residency requirements that determine where cloud inspection records may legally reside and process.
Market Dynamics
Cloud migration is compressing deployment timelines from quarters to weeks, forcing incumbent vendors to dismantle on-premises revenue models while manufacturing quality teams demand elastic compute for seasonal inspection surges.
Growth Catalysts
- EU AI Act Algorithmic Accountability:Automated inspection systems in aerospace and medical device manufacturing now require auditable decision trails, mandating software upgrades that embed compliance documentation natively into quality workflows.
- Industrial Cluster Modernization:Germany's automotive belt, Japan's precision manufacturing corridors, and Texas petrochemical complexes are retiring paper-based inspection logs in favor of mobile-native platforms with offline synchronization.
- IoT Sensor Proliferation:Predictive maintenance programs in wind energy and pipeline infrastructure generate continuous inspection data streams that exceed spreadsheet capacity, pulling demand toward orchestration platforms.
Market Restraints
- Cross-Border Data Residency Friction:GDPR localization requirements and China's data sovereignty rules fragment cloud architectures, forcing vendors to maintain redundant infrastructure that inflates operational overhead.
- Legacy System Entrenchment:Brownfield manufacturing facilities in the US Midwest and Northern England run inspection protocols on decade-old ERP modules with brittle APIs, extending sales cycles and integration costs.
- Specialized Talent Scarcity:Quality engineers capable of bridging ISO 9001 compliance frameworks with Python-based analytics pipelines command compensation premiums that compress vendor margins on implementation services.
Strategic Opportunities
- India Manufacturing Digitization:PLI scheme incentives for domestic electronics and pharmaceutical production create first-mover advantage for inspection platforms localized to BIS certification workflows and Hindi-language interfaces.
- Construction-Utility Convergence:Geospatial measurement integration from Hexagon AB's specialty is hybridizing with drone-based facade inspection, opening vertical expansion for platforms with native CAD interoperability.
- Subscription Financing Innovation:Asset-light SaaS leasing models reduce customer capex barriers, allowing mid-market food processors and textile mills to access enterprise-grade audit trail capabilities without balance sheet impact.
Industry Challenges
- Multi-Standard Certification Burden:Vendors serving aerospace must simultaneously maintain FAA airworthiness documentation, EASA compliance modules, and CAAC equivalency certificates, multiplying quality assurance overhead.
- API Fragmentation in Brownfield Environments:SAP ERP, Oracle Manufacturing, and proprietary SCADA systems expose inconsistent data schemas, forcing custom integration work that erodes platform gross margins.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Inspection Management Software Market |
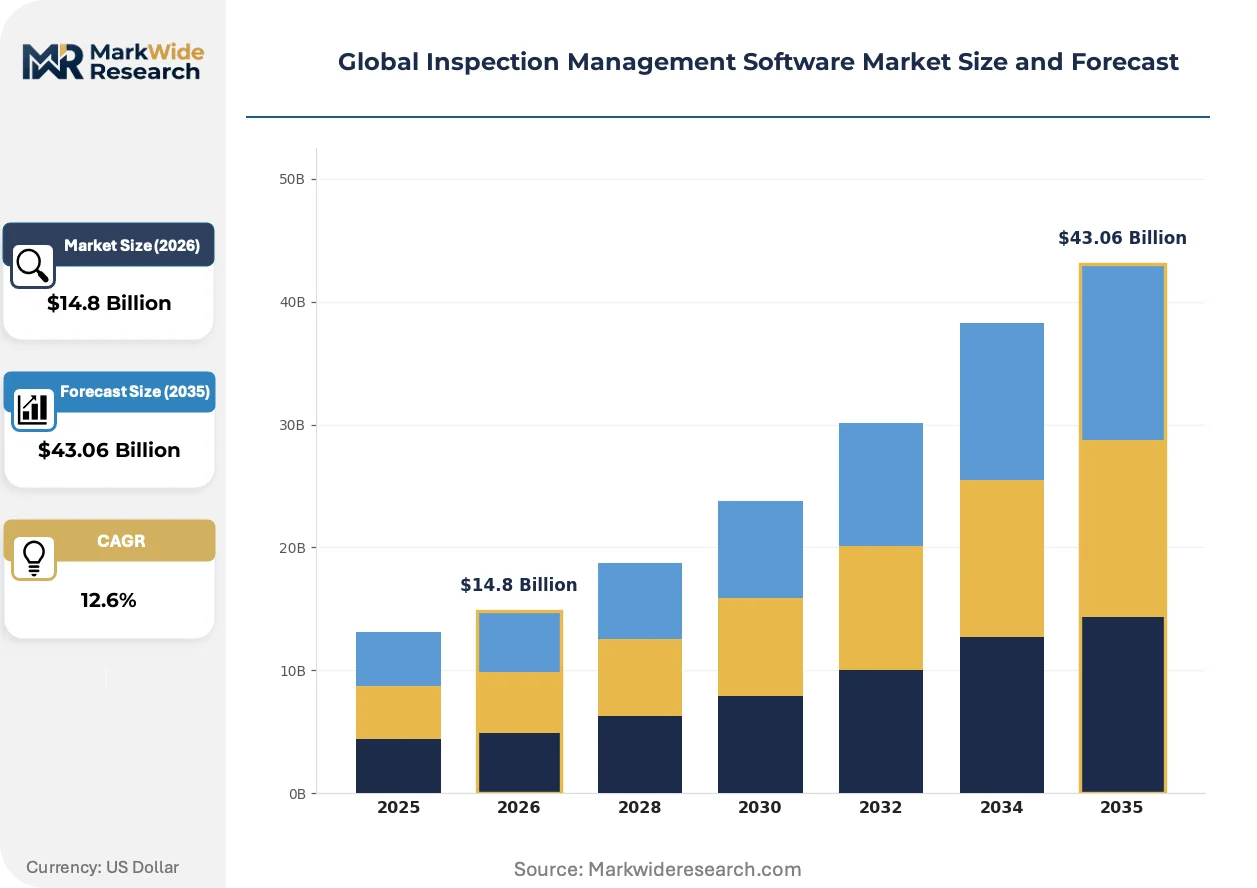
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $43.06 Billion |
| CAGR (2026 – 2036) | 12.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: Cloud-Based, On-Premises, Hybrid, Edge Computing Solution Type: Workflow Automation, Quality Control, Asset Inspection, Compliance Management, Risk Assessment Application: Manufacturing, Construction, Aerospace, Utilities, Public Safety End User: Facility Managers, Quality Assurance Teams, Safety Inspectors, Maintenance Providers, Regulatory Agencies |
| Companies Covered | SAP SE, Hexagon AB, Oracle Corporation, PTC Inc., Wolters Kluwer N.V., Autodesk Inc., Dassault Systèmes SE, Intelex Technologies Inc., Siemens AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Inspection Management Software Market Shifts & Advancements
Edge-to-cloud inspection architectures are collapsing latency thresholds for real-time defect detection, while regulatory pressure on algorithmic transparency is rewriting software development priorities across quality assurance verticals.
Computer vision systems for surface defect detection is hybridizing rule-based image processing with deep learning inference at the network edge. Automotive stamping plants in Stuttgart and Wolfsburg are deploying these hybrid models to catch micro-cracks in aluminum body panels at conveyor speeds exceeding prior pure-software limits. The technology is compressing the boundary between quality control and predictive maintenance, as defect pattern libraries feed upstream into die wear forecasting.
REACH substance restriction updates and EU AI Act conformity requirements are mandating traceable documentation for automated sorting decisions in electronics recycling facilities. Industrial consequence includes compulsory human-in-the-loop overrides for high-stakes classification calls and immutable audit logs stored on EU-sovereign cloud infrastructure. German white goods manufacturers and Dutch semiconductor recyclers are responding by procuring inspection modules with pre-certified compliance templates rather than building custom documentation stacks.
Consolidated procurement of quality and safety software is displacing point solutions as EHS managers seek unified platforms spanning ISO 45001 occupational health, ISO 9001 quality, and EPA environmental reporting. Chemical processors along the US Gulf Coast and pharmaceutical manufacturers in New Jersey are bundling inspection management into broader operational risk contracts, favoring vendors with pre-integrated environmental health modules over specialized quality-only tools.
Global Inspection Management Software Market Segmentation
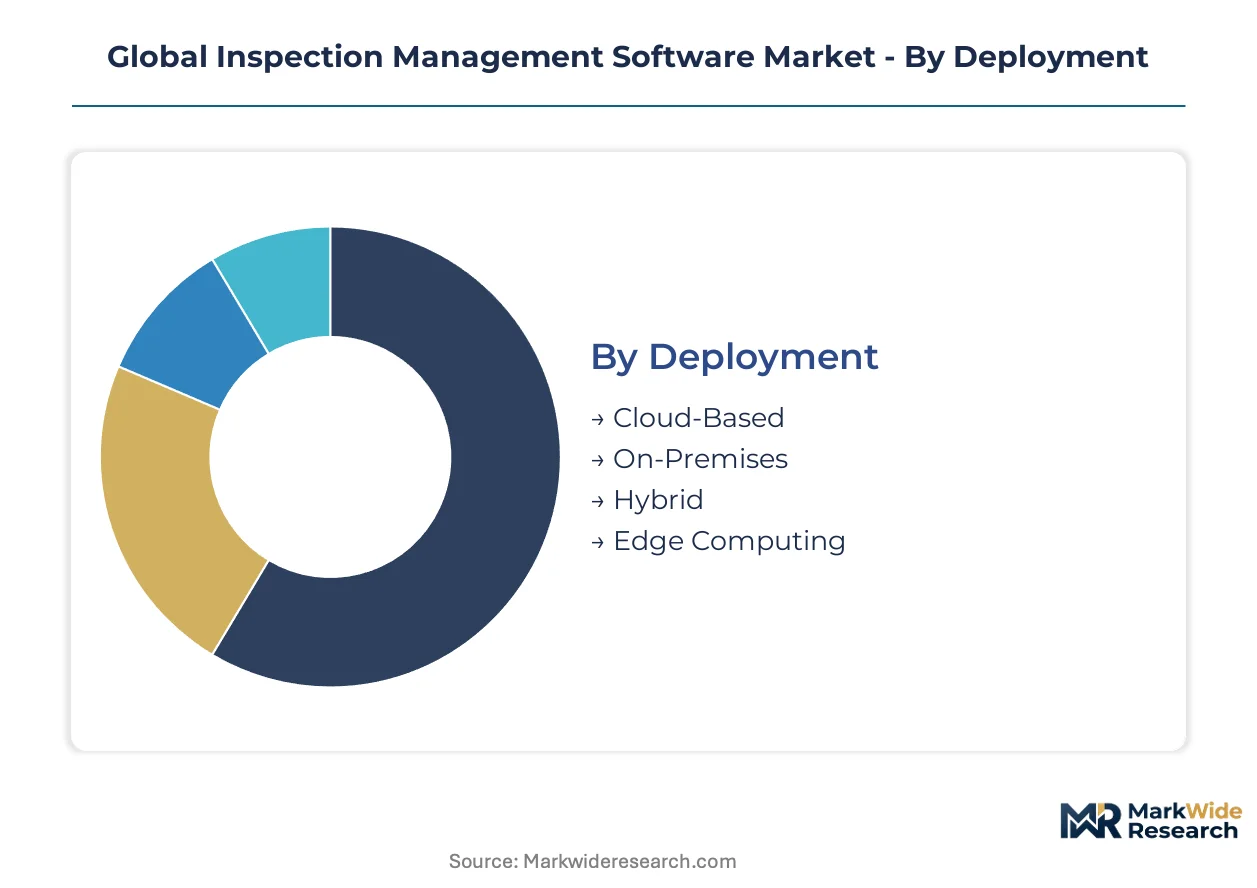
Deployment architecture determines total cost of ownership and regulatory compliance posture for inspection management platforms. Solution type and end-user specialization create divergent margin profiles and integration complexity. Application verticals impose distinct certification requirements and data sovereignty constraints.
Deployment:
Cost tier structures separate capital-intensive perpetual licenses from operational expenditure models with elastic scaling.
- Cloud-Based:Multi-tenant SaaS architectures with automatic updates and API-first integration stacks. German automotive suppliers and Texas petrochemical operators prioritize this model for remote facility access and seasonal inspection surge capacity without infrastructure provisioning delays.
- On-Premises:Single-tenant installations behind customer firewalls with full data localization control. Aerospace manufacturers in Toulouse and defense contractors near Washington DC mandate this tier for airworthiness documentation subject to ITAR and EASA classified data handling rules.
- Hybrid:Sensitive audit trails remain on-premises while mobile field data synchronizes through cloud gateways. Japanese precision manufacturers favor this split for protecting proprietary defect pattern libraries.
- Edge Computing:Real-time inference engines deployed directly on inspection hardware for sub-100ms defect detection latency. Wind turbine blade scanning operations in Denmark and pipeline crawler units in Alberta deploy these configurations.
On-Premises commands the established base. The steepest expansion runs through Cloud-Based deployments.
Solution Type:
Application focus determines recurring revenue durability and professional services attachment rates.
- Workflow Automation:Orchestrates inspection scheduling, assignment routing, and corrective action escalation across distributed teams. Food processors in the Netherlands and pharmaceutical manufacturers in New Jersey attach this module to reduce deviation closure times from weeks to days.
- Compliance Management:Pre-certified templates for ISO 9001, FDA 21 CFR Part 11, and EU AI Act algorithmic accountability documentation. Medical device manufacturers in Minnesota and Ireland procure these solutions to preempt regulatory audit findings.
- Quality Control:Statistical process control dashboards integrating SPC charts with non-conformance tracking. Automotive stamping plants in Stuttgart deploy these for real-time dimensional stability monitoring.
- Asset Inspection:Condition-based maintenance triggers linking inspection findings to work order generation. Electric utilities in Florida and railway operators in France standardize on this capability for infrastructure lifecycle optimization.
- Risk Assessment:Quantitative scoring models for prioritizing inspection frequency based on failure consequence and probability. Chemical processors along the US Gulf Coast implement these for OSHA PSM compliance and insurance premium reduction.
Workflow Automation commands the established base. Compliance Management is climbing the fastest as regulatory frameworks tighten algorithmic transparency requirements.
Application:
Customer verticals impose specialized certification demands and integration complexity that reshape vendor competitive positioning.
- Manufacturing:Shop-floor quality systems with MES and ERP bidirectional data exchange. Electronics assemblers in Shenzhen and contract manufacturers in Mexico dominate procurement volumes for traceable component inspection.
- Aerospace:FAA airworthiness directive tracking and EASA continuing airworthiness management organization documentation. Maintenance repair overhaul facilities in Singapore and Seattle require these specialized modules for fleet compliance.
- Construction:Georeferenced inspection checkpoints with CAD-BIM interoperability and drone imagery correlation. Infrastructure projects in Dubai and Sydney specify these capabilities for progress payment verification.
- Utilities:Linear asset inspection with GIS integration and vegetation management scheduling. Transmission operators in Germany and water utilities in California standardize on this vertical specialization.
- Public Safety:Emergency equipment inspection with NFPA code compliance and first-responder accessibility certification. Fire departments in Ontario and municipal building inspectors in Texas represent primary demand concentration.
Manufacturing commands the established base. Aerospace is gaining share fastest from regulatory digitization mandates.
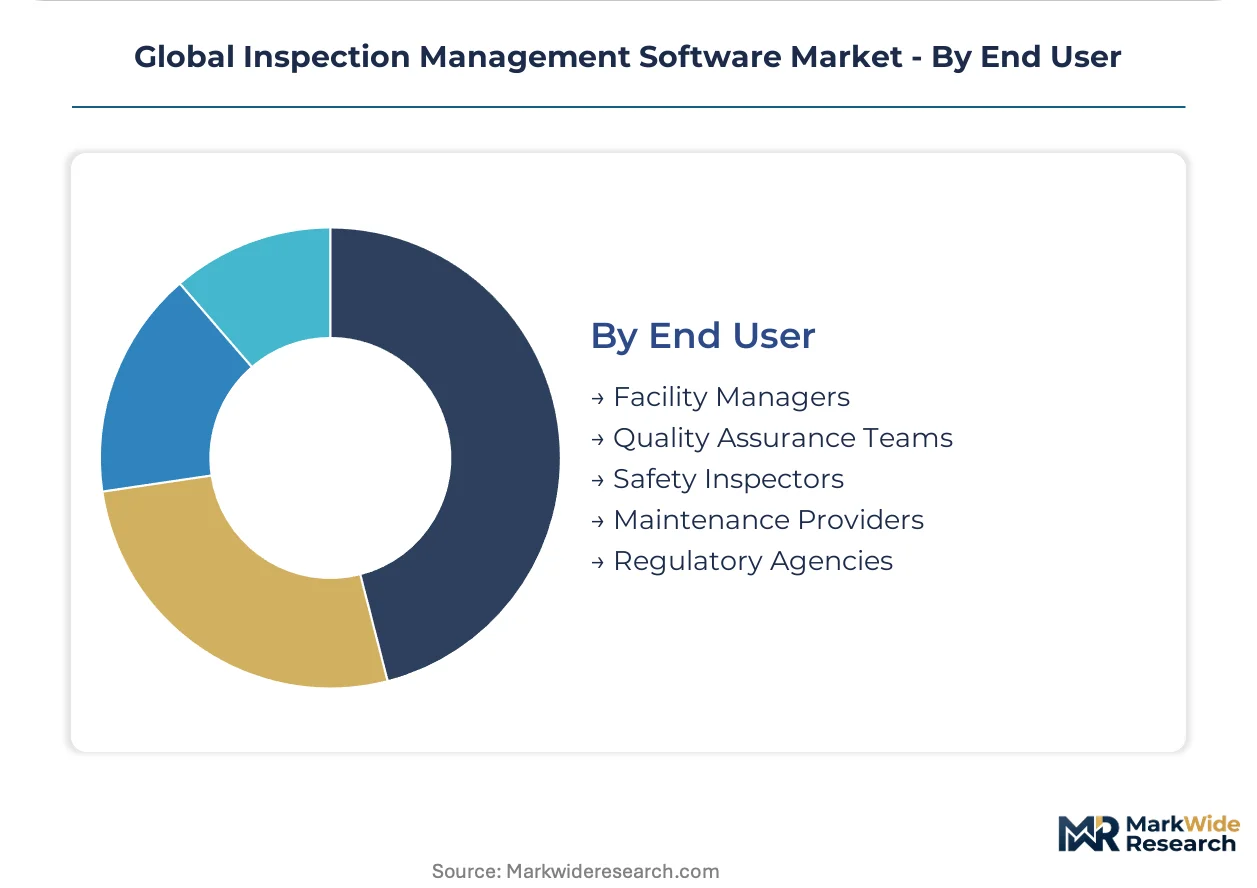
End User:
Organizational role determines user interface complexity, mobile dependency, and approval workflow hierarchy.
- Quality Assurance Teams:Statistical analysis tools with CAPA management and supplier scorecard integration. Medical device quality engineers in Massachusetts and automotive quality managers in Wolfsburg drive specification requirements.
- Regulatory Agencies:Audit trail reconstruction and cross-facility compliance comparison dashboards. FDA investigators and EASA certification engineers utilize read-only access tiers for surveillance activities.
- Facility Managers:Multi-asset overview consoles with maintenance budget forecasting and contractor performance tracking. University campus operators in the United Kingdom and hospital estates teams in Australia represent this segment.
- Safety Inspectors:Offline-capable mobile applications with photo annotation and immediate hazard escalation protocols. OSHA compliance officers and construction site safety coordinators in Alberta require ruggedized device support.
- Maintenance Providers:Work order integration with spare parts inventory and technician skill-matching algorithms. Wind farm service contractors in Denmark and elevator maintenance unions in France standardize on these capabilities.
Quality Assurance Teams command the established base. Regulatory Agencies are expanding most quickly from EU AI Act inspection authority expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Trade in inspection management software services runs surplus in Germany and the United States against persistent deficits in India and Southeast Asian manufacturing hubs. Licensing revenue from cloud-based quality platforms now exceeds cross-border consulting flows, reshaping how vendors allocate regional sales capacity.
United States
FDA digital health oversight and OSHA workplace safety directives drive procurement from medical device manufacturers in Minnesota and pharmaceutical clusters in New Jersey. The FAA mandates airworthiness documentation systems for maintenance repair overhaul facilities near Seattle. Texas petrochemical complexes along the Gulf Coast are retiring paper-based inspection logs for mobile-native platforms with offline synchronization.
Germany
EU AI Act algorithmic accountability requirements and REACH substance restriction updates compel software upgrades for automated sorting decisions. Stuttgart and Wolfsburg automotive stamping plants deploy hybrid computer vision models for micro-crack detection at conveyor speeds. Bavarian precision manufacturers favor hybrid cloud architectures protecting proprietary defect pattern libraries.
Japan
METI industrial digitization incentives and JIS quality standards accelerate replacement of legacy ERP modules in Nagoya and Osaka manufacturing corridors. Tokyo-based precision equipment makers demand edge-to-cloud architectures for sub-100ms defect detection latency. Chubu region automotive suppliers prioritize elastic compute scaling for seasonal inspection surges.
India
PLI scheme incentives for domestic electronics and pharmaceutical production create first-mover opportunity for platforms localized to BIS certification workflows. Maharashtra and Gujarat contract manufacturers procure traceable component inspection systems for export compliance. Karnataka software development hubs drive Hindi-language interface customization for mid-market food processors.
China
Data sovereignty rules and GB standards fragment cloud architectures, forcing redundant infrastructure investment for vendors serving NMPA-regulated medical device manufacturers. Shenzhen electronics assemblers dominate procurement volumes for shop-floor quality systems with MES integration. Yangtze River Delta pharmaceutical exporters navigate dual compliance with domestic and EU AI Act documentation requirements.
Global Inspection Management Software Market Competitive Landscape
On the supply side, the industry is consolidating around enterprise ERP incumbents with cross-sell leverage into quality workflows. Three strategic archetypes dominate: diversified software conglomerates anchoring bundled operational risk contracts, specialized measurement technology vendors with geospatial integration capabilities, and purpose-built EHS platforms extending beyond core quality functions. Competitive moves concentrate on API-first integration stacks and subscription financing innovations that compress customer capex barriers.
Within the diversified software tier, SAP SE and Oracle Corporation exemplify vendors leveraging enterprise install bases to anchor cross-sell opportunities into manufacturing quality workflows. Hexagon AB occupies a distinct position among measurement technology specialists, while Intelex Technologies Inc. represents the purpose-built EHS extension archetype with environmental health and safety modules.
| Leading Market Players |
|---|
| SAP SE |
| Hexagon AB |
| Oracle Corporation |
| PTC Inc. |
| Wolters Kluwer N.V. |
| Autodesk Inc. |
| Dassault Systèmes SE |
| Intelex Technologies Inc. |
| Siemens AG |
| Others |
Supply & Pricing Matrix
EU AI Act algorithmic accountability mandates compress both pricing tier spreads and supply chain architectures by forcing redundant compliance infrastructure across cloud regions. Vendors absorb localization costs while manufacturing quality teams demand elastic compute scaling without balance sheet impact.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels. Premium tiers bundle pre-certified EU AI Act compliance modules and dedicated sovereign cloud instances for aerospace manufacturers in Toulouse. Standard tiers target mid-market food processors with subscription financing that eliminates capex barriers. Price differentiation hinges on certification grade and customization depth. Cost compression in economy tiers intensifies because Indian PLI scheme beneficiaries negotiate volume discounts for Hindi-localized deployments. Contract manufacturers in Mexico demonstrate highest price sensitivity; defense contractors near Washington DC show least sensitivity due to ITAR-mandated on-premises requirements.
Supply Chain Analysis
Extended payment terms and supply-chain finance facilities from cloud hyperscalers enable SaaS vendors to defer infrastructure provisioning costs across multi-tenant architectures. Software development concentrates in India, Germany, and the United States. Delivery draws from API integration specialists, compliance documentation engineers, and edge computing hardware partners. Single-source vulnerability runs through hyperscaler cloud regions subject to GDPR localization requirements. Distribution runs through direct enterprise sales teams and systems integrators serving brownfield manufacturing facilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform economics in inspection management software are reaching an inflection as ERP incumbents bundle quality workflows into broader operational risk contracts, collapsing standalone point-solution margins.
For Market Incumbents: Entrench cross-sell leverage by embedding inspection modules within existing ERP install bases before specialized EHS platforms extend into quality workflows. Acquire API-first integration specialists to reduce custom implementation costs that erode gross margins in brownfield environments. Prioritize certification investment in FAA airworthiness and EU AI Act pre-compliance templates to preempt regulatory audit findings from eroding pricing power. For New Entrants and Emerging Players: Build out localized platforms for India's PLI scheme beneficiaries in Maharashtra and Gujarat electronics corridors, where first-mover advantage in BIS certification workflows remains uncontested. Target mid-market food processors and textile mills with asset-light SaaS leasing models that bypass incumbent enterprise sales cycles. Pursue channel partnerships with systems integrators serving construction-utility convergence projects requiring geospatial-CAD interoperability. For Investors and Strategic Acquirers: EU AI Act enforcement reshapes the acquisition landscape by elevating vendors with pre-certified algorithmic accountability documentation above pure-play workflow automation tools. Long-term viability centers on platforms spanning ISO 9001 quality, ISO 45001 safety, and EPA environmental reporting rather than specialized quality-only solutions. Target acquisition archetypes include purpose-built EHS platforms with environmental health modules and measurement technology vendors with native geospatial integration. Monitor FDA digital health guidance expansion as the signal indicating accelerated consolidation around compliance-embedded platforms.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | ERP incumbents bundle inspection modules into operational risk contracts spanning quality, safety, and environmental workflows. |
| Acquisition of Specialist Firm | API-first integration specialists reduce custom implementation costs eroding margins in brownfield manufacturing environments. |
| Geographic Expansion | Localized deployments in India's PLI scheme corridors capture first-mover position in BIS certification workflows. |
| Strategic Partnership | Hyperscaler alliances provide sovereign cloud infrastructure for EU AI Act data residency requirements. |
| Product Launch | Edge-to-cloud architectures with sub-100ms defect detection latency target wind energy and pipeline infrastructure verticals. |
Research Methodology
A spread of perspectives from quality assurance directors, regulatory affairs leads at medical device manufacturers, EHS managers in chemical processing, and cloud procurement officers converged on the working assumptions. Primary interviews with SAP and Oracle implementation partners, Hexagon AB geospatial specialists, and Intelex Technologies integration teams informed vendor competitive positioning. Secondary validation drew from FDA 21 CFR Part 11 guidance documents, EU AI Act conformity assessment procedures, ISO 9001 certification databases, and SEC filings from diversified software conglomerates. Bottom-up deployment model sizing and top-down quality software market triangulation anchored volume estimates.
Demand-supply balance modeling across the analysis window segmented by deployment architecture, solution type, application vertical, and end-user role. The analytical framework incorporated organization size tiers, integration complexity levels, and regional adoption patterns. CAGRs were derived from elasticity-adjusted replacement cycles for legacy ERP modules and regulatory-mandated upgrade timelines. Industry-specific forecast inputs included METI industrial digitization incentive disbursement rates and PLI scheme beneficiary registration data.
The forecast holds incumbent behavior within observed patterns; aggressive platform bundling moves by ERP conglomerates or hyperscaler vertical integration would shift outcomes. Macroeconomic contraction in German automotive corridors, delayed EU AI Act enforcement timelines, or breakthrough edge-AI hardware cost reductions would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
GCC Human Capital Management Software Market
Software & Services
Customer Self-Service Software Market
Software & Services
Global Franchise Management Software Market
Software & Services
Period-Tracking Software Market
Software & Services
Application Platform As a Service Market
Software & Services
Mainframe Software Market
Software & Services
Over the Air (OTA) Updates Market
Software & Services
Camera Tracking Software Market
Software & Services
Time Series Databases Software Market
Software & Services
Dropshipping Software Solutions Market
Software & Services
Global Script Writing Software Market
Software & Services
IT Professional Services Market
Software & Services
Optical Coatings Design Software Market
Software & Services
Global Servicenow Store Apps Market
Software & Services
Business Spend Management (BSM) Software Market
Software & Services
Procure to Pay Software Market