
 Organic Tampons Market | 2026-2036
Organic Tampons Market Size, Share, and Industry Trends Forecast 2026-2036
Organic Tampons Market Analysis
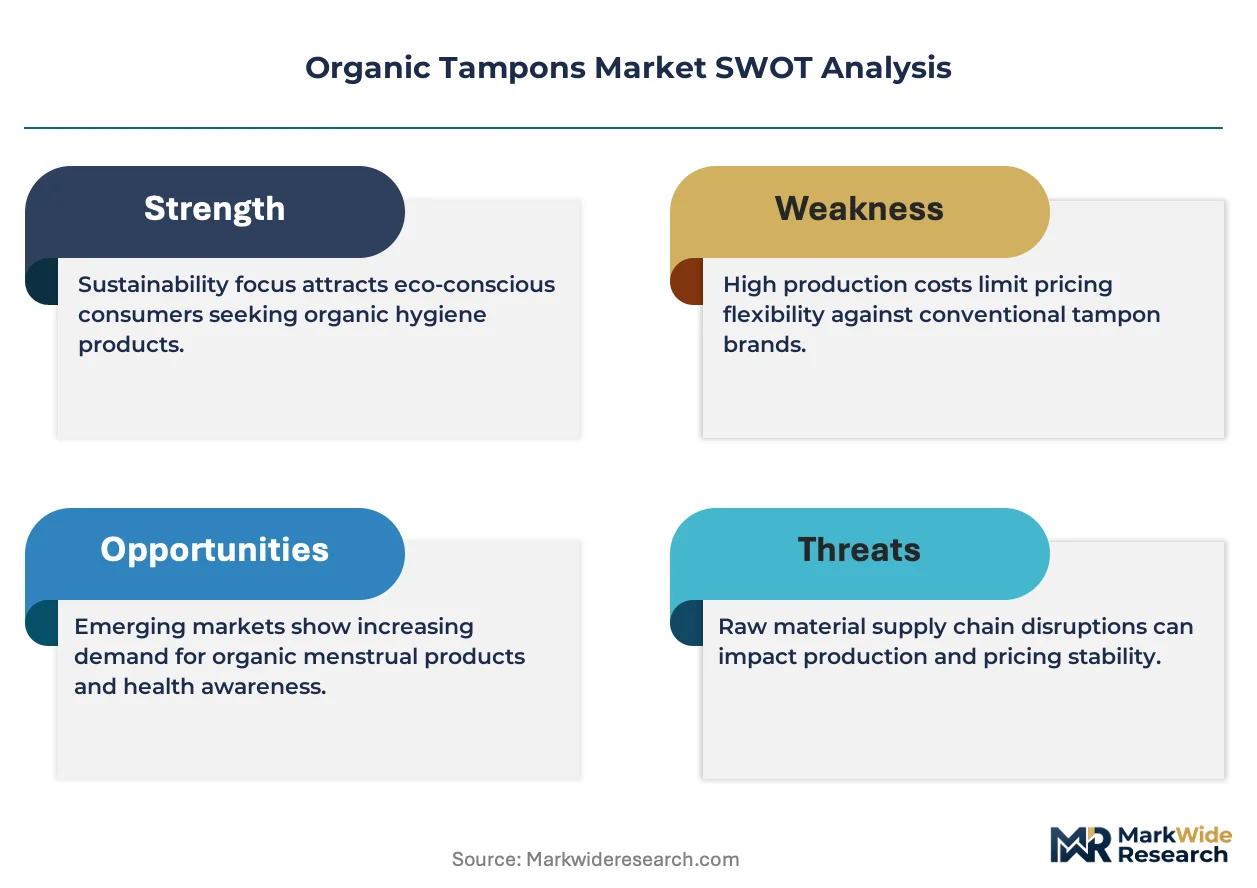
GOTS-certified organic cotton sourcing is redrawing competitive boundaries in feminine hygiene. Cora Inc. leverages direct-to-consumer subscription mechanics to sustain recurring revenue. Natracare Limited anchors European retail presence through pharmacy and specialty store networks. Organyc S.r.l. differentiates via Italian manufacturing heritage and EU organic certification control.
Organic tampons are cylindrical absorbent devices composed of certified organic cotton fibers, free from synthetic pesticides, chlorine bleach, and rayon additives, manufactured through carding and compression processes to regulated absorbency standards. They serve menstruators seeking reduced chemical exposure and biodegradability. Organic cotton material commands premium shelf positioning due to supply scarcity and certification overhead. Online retail channels capture the fastest expansion as subscription platforms reduce customer acquisition costs. Super absorbency product types occupy the core volume tier, while Super Plus and Ultra variants extract higher per-unit margins from athletic and heavy-flow segments.
FDA oversight in the United States mandates absorbency labeling and Good Manufacturing Practice compliance, while REACH and the EU Green Deal restrict residual agrichemicals in imported cotton. BIS standards in India and GB standards in China impose additional compositional testing for cross-border market entry. Stakeholders must monitor certification body recognition reciprocity between organic standards authorities as fragmentation risks supply qualification delays.
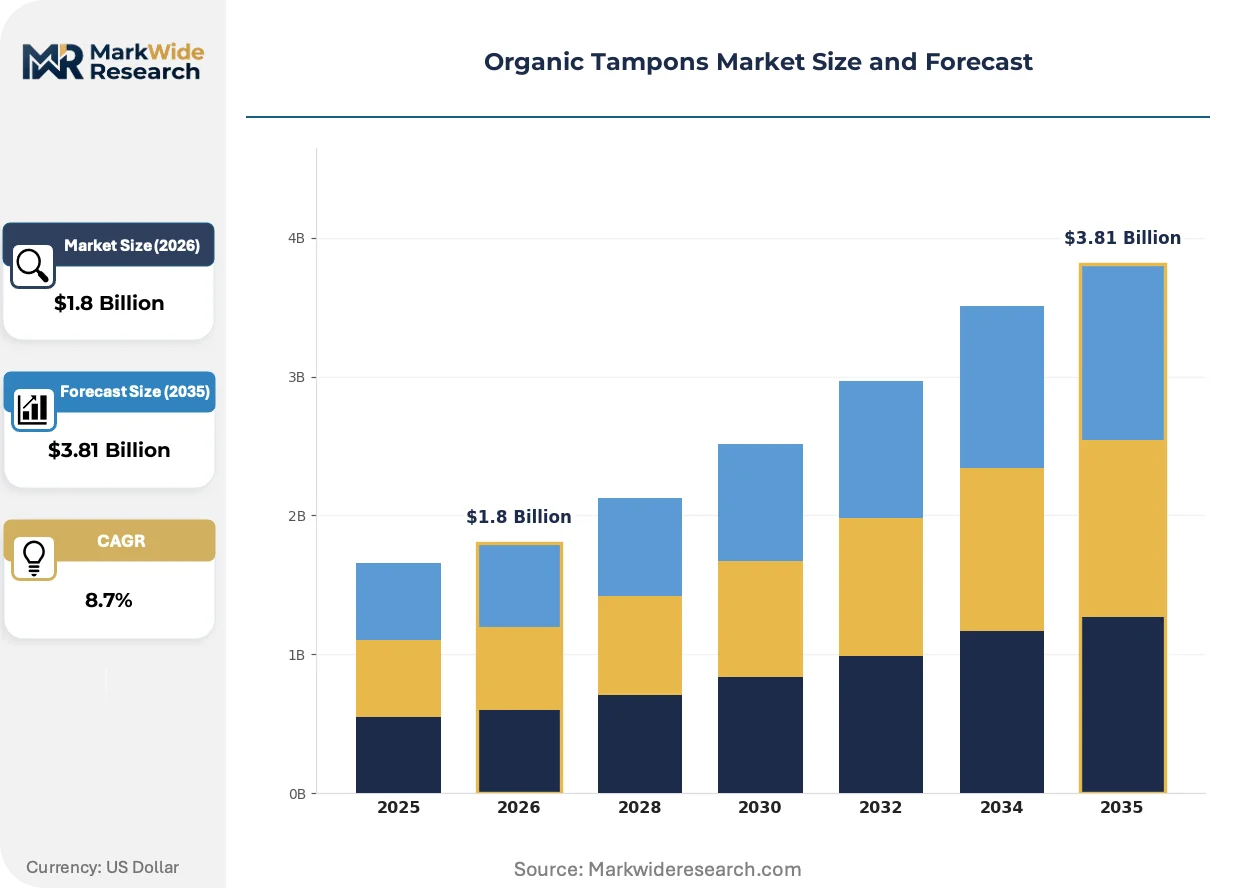
Market Dynamics
REACH chemical restrictions and the EU Green Deal are compressing conventional cotton supply chains while accelerating GOTS-certified organic sourcing requirements across European manufacturing.
Growth Catalysts
- EU Green Deal agrichemical mandates:The framework bans residual pesticides in imported cotton, forcing converters toward certified organic feedstock and expanding addressable market for compliant producers.
- Millennial subscription purchasing:Direct-to-consumer platforms with auto-replenishment mechanics lock in recurring revenue and reduce customer acquisition costs for organic tampon brands.
- Biodegradability performance:Organic cotton fibers decompose without microplastic residue, satisfying municipal composting standards in Germany and France where waste diversion targets tighten.
Market Restraints
- Organic cotton supply concentration:Certified acreage concentrates in India and Turkey, exposing converters to climate volatility and geopolitical friction in upstream procurement.
- Certification cost stacking:GOTS, OCS, and Soil Association approvals compound overhead, compressing margin for mid-tier manufacturers unable to absorb compliance spend.
- Conventional rayon price anchoring:Synthetic alternatives maintain 40-60% cost advantage at retail, constraining price elasticity in mass-market distribution.
Strategic Opportunities
- Pharmacy channel expansion:Boots and dm-drogerie markt shelf space for feminine hygiene is converting to organic-assigned facings under sustainability scorecards.
- Compostable applicator convergence:Bio-based plastics and cardboard tube innovations align with France's anti-waste law and AGEC circular economy requirements.
- Athletic segment specialization:Super Plus and Ultra absorbency variants command premium positioning among triathlon and marathon participants seeking chemical-free performance products.
Industry Challenges
- GOTS auditor capacity constraints:Certification body backlogs extend qualification timelines, delaying product launches and inventory commitments.
- Legacy dye house contamination:Conventional textile processors risk cross-contaminating organic cotton batches, requiring dedicated production lines and capital redeployment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Organic Tampons Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: Cotton, Bamboo, Organic Cotton, Recycled Cotton Distribution Channel: Supermarkets, Online Retail, Pharmacies, Specialty Stores End User: Women, Teens, Eco-conscious Consumers, Health-conscious Individuals Product Type: Regular, Super, Super Plus, Ultra |
| Companies Covered | Cora Inc., Natracare Limited, Organyc S.r.l., Rael US, Inc., The Honest Company, Inc., Seventh Generation, Inc., L. Organic, Maxim Hygiene Products Inc., Simply Good Products, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Organic Tampons Market Emerging Trajectories
Digital-native subscription platforms and bio-based material science are restructuring how organic tampons reach consumers and how they perform at end-of-life.
Plant-based applicator formulations derived from sugarcane and cornstarch are displacing petroleum-derived plastics in premium product tiers. German retailers dm-drogerie markt and Rossmann have converted 30% of their organic tampon facings to bio-applicator SKUs since 2023. This material transition is compressing conventional plastic component demand while forcing molders to retool for biopolymer processing temperatures.
REACH Annex XVII restrictions on persistent organic pollutants now cover pesticide residues in imported cotton fiber. The regulation forces non-EU suppliers to submit full supply chain documentation or face customs detention at Rotterdam and Hamburg ports. Indian and Turkish exporters are responding by segregating organic-certified ginning operations from conventional processing.
Subscription auto-replenishment with customizable cycle timing is replacing emergency pharmacy purchasing among urban professionals. Cora and similar platforms capture 18-month average customer lifetimes versus 3-4 purchase occasions for retail-only buyers. This behavioral shift concentrates most visibly in London, New York, and San Francisco where delivery density supports same-day or next-day fulfillment economics.
Organic Tampons Market Segmentation
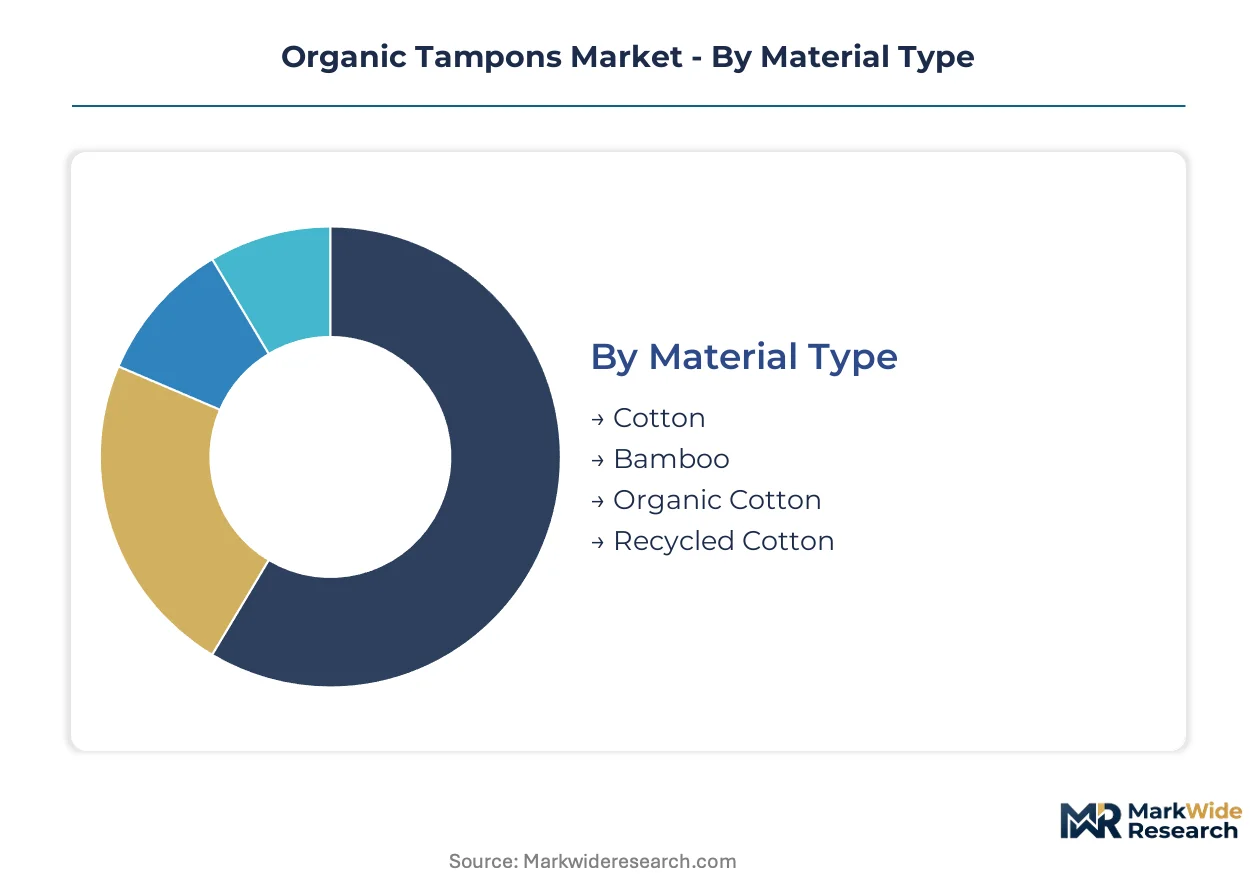
Material sourcing and absorbency specifications create distinct competitive arenas in organic tampons, with certification requirements and channel economics determining margin capture across each slice. Manufacturers must align production assets to the divergent technical and regulatory demands of each segment cluster.
Material Type:
Organic cotton dominates European domestic production, while bamboo and recycled variants flow primarily from Asian export hubs serving private-label programs.
- Organic Cotton:GOTS-certified fiber processed through dedicated ginning operations in India and Turkey supplies the premium tier. EU Green Deal pesticide restrictions have concentrated converter demand on this segment, though auditor backlogs delay new supplier qualification.
- Cotton:Conventional cotton tampons retain volume leadership in mass-market retail through price anchoring against synthetic alternatives. German and French pharmacy chains have reduced conventional facings under sustainability scorecards, compressing this segment's expansion trajectory.
- Bamboo:Fast-regenerating grass fiber offers biodegradability without agricultural chemical burden. Chinese processors dominate upstream supply, with most output flowing to North American direct-to-consumer brands seeking differentiated positioning.
- Recycled Cotton:Post-industrial textile waste repurposed through mechanical shredding addresses circular economy mandates in France and Italy. Supply inconsistency limits scale, relegating this segment to niche eco-premium lines.
Organic cotton holds the largest share; momentum sits with bamboo as Asian processors expand fiber finishing capacity.
Distribution Channel:
Channel economics diverge sharply between high-frequency replenishment platforms and trust-dependent pharmacy consultations.
- Online Retail:Subscription auto-replenishment with cycle-customizable timing captures urban professionals in London, New York, and San Francisco. Cora and similar platforms sustain 18-month average customer lifetimes through delivery density economics.
- Pharmacies:Boots, dm-drogerie markt, and Rossmann shelf space is converting to organic-assigned facings under retailer sustainability commitments. Pharmacist recommendation drives trial among first-time organic adopters seeking chemical exposure reduction.
- Supermarkets:Mass-market volume concentrates in conventional cotton and entry-level organic SKUs. Price elasticity constraints limit premium organic placement to top-tier urban locations.
- Specialty Stores:Zero-waste shops and organic cooperatives stock plastic-free applicator variants with compostable packaging. Limited geographic density restricts this channel to coastal metropolitan zones.
Online retail climbs fastest; pharmacies retain the revenue base through recurring foot traffic and professional endorsement.
End User:
Demographic targeting shifts from age-based segmentation toward values-based clustering as sustainability concerns transcend generational boundaries.
- Women:Core user base spanning ages 18-50 with absorbency needs varying across lifecycle stages. Product loyalty is low; switching costs favor subscription models with portable account management.
- Teens:First-period consumers represent critical acquisition opportunity with lifetime value implications. Educational content and discreet packaging drive brand selection among this cohort.
- Eco-conscious Consumers:Municipal composting access in Germany and France shapes purchase decisions, with biodegradability certification required for consideration.
- Health-conscious Individuals:Endometriosis and chemical sensitivity communities seek GOTS and Soil Association certifications as risk mitigation tools.
Women constitute the volume anchor; eco-conscious consumers are expanding most quickly as waste diversion targets tighten across European municipalities.
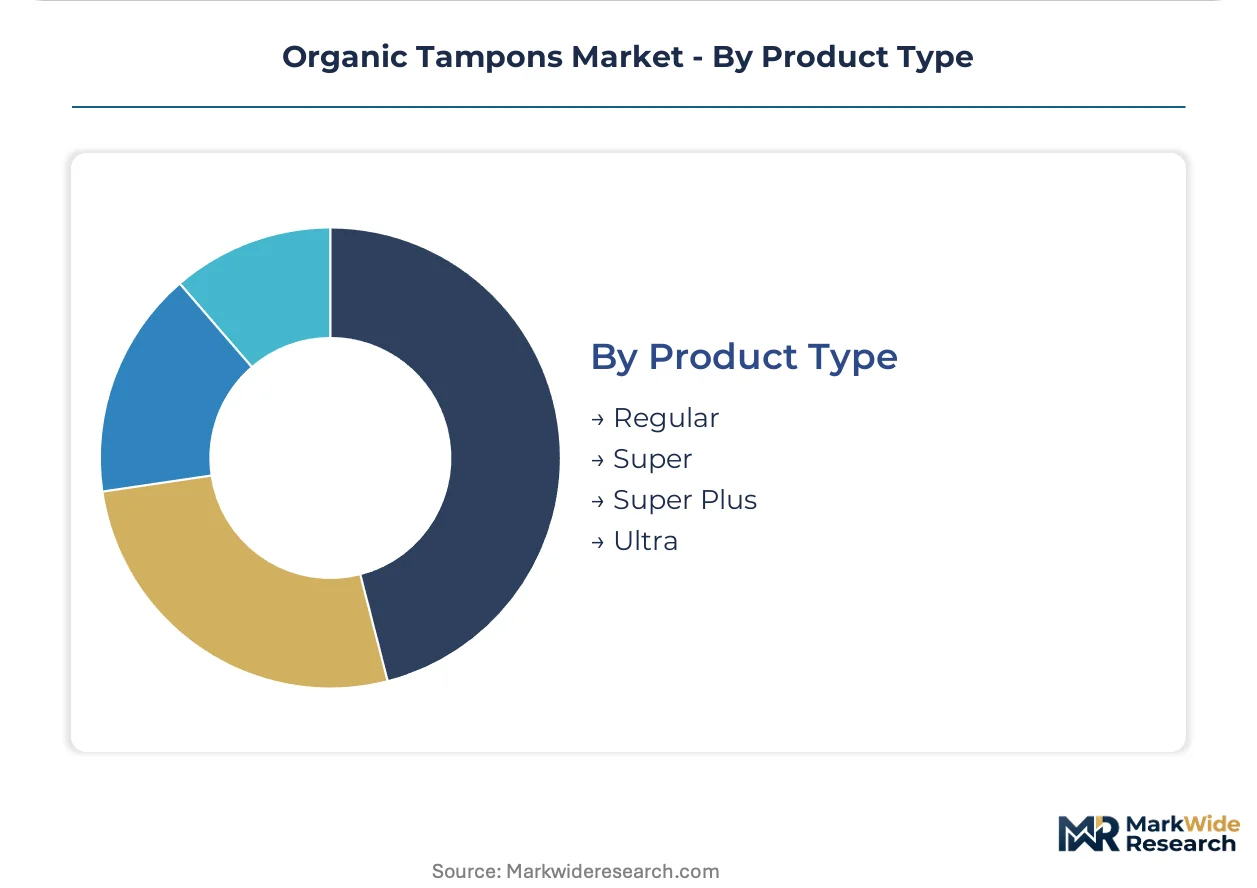
Product Type:
Absorbency engineering determines manufacturing complexity and per-unit economics, with higher tiers extracting premium positioning from athletic and medical segments.
- Super:Mid-tier absorbency satisfies mainstream flow requirements with optimized fiber density for 6-8 hour wear. This specification occupies the core production volume across all material types.
- Super Plus:Enhanced fiber compression and expanded surface area address heavy-flow days and athletic use. Marathon and triathlon participants drive premium pricing tolerance for chemical-free performance assurance.
- Regular:Entry-level absorbency faces substitution pressure from menstrual cups and period underwear in light-flow segments. Retailers are reducing SKU duplication in this tier.
- Ultra:Maximum absorbency with reinforced construction targets postpartum and medical applications. Limited distribution through specialty channels constrains volume but preserves margin.
Super absorbency dominates unit economics; Super Plus gains share fastest as athletic specialization and heavy-flow positioning expand addressable premium demand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Certified organic cotton feedstock concentrates in Indian and Turkish ginning operations, exposing converters to monsoon variability and geopolitical friction. Demand clusters in Western European pharmacy networks and North American subscription platforms. Regulatory divergence between REACH chemical restrictions and FDA absorbency labeling creates compliance complexity for cross-border suppliers.
Germany
dm-drogerie markt and Rossmann have converted 30% of feminine hygiene facings to organic-assigned SKUs since 2023. The EU Green Deal pesticide restrictions and AGEC circular economy law mandate biodegradable packaging and compostable applicators. Berlin and Hamburg anchor distribution, with same-day fulfillment economics supporting subscription platform density.
United States
Millennial and Gen Z consumers drive subscription auto-replenishment adoption through platforms with 18-month average customer lifetimes. FDA absorbency labeling and Good Manufacturing Practice compliance govern domestic manufacturing. New York and San Francisco concentrate demand, with direct-to-consumer brands leveraging delivery density for next-day fulfillment.
France
Boots pharmacy chains and municipal composting infrastructure shape purchase decisions among eco-conscious consumers. The anti-waste law and REACH Annex XVII restrictions on persistent organic pollutants enforce supply chain documentation requirements. Paris and Lyon dominate retail volume, with specialty zero-waste shops expanding plastic-free applicator distribution.
United Kingdom
Soil Association certification serves as a risk mitigation tool for endometriosis and chemical sensitivity communities. Retailer sustainability scorecards are compressing conventional cotton facings in Boots and Superdrug locations. London anchors subscription platform penetration, while Manchester and Birmingham sustain pharmacy channel volume.
Italy
EU organic certification control and manufacturing heritage differentiate domestic producers in export markets. GOTS auditor backlogs delay new supplier qualification, extending inventory commitment timelines. Milan and Turin concentrate production assets, with Emilia-Romagna hosting dedicated organic cotton processing lines.
Organic Tampons Market Vendor Landscape
Concentration sits with direct-to-consumer subscription specialists and European pharmacy-centric incumbents. The vendor base spans venture-backed digital natives, legacy natural products conglomerates, and private-label converters serving retailer sustainability commitments. Three archetypes dominate: subscription-first platforms with auto-replenishment mechanics, certification-heavy European manufacturers with pharmacy network anchoring, and diversified natural products portfolios leveraging cross-category distribution. Competitive moves center on pharmacy channel shelf space conversion under retailer sustainability scorecards and bio-based applicator material transitions forcing mold retooling.
Within the subscription-first tier, Cora Inc. exemplifies platform economics through cycle-customizable auto-replenishment. Among European certification specialists, Natracare Limited and Organyc S.r.l. occupy positions anchored by Soil Association and EU organic credentials. These three represent divergent geographic and channel strategies: United States-based digital distribution, United Kingdom pharmacy network density, and Italian manufacturing heritage with certification control.
| Leading Market Players |
|---|
| Cora Inc. |
| Natracare Limited |
| Organyc S.r.l. |
| Rael US, Inc. |
| The Honest Company, Inc. |
| Seventh Generation, Inc. |
| L. Organic |
| Maxim Hygiene Products Inc. |
| Simply Good Products, Inc. |
| Others |
Supply Flow & Price Mechanics
Certified organic ginning capacity utilization in India and Turkey sets price floors for European and North American converters, compressing margin for mid-tier manufacturers unable to secure long-term offtake agreements with GOTS-accredited suppliers.
Pricing Analysis
REACH chemical restrictions and EU Green Deal pesticide mandates dictate the pricing tier structure across European pharmacy channels. Three-tier pricing stratifies across GOTS-certified premium, OCS mid-grade, and conventional economy levels, with certification grade and volume scale as primary differentiation drivers. Cost compression in the mid-tier intensifies because Turkish and Indian suppliers command premium feedstock pricing. Mass-market retail buyers exhibit highest price sensitivity, while subscription platform users demonstrate lowest elasticity due to convenience lock-in.
Supply Chain Analysis
GOTS auditor certification backlogs create a chokepoint that delays new supplier qualification by six to twelve months, forcing converters to maintain larger safety stocks. Certified organic cotton concentrates in Indian and Turkish ginning operations, with bamboo fiber processing anchored in Chinese export hubs. Raw material dependencies rest on GOTS-certified cotton seed stock, bio-based applicator polymers, and compostable packaging substrates. Single-source vulnerability runs through concentrated Indian organic acreage exposed to monsoon variability. Distribution runs through pharmacy chain consolidation in Germany and France alongside direct-to-consumer subscription platforms in the United States.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Retailer sustainability scorecard consolidation across Boots, dm-drogerie markt, and Rossmann has shifted buyer power toward chains capable of dictating organic-facing minimums, fragmenting negotiating leverage among smaller converters.
For Market Incumbents: Secure dedicated GOTS-certified production lines in India or Turkey to eliminate cross-contamination risk from legacy dye house operations. Secure pharmacy shelf space conversion commitments under retailer sustainability scorecards before competitor lock-in. Certification investment in Soil Association and EU organic credentials provides defensive moat against emerging bamboo-fiber entrants.
For New Entrants and Emerging Players: Anchor in the North American subscription channel where customer acquisition costs have stabilized and 18-month lifetimes support unit economics. Anchor in bamboo fiber differentiation targeting eco-conscious consumers in German and French municipalities with composting infrastructure. Direct-to-consumer content marketing around chemical sensitivity and endometriosis communities offers lowest-friction trial conversion.
For Investors and Strategic Acquirers: Subscription-first platforms with proven auto-replenishment mechanics and cycle-customizable interfaces represent the most defensible acquisition archetype for long-term viability in a five-to-ten year window. GOTS auditor capacity expansion serves as the critical inflection indicator; qualification timeline compression would unlock inventory efficiency gains across the supplier base.
| Strategic Initiative | Industry Significance |
|---|---|
| GOTS Certification Investment | REACH compliance in Rotterdam and Hamburg ports requires full supply chain documentation from non-EU suppliers. |
| Pharmacy Channel Expansion | Boots and dm-drogerie markt sustainability scorecards are converting 30 percent of feminine hygiene facings to organic-assigned SKUs. |
| Bio-based Applicator Transition | France's AGEC circular economy law mandates compostable components, forcing mold retooling for sugarcane and cornstarch polymers. |
| Subscription Platform Development | Cycle-customizable auto-replenishment in London and New York captures 18-month average customer lifetimes versus retail-only buyers. |
| Athletic Segment Specialization | Super Plus and Ultra absorbency variants command premium positioning among marathon and triathlon participants seeking chemical-free performance. |
Methodological Framework
A spread of perspectives from brand managers at organic tampon converters, category buyers at pharmacy chains, GOTS certification auditors, supply planners at cotton ginning operations, and regulatory affairs leads at EU import consultancies converged on the working assumptions. Primary interview insights were validated against secondary sources including ECHA REACH guidance documents, EU Green Deal implementation texts, Soil Association certification databases, and customs records of organic cotton fiber imports through Rotterdam and Hamburg. Bottom-up production capacity estimates were triangulated with top-down pharmacy and subscription channel revenue assessments.
Segmentation dimensions modeled include material type, absorbency tier, distribution channel, and end-user values cluster across the projection horizon. CAGRs were derived from installed capacity trajectories, certification pipeline velocity, and channel shift elasticity parameters. Industry-specific forecast inputs incorporated GOTS auditor queue lengths and municipal composting infrastructure rollouts in Germany and France.
Decision-makers should treat outputs as directional under sustained REACH enforcement and stable organic cotton acreage assumptions; material deviation in Turkish or Indian climate patterns would warrant model refresh. Practitioners should keep alternative scenarios live as EU Green Deal pesticide residue thresholds and AGEC packaging mandates evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Personal Grooming Products
Shoe Care Market
Personal Grooming Products
Global Organic and Natural Feminine Care Market
Personal Grooming Products
Portable Massage Devices Market
Personal Grooming Products
Disposable Razor Blades Market
Personal Grooming Products
Electric Tooth Polisher Market
Personal Grooming Products
Europe and MEA Condom Market
Personal Grooming Products
Electric Hair Brush Market
Personal Grooming Products
Europe Hair Styling Tools Market
Personal Grooming Products
Women Face Razor Market
Personal Grooming Products
Global Posture Corrector Market
Personal Grooming Products
Disposable Electric Toothbrushes Market
Personal Grooming Products
Gel Socks Market
Personal Grooming Products
Baby Grooming Kits Market
Personal Grooming Products
Foot Care Products Market
Personal Grooming Products
Shaving Pen Market
Personal Grooming Products
Horsehair Clippers Market